
 Coal Intelligent Dry Separators Market | 2026-2036
Coal Intelligent Dry Separators Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Intelligent Dry Separators Market Insights
Project finance tied to environmental compliance is narrowing the competitive field for capital-intensive dry separation deployments. Tianjin Meiteng leverages its turnkey systems capability to anchor large mining contracts in northern China's coal belt. Tomra Systems competes through sensor-based sorting specialization that extends its technology leadership across acoustic and electrostatic platforms. Zhongke AMD sustains domestic market positioning by controlling integration services for retrofit installations at state-owned energy producers.
Coal intelligent dry separators are mechanical systems that sort coal from gangue without water, typically using electrostatic charge differential, air density classification, or magnetic susceptibility to achieve ash reduction below ten percent in run-of-mine feed. These units serve coal processing plants seeking to eliminate slurry ponds and reduce freshwater intensity in arid mining regions. Electrostatic technology dominates current procurement volumes due to proven performance on fine coal fractions, while air classifier systems represent the fastest-growing segment as operators retrofit existing wash plants for zero-liquid discharge. Turnkey systems capture the largest margin pool because engineering-procurement-construction contracts bundle hardware with commissioning liability, whereas aftermarket support remains fragmented across regional service networks.
China's MEE enforces discharge permits that restrict wet tailings volumes, directly elevating dry separation feasibility studies at provincial coal groups. The country's GB standards for coal quality classification mandate precise ash and sulfur reporting that sensor-based dry systems deliver without laboratory slurry preparation. India's CEA circulars on washery utilization for thermal coal create parallel compliance pressure in the Singrauli and Talcher coalfields. Stakeholders must monitor how carbon border adjustment mechanisms in destination markets for metallurgical coal reshape investment timelines for dry separation retrofits versus greenfield wet plants.
Market Dynamics
Water scarcity in northern China's coal belt is forcing a wholesale replacement of wet washing circuits with electrostatic and air-density separation systems, compressing capital deployment timelines for mine operators facing MEE discharge permit restrictions.
Growth Catalysts
- GB Standards Compliance:China's tightening coal quality classification mandates require precise ash and sulfur reporting that dry sensor systems deliver without laboratory slurry preparation, accelerating retrofit demand at state-owned mines.
- Electrostatic Technology Maturation:Proven performance on fine coal fractions below 50mm has validated dry separation for metallurgical coal applications previously requiring dense medium baths.
- Inner Mongolia Water Stress:Open-pit mining corridors in this autonomous region face acute freshwater constraints that make zero-liquid discharge processing economically essential rather than optional.
Market Restraints
- Capital Intensity Barrier:Turnkey electrostatic systems require engineering-procurement-construction contracts bundling hardware with commissioning liability, excluding smaller provincial mining groups from procurement.
- Technical Limitation on Ultrafines:Current air classifier designs struggle to achieve target ash reduction below 6mm particle sizes without secondary grinding circuits, limiting application scope.
- Skilled Technician Scarcity:Deployment of sensor-based sorting platforms demands field engineers capable of calibrating acoustic and electrostatic arrays, a capability concentrated in Tianjin and Beijing service hubs.
Strategic Opportunities
- India CEA Washery Mandates:Central Electricity Authority circulars on thermal coal beneficiation create parallel compliance pressure in Singrauli and Talcher coalfields where water availability varies seasonally.
- Retrofit Channel Expansion:Integration services for brownfield installations at existing wash plants represent underdeveloped margin pools beyond greenfield turnkey contracts.
- Carbon Border Adjustment Positioning:European CBAM mechanisms on imported metallurgical coal reshape investment timelines, favoring dry separation retrofits that reduce scope-three emissions reporting burdens.
Industry Challenges
- Commissioning Complexity:Electrostatic separator calibration requires site-specific adjustment for coal rank variability, extending project handover timelines and creating performance guarantee disputes.
- Aftermarket Fragmentation:Regional service networks for spare parts and sensor recalibration remain underdeveloped outside Shanxi and Inner Mongolia, constraining equipment utilization rates at remote mine sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Intelligent Dry Separators Market |
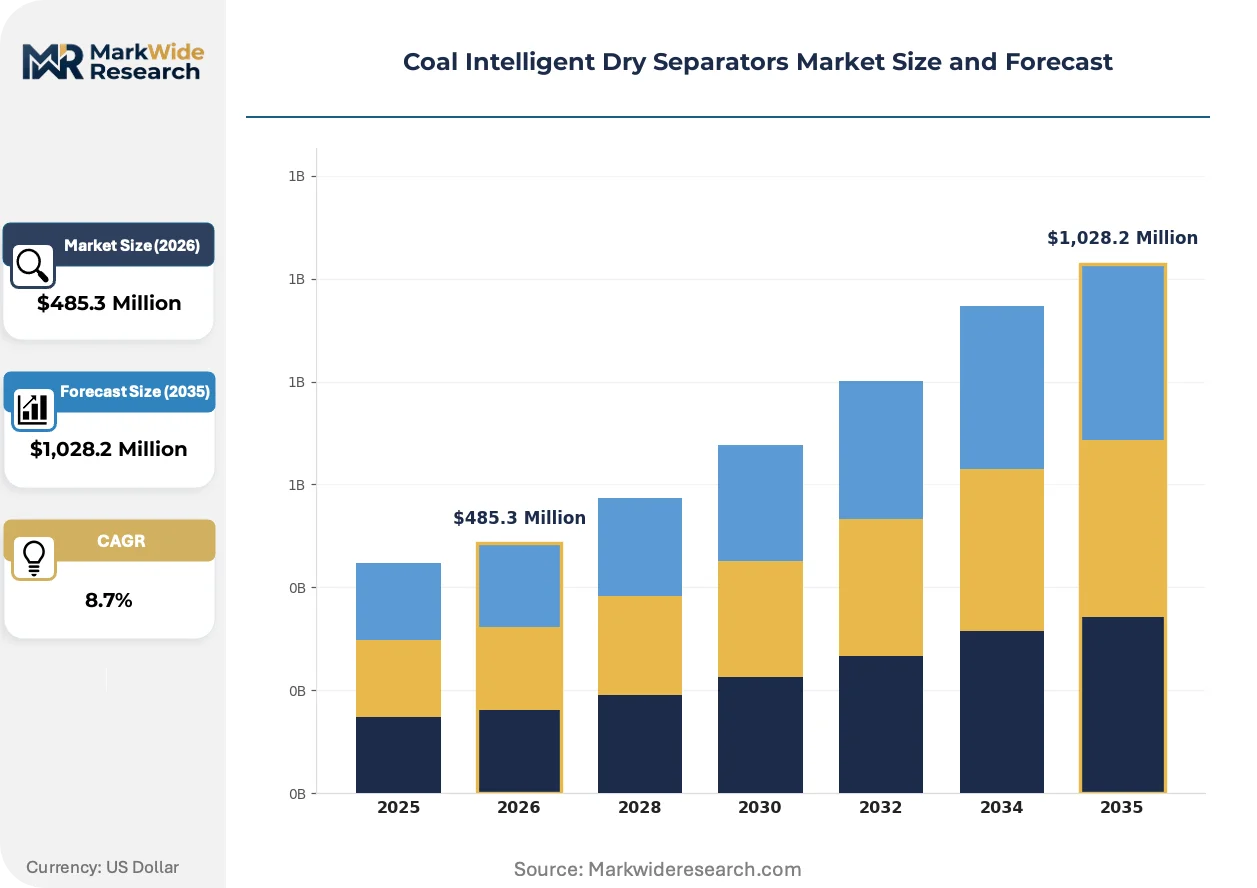
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrostatic, Air Classifier, Magnetic, Acoustic End User: Mining Companies, Energy Producers, Metallurgical Plants, Construction Firms Application: Coal Processing, Waste Management, Mineral Separation, Resource Recovery Solution: Turnkey Systems, Customized Solutions, Integration Services, Aftermarket Support |
| Companies Covered | Tianjin Meiteng, Tomra Systems, Comex Group, Julong Rongzhi, Taiho Intelligent, Beijing Honest Technology, Zhongke AMD, Tangshan Shenzhou Manufacturing, Hebei Jiuhe Precision Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Intelligent Dry Separators Market Trends and Innovations
Sensor fusion architectures combining acoustic emission detection with electrostatic charge measurement are compressing the performance gap between dry and wet separation for mid-volatility bituminous coals. Equipment suppliers are racing to embed machine learning models that auto-calibrate for feed variability without operator intervention.
Multi-sensor sorting platforms integrating X-ray transmission with electromagnetic sensing are rendering obsolete single-technology dry separators that rely solely on density differential. Large open-pit operators in Ordos and Xilinhot are deploying these hybrid systems for run-of-mine feeds exceeding 300 tonnes per hour. The technology is compressing capital recovery periods from seven years toward four years for high-ash deposits.
China's MEE enforcement of discharge permits restricting wet tailings volumes has elevated dry separation feasibility studies to board-level approval at provincial coal groups. The regulatory pressure is eliminating slurry pond construction from greenfield project designs in water-stressed jurisdictions. State-owned energy producers are now mandating dry processing circuits for all new mine developments in regions below national average precipitation levels.
Equipment procurement is consolidating toward performance-based contracting where suppliers assume ash reduction guarantees rather than selling hardware alone. Mining groups in Shanxi are shifting from capital purchase models toward throughput-based service agreements that transfer operational risk. This restructuring is most visible at Datong and Yangquan mining complexes where water tariffs now exceed power costs in processing economics.
Coal Intelligent Dry Separators Market Segmentation
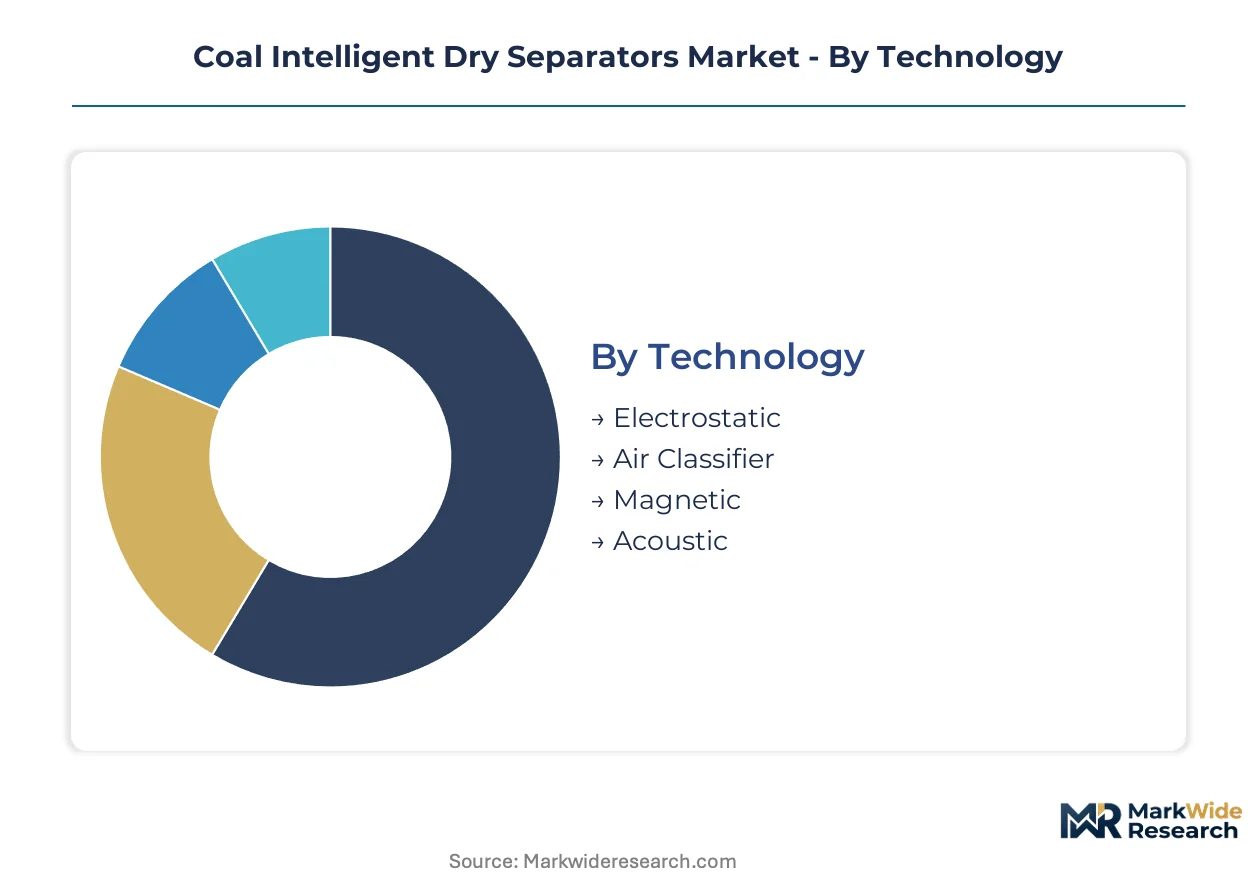
Segmentation in coal intelligent dry separators reveals how procurement patterns split between capital-intensive greenfield deployments and retrofit services. Mining operators select technology and solution combinations based on water scarcity severity, coal rank variability, and existing plant infrastructure age.
Technology:
After-sales-service intensity varies sharply across technology types, with electrostatic arrays demanding specialized recalibration technicians and acoustic platforms requiring frequent sensor replacement in dusty environments.
- Electrostatic:Charge differential separation exploits coal-gangue conductivity gaps to achieve ash reduction below ten percent without water. Procurement concentrates in Shanxi Province's state-owned mines where MEE discharge permits restrict wet tailings volumes and electrostatic performance on fine fractions below 50mm has displaced dense medium baths.
- Air Classifier:Density-based pneumatic sorting uses controlled air velocity to stratify particles by specific gravity. Open-pit corridors in Inner Mongolia's Ordos basin deploy these systems most aggressively, as zero-liquid discharge processing becomes economically essential rather than optional under acute freshwater constraints.
- Magnetic:Susceptibility-based separation targets pyritic sulfur removal in high-sulfur bituminous deposits.
- Acoustic:Emission detection platforms identify coal-gangue interfaces through stress-wave analysis in run-of-mine feeds.
Electrostatic technology holds the largest share; momentum sits with air classifier systems gaining share fastest in water-stressed jurisdictions.
End User:
Customer type determines contract structure complexity, with energy producers favoring long-term service agreements and metallurgical plants insisting on performance guarantees for ash specification compliance.
- Mining Companies:Open-pit and underground operators purchase turnkey systems for greenfield developments and brownfield retrofits. Shanxi and Inner Mongolia mining groups dominate order books, driven by MEE enforcement of discharge permits that eliminate slurry pond construction from new project designs.
- Energy Producers:State-owned thermal power utilities deploy dry separation to secure compliant feedstock for supercritical boilers. Procurement concentrates at Datong and Yangquan complexes where water tariffs now exceed power costs in processing economics, shifting purchase models toward throughput-based service agreements.
- Metallurgical Plants:Coking coal processors require precise ash and sulfur reporting that sensor-based dry systems deliver without laboratory slurry preparation.
- Construction Firms:Contract miners and infrastructure developers acquire mobile units for temporary processing at remote project sites.
Mining companies command the dominant procurement volume; energy producers are expanding most quickly as tariff structures rewrite capital allocation priorities.
Application:
Application scope dictates equipment mobility requirements and integration depth with existing material handling infrastructure.
- Coal Processing:Run-of-mine beneficiation for thermal and metallurgical coal grades represents the core application. Demand clusters in northern China's coal belt where GB standards for coal quality classification mandate precise reporting that dry sensor systems enable.
- Waste Management:Dry separation of coal refuse for landfill diversion and combustion feedstock. Procurement rises at decommissioned wet wash plants seeking to repurpose tailings piles without slurry rewetting.
- Mineral Separation:Extension to non-coal minerals including barite and fluorspar processing in polymetallic deposits.
- Resource Recovery:Reprocessing of historic coal waste dumps for residual energy content extraction.
Coal processing absorbs the majority of installed capacity; resource recovery shows the steepest expansion trajectory as legacy dump rehabilitation gains regulatory support.
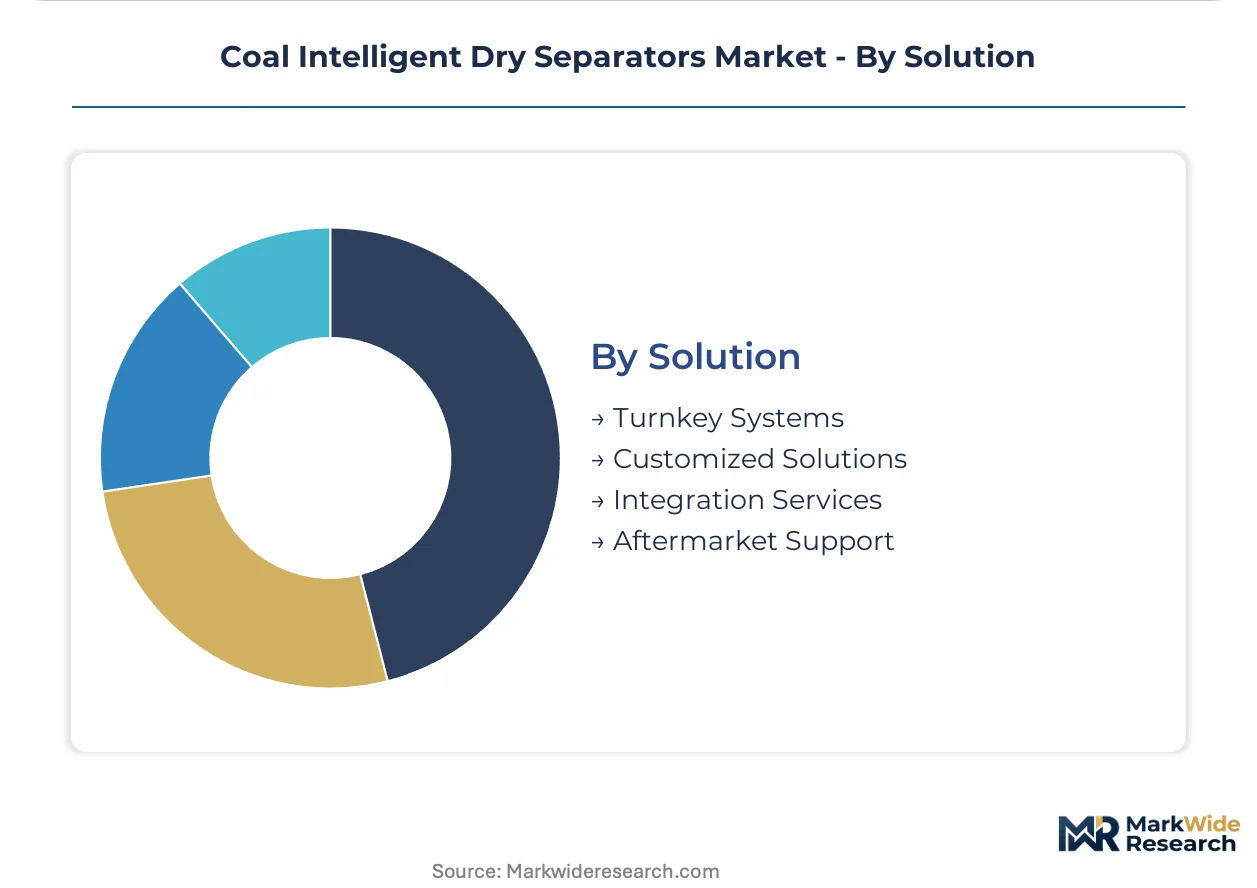
Solution:
Solution architecture determines margin capture and liability allocation between equipment supplier and mine operator.
- Turnkey Systems:Engineering-procurement-construction contracts bundle hardware supply with installation, commissioning, and performance guarantees. These contracts capture the largest margin pool but exclude smaller provincial mining groups from procurement due to capital intensity barriers and extended project handover timelines.
- Integration Services:Brownfield retrofit design and installation at existing wash plants. This segment represents underdeveloped margin pools beyond greenfield contracts, with Zhongke AMD and regional specialists controlling retrofit channels at state-owned energy producers.
- Customized Solutions:Site-specific modifications for unique coal rank variability or feed rate requirements.
- Aftermarket Support:Spare parts, sensor recalibration, and field service. Regional service networks remain fragmented outside Shanxi and Inner Mongolia, constraining equipment utilization rates at remote mine sites and creating opportunities for service hub expansion.
Turnkey systems dominate revenue; aftermarket support is climbing fastest as installed base expansion outpaces service network development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE discharge permit restrictions are reshaping procurement patterns across coal belts where water scarcity intersects with beneficiation mandates. Provincial energy groups in Shanxi and Inner Mongolia are accelerating dry separation feasibility studies ahead of permit renewal cycles. The regulatory pressure is eliminating slurry pond construction from greenfield designs in water-stressed jurisdictions.
China
Shanxi Province's state-owned mines dominate electrostatic unit procurement as GB standards tighten coal quality classification requirements. The MEE enforces discharge permits that restrict wet tailings volumes, directly elevating dry separation at provincial coal groups. Datong and Yangquan mining complexes are shifting toward throughput-based service agreements where water tariffs now exceed power costs.
India
Singrauli and Talcher coalfields face parallel compliance pressure from CEA circulars mandating thermal coal beneficiation. Seasonal water availability variations make dry separation economically essential during drought periods. State-owned power utilities in these basins are retrofitting existing wash plants with air classifier systems to maintain generation continuity.
Australia
Queensland's Bowen Basin metallurgical coal producers are evaluating dry separation retrofits ahead of European carbon border adjustment mechanism implementation. The country's national environmental regulator has tightened mine water discharge standards for new project approvals. Mackay-Gladstone industrial corridors are hosting feasibility studies for zero-liquid discharge processing at coking coal operations.
United States
Appalachian Basin thermal coal operators in West Virginia and Kentucky are piloting electrostatic systems to reduce slurry pond liability exposure. EPA coal combustion residual regulations are elevating dry processing economics for power plant feedstock preparation. Pittsburgh-Charleston industrial clusters are seeing equipment trials focused on mid-volatility bituminous applications.
South Africa
Water-scarce Mpumalanga coal belt operations are deploying air density separators to maintain production during irrigation restriction periods. The country's Department of Water and Sanitation has imposed abstraction limits on mining licenses in catchment-stressed catchments. Witbank-Middelburg mining complexes are consolidating procurement toward performance-based contracting models.
Coal Intelligent Dry Separators Market Competitive Landscape
On the supply side, the industry is consolidating around turnkey systems providers capable of absorbing commissioning liability and regional specialists controlling retrofit integration channels. The vendor base splits between electrostatic technology leaders and multi-sensor platform developers racing to embed machine learning calibration. Two strategic archetypes dominate: engineering-procurement-construction bundlers capturing greenfield margin pools, and aftermarket service networks exploiting installed base expansion. Competitive moves center on performance-based contracting restructuring and sensor fusion architecture development.
Within the turnkey systems tier, Tianjin Meiteng anchors large mining contracts through its integrated project delivery capability. Tomra Systems occupies a position exemplifying sensor-based specialization across acoustic and electrostatic platforms. Zhongke AMD sits within the domestic integration services archetype, controlling retrofit channels at state-owned energy producers in northern China's coal belt.
| Leading Market Players |
|---|
| Tianjin Meiteng |
| Tomra Systems |
| Comex Group |
| Julong Rongzhi |
| Taiho Intelligent |
| Beijing Honest Technology |
| Zhongke AMD |
| Tangshan Shenzhou Manufacturing |
| Hebei Jiuhe Precision Machinery |
| Others |
Pricing and Supply Chain Analysis
Tianjin-Beijing freight corridors connecting electrostatic separator manufacturing hubs to Shanxi mining complexes impose logistics premiums that amplify price spreads between turnkey system providers and regional retrofit specialists. Water tariff escalation at Datong and Yangquan complexes is compressing procurement cycles and forcing buyers toward performance-based contracting that transfers operational risk upstream.
Pricing Analysis
Certification level (GB/ISO-compliant MEE discharge ratings) creates the primary spread between premium electrostatic arrays and standard air classifier units. Turnkey EPC contracts with commissioning liability bundles command price premiums over hardware-only transactions, while aftermarket service agreements show rising penetration as water tariffs exceed power costs. Cost compression in standard-tier equipment is intensifying because magnetic and acoustic sensor platforms face commoditization pressure from domestic Chinese suppliers. Provincial mining groups in Shanxi exhibit highest price sensitivity due to capital intensity barriers, whereas state-owned energy producers at Yangquan demonstrate lowest sensitivity under throughput-based service models.
Supply Chain Analysis
Tariff exposure between precision sensor suppliers in Japan and South Korea and final assembly operations in Tianjin dominates supply chain risk assessment for electrostatic array manufacturers. Component sourcing concentrates in Germany for high-voltage power electronics, China for pneumatic classification hardware, and South Korea for electromagnetic sensor modules. Raw material dependencies include rare-earth magnetic materials, specialized ceramic insulators, and machine-vision processing chipsets. Single-source vulnerability persists for acoustic emission detection arrays calibrated to specific coal rank signatures. Distribution runs through regional service hubs in Shanxi and Inner Mongolia before reaching remote mine sites, constraining spare parts velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment procurement cycles in this market track coal price recovery phases, with MEE discharge permit renewal waves triggering concentrated demand spikes every three to five years.
For Market Incumbents: Pre-empt sensor fusion commoditization by embedding proprietary machine learning calibration layers that lock customers into recurring recalibration revenue streams. Acquire distressed retrofit specialists in Shanxi to consolidate integration service channels before provincial mining groups consolidate procurement. Tianjin Meiteng and Tomra Systems must defend against domestic Chinese suppliers eroding price premiums in standard-tier electrostatic equipment. For New Entrants and Emerging Players: Pursue aftermarket service hub gaps in South Africa's Mpumalanga belt and India's Singrauli coalfield where regional networks remain fragmented and equipment utilization rates suffer. Target mobile dry separation units for construction firms and contract miners seeking temporary processing capacity at remote project sites. Lead with sensor recalibration subscriptions rather than capital equipment sales to bypass incumbent EPC bundling advantages. For Investors and Strategic Acquirers: Brownfield retrofit specialists with established relationships at state-owned energy producers represent the most defensible acquisition archetype in this market. Long-term viability hinges on water scarcity intensification across coal belts and carbon border adjustment mechanism expansion into metallurgical coal trade. Watch for MEE permit enforcement acceleration in Shanxi as the inflection signal indicating demand surge timing.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Transition | Transfers commissioning liability to suppliers and locks in recurring service revenue at Datong complexes. |
| Sensor Fusion Platform Development | Combines acoustic and electrostatic arrays to displace single-technology separators in Ordos basin deployments. |
| Regional Service Hub Expansion | Addresses aftermarket fragmentation constraining utilization rates at remote South African mine sites. |
| Retrofit Integration Channel Control | Captures underdeveloped margin pools at existing wash plants facing MEE discharge permit restrictions. |
| Machine Learning Calibration Embedding | Auto-adjusts for coal rank variability without operator intervention, reducing skilled technician dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MEE discharge permit databases, GB standards compliance filings, and provincial coal group procurement records. Primary interviews engaged equipment procurement directors at state-owned mining groups, commissioning engineers at Tianjin-based system integrators, and aftermarket service managers at regional maintenance hubs. Secondary validation drew from customs trade data on electrostatic separator imports, SEC filings of listed sensor technology suppliers, and CEA circulars on thermal coal beneficiation mandates. Bottom-up unit deployment tracking triangulates against top-down market sizing across technology, end-user, and solution segments.
Forecast inputs incorporate electrostatic and air classifier technology maturation curves, water tariff escalation trajectories at northern Chinese mining complexes, and MEE enforcement intensity scenarios. Segmentation dimensions modeled include technology type, end-user archetype, application scope, and solution architecture across the projection horizon. CAGRs derive from installed base expansion rates net of replacement cycles and retrofit penetration assumptions. Industry-specific inputs include coal rank variability coefficients affecting separator calibration frequency and carbon border adjustment mechanism coverage expansion for metallurgical coal exports.
Sensitivities concentrate around MEE permit enforcement acceleration, water scarcity severity in Inner Mongolia's Ordos basin, and sensor fusion technology cost reduction curves. Forecasts reflect assumptions regarding regulatory continuity in China's coal quality classification standards and sustained capital allocation priority for zero-liquid discharge processing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Methane Hydrate Market
Fuels
North America Bunker Fuel Market
Fuels
Europe Wood Pellet Market
Fuels
Canada Coal Market
Fuels
China Bunker Fuel Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Electric Fuel Heater Market
Fuels
Methane Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
LPG Vaporizer Market
Fuels
China Coal Market
Fuels
Gasoline Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Turbine Drip Oil Market
Fuels
Fuel Analyzer Market
Fuels
Gas Feed System Market