
 Global Renewable Fuel Market | 2026-2036
Global Renewable Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Renewable Fuel Market Outlook
Advanced biofeedstocks derived from agricultural residues and waste oils is recalibrating cost structures for second-generation renewable diesel. Neste leverages proprietary NEXBTL refining technology to dominate renewable diesel output from waste and residue raw materials. Valero Energy Corp. anchors its position through Diamond Green Diesel, a joint venture that operates at substantial scale across Gulf Coast processing facilities. POET LLC specializes in corn ethanol production and biorefining infrastructure across the US Midwest, sustaining one of the largest biofuel manufacturing footprints globally.
Renewable fuel encompasses liquid and gaseous energy carriers manufactured from biomass, waste streams, or advanced biological feedstocks, typically processed through transesterification, fermentation, or thermochemical conversion to achieve specified cetane, octane, or methane indices for combustion engines or turbines. Its primary purpose is displacing fossil-derived gasoline, diesel, jet fuel, and natural gas in hard-to-electrify transport and industrial heat applications. Renewable diesel derived from vegetable oils and animal fats leads value generation due to drop-in compatibility with existing infrastructure and premium pricing in low-carbon fuel standard markets. Ethanol from sugarcane and corn maintains volume leadership, though margin compression in standard blending markets pushes producers toward higher-value cellulosic pathways. Biogas upgrading to biomethane represents the fastest-expanding delivery mode segment, as pipeline injection standards unlock residential and industrial offtake.
The US Environmental Protection Agency administers Renewable Fuel Standard volume obligations that mandate minimum biofuel blending, directly shaping refiner procurement and production investment. The European Union's F-Gas Regulation and Renewable Energy Directive II impose escalating greenhouse-greduction thresholds for transport fuels, while California's Air Resources Board operates the Low Carbon Fuel Standard that generates tradable credits based on lifecycle carbon intensity scores. Stakeholders must monitor feedstock cost volatility, policy renewal timelines, and certification scheme interoperability to secure offtake contracts and capital deployment.
Market Dynamics
The EU Green Deal's tightening carbon intensity benchmarks for transport fuels is forcing aviation refiners into accelerated sustainable aviation fuel offtake negotiations, compressing procurement timelines and reshaping feedstock sourcing strategies across hard-to-electrify transport segments.
Growth Catalysts
- California's Low Carbon Fuel Standard:The tradable credit mechanism based on lifecycle carbon intensity scores generates premium pricing for renewable diesel, pulling investment toward waste and residue feedstock processing infrastructure.
- Sugarcane ethanol infrastructure in Brazil:Existing crushing capacity and flex-fuel vehicle penetration above 80 percent create captive demand that insulates producers from blending mandate volatility seen in other geographies.
- Biogas upgrading to biomethane:Pipeline injection standards in Germany and the Netherlands unlock residential heating and industrial offtake, expanding addressable market beyond transport fuels.
Market Restraints
- Feedstock cost volatility:Used cooking oil and animal fat prices fluctuate with food industry output, compressing renewable diesel margins when virgin vegetable oil markets spike.
- Supply concentration in Southeast Asian palm oil:Geopolitical friction and sustainability certification disputes create procurement risk for European and North American renewable diesel producers dependent on imported feedstocks.
- Blending wall constraints:Legacy internal combustion engine compatibility limits ethanol penetration beyond E15 in the US retail gasoline pool, capping volume expansion regardless of production capacity.
Strategic Opportunities
- Underpenetrated Indian ethanol market:The country's ethanol blending program targets 20 percent by 2025, creating feedstock demand that domestic sugarcane and grain surplus can supply.
- Electrofuel synthesis integration:Combining green hydrogen with captured carbon dioxide enables synthetic aviation fuel production with near-zero lifecycle emissions, opening premium offtake channels.
- EU Renewable Energy Directive II:Escalating greenhouse-gas reduction thresholds for transport fuels mandate advanced biofuel volumes that agricultural residue and waste oil pathways can satisfy.
Industry Challenges
- ISCC certification complexity:Multi-jurisdictional audit requirements for sustainable supply chain verification delay feedstock procurement contracts and capital deployment timelines.
- Capex intensity for cellulosic ethanol:Enzymatic hydrolysis and pretreatment equipment requires substantial upfront investment that first-generation producers struggle to justify given margin compression in standard blending markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Renewable Fuel Market |
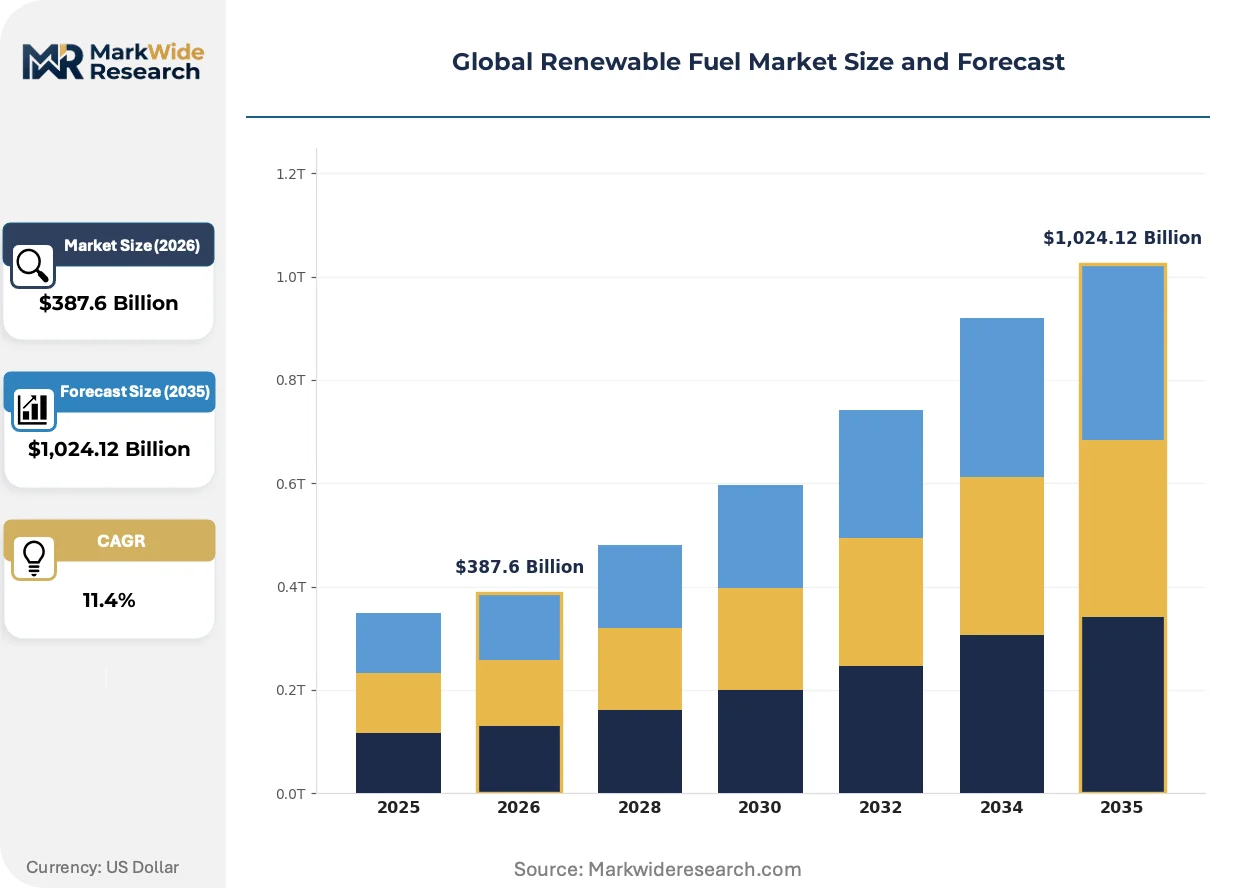
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Biodiesel, Ethanol, Biogas, Renewable Diesel Delivery Mode: Pipeline, Truck Transport, Rail Transport, Barge Transport End User: Transportation, Power Generation, Industrial, Residential Feedstock: Vegetable Oils, Animal Fats, Sugarcane, Agricultural Residues |
| Companies Covered | Neste, Valero Energy Corp., Chevron Corporation, Archer Daniels Midland Co., Cargill Inc., POET LLC, TotalEnergies SE, BP Plc, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Renewable Fuel Market Strategic Shifts
Technology convergence between thermochemical conversion and biological processing routes is fragmenting the competitive landscape, with modular production units enabling distributed manufacturing closer to feedstock origins rather than centralized refining.
Pyrolysis oil upgrading to renewable diesel is modularizing through containerized reactor systems that slash construction timelines from years to months. Remote forestry operations and agricultural cooperatives in Sweden and Finland deploy these units to convert forest residues into transport fuel precursors on-site. The approach collapses feedstock logistics costs and enables small-scale producers to access low-carbon fuel standard markets previously dominated by integrated refiners.
REACH authorization requirements for chemical intermediates used in advanced biofuel catalysts are tightening compliance burdens for European producers. The regulation forces reformulation of hydroprocessing catalysts to eliminate substances of very high concern, extending R&D cycles by 18-24 months. German and Dutch renewable diesel facilities absorb these delays through buffer inventory strategies while accelerating partnerships with catalyst suppliers possessing pre-authorized substance portfolios.
Airline procurement departments now mandate book-and-claim certificate systems for sustainable aviation fuel purchases, decoupling physical fuel delivery from emissions accounting. This securitization enables carriers based in Singapore and the United Arab Emirates to source SAF from production facilities in the US and Europe without logistical integration into their refueling networks. The mechanism concentrates demand verification expertise among certification bodies and creates secondary trading markets for environmental attributes distinct from commodity fuel markets.
Global Renewable Fuel Market Segmentation
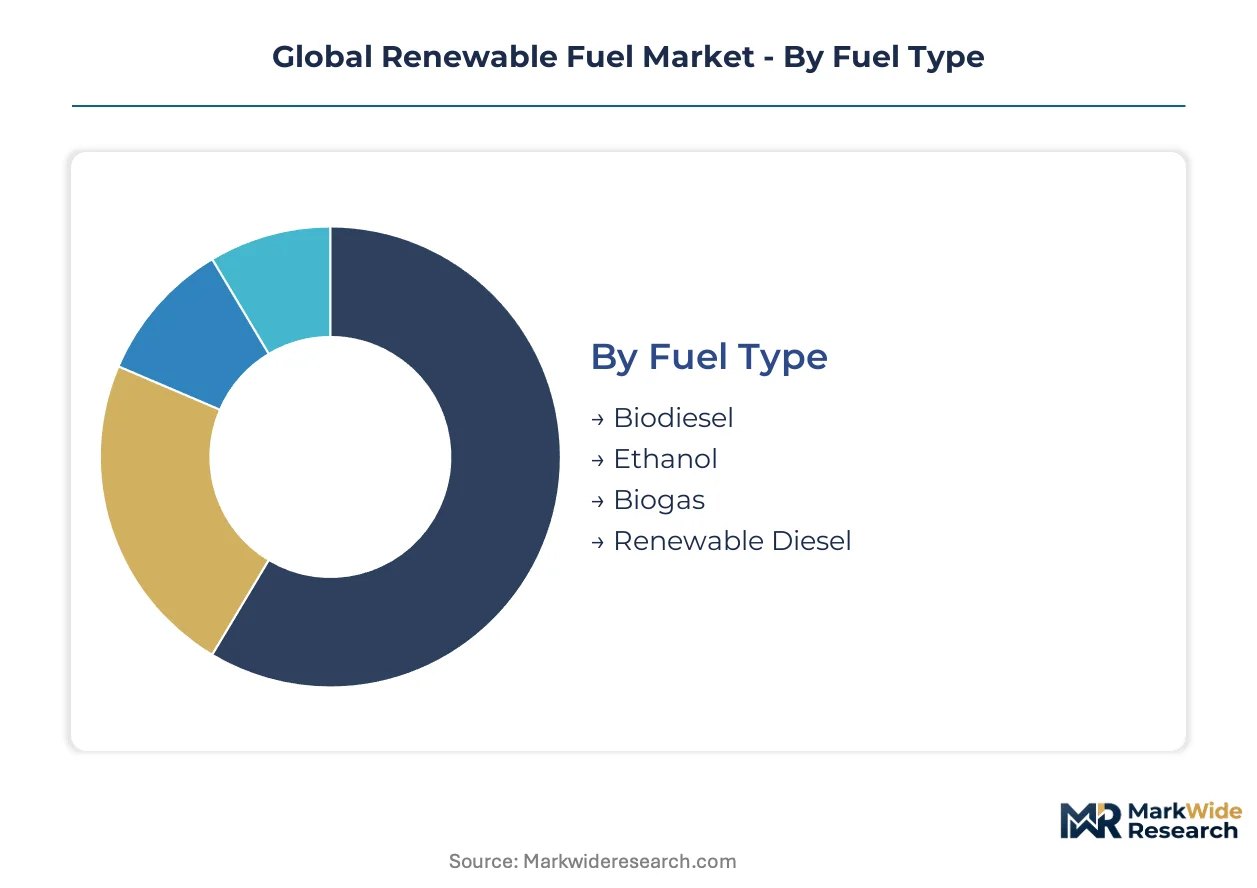
Segmentation in renewable fuels determines compliance pathways, infrastructure requirements, and margin profiles across divergent feedstock and end-use combinations. Each category carries distinct certification burdens from ISCC, RSB, or national regulators that shape procurement strategies and capital allocation decisions.
Fuel Type:
Certification intensity varies sharply across fuel categories, with drop-in hydrocarbons facing ASTM D7566 aviation approval and road transport fuels navigating national blending mandates.
- Renewable Diesel:Hydrotreated vegetable oils and animal fats achieve cetane specifications above 70, enabling seamless substitution in existing diesel engines without infrastructure modification. Demand concentrates in California and Oregon where Low Carbon Fuel Standard credits generate premium pricing above conventional diesel.
- Ethanol:Fermentation-derived alcohol from sugarcane and corn delivers octane enhancement at 10-15% blend rates in conventional gasoline pools. Brazil's flex-fuel vehicle fleet above 80% penetration creates captive consumption insulated from mandate volatility affecting US and European markets.
- Biodiesel:Fatty acid methyl esters produced through transesterification of vegetable oils meet ASTM D6751 specifications for blending up to 20% in conventional diesel.
- Biogas:Anaerobic digestion of organic waste streams yields methane-rich gas requiring upgrading to pipeline-quality biomethane specifications.
Ethanol sits at the top of the volume ranking, with renewable diesel climbing the fastest.
Delivery Mode:
Logistics infrastructure determines market access costs, with pipeline injection unlocking continuous offtake and truck transport serving distributed demand clusters.
- Pipeline:Dedicated renewable fuel pipelines and common-carrier systems enable bulk transfer from Gulf Coast production facilities to Midwest and Northeast demand centers. Germany and the Netherlands lead biomethane pipeline injection with standardized quality specifications that unlock residential heating contracts.
- Truck Transport:Tanker and tank wagon delivery serves retail fueling stations, industrial boilers, and agricultural equipment lacking pipeline connectivity. California's renewable diesel demand relies heavily on truck distribution from Los Angeles and San Francisco Bay Area terminals.
- Rail Transport:Unit trains and manifest service move ethanol from Iowa and Illinois production to coastal blending terminals.
- Barge Transport:Inland waterway movement along Mississippi River and European Rhine corridor serves refineries and storage hubs.
Pipeline delivery commands the highest margin per unit, with truck transport expanding most quickly into underpenetrated industrial zones.
End User:
Customer type dictates contract structures, with aviation offtake requiring long-term purchase agreements and residential markets favoring spot procurement.
- Transportation:Road, rail, aviation, and marine sectors consume liquid renewable fuels for combustion engines where electrification remains technically constrained. Sustainable aviation fuel procurement by European and North American carriers accelerates under EU Green Deal carbon intensity benchmarks.
- Industrial:Process heat applications in cement, steel, and chemical manufacturing utilize biomethane and renewable diesel for high-temperature combustion. German industrial clusters in North Rhine-Westphalia anchor biogas demand for combined heat and power installations.
- Power Generation:Grid-scale and distributed generation facilities burn biogas and liquid biofuels for dispatchable electricity.
- Residential:Space heating and cooking applications in rural areas without natural gas grid access consume compressed biomethane and liquid biofuels.
Transportation dominates volume consumption, with industrial offtake gaining share fastest through process heat decarbonization mandates.
Feedstock:
Raw material provenance determines lifecycle carbon intensity scores and eligibility for advanced biofuel quotas under regulatory frameworks.
- Vegetable Oils:Soybean, rapeseed, and palm oils serve as primary inputs for renewable diesel and biodiesel production through hydrotreating or transesterification. Southeast Asian palm oil supply concentration creates procurement risk for European producers facing sustainability certification disputes.
- Animal Fats:Tallow, poultry fat, and used cooking oil deliver lower carbon intensity scores than virgin vegetable oils under California LCFS methodology. Neste's Singapore facility processes substantial animal fat volumes for premium-credit renewable diesel output.
- Sugarcane:Brazilian crushing mills convert cane juice and molasses to ethanol with favorable energy balance ratios.
- Agricultural Residues:Corn stover, wheat straw, and forestry waste enable cellulosic ethanol and advanced biofuel production.
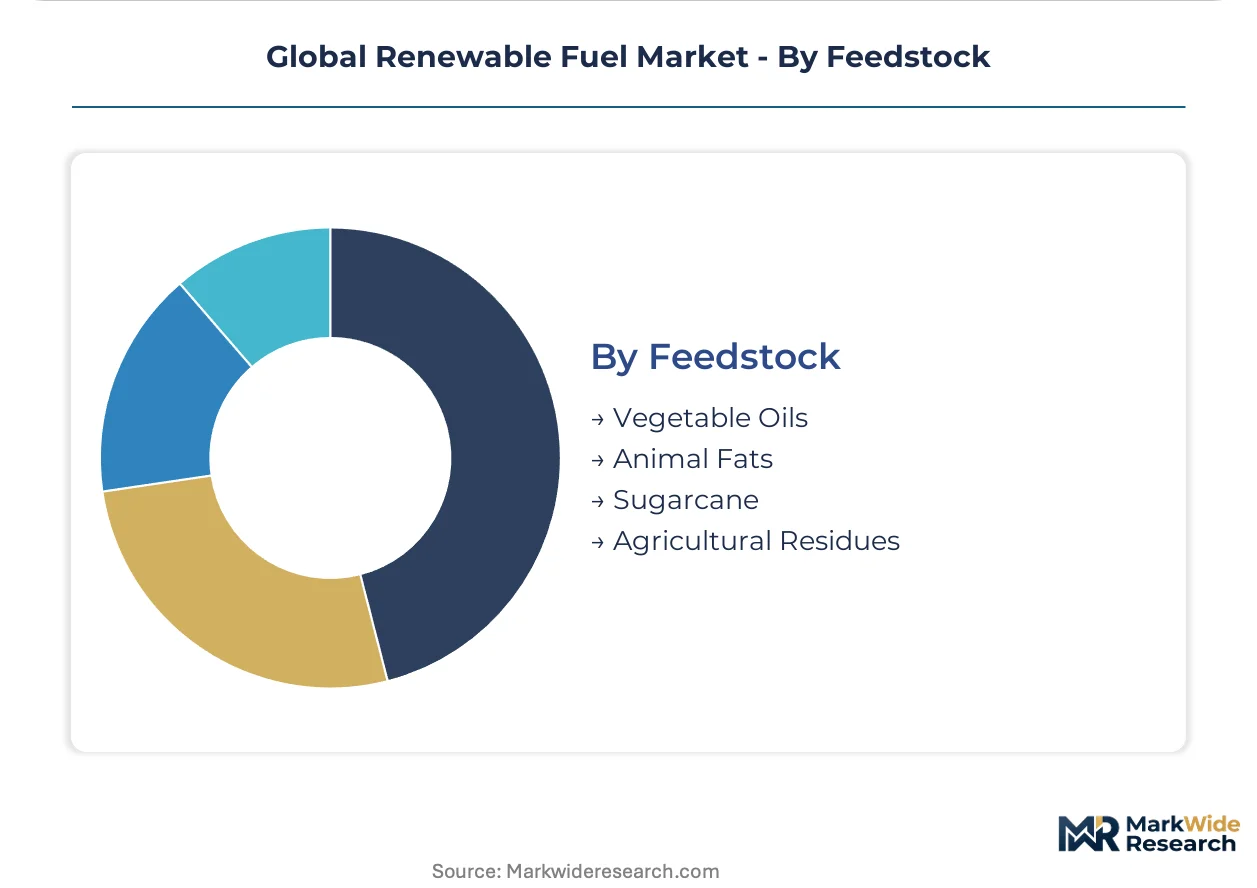
Vegetable oils lead feedstock utilization by volume, with agricultural residues expanding most quickly through advanced biofuel mandate escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast refining corridor anchors renewable diesel production capacity through integrated processing facilities serving California Low Carbon Fuel Standard markets. National blending mandates and carbon intensity regulations reshape procurement patterns across major consuming economies. Industrial clusters concentrate where pipeline infrastructure, feedstock logistics, and policy incentives align.
United States
California's Air Resources Board operates the Low Carbon Fuel Standard that generates tradable credits for renewable diesel and ethanol producers. The EPA administers Renewable Fuel Standard volume obligations mandating minimum biofuel blending across the gasoline and diesel pools. Gulf Coast processing facilities in Texas and Louisiana leverage existing refinery infrastructure for hydrotreating vegetable oils and animal fats into drop-in renewable diesel.
Brazil
Sugarcane ethanol infrastructure and flex-fuel vehicle penetration above 80 percent create captive consumption insulated from international mandate volatility. The National Petroleum Agency oversees blending requirements while supporting ethanol export parity mechanisms. São Paulo state crushing mills concentrate production capacity within 200 kilometers of flex-fuel vehicle manufacturing clusters in the ABC industrial region.
Germany
The EU Renewable Energy Directive II imposes escalating greenhouse-gas reduction thresholds for transport fuels consumed across German road and rail networks. ECHA REACH authorization requirements tighten compliance burdens for chemical intermediates used in advanced biofuel catalysts. North Rhine-Westphalia industrial clusters anchor biogas demand for combined heat and power installations serving cement and steel process heat applications.
Netherlands
Pipeline injection standards for biomethane unlock residential heating contracts and industrial offtake beyond traditional transport fuel markets. The national climate agreement mandates sector-specific emission reductions that pull biogas upgrading investment toward grid injection infrastructure. Rotterdam port terminals serve as consolidation points for waste oil and residue feedstocks destined for Northwest European renewable diesel facilities.
India
The national ethanol blending program targets 20 percent integration by 2025, creating feedstock demand that domestic sugarcane and grain surplus can supply. State-level excise incentives complement central procurement mechanisms administered through oil marketing companies. Maharashtra and Uttar Pradesh sugar belt cooperatives expand crushing capacity to capture ethanol procurement premiums above historical molasses valuations.
Global Renewable Fuel Market Competitive Environment
Capacity expansion dominates the current landscape as integrated refiners retrofit hydrotreating units for renewable diesel output. The market structure consolidates around petroleum majors with existing processing infrastructure and specialized biorefiners with dedicated feedstock sourcing capabilities. Three archetypes define competitive positioning: integrated oil companies leveraging legacy refining assets, agricultural processors controlling origination-to-fuel value chains, and pure-play renewable fuel specialists with proprietary conversion technologies. Geographic expansion into Southeast Asian feedstock markets and strategic partnerships for sustainable aviation fuel offtake represent the dominant competitive moves reshaping procurement relationships.
Among integrated petroleum majors, Shell plc and BP Plc exemplify the refinery-retrofit archetype through hydrotreater investments targeting Low Carbon Fuel Standard credit generation. Neste occupies a specialist position within the pure-play tier, having built proprietary NEXBTL technology around waste and residue feedstock processing at scale. These three companies represent divergent strategic postures: asset-heavy incumbents defending downstream position through fuel diversification versus technology-led challengers capturing premium margins in compliance-driven markets.
| Leading Market Players |
|---|
| Neste |
| Valero Energy Corp. |
| Chevron Corporation |
| Archer Daniels Midland Co. |
| Cargill Inc. |
| POET LLC |
| TotalEnergies SE |
| BP Plc |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
California Air Resources Board Low Carbon Fuel Standard credit premiums pull renewable diesel procurement toward waste and residue feedstocks, forcing supply chains to reconfigure around animal fat aggregation networks and used cooking oil collection infrastructure rather than virgin vegetable oil origination. This feedstock pivot compresses procurement timelines and elevates logistics costs as suppliers compete for geographically dispersed, low-density raw material streams.
Pricing Analysis
Input-cost pass-through dominates renewable fuel pricing, with vegetable oil and animal fat indices feeding directly into contract formulas for hydrotreated renewable diesel. Three-tier pricing structure across ISCC-certified premium, standard compliance, and economy feedstock tiers reflects carbon intensity scoring under California LCFS methodology. Pricing pressure stems from Southeast Asian palm oil sustainability certification disputes that restrict European refiner access to lower-cost virgin inputs. Industrial heat offtakers exhibit highest price sensitivity due to direct competition with natural gas, while aviation procurement departments absorb premiums for sustainable aviation fuel to secure book-and-claim certificate positions.
Supply Chain Analysis
Feedstock supply rests on Malaysian and Indonesian palm oil plantations, Brazilian sugarcane crushing mills, and North American animal rendering facilities for tallow and poultry fat inputs. Used cooking oil aggregation depends on restaurant and food processing sector collection networks across the United States and European Union member states. Single-source vulnerability concentrates in Southeast Asian palm oil sustainability certification disputes that trigger procurement disruptions for European renewable diesel producers. Distribution runs through Gulf Coast hydrotreating facilities, Rotterdam consolidation terminals, and dedicated renewable fuel pipelines serving California compliance markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through waste and residue feedstock processing premiums, as California LCFS credit generation and EU Renewable Energy Directive II advanced biofuel quotas elevate pricing for low-carbon intensity pathways above conventional vegetable oil alternatives.
For Market Incumbents: Deepen backward integration into animal fat rendering and used cooking oil collection infrastructure to secure captive feedstock supply against price volatility in virgin vegetable oil markets. Expand hydrotreating capacity at Gulf Coast facilities to capture California LCFS credit premiums before renewable diesel production capacity saturates compliance-driven demand pools. Prioritize ISCC certification investment to maintain eligibility for European advanced biofuel quotas under escalating greenhouse-gas reduction thresholds.
For New Entrants and Emerging Players: Begin with modular pyrolysis oil upgrading systems deployed at remote forestry operations in Sweden and Finland, collapsing feedstock logistics costs for distributed renewable diesel production. Target agricultural cooperative partnerships for corn stover and wheat straw aggregation to supply cellulosic ethanol pathways under Indian and EU advanced biofuel mandates. Pursue electrofuel synthesis integration combining green hydrogen with captured carbon dioxide for synthetic aviation fuel production with near-zero lifecycle emissions.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play renewable fuel specialists possessing proprietary conversion technologies and established waste and residue feedstock sourcing relationships. Five-to-ten-year viability hinges on sustained regulatory support for low-carbon fuel standards and carbon intensity benchmarking mechanisms across European and North American transport fuel markets. Monitor book-and-claim certificate trading volume and pricing as inflection indicator for sustainable aviation fuel demand maturation and environmental attribute market liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Aggregation | Captive supply of animal fats and used cooking oil insulates renewable diesel margins from virgin vegetable oil price spikes. |
| Modular Pyrolysis Deployment | Containerized reactor systems at Swedish forestry operations collapse feedstock logistics costs for distributed production. |
| Electrofuel Synthesis Investment | Green hydrogen and captured carbon dioxide integration enables synthetic aviation fuel with near-zero lifecycle emissions. |
| ISCC Certification Acceleration | Multi-jurisdictional audit completion unlocks European advanced biofuel quota eligibility and sustainable aviation fuel offtake contracts. |
| Long-term SAF Offtake Negotiation | Aviation refiner procurement departments mandate book-and-claim certificate systems decoupling physical delivery from emissions accounting. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with renewable diesel refinery operators, ethanol plant managers, biogas upgrading facility engineers, sustainable aviation fuel procurement officers, and Low Carbon Fuel Standard credit traders with secondary validation. EPA Renewable Fuel Standard volume obligation databases, California Air Resources Board LCFS credit transaction records, EU Renewable Energy Directive II implementation reports, and ISCC certification registry data anchored supply-side capacity and demand-side compliance analysis. Bottom-up facility-level production estimates and top-down regulatory mandate targets underwent cross-triangulation to resolve discrepancies.
Historical reference periods spanning renewable fuel standard implementation phases anchored the projection horizon, with segmentation across fuel type, feedstock provenance, delivery mode infrastructure, and end-use sector demand pools. CAGRs derived from facility expansion announcements, regulatory mandate escalation schedules, and carbon intensity benchmark trajectories under EU Green Deal and California LCFS frameworks. Modeled inputs incorporated hydrotreater retrofit timelines, enzymatic hydrolysis capacity buildout rates, and biomethane pipeline injection standard adoption curves.
Several conditions sit outside the modeled scope, including unannounced regulatory mandate suspensions, breakthrough electrochemical conversion technology commercialization, and geopolitical disruptions to Southeast Asian palm oil trade flows. Forecasts reflect documented assumptions regarding sustained low-carbon fuel standard enforcement and carbon credit market liquidity. A small set of named triggers warrants ongoing watch: EU Renewable Energy Directive III negotiation outcomes, California LCFS carbon intensity benchmark acceleration decisions, and sustainable aviation fuel book-and-claim certificate trading market development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Hydrotreated Vegetable Oil Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Sustainable Fuel Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Hydrogen Furnace Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Aviation Alternative Fuel Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Sustainable Marine Fuel Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
Global Carbon-Neutral Fuels Market
Alternative Fuels
Green Diesel Market