
 India Oil and Gas Downstream Market | 2026-2036
India Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
India Oil and Gas Downstream Market Foresight
Gujarat is reconfiguring India's downstream geography through major refinery complexes and petrochemical integration zones. Reliance Industries Ltd dominates the Jamnagar refining hub with unmatched scale and complexity. Indian Oil Corporation Ltd anchors the public sector landscape through its pan-India refining and marketing network. Bharat Petroleum Corporation Ltd differentiates via specialized product streams and coastal logistics advantages.
India Oil and Gas Downstream encompasses the conversion of crude oil into refined products through fractional distillation, catalytic cracking, and hydroprocessing, yielding fuels and petrochemical feedstocks with specified sulfur content and octane ratings. The sector serves transportation, power generation, and manufacturing industries across India's industrial base. Diesel and petrol within the product type dimension command the largest volume pools, while LPG exhibits structural expansion tied to residential energy transition programs. The service type dimension shows refining operations capturing the dominant capital allocation, though logistics and distribution infrastructure attract incremental investment to bridge supply gaps in eastern and northeastern states.
The Petroleum and Natural Gas Regulatory Board, the Bureau of Indian Standards, and the Central Pollution Control Board collectively shape product specifications, pipeline access rules, and emission thresholds for refiners and marketers. Compliance with BIS fuel quality norms and PNGRB infrastructure codes determines operational permissions and market entry conditions. Stakeholders must track regulatory timelines for Bharat Stage VI emission norms and biofuel blending mandates to align capacity planning with enforceable product standards.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's open access guidelines are fragmenting pipeline monopolies and forcing incumbents to surrender captive infrastructure to third-party users, compressing logistics margins while expanding market contestability.
Growth Catalysts
- Biofuel blending mandates:The government's ethanol blending program is pulling agricultural feedstocks into fuel supply chains and mandating refinery retrofit investments.
- Maharashtra industrial corridor demand:Manufacturing clusters around Mumbai-Pune are consuming rising volumes of industrial naphtha and specialty solvents.
- Catalytic cracking upgrades:Fluid catalytic cracking unit expansions at western refineries are lifting light distillate yields to match transport fuel demand profiles.
Market Restraints
- Crude import dependency:Near-total reliance on West African and Middle Eastern crude exposes refiners to freight rate volatility and currency fluctuation.
- Gujarat supply concentration:Over half of national refining capacity sits within a 200-kilometer coastal band, creating catastrophic risk exposure.
- BIS fuel quality compliance costs:Successive sulfur reduction mandates require continuous hydrotreater investments without corresponding product premium capture.
Strategic Opportunities
- Eastern India pipeline gaps:Bihar, Odisha, and West Bengal lack adequate product pipeline connectivity, creating terminal and coastal barge logistics openings.
- Petrochemical integration:Polymer demand from packaging and automotive sectors is pulling refiners downstream into propylene and aromatics production.
- PLI scheme for specialty chemicals:Production-linked incentives for advanced chemistry manufacturing are drawing capital toward import-substituting intermediates.
Industry Challenges
- Process control engineering scarcity:Refinery digitization and advanced process control implementation face acute shortages of instrumentation specialists.
- Hydrocracker turnaround coordination:Synchronized maintenance windows across multiple units strain contractor availability and spare parts inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Oil and Gas Downstream Market |
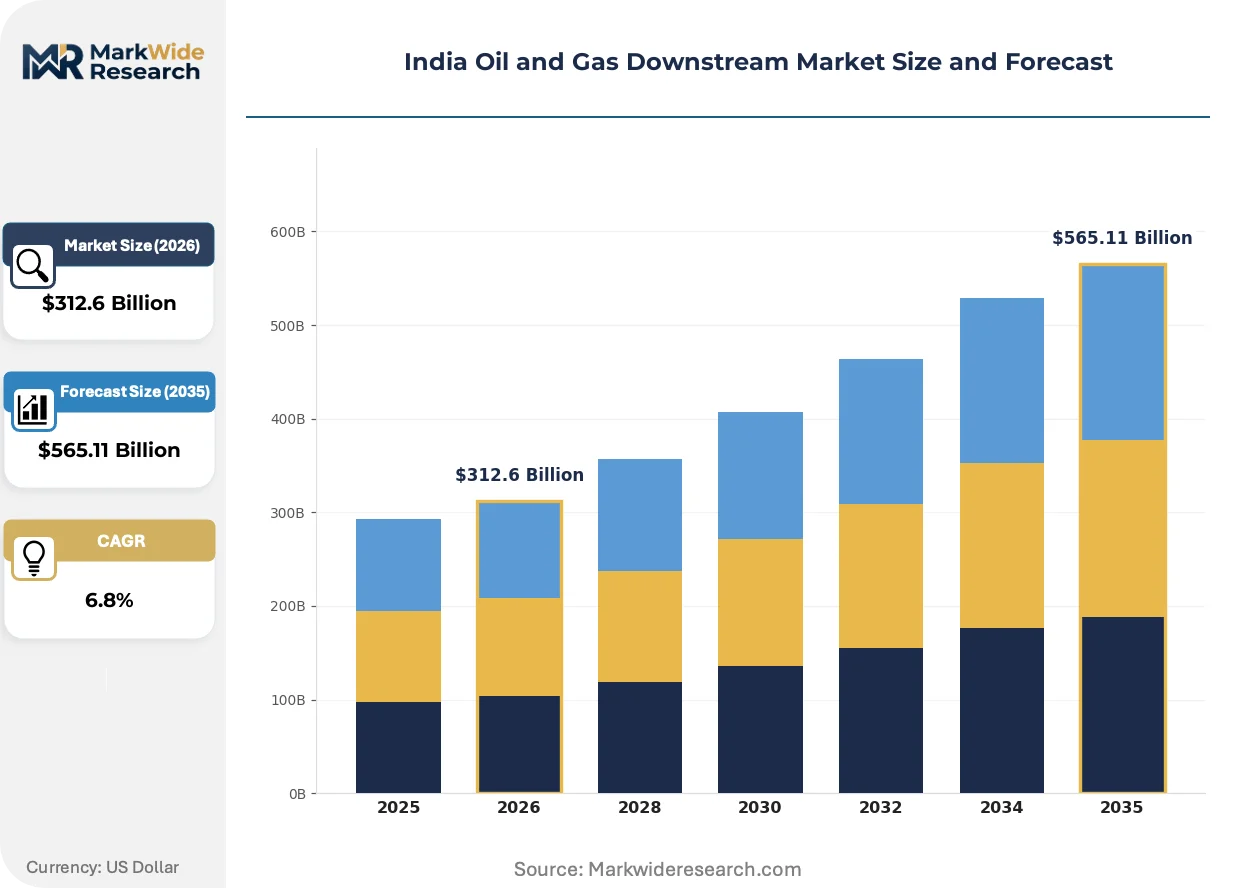
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petrol, Diesel, Kerosene, LPG Application: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail Outlets, Direct Supply, B2B, E-commerce Service Type: Refining, Distribution, Trading, Logistics |
| Companies Covered | Reliance Industries Ltd, Chennai Petroleum Corporation Ltd, Indian Oil Corporation Ltd, HPCL-Mittal Energy Ltd, Mangalore Refinery & Petrochemicals Ltd, Bharat Petroleum Corporation Ltd, Nayara Energy Ltd, Numaligarh Refinery Ltd, Hindustan Petroleum Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Oil and Gas Downstream Market Shifts & Advancements
Digital instrumentation and emissions monitoring systems are penetrating refinery operations at accelerating rates, compressing the gap between process data generation and real-time optimization decisions.
Advanced process control software is digitizing crude unit distillation and reactor temperature management across Indian Oil Corporation and Bharat Petroleum facilities. Operations teams are deploying these platforms to reduce energy intensity and product giveaway. The technology is digitizing legacy analog control loops into model-predictive frameworks that adjust feed rates automatically.
The Bureau of Indian Standards is tightening particulate matter and nitrogen oxide emission thresholds for combustion equipment at refining complexes. Refiners must install continuous emissions monitoring systems and submit verified data to state pollution control boards. Coastal Gujarat facilities face the most stringent compliance timelines due to their proximity to sensitive marine ecosystems.
Industrial buyers of furnace oil and bitumen are consolidating procurement through long-term supply contracts with fixed differentials to Platts benchmarks. Small and mid-sized manufacturing units are exiting spot market purchases in favor of integrated supply agreements with storage-and-delivery provisions. Tamil Nadu textile and cement clusters exhibit the most pronounced shift toward contractual sourcing.
India Oil and Gas Downstream Market Segmentation
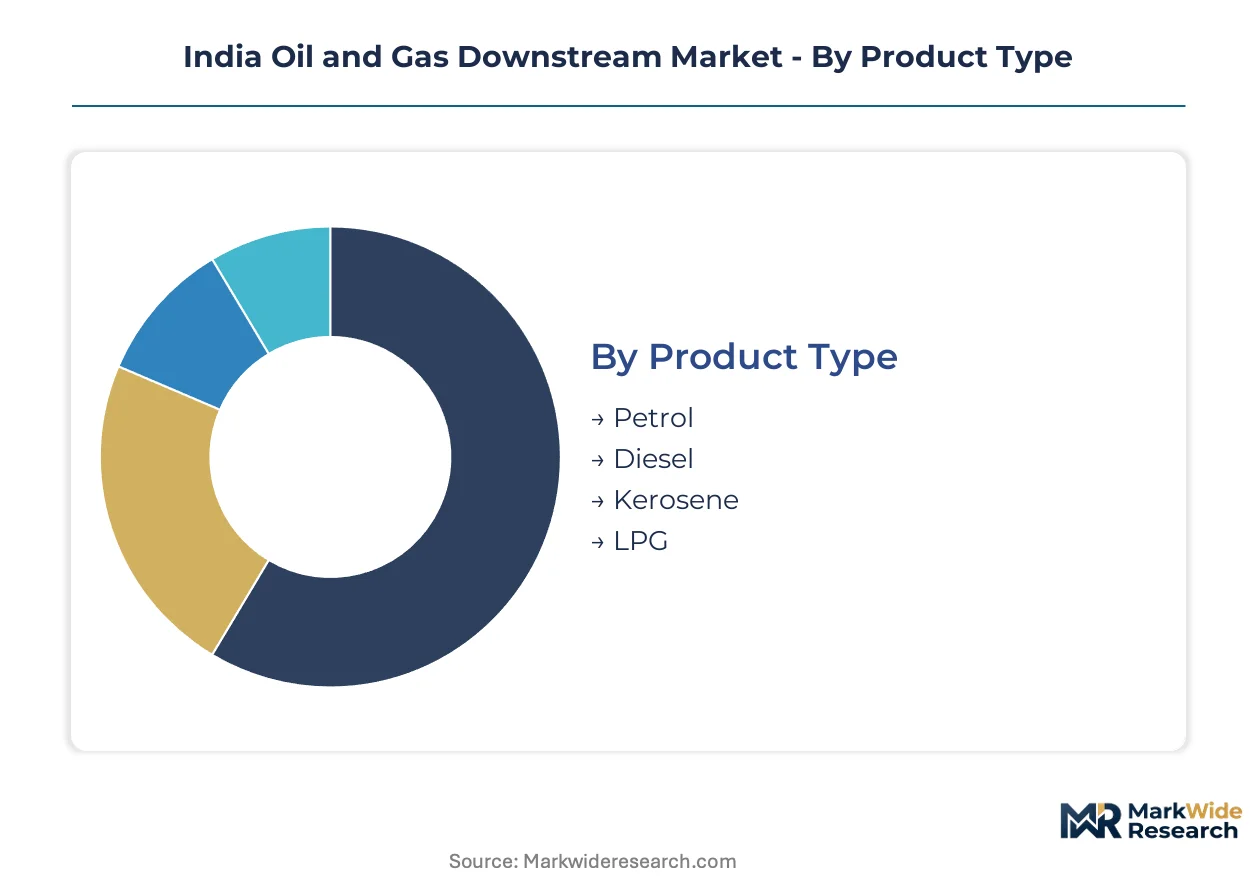
Segmentation in India's downstream oil and gas sector reveals how refining complexity, logistics infrastructure, and end-use concentration shape capital allocation across product streams and service layers. Understanding these divisions exposes where margin compression and expansion pressures concentrate for processors and distributors.
Product Type:
After-sales service intensity varies sharply across fuel types, with diesel requiring bulk delivery logistics and LPG demanding cylinder exchange networks that tie refiners to last-mile operations.
- Diesel:High-cetane middle distillate serving freight transport, agricultural pumps, and backup power generation across Gujarat and Maharashtra industrial belts. Demand concentrates in long-haul trucking corridors where Bharat Stage VI sulfur specifications have forced hydrotreater investments at Jamnagar and Vadodara refineries.
- Petrol:Light distillate formulated for octane ratings between 91 and 95, consumed predominantly by two-wheeler and passenger vehicle fleets in urban Maharashtra and Tamil Nadu clusters. Mumbai-Pune expressway traffic volumes and Delhi-NCR congestion patterns dictate regional blending formulations and storage terminal positioning.
- LPG:Liquefied petroleum gas distributed through subsidized domestic cylinder networks and commercial bulk installations, with PMUY rural connections expanding the addressable base in Bihar and Uttar Pradesh.
- Kerosene:Illuminating and cooking fuel facing structural demand erosion as electrification and LPG substitution advance in rural Odisha and West Bengal markets.
Diesel holds the largest share; momentum sits with LPG as residential energy transition programs accelerate cylinder penetration.
Application:
Cost tier differentiation separates industrial buyers seeking long-term contracts with fixed Platts differentials from residential consumers locked into regulated pricing frameworks.
- Transportation:Road, rail, and marine fuel consumption dominating volume offtake, with state transport undertakings in Tamil Nadu and Karnataka anchoring bulk diesel procurement through tender mechanisms.
- Industrial:Manufacturing furnaces, process heat, and captive power generation consuming furnace oil, naphtha, and petrochemical feedstocks across Mumbai-Pune chemical belts and Gujarat specialty chemical zones.
- Residential:Cooking and heating applications concentrated in LPG cylinder networks and piped natural gas transitions in Delhi, Mumbai, and Hyderabad urban agglomerations.
- Commercial:Hospitality, retail, and institutional fuel demand spanning diesel generator sets and LPG for food service in tier-2 city expansion corridors.
Transportation commands volume leadership; industrial applications are climbing the fastest as manufacturing reshoring intensifies.
Distribution Channel:
Customer type fragmentation splits between price-sensitive retail motorists and volume-committed industrial buyers with diverging logistics requirements.
- Retail Outlets:Company-owned and dealer-operated petrol pumps constituting the dominant customer touchpoint, with Indian Oil Corporation and Bharat Petroleum networks covering national highways and district headquarters.
- B2B:Direct commercial relationships with fleet operators, mining companies, and state electricity boards purchasing diesel and furnace oil through annual supply agreements with embedded storage provisions.
- Direct Supply:Pipeline-delivered products to industrial consumers and aviation fuel through into-plane arrangements at Chennai, Mumbai, and Delhi airports.
- E-commerce:Emerging digital platforms for LPG cylinder booking and lubricant sales, penetrating urban convenience segments without displacing physical infrastructure.
Retail outlets maintain the deepest penetration; B2B channels are gaining share fastest as procurement consolidation accelerates.
Service Type:
Supply concentration in refining operations concentrates capital intensity and regulatory exposure, while logistics services fragment across pipeline, coastal, and road modalities.
- Refining:Crude distillation, catalytic cracking, and hydroprocessing operations converting imported West African and Middle Eastern grades into specification products, with complexity differentials determining margin capture at Jamnagar and Kochi facilities.
- Logistics:Product movement through PNGRB-regulated pipelines, coastal tankers, and road tankers bridging the eastern India connectivity gap where pipeline infrastructure remains underdeveloped.
- Distribution:Terminal operations, depot management, and last-mile delivery coordination ensuring product availability across retail and commercial networks.
- Trading:Spot and term crude procurement, product arbitrage, and inventory optimization functions managing import dependency and currency exposure.
Refining captures the dominant capital allocation; logistics exhibits the steepest expansion trajectory as eastern infrastructure gaps attract incremental investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Petroleum and Natural Gas Regulatory Board anchors western India's downstream dominance through pipeline access regulations and coastal refinery zoning. State-level industrial policies in Maharashtra and Gujarat determine petrochemical cluster formation. Eastern connectivity gaps persist despite incremental infrastructure commitments.
Maharashtra
Mumbai-Pune manufacturing corridors consume industrial naphtha and specialty solvents for chemical processing. The state's industrial policy incentivizes refinery-petrochemical integration through land allocation preferences. Ratnagiri and Raigad coastal zones host import terminals serving hinterland demand clusters.
Gujarat
Jamnagar and Vadodara refining complexes process West African and Middle Eastern crude grades for national product supply. Coastal regulation zones administered by the Gujarat Maritime Board govern tanker movements and storage farm expansions. Dahej and Hazira industrial estates concentrate polymer demand from packaging converters.
Tamil Nadu
Chennai-Coimbatore industrial belts drive diesel consumption through textile processing and automotive component manufacturing. State pollution control mandates enforce sulfur emission thresholds at Manali refinery operations. Ennore port logistics infrastructure handles product imports for southern distribution networks.
West Bengal
Haldia petrochemical zone absorbs naphtha feedstocks for synthetic fiber and plasticizer production. The Eastern India pipeline deficit forces reliance on coastal barge movements from Paradip and Visakhapatnam. Durgapur-Asansol manufacturing corridor exhibits latent demand for furnace oil and bitumen.
Odisha
Paradip refinery capacity expansions target eastern product supply gaps in Bihar and Jharkhand markets. State mineral processing industries consume diesel for iron ore and bauxite logistics. Bhubaneswar-Cuttack urbanization drives LPG cylinder demand through PMUY rural connection programs.
India Oil and Gas Downstream Market Competitive Landscape
Capability concentration sits with integrated petrochemical operators; scale advantage sits with national marketing network holders. The market structure bifurcates between coastal refining specialists with complexity premiums and pipeline-anchored distributors with geographic reach. Three archetypes dominate: complexity-led integrated refiners, logistics-captive marketers, and niche petrochemical feedstock suppliers. Competitive moves center on catalytic cracking upgrades and eastern terminal acquisitions.
Within the integrated complexity tier, Reliance Industries Ltd and Indian Oil Corporation Ltd occupy anchor positions. Reliance exemplifies the petrochemical-backward archetype through Jamnagar scale. Indian Oil represents the national distribution network model with pan-India depot coverage. Bharat Petroleum Corporation Ltd sits within the coastal logistics specialist category.
| Leading Market Players |
|---|
| Reliance Industries Ltd |
| Chennai Petroleum Corporation Ltd |
| Indian Oil Corporation Ltd |
| HPCL-Mittal Energy Ltd |
| Mangalore Refinery & Petrochemicals Ltd |
| Bharat Petroleum Corporation Ltd |
| Nayara Energy Ltd |
| Numaligarh Refinery Ltd |
| Hindustan Petroleum Corporation Ltd |
| Others |
Supply & Pricing Matrix
Hazira-Dahej coastal freight corridors transmit Jamnagar refinery output to Gujarat industrial estates at rates that compress logistics margins while amplifying price differentiation between pipeline-served western markets and barge-dependent eastern zones. This freight-cost geography concentrates pricing power with coastal complexity leaders and forces inland distributors to absorb transport premiums or surrender volume.
Pricing Analysis
Western India diesel quotes trade at persistent discounts to eastern Bihar and West Bengal markets due to Paradip-Haldia barge economics and pipeline access asymmetry. Contract-based long-term offtake dominates industrial procurement, with Platts-linked differentials widening for buyers lacking storage infrastructure. Price differentiation rests on volume scale and geographic delivery cost, with small manufacturing units in Tamil Nadu textile clusters facing the steepest sensitivity. Cost compression in furnace oil is intensifying because cement and bitumen buyers are consolidating procurement through integrated supply agreements.
Supply Chain Analysis
Reliance Industries and Indian Oil Corporation hold captive refining capacity across Jamnagar, Vadodara, and Panipat complexes, with no significant third-party tolling available for specialty batches. Crude supply draws from West African and Middle Eastern grades, with freight rates and rupee-dollar volatility transmitting directly to import parity pricing. Single-source vulnerability concentrates in the Jamnagar coastal band where over half of national capacity faces catastrophic risk exposure. Distribution runs through PNGRB-regulated pipelines, coastal tankers, and road bridging for eastern deficit states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in eastern logistics infrastructure where pipeline gaps force manufacturing clusters into costly spot procurement. PMUY rural LPG expansion and Maharashtra industrial corridor demand are creating niche entry points for terminal operators and coastal barge specialists.
For Market Incumbents: Build regulatory moat through PNGRB pipeline certification and BIS fuel quality compliance investments ahead of Bharat Stage VI tightening. Defensive consolidation should target eastern terminal acquisitions in Bihar and Odisha to preempt new entrant logistics positioning. Hydrotreater capacity additions at Kochi and Chennai refineries will anchor margin defense against complexity premiums at Jamnagar.
For New Entrants and Emerging Players: Pursue coastal barge logistics contracts serving Haldia-Durgapur manufacturing corridors where pipeline infrastructure remains underdeveloped. White-space targets include LPG cylinder distribution networks in Uttar Pradesh and Bihar PMUY expansion zones, plus specialty solvent supply to Mumbai-Pune chemical belts. Go-to-market positioning should emphasize fixed-differential Platts contracts with embedded storage provisions for small and mid-sized textile and cement buyers.
For Investors and Strategic Acquirers: Carve-out targets emerge from public sector downstream subsidiaries with stranded eastern assets and underutilized terminal infrastructure. Long-term viability frames around petrochemical integration depth and regulatory capture in pipeline access rules. Acquisition archetypes include coastal logistics specialists with Hazira-Ratnagiri coastal positioning. Watch biofuel blending mandate enforcement timelines as inflection indicator for ethanol supply chain investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Cracking Upgrade | Fluid catalytic cracking expansions at western refineries lift light distillate yields to match transport fuel demand profiles. |
| Eastern Terminal Acquisition | Pipeline deficit states offer terminal and coastal barge logistics openings for supply chain positioning. |
| Petrochemical Integration | Polymer demand from packaging and automotive sectors pulls refiners downstream into propylene production. |
| Biofuel Blending Compliance | Ethanol program mandates pull agricultural feedstocks into fuel supply chains and require refinery retrofits. |
| Long-term Supply Contracting | Industrial buyers consolidate procurement through fixed-differential agreements to exit volatile spot markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across refining operations, terminal logistics, and industrial procurement functions. Primary interviews captured perspective from refinery operations managers, PNGRB regulatory affairs leads, downstream chemical procurement directors, and coastal shipping operators. Secondary validation drew from Petroleum and Natural Gas Regulatory Board pipeline access filings, Bureau of Indian Standards fuel quality notifications, Central Pollution Control Board emission compliance records, and customs crude import data. Bottom-up capacity modeling and top-down demand aggregation were triangulated to reconcile volume estimates.
Calibration anchored volume projections to refinery throughput disclosures and regional demand clustering across industrial corridors. Segmentation dimensions modeled include product type, application end-use, distribution channel, and service layer complexity. CAGRs were derived from capacity expansion timelines and demand elasticity assumptions across the projection horizon. Industry-specific forecast inputs incorporated biofuel blending mandate enforcement schedules and Bharat Stage VI sulfur reduction compliance costs.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, West African crude freight indices, or agricultural commodity prices for ethanol feedstocks would shift the trajectory. Forecasts reflect assumptions around regulatory timeline adherence and infrastructure commissioning schedules. Quarterly review of PNGRB pipeline access rulings, BIS specification amendments, and refinery turnaround announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Subsea Production and Processing System Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Marine Seismic Equipment and Acquisition Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market