
 Anthracite Coal Mining Market | 2026-2036
Anthracite Coal Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Anthracite Coal Mining Market Analysis
Buyer concentration among steel manufacturers is decoupling from traditional power-utility offtake as metallurgical coal contracts command premium terms. Sibanthracite Group leverages its Siberian deposit scale to dominate seaborne premium anthracite exports. Mechel PAO anchors Russian domestic supply through captive rail and port infrastructure. China Shenhua Energy Company controls the world's largest anthracite reserves through integrated longwall operations.
Anthracite coal refers to the highest-rank metamorphic coal containing 86–92 percent fixed carbon, volatile matter below 8 percent, and energy content exceeding 24 MJ/kg, valued for smokeless combustion and metallurgical reduction. Metallurgical coal segments sustain margin pools as blast furnace operators prioritize low-phosphorus, high-coke-strength material for steel quality. Underground mining leads extraction method share where seam depth exceeds 300 meters and surface disturbance restrictions apply. Power generation segments face structural decline in OECD markets while industrial heating segments compete against natural gas conversion in Eastern Europe.
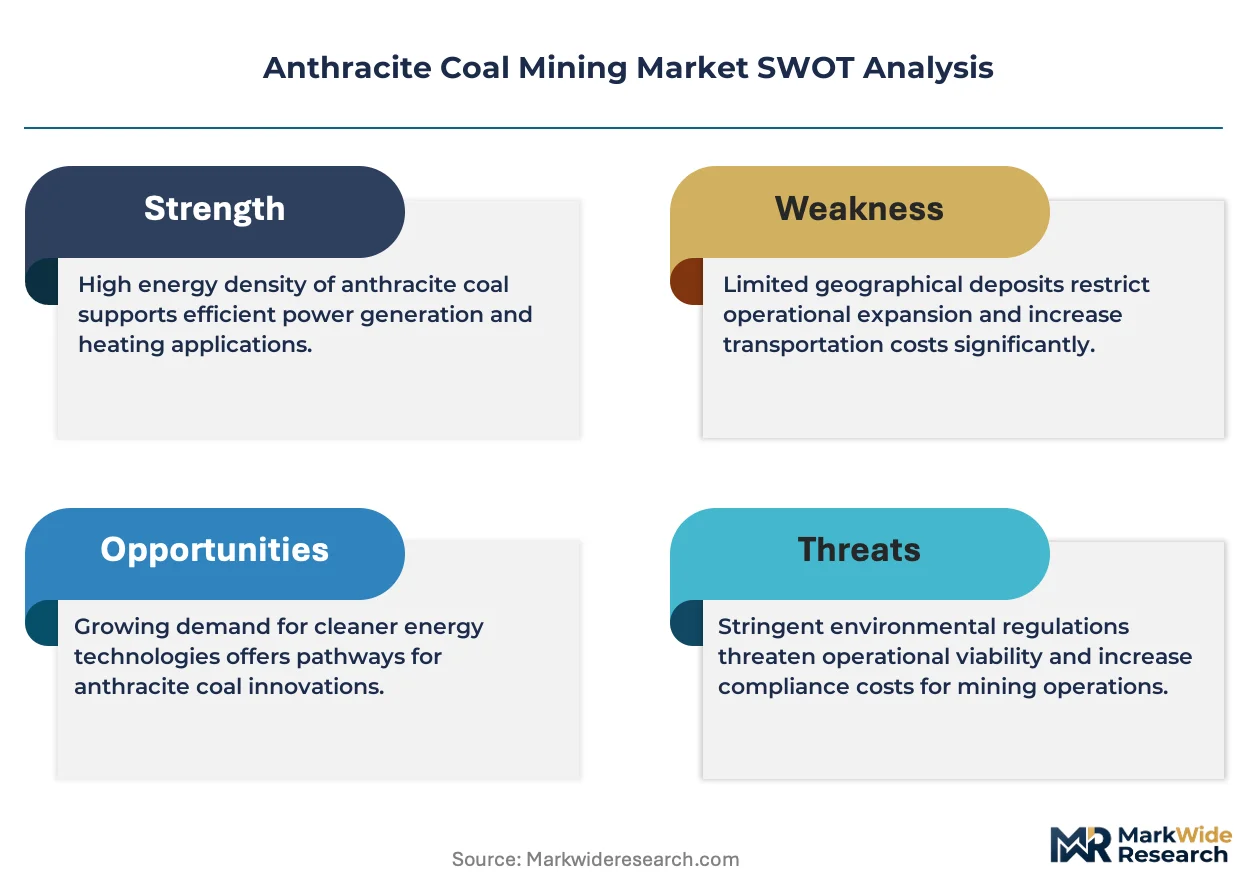
EPA emissions standards in the United States restrict sulfur dioxide and particulate releases from anthracite combustion, redirecting domestic supply toward metallurgical export markets. China's MEE enforces mine safety and rehabilitation bonds that raise capital barriers for small-scale operators. Vietnam's CEA oversees Vinacomin's production quotas and export licensing for northern anthracite basins. Stakeholders must monitor regulatory divergence between metallurgical exemption pathways and thermal coal phase-out timelines across producing jurisdictions.
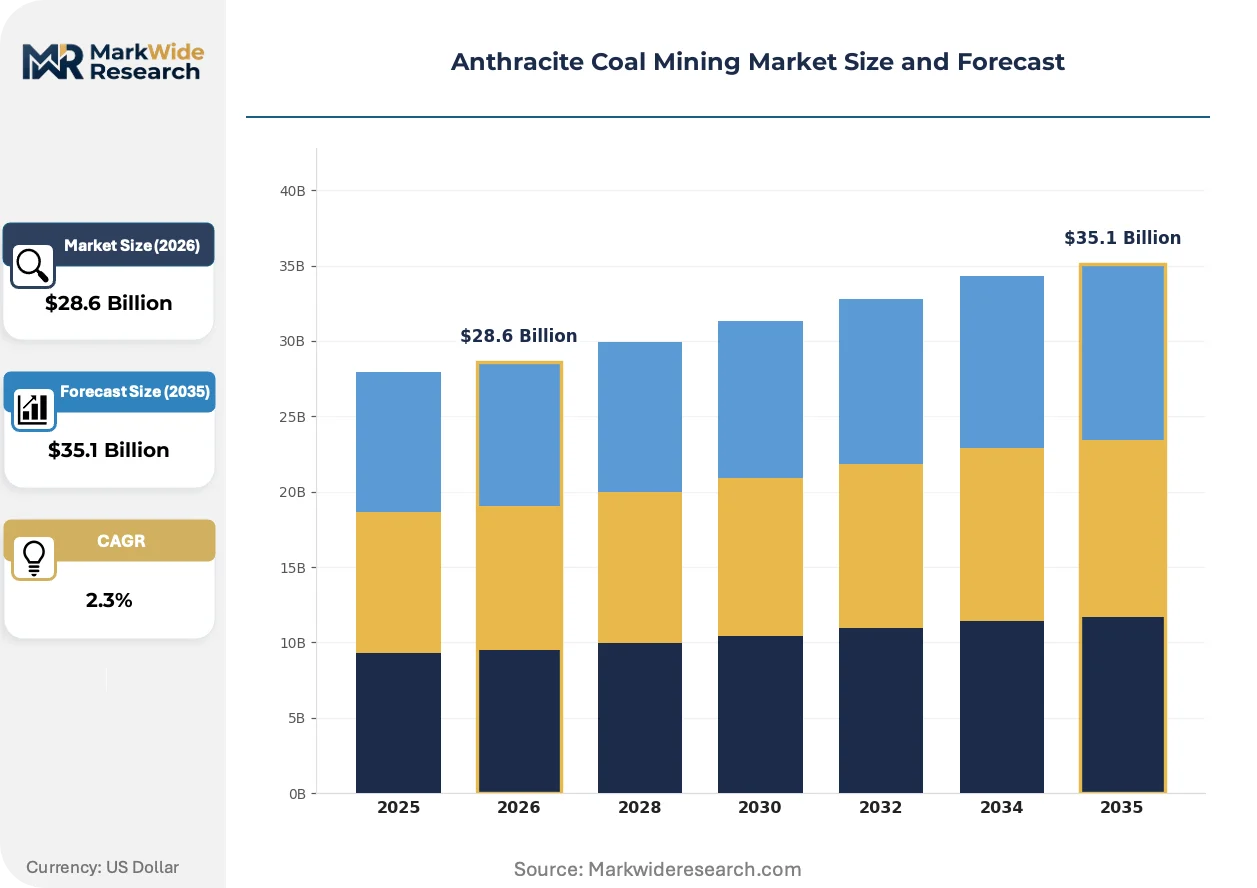
Market Dynamics
Steel manufacturers in East Asia are decoupling procurement from traditional power-utility offtake, redirecting premium anthracite flows toward metallurgical contracts as emissions protocols tighten across industrial basins.
Growth Catalysts
- Vietnam's CEA Production Quotas:Vinacomin expands captive supply for metallurgical buyers in northern coal basins, anchoring regional seaborne trade.
- Blast Furnace Operators:Prioritization of low-phosphorus, high-coke-strength material for steel quality sustains margin pools in premium segments.
- Underground Extraction Methods:Surface permit restrictions and stricter environmental review processes drive preference for deep-seam operations where depth exceeds 300 meters.
Market Restraints
- Natural Gas Substitution:Industrial heating segments in Eastern Europe face competitive pressure from pipeline gas conversion, eroding thermal coal offtake.
- Capital Barriers:China's MEE mine safety and rehabilitation bonds raise entry costs for small-scale operators, consolidating production among state-backed incumbents.
- OECD Thermal Decline:Power generation segments face structural demand erosion as grid operators accelerate renewable dispatch and retire coal-fired capacity.
Strategic Opportunities
- Metallurgical Exemption Pathways:Regulatory divergence between thermal phase-out timelines and steel industry carve-outs creates arbitrage windows for premium exporters.
- Seaborne Premium Positioning:Siberian deposit scale enables dominance in high-carbon, low-volatile export grades serving East Asian steel mills.
- Captive Infrastructure Control:Integrated rail and port assets allow supply chain bypass of congested third-party terminals.
Industry Challenges
- Longwall Automation Skills Gap:Underground operations require specialized technicians for automated cutting and roof support systems, constraining output scaling.
- Rehabilitation Bond Timing:Closure liability accounting compresses project IRRs and extends capital recovery periods for greenfield developments.
- Emissions Compliance Integration:EPA sulfur dioxide and particulate standards require retrofitted scrubber installations at legacy preparation plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthracite Coal Mining Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $35.1 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Coal, Metallurgical Coal, Semi-Anthracite, Coking Coal End User: Power Generation, Steel Manufacturing, Cement Production, Industrial Heating Extraction Method: Surface Mining, Underground Mining, Room and Pillar Mining, Longwall Mining Market Channel: Direct Sales, Distributors, Online Platforms, Wholesale |
| Companies Covered | Sibanthracite Group, Mechel PAO, China Shenhua Energy Company, Sadovaya Group, Lehigh Anthracite, Reading Anthracite Company, Yanzhou Coal Mining Company, Vinacomin - Vietnam National Coal & Mineral Industries Group, Blaschak Coal Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthracite Coal Mining Market Emerging Trajectories
Automation and regulatory bifurcation are compressing the operational frontier for anthracite producers, while procurement concentration among steel mills reconfigures contract structures away from spot thermal markets.
Longwall automation systems with remote-operated shearers and real-time roof monitoring are consolidating extraction economics at depths beyond 300 meters. Vietnamese and Russian operators deploy these systems most aggressively, reducing labor intensity and face downtime. The technology is consolidating production share among capital-rich incumbents capable of amortizing sensor and control infrastructure across multi-panel reserves.
China's MEE enforcement of dual carbon goals and mine rehabilitation bonds is redirecting investment toward state-consolidated operators with balance-sheet capacity for compliance. Smaller private mines face forced closure or absorption, concentrating output among Vinacomin and Shenhua-tier producers. Metallurgical coal segments gain regulatory insulation relative to thermal grades, widening the premium spread for low-volatile anthracite.
Steel mill procurement teams are compressing contract durations and unbundling logistics from material pricing, shifting risk to suppliers. Long-term offtake agreements with fixed rail and port commitments are displacing annual spot negotiations for premium grades. This pattern concentrates most visibly in Vietnam's northern basins and East Asian port clusters where blast furnace operators seek supply security amid import dependency.
Anthracite Coal Mining Market Segmentation
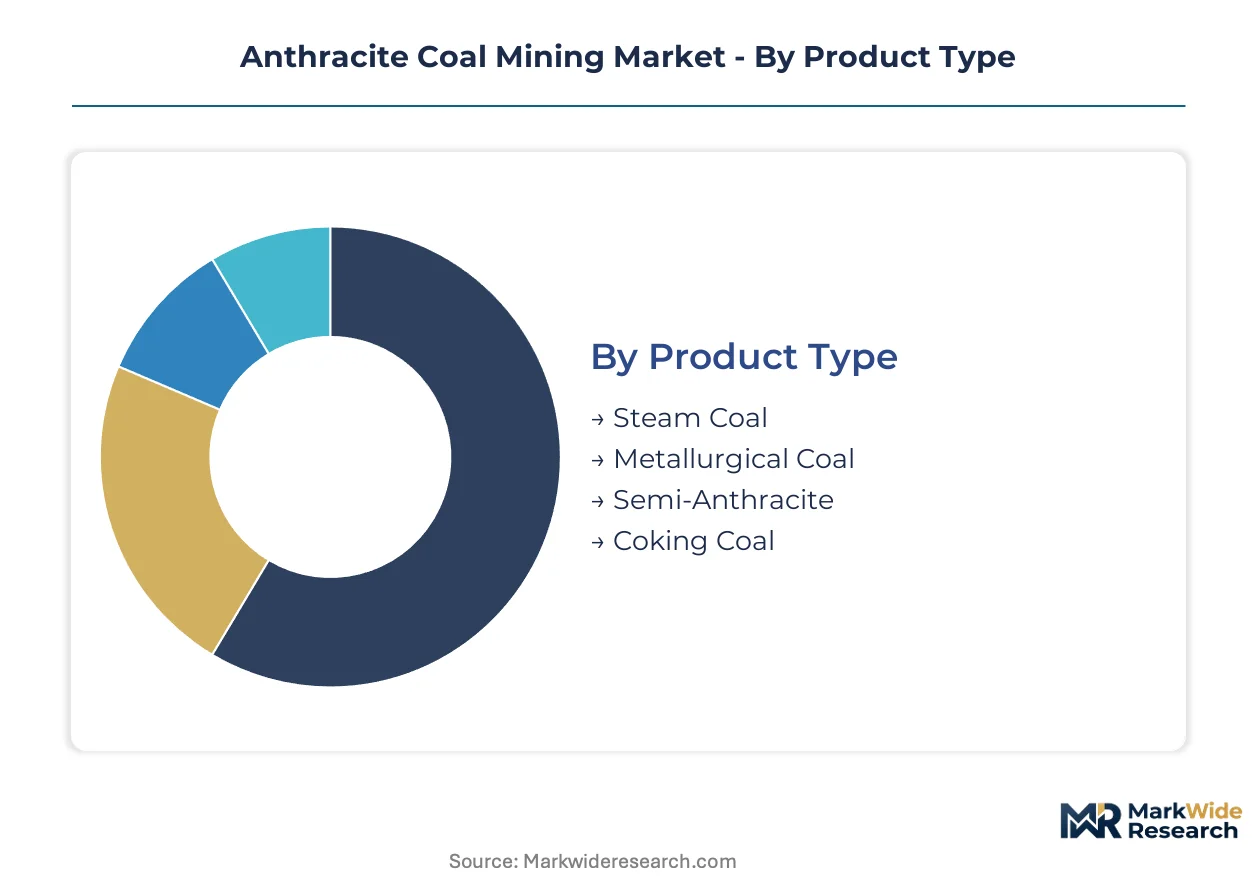
Anthracite coal mining segments diverge sharply between metallurgical and thermal applications, with buyer procurement criteria driving fundamentally different contract structures and margin profiles across each category.
Product Type:
Buyer specifications for carbon content and volatile matter dictate sourcing decisions, with steel mills paying premiums for low-phosphorus grades while power utilities prioritize cost efficiency over chemical purity.
- Metallurgical Coal:Contains 86–92 percent fixed carbon with volatile matter below 8 percent, delivering the high coke strength required for blast furnace reduction chemistry. Steel manufacturers in Vietnam's northern basins and East Asian port clusters anchor demand through multi-year offtake agreements with fixed rail commitments.
- Coking Coal:Blends with metallurgical grades in coke oven batteries to control reactivity and mechanical strength of the final coke burden. Blast furnace operators in coastal China and Japan specify precise blend ratios, creating arbitrage windows for premium exporters with consistent quality assays.
- Steam Coal:Lower-grade anthracite with higher volatile content serves industrial boilers and legacy power stations facing natural gas substitution pressure in Eastern Europe.
- Semi-Anthracite:Intermediate carbon rank bridges thermal and metallurgical applications, finding niche demand in cement kiln firing where flame temperature requirements sit below steelmaking thresholds.
Metallurgical coal leads on scale; coking coal leads on momentum as steel quality specifications tighten.
End User:
Application-specific combustion requirements and regulatory exposure split the customer base between structurally declining thermal segments and metallurgically insulated growth pools.
- Steel Manufacturing:Blast furnace and electric arc furnace operations consume premium low-volatile anthracite for coke production and direct injection. East Asian steel mills decouple procurement from power utility offtake patterns, compressing contract durations while demanding unbundled logistics pricing.
- Industrial Heating:Brick kilns, lime calciners, and specialty ceramics manufacturers rely on smokeless combustion properties in jurisdictions with particulate restrictions. Eastern European industrial clusters face accelerating natural gas conversion as pipeline infrastructure expands.
- Power Generation:Legacy coal-fired plants in OECD markets face structural demand erosion from renewable dispatch priority and accelerated retirement schedules.
- Cement Production:Rotary kiln operators blend anthracite with petcoke and alternative fuels, with thermal substitution rates climbing as EU carbon border adjustments phase in.
Steel manufacturing commands margin concentration; industrial heating faces the steepest demand compression.
Extraction Method:
Seam depth and surface disturbance restrictions determine capital intensity, with deeper deposits favoring mechanized underground systems over contour stripping operations.
- Underground Mining:Longwall and room-and-pillar systems access seams below 300 meters where surface permits face stricter environmental review. Russian and Vietnamese operators deploy automated shearers with real-time roof monitoring, consolidating production share among capital-rich incumbents.
- Longwall Mining:Full-seam extraction with remote-operated equipment achieves labor productivity multiples over conventional methods. Siberian deposit scale enables amortization of sensor and control infrastructure across multi-panel reserves.
- Surface Mining:Contour and area stripping methods apply where overburden ratios remain economic, though permit timelines lengthen in jurisdictions with rehabilitation bond requirements.
- Room and Pillar Mining:Partial extraction technique leaves coal pillars for roof support, applied in thinner seams or where surface subsidence must be minimized for infrastructure protection.
Underground mining dominates reserve access; longwall systems expand most quickly as automation skills mature.
Market Channel:
Contract structure and logistics risk allocation vary by buyer scale, with integrated steel mills bypassing intermediaries while smaller industrial users rely on distributor networks for volume flexibility.
- Direct Sales:Long-term offtake agreements link producers to blast furnace operators with fixed rail and port commitments, displacing annual spot negotiations for premium grades. Vinacomin and Shenhua-tier producers anchor this channel through captive infrastructure control.
- Distributors:Regional stockholders buffer smaller cement and industrial heating customers from supply interruptions, though margin compression follows as procurement teams unbundle logistics from material pricing.
- Wholesale:Bulk intermediaries aggregate volumes from fragmented private mines in China, facing consolidation pressure as MEE enforcement raises capital barriers for small-scale operators.
- Online Platforms:Digital spot marketplaces emerge for standardized thermal grades, though metallurgical coal transactions remain relationship-driven given quality verification requirements.
Direct sales capture value concentration; distributor networks face margin erosion from procurement unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia commands deeper longwall operations than Vietnam, yet both jurisdictions concentrate metallurgical supply within state-coordinated production frameworks. Geographic dispersion across extraction depths and regulatory regimes fragments competitive positioning among exporters.
Russia
Siberian basins anchor seaborne premium anthracite flows through automated longwall panels. The MEE enforces mine rehabilitation bonds that consolidate output among capital-rich operators. Kuzbass region longwall complexes deploy remote-operated shearers across multi-panel reserves.
Vietnam
Vinacomin expands captive supply for northern metallurgical buyers under CEA production quotas. The CEA oversees export licensing and environmental compliance for Quang Ninh province operations. Cam Pha city anchors coal preparation and port loading infrastructure for East Asian steel mill contracts.
China
Shenhua-tier producers control integrated longwall operations across Shanxi and Shaanxi reserves. The MEE dual carbon enforcement redirects investment toward state-consolidated operators with balance-sheet compliance capacity. Datong city longwall complexes serve domestic metallurgical demand amid thermal phase-out pressure.
United States
Pennsylvania anthracite operators redirect supply toward metallurgical export markets as EPA sulfur dioxide standards constrain domestic thermal combustion. The EPA enforces particulate release limits at legacy preparation plants. Schuylkill County deep mines serve specialty carbon and filtration material processors.
Ukraine
Donbas basin underground operations face infrastructure strain amid regional conflict displacement of production capacity. The country's national mining regulator enforces safety protocols and subsidence monitoring for active longwall faces. Lviv-Volyn basin room-and-pillar mines supply industrial heating customers in Western European border zones.
Anthracite Coal Mining Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction depth tiers and metallurgical quality grades. State-backed operators leverage captive rail and port infrastructure to bypass third-party terminal congestion. Three archetypes dominate: vertically integrated energy conglomerates with multi-commodity balance sheets, pure-play anthracite specialists concentrating premium seaborne exports, and state mining bureaus serving domestic steel security mandates. Competitive moves center on longwall automation deployment and rehabilitation bond pre-funding to compress project IRRs.
Among Russian and Vietnamese state-coordinated producers, Sibanthracite Group and Vinacomin exemplify scale-driven archetypes with Siberian deposit access and northern basin captive supply respectively. Mechel PAO occupies a diversified conglomerate position spanning metallurgical coal and steel production integration. These three anchors represent the regulatory bifurcation between export-oriented premium positioning and domestic supply security frameworks.
| Leading Market Players |
|---|
| Sibanthracite Group |
| Mechel PAO |
| China Shenhua Energy Company |
| Sadovaya Group |
| Lehigh Anthracite |
| Reading Anthracite Company |
| Yanzhou Coal Mining Company |
| Vinacomin - Vietnam National Coal & Mineral Industries Group |
| Blaschak Coal Corporation |
| Others |
Supply Flow & Price Mechanics
Metallurgical-thermal grade bifurcation creates divergent pricing power and logistics configurations across the anthracite value chain. Premium low-volatile grades command fixed rail and port commitments under multi-year offtake structures, while thermal segments face spot-market volatility and natural gas substitution pressure.
Pricing Analysis
Capacity additions in Vietnam's northern basins are reshaping price floors for seaborne metallurgical grades. Contract-based long-term offtake dominates premium segments, with price differentiation driven by coke strength after reaction and phosphorus content assays. Cost compression in thermal grades is intensifying because pipeline gas expansion erodes industrial heating demand. Power utilities exhibit highest price sensitivity; integrated steel mills accept premium spreads for supply security.
Supply Chain Analysis
Specialized longwall technician shortages in Russian Siberia and Vietnamese Quang Ninh province constrain output scaling at automated faces. Supply concentrates in Russia, Vietnam, and China, with extraction equipment and roof support systems drawing from German and Chinese manufacturing bases. Single-source vulnerability runs through concentrated port loading infrastructure at Cam Pha and Vostochny terminals. Distribution runs through captive rail networks controlled by state-backed producers, bypassing third-party terminal congestion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as East Asian blast furnace operators prioritize low-phosphorus, high-coke-strength material for steel quality specifications.
For Market Incumbents: Cement metallurgical supply security through captive infrastructure pre-commitments and automated longwall panel expansion. Natural gas substitution in Eastern European industrial heating segments threatens thermal revenue pools; vertical integration into port loading assets insulates against third-party terminal congestion. For New Entrants and Emerging Players: The premium-economy price-point gap in semi-anthracite grades offers white-space access for cement kiln and specialty carbon processors. Vietnam's CEA production quota system creates regulatory shelter for state-joint venture structures; target direct sales channel bypass of distributor networks through quality certification investment. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play premium anthracite specialists with Siberian or Vietnamese reserve access and automated extraction deployment. Long-term viability across the analysis window favors operators with rehabilitation bond pre-funding capacity and metallurgical customer concentration. Watch for EPA emissions standard tightening or MEE enforcement escalation as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Longwall Automation Deployment | Remote-operated shearer installation at depths beyond 300 meters compresses labor costs and face downtime. |
| Captive Infrastructure Expansion | Integrated rail and port asset control enables supply chain bypass of congested third-party terminals. |
| Metallurgical Customer Concentration | Multi-year offtake agreements with East Asian steel mills displace spot thermal market exposure. |
| Rehabilitation Bond Pre-Funding | Early closure liability accounting extends capital recovery periods but accelerates permit approval timelines. |
| Quality Certification Investment | Low-phosphorus assay verification opens premium contract tiers with Japanese and Korean blast furnace operators. |
Methodological Framework
Coverage spans East Asia, Southeast Asia, Eastern Europe, and North America, with primary inputs from each region combined with secondary validation. Interviews with mine operations managers, metallurgical procurement officers at steel mills, rail logistics coordinators, and environmental compliance directors were triangulated against customs trade data, MEE enforcement disclosures, EPA emissions filings, and Vinacomin production quota announcements. Bottom-up reserve estimates and top-down seaborne trade volume reconciliation anchored the analytical framework.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions include metallurgical versus thermal application, extraction method tier, and end-user industry concentration. CAGRs were derived from panel regression of historical production data against steel output and emissions policy stringency indices. Mine automation penetration rates and rehabilitation bond cost schedules served as industry-specific forecast inputs.
Caveats apply where EPA regulatory tightening or MEE enforcement escalation could materially shift the outlook for thermal versus metallurgical grade demand splits. Forecasts reflect assumptions about East Asian steel production trajectories and natural gas pipeline expansion timelines in Eastern Europe. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Carbonizers Market
Fuels
Global Methane Hydrate Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Gas Hydrates Market
Fuels
Pyrolysis Gas Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Gas Feed System Market
Fuels
Fuel Analyzer Market
Fuels
Coal Trading Market
Fuels
Bituminous Coal Market
Fuels
Fuel Oil Market
Fuels
Saudi Arabia Automotive Fuels Market