
 High-Temperature Industrial Burner Market | 2026-2036
High-Temperature Industrial Burner Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Industrial Burner Market Foresight
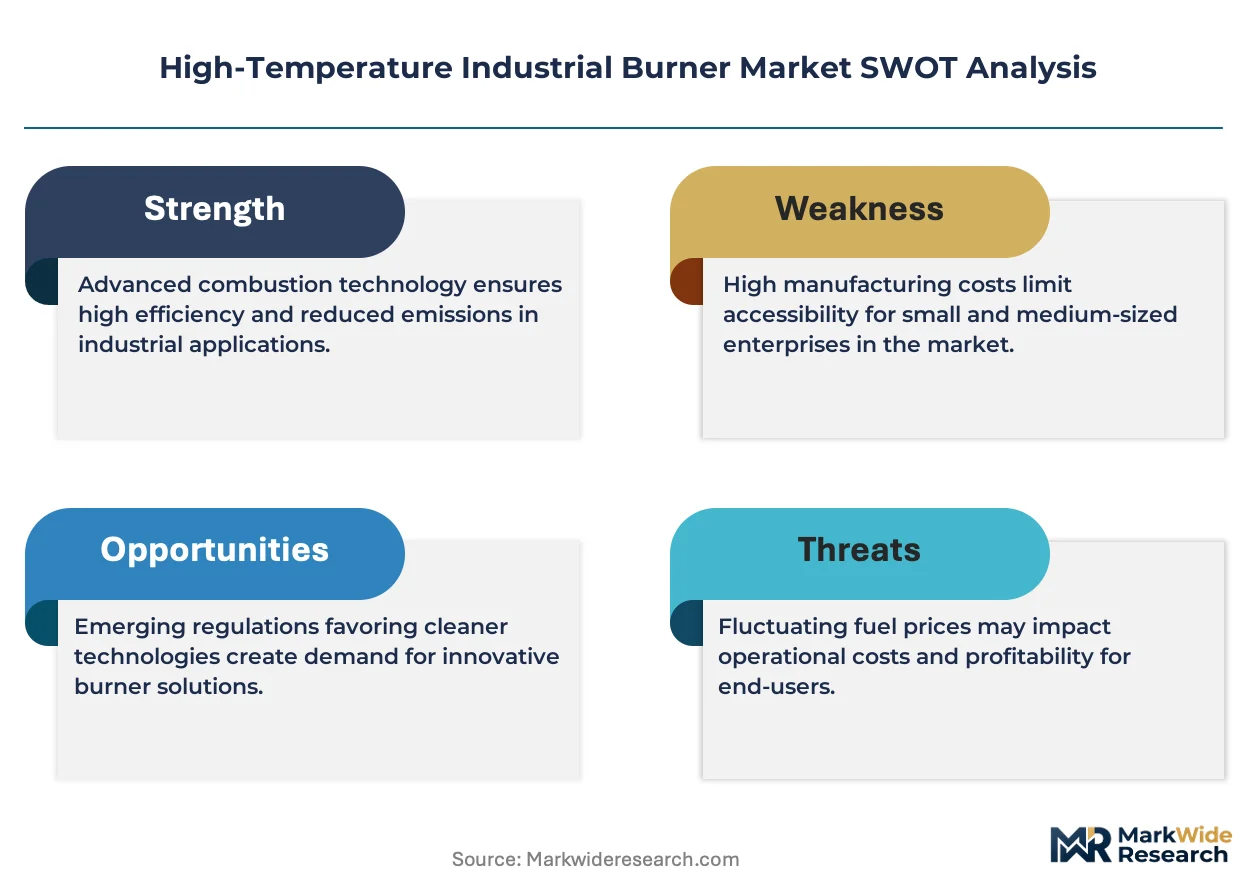
Ceramic matrix composites is broadening the thermal envelope for next-generation burner nozzles and flame tubes. Honeywell International Inc. leverages its aerospace materials heritage to transfer ceramic expertise into industrial combustion hardware. Fives Group anchors its position through captive foundry operations in France and integrated burner-furnace systems. Bloom Engineering specializes in custom high-velocity designs for the North American forging sector.
High-temperature industrial burners are engineered combustion devices designed to sustain operating temperatures exceeding 1,000°C through controlled fuel-air mixing and flame stabilization, typically employing alloy steel or refractory-lined construction to withstand thermal cycling and corrosive flue gases. Their primary purpose is to deliver precise, high-intensity heat for processes including metal melting, glass forming, and petrochemical cracking. Gas burners dominate installed capacity across mature markets due to pipeline infrastructure density and lower per-unit emissions profiles, while regenerative technology captures the fastest growth trajectory as facilities retrofit for waste-heat recovery. Dual-fuel configurations retain strategic importance in regions with volatile natural gas pricing or interrupted supply.
The EPA enforces Maximum Achievable Control Technology standards that compel burner OEMs to certify NOx and CO emissions below threshold limits for new and modified sources. China's MEE implements dual carbon goals through provincial emissions trading schemes that penalize high-carbon combustion processes. The EU F-Gas Regulation restricts fluorinated greenhouse gases used in certain burner cooling systems, redirecting R&D toward air-cooled architectures. Stakeholders must weigh retrofit economics against regulatory compliance deadlines while tracking ceramic material qualification timelines.
Market Dynamics
Regenerative burner technology is compressing payback periods for waste-heat recovery retrofits, compelling steel and glass producers to accelerate furnace upgrades ahead of emissions compliance deadlines in multiple jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is redirecting capital toward air-cooled burner architectures, creating replacement demand across European metal processing.
- Jiangsu Province cluster expansion:Chinese stainless steel capacity additions are specifying low-NOx regenerative systems to satisfy provincial emissions trading schemes.
- Ceramic matrix composites:Advanced refractory materials are extending flame tube service intervals, reducing maintenance-driven downtime in continuous casting operations.
Market Restraints
- Nickel alloy supply concentration:Superalloy feedstock for burner nozzles concentrates among a limited supplier base, exposing OEMs to volatile input costs.
- Dual-fuel configuration complexity:Backup oil firing capability adds engineering overhead that lengthens project commissioning timelines.
- REACH compliance burden:European chemical registration requirements for refractory coatings create documentation friction for non-EU manufacturers.
Strategic Opportunities
- Gujarat State petrochemical corridor:India's crackers and reformers present untapped demand for high-velocity burners with hydrogen-ready fuel trains.
- Hydrogen combustion convergence:Integration of pure hydrogen firing with existing natural gas infrastructure opens retrofit contracts at integrated steel mills.
- China dual carbon policy tailwind:National carbon intensity targets are mandating waste-heat recovery in new industrial furnace specifications.
Industry Challenges
- Combustion modeling expertise scarcity:Computational fluid dynamics specialists capable of optimizing flame geometry for ultra-low-NOx performance command premium compensation.
- Legacy DCS integration friction:Retrofitting digital burner management systems onto 1980s-vintage distributed control architectures requires custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Industrial Burner Market |
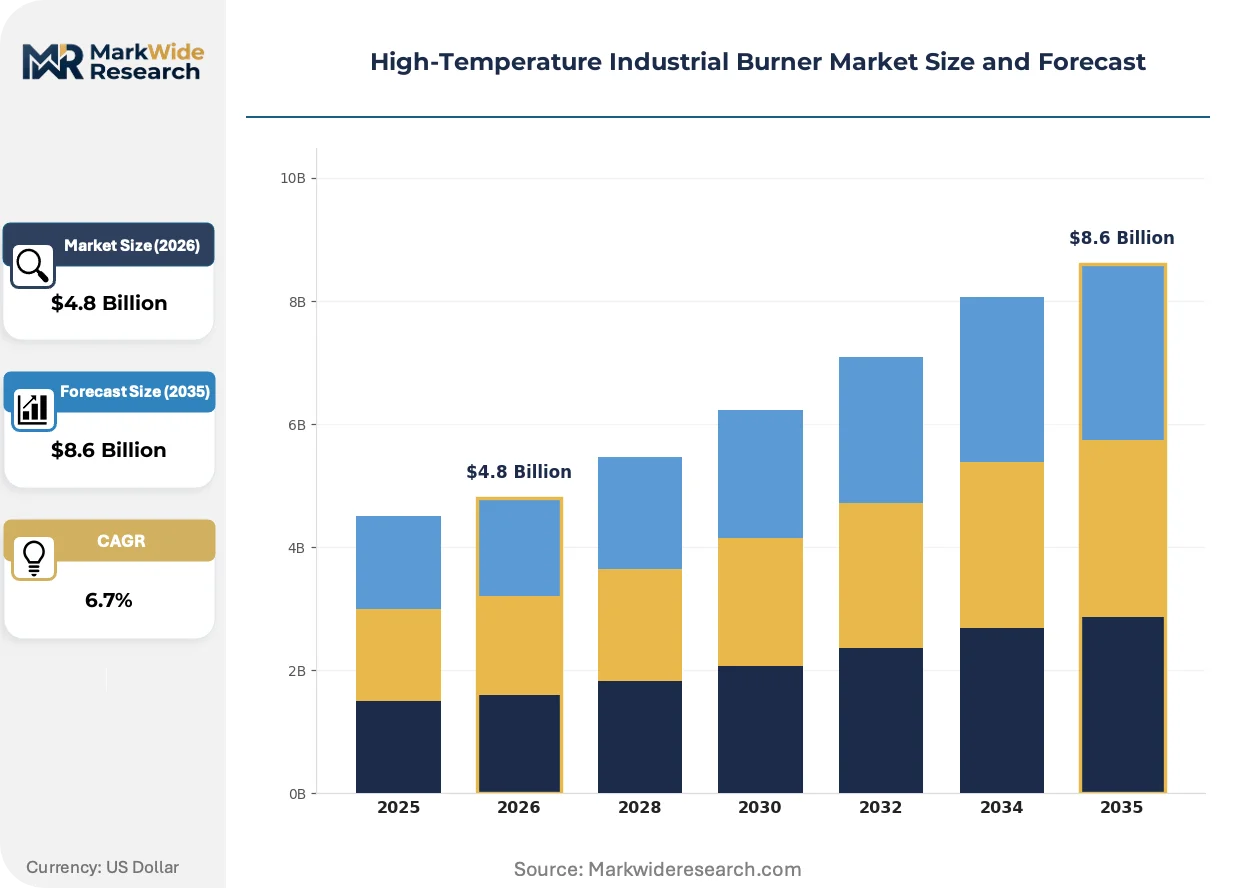
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Burners, Oil Burners, Dual-Fuel Burners, High-Temperature Burners End User: Manufacturing, Chemical Processing, Food Processing, Metal Production Technology: Combustion, Infrared, Regenerative, Rotary Installation: Onshore, Offshore, Stationary, Portable |
| Companies Covered | Honeywell International Inc., Fives Group, Bloom Engineering, Selas Heat Technology Company, Weishaupt Group, Oilon Group Oy, Baltur S.p.A, Andritz AG, Zeeco, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Industrial Burner Market Shifts & Advancements
Digital combustion control and advanced materials science are converging to redefine burner performance benchmarks, while regulatory pressure compresses technology adoption cycles across heavy manufacturing.
Self-optimizing burner management systems is decentralizing combustion tuning authority from central control rooms to edge-mounted sensors and actuators. Steel minimills in the US Gulf Coast are piloting these architectures to maintain flame stability across scrap-quality variations. The shift is compressing response latency from seconds to milliseconds, enabling tighter emissions control during load swings.
China's MEE is tightening enforcement of dual carbon goals through provincial emissions trading schemes that penalize unabated combustion processes. Glass manufacturers in Hebei Province are accelerating regenerative retrofits to avoid carbon allowance shortfalls. The policy is elevating burner efficiency from operational preference to license-to-operate requirement.
After-sales service unbundling is disrupting traditional OEM revenue models as end-users seek specialized combustion tuning from third-party technical service providers. North American forging houses are contracting independent flame diagnostics firms rather than burner manufacturers for annual optimization audits. The pattern is most pronounced in mature industrial corridors where installed base density supports independent service economics.
High-Temperature Industrial Burner Market Segmentation
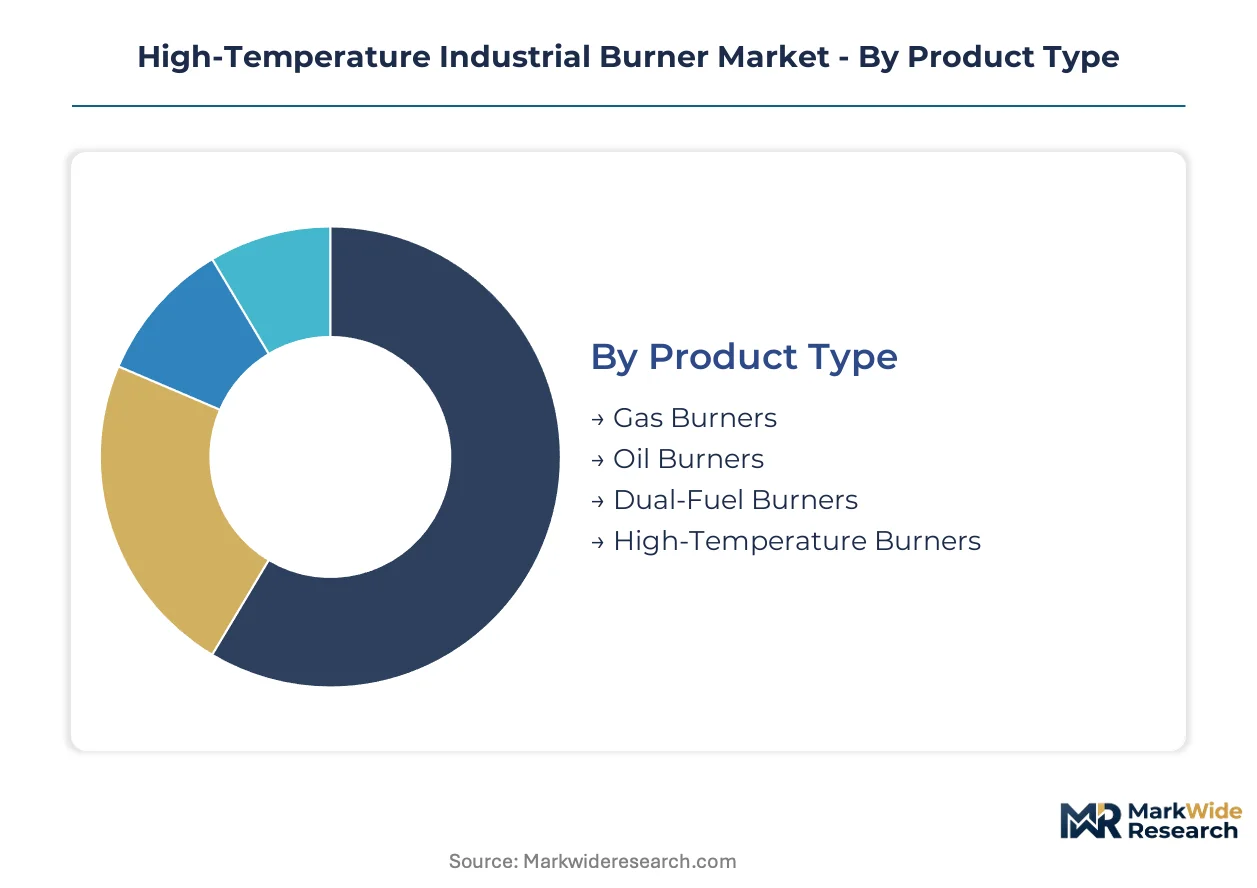
High-temperature industrial burner procurement decisions hinge on fuel availability, emissions compliance deadlines, and furnace retrofit economics. Segment boundaries blur as dual-fuel architectures and regenerative retrofits reshape capital allocation patterns across heavy manufacturing.
Product Type:
Capital intensity varies sharply across fuel configurations, with dual-fuel systems demanding redundant fuel trains and control logic that inflate upfront engineering costs.
- Gas Burners:These systems rely on natural gas or hydrogen-enriched fuel streams with staged combustion zones to limit thermal NOx formation. Pipeline density in Gujarat State and Jiangsu Province sustains dominant share, though hydrogen-ready fuel trains now command premium specifications at integrated steel mills.
- Dual-Fuel Burners:Backup oil firing capability requires parallel fuel handling skids, atomization hardware, and flame detection redundancy that lengthen commissioning timelines. Volatile natural gas pricing in South Asian markets sustains strategic demand despite engineering complexity.
- Oil Burners:Heavy fuel oil and diesel configurations retain relevance in remote mining corridors lacking pipeline infrastructure.
- High-Temperature Burners:Specialized refractory-lined designs exceed 1,400°C for glass melting and petrochemical cracking.
Most installed capacity flows through gas burners. Expansion is steepest in dual-fuel configurations as energy security concerns reshape procurement criteria.
End User:
Process temperature requirements and batch versus continuous operation dictate burner specification tiers across industrial verticals.
- Metal Production:Electric arc furnaces and ladle metallurgy stations require high-velocity flame impingement for rapid scrap melting and alloy homogenization. Chinese stainless steel expansions in Jiangsu Province specify low-NOx regenerative systems to satisfy provincial emissions trading schemes.
- Chemical Processing:Steam crackers and reformers demand precise heat distribution for endothermic reactions with minimal coking. Gujarat State's petrochemical corridor presents untapped demand for hydrogen-ready fuel trains as crackers retrofit for feedstock flexibility.
- Manufacturing:Heat treatment and forging operations prioritize flame stability across load variations.
- Food Processing:Direct and indirect firing configurations address sanitation and flavor contamination constraints.
Metal production commands the largest installed base. Chemical processing shows the steepest specification escalation as crackers integrate carbon capture readiness.
Technology:
Retrofit economics and emissions compliance timelines are compressing adoption cycles for waste-heat recovery architectures.
- Regenerative:Alternating burner pairs recover exhaust enthalpy through ceramic honeycomb media, cutting fuel consumption by 30-50% in steel reheating furnaces. Hebei Province glass manufacturers are accelerating retrofits to avoid carbon allowance shortfalls under China's MEE enforcement.
- Combustion:Conventional momentum-driven mixing remains cost-effective for low-duty batch operations.
- Infrared:Surface combustion designs deliver radiant heat for coating cure and preheating applications.
- Rotary:Kiln-specific flame geometries address cement and lime calcination requirements.
Regenerative systems anchor new furnace specifications. Infrared configurations are climbing fastest in automotive paint shop retrofits.
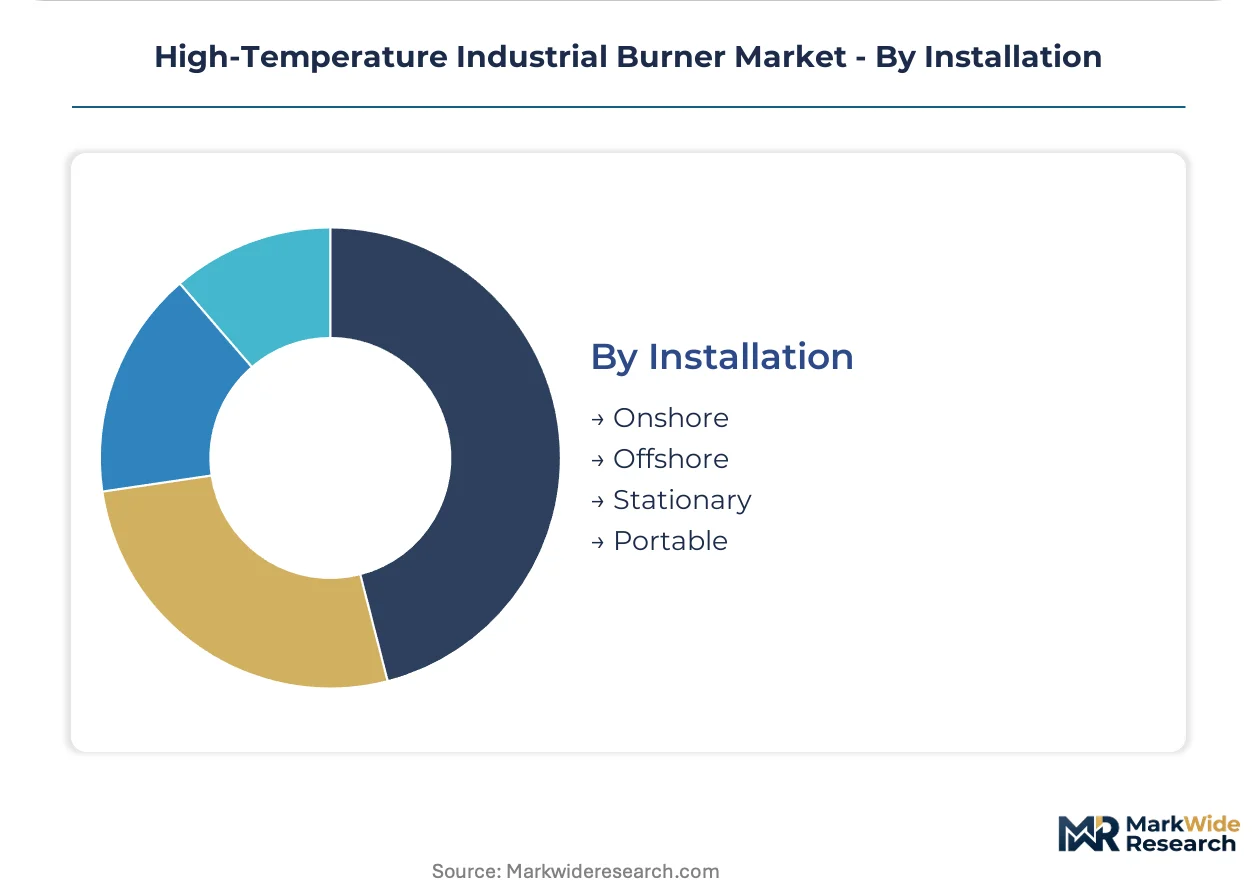
Installation:
Mobility requirements and foundation constraints split procurement between fixed infrastructure and redeployable assets.
- Stationary:Permanent refractory foundations and fixed piping arrays dominate steel mill and glass tank installations where decades-long asset lifecycles justify civil engineering investment.
- Onshore:Fixed plant configurations prevail across manufacturing and chemical processing corridors.
- Portable:Skid-mounted burner packages serve construction preheating, emergency repairs, and seasonal agricultural drying with rapid deployment requirements.
- Offshore:Platform-specific flame safety systems address marine environment corrosion and space constraints.
Stationary systems carry the bulk of cumulative investment. Portable configurations are gaining share fastest in infrastructure construction and disaster recovery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu Province anchors global demand concentration for high-temperature industrial burners, with Chinese stainless steel expansions driving regenerative system procurement ahead of emissions compliance deadlines. India's Gujarat State petrochemical corridor and Germany's industrial heartland follow as secondary demand poles, each shaped by distinct regulatory enforcement timelines and fuel infrastructure maturity.
China
Jiangsu Province stainless steel capacity additions specify low-NOx regenerative systems to satisfy provincial emissions trading schemes under MEE enforcement. The dual carbon policy mandates waste-heat recovery in new industrial furnace specifications nationwide. Hebei Province glass manufacturers accelerate retrofits to avoid carbon allowance shortfalls.
India
Gujarat State's crackers and reformers present demand for high-velocity burners with hydrogen-ready fuel trains as petrochemical capacity expands. The Bureau of Energy Efficiency implements perform-achieve-trade schemes that penalize inefficient combustion processes. Maharashtra's steel belt follows with ladle metallurgy station upgrades.
Germany
Ruhr industrial corridor steel producers retrofit reheating furnaces ahead of EU F-Gas Regulation phasedown deadlines. REACH compliance requirements for refractory coatings create documentation friction for non-EU suppliers. Bavarian automotive forging houses specify flame stability systems for heat treatment operations.
United States
Gulf Coast steel minimills pilot self-optimizing burner management systems to maintain flame stability across scrap-quality variations. EPA Maximum Achievable Control Technology standards compel NOx and CO emissions certification below threshold limits. Ohio River Valley forging sector contracts independent flame diagnostics firms for optimization audits.
Japan
Kansai region glass manufacturers adopt ceramic matrix composite flame tubes to extend service intervals in continuous melting operations. METI carbon neutrality roadmaps redirect capital toward air-cooled burner architectures. Chubu industrial corridor chemical processors integrate hydrogen combustion readiness into cracker specifications.
High-Temperature Industrial Burner Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive foundry integration, creating a tiered structure where aerospace heritage transfers, integrated furnace systems, and custom high-velocity designs each occupy distinct competitive positions. The vendor base stratifies into three archetypes: conglomerate-affiliated technology transfer specialists, captive-manufacturing integrated system providers, and application-specific engineering boutiques. Dominant competitive moves include backward integration into superalloy supply chains and strategic partnerships for hydrogen combustion qualification.
Within the conglomerate-affiliated tier, Honeywell International Inc. exemplifies aerospace-to-industrial technology migration, while Fives Group anchors European integrated system supply through captive manufacturing capabilities. Bloom Engineering occupies the specialist position in North American custom burner engineering. These three represent the structural poles around which mid-cap regional fabricators and emerging hydrogen-ready technology developers organize their competitive positioning.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Fives Group |
| Bloom Engineering |
| Selas Heat Technology Company |
| Weishaupt Group |
| Oilon Group Oy |
| Baltur S.p.A |
| Andritz AG |
| Zeeco, Inc. |
| Others |
Supply & Pricing Matrix
Computational fluid dynamics specialists concentrated in Germany's Ruhr corridor and Japan's Kansai region command premium compensation that widens pricing spreads between premium custom-engineered burners and standardized commodity configurations. Labor-cost differentials between these engineering hubs and emerging manufacturing centers in Gujarat State feed directly into tiered pricing architectures.
Pricing Analysis
Input-cost pass-through from nickel superalloy feedstock anchors pricing volatility in high-performance burner nozzles and flame tubes. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified ceramic matrix composite designs from alloy-steel commodity burners and basic refractory-lined units. Pricing pressure stems from REACH compliance documentation burdens that inflate European refractory coating costs. Steel minimills in the US Gulf Coast exhibit highest price sensitivity due to scrap-margin compression, while Japanese glass manufacturers show lowest sensitivity given continuous-melting uptime premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese superalloy processing capacity for nickel-chromium feedstock used in high-temperature nozzles. Manufacturing concentrates in China, Germany, and the United States for burner hardware assembly, while ceramic honeycomb regenerative media sources primarily from Japan and the United States. Raw material dependencies span nickel superalloys, ceramic matrix composites, and refractory-grade alumina. Tariff exposure on Chinese-processed nickel compounds threatens margin stability at European OEMs. Distribution runs through captive foundry operations at integrated furnace manufacturers and direct-specification channels for large steel and glass producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Germany's Ruhr corridor exceed India's Bureau of Energy Efficiency scheme administration costs by multiples, redirecting capital toward Gujarat State and Jiangsu Province capacity additions.
For Market Incumbents: To counter hydrogen-ready technology qualification delays, accelerate backward integration into ceramic matrix composite supply chains and anchor capacity additions in Jiangsu Province to capture Chinese stainless steel expansion demand. Dual-fuel configuration complexity at legacy installations presents margin defense through aftermarket service unbundling. For New Entrants and Emerging Players: Capture Gujarat State petrochemical corridor demand for high-velocity burners with hydrogen-ready fuel trains, where incumbent presence remains thin. Target portable burner packages for infrastructure construction and disaster recovery applications as the most penetrable segment. Lead with rapid-deployment service models rather than integrated furnace systems. For Investors and Strategic Acquirers: Industrial conglomerates with aerospace materials heritage are the most active acquirer in this space, seeking combustion hardware capabilities to complement existing thermal management portfolios. Long-term viability hinges on hydrogen combustion convergence timelines. Target acquisition archetypes are regional fabricators with captive foundry operations and MEE compliance track records in China. Monitor ceramic matrix composite qualification timelines at major steel producers as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive nickel-chromium feedstock secures margin stability against Chinese processing concentration. |
| Hydrogen-Ready Fuel Train Qualification | MEE dual carbon enforcement at Jiangsu Province steel mills mandates low-carbon combustion readiness. |
| Ceramic Matrix Composite Flame Tube Adoption | Kansai region glass manufacturers extend service intervals through advanced refractory materials. |
| Regenerative Retrofit Acceleration | Hebei Province carbon allowance shortfalls under MEE enforcement compel waste-heat recovery adoption. |
| Aftermarket Service Unbundling | North American forging houses contract independent flame diagnostics firms for optimization audits. |
Research Methodology
Coverage spans East Asian manufacturing corridors, European industrial heartlands, and North American steel and petrochemical belts, with primary inputs from each. The analysis combines structured interviews with plant engineers at steel minimills and glass manufacturers, procurement leads at integrated petrochemical complexes, aftermarket service directors, and R&D heads at burner OEMs with secondary validation from SEC filings of listed industrial conglomerates, MEE provincial emissions trading scheme disclosures, EU F-Gas Regulation implementation documents, and customs data on superalloy trade flows. Bottom-up unit economics triangulate against top-down industry capacity assessments.
Rate-of-change decomposition separates volume expansion from specification escalation and technology substitution effects across the projection horizon. The analytical framework models segmentation across fuel configuration, end-use vertical, regenerative versus conventional technology, and installation mobility, with regional regulatory cluster as an overlay dimension. CAGRs derive from installed base turnover rates, retrofit payback period compression, and compliance deadline clustering. Industry-specific forecast inputs include MEE dual carbon policy enforcement intensity and EU F-Gas phasedown timelines.
Policy enforcement delays, ceramic material qualification setbacks, and nickel superalloy supply disruptions are the dominant revision risks. Forecasts reflect documented assumptions about regulatory compliance timelines and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Oil & Gas Lubricants Market
Fuels
Emulsified Fuel Market
Fuels
North America LNG Bunkering Market
Fuels
Tire Derived Fuel Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
No.2 Diesel Fuel Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
North America Bunker Fuel Market
Fuels
Fuel Grinder Market
Fuels
India Retail Fuel Market
Fuels
Mobile Fuel Delivery Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Anthracite Coal Mining Market
Fuels
South America Bunker Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Petroleum Fuel Dyes Sales Market