
 India City Gas Distribution (CGD) Market | 2026-2036
India City Gas Distribution (CGD) Market Size, Share, and Industry Trends Forecast 2026-2036
India City Gas Distribution (CGD) Market Foresight
Product bundling of CNG dispensing with piped natural gas connections is hardening buyer expectations for integrated fuel solutions. Mahanagar Gas Limited leverages its Mumbai monopoly to anchor residential conversions while cross-subsidizing automotive infrastructure. Gujarat Gas Limited dominates the industrial belt with dedicated pipeline corridors serving manufacturing plants. Adani Total Gas Limited extends its Gujarat-origin network into newer geographic circles through aggressive bidding in PNGRB licensing rounds.
City Gas Distribution comprises the localized pipeline infrastructure, compression facilities, and retail dispensing networks that deliver natural gas and compressed biogas directly to end consumers at pressures typically below 16 bar for residential and commercial use, with dedicated high-pressure lines feeding industrial offtake. The system functions as the terminal delivery layer between national transmission grids and point-of-use combustion equipment. Natural gas and CNG together anchor volume throughput, while compressed biogas represents the fastest-growing product stream as blending obligations mature. The automotive customer segment generates the highest per-unit margin pools due to fuel-switch economics versus diesel, whereas residential connections provide annuity-like demand basins that amortize fixed pipeline investments.
The Petroleum and Natural Gas Regulatory Board licenses geographic areas and sets pipeline tariffs, while the Bureau of Indian Standards governs material specifications for polyethylene and steel distribution networks. The PLI scheme for domestic manufacturing of gas equipment reinforces local content requirements that shape procurement patterns for infrastructure buildouts. Stakeholders must monitor compressed biogas integration mandates and state-level municipal cooperation frameworks that determine last-mile rollout velocity.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's compressed biogas blending mandate is compressing project timelines and forcing accelerated capital deployment across licensed geographic areas.
Growth Catalysts
- PNGRB Licensing Rounds:Expanded geographic authorizations unlock new market entry points for pipeline infrastructure buildouts in previously unserved urban clusters.
- Automotive Fleet Conversion:State transport corporations and logistics operators switch commercial vehicle fleets from diesel to CNG under emission compliance pressure.
- Compressed Biogas Integration:Mandatory blending obligations under the Sustainable Alternative Towards Affordable Transportation framework create dedicated offtake channels for agricultural waste-derived fuel.
Market Restraints
- Steel and Polyethylene Input Volatility:Pipeline material costs fluctuate with global polymer and metal commodity cycles, squeezing project returns during construction phases.
- Cross-Country Pipeline Dependence:Natural gas supply concentrates through the Hazira-Vijaipur-Jagdishpur trunk line and its extensions, creating single-point vulnerability for northern distribution networks.
- Land Acquisition Friction:Right-of-way clearances under state municipal frameworks delay last-mile connectivity in dense urban corridors.
Strategic Opportunities
- Eastern India Penetration:West Bengal and Odisha present underdeveloped city gas infrastructure with rising industrial demand from steel and ceramics manufacturing.
- Industrial Cogeneration:Dedicated high-pressure lines serving captive power plants in Gujarat's chemical belt expand per-customer volume throughput.
- Smart Metering Convergence:Integration of IoT-enabled consumption monitoring with billing platforms reduces commercial losses and improves demand forecasting precision.
Industry Challenges
- Skilled Welding and Pipeline Technician Scarcity:Specialized certification requirements for polyethylene fusion and steel welding outpace vocational training output.
- Legacy Distribution System Integration:Municipal water and sewage corridors compete for underground space, forcing complex routing engineering in established metros.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India City Gas Distribution (CGD) Market |
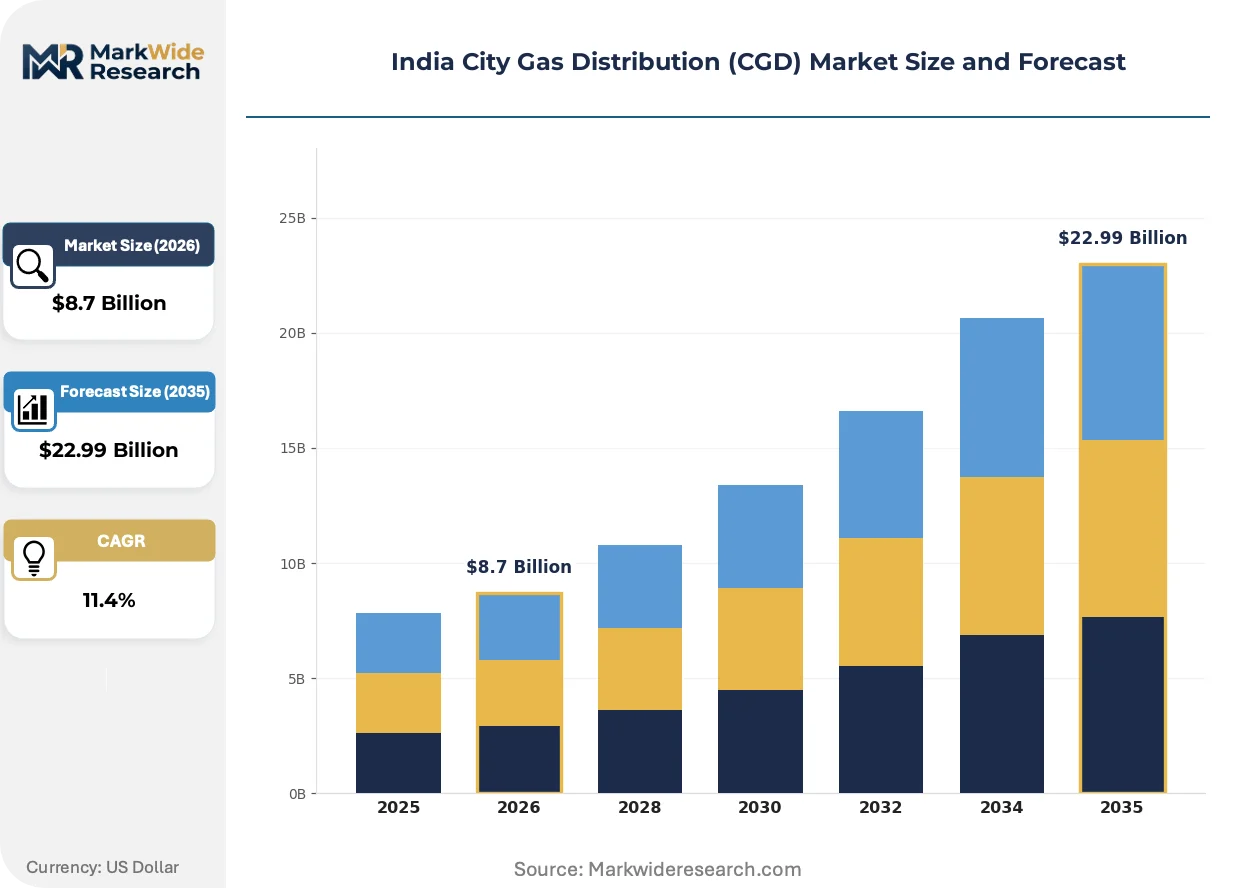
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas, Compressed Biogas, LNG, CNG Customer Type: Residential, Commercial, Industrial, Automotive Service Type: Distribution, Transmission, Storage, Consultancy End User: Households, Restaurants, Manufacturing Plants, Transportation |
| Companies Covered | Mahanagar Gas Limited, GAIL Gas Limited, Adani Total Gas Limited, Haryana City Gas Distribution Network Limited, Maharashtra Natural Gas Limited, Indraprastha Gas Limited, Gujarat Gas Limited, Aavantika Gas Limited, THINK Gas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India City Gas Distribution (CGD) Market Shifts & Advancements
Digital infrastructure and feedstock diversification are compressing operational boundaries between conventional natural gas and renewable gas streams.
Composite cylinder technology is unifying automotive and stationary storage applications through lightweight, corrosion-resistant fiber-wrapped designs. Fleet operators and residential distributors adopt these units simultaneously, collapsing the historical separation between mobility and stationary gas containment. The technology is unifying procurement specifications across previously distinct buyer segments.
The Petroleum and Natural Gas Regulatory Board's unified tariff framework for compressed biogas injection eliminates historical price discrimination against non-fossil feedstocks. This regulatory parity accelerates project financing for agricultural residue-based plants. Distribution licensees in Punjab and Haryana respond by securing long-term biogas purchase agreements with rice straw aggregators.
Commercial buyers now negotiate bundled fuel supply contracts spanning CNG dispensing, piped natural gas, and compressed biogas volumes under single pricing mechanisms. Large manufacturing facilities in Maharashtra's industrial corridors drive this consolidation, replacing multiple supplier relationships with integrated offtake agreements. This consolidation concentrates negotiating leverage among high-volume consumers.
India City Gas Distribution (CGD) Market Segmentation
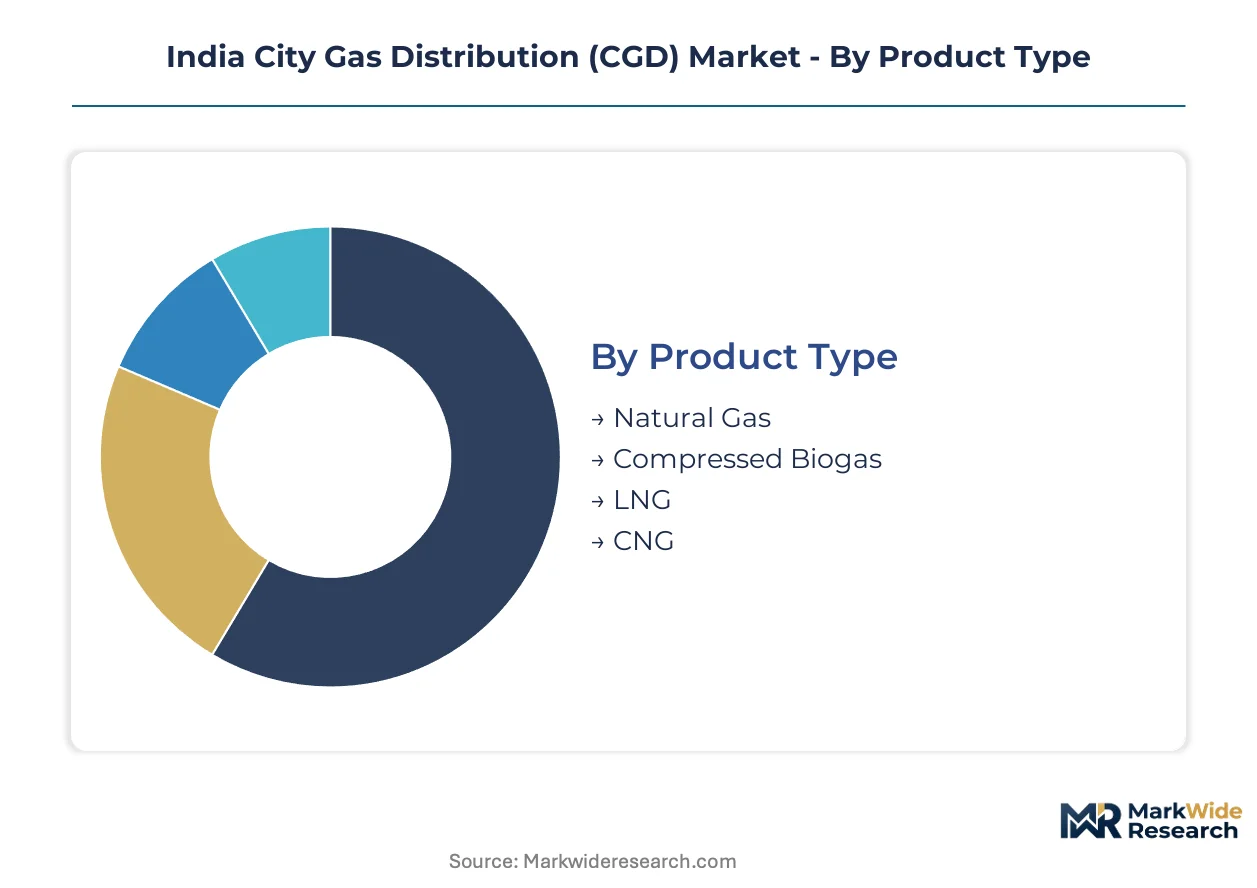
Segmentation in India's CGD market reveals how infrastructure economics and regulatory mandates reshape buyer priorities across fuel types and service tiers. Licensees structure capital deployment around customer density, feedstock access, and tariff visibility rather than uniform geographic rollout.
Product Type:
Buyers select fuel streams based on equipment compatibility, emission compliance deadlines, and supply security rather than unit cost alone.
- Natural Gas:Methane-rich pipeline supply at standardized pressure tiers serves as the baseline fuel for stationary combustion equipment. Demand concentrates in Gujarat's chemical corridor and Delhi-NCR's residential clusters where pipeline density supports continuous offtake.
- Compressed Biogas:Upgraded biogas meeting IS 16087 specifications delivers renewable thermal content for obligated blending. Punjab and Haryana distribution networks source aggressively from rice straw aggregation hubs under SATAT framework purchase guarantees.
- LNG:Cryogenic liquid supply fills gaps in pipeline-deficient geographies through ISO container logistics.
- CNG:High-pressure compressed storage fuels mobility applications with established dispensing protocols.
Natural gas leads on scale; compressed biogas leads on momentum.
Customer Type:
Margin profiles diverge sharply between annuity-style residential connections and high-throughput industrial offtake.
- Industrial:Dedicated high-pressure lines feeding captive power and process heat applications generate the highest per-connection revenue. Gujarat's ceramics and steel manufacturers anchor volume commitments that amortize trunk pipeline investments.
- Automotive:Fleet conversion economics under BS-VI emission norms compress payback periods for CNG vehicle retrofits. State transport corporations in Maharashtra and Karnataka drive demand concentration through centralized procurement.
- Residential:Piped cooking gas connections build predictable demand basins with low churn.
- Commercial:Restaurants and hotels prioritize supply reliability over marginal cost savings.
Industrial customers anchor revenue concentration; automotive buyers expand most quickly.
Service Type:
Capital allocation decisions separate asset-heavy infrastructure owners from fee-based service providers.
- Distribution:Last-mile pipeline networks and pressure regulation stations constitute the core licensed activity. Licensees in newer PNGRB rounds prioritize this layer before upstream integration.
- Transmission:City gate stations and intermediate compression link distribution grids to national trunk lines.
- Storage:Underground caverns and above-ground bullet tanks buffer supply volatility.
- Consultancy:Engineering and project management services support new market entrants lacking operational heritage.
Distribution commands capital deployment; consultancy captures entry-wave demand.
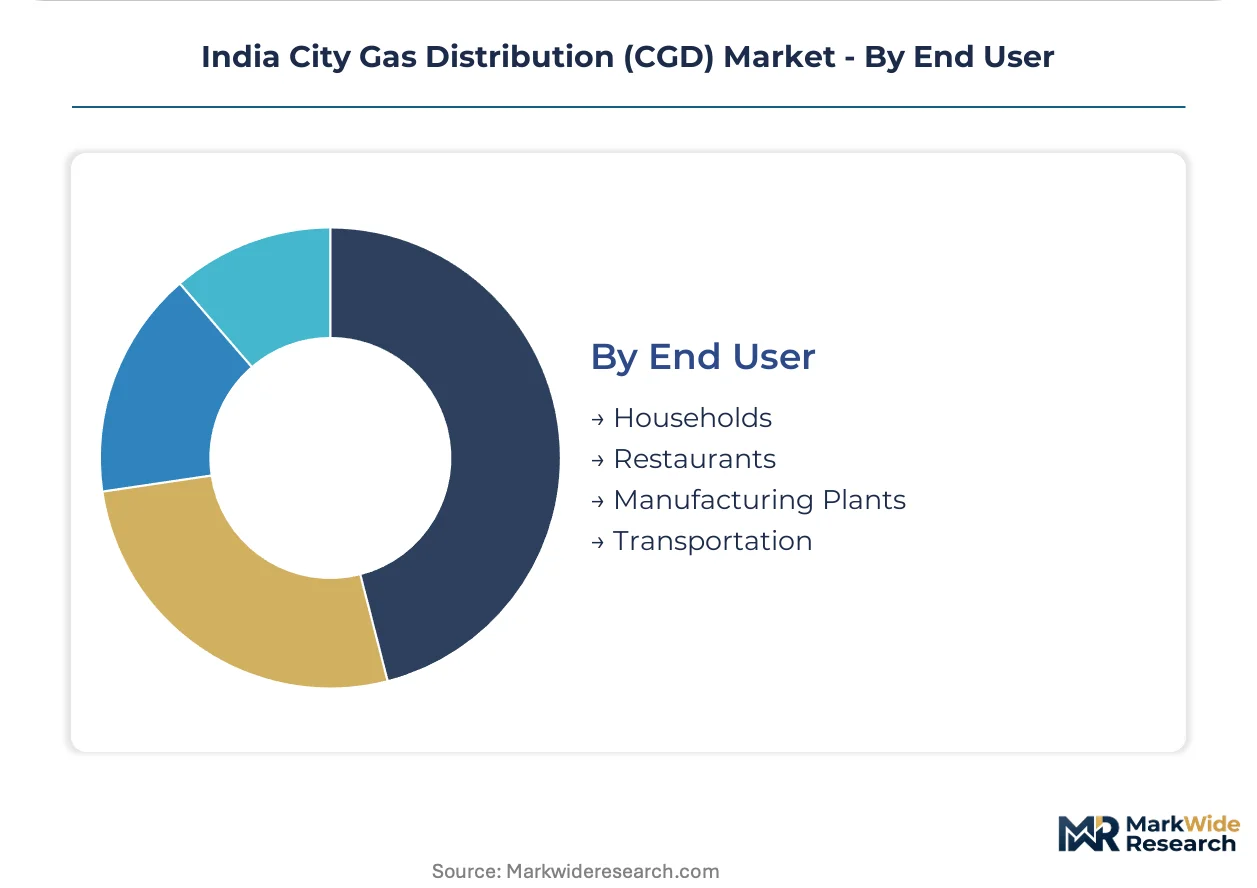
End User:
Final consumption patterns determine pressure requirements, metering specifications, and safety protocol intensity.
- Manufacturing Plants:Continuous process industries in Gujarat's chemical belt require redundant supply arrangements and dedicated backup storage. Ceramic kilns and pharmaceutical sterilization units anchor the highest pressure tier demand.
- Transportation:Intra-city buses and long-haul trucks access CNG through daughter station networks and mother station compression. Fleet operators negotiate volume commitments in exchange for guaranteed dispensing priority.
- Households:Domestic cooking applications dominate connection counts with standardized low-pressure service.
- Restaurants:Commercial kitchens balance throughput needs against space constraints for on-site storage.
Manufacturing plants anchor throughput scale; transportation gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The India City Gas Distribution industry traces its commercial roots to the mid-1990s when the Hazira-Bijaipur-Jagdishpur pipeline first enabled compressed natural gas dispensing in Delhi and Mumbai. Subsequent Petroleum and Natural Gas Regulatory Board licensing rounds progressively decentralized infrastructure ownership beyond state-owned incumbents.
Maharashtra
Mumbai's dense urban fabric supports the highest concentration of CNG dispensing stations nationwide. The state's transport utilities mandate fleet conversion under Maharashtra State Road Transport Corporation procurement directives. Pune and Thane industrial corridors anchor dedicated pipeline networks serving automotive component manufacturers.
Gujarat
Ankleshwar-Vadodara chemical belt generates sustained industrial demand through captive power and process heat applications. Gujarat State Petroleum Corporation legacy infrastructure feeds expanded city gas networks under PNGRB Geographical Area authorizations. Surat and Rajkot municipal corporations accelerate residential connection targets through subsidized connection schemes.
Delhi-NCR
Supreme Court-mandated air quality compliance compresses diesel vehicle operating windows across National Capital Territory boundaries. Indraprastha Gas Limited maintains dispensing priority for public transport fleets under Delhi Transport Corporation contracts. Gurugram and Faridabad extensions face right-of-way friction along Delhi-Jaipur and Delhi-Mathura highway corridors.
Haryana
Rice straw aggregation hubs in Karnal and Panipat districts supply feedstock for compressed biogas plants under SATAT framework purchase guarantees. Haryana City Gas Distribution Network Limited secures long-term supply agreements with agricultural residue processors. Ambala and Hisar urban clusters represent priority expansion zones for piped natural gas residential penetration.
West Bengal
Asansol-Durgapur industrial belt presents underdeveloped pipeline density despite rising steel and ceramics manufacturing thermal demand. Haldia petrochemical complex proximity offers potential city gas feedstock integration. Kolkata municipal jurisdiction delays last-mile connectivity through complex underground utility coordination requirements.
India City Gas Distribution (CGD) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across geographic exclusivity and customer mix dimensions. Incumbents holding legacy PNGRB licenses in dense urban cores command superior returns through amortized infrastructure and captive residential bases. Three archetypes dominate: state-backed integrated energy groups, regional pure-play distributors, and diversified infrastructure conglomerates. Consolidation pressure manifests through asset acquisitions in adjacent Geographical Areas and cross-holding arrangements with national transmission operators.
Among state-affiliated entities, GAIL Gas Limited and Gujarat Gas Limited anchor the integrated archetype through pipeline ownership and distribution licensing. Mahanagar Gas Limited and Indraprastha Gas Limited exemplify regional pure-play positioning with metropolitan exclusivity. Adani Total Gas Limited represents conglomerate-backed expansion through aggressive bidding in successive PNGRB rounds.
| Leading Market Players |
|---|
| Mahanagar Gas Limited |
| GAIL Gas Limited |
| Adani Total Gas Limited |
| Haryana City Gas Distribution Network Limited |
| Maharashtra Natural Gas Limited |
| Indraprastha Gas Limited |
| Gujarat Gas Limited |
| Aavantika Gas Limited |
| THINK Gas |
| Others |
Supply & Pricing Matrix
The Petroleum and Natural Gas Regulatory Board's compressed biogas blending mandate gates qualified supply access and premium-tier pricing for distribution licensees meeting SATAT framework obligations. PNGRB tariff regulations cap pipeline transportation charges while allowing margin recovery through CNG dispensing premiums, creating a bifurcated pricing architecture where biogas-integrated operators command preferential licensing terms.
Pricing Analysis
Long-term offtake contracts with price escalation clauses dominate industrial customer relationships, while CNG dispensing operates on regulated tariff-plus-margin structures set by PNGRB. Price differentiation hinges on geographic exclusivity density and feedstock integration depth, with compressed biogas-blended supply commanding modest premiums over conventional natural gas. Cost compression in steel and polyethylene input tiers is intensifying because global commodity volatility squeezes construction-phase returns. Fleet operators exhibit highest price sensitivity due to fuel-switch economics versus diesel, whereas captive power users prioritize supply security.
Supply Chain Analysis
Reverse-logistics flows for composite cylinder refurbishment and steel pipeline recovery are emerging as secondary material channels, though scale remains limited. Upstream supply draws from Qatar, Russia, and domestic KG-D6 fields for natural gas feedstock, with agricultural residue aggregation from Punjab and Haryana feeding compressed biogas plants. Single-source vulnerability concentrates through the Hazira-Vijaipur-Jagdishpur trunk line and its northern extensions. Distribution runs through city gate stations operated by GAIL Gas Limited and Gujarat Gas Limited, with last-mile polyethylene networks deployed by licensed geographic area operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India City Gas Distribution market functions as a geographic-arbitrage play where licensees in Gujarat and Maharashtra leverage amortized infrastructure against greenfield capital deployment costs in eastern states. Regulatory divergence between PNGRB-mandated blending obligations and state-level municipal cooperation frameworks creates differential rollout velocities worth monitoring.
For Market Incumbents: To counter margin compression from rising polyethylene and steel input costs, incumbents should deepen backward integration into compressed biogas production through direct agricultural residue aggregation partnerships in Punjab and Haryana. Channel control over CNG dispensing station networks in Mumbai and Delhi-NCR defends against new entrant poaching of high-volume fleet contracts. For New Entrants and Emerging Players: IoT-enabled smart metering platforms offer a technology-first wedge for new entrants lacking operational heritage in legacy geographies. West Bengal and Odisha present the most penetrable expansion corridors given underdeveloped pipeline density against rising industrial thermal demand from steel and ceramics manufacturing. A go-to-market angle anchored on industrial cogeneration partnerships with captive power users bypasses residential connection friction. For Investors and Strategic Acquirers: Valuations sit cheapest among regional pure-play distributors holding single-city exclusivity without upstream integration. Long-term viability across the five-to-ten year window hinges on compressed biogas blending execution and PNGRB licensing round success. The signal to watch is PNGRB authorization timing for eastern geographic areas, which would validate expansion thesis assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Compressed Biogas Plant Integration | Backward integration into agricultural residue processing secures SATAT-mandated supply under PNGRB purchase guarantees. |
| Smart Metering Platform Deployment | IoT-enabled consumption monitoring reduces commercial losses and improves demand forecasting precision for distribution licensees. |
| Eastern Geographic Area Bidding | PNGRB licensing rounds in West Bengal and Odisha unlock first-mover advantages in underpenetrated industrial corridors. |
| Industrial Cogeneration Partnership | Dedicated high-pressure line commitments from Gujarat ceramics manufacturers amortize trunk pipeline capital deployment. |
| Composite Cylinder Procurement Unification | Lightweight fiber-wrapped storage collapses procurement specifications across automotive and stationary buyer segments. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Delhi-NCR, Haryana, and West Bengal, with primary inputs from each region combined with secondary validation. Interviews with PNGRB licensing officers, city gas distribution project directors, agricultural residue aggregators, and industrial procurement managers at ceramics and steel plants informed demand-side assumptions. Secondary sources include PNGRB authorization records, Bureau of Indian Standards material specifications, SATAT framework purchase guarantee documentation, and Petroleum and Natural Gas Ministry policy circulars. Bottom-up connection and throughput estimates triangulate against top-down national gas consumption projections.
Rate-of-change decomposition separates volume growth from price movement across the analysis window, with segmentation modeling across fuel type, customer category, service tier, and end-use application. The analytical framework incorporates pipeline construction timelines, PNGRB licensing round schedules, and compressed biogas plant commissioning curves as industry-specific forecast inputs. CAGRs derive from geometric progression of annual volume estimates adjusted for regulatory mandate acceleration effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PNGRB authorization delays and agricultural residue supply chain development. Practitioners should monitor SATAT framework purchase guarantee utilization rates and state-level municipal cooperation agreement signings for early signals of rollout velocity revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Coal Market
Fuels
Global Methane Hydrate Market
Fuels
Oil Dispensing Stations Market
Fuels
China LNG Bunkering Market
Fuels
South America Aviation Fuel Market
Fuels
LNG Fueling Station Market
Fuels
Electric Fuel Heater Market
Fuels
LNG Filling Station Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
LPG Vaporizer Market
Fuels
China Coal Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
North America Bunker Fuel Market
Fuels
Charcoal Briquette Market