
 Liquefied Helium Tanks Market | 2026-2036
Liquefied Helium Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Liquefied Helium Tanks Market Analytics
Asset-light leasing models for cryogenic infrastructure is reshaping competitive entry barriers, allowing mid-scale buyers to access liquefied helium tanks without capital-intensive ownership. Linde plc leverages its integrated gas-to-tank value chain to sustain pricing power across industrial clusters. Air Products and Chemicals anchors its position through specialized engineering for high-purity helium containment systems. Iwatani Corporation differentiates via regional dominance in Asian cryogenic logistics networks.
Liquefied helium tanks are double-walled vacuum-insulated pressure vessels designed to maintain helium at cryogenic temperatures near minus 269 degrees Celsius, utilizing multi-layer insulation and suspended inner vessels to minimize boil-off losses for superconducting and analytical applications. Vacuum insulated tanks occupy the largest installed base due to their thermal efficiency in long-duration storage, while portable tanks represent the fastest-growing configuration as field-deployable cryogenics expand in semiconductor manufacturing and space launch operations. Dewar vessels retain niche margins in scientific research settings where small-volume precision dispensing governs procurement decisions.
The US Department of Transportation enforces cryogenic tank certification under 49 CFR standards, while the EU Pressure Equipment Directive mandates CE-marked conformity for helium transport vessels entering European territory, collectively elevating manufacturing compliance costs and consolidating supplier qualification pools. China's SAMR oversees national cryogenic vessel safety codes under GB standards, creating divergent testing protocols that fragment market access requirements. Stakeholders must monitor evolving hydrogen-helium infrastructure overlap as dual-use tank specifications gain regulatory traction.
Market Dynamics
Helium supply concentration in Qatar's North Field expansion is forcing buyers to secure dedicated cryogenic storage capacity ahead of liquefaction bottlenecks, restructuring procurement from spot markets toward long-term tank leasing arrangements.
Growth Catalysts
- Superconducting magnet proliferation:MRI manufacturers are expanding helium storage footprints as high-field magnet systems require larger cryogen volumes for continuous operation.
- 49 CFR certification tightening:The US Department of Transportation's enhanced cryogenic tank standards are accelerating fleet replacement cycles among North American logistics operators.
- Semiconductor fab buildouts:Advanced lithography systems using extreme ultraviolet technology consume helium for plasma generation, driving demand for portable dewar configurations at fabrication sites.
Market Restraints
- Helium feedstock scarcity:Concentration of crude helium extraction in Qatar and Algeria creates supply vulnerability for tank operators dependent on predictable fill cycles.
- Multi-layer insulation cost volatility:Aluminum foil and fiberglass paper prices fluctuate with energy markets, compressing margins on vacuum-insulated vessel production.
- CE marking complexity:The EU Pressure Equipment Directive's conformity assessment procedures extend certification timelines by eight to fourteen months for new tank designs.
Strategic Opportunities
- Space launch cryogenics:Reusable rocket programs in Texas and Florida require field-deployable helium tanks for propellant tank pressurization, opening dedicated aerospace specifications.
- India's PLI scheme for semiconductors:Production-linked incentives for domestic chip fabrication will necessitate localized helium logistics infrastructure.
- Hydrogen-helium dual-use vessels:Converging cryogenic storage specifications for liquid hydrogen and helium are enabling tank manufacturers to serve emerging clean hydrogen supply chains.
Industry Challenges
- Welder certification scarcity:Qualified technicians for stainless steel cryogenic vessel fabrication are concentrated in Germany and Japan, constraining production scaling.
- Legacy fleet retrofit complexity:Existing tanks lack telemetry integration for boil-off monitoring, complicating fleet digitization initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquefied Helium Tanks Market |
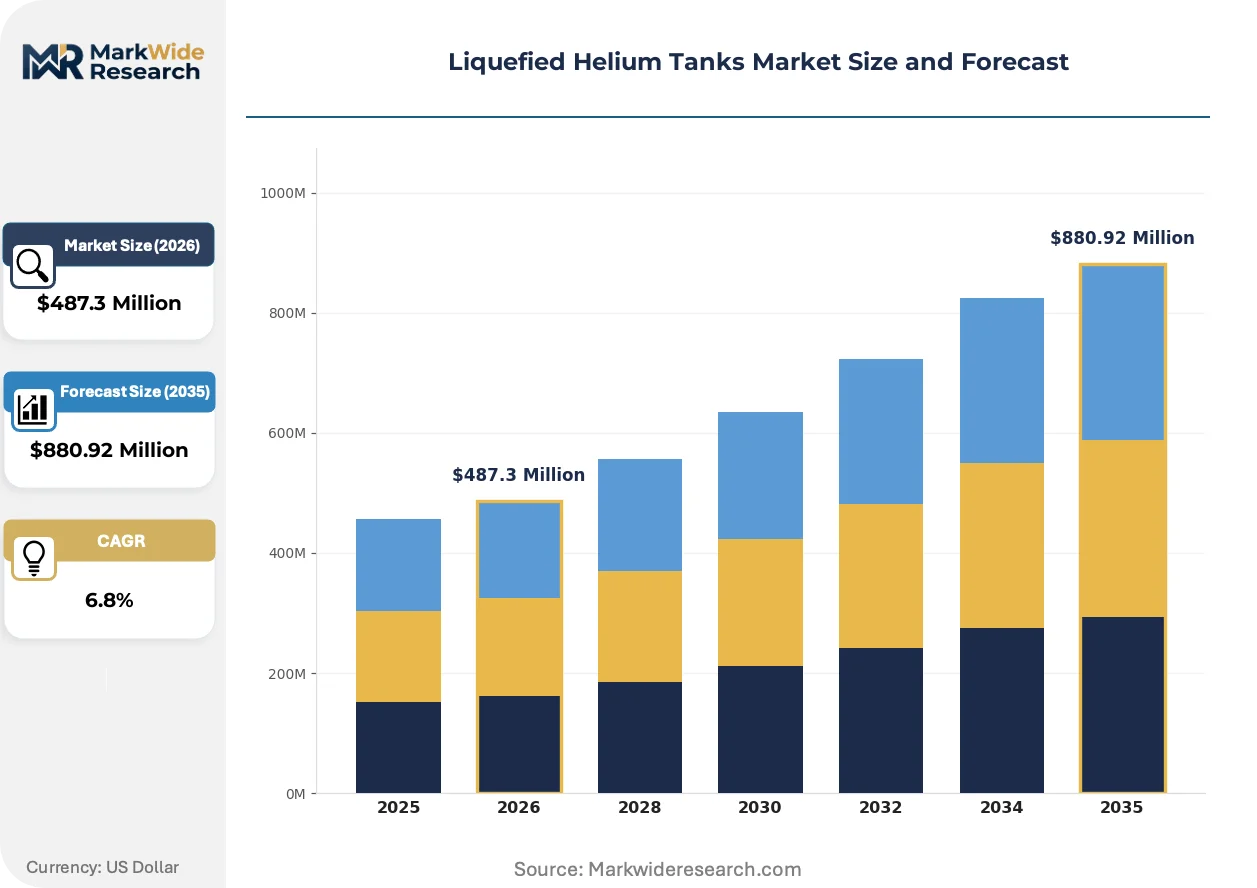
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Insulated Tanks, Pressure Vessels, Portable Tanks, Dewars End User: Aerospace, Healthcare, Research Institutes, Industrial Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Application: Cryogenics, LNG, Electronics Cooling, Scientific Research |
| Companies Covered | Air Liquide, Air Products and Chemicals, Linde plc, Gazprom, Messer Group, Matheson Tri-Gas, QatarEnergy, Iwatani Corporation, Gulf Cryo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquefied Helium Tanks Market Evolving Landscape
Active insulation systems and predictive maintenance telemetry are displacing passive storage designs across high-value helium applications, compressing operational cost structures for buyers with continuous consumption profiles.
Magnetic levitation suspension systems for inner vessels are migrating from aerospace prototypes to commercial MRI helium tanks. Hospital procurement groups in the United States are specifying these configurations for new magnet installations. The technology is migrating from premium aerospace applications toward mid-scale healthcare deployments, enabling longer hold times between refills.
The EU F-Gas Regulation's phasedown of fluorinated greenhouse gases is redirecting engineering resources toward helium recovery and reclamation systems. Industrial gas distributors must now account for vented helium in carbon-equivalent reporting. Semiconductor manufacturers in the Netherlands and Ireland are installing closed-loop helium purification to maintain access to EU-sourced supply.
Buyers are consolidating tank procurement through integrated service contracts bundling equipment, logistics, and helium supply. Electronics manufacturers in South Korea are replacing separate vendor relationships with single-source cryogenic service agreements. This consolidation is most visible in the Gyeonggi-do cluster, where three major memory chip producers have shifted to ten-year operational leases.
Liquefied Helium Tanks Market Segmentation
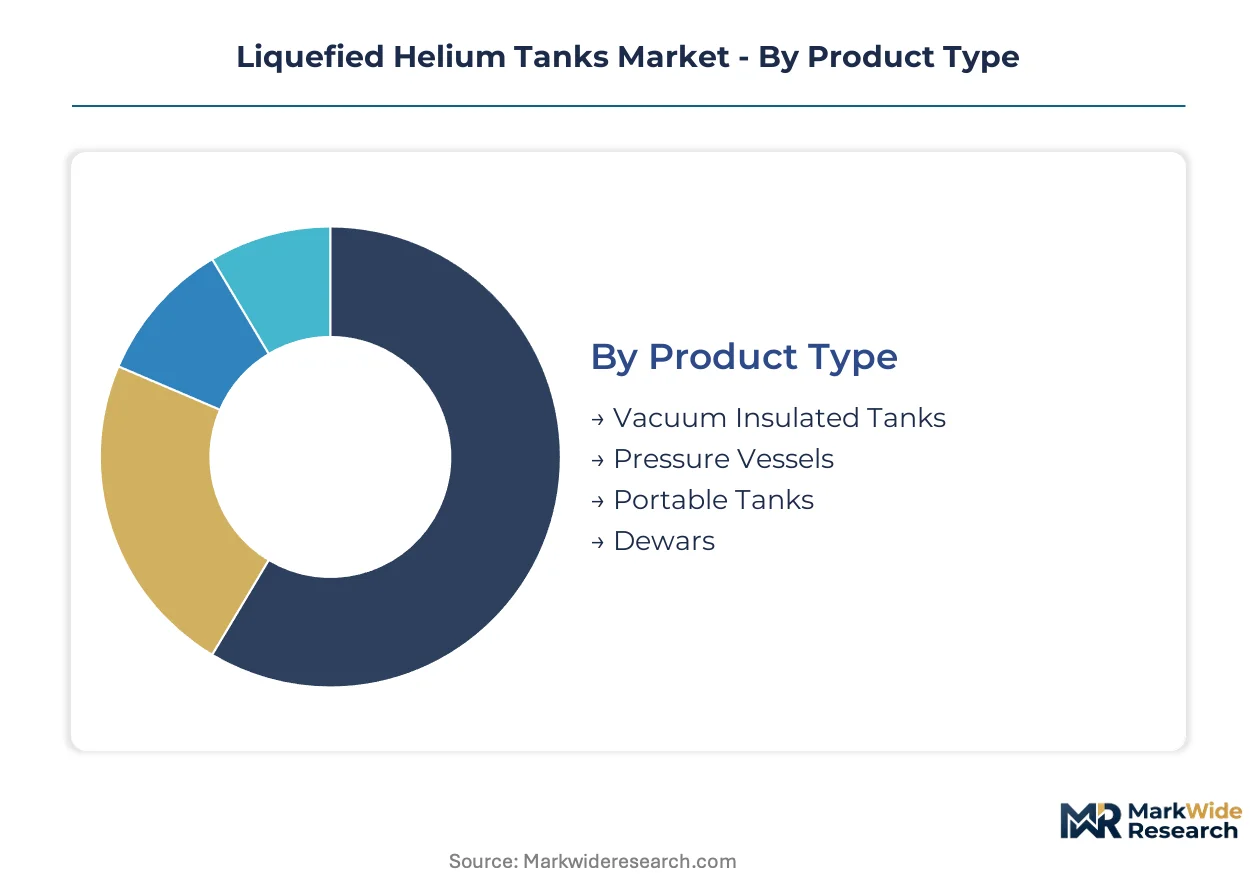
Helium tank procurement patterns diverge sharply across use-case thermal requirements and mobility constraints. Buyers prioritize thermal efficiency for stationary bulk storage versus portability for field-deployed cryogenics.
Product Type:
Mature vacuum-insulated designs dominate installed base economics, while emerging portable configurations reshape deployment flexibility for distributed applications.
- Vacuum Insulated Tanks:Double-walled vessels with multi-layer insulation and suspended inner chambers maintain helium at minus 269 degrees Celsius with minimal boil-off. Healthcare facilities in the United States specify these for MRI magnet cooling where continuous thermal stability governs operational uptime.
- Portable Tanks:Field-deployable dewar configurations enable cryogen transport to semiconductor fabrication sites and space launch facilities. Texas and Florida aerospace clusters are driving specification changes for rapid-connect fittings and telemetry integration.
- Pressure Vessels:High-pressure containment systems serve industrial gas distribution networks requiring gaseous helium delivery.
- Dewars:Small-volume precision vessels address laboratory-scale dispensing requirements in academic and government research settings.
Vacuum insulated tanks handle the majority of throughput; portable tanks are gaining share fastest among new deployments.
End User:
Cost tier separation between capital-intensive healthcare infrastructure and research-funded scientific installations drives specification divergence across buyer categories.
- Healthcare:MRI manufacturers and hospital procurement groups require certified tanks meeting FDA device standards and DOT 49 CFR transport rules. Superconducting magnet proliferation in diagnostic imaging centers is expanding helium storage footprints at major medical device installations.
- Aerospace:Reusable rocket programs demand field-deployable tanks for propellant pressurization with rapid-cycle filling protocols. Space launch facilities in Texas specify aerospace-grade telemetry integration for boil-off monitoring during countdown sequences.
- Research Institutes:National laboratories and university physics departments prioritize precision dispensing and minimal vibration transfer for sensitive instrumentation.
- Industrial:Welding shielding gas applications and leak detection systems consume helium in manufacturing quality control processes.
Healthcare commands the largest equipment procurement budgets; aerospace is expanding most quickly on contract volume.
Distribution Channel:
Customer type segmentation separates integrated service buyers seeking bundled solutions from transactional purchasers optimizing unit economics.
- Direct Sales:Original equipment manufacturers and integrated gas suppliers negotiate long-term service contracts bundling tanks, logistics, and helium supply. South Korean electronics manufacturers in the Gyeonggi-do cluster have consolidated vendor relationships through ten-year operational leases.
- Distributors:Regional industrial gas specialists maintain localized inventory for maintenance, repair, and emergency replacement demand.
- Online Sales:Digital procurement platforms serve small-volume research buyers with standardized dewar configurations and rapid fulfillment.
- Retail:Limited presence confined to welding supply outlets for gaseous helium cylinder exchange programs.
Direct sales channels manage the highest contract values; online platforms are climbing fastest in transaction velocity.
Application:
Volume requirements span orders of magnitude from milliliter-scale scientific dispensing to tonnage-level industrial liquefaction, fragmenting supplier qualification pools.
- Cryogenics:Superconducting systems require continuous helium circulation for magnet cooling in MRI installations and particle accelerators. The EU F-Gas Regulation's fluorinated gas phasedown is redirecting engineering resources toward helium recovery infrastructure in Netherlands and Ireland semiconductor facilities.
- Electronics Cooling:Extreme ultraviolet lithography systems in advanced semiconductor manufacturing consume helium for plasma generation and temperature stabilization. India's PLI scheme for domestic chip fabrication will necessitate localized helium logistics infrastructure.
- Scientific Research:Low-temperature physics experiments and quantum computing prototypes demand ultra-high purity containment with minimal contamination risk.
- LNG:Liquefied natural gas facilities utilize helium for leak detection and cryogenic pipeline purging during maintenance cycles.
Cryogenics applications absorb the dominant share of tank capacity; electronics cooling is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives for semiconductor manufacturing are redrawing cryogenic infrastructure investment maps across major economies. Qatar's North Field expansion continues to anchor helium feedstock availability, while regulatory tightening in transport certification reshapes tank procurement timelines in developed markets.
United States
FDA device standards and DOT 49 CFR transport rules govern MRI helium tank procurement at hospital systems. The FAA oversees aerospace-grade specifications for reusable rocket programs in Texas and Florida. Space launch facilities in Boca Chica and Cape Canaveral are driving demand for field-deployable tanks with rapid-connect telemetry integration.
Germany
CE marking under the EU Pressure Equipment Directive extends certification timelines for new tank designs entering European territory. The country's national cryogenic vessel safety regulator enforces conformity assessment procedures that consolidate supplier qualification pools. Industrial gas distributors in the Ruhr Valley are retrofitting legacy fleets with boil-off monitoring systems.
China
SAMR oversees national cryogenic vessel safety codes under GB standards, creating divergent testing protocols that fragment market access requirements. The country's dual carbon goals are redirecting engineering resources toward hydrogen-helium dual-use vessel specifications. Yangtze River Delta semiconductor fabs are expanding helium storage footprints for extreme ultraviolet lithography systems.
India
The PLI scheme for domestic chip fabrication is necessitating localized helium logistics infrastructure across the subcontinent. BIS certification requirements govern pressure equipment imports for cryogenic applications. Karnataka and Telangana are emerging as concentration points for new semiconductor manufacturing clusters with dedicated tank leasing arrangements.
South Korea
MFDS regulations intersect with industrial gas distribution standards for healthcare and electronics applications. The Seoul Capital Area memory chip producers in Gyeonggi-do have consolidated vendor relationships through ten-year operational leases bundling tanks, logistics, and helium supply. Busan-Ulsan port infrastructure is expanding cryogenic handling capacity for import-dependent feedstock security.
Liquefied Helium Tanks Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where integrated gas suppliers hold pricing power through captive helium sourcing. Three archetypes dominate: vertically integrated industrial gas majors with in-house tank fabrication, specialized cryogenic engineering firms focused on containment systems, and regional logistics operators leasing standardized vessel fleets. Competitive moves concentrate on backward integration into helium extraction assets and geographic expansion through operational lease portfolios.
Among integrated industrial gas suppliers, Linde plc, Air Products and Chemicals, and Iwatani Corporation occupy positions that exemplify distinct strategic vectors. Linde plc represents the vertically integrated archetype with upstream control over gas-to-tank value chains. Air Products and Chemicals sits within the specialized engineering tier for high-purity containment applications. Iwatani Corporation anchors the regional logistics archetype through Asian cryogenic network dominance.
| Leading Market Players |
|---|
| Air Liquide |
| Air Products and Chemicals |
| Linde plc |
| Gazprom |
| Messer Group |
| Matheson Tri-Gas |
| QatarEnergy |
| Iwatani Corporation |
| Gulf Cryo |
| Others |
Value Network & Pricing Analysis
Qatar's North Field helium concentration anchors feedstock pricing power upstream, while downstream margin pools concentrate with integrated gas suppliers controlling captive liquefaction and tank leasing networks. Buyers face asymmetric bargaining positions when negotiating long-term tank contracts against suppliers with backward integration into extraction assets.
Pricing Analysis
Certification level creates the primary spread between DOT 49 CFR-grade aerospace vessels and standard industrial configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA device-grade, CE-marked transport, and uncertified laboratory dewar tiers. Cost compression in standard industrial vessels is intensifying because aluminum foil and fiberglass paper input volatility squeezes multi-layer insulation margins. Hospital procurement groups show lowest price sensitivity given magnet uptime requirements, while research institutes optimize for unit economics on small-volume orders.
Supply Chain Analysis
Extended payment terms from integrated gas majors are squeezing regional tank fabricators dependent on stainless steel supply-chain finance facilities. Manufacturing draws from Germany, Japan, and China for qualified welder pools and cryogenic-grade stainless steel feedstock. Single-source vulnerability concentrates in Qatar and Algeria for crude helium extraction. Distribution runs through direct operational lease contracts bundling equipment, logistics, and helium supply to electronics and healthcare clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from telemetry-enabled boil-off monitoring and predictive maintenance contracts is expanding faster than hardware sales, repositioning tank procurement as a lifecycle service relationship rather than capital equipment transaction.
For Market Incumbents: Pre-empt hydrogen-helium dual-use vessel specifications before clean hydrogen infrastructure scales, locking in certification lead time advantages. Deepen backward integration into Qatar's North Field expansion through dedicated offtake agreements. Counter emerging regional logistics operators in India and Southeast Asia by accelerating ten-year operational lease penetration. For New Entrants and Emerging Players: Build out portable tank configurations for India's PLI-driven semiconductor clusters where localized helium logistics infrastructure remains underdeveloped. Target Karnataka and Telangana fab buildouts with rapid-connect telemetry integration as the most penetrable geography. Pursue asset-light leasing models to bypass capital-intensive fabrication capacity requirements. For Investors and Strategic Acquirers: Capital is best deployed toward specialized cryogenic engineering firms with CE-marking expertise and established welder certification pipelines in Germany or Japan. Long-term viability hinges on regulatory compliance capabilities tightening across DOT, EU Pressure Equipment Directive, and SAMR jurisdictions. Watch hydrogen-helium dual-use vessel order books as inflection indicator for clean hydrogen infrastructure convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Helium Extraction | Captive feedstock from Qatar's North Field insulates margin against spot price volatility. |
| CE Marking Acceleration | Compressed fourteen-month certification timelines open first-mover advantage in EU healthcare procurement. |
| Telemetry-Enabled Fleet Retrofit | Boil-off monitoring contracts convert hardware sales into recurring service revenue streams. |
| Hydrogen-Helium Dual-Use Vessel Development | Converging cryogenic specifications access emerging liquid hydrogen supply chain demand. |
| India PLI Localization Partnership | Karnataka and Telangana semiconductor clusters require dedicated tank leasing infrastructure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOT certification databases, EU Pressure Equipment Directive filings, and customs trade records for cryogenic vessel imports. Plant managers at MRI magnet manufacturers, procurement leads at semiconductor fabs, and aftermarket service heads at industrial gas distributors provided operational data. Bottom-up tank deployment counts triangulate against top-down helium consumption estimates from national statistics offices.
Forecast inputs span vacuum-insulated versus portable tank configurations, healthcare versus aerospace end-use segmentation, and direct sales versus distributor channel splits across the analysis window. CAGRs derive from modeled helium demand intensity per MRI installation and EUV lithography system deployment. Semiconductor fab buildout pipelines and space launch facility expansion schedules inform electronics cooling and aerospace application trajectories.
Sensitivities concentrate around Qatar supply disruption, CE marking timeline extensions, and hydrogen infrastructure convergence pace. Forecasts reflect assumptions on welder certification availability and aluminum foil input cost stability. Macroeconomic contraction in semiconductor capital expenditure, regulatory restriction on helium venting under EU F-Gas Regulation, or breakthrough in high-temperature superconducting magnet technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Brazil LNG Market
Fuels
South Africa Bunker Fuel Market
Fuels
Gasoline Market
Fuels
Mobile Gas Pumping System Market
Fuels
LPG Tanker Market
Fuels
Gasoline Octane Improvers Market
Fuels
Global Gas Treatment Market
Fuels
High Octane Racing Fuel Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Aboveground Fuel Storage Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Biobutanol Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market