
 North America Aviation Fuel Market | 2026-2036
North America Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aviation Fuel Market Analytics
The North America aviation fuel supply base is pivoting between conventional Jet A refining and sustainable aviation fuel (SAF) production, with capital allocation diverging sharply between legacy hydrocarbon infrastructure and biorefinery builds. Exxon Mobil Corporation leverages its integrated Gulf Coast refining network to sustain high-volume Jet A output for commercial carriers. Chevron Corporation anchors West Coast supply through its Richmond and El Segundo facilities, while Shell PLC differentiates via SAF partnerships with biofuel developers.
North America aviation fuel comprises refined petroleum products meeting strict ASTM specifications—Jet A requires a minimum flash point of 38°C and freeze point below -40°C—formulated to power turbine engines under extreme altitude and temperature conditions. Jet A and Jet A-1 dominate volume, with Jet A-1 gaining structural share on international flights due to its lower freeze point specification for polar routes. Biofuel represents the fastest-expanding fuel type, though margin pools currently concentrate in direct sales channels serving major commercial airlines with long-term offtake agreements.
The EPA enforces renewable fuel obligations under the RFS program, while the FAA coordinates SAF certification through ASTM D7566, and Transport Canada imposes parallel Clean Fuel Regulations on aviation fuel imports. These frameworks shape refinery investment timelines and product slate decisions across the continent. Stakeholders must monitor blending mandate trajectories and biorefinery construction schedules to align supply commitments with evolving certification requirements.
Market Dynamics
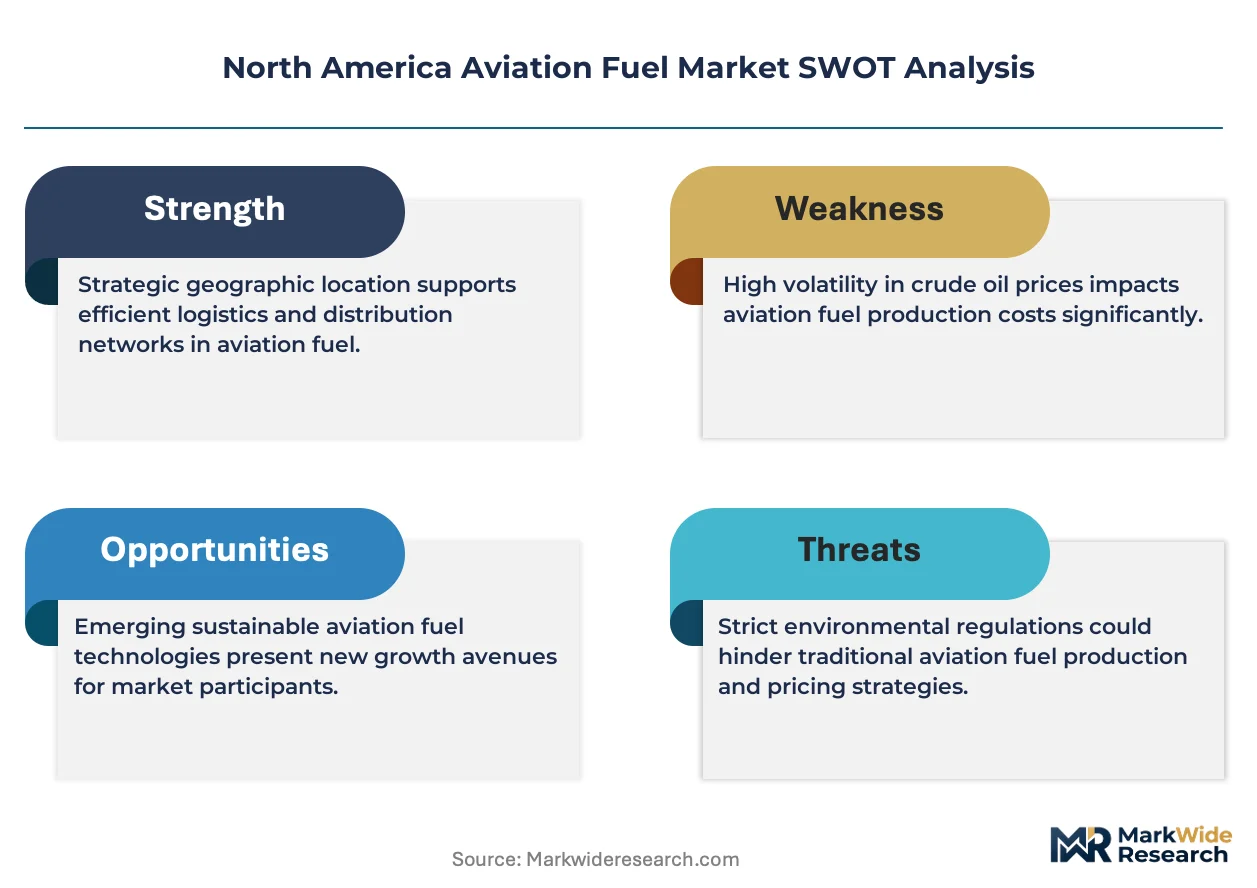
Jet A and SAF production capacity allocation represents the dominant structural tension across North American aviation fuel supply, as refiners weigh sunk-cost hydrocarbon infrastructure against biorefinery capital commitments under tightening EPA renewable fuel obligations.
Growth Catalysts
- EPA Renewable Fuel Standard mandates:Blending obligations for SAF at major US hubs are accelerating offtake contract negotiations between biorefineries and commercial carriers.
- Transcontinental fleet utilization:United States and Canadian airlines are expanding route density on long-haul corridors, concentrating fuel demand at Atlanta Hartsfield-Jackson and Dallas-Fort Worth distribution nodes.
- ASTM D7566 certification pathway:The FAA-coordinated standard is unblocking biofuel deployment for turbine engines, creating regulatory clarity for refinery investment decisions.
Market Restraints
- Feedstock cost volatility:Agricultural oil and waste lipid prices fluctuate with commodity crop cycles, compressing SAF margin pools against stable Jet A refining economics.
- Gulf Coast refining concentration:Exxon Mobil's integrated network dominates high-volume Jet A output, creating supply vulnerability during hurricane-season disruptions.
- Freeze point specification divergence:Jet A-1's lower freeze point requirement for polar routes fragments inventory management, forcing carriers to maintain dual fuel stocks.
Strategic Opportunities
- US Southeast hub expansion:Atlanta and Dallas-Fort Worth anchoring positions enable backward integration into regional biorefinery builds with direct pipeline connectivity.
- Power-to-liquid synthesis:Electrofuel pathways combining renewable hydrogen with captured carbon are opening novel production routes independent of agricultural feedstocks.
- Clean Fuel Regulations alignment:Transport Canada's parallel mandates create cross-border certificate trading potential for US producers with excess RIN generation.
Industry Challenges
- ASTM certification timeline compression:Novel biofuel pathways require multi-year approval cycles, delaying commercial deployment against mandate deadlines.
- Legacy infrastructure retrofit complexity:Existing Jet A storage and pipeline systems demand material compatibility testing before SAF blending ratios can escalate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aviation Fuel Market |
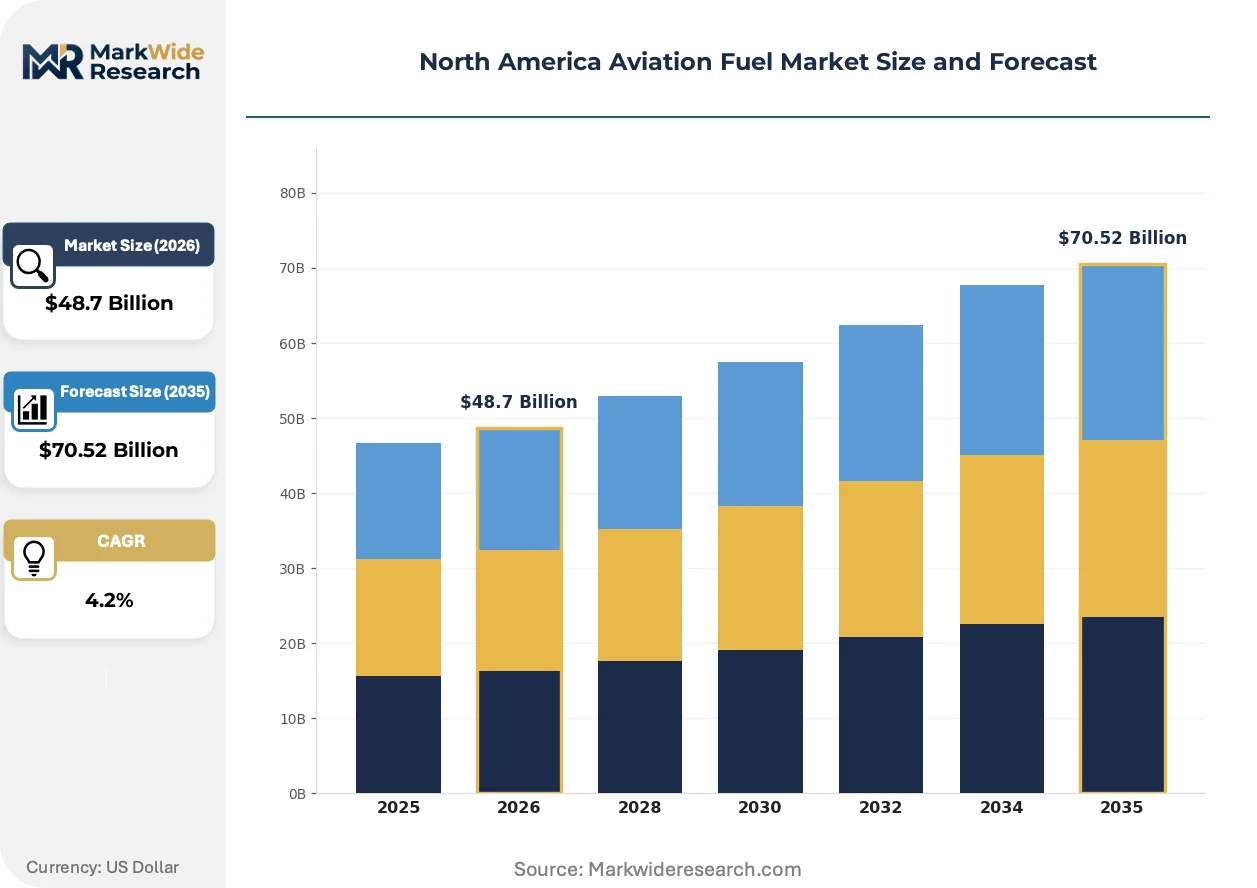
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Avgas, Biofuel End User: Commercial Airlines, Military, Cargo Operators, Private Aviation Distribution Channel: Direct Sales, Retail, Online, Wholesale Application: Domestic Flights, International Flights, Training Flights, Freight Transport |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, BP PLC, Shell PLC, TotalEnergies SE, Valero Energy Corporation, Suncor Energy Inc., Hess Corporation, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aviation Fuel Market Evolving Landscape
Digital fuel management platforms and alternative feedstock pathways are compressing the traditional separation between conventional refining and biofuel production, eroding the operational silos that historically structured supply chain decisions.
Hydrotreated esters and fatty acids (HEFA) technology is unifying agricultural waste processing with aviation-grade fuel output. Major US carriers are embedding HEFA offtake into long-term procurement contracts. This unification is collapsing the distinction between energy and agricultural commodity supply chains, forcing fuel buyers to develop feedstock hedging capabilities.
The EPA's renewable volume obligations under the RFS program are tightening blending mandates for transportation fuels. Refiners face capital allocation pressure between hydrotreater upgrades and greenfield biorefinery construction. US Southeast distribution hubs are responding by pre-positioning storage capacity for segregated SAF batches ahead of mandate escalation.
Long-term offtake agreements are displacing spot market procurement for commercial airlines. Direct sales channels between biorefineries and carrier procurement departments are consolidating volume commitments. This shift is most visible at Atlanta Hartsfield-Jackson, where Delta Air Lines has structured dedicated supply arrangements bypassing traditional distributor intermediaries.
North America Aviation Fuel Market Segmentation
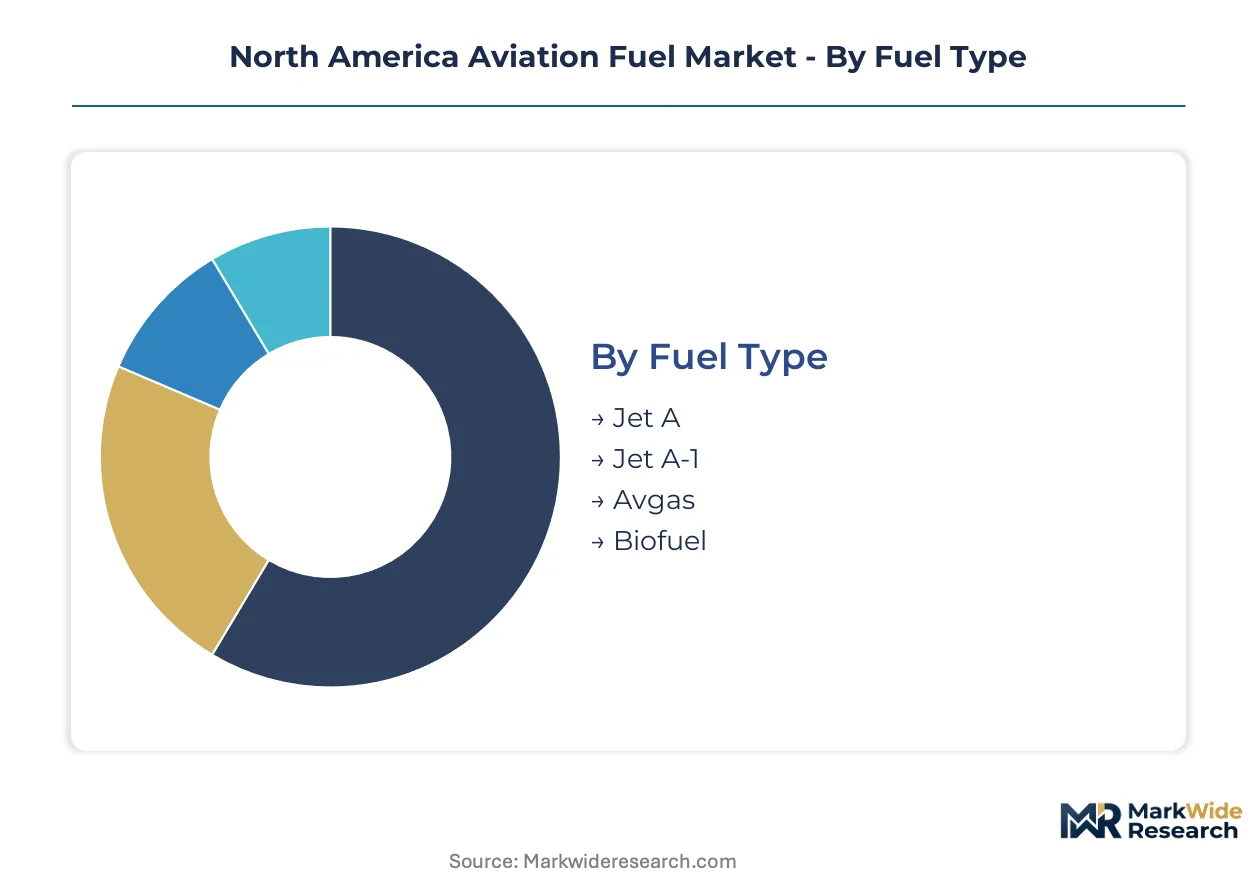
Segmentation reveals how fuel specifications, user requirements, and distribution economics fragment procurement strategies across North American aviation. Each dimension exposes distinct margin pools and infrastructure dependencies that shape supplier positioning.
Fuel Type:
Upgrade cycles between conventional and sustainable formulations are restructuring refinery capital allocation across the continent.
- Jet A:Refined kerosene meeting ASTM D1655 with 38°C minimum flash point and -40°C freeze point ceiling. Demand concentrates at Atlanta Hartsfield-Jackson and Dallas-Fort Worth hubs serving domestic narrow-body fleets, constrained by EPA renewable volume obligations that mandate escalating SAF blending.
- Jet A-1:Lower freeze point specification of -47°C enables polar route operations without fuel warming systems. International departures from New York JFK and Los Angeles LAX anchor procurement volumes, driven by Transport Canada Clean Fuel Regulations requiring cross-border certificate alignment.
- Avgas:High-octane aviation gasoline for piston engines with leaded and unleaded variants. Private airfields and flight schools in Texas and Florida sustain demand.
- Biofuel:HEFA and emerging power-to-liquid pathways certified under ASTM D7566. Long-term offtake contracts with Delta and United are compressing spot market exposure.
Jet A leads volumes today; biofuel is gaining share fastest.
End User:
Procurement scale and contract duration diverge sharply between scheduled carriers and mission-driven operators.
- Commercial Airlines:Network carriers with 500+ aircraft fleets negotiate multi-year direct supply agreements. United States majors are embedding SAF procurement into ESG-linked financing structures.
- Military:Defense Logistics Agency Energy manages strategic petroleum reserves with Jet A-1 for tanker and transport operations. Fuel security mandates override cost optimization.
- Cargo Operators:FedEx and UPS operate dedicated fuel hedging desks matching jet fuel exposure to package volume forecasts. Memphis and Louisville distribution nodes require 24-hour supply guarantees.
- Private Aviation:Fractional ownership fleets and charter operators purchase through FBO networks with volume-tier pricing. California and Florida account for disproportionate Avgas consumption.
Commercial airlines command procurement volume; cargo operators are expanding capacity fastest.
Distribution Channel:
Channel selection reflects buyer scale, storage infrastructure, and risk transfer preferences.
- Direct Sales:Refinery-to-carrier contracts eliminating intermediary margins. Delta's Atlanta supply arrangement exemplifies backward integration into terminal operations.
- Retail:Fixed-base operators serving general aviation with marked-up per-gallon pricing. Regional airport economics depend on throughput minimums.
- Online:Digital procurement platforms for spot market exposure and price discovery. Emerging among mid-size cargo fleets.
- Wholesale:Distributor networks aggregating volumes for smaller carriers and international airlines without US terminal access.
Direct sales dominate value capture; online channels are expanding transaction velocity fastest.
Application:
Route distance and operational tempo dictate fuel specification mixing and inventory positioning.
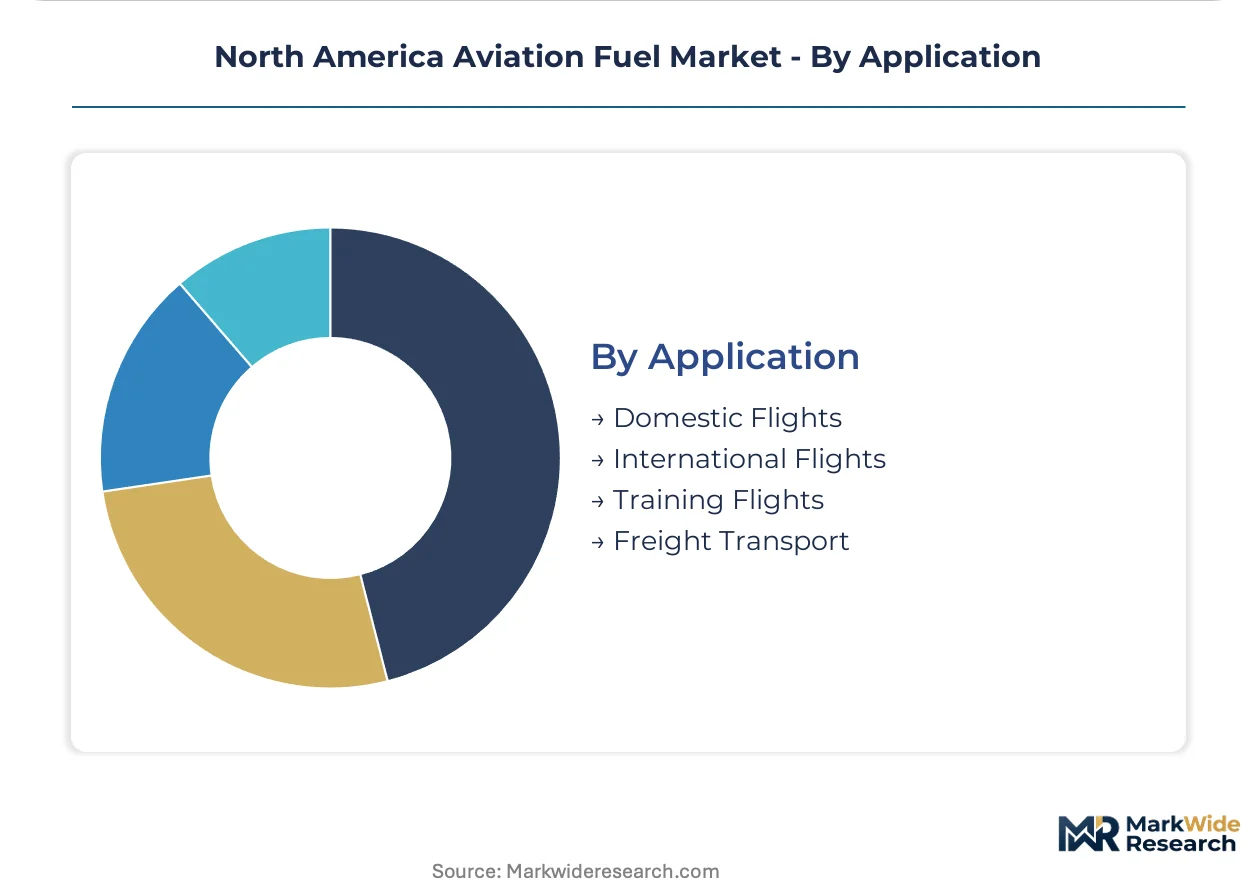
- Domestic Flights:Short-haul operations utilizing Jet A with minimal cold-weather requirements. US Southeast corridor density supports pipeline-fed hub economics.
- International Flights:Long-haul polar and transoceanic routes requiring Jet A-1 freeze point compliance. EPA renewable obligations apply to fuel uplifted at US airports regardless of destination.
- Training Flights:Repetitive pattern work at flight schools consuming Avgas in high-frequency, low-volume transactions.
- Freight Transport:Time-definite cargo operations with fuel cost passed through to shippers via fuel surcharges indexed to US Gulf Coast jet fuel spot prices.
Domestic flights anchor consumption volume; freight transport is expanding tonne-kilometers fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery technicians and petrochemical engineers cluster along the Gulf Coast and Midwest pipeline corridors, anchoring North American aviation fuel production capacity.
United States
Atlanta Hartsfield-Jackson and Dallas-Fort Worth concentrate Jet A demand from domestic narrow-body fleets. EPA renewable fuel obligations under the RFS program mandate escalating SAF blending at major hubs. Gulf Coast refineries in Texas and Louisiana sustain high-volume kerosene output for commercial carriers.
Canada
Transcontinental polar routes drive Jet A-1 procurement at Toronto Pearson and Vancouver International. Transport Canada Clean Fuel Regulations impose certificate requirements on aviation fuel imports. Suncor Energy operates integrated refining at Edmonton serving western Canadian carriers.
Mexico
Mexico City International anchors Central American connecting traffic with growing fuel uplift volumes. Energy regulatory reforms under CRE open refined product import licensing to private distributors. Tula and Salamanca refineries process domestic crude for regional jet fuel supply.
North America Aviation Fuel Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light biofuel developers for procurement relationships with major carriers. The supplier base concentrates around petroleum majors with Gulf Coast infrastructure and emerging biorefinery specialists. Two strategic archetypes dominate: legacy hydrocarbon producers leveraging sunk-cost refining networks, and technology-forward developers securing long-term SAF offtake contracts. Competitive moves center on hydrotreater upgrades for renewable diesel coproduction and direct airline partnerships bypassing distributor intermediaries.
Within the integrated petroleum tier, Exxon Mobil Corporation and Chevron Corporation exemplify capital-intensive refining archetypes anchored to Gulf and West Coast infrastructure. Shell PLC occupies a transitional position, representing the pivot toward biorefinery partnerships and ASTM D7566-certified sustainable fuel pathways.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP PLC |
| Shell PLC |
| TotalEnergies SE |
| Valero Energy Corporation |
| Suncor Energy Inc. |
| Hess Corporation |
| Phillips 66 |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between ASTM D1655 conventional Jet A and ASTM D7566-certified sustainable aviation fuel manifests in dual pricing regimes and bifurcated supply chain investments. Major US carriers negotiate long-term offtake contracts for SAF at premiums reflecting biorefinery capital recovery, while Gulf Coast refiners maintain spot-market Jet A pricing anchored to Gulf Coast spot indices and pipeline tariff structures.
Pricing Analysis
Direct sales contracts versus wholesale distributor markups define the dominant pricing split. Long-term offtake agreements between biorefineries and network carriers like Delta and United embed volume-scale and certification-grade price differentiation. Pricing pressure stems from agricultural feedstock volatility compressing SAF margin pools against stable hydrocarbon refining economics. Cargo operators with dedicated hedging desks exhibit lowest price sensitivity; fractional ownership fleets purchasing through FBO retail channels face highest per-gallon exposure.
Supply Chain Analysis
Empty tanker returns and contaminated batch segregation flows shape reverse logistics complexity in aviation fuel distribution. Supply concentrates in Texas, Louisiana, and California, with Gulf Coast refineries drawing from domestic crude and Canadian heavy oil feedstocks. Agricultural oil and waste lipid dependencies expose SAF producers to commodity crop cycle volatility. Hurricane-season disruption represents the dominant structural risk to Gulf Coast refining concentration. Distribution runs through pipeline-fed hub terminals at Atlanta Hartsfield-Jackson and Dallas-Fort Worth, with final mile delivery via airport hydrant systems and into-plane services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America aviation fuel market functions as a geographic-arbitrage play between EPA renewable fuel obligation stringency in the United States and Transport Canada Clean Fuel Regulations certificate alignment requirements, with compliance cost differentials driving cross-border supply repositioning.
For Market Incumbents: Deepen backward integration into regional biorefinery builds with direct pipeline connectivity to Atlanta and Dallas-Fort Worth distribution nodes. Incumbents must defend against emerging HEFA technology developers by accelerating hydrotreater upgrades for renewable diesel coproduction, leveraging sunk-cost Gulf Coast infrastructure while EPA mandate timelines compress. Channel control through dedicated terminal operations represents the critical defensive lever against asset-light biofuel entrants.
For New Entrants and Emerging Players: Capture power-to-liquid synthesis pathways combining renewable hydrogen with captured carbon, bypassing agricultural feedstock dependencies that constrain HEFA economics. The most penetrable white space sits in electrofuel production serving international departures from New York JFK and Los Angeles LAX requiring Jet A-1 freeze point compliance. A direct airline partnership model bypassing distributor intermediaries—exemplified by Delta's Atlanta supply arrangement—offers the clearest go-to-market angle for volume commitment security.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented biorefinery developers lack offtake contract scale to justify standalone capital deployment. Long-term viability across the next decade hinges on ASTM D7566 certification pathway access and EPA renewable volume obligation trajectory alignment. Acquisition targets should display captive feedstock arrangements or power-to-liquid technology differentiation. Practitioners should monitor EPA mandate escalation schedules and biorefinery construction completion rates for early inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biorefinery Assets | Exxon Mobil and Chevron leverage Gulf Coast infrastructure for SAF coproduction capacity. |
| Long-term Offtake Agreement Structuring | Delta's Atlanta arrangement eliminates distributor margins and secures dedicated supply. |
| Power-to-Liquid Technology Investment | Electrofuel pathways reduce agricultural feedstock dependency for emerging producers. |
| Pipeline Connectivity Expansion | Direct terminal links to Dallas-Fort Worth and Atlanta hubs reduce logistics chokepoint exposure. |
| ASTM D7566 Certification Acceleration | FAA-coordinated approval timelines determine commercial deployment viability against mandate deadlines. |
Research Methodology
Direct dialogue with refinery operations managers, airline fuel procurement directors, biorefinery project developers, and EPA regulatory affairs specialists grounded qualitative insights, validated against EIA petroleum supply data, FAA certification filings, EPA renewable fuel standard docket records, and SEC 10-K refinery segment disclosures. Bottom-up volume modeling triangulated with top-down market sizing across fuel type, end user, and distribution channel dimensions.
Segment-level value outputs across the projection horizon reflect structured growth rate derivation incorporating Jet A-1 freeze point specification demand for polar routes, SAF blending mandate trajectories under EPA renewable volume obligations, and transcontinental fleet utilization patterns at major hub airports. Modeled dimensions span fuel certification grade, end-user procurement scale, distribution channel structure, and application route distance. CAGRs were derived from production capacity buildout schedules and offtake contract velocity analysis.
Feedstock price volatility, ASTM certification timeline delays, and hurricane-season supply disruption are the dominant revision risks to forecast outputs. Forecasts reflect assumptions regarding EPA mandate enforcement consistency and biorefinery construction completion rates. Practitioners should monitor agricultural commodity futures, FAA certification docket progress, and Gulf Coast weather pattern severity for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Methane Market
Fuels
India Petrol Station Market
Fuels
Smart Gas Solutions Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Biobutanol Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Europe Aviation Fuel Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
LNG Filling Station Market
Fuels
South Africa Bunker Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Global Gas Treatment Market