
 Renewable Energy Cable Market | 2026-2036
Renewable Energy Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Cable Market Insights
Modular cable bundling is broadening procurement options for offshore wind developers. Prysmian Group leverages integrated manufacturing from conductor drawing to armoring. Nexans anchors its position through deepwater installation capabilities and project-specific engineering. NKT A/S specializes in high-voltage direct current systems for long-distance submarine transmission.
Renewable energy cables are engineered conductors with cross-linked polyethylene or ethylene propylene rubber insulation, designed to transmit power from generation assets to grid interconnection points under variable thermal, mechanical, and environmental loads. Submarine cable dominates value capture due to specialized armoring and installation complexity. Wind power application leads volume demand, while solar power represents the fastest-growing segment as utility-scale photovoltaic installations expand across diverse geographies.
The EU Green Deal and F-Gas Regulation shape material selection and environmental compliance across European supply chains. Germany's KBA and Denmark's energy authority enforce submarine cable burial depth and marine ecosystem protection standards. China's MIIT mandates GB standard certification for domestic offshore wind cable procurement. Stakeholders must monitor regulatory divergence between IEC and national standards as project pipelines internationalize.
Market Dynamics
Offshore wind farm scale inflation is compressing project timelines and forcing cable manufacturers to pre-position manufacturing capacity before seabed lease awards finalize. The North Sea corridor's auction velocity now outpaces supplier qualification cycles.
Growth Catalysts
- EU Green Deal offshore targets:Germany, Denmark, and the Netherlands have codified gigawatt-scale installation mandates that lock in submarine cable demand through 2035.
- High-voltage direct current systems:Long-distance transmission from remote offshore arrays to onshore grids is pulling investment into specialized converter station and cable technology.
- Seabed lease auction acceleration:Crown Estate rounds in UK waters and BSH permitting in German zones are compressing development cycles and front-loading procurement.
Market Restraints
- Copper and aluminum price volatility:Conductor metals constitute 35-45% of cable cost structures, exposing margins to commodity exchange swings.
- Installation vessel scarcity:Purpose-built cable lay vessels concentrate among Northern European operators, creating queue bottlenecks during weather windows.
- IEC 62288 certification timelines:Submarine cable type approval requires 18-24 months of factory and field testing, delaying revenue recognition.
Strategic Opportunities
- Floating offshore wind platforms:Dynamic cable systems for tethered turbines in deepwater zones off Scotland and Portugal represent uncontracted demand.
- Inter-array cable standardization:66 kV AC systems are converging on common specifications, enabling inventory pooling across project portfolios.
- US Inflation Reduction Act offshore provisions:Domestic content bonuses for Atlantic Coast projects are incentivizing local manufacturing investments.
Industry Challenges
- Submarine cable jointing technician shortage:Specialized splicing skills for high-voltage insulation require years of apprenticeship, constraining installation fleet expansion.
- Cross-linked polyethylene compounding capacity:Insulation material supply concentrates among petrochemical complexes in Belgium and Germany, creating single-source exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Cable Market |
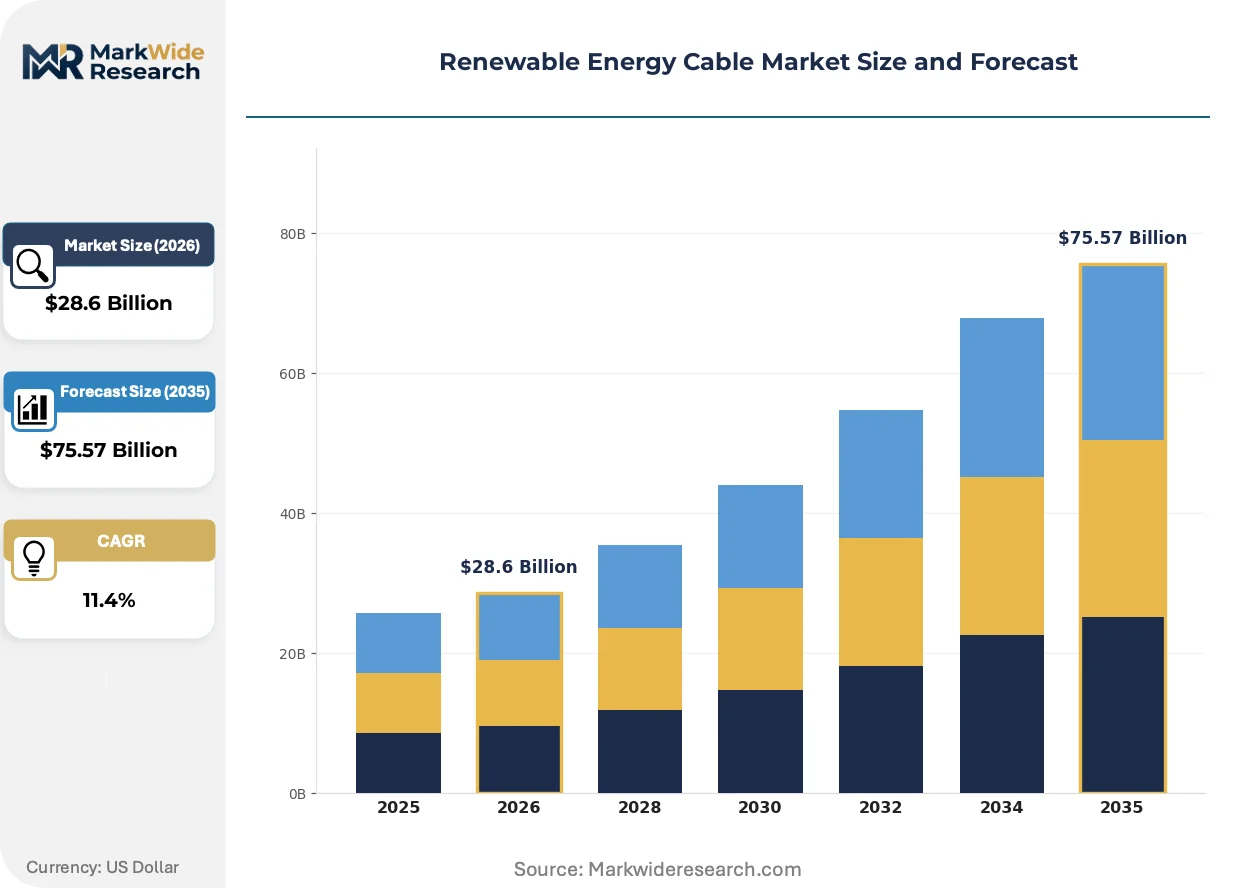
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage Cable, High Voltage Cable, Low Voltage Cable, Submarine Cable Application: Wind Power, Solar Power, Hydropower, Geothermal Energy Installation: Indoor, Outdoor, Underwater, Overhead End User: Utilities, Industrial Plants, Commercial Buildings, Residential Projects |
| Companies Covered | Prysmian Group, Nexans, NKT A/S, LS Cable & System, Furukawa Electric, Sumitomo Electric, Southwire Company, TFKABLE, HELUKABEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Cable Market Trends and Innovations
Material science advances and installation methodology refinements are compressing cable system costs while extending operational lifespans in corrosive marine environments. Three developments are restructuring competitive positioning.
Cross-linked polyethylene with triple-layer extrusion is absorbing thermal cycling stress from higher current loads in 220 kV and 525 kV systems. Offshore wind developers in the North Sea are specifying this insulation for arrays exceeding 1 GW capacity. The technology is absorbing market share from ethylene propylene rubber in high-voltage submarine applications.
REACH SVHC restrictions on lead-based stabilizers are forcing reformulation of cable sheathing compounds across European supply chains. Compounders must validate alternative heat and UV stabilizers without degrading 30-year service life guarantees. Submarine cable manufacturers serving German and Danish projects are absorbing compliance costs into long-term supply agreements.
Utility-scale solar developers are unbundling engineering-procurement-construction contracts to source cables directly from manufacturers rather than through EPC intermediaries. This disintermediation compresses margin stacking and accelerates specification alignment between array designers and insulation engineers. The pattern is most pronounced in utility-scale photovoltaic installations across Spain and Italy where project sponsors maintain in-house electrical engineering teams.
Renewable Energy Cable Market Segmentation
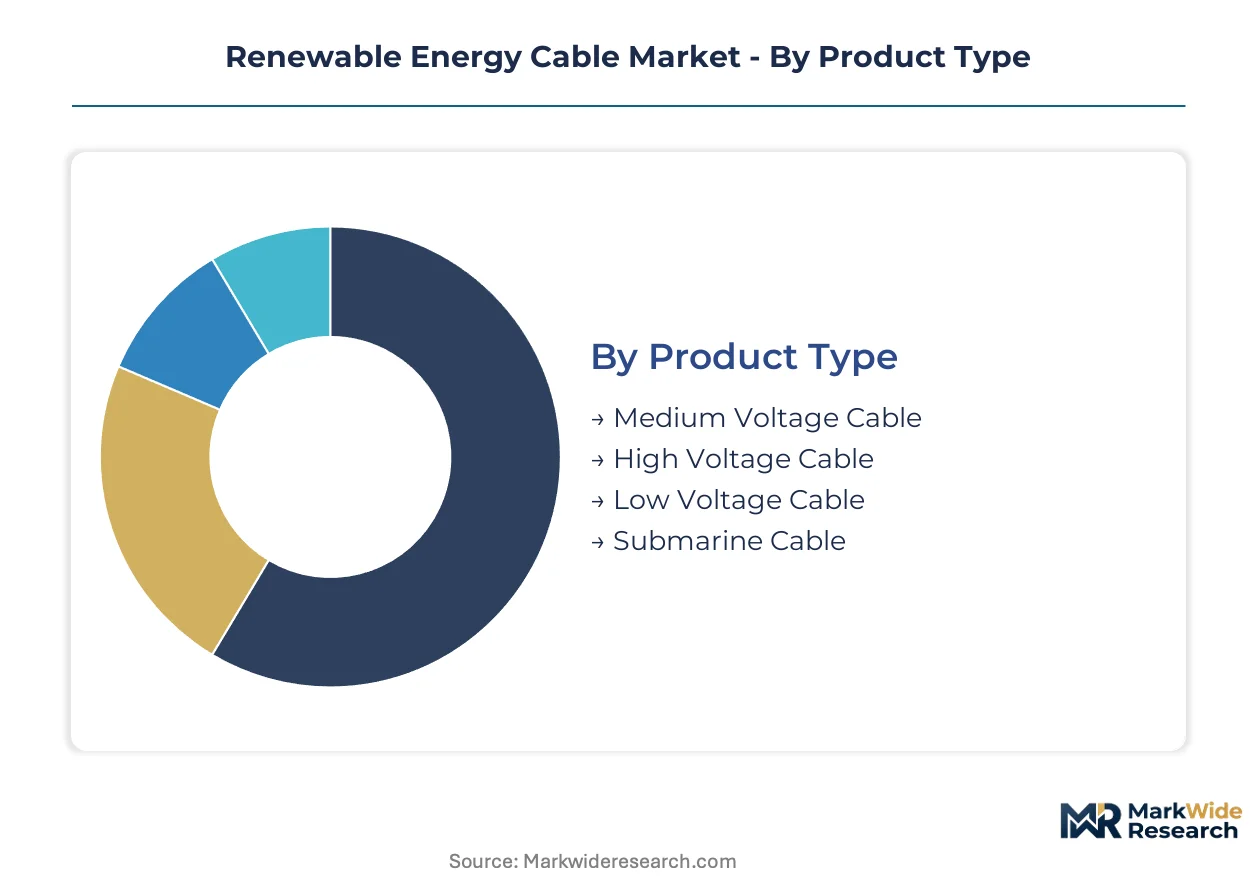
Segmentation in renewable energy cables reflects divergent technical specifications, installation environments, and procurement patterns across generation technologies. Voltage class and conductor armoring drive cost structures, while application mix shifts with policy support for offshore wind and utility-scale solar.
Product Type:
Submarine cable commands the volume-premium split, absorbing disproportionate capital allocation due to specialized manufacturing and marine installation requirements.
- Submarine Cable:Steel wire armoring and lead alloy sheathing protect polymeric insulation against hydrostatic pressure and seabed abrasion. Prysmian Group and Nexans dominate procurement for North Sea offshore wind arrays where burial depth regulations enforced by Germany's KBA and Denmark's energy authority add compliance layers. Lead times extend 24-36 months for 220 kV+ systems.
- High Voltage Cable:Cross-linked polyethylene insulation in triple-layer extrusion handles thermal cycling from 132 kV to 525 kV transmission. Demand concentrates in inter-array and export cable systems for 500 MW+ offshore wind projects in UK Crown Estate lease zones. Converter station integration requirements favor vendors with HVDC system expertise.
- Medium Voltage Cable:11-66 kV systems connect onshore wind turbines and solar inverters to substations. Standardization around 66 kV AC is enabling inventory pooling across European project portfolios.
- Low Voltage Cable:1 kV-rated conductors with PVC or XLPE insulation serve distributed solar rooftop and residential battery storage interconnection. Procurement runs through electrical wholesalers rather than direct manufacturer contracting.
Mature deployment sits with medium voltage systems in established onshore wind markets. Newer deployment is concentrated in submarine cable for deepwater floating platform projects off Scotland and Portugal.
Application:
Wind power anchors procurement volumes while solar power captures margin expansion through disintermediated direct sourcing.
- Wind Power:Offshore arrays above 1 GW capacity specify 66 kV inter-array and 220 kV export cables with 30-year service life guarantees. EU Green Deal targets in Germany, Denmark, and the Netherlands lock in submarine cable demand through project pipelines exceeding 100 GW combined capacity. Dynamic cable systems for floating platforms represent uncontracted technology evolution.
- Solar Power:Utility-scale photovoltaic developers in Spain and Italy are unbundling EPC contracts to source DC and AC cables directly from manufacturers. This procurement shift compresses margin stacking and accelerates specification alignment between array designers and insulation engineers. Tracking systems and bifacial modules are extending cable routing complexity.
- Hydropower:Underground tunnel installations in Alpine regions require lead-sheathed cables with moisture barriers. Refurbishment cycles for aging European infrastructure drive replacement demand.
- Geothermal Energy:High-temperature ethylene propylene rubber insulation withstands thermal fluids in Icelandic and Italian volcanic zone installations. Project scale remains constrained by exploration risk.
Established application dominance rests with wind power offshore corridors. Steepest expansion trajectory belongs to solar power as PPA-backed utility projects proliferate across Southern European markets.
Installation:
Underwater placement absorbs capital intensity while overhead routing retains cost advantage in terrestrial environments.
- Underwater:Submarine cable lay vessels with dynamic positioning install armored conductors in water depths exceeding 60 meters. Purpose-built fleet scarcity concentrates among Northern European operators, creating queue bottlenecks during weather windows. Jointing technician apprenticeship requirements constrain installation velocity.
- Outdoor:Direct burial and duct bank installations dominate onshore wind and solar farm construction. UV-resistant polyethylene sheathing and rodent protection add material cost premiums.
- Indoor:Switchgear and inverter station terminations require flame-retardant halogen-free compounds. Data center renewable power purchasing is emerging as a demand pocket.
- Overhead:Aerial bundled cable systems reduce tree-clearing requirements in forested European terrain. Regulatory preference for undergrounding in Germany and Denmark limits addressable market.
Conventional installation maturity centers on outdoor terrestrial deployment. Emerging installation complexity concentrates in underwater systems for floating offshore wind platforms.
End User:
Utilities dominate procurement scale while industrial plants drive technical specification evolution.
- Utilities:Transmission system operators in Germany, the Netherlands, and the UK specify submarine cables through 10-15 year framework agreements. Long-term supply contracts absorb REACH SVHC compliance costs for lead-free sheathing reformulation. Grid integration timelines for offshore wind are compressing procurement cycles.
- Industrial Plants:Corporate renewable power purchase agreements are driving direct cable procurement for on-site solar and storage. In-house electrical engineering teams in automotive and chemical sectors are bypassing traditional EPC intermediaries.
- Commercial Buildings:Rooftop solar and EV charging infrastructure specify low and medium voltage cables through electrical contractor channels. Green building certification schemes are tightening fire performance requirements.
- Residential Projects:Distributed solar and heat pump electrification drive retail cable volumes. Installer certification programs in Germany and France are fragmenting procurement authority.
Established procurement concentration sits with utilities in offshore wind transmission. Newer procurement patterns are emerging in industrial plant direct sourcing for corporate renewable targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea offshore wind zones concentrate procurement through Denmark's Esbjerg port cluster, Germany's Bremerhaven manufacturing belt, and Dutch Rotterdam cable terminals. EU Green Deal targets lock in submarine cable demand across these coastal special economic corridors.
Germany
Offshore wind arrays exceeding 1 GW capacity drive 220 kV export cable procurement from Bremerhaven manufacturing complexes. Germany's KBA enforces submarine burial depth standards and marine ecosystem protection protocols. North Sea lease zones off Lower Saxony and Schleswig-Holstein anchor converter station integration projects.
United Kingdom
Crown Estate seabed auctions compress development timelines and front-load cable procurement for Dogger Bank and Norfolk Vanguard arrays. The UK's Marine Management Organisation coordinates spatial planning with transmission system operators. Scottish floating wind projects off Aberdeen and Peterhead test dynamic cable systems in water depths exceeding 60 meters.
Denmark
Energy island projects in the Baltic and North Seas mandate submarine cable corridors connecting artificial hub platforms to multiple nations. Denmark's energy authority certifies cable burial standards and environmental impact assessments. Esbjerg port facilities host jointing technician training centers serving North Sea installation fleets.
Netherlands
Hollandse Kust offshore zones specify 66 kV inter-array systems through Rotterdam cable terminals and Eemshaven converter stations. The Dutch Enterprise Agency coordinates grid integration timelines with transmission system operators. IJmuiden manufacturing facilities specialize in lead alloy sheathing for high-voltage submarine applications.
China
Provincial offshore wind targets in Guangdong and Fujian accelerate domestic cable procurement through Yangtze River Delta manufacturing clusters. MIIT mandates GB standard certification for submarine cable procurement in state-backed projects. Shanghai and Ningbo port facilities support installation vessel mobilization for Taiwan Strait developments.
Renewable Energy Cable Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across voltage class and installation environment segments. The market exhibits tiered concentration with three to five integrated manufacturers commanding premium submarine cable procurement. Strategic archetypes span full-cycle manufacturers with conductor-to-armoring integration, installation-service bundlers with captive vessel fleets, and component specialists in insulation compounding. Capacity pre-positioning ahead of seabed lease awards and backward integration into conductor drawing represent dominant competitive moves.
Among European-integrated manufacturers, Prysmian Group, Nexans, and NKT A/S exemplify archetypes spanning manufacturing depth and installation capability. Prysmian Group occupies a position as a full-cycle producer with integrated conductor drawing through armoring operations. Nexans represents the installation-bundler archetype with project-specific engineering and deepwater deployment capabilities. NKT A/S anchors the high-voltage transmission specialist tier with converter station integration expertise for long-distance submarine systems.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT A/S |
| LS Cable & System |
| Furukawa Electric |
| Sumitomo Electric |
| Southwire Company |
| TFKABLE |
| HELUKABEL |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap cable specialists in Northern Europe anchor supply discipline through generational capital allocation, insulating pricing power against commodity swings while sovereign-backed Chinese producers undercut on volume tenders. This ownership bifurcation concentrates margin resilience among integrated manufacturers with captive conductor drawing and armoring operations.
Pricing Analysis
Cost-down pressure on 66 kV inter-array systems accelerates because utility-scale offshore wind developers in the North Sea corridor are unbundling EPC contracts for direct manufacturer procurement. Project-based long-term offtake agreements dominate, with price differentiation separating IEC 62288-certified submarine cable from medium-voltage terrestrial alternatives. Brand premium and installation service bundling command pricing power for Prysmian Group and Nexans, while price sensitivity concentrates among independent power producers in Southern European solar markets.
Supply Chain Analysis
Domestic-content mandates in the US Inflation Reduction Act and China's MIIT GB certification requirements are reshaping sourcing toward regional manufacturing clusters in Germany, China, and the United States. Raw material dependencies center on copper cathode from Chilean smelters, aluminum billet from Rusal-linked Russian sources, and cross-linked polyethylene compounding from Belgian petrochemical complexes. Single-source vulnerability in submarine cable lay vessel fleets concentrates installation queue risk among Northern European operators. Distribution runs through transmission system operator framework agreements and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
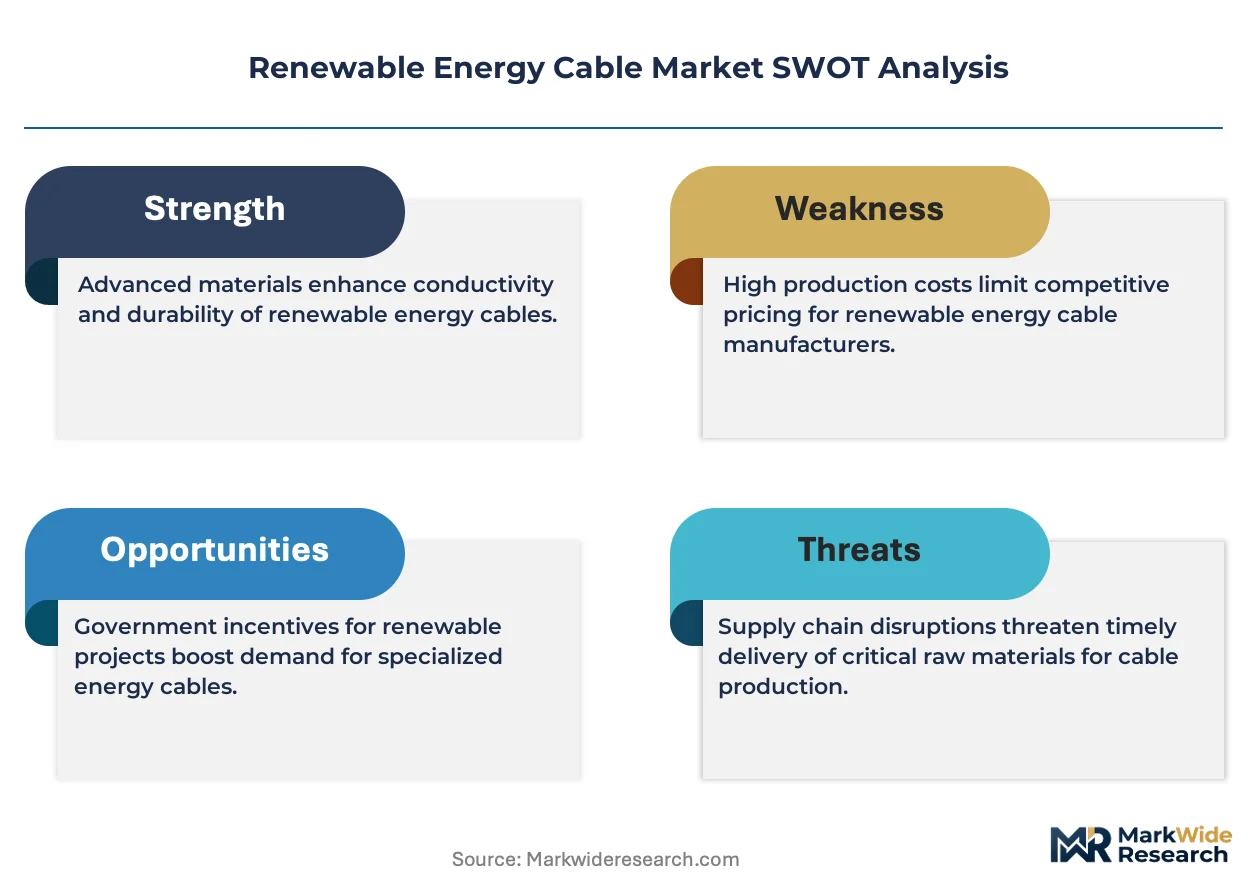
This market functions as a consolidation play where copper price volatility and IEC certification timelines force sub-scale compounders and regional distributors toward distressed exits.
For Market Incumbents: Deepen backward integration into conductor drawing and lead alloy sheathing to defend margin position against commodity exchange swings. Prysmian Group and Nexans should pre-position manufacturing capacity in Bremerhaven and Esbjerg ahead of Crown Estate lease awards, while investing in jointing technician apprenticeship programs to alleviate installation fleet constraints.
For New Entrants and Emerging Players: Capture uncontracted demand in floating offshore wind dynamic cable systems off Scotland and Portugal, where water depths exceed 60 meters and established suppliers lack proven deployment track records. Partner with installation vessel operators on project-specific engineering contracts rather than competing on manufacturing scale.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap insulation compounders with REACH SVHC-compliant lead-free sheathing formulations in Germany and Denmark. Watch seabed lease auction velocity as the inflection signal—accelerating Crown Estate and BSH permitting timelines indicate procurement cycle compression that rewards pre-qualified cable inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductor Drawing | Captive copper and aluminum supply insulates Prysmian Group and Nexans from LME price volatility. |
| Submarine Cable Lay Vessel Partnership | Installation service bundling compresses project timelines for North Sea offshore wind developers. |
| REACH SVHC-Compliant Sheathing Reformulation | Lead-free compound validation secures German KBA and Danish energy authority certification access. |
| Jointing Technician Apprenticeship Expansion | Specialized splicing skills alleviate installation fleet bottlenecks during weather windows. |
| Floating Wind Dynamic Cable R&D | Tethered turbine systems in deepwater zones off Scotland and Portugal represent uncontracted technology evolution. |
Research Methodology
Independent corroboration across primary interviews with submarine cable project developers, transmission system operator procurement officers, EPC contractor electrical engineers, and insulation compounder R&D directors underwrites the qualitative findings. Secondary validation draws from IEC standard documentation, EU Green Deal policy filings, Crown Estate seabed lease records, and FERC interconnection queue data. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling triangulate volume and value estimates.
Comparable-period anchoring to historical offshore wind installation data and submarine cable procurement cycles structures the projection horizon. Segmentation dimensions span voltage class, installation environment, application technology, and regional regulatory framework. CAGRs derive from regression analysis against offshore wind capacity buildout trajectories, converter station deployment schedules, and raw material price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to seabed lease auction delays, installation vessel availability, and copper price volatility. Assumptions reflect documented project pipelines, certification timelines, and supply chain capacity constraints. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar District Heating Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
Wind Turbine Inspection Services Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar Showers Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Solar Thermal Water Heater Market