
 3D Medical Imaging Devices Market | 2026-2036
3D Medical Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
3D Medical Imaging Devices Market Analytics
The capital-intensity divergence between installed-base incumbents and software-native entrants is rotating competitive dynamics toward hybrid hardware-software ecosystems. Siemens Healthineers leverages its detector manufacturing scale to control component costs across CT and PET modalities. GE Healthcare anchors its position through backward integration into helium-free MRI magnet technology, reducing supply chain exposure.
3D medical imaging devices generate volumetric anatomical reconstructions from multi-planar data acquisition, with spatial resolution thresholds typically below one millimeter for diagnostic-grade CT systems. These systems enable pre-surgical planning, treatment monitoring, and minimally invasive intervention guidance across clinical settings. CT scanners occupy the largest installed base among product type categories, while 3D ultrasound technology captures expanding share in point-of-care cardiology applications. Magnetic resonance imaging commands premium pricing in neurology and orthopedic segments where soft-tissue contrast specificity determines clinical utility.
FDA premarket notification requirements under 21 CFR Part 892 govern device safety and efficacy claims for US market entry, while EU MDR and CE marking frameworks impose post-market surveillance obligations across European member states. Japan's PMDA operates accelerated review pathways for software-as-a-medical-device integrations with existing imaging platforms. Stakeholders must monitor evolving reimbursement codes for AI-augmented reads and synthetic image generation as health technology assessment bodies recalibrate value frameworks.
Market Dynamics
AI-enabled reconstruction algorithms are compressing scan times and radiation doses, forcing hardware manufacturers to integrate software stacks or cede margin to pure-play analytics vendors.
Growth Catalysts
- US FDA 510(k) Pathway Acceleration:Streamlined clearance for AI-augmented 3D reconstruction software reduces time-to-market from 18 months to under 6 months for qualified submissions.
- Helium Supply Constraints:Magnet technology shifts toward conduction-cooled superconducting coils eliminate dependency on cryogen logistics chains concentrated in Qatar and Algeria.
- Cardiology Point-of-Care Expansion:Portable 3D ultrasound systems penetrate emergency departments and ambulatory surgical centers previously served only by cart-based CT.
Market Restraints
- Detector Material Concentration:Ceramic scintillator substrates for CT photodiodes rely on rare-earth processing facilities clustered in China's Jiangxi province.
- EU MDR Recertification Burden:Legacy imaging systems face 18-24 month compliance timelines and notified body capacity bottlenecks for CE mark renewal.
- Interventional Radiologist Training Gaps:Fellowship programs produce fewer than 400 US-trained specialists annually against replacement demand for retiring cohorts.
Strategic Opportunities
- India PLI Scheme for Medical Electronics:Manufacturing incentives cover 5% of incremental sales value for domestic CT and MRI component production.
- Synthetic Image Generation:FDA-cleared algorithms reconstruct diagnostic-quality CT from sparse-view acquisitions, enabling dose reduction without hardware replacement.
- Subscription-Based Software Licensing:Per-scan pricing models penetrate price-sensitive outpatient imaging chains in Brazil and Mexico.
Industry Challenges
- PACS Integration Complexity:Hospital IT departments face 6-9 month deployment cycles for 3D visualization tools into legacy DICOM archives.
- CE Mark Notified Body Queues:EU MDR technical documentation reviews for Class IIb imaging devices currently exceed 14 months at leading certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Medical Imaging Devices Market |
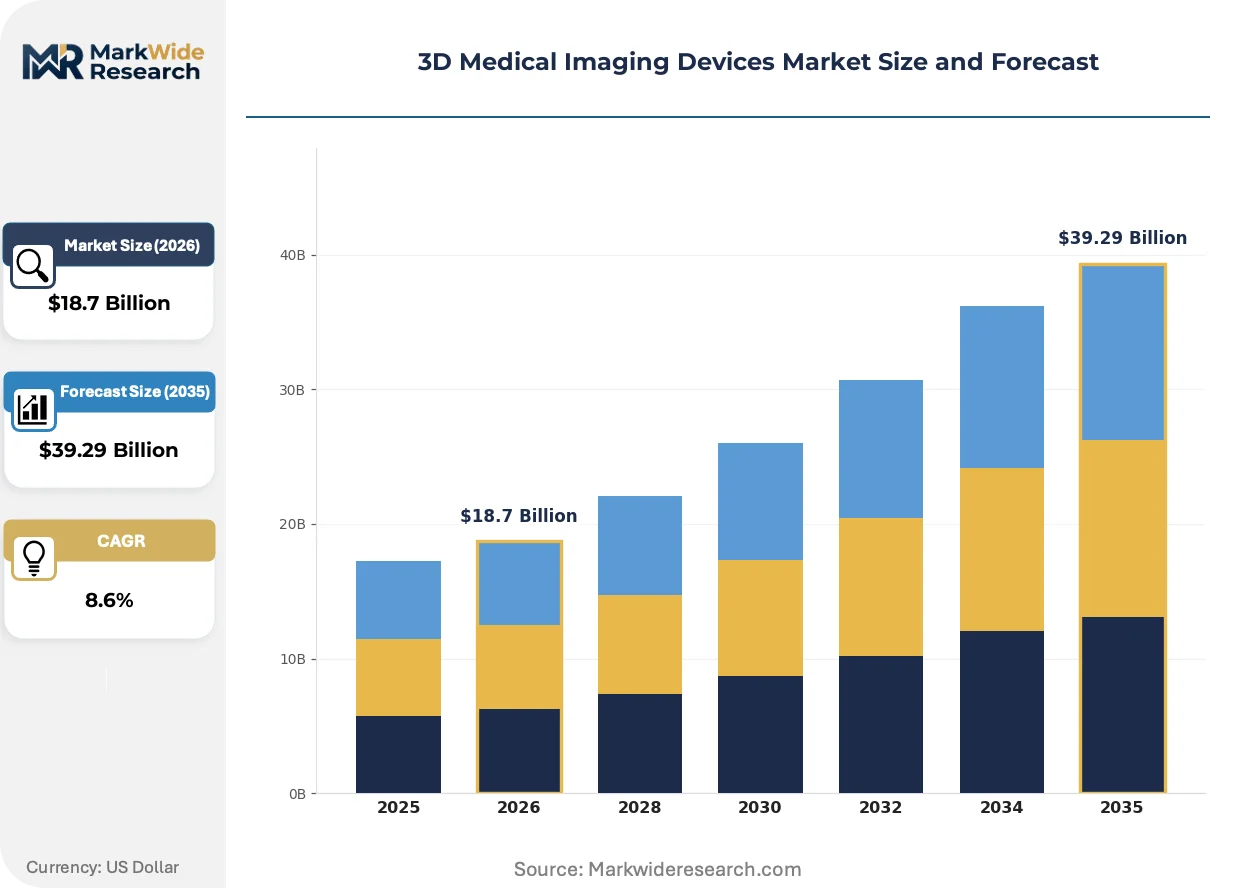
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Machines, Ultrasound Systems, PET Scanners End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Clinics Technology: Optical Coherence Tomography, Computed Tomography, Magnetic Resonance Imaging, 3D Ultrasound Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon Medical Systems, Hitachi High-Tech, Esaote, Shimadzu, Medtronic, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Medical Imaging Devices Market Evolving Landscape
Photon-counting detector technology is resetting performance baselines across CT modalities while regulatory frameworks adapt to software-as-a-medical-device business models.
Photon-counting CT is fragmenting the installed base economics of energy-integrating detectors. Academic medical centers in Germany and the United States are prioritizing dual-source configurations for cardiac and pediatric applications. The technology is fragmenting procurement criteria toward spectral resolution metrics rather than slice count alone.
EU MDR post-market surveillance requirements are extending liability to software updates and AI algorithm versions. Manufacturers must maintain clinical evidence portfolios across device lifecycles exceeding 10 years. Radiology departments in France and Italy are delaying procurement decisions until supplier MDR compliance documentation matures.
Hospital procurement committees are unbundling service contracts from equipment financing, compressing vendor margin capture from 25-year total-cost-of-ownership models to 5-year hardware leases with separate software subscriptions. This pattern is most visible in United States health systems consolidating purchasing through regional group purchasing organizations.
3D Medical Imaging Devices Market Segmentation
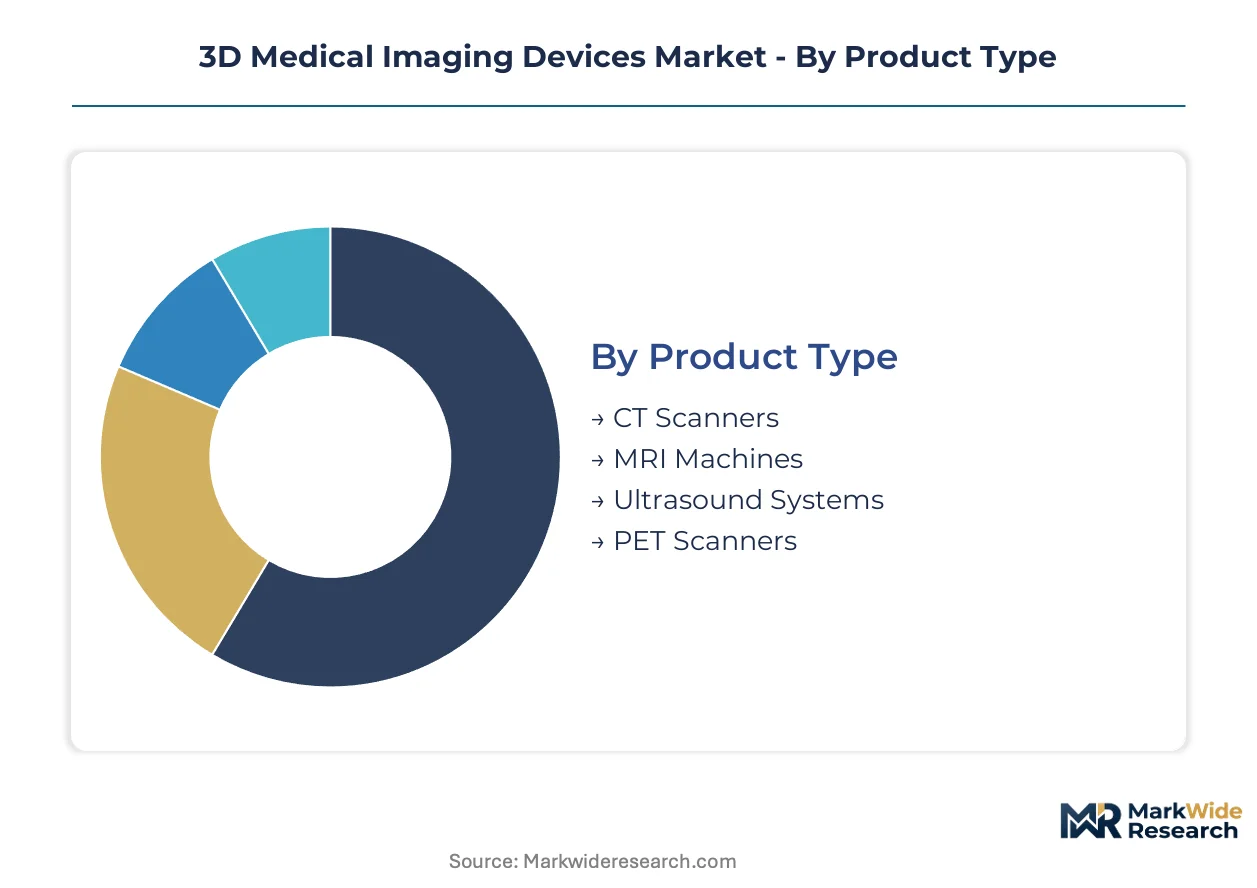
Segmentation in 3D medical imaging devices reveals divergent procurement patterns across hardware platforms and clinical settings. Equipment replacement cycles, reimbursement codes, and site-of-care migration create distinct demand profiles that reshape vendor go-to-market strategies.
Product Type:
Domestic manufacturing concentration varies sharply across modalities, with CT and MRI systems drawing heavily on regional supply chains while portable ultrasound platforms enable broader geographic distribution.
- CT Scanners:Energy-integrating and photon-counting detector architectures generate sub-millimeter spatial resolution from multi-slice helical acquisition protocols. Demand concentrates in United States academic medical centers and German university hospitals replacing decade-old installed bases; helium-free magnet alternatives and AI reconstruction software drive procurement criteria beyond raw slice count.
- MRI Machines:Superconducting and conduction-cooled magnet systems produce high-contrast soft-tissue differentiation through radiofrequency coil arrays and gradient field manipulation. Japanese and United States neurology departments prioritize 3T and 7T field strengths for functional brain mapping; supply chain exposure to cryogen logistics accelerates adoption of closed-loop cooling architectures.
- Ultrasound Systems:Piezoelectric transducer arrays with beamforming electronics enable real-time volumetric cardiac and abdominal imaging at point-of-care settings. Brazil and Mexico outpatient chains favor cart-based and handheld configurations for price-sensitive deployment.
- PET Scanners:Scintillation crystal arrays coupled to photomultiplier tubes detect positron-emitting radiotracer distribution for metabolic and oncologic assessment. Cyclotron proximity requirements limit site penetration to major metropolitan clusters with radiopharmaceutical infrastructure.
CT Scanners holds the largest share; momentum sits with Ultrasound Systems.
End User:
Procurement authority and capital allocation cycles diverge across facility types, with consolidated health systems leveraging volume leverage against independent imaging centers optimizing throughput per square meter.
- Hospitals:Integrated inpatient-outpatient campuses with 24/7 emergency coverage and surgical suites require redundant imaging capacity across CT, MRI, and interventional fluoroscopy. United States health systems consolidate purchasing through regional group purchasing organizations, unbundling service contracts from equipment financing.
- Diagnostic Imaging Centers:Freestanding facilities optimize scan throughput and payer mix to maximize revenue per modality hour. Indian and Brazilian chains adopt subscription-based software licensing to reduce upfront capital outlay.
- Research Institutions:Academic medical centers and national laboratories prioritize spectral resolution, field strength, and protocol flexibility over reimbursement optimization. Germany and United States NIH-funded sites drive early adoption of photon-counting CT and 7T MRI.
- Outpatient Clinics:Ambulatory settings with limited footprint deploy portable ultrasound and low-dose CT for same-day diagnosis and triage. Cardiology-focused clinics in Japan and United States penetrate emergency department adjacent spaces.
Hospitals dominates installed value; Diagnostic Imaging Centers are climbing the fastest.
Technology:
Regulatory clearance pathways and software-hardware integration requirements fragment competitive positioning between device-native manufacturers and algorithm-focused entrants.
- Computed Tomography:X-ray tube and rotating gantry systems reconstruct tomographic slices from attenuation data, with photon-counting detectors resetting performance baselines for spectral imaging. FDA 510(k) pathway acceleration compresses time-to-market for AI-augmented reconstruction algorithms.
- Magnetic Resonance Imaging:Superconducting coils and gradient systems encode spatial information through nuclear magnetic resonance signal detection. EU MDR recertification burdens and notified body capacity constraints delay CE mark renewal for legacy system manufacturers.
- 3D Ultrasound:Electronic beam steering and matrix array transducers generate real-time volumetric data without ionizing radiation exposure. Point-of-care cardiology applications in United States emergency departments drive fastest volume expansion.
- Optical Coherence Tomography:Near-infrared interferometry achieves micrometer-scale resolution for retinal and intravascular imaging. Ophthalmology suites in Japan and Germany represent concentrated demand for spectral-domain and swept-source configurations.
Computed Tomography commands premium pricing; 3D Ultrasound shows steepest expansion trajectory.
Application:
Clinical utility and reimbursement density vary across specialties, with oncology and cardiology presenting contrasting volume-margin profiles that reshape vendor targeting priorities.
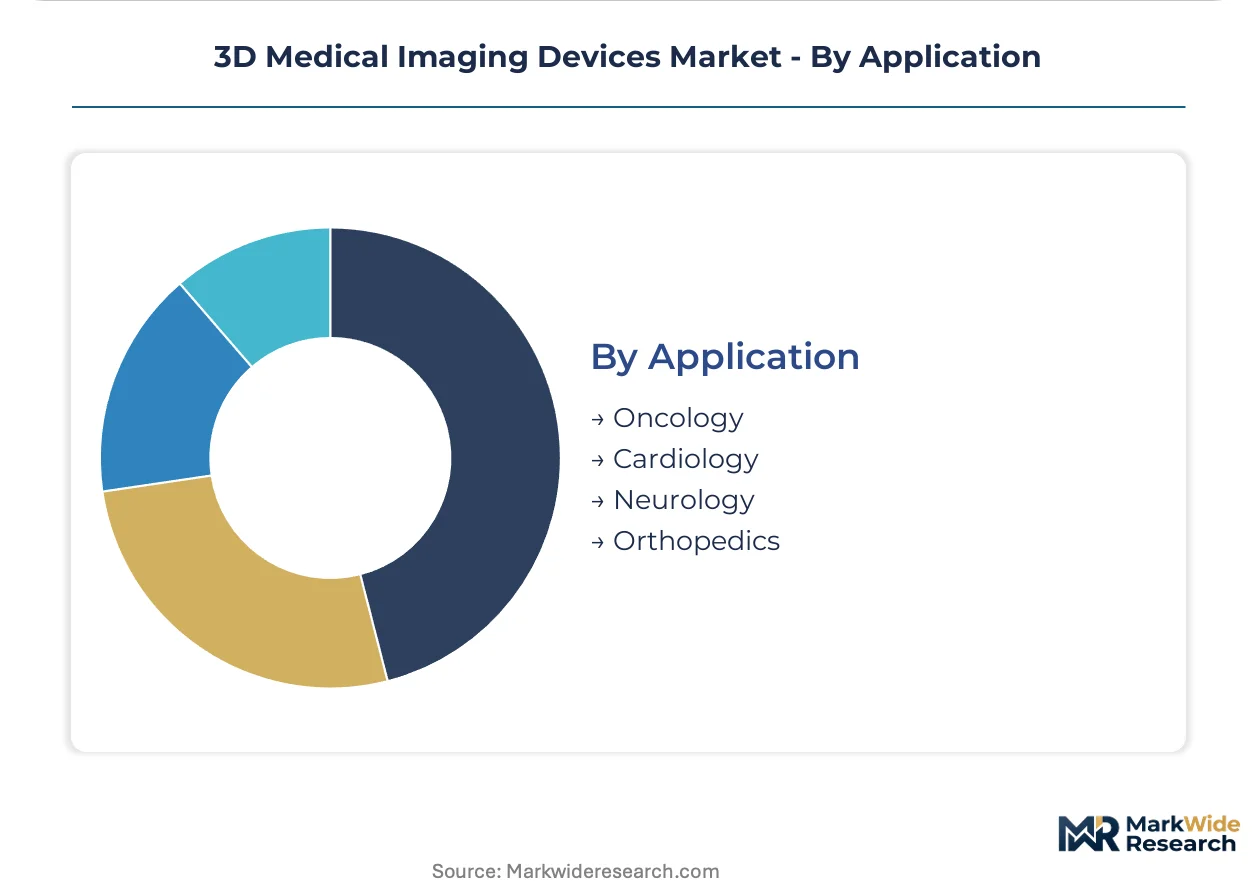
- Oncology:Staging, treatment planning, and response assessment protocols demand multi-modal imaging fusion across CT, PET, and MRI platforms. United States comprehensive cancer centers and French hospital networks prioritize quantitative imaging biomarkers for immunotherapy monitoring.
- Cardiology:Coronary CT angiography, cardiac MRI, and 3D echocardiography enable non-invasive functional assessment and structural intervention planning. German and Japanese catheterization laboratories integrate intraprocedural imaging for transcatheter valve replacement guidance.
- Neurology:Diffusion tensor imaging, functional MRI, and perfusion CT support stroke triage, epilepsy surgical planning, and neurodegenerative disease monitoring. High-field MRI installations concentrate in United States and Japanese academic referral centers.
- Orthopedics:Weight-bearing CT, metal-artifact reduction MRI, and 3D pre-surgical templating guide joint replacement and sports medicine procedures. Ambulatory surgery centers in United States and Germany favor compact-bore systems for office-based integration.
Oncology holds the largest share; Cardiology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where reimbursement density supports premium hardware procurement, while cost-sensitive markets in Brazil and India compress vendor margins through aggressive tendering and localized manufacturing mandates.
United States
Academic medical centers in Boston and Houston drive replacement demand for decade-old CT and MRI installed bases. FDA 510(k) pathway acceleration for AI-augmented reconstruction software compresses regulatory timelines below six months. The Cleveland Clinic and Mayo Clinic anchor early adoption of photon-counting detector technology for cardiac applications.
Germany
University hospitals in Munich and Heidelberg prioritize spectral resolution metrics over slice count in CT procurement decisions. EU MDR recertification burdens and notified body capacity constraints delay CE mark renewal for legacy system manufacturers. The Baden-Württemberg medical technology cluster concentrates detector manufacturing and precision engineering capabilities.
Japan
Neurology departments at University of Tokyo Hospital and Osaka University Hospital anchor demand for 7T MRI field strengths in functional brain mapping. PMDA operates accelerated review pathways for software-as-a-medical-device integrations with existing imaging platforms. The Nagoya medical device corridor concentrates superconducting magnet and gradient coil production.
India
Domestic imaging chains in Mumbai and Delhi adopt subscription-based software licensing to reduce upfront capital outlay for CT and MRI procurement. PLI scheme incentives cover 5% of incremental sales value for domestic CT and MRI component production. The Bangalore medical electronics cluster attracts contract manufacturing for portable ultrasound platforms.
Brazil
Outpatient imaging chains in São Paulo and Rio de Janeiro favor cart-based and handheld ultrasound configurations for price-sensitive deployment. ANVISA regulatory pathways for imported imaging equipment impose documentation requirements that favor established vendor relationships. The Campinas medical device hub supports regional distribution and service infrastructure for Latin American markets.
3D Medical Imaging Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated hardware-software ecosystems commanding premium positioning while component specialists capture margin in detector and magnet subsystems. The vendor base stratifies across three tiers: full-platform multinationals with captive manufacturing, regional assemblers leveraging licensed technology, and pure-play software entrants exploiting FDA pathway acceleration. Dominant competitive moves include backward integration into helium-free magnet technology and strategic partnerships for AI reconstruction algorithm licensing.
Within the full-platform tier, Siemens Healthineers and GE Healthcare exemplify integrated hardware-software positioning, while Koninklijke Philips occupies a position emphasizing diagnostic informatics and workflow integration. These three anchors represent divergent strategic bets on detector manufacturing scale, magnet technology verticality, and software-native reconstruction capabilities respectively.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon Medical Systems |
| Hitachi High-Tech |
| Esaote |
| Shimadzu |
| Medtronic |
| Hologic |
| Others |
Value Network & Pricing Analysis
Gantry manufacturing scale at Siemens Healthineers and GE Healthcare creates cost advantages that compress price floors for mid-tier CT systems while elevating premium thresholds for photon-counting configurations. Detector fabrication concentration in Germany and Japan locks in component pricing power that propagates through finished system quotes across North American and Asian hospital procurement cycles.
Pricing Analysis
The customization-premium spread separates configured-to-order photon-counting CT systems from standard energy-integrating platforms by margins reflecting spectral resolution certification tiers. Pricing stratifies across premium, standard, and economy tiers based on field strength gradients in MRI and AI reconstruction software bundling. Cost compression in the standard tier intensifies because Chinese component assemblers penetrate Latin American markets with licensed detector technology. Outpatient imaging chains in Brazil and Mexico exhibit highest price sensitivity; academic medical centers in the United States and Germany demonstrate lowest sensitivity due to NIH and DFG funding insulation.
Supply Chain Analysis
Strategic stockpiling of helium-3 and ceramic scintillator substrates dominates inventory strategy as Qatar and Algeria supply chain vulnerabilities force manufacturers toward six-month safety buffers. Superconducting wire drawing concentrates in Japan, Germany, and the United States; rare-earth processing for CT photodiodes rests on Jiangxi province facilities. Single-source vulnerability in cryogen logistics threatens MRI production schedules. Distribution runs through regional service hubs co-located with university hospital clusters to minimize gantry installation downtime.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector commercialization and FDA 510(k) pathway acceleration for AI reconstruction software constitute dual inflection points compressing incumbent hardware replacement cycles while opening software-native entry vectors.
For Market Incumbents: Secure captive supply of conduction-cooled superconducting coils through backward integration into magnet manufacturing, eliminating helium dependency exposure. Defend installed base service contracts against pure-play analytics vendors by embedding AI reconstruction algorithms as standard features rather than premium add-ons. Channel control through regional GPO consolidation in United States health systems represents the priority defensive lever. For New Entrants and Emerging Players: PACS integration latency in legacy hospital IT environments creates service-layer gaps where six-to-nine-month deployment cycles frustrate clinical workflow demands. Penetrate price-sensitive diagnostic imaging centers in India and Brazil through subscription-based per-scan licensing models that eliminate upfront capital barriers. Cardiology point-of-care ultrasound applications in United States emergency departments offer the most penetrable segment given incumbent cart-based system inertia. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-as-a-medical-device platforms with FDA-cleared algorithms over capital-intensive hardware manufacturing scale. Long-term viability across the projection horizon hinges on regulatory pathway acceleration and reimbursement code expansion for AI-augmented reads. Acquisition target archetype: photon-counting detector technology specialists with academic medical center validation. The signal to watch is CE mark notified body queue clearance rates for Class IIb imaging devices.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses regulatory timelines below six months for AI reconstruction algorithms. |
| Helium-Free Magnet Technology Development | Eliminates supply chain exposure to Qatar and Algeria cryogen logistics. |
| Hospital System Partnership Expansion | Locks in 5-year hardware leases with separate software subscription revenue. |
| Software Companion Development | Enables synthetic CT generation from sparse-view acquisitions without hardware replacement. |
| Reimbursement Strategy Alignment | Secures CMS and private payer codes for AI-augmented diagnostic reads. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across product type, end user, technology, and application dimensions.
Sensitivity analysis around detector material cost volatility and helium supply disruption scenarios frames the analytical approach across the projection horizon. Segmentation dimensions modeled include modality platform, site-of-care migration pattern, field strength tier, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and software penetration curve fitting. Industry-specific forecast inputs incorporate PMDA accelerated review pathway utilization rates and EU MDR notified body capacity constraints.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Specific risk factors include tariff exposure on Chinese rare-earth processing, CE mark recertification delays, and interventional radiologist training pipeline shortfalls. Revision becomes warranted when photon-counting detector yield rates cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hair Removal Devices Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Intrathecal Pumps Market
Medical Devices
Neuromodulation Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Medical Polyimide Tubing Market