
 Europe Novel Drug Delivery System (NDDS) Market | 2026-2036
Europe Novel Drug Delivery System (NDDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Novel Drug Delivery System (NDDS) Market Foresight
Hospital procurement groups is unwinding traditional purchasing patterns as pharma companies and contract manufacturing organizations gain direct influence over device selection. Gerresheimer AG leverages its glass and polymer primary packaging expertise to anchor supply relationships across European biologics pipelines. Novo Nordisk competes through vertically integrated control of prefilled pen and autoinjector platforms for diabetes and obesity therapies. Sanofi differentiates via lipid nanoparticle delivery capabilities that sustain its mRNA and oncology portfolios.
A novel drug delivery system encompasses engineered platforms that transport pharmaceutical active ingredients to targeted physiological sites through controlled release, enhanced bioavailability, or tissue-specific localization, utilizing formulations such as polymeric matrices with defined molecular weight cutoffs or liposomal bilayers with specified phase transition temperatures to achieve therapeutic thresholds while minimizing systemic exposure. Injectable systems occupy the largest revenue pool across European NDDS demand, driven by biologics proliferation and self-administration trends, while nanoparticle platforms represent the fastest-expanding technology segment as oncology applications concentrate investment. Oral drug delivery retains mature scale for small-molecule portfolios, though transdermal patches capture growing share in pain management where patient compliance requirements tighten.
EMA's centralized marketing authorization procedures and the EU Medical Device Regulation reshape clinical evidence requirements and post-market surveillance obligations for combination products, while REACH and the F-Gas Regulation constrain solvent selections and propellant formulations in inhalation device manufacturing. The European Pharmacopoeia standards and notified body conformity assessments determine market access speed for novel platform submissions. Stakeholders must monitor regulatory science pilot programs on nanomedicine characterization and adapt quality management systems ahead of anticipated guidances on real-world performance data for drug-device combinations.
Market Dynamics
Injectable biologics pipelines are concentrating manufacturing investment around Frankfurt and Munich clusters, while EMA's evolving ATMP guidelines force sponsors to rebuild quality management systems for combination products.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements for drug-device combinations are accelerating notified body specialization, creating competitive moats for early-compliant manufacturers.
- Self-administration preference:Diabetes and obesity therapy segments are pulling prefilled pen platforms into home-care settings, displacing hospital-centric infusion models.
- Lipid nanoparticle maturation:Oncology applications are driving platform standardization for mRNA payloads, with specified phase transition temperatures now codified in European Pharmacopoeia monographs.
Market Restraints
- Perfluorocarbon propellant constraints:The F-Gas Regulation is restricting inhalation device formulations, forcing reformulation cycles that extend development timelines by 18-24 months.
- Notified body capacity bottleneck:Only 12 designated entities currently handle MDR conformity assessments for high-risk combination products, creating queue delays for novel platform submissions.
- Glass primary packaging concentration:Borosilicate tubing supply concentrates among three European suppliers, exposing biologics pipelines to input volatility.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Underdeveloped CMO infrastructure in Central European markets offers first-mover positioning for injectable assembly capacity serving Western European sponsors.
- Real-world performance data mandates:Anticipated EMA guidance on post-market surveillance for drug-device combinations will reward sponsors with integrated digital health capture systems.
- Transdermal patch convergence:Microneedle arrays combined with connected compliance monitoring are opening pain management segments previously resistant to topical delivery.
Industry Challenges
- Characterization scientist scarcity:Nanomedicine physicochemical analysis requires hybrid skill sets spanning colloid chemistry and regulatory documentation that European universities currently underproduce.
- Legacy quality system retrofitting:Pharmaceutical sponsors with entrenched small-molecule GMP infrastructure face capital-intensive cleanroom reconfiguration for aseptic biologics filling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Novel Drug Delivery System (NDDS) Market |
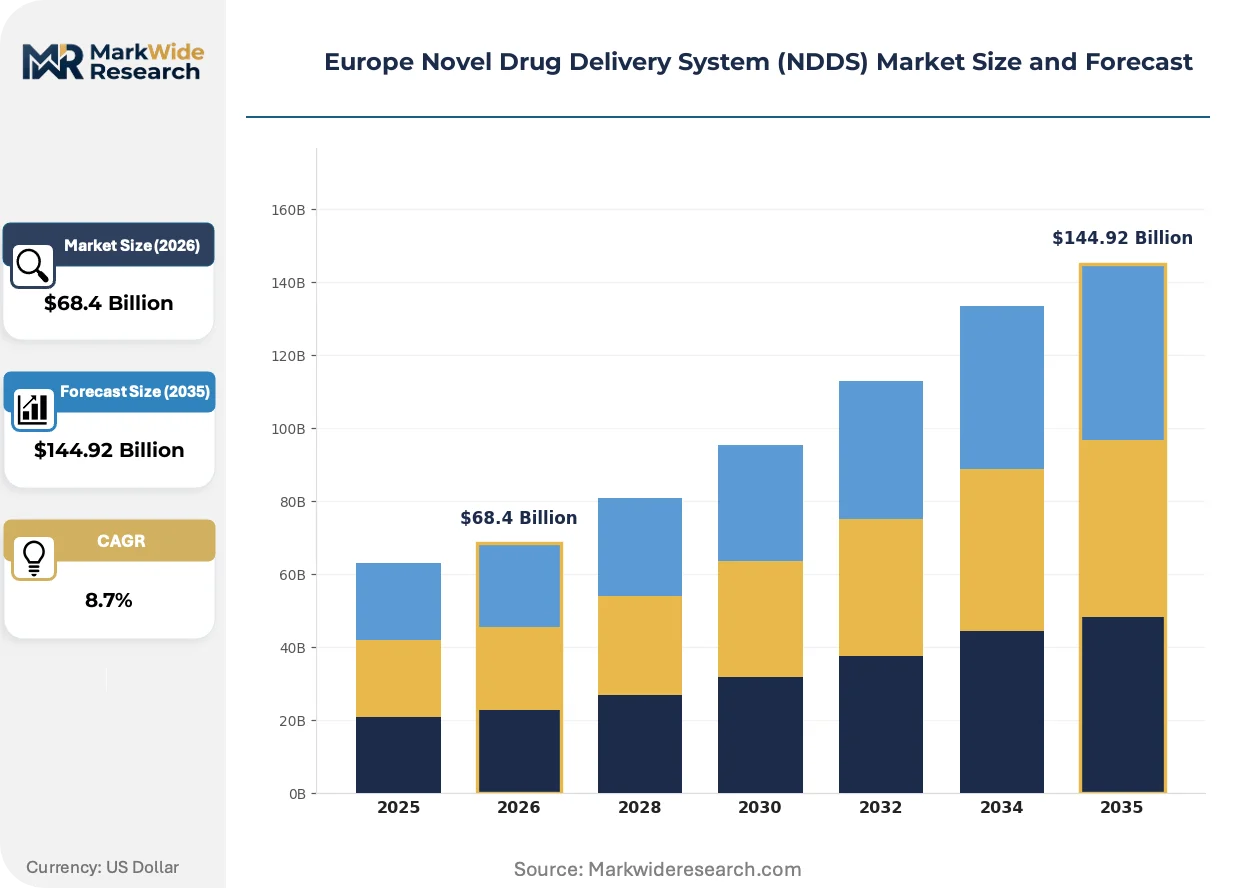
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Systems, Transdermal Patches, Inhalation Devices, Oral Drug Delivery Technology: Nanoparticles, Liposomes, Microemulsions, Polymeric Systems End User: Hospitals, Research Laboratories, Pharma Companies, Contract Manufacturing Organizations Application: Oncology, Pain Management, Cardiovascular Diseases, Neurological Disorders |
| Companies Covered | Gerresheimer AG, Novo Nordisk, Fresenius Kabi, Sanofi, Novartis, Nemera, SHL Medical, AstraZeneca, B. Braun, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Novel Drug Delivery System (NDDS) Market Shifts & Advancements
Platform engineering is compressing development cycles while regulatory science pilots on nanomedicine characterization are rewriting submission standards. Three developments are actively restructuring competitive positioning.
Microneedle patch technology is miniaturizing transdermal delivery into arrays of 25-2000 micrometer projections that breach the stratum corneum without reaching dermal nociceptors. Pain management and vaccine sponsors in Germany and the Netherlands are piloting self-administration models that bypass cold-chain requirements. The structural consequence is miniaturizing distribution infrastructure, enabling pharmacy-direct dispensing that disintermediates hospital outpatient departments.
REACH chemical safety registrations are constraining solvent selections in polymeric nanoparticle synthesis, with ECHA's 2024 updates adding 12 substances of very high concern to the authorization list. Manufacturers are responding by shifting to supercritical CO2 precipitation methods that eliminate organic phase requirements. Oncology-focused CDMOs in Belgium and Switzerland are most affected, with reformulation timelines compressing competitive windows for generic biologics entrants.
Hospital procurement consortia are fragmenting into therapeutic-area specific buying groups that bypass traditional group purchasing organizations. Biologics sponsors now negotiate directly with formulary committees at academic medical centers in Paris, Berlin, and Milan. This disintermediation is most visible in diabetes and obesity therapy categories, where Novo Nordisk and Eli Lilly maintain dedicated key account teams that influence device selection criteria ahead of tender specifications.
Europe Novel Drug Delivery System (NDDS) Market Segmentation
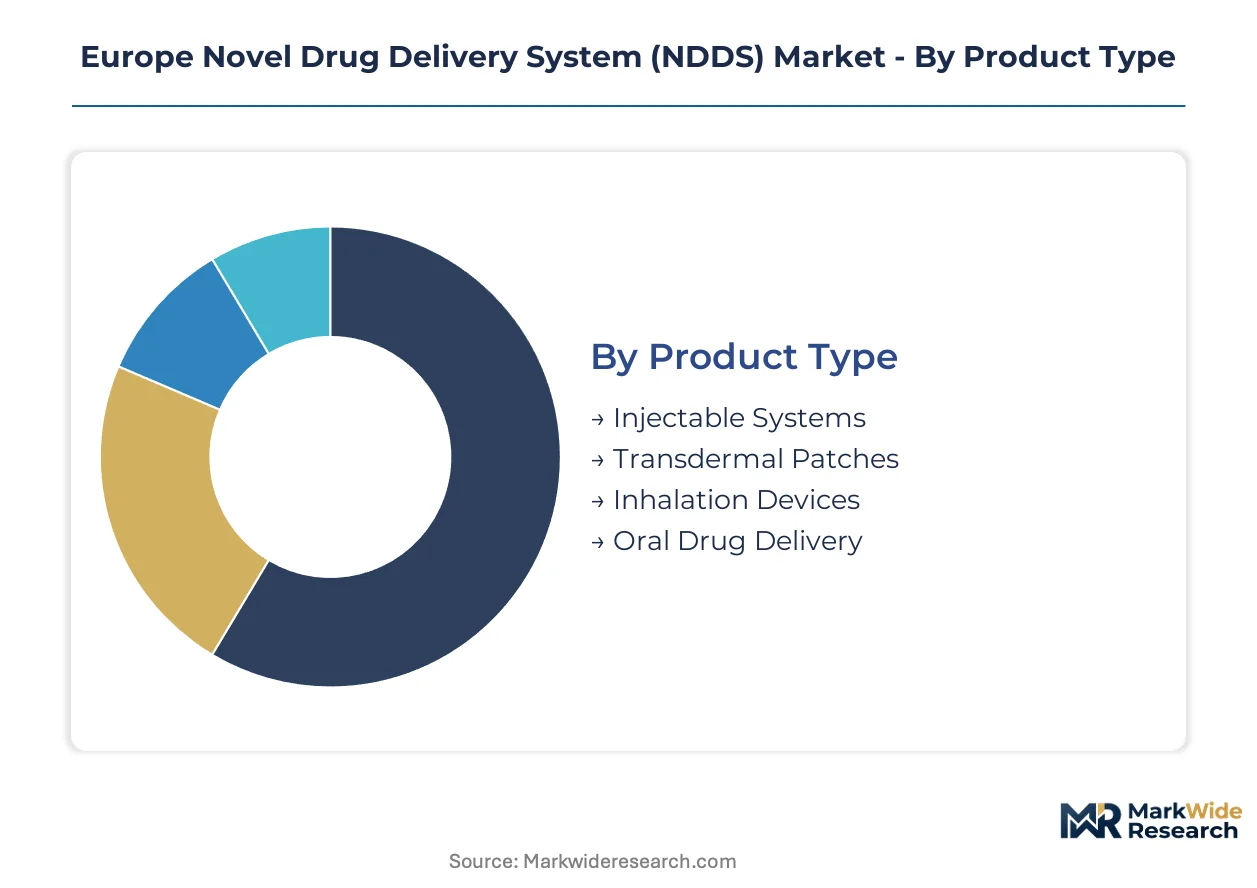
Product differentiation in European NDDS markets hinges on regulatory classification boundaries between drug, device, and combination products. Each segment carries distinct EMA submission pathways and notified body engagement requirements that reshape commercial timelines.
Product Type:
EMA's MDR implementation distinguishes drug-device combinations from standalone pharmaceuticals, creating divergent evidence standards across platform categories.
- Injectable Systems:Prefilled syringes, autoinjectors, and pen platforms incorporate primary containment with needle safety mechanisms. Germany's diabetes and obesity therapy pipelines in Frankfurt and Munich clusters drive volume concentration, though glass tubing supply constraints among three European vendors create input vulnerability.
- Transdermal Patches:Reservoir and matrix designs with rate-controlling membranes deliver sustained plasma levels. Microneedle arrays in the Netherlands and Germany are breaching pain management segments previously resistant to topical routes, bypassing cold-chain infrastructure requirements.
- Inhalation Devices:Pressurized metered-dose and dry powder platforms face F-Gas Regulation constraints on perfluorocarbon propellants.
- Oral Drug Delivery:Modified-release matrices and enteric coatings retain mature scale for small-molecule portfolios across European formulators.
Injectable Systems handles the majority of throughput; Transdermal Patches is the fastest mover on share.
Technology:
Platform selection determines manufacturing complexity and analytical characterization burden, with nanoscale systems demanding hybrid skill sets that European universities underproduce.
- Nanoparticles:Polymeric or lipid-based carriers below 1000 nanometers achieve enhanced permeability and retention in tumor tissue. REACH chemical safety registrations are constraining solvent selections, with Belgian and Swiss oncology CDMOs shifting to supercritical CO2 precipitation methods.
- Liposomes:Phospholipid bilayer vesicles with aqueous cores encapsulate hydrophilic and hydrophobic payloads simultaneously. Specified phase transition temperatures now appear in European Pharmacopoeia monographs, standardizing quality benchmarks for mRNA and oncology applications.
- Microemulsions:Thermodynamically stable oil-water dispersions enhance bioavailability of poorly soluble actives.
- Polymeric Systems:Biodegradable matrices with defined molecular weight cutoffs control release kinetics through erosion or diffusion mechanisms.
Nanoparticles commands the steepest expansion trajectory; Liposomes carries the heaviest regulatory documentation load.
End User:
Procurement authority is fragmenting from centralized hospital consortia toward therapeutic-area specific buying groups with direct sponsor engagement.
- Hospitals:Academic medical centers in Paris, Berlin, and Milan maintain formulary committees that negotiate device selection criteria ahead of tender specifications. Traditional group purchasing organization dominance is unwinding as biologics sponsors deploy dedicated key account teams.
- Pharma Companies:Vertically integrated sponsors control prefilled pen and autoinjector platform specifications for diabetes and obesity portfolios. Internal device engineering capabilities determine speed-to-market for combination product submissions.
- Contract Manufacturing Organizations:Injectable assembly capacity in Central Europe remains underdeveloped, offering first-mover positioning for Poland and Czech Republic infrastructure.
- Research Laboratories:Characterization scientist scarcity for nanomedicine physicochemical analysis constrains early-stage platform development.
Pharma Companies directs the largest procurement volume; Contract Manufacturing Organizations is climbing the fastest on outsourcing momentum.
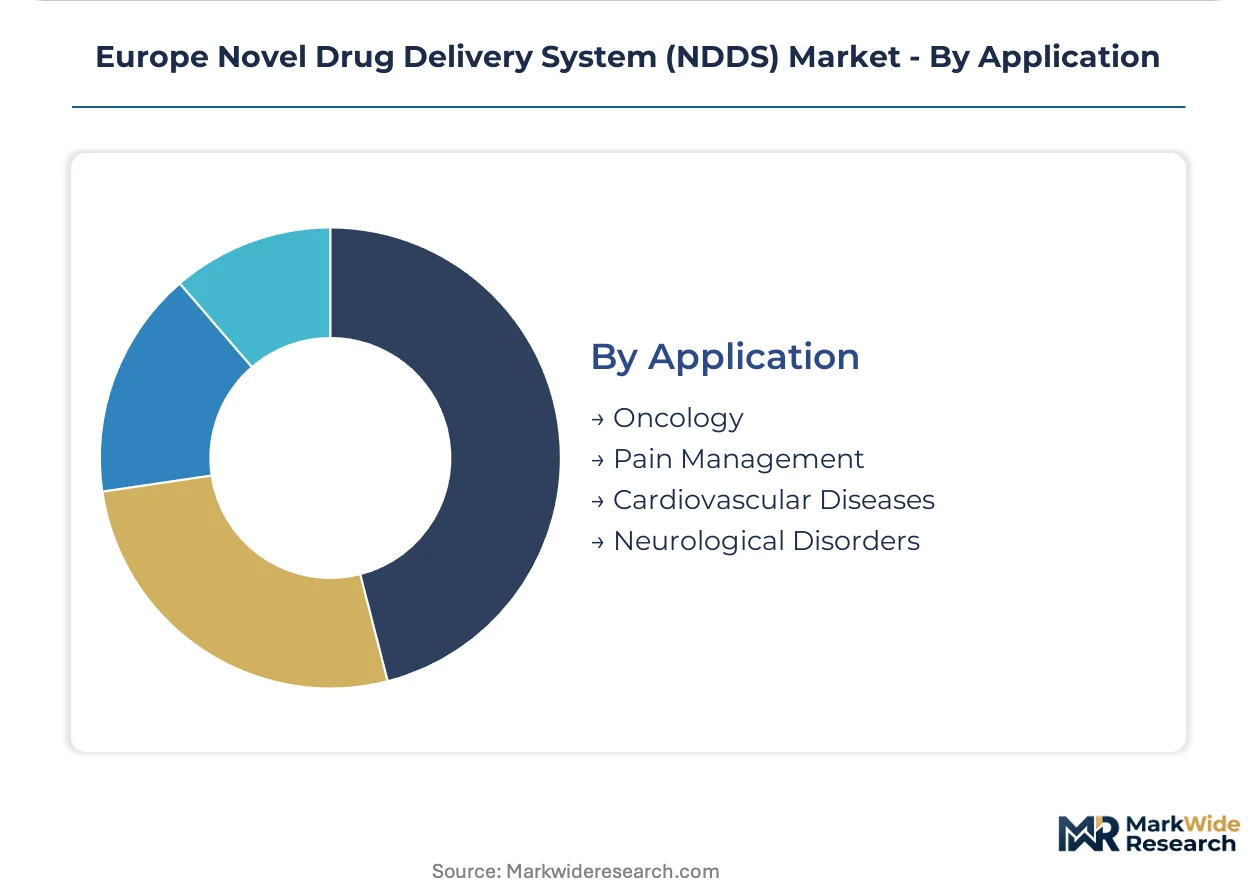
Application:
Therapeutic area focus determines reimbursement pathway complexity and real-world evidence requirements for market access.
- Oncology:Lipid nanoparticle and antibody-drug conjugate platforms demand tissue-specific localization with minimized systemic exposure. EMA's evolving ATMP guidelines force sponsors to rebuild quality management systems for cell and gene therapy combinations.
- Pain Management:Patient compliance requirements are tightening around sustained-release formulations that reduce dosing frequency. Transdermal and microneedle platforms displace oral opioid schedules with abuse-deterrent delivery profiles.
- Cardiovascular Diseases:Anticoagulant and antihypertensive portfolios utilize oral modified-release and injectable depot systems.
- Neurological Disorders:Blood-brain barrier penetration challenges concentrate investment in nanoparticle surface engineering and intrathecal delivery routes.
Oncology absorbs the dominant development spend; Pain Management is gaining share fastest on self-administration preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main logistics corridor underwrites Frankfurt's dominance as Europe's pharmaceutical distribution hub, with temperature-controlled warehousing capacity expanding 340,000 cubic meters since 2022. This infrastructure anchors the continent's biologics cold chain.
Germany
Frankfurt and Munich pharmaceutical clusters drive injectable systems demand through diabetes and obesity therapy pipelines. The EMA's centralized marketing authorization procedures expedite combination product submissions from Bavaria-based sponsors. Baden-Württemberg's precision engineering ecosystem supplies autoinjector assembly equipment to Western European CMOs.
Switzerland
Basel's pharmaceutical headquarters concentrate lipid nanoparticle R&D investment for oncology applications. Swissmedic's alignment with EMA standards accelerates parallel submission pathways for nanomedicine platforms. The Greater Zurich Area hosts supercritical CO2 precipitation facilities that circumvent REACH solvent constraints affecting Belgian competitors.
France
Paris academic medical centers fragment procurement authority through therapeutic-area specific formulary committees. ANSM's national pilot programs on real-world performance data reward sponsors with integrated digital health systems. The Île-de-France region anchors Sanofi's delivery platform development for mRNA portfolios.
Netherlands
Rotterdam's port infrastructure enables API import efficiency for polymeric nanoparticle manufacturers serving Benelux markets. The Dutch Medicines Evaluation Board participates in EMA regulatory science initiatives on microneedle characterization. Eindhoven's high-tech systems sector supplies precision molding for transdermal patch production.
Belgium
Flemish oncology CDMOs face compressed competitive windows as REACH authorization lists expand substances of very high concern. The Federal Agency for Medicines and Health Products enforces European Pharmacopoeia standards for liposome phase transition specifications. Brussels' regulatory proximity attracts EMA consultation-seeking sponsors from across the continent.
Europe Novel Drug Delivery System (NDDS) Market Competitive Landscape
Listed leaders compete with private specialists across platform standardization and regulatory compliance capabilities. The vendor base stratifies into three tiers: vertically integrated pharmaceutical sponsors controlling device specifications, independent device engineering specialists, and regional contract manufacturers. Strategic moves concentrate on notified body pre-certification partnerships and cleanroom capacity expansion in Central European markets.
Among Germany-based fabricators, Gerresheimer AG exemplifies the primary packaging archetype through glass and polymer containment expertise. Novo Nordisk occupies a position representing sponsor-led device integration for chronic therapy administration. Sanofi sits within the nanomedicine platform tier, anchoring lipid nanoparticle capabilities that sustain oncology and infectious disease portfolios.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Novo Nordisk |
| Fresenius Kabi |
| Sanofi |
| Novartis |
| Nemera |
| SHL Medical |
| AstraZeneca |
| B. Braun |
| Others |
Supply & Pricing Matrix
Supercritical CO2 precipitation methods displacing organic solvent-based nanoparticle synthesis are redrawing manufacturing geography toward Switzerland and compressing cost structures for polymeric platform producers. This substitution simultaneously loosens REACH authorization constraints on Belgian competitors and concentrates premium pricing power with early adopters of green chemistry routes.
Pricing Analysis
Volume-discount tiering structures separate high-volume biologics sponsors negotiating multi-year autoinjector contracts from mid-tier CMOs purchasing glass tubing on spot markets. Pricing stratifies across premium CE-marked combination products, standard notified body-certified devices, and economy-grade primary packaging for generic portfolios. Cost compression in the economy tier is intensifying as Indian and Chinese glass suppliers enter European qualification pipelines. Academic medical centers with dedicated formulary committees exhibit lowest price sensitivity; small-molecule generic sponsors remain most exposed to input volatility.
Supply Chain Analysis
Just-in-time inventory strategies dominate injectable assembly operations, though strategic stockpiling of borosilicate glass tubing is emerging among German biologics sponsors exposed to three-vendor concentration. Supply draws from Germany for precision autoinjector components, Switzerland for supercritical CO2 processing equipment, and Italy for polymeric membrane materials. Single-source vulnerability concentrates in borosilicate tubing supply, where Schott, Nipro, and Stevanato Group control European capacity. Distribution runs through Frankfurt's Rhine-Main logistics corridor, with temperature-controlled warehousing feeding hospital procurement consortia and pharmacy-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid skill sets spanning nanomedicine physicochemical characterization and EMA regulatory documentation are undersupplied across European universities, constraining platform development velocity and inflating specialist compensation premiums.
For Market Incumbents: Consolidate notified body pre-certification partnerships ahead of anticipated EMA guidance on real-world performance data for drug-device combinations. Deepen captive supply of glass primary packaging through equity stakes in tubing manufacturers, insulating against input volatility that threatens margin stability in prefilled syringe portfolios. For New Entrants and Emerging Players: Differentiate on microneedle patch platforms combined with connected compliance monitoring, targeting pain management segments where patient adherence requirements are tightening. Poland and Czech Republic injectable assembly capacity offers white-space positioning for Western European sponsor relationships, with direct key account teams bypassing fragmented hospital procurement consortia. For Investors and Strategic Acquirers: The market sits at a platform standardization phase that favors CDMOs with integrated digital health capture systems and cleanroom infrastructure in Central European markets. Acquisition targets with EMA consultation history and supercritical CO2 precipitation capabilities offer defensive positioning through regulatory moats. Watch lipid nanoparticle phase transition temperature specifications in European Pharmacopoeia monographs as inflection indicator for oncology platform commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Pre-Certification Partnership | EMA's MDR implementation creates competitive moats for early-compliant combination product manufacturers. |
| Supercritical CO2 Precipitation Capacity | REACH solvent constraints force Belgian and Swiss oncology CDMOs toward green chemistry manufacturing routes. |
| Central European Cleanroom Expansion | Underdeveloped Poland and Czech Republic infrastructure offers first-mover positioning for injectable assembly serving Western sponsors. |
| Digital Health Capture Integration | Anticipated EMA post-market surveillance guidance rewards sponsors with real-world performance data infrastructure. |
| Microneedle Patch Platform Development | Dutch and German pain management pilots bypass cold-chain requirements and disintermediate hospital outpatient departments. |
Research Methodology
A spread of perspectives from regulatory affairs leads at EMA-notified bodies, formulary directors at Paris and Berlin academic medical centers, hospital procurement managers, and nanomedicine characterization scientists converged on the working assumptions. Primary interview insights triangulated against EMA submission databases, European Pharmacopoeia monograph revisions, ClinicalTrials.gov protocol records, and REACH authorization list updates. Bottom-up platform-level demand modeling and top-down therapeutic area spending analysis cross-validated volume and value estimates.
Segmentation dimensions modeled include product type classification across injectable systems, transdermal patches, inhalation devices, and oral platforms; technology tiers spanning nanoparticles, liposomes, and polymeric matrices; end-user archetypes from vertically integrated pharma sponsors to regional CMOs; and application areas across oncology, pain management, and diabetes therapy. CAGRs derived from patent filing trajectories, pipeline stage advancement rates, and notified body capacity expansion timelines across the projection horizon. Pricing elasticity assumptions incorporated formulary committee negotiation patterns and glass tubing supply concentration effects.
Material uncertainties — EMA regulatory science pilot outcomes on nanomedicine characterization, notified body designation expansions for high-risk combination products, and F-Gas Regulation amendment scopes — sit outside the modeled envelope. Forecasts reflect documented assumptions on pipeline advancement rates and procurement authority fragmentation trajectories. Revision becomes warranted when centralized hospital purchasing consortium dissolution accelerates beyond therapeutic-area specific buying group formation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Meningitis Vaccine Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Ebola Drug and Vaccine Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Parenteral Drugs Market