
 Anesthesia Face Masks Market | 2026-2036
Anesthesia Face Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Face Masks Market Analysis
ISO 13485-certified manufacturing is rotating toward the center of purchasing decisions in developed markets. Smiths Medical leverages captive silicone molding operations across multiple continents to secure supply continuity for premium mask lines. Intersurgical Ltd. anchors its position through exhaustive size granularity, offering small through extra-large configurations that reduce anesthesia leakage rates in pediatric applications. Ambu A/S differentiates via disposable-focused R&D intensity, channeling development resources toward eliminating reprocessing costs for high-volume hospital buyers.
An anesthesia face mask constitutes a dome-shaped interface positioned over the patient's nose and mouth to deliver inhalational anesthetic agents and oxygen while maintaining a sealed airway pathway; specifications typically encompass port diameters of 22 mm per ISO 5356-1 and cushion materials engineered to distribute sealing pressure below 30 mmHg to prevent facial nerve injury. Silicone dominates material selection for reusable segments due to autoclavability exceeding 100 cycles, while PVC anchors disposable volumes where unit economics favor single-patient use. Hospitals represent the deepest end-user pool, though outpatient clinics represent the fastest-growing channel as procedure migration accelerates.
The FDA's 510(k) premarket notification framework and the European Union's Medical Device Regulation (MDR) collectively elevate barrier-to-entry thresholds for new market participants, particularly around biocompatibility testing per ISO 10993 and clinical evaluation documentation. The EPA's evolving scrutiny of PVC plasticizer leachates, notably DEHP, is redirecting formulation roadmaps toward alternative thermoplastic elastomers in North American supply chains. Stakeholders must monitor regulatory divergence between FDA and notified body interpretation of substantial equivalence for modified mask geometries.
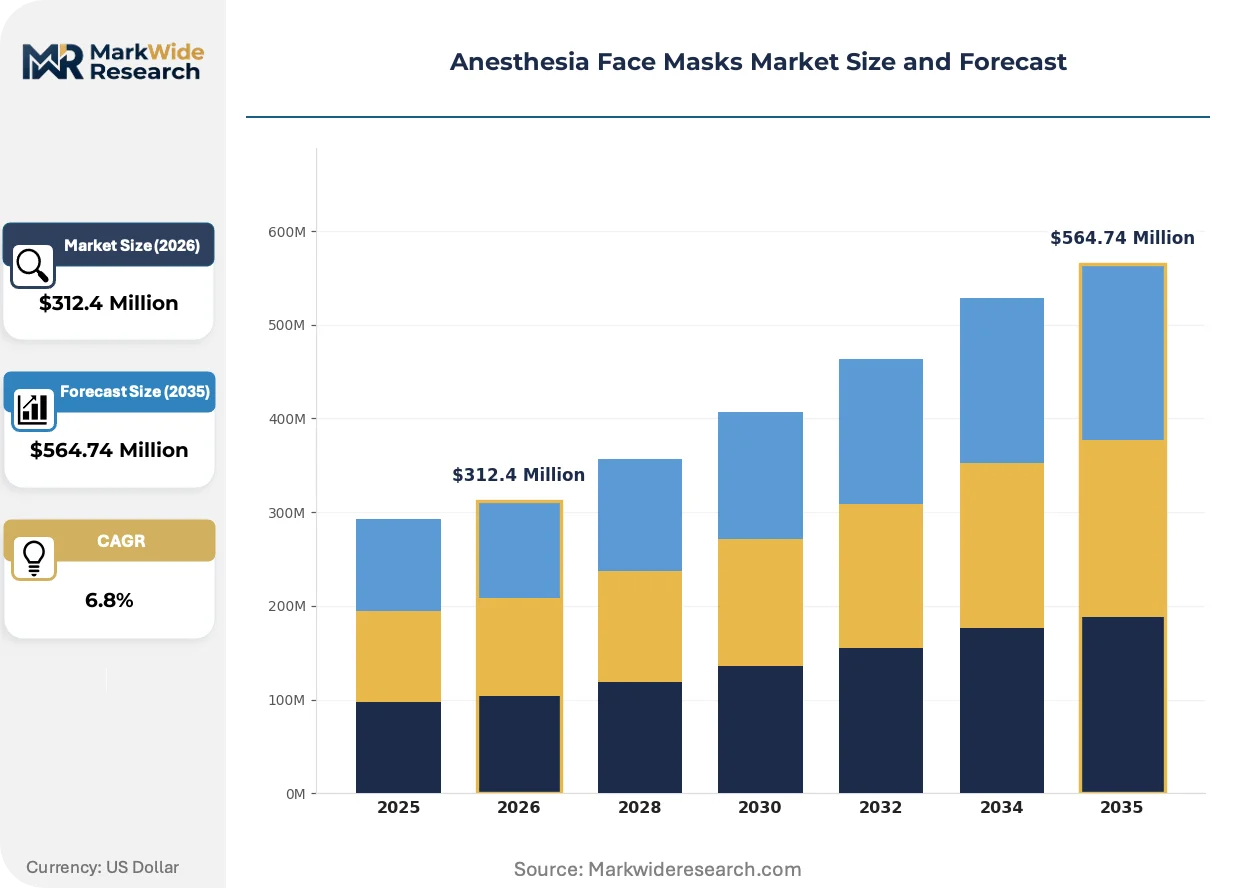
Market Dynamics
The migration of surgical procedures from inpatient facilities to ambulatory surgical centers is compressing mask utilization cycles and elevating single-use preference over reusable alternatives, fundamentally restructuring procurement volume distribution across healthcare delivery channels.
Growth Catalysts
- ASC Expansion:Ambulatory surgical centers in the United States are accelerating procedure throughput, generating concentrated demand for high-volume disposable anesthesia mask procurement.
- FDA 510(k) Pathway Refinement:Streamlined premarket notification processes for Class II modifications are shortening product iteration cycles for established manufacturers with robust biocompatibility dossiers.
- Silicone Autoclavability:Premium reusable segments leverage silicone cushion materials exceeding 100 sterilization cycles, sustaining hospital capital equipment investment despite single-use growth.
Market Restraints
- DEHP Regulatory Pressure:EPA scrutiny of phthalate plasticizer leachates in PVC formulations is forcing North American supply chain reconfiguration toward alternative thermoplastic elastomers with unproven scale economics.
- ISO 13485 Certification Concentration:Quality management system certification requirements concentrate qualified manufacturing capacity in Western Europe and select East Asian contract producers, limiting new entrant access.
- MDR Clinical Evaluation Burden:European Union Medical Device Regulation documentation requirements for substantial equivalence claims impose 18-24 month approval timelines that freeze product portfolio refresh rates.
Strategic Opportunities
- Pediatric Size Granularity:Underpenetrated niches in neonatal and infant mask configurations present white space for specialized cushion geometry development addressing facial nerve protection below 30 mmHg pressure thresholds.
- Outpatient Clinic Channel:Procedure migration to non-hospital settings in Germany and France is creating demand for compact, pre-assembled mask-ventilation circuit kits eliminating reprocessing infrastructure.
- ISO 10993-5 Cytotoxicity Streamlining:Harmonized biocompatibility testing protocols across notified bodies are reducing redundant study costs for multi-market product registrations.
Industry Challenges
- Biocompatibility Study Talent Scarcity:Contract research organizations with ISO 10993-10 sensitization and ISO 10993-6 implantation testing capabilities face 6-9 month backlog queues, delaying 510(k) submission timelines.
- Legacy Reprocessing Infrastructure Stranded Costs:Hospital central sterile supply departments with capital-intensive washer-disinfector and autoclave investments resist full conversion to disposable models despite infection control mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Face Masks Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Masks, Disposable Masks, Neonatal Masks, Pediatric Masks Material: Silicone, PVC, Rubber, Thermoplastic Size: Small, Medium, Large, Extra Large End User: Hospitals, Outpatient Clinics, Dental Practices, Emergency Services |
| Companies Covered | Smiths Medical, Intersurgical Ltd., Ambu A/S, GE Healthcare, Drägerwerk AG & Co. KGaA, Becton Dickinson Company, Medline Industries LP, Hsiner Co. Ltd., Kindwell Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Face Masks Market Emerging Trajectories
Material science advances and regulatory harmonization efforts are converging to reshape product architecture and go-to-market economics, with particular pressure on plasticizer chemistry and manufacturing quality systems.
Micro-cuff silicone sealing technology is miniaturizing the pressure distribution footprint across pediatric and geriatric facial topologies, enabling secure airway maintenance at sub-25 mmHg cushion pressures. Children's hospitals and specialized pediatric surgical centers are adopting these configurations at 2-3x the rate of general acute care facilities. The technology is miniaturizing the addressable patient population for premium mask lines downward into neonatal weight categories previously managed with uncuffed alternatives.
REACH Annex XVII restrictions on phthalate content in medical devices are compelling European manufacturers to validate alternative plasticizers in PVC cushion compounds before 2025 enforcement deadlines. Industrial consequence includes accelerated thermoplastic elastomer formulation partnerships between mask producers and polymer suppliers. Pediatric and long-duration procedure segments are most affected, with notified bodies demanding extended leachate migration studies for products exceeding 1-hour patient contact durations.
Hospital buying consortiums are consolidating anesthesia supply contracts into multi-year, single-source agreements bundling masks, breathing circuits, and filters under total-procedure-cost metrics. Independent distributors and regional medical-surgical dealers are losing shelf space to direct manufacturer relationships with IDN procurement offices. The United States exhibits the most visible consolidation, where ten health systems now control 35-40% of anesthesia mask purchasing volume through centralized standardization committees.
Anesthesia Face Masks Market Segmentation
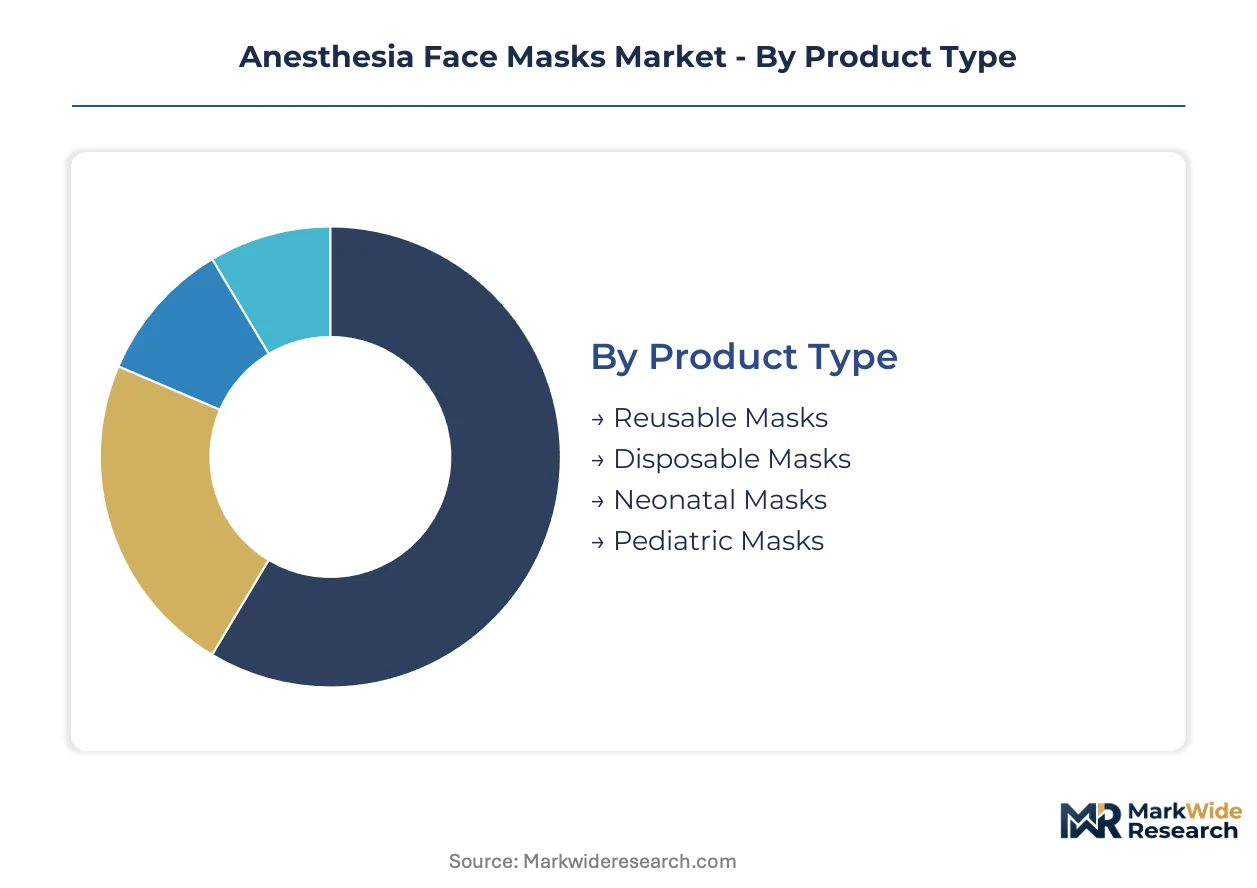
Anesthesia face masks fragment across four critical dimensions that determine procurement economics and clinical utility. Product type and material selection drive sterilization protocol decisions, while size granularity and end-user channel shape volume distribution and pricing power across healthcare delivery networks.
Product Type:
Disposable configurations face intensifying substitution pressure from single-use ventilation alternatives, yet reusable segments defend position through total cost-of-ownership arguments in capital-constrained hospital systems.
- Reusable Masks:Silicone cushion construction withstands 100+ autoclave cycles per ISO 17665 validation. Demand concentrates in German university hospitals and French public hospital networks where central sterile supply infrastructure amortizes reprocessing labor costs across high surgical volumes.
- Disposable Masks:PVC or thermoplastic elastomer formulations eliminate cross-contamination risk and reprocessing labor. United States ambulatory surgical centers are standardizing on these configurations as procedure throughput accelerates and infection control mandates tighten.
- Neonatal Masks:Micro-cuff silicone sealing technology addresses facial nerve protection below 25 mmHg pressure thresholds in sub-3kg patient populations.
- Pediatric Masks:Intermediate size configurations bridge neonatal and adult geometries, capturing demand from children's hospitals prioritizing anatomical fit precision.
Disposable masks retain volume leadership; neonatal configurations hold the steepest expansion curve as premature birth intervention rates climb.
Material:
Cost tier stratification separates premium autoclavable compounds from economy single-use formulations, with regulatory pressure on plasticizer chemistry compressing intermediate options.
- Silicone:Platinum-cured elastomer delivers biocompatibility per ISO 10993-5 and thermal stability exceeding 134°C steam sterilization. Premium reusable mask lines in Switzerland and Germany specify medical-grade silicone for 500+ cycle durability.
- PVC:Plasticized polyvinyl chloride dominates disposable volumes where unit economics favor single-patient use. EPA scrutiny of DEHP leachates is forcing North American supply chains toward alternative plasticizers before enforcement deadlines.
- Rubber:Natural and synthetic latex compounds persist in legacy reusable lines, though latex sensitivity concerns limit new adoption.
- Thermoplastic:TPE formulations are gaining validation as DEHP-free alternatives, with polymer suppliers accelerating medical-grade compound development partnerships.
PVC maintains shipment dominance; thermoplastic elastomers are expanding most quickly as phthalate restrictions harden.
Size:
Application-specific anatomical requirements distribute demand across patient demographics, with pediatric precision driving premium pricing power.
- Small:Pediatric and small-adult configurations require cushion geometry optimization to prevent facial nerve compression below 30 mmHg sealing pressure.
- Medium:Standard adult dimensions capture the broadest patient population and highest absolute shipment volumes across general surgical procedures.
- Large:Bariatric and large-adult specifications address obesity prevalence trends in United States and Mexican surgical populations.
- Extra Large:Specialized configurations for morbid obesity cases and specific facial topography variations command 40-60% price premiums over standard sizes.
Medium size brackets anchor volume; extra-large specifications gain share fastest as bariatric procedure volumes rise.
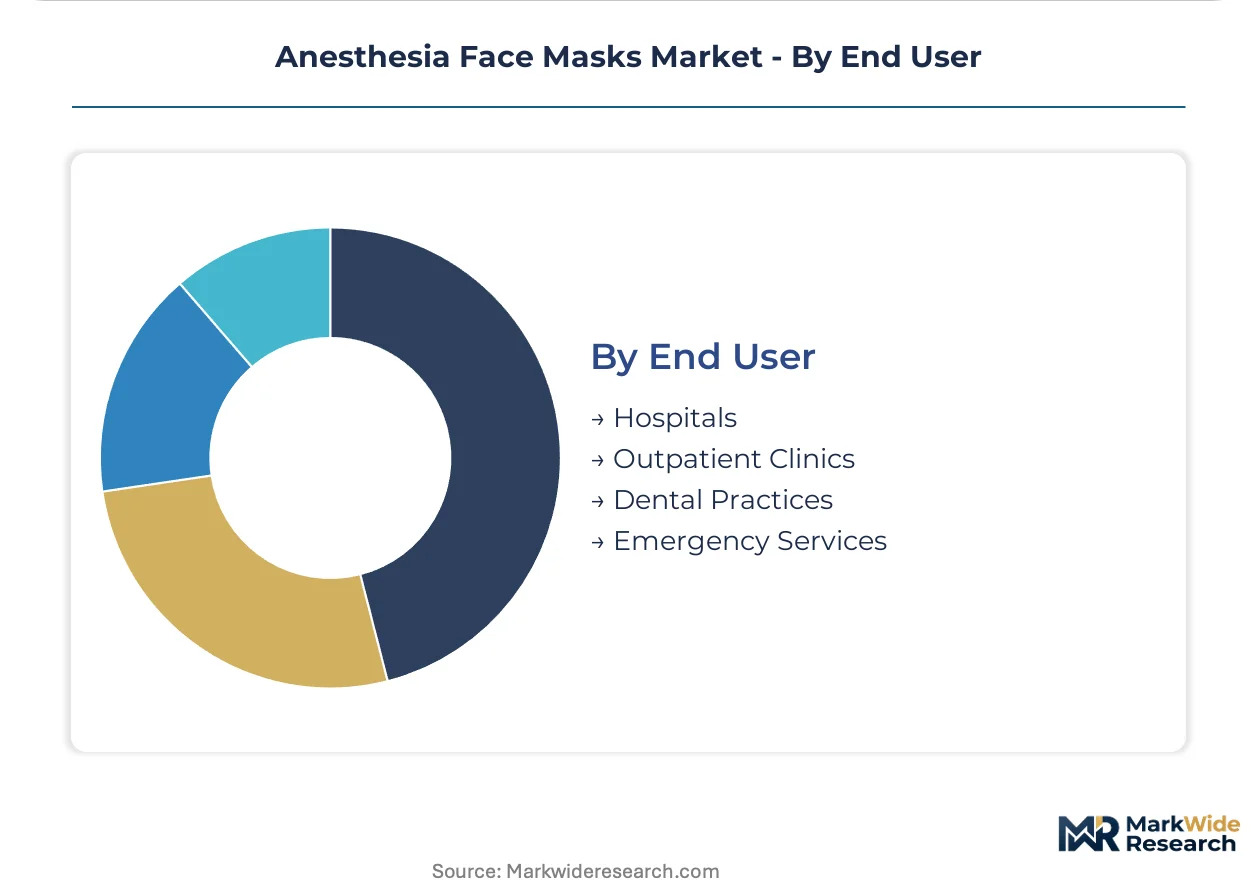
End User:
Customer type determines procurement sophistication, with hospital buying consortiums extracting price concessions that outpatient channels cannot match.
- Hospitals:Integrated delivery networks in the United States and national health service trusts in the United Kingdom consolidate anesthesia supply contracts into multi-year agreements bundling masks, circuits, and filters.
- Outpatient Clinics:Procedure migration to non-hospital settings in Germany and France creates demand for compact, pre-assembled mask-ventilation kits eliminating reprocessing infrastructure investment.
- Dental Practices:Conscious sedation applications require smaller minimum order quantities and distributor-supported inventory management.
- Emergency Services:Pre-hospital airway management demands ruggedized, rapid-deployment configurations with universal 22mm ISO 5356-1 port compatibility.
Hospitals command volume leadership; outpatient clinics are climbing the fastest as same-day surgery protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Swiss manufacturers supply hospital networks across Eastern Europe and the Middle East, while the United States runs a modest trade deficit in disposable mask categories sourced from Asian contract producers. Import dependency concentrates in PVC resin and medical-grade silicone feedstocks, with regional supply chains diverging around phthalate regulatory thresholds.
United States
Ambulatory surgical center expansion in Texas, Florida, and Arizona compresses mask utilization cycles toward single-use preference. FDA 510(k) clearance timelines for Class II device modifications shape product refresh rates for domestic manufacturers. The Minneapolis-St. Paul corridor hosts concentrated anesthesia device engineering talent pools serving integrated delivery network procurement offices.
Germany
University hospital networks in Bavaria and Baden-Württemberg sustain demand for autoclavable silicone configurations exceeding 100 sterilization cycles. REACH Annex XVII phthalate restrictions accelerate thermoplastic elastomer validation partnerships between mask producers and polymer suppliers. The Freiburg medical technology cluster anchors precision molding operations for pediatric micro-cuff geometries.
China
Domestic surgical volume growth in tier-one cities drives consumption of economy-grade disposable masks for high-throughput procedures. NMPA medical device registration requirements for imported silicone materials extend supply chain qualification timelines. The Suzhou industrial park concentrates contract manufacturing capacity serving European and North American brand holders.
Japan
Aging surgical demographics elevate demand for geriatric-optimized cushion geometries distributing pressure below 25 mmHg. PMDA quality management system inspections enforce ISO 13485 compliance rigor that filters out non-specialized suppliers. The Osaka-Kobe manufacturing belt sustains captive silicone compounding operations for premium reusable mask lines.
India
Private hospital chain expansion in Maharashtra and Karnataka creates procurement volume for mid-tier disposable configurations. CDSCO medical device rules harmonization with IMDRF standards streamlines import pathways for established manufacturers. The Chennai medical device cluster hosts assembly operations for export-oriented mask-ventilation circuit kits.
Anesthesia Face Masks Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The vendor base stratifies into three tiers: multinational diversifiers with full anesthesia workstation portfolios, mid-cap disposable specialists channeling R&D toward infection control economics, and regional fabricators serving price-sensitive procurement channels. Competitive maneuvering concentrates on M&A for size granularity IP and strategic partnerships with polymer suppliers for DEHP-free formulation access.
Within the disposable-specialist tier, Ambu A/S and Intersurgical Ltd. exemplify divergent strategic anchors. Smiths Medical occupies a position bridging premium reusable silicone lines with high-volume disposable supply contracts. Drägerwerk AG & Co. KGaA anchors the integrated-systems archetype where mask procurement bundles into anesthesia workstation agreements. GE Healthcare and Becton Dickinson Company represent diversified health technology conglomerates where mask categories sit within broader respiratory and critical care portfolios.
| Leading Market Players |
|---|
| Smiths Medical |
| Intersurgical Ltd. |
| Ambu A/S |
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Becton Dickinson Company |
| Medline Industries LP |
| Hsiner Co. Ltd. |
| Kindwell Medical |
| Others |
Supply Flow & Price Mechanics
Multi-year single-source contracts bundling masks, circuits, and filters lock in supply access for integrated delivery networks while anchoring price visibility across volatile raw material cycles. Hospital buying consortiums in the United States leverage these arrangements to compress procurement costs as ambulatory surgical center volumes accelerate.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 13485 certification grade and silicone cushion durability measured in autoclave cycles. Cost compression in PVC disposable tiers is intensifying because EPA DEHP scrutiny forces reformulation toward unproven thermoplastic elastomer alternatives. Ambulatory surgical centers exhibit highest price sensitivity; German university hospitals demonstrate lowest sensitivity due to capital equipment amortization logic.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach elevates inbound logistics costs for Asian contract manufacturers serving North American brand holders. Geographic supply concentration centers on China for PVC resin compounding, Germany for precision silicone molding, and Switzerland for medical-grade elastomer formulation. Raw material dependencies draw from petroleum-derived vinyl chloride monomer, platinum-cured silicone polymers, and DEHP alternative plasticizers. Single-source vulnerability concentrates in medical-grade silicone feedstocks where Japanese and German suppliers dominate. Distribution runs through hospital buying consortiums and group purchasing organizations that displace independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as ten United States health systems now control 35-40% of anesthesia mask purchasing volume through centralized standardization committees, extracting terms that fragment margin pools across the vendor base.
For Market Incumbents: Shield premium reusable silicone lines by deepening backward integration into captive compounding operations in Japan and Germany, insulating against medical-grade silicone feedstock volatility. Accelerate ISO 10993-5 cytotoxicity dossier refresh cycles to preempt FDA 510(k) submission delays as biocompatibility study queues lengthen at contract research organizations. For New Entrants and Emerging Players: FDA 510(k) streamlined pathway for Class II device modifications offers fastest regulatory entry for established contract manufacturers with existing biocompatibility documentation. Target neonatal micro-cuff configurations where facial nerve protection below 25 mmHg remains underpenetrated and pricing power exceeds standard adult tiers. Lead with pre-assembled mask-ventilation circuit kits for German and French outpatient clinics eliminating reprocessing infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap disposable specialists with validated DEHP-free thermoplastic elastomer partnerships. Long-term viability over the next decade hinges on polymer chemistry IP and pediatric size granularity portfolios. Watch REACH Annex XVII enforcement timelines as inflection indicator for European supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Cytotoxicity Streamlining | Redundant biocompatibility study elimination accelerates multi-market product registrations for notified body alignment. |
| DEHP-Free Formulation Partnership | Polymer supplier collaborations secure alternative plasticizer access ahead of EPA and REACH enforcement deadlines. |
| Pediatric Micro-Cuff Development | Sub-25 mmHg pressure distribution technology captures neonatal segments at 2-3x adoption rates versus general acute care. |
| Hospital System Direct Contracting | Bypassing independent distributors secures shelf space within integrated delivery network procurement offices. |
| Ambulatory Surgical Center Kit Assembly | Pre-configured mask-ventilation circuits eliminate reprocessing infrastructure for same-day surgery protocols. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with anesthesia department heads, biomedical engineers, GPO contracts managers, and central sterile supply directors; and secondary validation against FDA 510(k) filings, hospital procurement databases, EPA chemical substance registrations, and customs trade flow records. Bottom-up volume triangulation across product type, material, size, and end-user segments converged with top-down value estimates derived from manufacturer revenue disclosures and distributor channel checks.
Across the analysis window, the forecasting framework modeled demand drivers including ambulatory surgical center expansion rates, procedure migration patterns, and regulatory compliance cost burdens. Segmentation dimensions encompassed product type hierarchy, material chemistry tiers, anatomical size brackets, and healthcare delivery channel evolution. CAGRs were derived from elasticity-adjusted procedure volume projections and price trajectory assumptions tied to raw material cost cycles and buying consortium negotiation intensity.
Underlying assumptions cover continued FDA 510(k) pathway stability, REACH Annex XVII enforcement adherence, and silicone autoclavability validation standards, with deviation risk concentrated in DEHP alternative plasticizer scale economics and biocompatibility study capacity constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
North America Vagus Nerve Stimulation Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Brazil Respiratory Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Human Enhancement Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Clear Aligners Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Penile Implants Market