
 Global Bed Monitoring System and Baby Monitoring System Market | 2026-2036
Global Bed Monitoring System and Baby Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bed Monitoring System and Baby Monitoring System Market Foresight
Hospital procurement is rotating toward home healthcare providers as the fastest-expanding buyer archetype for bed and baby monitoring infrastructure. Nanit leverages its computer vision stack to dominate the premium consumer segment for infant sleep analytics. Owlet Baby Care, Inc. specializes in wearable pulse-oximetry socks that anchor its position among direct-to-parent channels. Koninklijke Philips N.V. controls institutional sales through its entrenched presence in neonatal intensive care equipment across North American and European health systems.
Bed monitoring systems and baby monitoring systems comprise networked sensor arrays, wearable biometric patches, and video-analytics platforms that detect occupancy, movement, respiration, and cardiac signals for at-risk infants and bedridden adults. Pressure mats and radar sensors typically operate at frequencies between 24 GHz and 60 GHz to enable non-contact vital sign capture without skin adhesion. Wireless sensors lead product-type revenue due to their interoperability with existing hospital IT infrastructure, while wearable devices represent the fastest-growing category as miniaturized MEMS accelerometers and optical heart-rate modules penetrate pediatric and geriatric home settings. Application-level margin pools concentrate in vital signs monitoring and sleep pattern analysis, where software subscription layers stack atop hardware deployments.
FDA premarket notification requirements for software-as-medical-device functionality constrain market entry timelines for AI-powered baby monitors in the United States, while the EU Medical Device Regulation imposes clinical evidence thresholds on fall-detection algorithms sold across European member states. EMA notified-body scrutiny of predictive analytics in patient monitoring is elevating quality-management system investments among vendors seeking CE marking. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as Medicare and private payors recalibrate coverage for hospital-at-home bed monitoring deployments.
Market Dynamics
Hospital-at-home reimbursement expansions by Medicare are redirecting procurement flows from acute-care facilities toward distributed home healthcare networks, compressing traditional capital-equipment sales cycles into subscription-based remote monitoring deployments.
Growth Catalysts
- Wireless sensor interoperability:24-60 GHz radar and pressure-mat arrays integrate with existing hospital IT infrastructure, lowering deployment friction for health systems in Germany and the United States.
- FDA software-as-medical-device pathways:Pre-market notification frameworks for AI-enabled infant monitors create defined regulatory on-ramps, accelerating commercialization timelines for predictive analytics vendors.
- Geriatric home care expansion:Japan's aging population and METI-backed telehealth initiatives are driving non-contact vital sign monitoring into single-resident dwellings and assisted-living facilities.
Market Restraints
- MEMS component supply concentration:Miniaturized accelerometer and optical heart-rate module fabrication clusters in Taiwan and South Korea create single-source vulnerability for wearable device manufacturers.
- EU MDR clinical evidence thresholds:Fall-detection algorithms require notified-body scrutiny under CE marking rules, extending validation timelines and elevating quality-management system costs for European market entry.
- Radar-frequency spectrum allocation:60 GHz non-contact sensing faces competing claims from telecommunications and automotive LiDAR applications in multiple jurisdictions, threatening dedicated bandwidth availability.
Strategic Opportunities
- India's hospital-at-home pilot programs:CDSCO regulatory harmonization efforts and private insurer remote-patient-monitoring experiments create first-mover positioning for wireless bed-monitoring kit vendors.
- Computer vision and edge-AI convergence:On-device infant sleep analytics reduce cloud dependency and latency, opening premium consumer segments in privacy-sensitive European markets.
- Direct-to-parent channel expansion:Subscription-based sleep coaching and pediatric telehealth integration bypass traditional retail and clinical distribution, capturing lifetime value through software layering.
Industry Challenges
- Biomedical algorithm validation talent scarcity:FDA 510(k) software documentation and clinical-performance testing require specialized regulatory-affairs and machine-learning engineering competencies that outpace graduate program output.
- Legacy EHR integration complexity:Proprietary data formats in established hospital information systems force costly middleware development for sensor-to-record continuity.
- Patent thickets in optical heart-rate sensing:PPG signal-processing IP portfolios held by incumbent wearable manufacturers create licensing friction for pediatric pulse-oximetry entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bed Monitoring System and Baby Monitoring System Market |
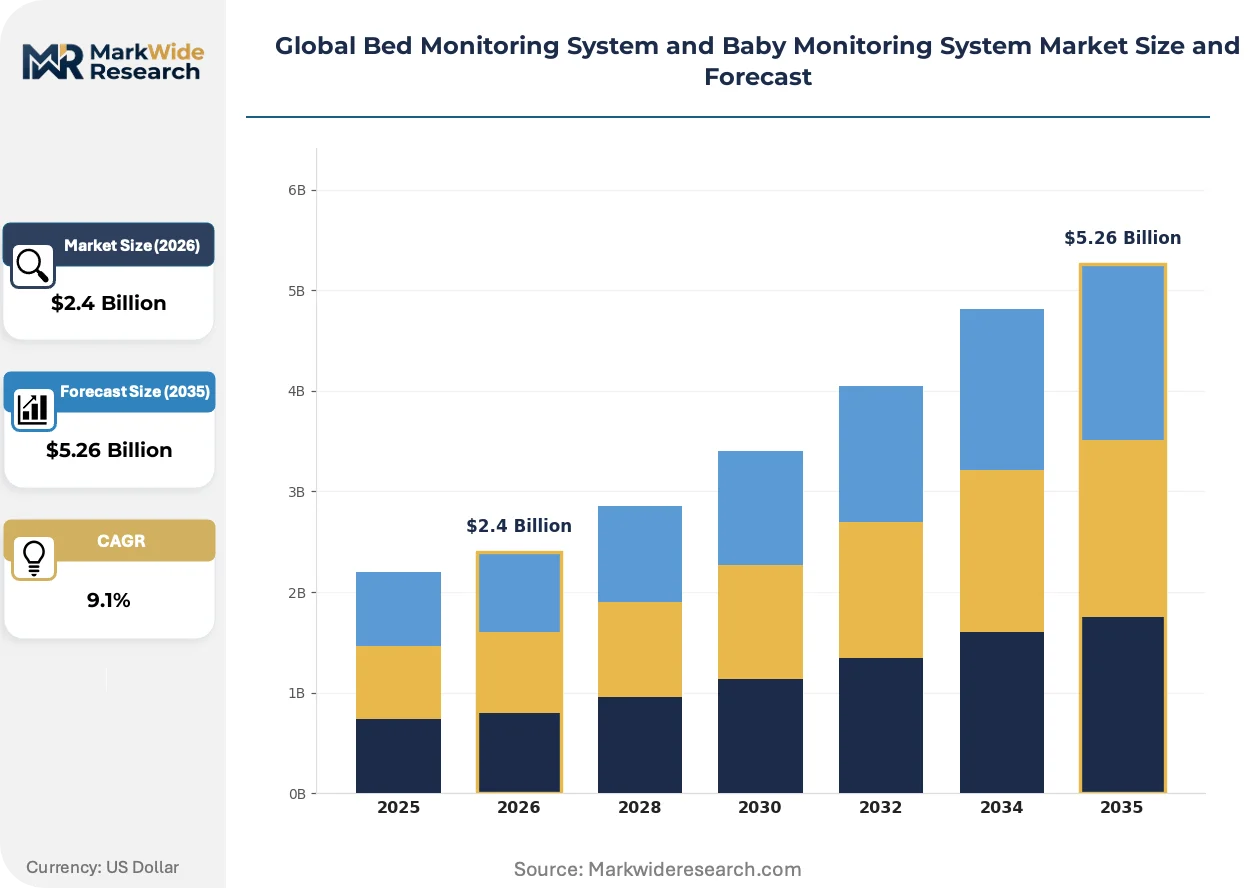
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.26 Billion |
| CAGR (2026 – 2036) | 9.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Pressure Mats, Video Monitors, Audio Monitors, Wearable Devices Technology: Infrared Sensors, Radar Sensors, Ultrasonic Sensors, Bluetooth, RFID Application: Fall Detection, Vital Signs Monitoring, Sleep Pattern Analysis, Infant Movement Tracking, Bed Occupancy Detection End User: Hospitals, Pediatric Care Centers, Senior Living Facilities, Home Healthcare Providers, Neonatal Units |
| Companies Covered | Owlet Baby Care, Inc., Nanit, VTech Holdings Ltd, Motorola Mobility LLC, Koninklijke Philips N.V., Tekscan, Inc., WellSense Health Plan, XSENSOR Technology Corporation, Angelcare Monitors Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bed Monitoring System and Baby Monitoring System Market Shifts & Advancements
Sensor modality competition and algorithmic differentiation are fragmenting product architectures, with vendors placing divergent bets on contact versus non-contact vital sign capture and cloud versus edge inference deployment.
Radar-based non-contact monitoring is bifurcating the product landscape. 24-60 GHz frequency-modulated continuous-wave sensors detect micro-movements associated with respiration and cardiac contraction without skin adhesion. Geriatric home care providers in Japan and Germany are adopting these systems for fall-risk patients who resist wearable compliance. The technology is bifurcating hardware margins between premium radar-array configurations and commoditized pressure-mat alternatives, compressing mid-tier positioning.
EMA notified-body scrutiny under the EU Medical Device Regulation is elevating clinical evidence requirements for predictive analytics. Fall-detection and sleep-apnea algorithms now require prospective validation studies, not retrospective performance claims. Pediatric monitoring vendors targeting European health systems are restructuring quality-management systems and expanding clinical-affairs teams to satisfy MDR Annex XIV documentation thresholds, with CE marking timelines extending accordingly.
Subscription unbundling from hardware is restructuring buyer relationships. Home healthcare agencies and direct-to-parent channels increasingly separate sensor kit procurement from ongoing sleep-analytics or vital-sign-monitoring services. This pattern concentrates most visibly in United States hospital-at-home programs, where Medicare reimbursement for remote patient monitoring creates recurring revenue pools that offset upfront equipment subsidies and extend customer lifetime value beyond initial deployment.
Global Bed Monitoring System and Baby Monitoring System Market Segmentation
Product architecture in bed and baby monitoring fragments across sensor modality, connectivity protocol, and care setting. Procurement patterns diverge sharply between institutional buyers seeking EHR integration and direct-to-consumer channels prioritizing installation simplicity. Understanding substitution dynamics across these dimensions clarifies where vendors must defend positioning against adjacent technologies.
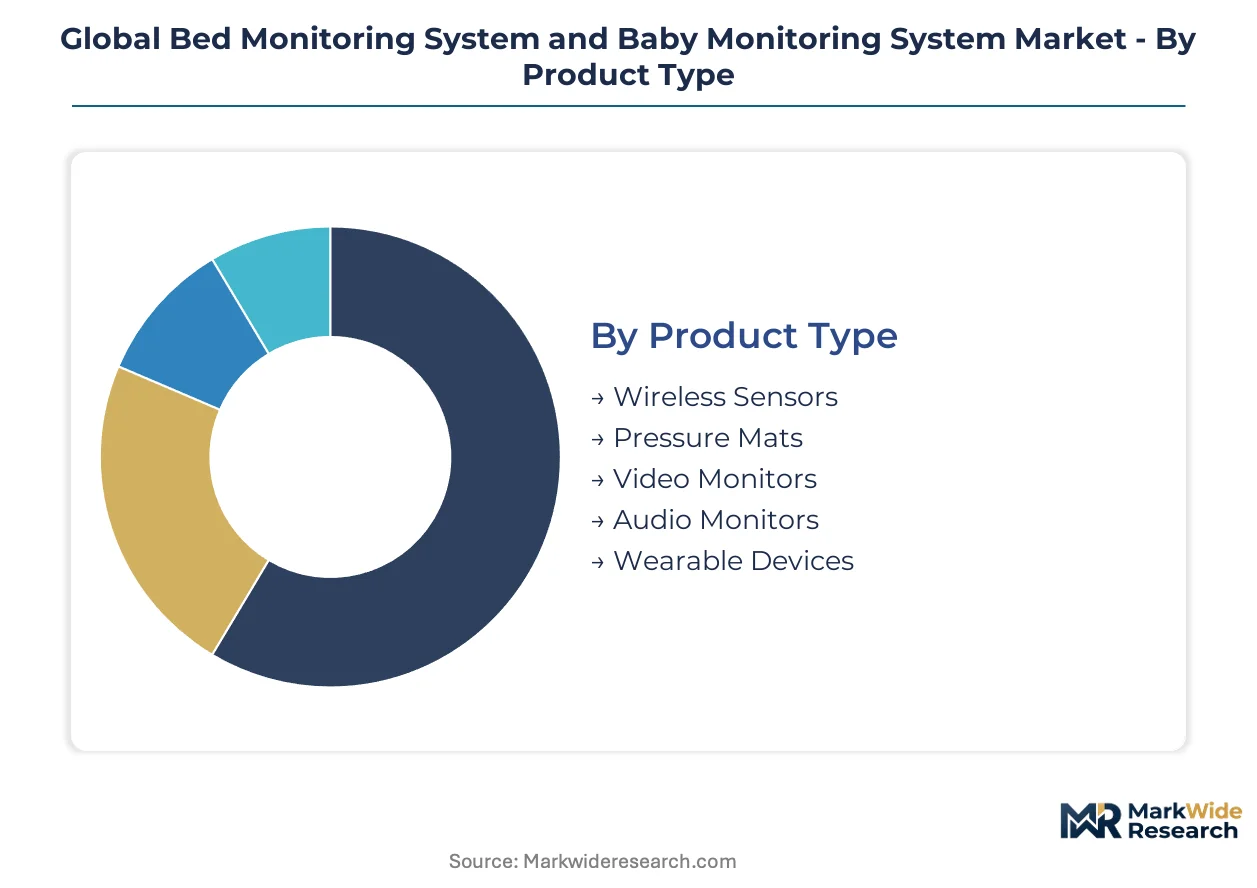
Product Type:
Wireless sensors face intensifying substitution pressure from integrated video-analytics platforms that bundle multiple detection functions in single hardware units.
- Wireless Sensors:Radar and pressure-mat arrays operating at 24-60 GHz transmit occupancy and micro-movement data via Wi-Fi or proprietary protocols to central monitoring stations. Hospital-at-home programs in the United States are consolidating procurement around these kits as Medicare reimbursement codes for remote patient monitoring expand coverage eligibility.
- Wearable Devices:Miniaturized MEMS accelerometers and optical heart-rate modules embedded in socks, patches, or garments deliver continuous biometric streams. Pediatric and geriatric home settings in Japan are absorbing these devices fastest as METI-backed telehealth initiatives subsidize deployment for aging-in-place populations.
- Pressure Mats:Capacitive or piezoelectric floor pads detect bed entry/exit events and prolonged occupancy without patient contact.
- Video Monitors:Camera-based systems with computer vision algorithms track infant sleep position and breathing patterns.
- Audio Monitors:Sound-activated transmission devices alerting caregivers to crying or distress vocalizations.
Wireless sensors retain volume leadership; wearable devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium radar configurations from commoditized infrared alternatives, with Bluetooth bridging mid-market positioning through smartphone ecosystem compatibility.
- Radar Sensors:Frequency-modulated continuous-wave systems at 24-60 GHz capture respiration and cardiac contraction through clothing and bedding. German assisted-living operators are standardizing on these arrays for fall-risk residents who remove wearables overnight.
- Infrared Sensors:Passive thermal detection of body heat and movement patterns dominates entry-level baby monitor pricing tiers.
- Ultrasonic Sensors:High-frequency acoustic ranging measures distance and motion with minimal power draw.
- Bluetooth:Low-energy protocols enable direct smartphone pairing for consumer-grade sleep analytics applications.
- RFID:Radio-frequency identification tags track patient location and bed assignment in acute-care workflows.
Radar sensors command the premium price band; Bluetooth-enabled modules are climbing fastest through consumer channel penetration.
Application:
Margin pools concentrate where software subscription layers stack atop hardware, particularly in predictive analytics for sleep and respiratory events.
- Vital Signs Monitoring:Continuous tracking of heart rate, respiration rate, and blood oxygen saturation generates the highest recurring revenue attachment. United States hospital-at-home networks are mandating these capabilities for reimbursed remote patient monitoring programs.
- Sleep Pattern Analysis:Computer vision and radar-derived metrics on sleep stages, position changes, and apnea events feed coaching subscriptions. Privacy-conscious European consumers are driving edge-AI deployment to minimize cloud data transmission.
- Fall Detection:Algorithmic interpretation of movement cessation or velocity anomalies triggers emergency alerts.
- Infant Movement Tracking:Breathing motion detection and rollover prevention for sudden infant death syndrome risk mitigation.
- Bed Occupancy Detection:Binary presence/absence signaling for wander management and pressure ulcer prevention protocols.
Vital signs monitoring anchors revenue concentration; sleep pattern analysis is expanding most quickly through software unbundling.
End User:
Customer type determines regulatory pathway complexity, with institutional buyers demanding FDA 510(k) or CE marking documentation that consumer channels bypass.
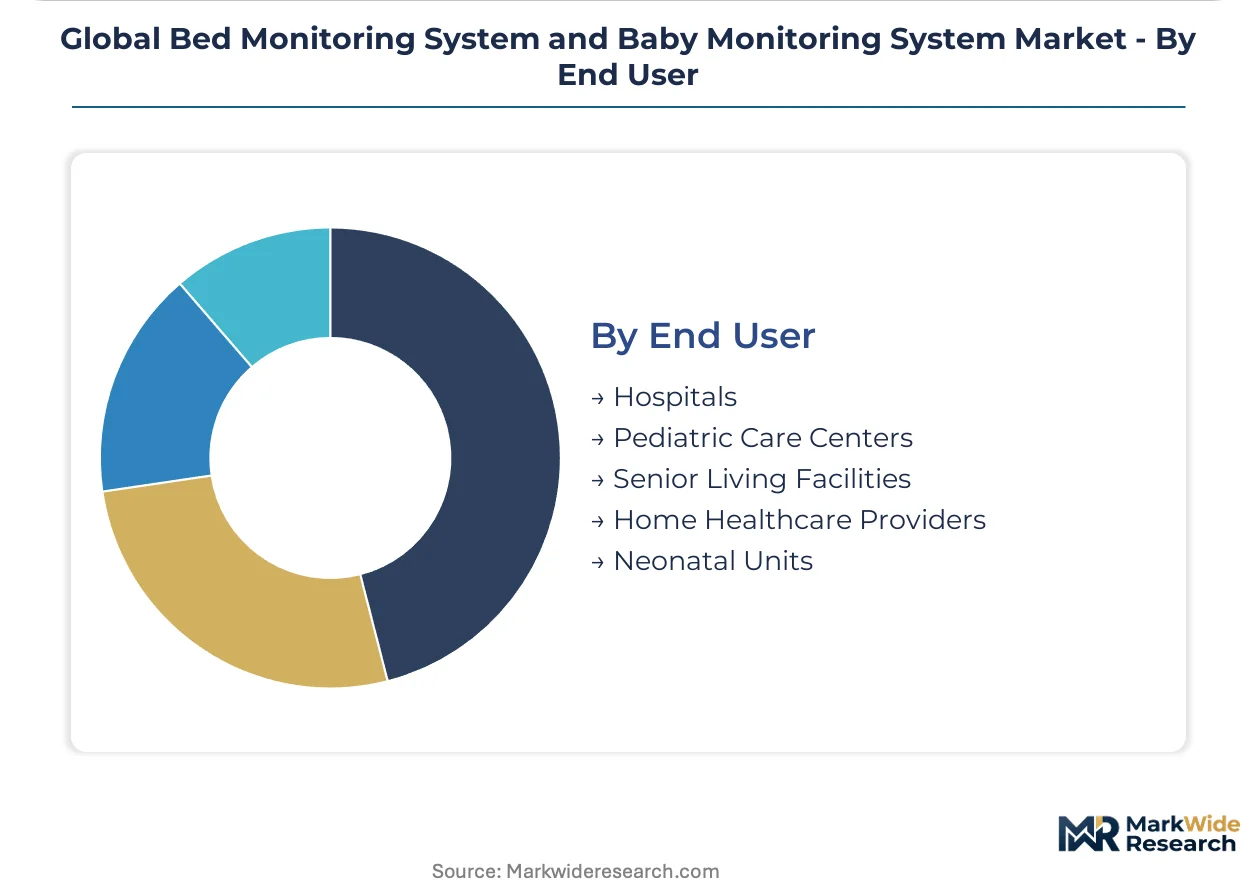
- Home Healthcare Providers:Distributed nursing agencies deploying sensor kits for hospital-at-home reimbursement programs require scalable fleet management and EHR interoperability. Medicare expansion in the United States is redirecting capital-equipment budgets toward these subscription-based deployments.
- Hospitals:Acute-care facilities maintain procurement of integrated monitoring infrastructure for step-down units and early discharge programs.
- Pediatric Care Centers:Outpatient clinics managing chronic pediatric conditions with remote surveillance protocols.
- Senior Living Facilities:Assisted-living and memory-care operators adopting non-contact monitoring for resident safety compliance.
- Neonatal Units:Neonatal intensive care departments requiring FDA-cleared devices for premature infant monitoring.
Home healthcare providers are capturing procurement volume growth; hospitals maintain the highest average contract value through bundled system sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth logistics corridor underwrites United States distribution for hospital-at-home sensor kits, while the Rhine-Main freight network positions Germany as Europe's primary entry point for radar-based monitoring arrays.
United States
Medicare reimbursement expansion for remote patient monitoring is redirecting procurement from acute-care facilities toward distributed home healthcare networks. FDA 510(k) software-as-medical-device pathways for AI-enabled infant monitors create defined regulatory on-ramps for predictive analytics vendors. The Boston-Cambridge medical device cluster concentrates algorithm development talent for fall-detection and sleep-apnea systems.
Germany
Assisted-living operators in Baden-Württemberg are standardizing on 24-60 GHz radar arrays for fall-risk residents who remove wearables overnight. EU MDR notified-body scrutiny under CE marking rules extends validation timelines for predictive analytics vendors targeting European health systems. The Munich-Stuttgart industrial corridor hosts precision sensor fabrication for pressure-mat and radar configurations.
Japan
METI-backed telehealth initiatives are driving non-contact vital sign monitoring into single-resident dwellings and assisted-living facilities for aging-in-place populations. PMDA consultation pathways for software-as-medical-device functionality align with global harmonization efforts. The Kanto region around Tokyo anchors domestic production of MEMS accelerometers for wearable pediatric and geriatric devices.
India
CDSCO regulatory harmonization efforts and private insurer remote-patient-monitoring experiments create first-mover positioning for wireless bed-monitoring kit vendors. Hospital-at-home pilot programs in Maharashtra and Karnataka are testing subscription-based deployment models. The Bengaluru-Hyderabad technology corridor concentrates software development for edge-AI sleep analytics platforms.
United Kingdom
NHS England hospital-at-home expansion is consolidating procurement around wireless sensor kits with EHR interoperability requirements. MHRA recognition of FDA 510(k) clearances accelerates market entry for US-origin AI-enabled monitoring devices. The Oxford-Cambridge health technology cluster drives clinical validation studies for predictive fall-detection algorithms.
Global Bed Monitoring System and Baby Monitoring System Market Competitive Landscape
Listed leaders compete with private specialists across regulatory sophistication and channel access. The vendor base fragments across institutional sales, direct-to-consumer distribution, and hybrid subscription-hardware models. Three archetypes dominate: entrenched medical device conglomerates with neonatal intensive care presence, computer vision specialists targeting premium consumer sleep analytics, and wearable biometric startups with pulse-oximetry differentiation. M&A activity concentrates on algorithm talent acquisition and CE marking capability expansion.
Among private monitoring specialists, Owlet Baby Care, Inc. and Nanit occupy positions at opposite ends of the infant monitoring spectrum, while Koninklijke Philips N.V. anchors the institutional tier through its entrenched presence in North American and European health systems. These three exemplify the channel bifurcation between direct-to-parent subscriptions and hospital procurement cycles.
| Leading Market Players |
|---|
| Owlet Baby Care, Inc. |
| Nanit |
| VTech Holdings Ltd |
| Motorola Mobility LLC |
| Koninklijke Philips N.V. |
| Tekscan, Inc. |
| WellSense Health Plan |
| XSENSOR Technology Corporation |
| Angelcare Monitors Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at Taiwanese MEMS foundries shapes component availability and establishes price floors for wearable pulse-oximetry modules. Scale advantages in radar sensor fabrication concentrate negotiating leverage among German and Japanese precision manufacturers, compressing margins for mid-tier pressure-mat assemblers sourcing from fragmented Asian component markets.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital-at-home deployments from direct-to-consumer subscriptions. Three-tier pricing stratifies across FDA-cleared medical devices, CE-marked wellness monitors, and unregulated entry-level audio units. Certification-grade differentiation commands substantial premiums as Medicare reimbursement codes require specific software validation documentation. Price erosion runs through commoditized infrared baby monitors facing substitution from smartphone-integrated camera applications. Home healthcare providers exhibit highest price sensitivity due to thin reimbursement margins, while neonatal intensive care units prioritize clinical evidence over procurement cost.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes strain working capital for European and North American distributors managing radar array inventory. Component sourcing draws from Taiwan for MEMS accelerometers, South Korea for optical heart-rate modules, and Germany for precision pressure sensors. Single-source vulnerability pervades miniaturized biometric chip fabrication, with geopolitical friction threatening just-in-time delivery schedules. Distribution runs through medical device GPOs for institutional buyers and direct-to-parent e-commerce platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home reimbursement expansion signals early-cycle penetration acceleration, with Medicare remote patient monitoring codes creating sustainable demand tailwinds for subscription-based monitoring services.
For Market Incumbents: Fortify software validation capabilities against tightening FDA 510(k) documentation requirements for AI-enabled infant monitors. Deepen backward integration into MEMS sensor fabrication to offset Taiwan supply concentration, while expanding clinical-affairs teams to navigate EU MDR Annex XIV evidence thresholds for fall-detection algorithms. For New Entrants and Emerging Players: Differentiate on edge-AI deployment architectures that minimize cloud dependency for privacy-sensitive European consumers. Target India's hospital-at-home pilot programs in Maharashtra and Karnataka, where CDSCO regulatory harmonization and private insurer experiments create first-mover positioning without entrenched incumbent presence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among computer vision specialists layering sleep-coaching subscriptions atop hardware deployments. Five-to-ten year viability favors vendors with demonstrated CE marking capability and established hospital GPO relationships. Watch FDA software-as-medical-device guidance evolution as inflection indicator for AI-powered monitor commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified-body scrutiny elevates quality-management investments for predictive analytics vendors. |
| Hospital System Partnership | Medicare reimbursement expansion redirects procurement toward distributed home healthcare networks. |
| Software Companion Development | Subscription unbundling from hardware extends customer lifetime value through analytics layering. |
| Reimbursement Strategy | Remote patient monitoring code alignment determines addressable market for hospital-at-home programs. |
| FDA Submission | 510(k) software documentation requirements constrain market entry timelines for AI-powered monitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital procurement committees, biomedical engineering directors, home healthcare agency administrators, and neonatal intensive care clinicians. Secondary validation incorporated FDA 510(k) clearance databases, EMA notified-body documentation, CMS Medicare reimbursement filings, and hospital GPO contract repositories. Bottom-up sensor shipment estimates triangulated against top-down healthcare IT expenditure projections.
Across the analysis window, forecasts model product type substitution dynamics, connectivity protocol adoption curves, and end-user procurement pattern shifts. Segmentation dimensions span sensor modality, application software layering, and care setting regulatory pathway. CAGRs derive from installed base expansion rates and recurring revenue attachment coefficients specific to remote patient monitoring reimbursement evolution.
Decision-makers should treat outputs as directional under stable Medicare remote patient monitoring reimbursement and unaltered FDA software validation frameworks; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
North America Remote Patient Monitoring Systems Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Patient Monitoring Systems Market
Patient Monitoring
Japan Patient Care Monitoring Equipment Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Sleep Tracking Devices Market