
 Smart Pills Technology Market | 2026-2036
Smart Pills Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pills Technology Market Intelligence
Revenue from recurring data analytics and patient monitoring services is tilting the profit pool away from single-use capsule hardware. Medtronic leverages its extensive hospital network and clinical trial infrastructure to drive adoption in therapeutic monitoring. Olympus Corporation specializes in advanced imaging capsules, competing on diagnostic accuracy, while CapsoVision focuses on solutions that eliminate the need for data recorder equipment.
Smart pills technology encompasses ingestible electronic devices designed for gastrointestinal diagnostics and monitoring. These capsules integrate miniature sensors, cameras, and low-power wireless transmitters to capture and send data from within the digestive tract. While smart capsules for diagnostic applications currently lead the market, therapeutic monitoring represents the fastest-growing application area. Demand from hospitals remains the largest end-user segment, though home care settings are gaining traction.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) define the primary pathways for market approval. These bodies require extensive clinical validation of device safety and diagnostic efficacy. The EU's Medical Device Regulation (MDR) further imposes stringent post-market surveillance on manufacturers. Success for market participants hinges on navigating these complex approval processes while ensuring patient data security under regulations like GDPR.
Market Dynamics
The smart pills technology market is being reshaped by the fundamental shift from single-use diagnostic hardware toward recurring revenue from data analytics and patient monitoring services. This transition prioritizes software platforms and data interpretation over the physical capsule, altering profit pools and competitive strategies.
Growth Catalysts
- Chronic Disease Prevalence:The rising incidence of gastrointestinal disorders, such as Crohn's disease and irritable bowel syndrome, creates sustained demand for non-invasive monitoring tools, particularly in therapeutic monitoring applications.
- Technological Miniaturization:Advances in sensor technology, low-power wireless transmission, and battery life enable the development of more sophisticated capsules with enhanced imaging and sensing capabilities for improved diagnostic accuracy.
- Regulatory Support:Favorable regulatory pathways from bodies like the US FDA and clear standards for CE marking under the EU's MDR in key markets like the United States and Germany reduce barriers to entry for new devices.
Market Restraints
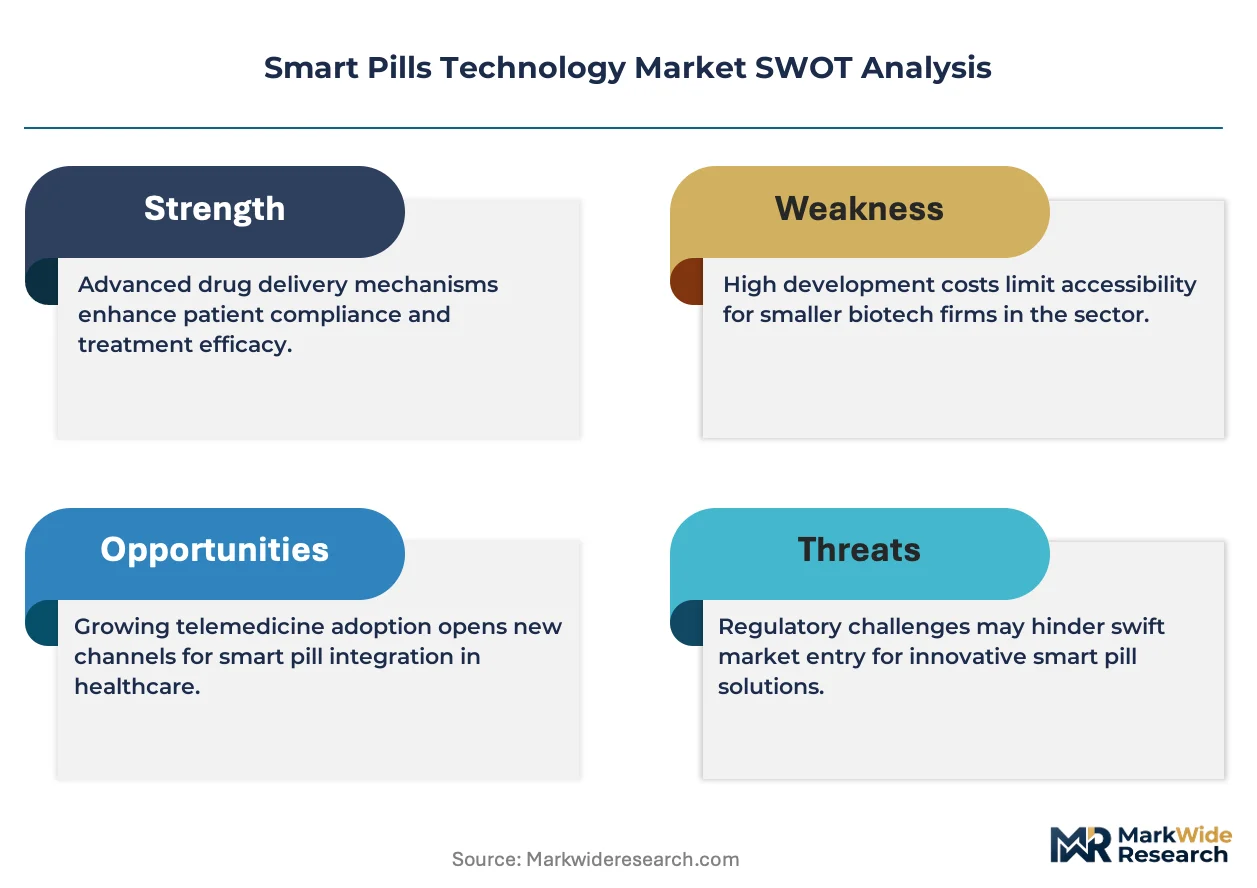
- High Procedure Costs:The significant cost associated with smart pill procedures and limited reimbursement coverage in many healthcare systems restrict patient access and slow adoption rates, especially outside of well-funded hospitals.
- Data Security Concerns:The transmission and storage of sensitive patient health data raise significant privacy concerns, requiring strict adherence to regulations like HIPAA in the US and GDPR in Europe, which adds complexity and cost.
- Technical Limitations:Current-generation capsules lack propulsion systems, leading to passive movement through the GI tract that can result in missed lesions or incomplete examinations, limiting diagnostic reliability.
Strategic Opportunities
- Therapeutic Delivery Systems:The development of smart pills capable of precise, localized drug delivery directly to affected tissues in the GI tract represents a significant opportunity to move beyond diagnostics into active treatment.
- AI-Powered Diagnostics:Integrating artificial intelligence and machine learning algorithms to automate the analysis of vast image and sensor data can dramatically reduce reading times for clinicians and improve diagnostic consistency.
- Expansion in Asian Markets:Technologically advanced healthcare systems in countries like Japan and South Korea, combined with aging populations, present underpenetrated markets for advanced gastrointestinal diagnostic technologies.
Industry Challenges
- EHR System Integration:A primary operational hurdle is the lack of seamless interoperability between the data platforms of smart pill systems and the electronic health record (EHR) systems used by hospitals, creating data silos.
- Complex Clinical Validation:Manufacturers face long and costly clinical trial processes to demonstrate safety and efficacy for regulatory approval from bodies like the FDA and to comply with the EU's stringent MDR requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pills Technology Market |
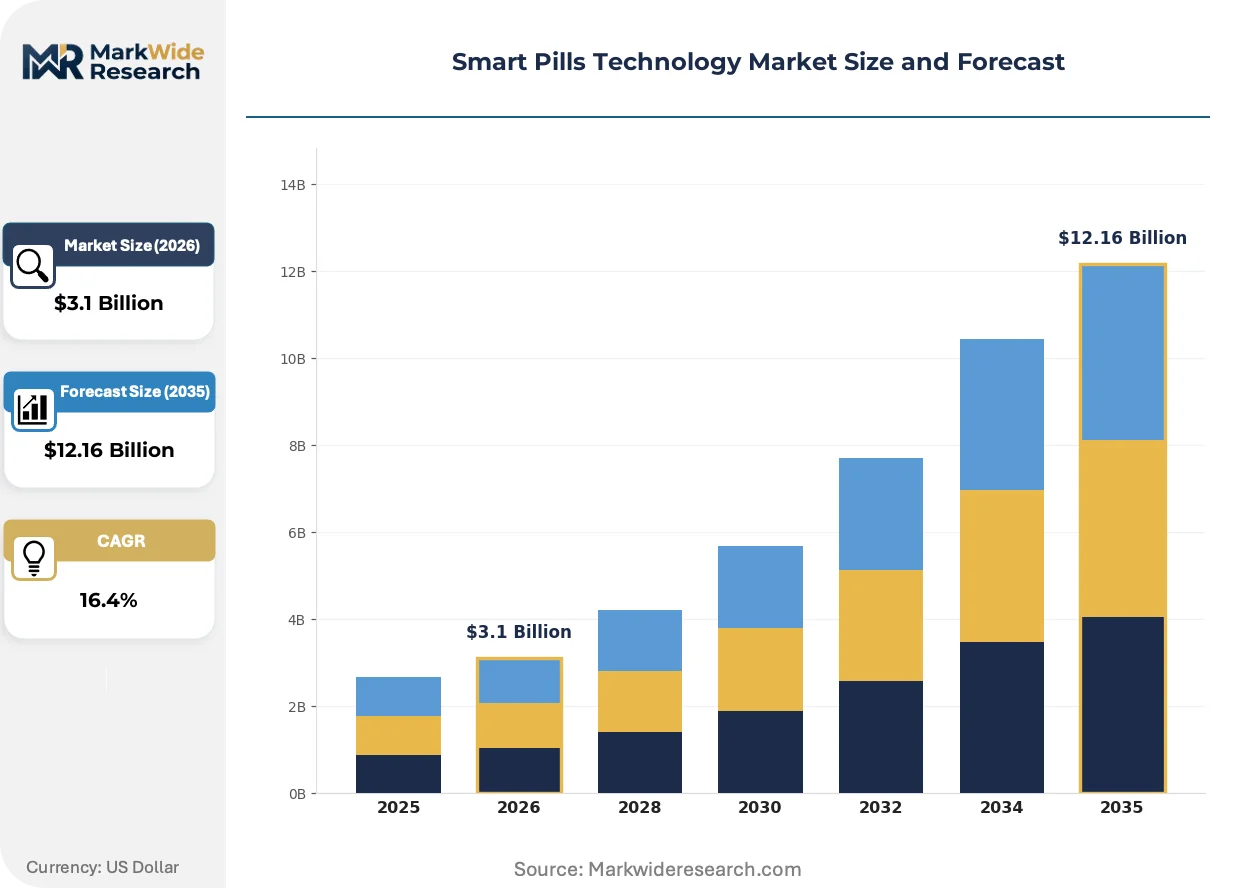
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Oral Route, Injectable, Transdermal, Inhalable Device Type: Wearable Sensors, Implantable Devices, Smart Capsules, Diagnostic Tools Application Area: Chronic Disease Management, Diagnostics, Therapeutic Monitoring, Patient Adherence End User: Hospitals, Clinics, Research Institutions, Home Care |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, IntroMedic, AnX Robotics, etectRx, Check-Cap, JINSHAN Science & Technology, BodyCap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pills Technology Market Strategic Shifts & Innovations
The market's evolution is defined by a move toward integrated systems that combine advanced sensing with powerful analytical software. This creates a new value proposition centered on comprehensive GI tract monitoring and actionable clinical insights rather than just image capture.
Multi-sensor fusion technology integrates high-resolution cameras with pH, temperature, and pressure sensors within a single ingestible capsule. Gastroenterology departments in large hospitals are the primary adopters of these advanced diagnostic tools. This integration of multiple data streams into a single device is collapsing the need for separate, sequential diagnostic procedures, enabling a more efficient and comprehensive patient workup.
The European Union's Medical Device Regulation (MDR) imposes stringent requirements for post-market surveillance on all medical devices. This regulation is forcing manufacturers to establish robust systems for continuously collecting and analyzing real-world performance and safety data throughout a product's lifecycle. This compliance burden most heavily affects smaller innovators and startups, which must now dedicate significant resources to ongoing regulatory activities.
A notable behavioral shift involves healthcare providers moving away from one-time hardware purchases toward subscription-based models for data analysis services. This disrupts the traditional sales channel focused on capital equipment for hospitals, enabling home care providers and specialized clinics to adopt the technology. This trend is particularly evident in the United States, where outcome-based reimbursement models encourage continuous patient monitoring.
Smart Pills Technology Market Segmentation
The smart pills technology market segments across various critical dimensions, reflecting diverse product functionalities and end-user requirements. Understanding these distinctions is crucial for market participants to tailor product development and strategic market entry. Each segment addresses specific clinical needs within the broader healthcare ecosystem.
Delivery Mode:
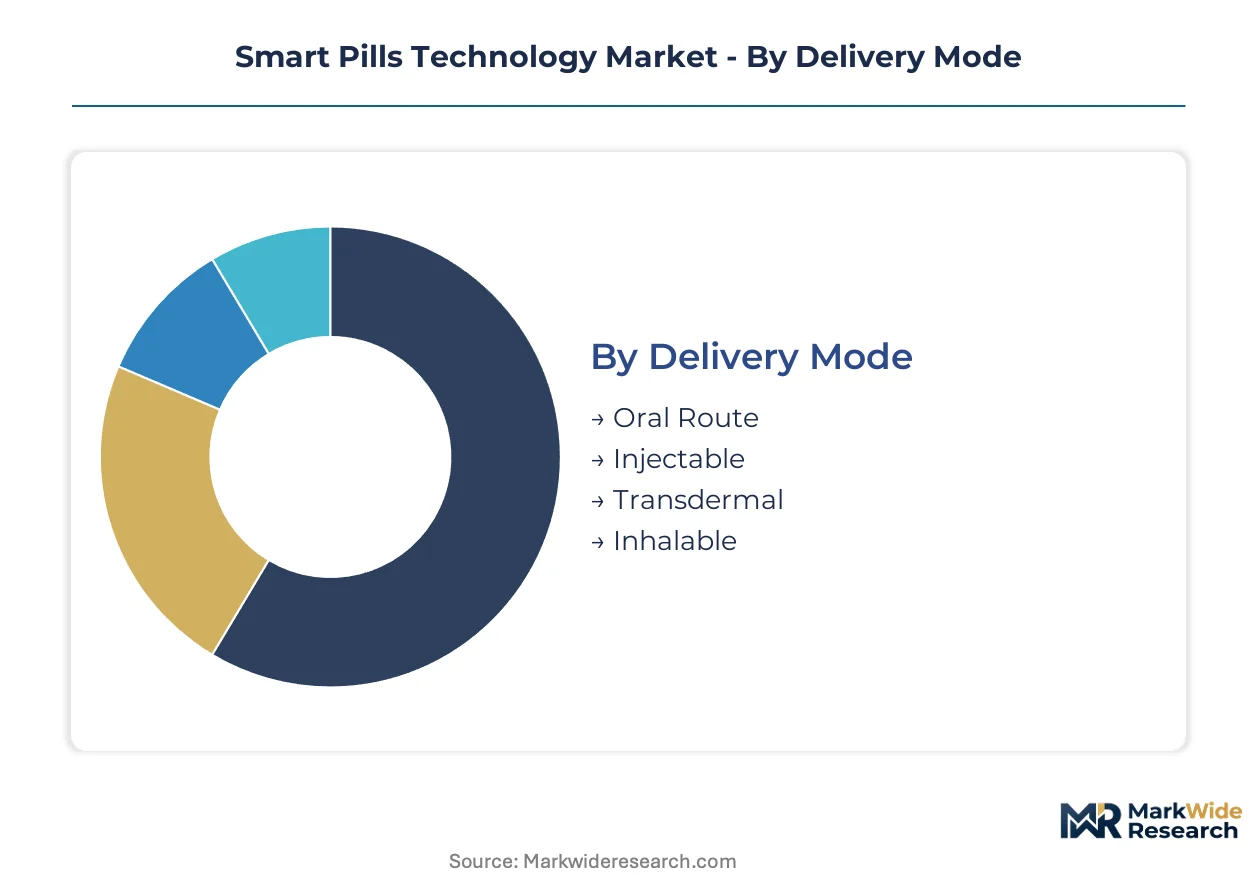
Delivery modes for smart pills technology exhibit varying adoption cycles, with some methods already mature and others representing future growth. Oral administration offers the fastest patient turnover due to its non-invasive nature and ease of use. More complex delivery systems, such as injectables, typically involve longer development and adoption timelines.
- Oral Route:These ingestible devices navigate the gastrointestinal tract, capturing diagnostic data or delivering therapeutics without surgical intervention. Demand concentrates in developed healthcare markets like the United States due to high chronic disease prevalence and patient preference for non-invasive procedures.
- Injectable:Smart injectable systems deliver active pharmaceutical ingredients with enhanced precision or monitoring capabilities directly into the body. This mode is gaining traction in therapeutic monitoring applications, particularly for conditions requiring controlled release or real-time physiological feedback, especially in Germany.
- Transdermal:Transdermal smart patches or films facilitate drug delivery or physiological monitoring through the skin.
- Inhalable:Inhalable smart devices target respiratory conditions, offering localized drug delivery or diagnostic sensing within the lungs.
Oral Route dominates the installed base for smart pills technology. Injectable is where expansion concentrates.
Device Type:
Device types within this market serve distinct application needs, from continuous external monitoring to internal diagnostic imaging. Each device class addresses specific clinical requirements, influencing its design complexity and integration into existing healthcare workflows. The functional role of each device type defines its market trajectory.
- Smart Capsules:These ingestible electronic devices integrate miniature cameras, sensors, and wireless transmitters for gastrointestinal diagnostics and monitoring. Their non-invasive nature drives demand from hospitals for initial screenings and follow-up examinations in countries with advanced diagnostic infrastructure, such as Japan.
- Diagnostic Tools:This broad category encompasses various devices used for identifying and characterizing diseases, including imaging systems and laboratory analysis equipment. Demand for these tools is high across all healthcare settings, particularly in research institutions focused on early disease detection and personalized medicine.
- Wearable Sensors:External devices monitor physiological parameters like heart rate, activity, and sleep patterns, often for patient adherence.
- Implantable Devices:Surgically placed devices provide long-term monitoring or therapeutic intervention, such as pacemakers or continuous glucose monitors.
The innovation focus within device types is heavily weighted towards enhancing diagnostic accuracy, driven by increasing clinical validation requirements.
Application Area:
Application areas exhibit varying volume profiles, reflecting the prevalence of conditions and the maturity of technological solutions. Diagnostic applications currently command the highest volume of procedures, driven by the widespread need for internal imaging. Therapeutic monitoring represents a rapidly expanding segment with increasing patient engagements.
- Diagnostics:This application involves using smart pills to visualize and assess the gastrointestinal tract for conditions like Crohn's disease or polyps. Hospitals drive significant demand for diagnostic smart capsules, especially in regions with high healthcare expenditure like the United States.
- Therapeutic Monitoring:Smart pills in this area track the effects of medications or disease progression, offering real-time data for treatment adjustments. This segment is experiencing the steepest expansion trajectory, particularly in chronic disease management where continuous oversight improves patient outcomes.
- Chronic Disease Management:Smart pills assist in long-term oversight of conditions such as inflammatory bowel disease, providing continuous data streams.
- Patient Adherence:These applications ensure patients take prescribed medications correctly and on schedule, improving treatment efficacy and reducing readmissions.
The market is experiencing a significant shift towards therapeutic monitoring, driven by the need for personalized medicine and continuous patient data.
End User:
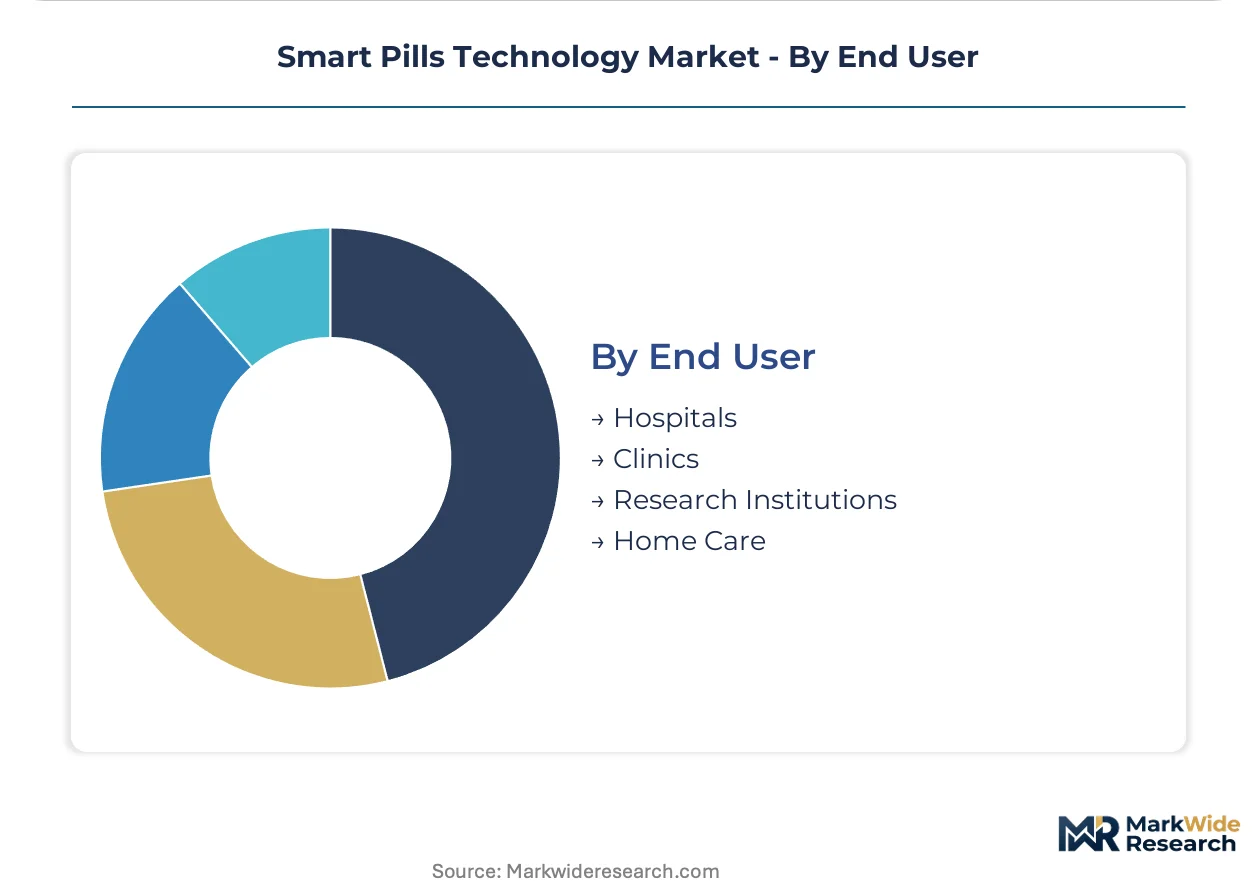
End-user segments are differentiated by their operational scales, patient populations, and integration capabilities for smart pill technologies. Hospitals remain the largest customer type, requiring robust systems for high-volume diagnostic procedures. Home care settings represent a rapidly expanding user base, emphasizing ease of use and remote data transmission.
- Hospitals:These large-scale medical facilities are the primary adopters of smart pill technology for both diagnostic and therapeutic monitoring applications. Their extensive infrastructure and high patient throughput drive substantial demand for advanced imaging capsules and data analytics services, particularly in Europe.
- Home Care:This segment involves patients using smart pills in their residences, with data transmitted remotely to healthcare providers. The convenience and reduced cost associated with home-based monitoring are accelerating adoption, especially for chronic disease management in the United States.
- Clinics:Smaller medical practices and specialized gastroenterology clinics utilize smart pills for targeted diagnostic procedures and patient follow-ups.
- Research Institutions:Academic and private research bodies employ smart pills for clinical trials, technology validation, and developing new applications.
Growth in this segment is primarily influenced by evolving reimbursement models and the increasing emphasis on decentralized patient care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for smart pills technology differs significantly across major global markets, with some regions prioritizing diagnostic hardware while others focus on recurring data analytics services. Developed healthcare markets like the United States and Germany exhibit strong demand for advanced solutions due to higher healthcare expenditure and technology adoption. This regional disparity influences product development and strategic market entry for participants.
United States
Demand for smart pills technology in the United States is driven by the high prevalence of chronic gastrointestinal disorders and the increasing adoption of home care settings. Regulatory approvals from the US FDA are essential for market entry, ensuring device safety and diagnostic efficacy. Major medical technology hubs like Boston and the San Francisco Bay Area continue to foster innovation in ingestible sensors and remote patient monitoring platforms.
Germany
Germany represents a significant market for smart pills, particularly for therapeutic monitoring applications and advanced diagnostic imaging. Adherence to EU CE marking standards and the stringent Medical Device Regulation (MDR) defines the regulatory landscape for manufacturers. The Bavaria and North Rhine-Westphalia regions are key centers for medical device manufacturing and research, attracting investment in smart pill development.
Japan
Japan exhibits strong demand for smart capsules, leveraging its advanced diagnostic infrastructure and an aging population requiring sophisticated non-invasive tools. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing clinical validation and patient safety. The Kanto region, including Tokyo, serves as a nexus for medical technology research and the adoption of multi-sensor fusion technologies in gastroenterology departments.
South Korea
South Korea's technologically advanced healthcare system and an aging demographic present a growing market for smart pills, particularly in underpenetrated diagnostic and therapeutic areas. The Ministry of Food and Drug Safety (MFDS) regulates medical devices, requiring rigorous clinical data for market authorization. The Seoul Capital Area is a prominent hub for digital health innovation, integrating AI-powered diagnostics with smart pill platforms.
France
French hospitals are primary adopters of smart pill technology for both diagnostic procedures and therapeutic monitoring, driven by robust healthcare spending. Compliance with the EU's Medical Device Regulation (MDR) and data protection under GDPR is critical for market access and post-market surveillance. The Île-de-France region, centered around Paris, supports a vibrant ecosystem of medical technology companies and research institutions focused on gastrointestinal health.
Smart Pills Technology Market Key Industry Players
Capability concentration sits with one tier of the smart pills technology market, focusing on advanced hardware and sensor miniaturization, while scale advantage sits with another tier, emphasizing data analytics and service delivery. The market exhibits a tiered structure, with established medical device giants, specialized imaging capsule manufacturers, and emerging software-centric firms. Strategic partnerships for data integration and targeted mergers and acquisitions for technology acquisition are common competitive moves.
Specialists in advanced imaging and data capture, such as Olympus Corporation, represent a segment focused on diagnostic accuracy and high-resolution visualization. Medtronic occupies a position as an integrated solutions provider, leveraging its extensive hospital network and clinical trial infrastructure for therapeutic monitoring. CapsoVision exemplifies innovators focused on simplifying workflows by eliminating the need for external data recorder equipment, enhancing user convenience and accessibility.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision |
| IntroMedic |
| AnX Robotics |
| etectRx |
| Check-Cap |
| JINSHAN Science & Technology |
| BodyCap |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, particularly stringent EU MDR and US FDA approval processes, directly influence pricing tier spreads and the strategic configuration of the smart pills technology supply chain. These complex pathways elevate market entry costs and favor established players with proven compliance capabilities.
Pricing Analysis
Subscription-based models for data analytics services increasingly define pricing in the smart pills technology market, shifting from traditional per-unit hardware sales. Price differentiation stems from diagnostic accuracy, particularly for advanced imaging capsules, and the extent of bundled data interpretation services. Pricing pressure arises from limited reimbursement coverage in many healthcare systems, influencing adoption rates in cost-sensitive segments. Home care settings exhibit higher price sensitivity compared to large, well-funded hospitals that prioritize advanced diagnostic capabilities.
Supply Chain Analysis
Export control regimes, particularly those governing advanced sensor and imaging technologies, influence the sourcing of critical components for smart pills. The supply chain for smart pills technology concentrates manufacturing of specialized components in countries like Japan, South Korea, and Germany. Key dependencies include miniaturized cameras, micro-sensors, and low-power wireless transmission modules, creating single-source vulnerabilities. Distribution runs primarily through direct sales channels to hospitals and partnerships with group purchasing organizations, supported by remote data infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart pills technology market presents a defensive-moat story, primarily due to significant regulatory entrenchment. Extensive clinical validation requirements from bodies like the US FDA and EMA create substantial barriers to entry, protecting established market positions.
For Market Incumbents: Insulate core diagnostic hardware revenues by deepening integration with hospital EHR systems. This mitigates the threat from software-centric entrants by creating seamless clinical workflows and reducing data silos. Pursue strategic acquisitions of AI-powered diagnostic software firms to enhance data interpretation capabilities, leveraging existing clinical trial infrastructure. Investment in advanced manufacturing processes in key regions like Germany can also secure supply chains against component scarcity.
For New Entrants and Emerging Players: Pursue niche therapeutic monitoring applications with high unmet needs, such as localized drug delivery for specific GI conditions. The home care segment in the United States represents a penetrable market due to evolving reimbursement models and demand for continuous patient data. Develop AI-powered diagnostic platforms that significantly reduce clinician reading times, offering a compelling value proposition. A go-to-market strategy focused on direct engagement with specialized clinics and gastroenterology practices can bypass established hospital networks.
For Investors and Strategic Acquirers: The EU's Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust post-market surveillance and clinical validation capabilities. This market offers long-term viability, driven by chronic disease prevalence and technological advancements. Target acquisition archetypes include specialized firms with proprietary sensor miniaturization expertise or proven AI algorithms for data analysis. The signal to watch is the pace of reimbursement expansion for home-based therapeutic monitoring solutions in developed markets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Acceleration | Expedites market access for novel diagnostic capsules in the United States. |
| Hospital System Partnerships | Secures high-volume adoption of smart pill technology within Europe's largest healthcare networks. |
| Software Companion Development | Enhances diagnostic value by integrating AI-powered analytics with existing hardware platforms. |
| Reimbursement Strategy Optimization | Expands patient access and accelerates adoption in cost-sensitive home care settings. |
| Multi-sensor Fusion Integration | Improves diagnostic accuracy and reduces procedure complexity for gastroenterology departments. |
Research Approach
Initial hypotheses were tested against primary input from clinicians, hospital procurement managers, regulatory affairs specialists, and medical device engineers, then refined through iterative processes. This study combined extensive primary interviews with robust secondary validation from sources including US FDA device approvals, EMA clinical trial data, and industry association reports. Bottom-up data aggregation and top-down market sizing approaches ensured comprehensive coverage. Data triangulation across these diverse inputs strengthened the findings.
Demand-supply balance formed the core of the analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included delivery mode, device type, application area, end-user, and regional regulatory compliance frameworks. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected technological adoption curves. Key industry-specific forecast inputs included chronic disease prevalence rates and healthcare expenditure growth in developed markets.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure or regulatory policy would shift the trajectory of smart pills technology adoption. Forecasts reflect prevailing assumptions regarding technological advancements and patient acceptance. Material shifts in reimbursement policies or major clinical trial outcomes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laser Resurfacing Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Physiotherapy Laser Wrist Watch Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Endodontic Files Market