
 Neurovascular Microcatheter Market | 2026-2036
Neurovascular Microcatheter Market Size, Share, and Industry Trends Forecast 2026-2036
Neurovascular Microcatheter Market Insights
Procedure-specific software licensing for electromagnetic navigation is repositioning how catheter systems generate recurring revenue beyond hardware sales. Medtronic leverages integrated imaging-to-device workflows across its neurovascular portfolio. Stryker Corporation anchors North American distribution through dedicated stroke care specialist teams. Penumbra, Inc. differentiates with proprietary aspiration catheter technology paired with physician training ecosystems.
A neurovascular microcatheter is a small-diameter, flexible catheter typically constructed from braided stainless steel or nitinol hypotubes with polymer jacketing, designed to navigate cerebral vasculature for therapeutic delivery or diagnostic access. The device achieves distal trackability through graduated stiffness profiles and hydrophilic coatings that reduce frictional resistance against vessel walls. Coiling catheters capture substantial margin pools due to their dominance in intracranial aneurysm embolization procedures requiring precise coil deployment control. Electromagnetic navigation represents the fastest-expanding technology segment as real-time three-dimensional catheter tip tracking reduces fluoroscopy exposure and contrast dye volumes during complex interventions.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for neurovascular device manufacturers seeking market access. ISO 13485 quality management systems and FDA 21 CFR Part 820 regulations govern manufacturing consistency for catheter components that contact blood and neural tissue. The Japanese PMDA's sakigake designation accelerates review for innovative stroke devices, creating competitive pressure for simultaneous multi-regional regulatory filings. Stakeholders must monitor how evolving FDA guidance on computational modeling for catheter performance validation reshapes preclinical submission strategies.
Market Dynamics
Electromagnetic navigation systems are compressing fluoroscopy exposure limits while expanding reimbursable procedure volumes across stroke center networks, fundamentally altering capital allocation priorities for neurointerventional suites.
Growth Catalysts
- Japan's sakigake designation:Accelerated PMDA review timelines compress competitive entry windows for novel catheter technologies. Stroke device innovators prioritize simultaneous Japanese filings to capture early-mover reimbursement advantages.
- Metropolitan hospital clustering:Comprehensive stroke center certification in the United States concentrates demand within urban corridors. Capital investment in neurointerventional suites follows population density and emergency medical services catchment optimization.
- Hydrophilic polymer coatings:Friction-reduction surface treatments enable distal navigation through tortuous cerebrovascular anatomy. Trackability improvements expand treatable patient anatomies and reduce procedure abandonment rates.
Market Restraints
- Nitinol hypotube supply concentration:Superelastic alloy sourcing depends on limited specialty wire drawing capacity. Geopolitical friction affecting raw nickel and titanium supply chains elevates input cost volatility for catheter manufacturers.
- EU MDR clinical evidence requirements:Conformity assessment timelines for legacy devices extend market access delays. Small and mid-sized manufacturers face disproportionate burden in generating post-market clinical follow-up data.
- Fluoroscopy dose accumulation limits:Occupational exposure regulations constrain procedure volumes per operator. Staffing models require rotation protocols that reduce suite utilization efficiency.
Strategic Opportunities
- Underpenetrated stroke belt regions:Southeastern United States counties exhibit aneurysm treatment rates below national benchmarks. Mobile stroke unit deployment creates distributed access points for catheter-based intervention.
- Software-as-a-service navigation licensing:Electromagnetic tracking platforms generate recurring revenue streams beyond hardware replacement cycles. Procedure-specific modules enable tiered functionality pricing across hospital capital tiers.
- AI-augmented imaging integration:Machine learning algorithms for hemorrhage detection converge with catheter navigation workflows. Real-time image guidance reduces contrast dye volumes and operator cognitive load.
Industry Challenges
- Neurointerventionalist training pipeline:Fellowship program graduation rates lag behind stroke center expansion velocity. Simulator-based credentialing requirements extend time-to-autonomy for new operators.
- FDA 21 CFR Part 820 quality system remediation:Warning letter citations for catheter manufacturers elevate compliance expenditure. Documentation rigor for design history files consumes engineering resources.
- Legacy imaging system interoperability:Electromagnetic navigation platforms require proprietary interface protocols. Hospital capital planning must coordinate multi-vendor integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurovascular Microcatheter Market |
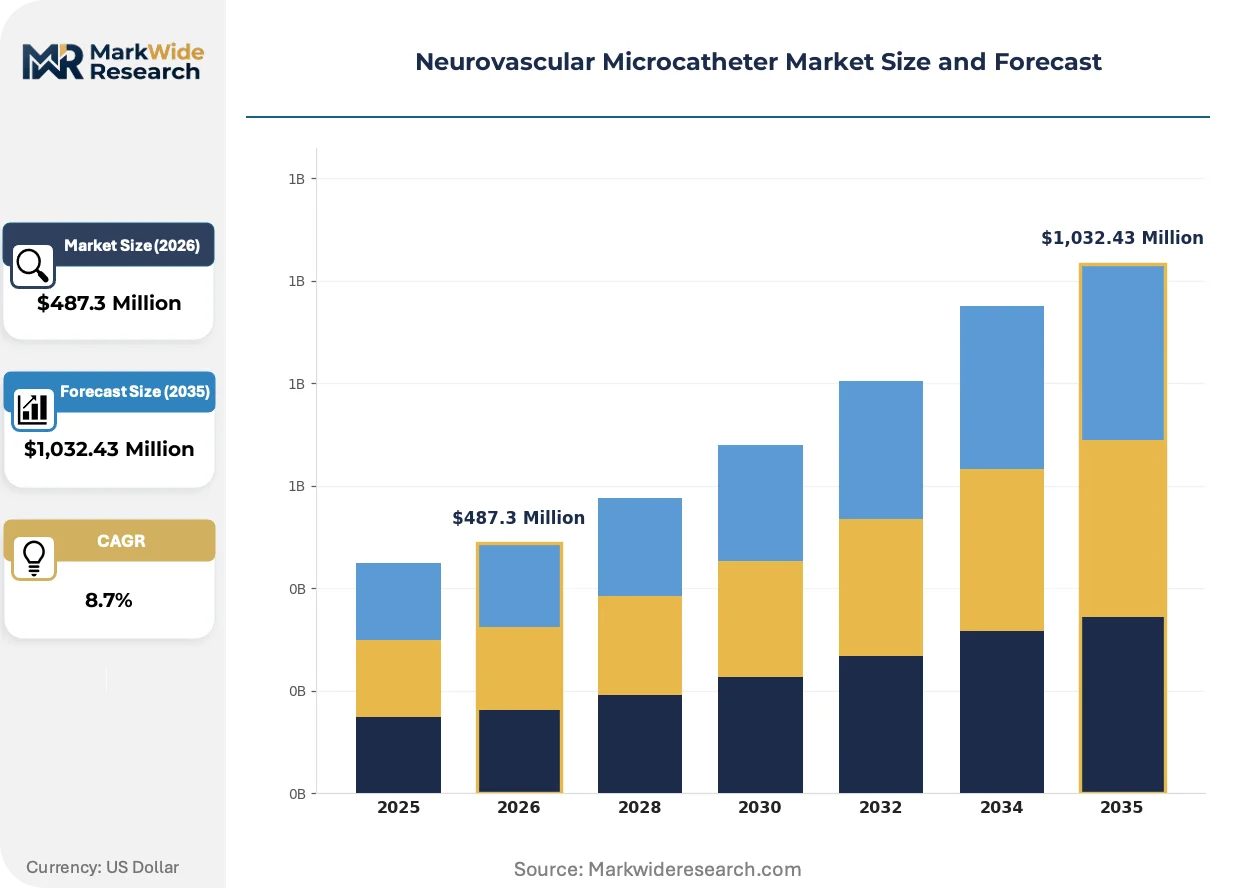
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Coiling Catheters, Stenting Catheters, Microcatheter Kits End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Laboratories Technology: Fluoroscopic Guidance, Magnetic Resonance Imaging, Optical Coherence Tomography, Electromagnetic Navigation Application: Intracranial Aneurysm, Arteriovenous Malformation, Ischemic Stroke, Intracranial Stenting |
| Companies Covered | Medtronic, Stryker Corporation, Johnson & Johnson Services, Inc., Penumbra, Inc., Terumo Corporation, Integer Holdings Corporation, MicroVention, Inc., ASAHI INTECC CO., LTD., Acandis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurovascular Microcatheter Market Trends and Innovations
Real-time three-dimensional catheter tip tracking is displacing two-dimensional fluoroscopy dependency while enabling procedure standardization across operator experience levels. This technological pivot reshapes training economics and capital deployment patterns simultaneously.
Robotic catheter steering mechanisms are automating distal navigation through cerebrovascular tortuosity. Academic medical centers in Germany and Japan deploy teleoperation capabilities for remote expert intervention. This automation compresses the learning curve for complex aneurysm approaches while enabling hub-and-spoke care models.
MDR Article 120 transition timelines are forcing portfolio rationalization among European catheter manufacturers. Legacy device registrations face mandatory clinical data generation or market withdrawal. Small-volume indications disproportionately attract discontinuation decisions, consolidating available treatment options.
Comprehensive stroke center certification criteria now mandate 24/7 neurointerventional coverage. Hospital systems consolidate elective case scheduling to justify fixed cost coverage. United States metropolitan markets exhibit preference concentration toward dual-trained vascular-neuro specialists.
Neurovascular Microcatheter Market Segmentation
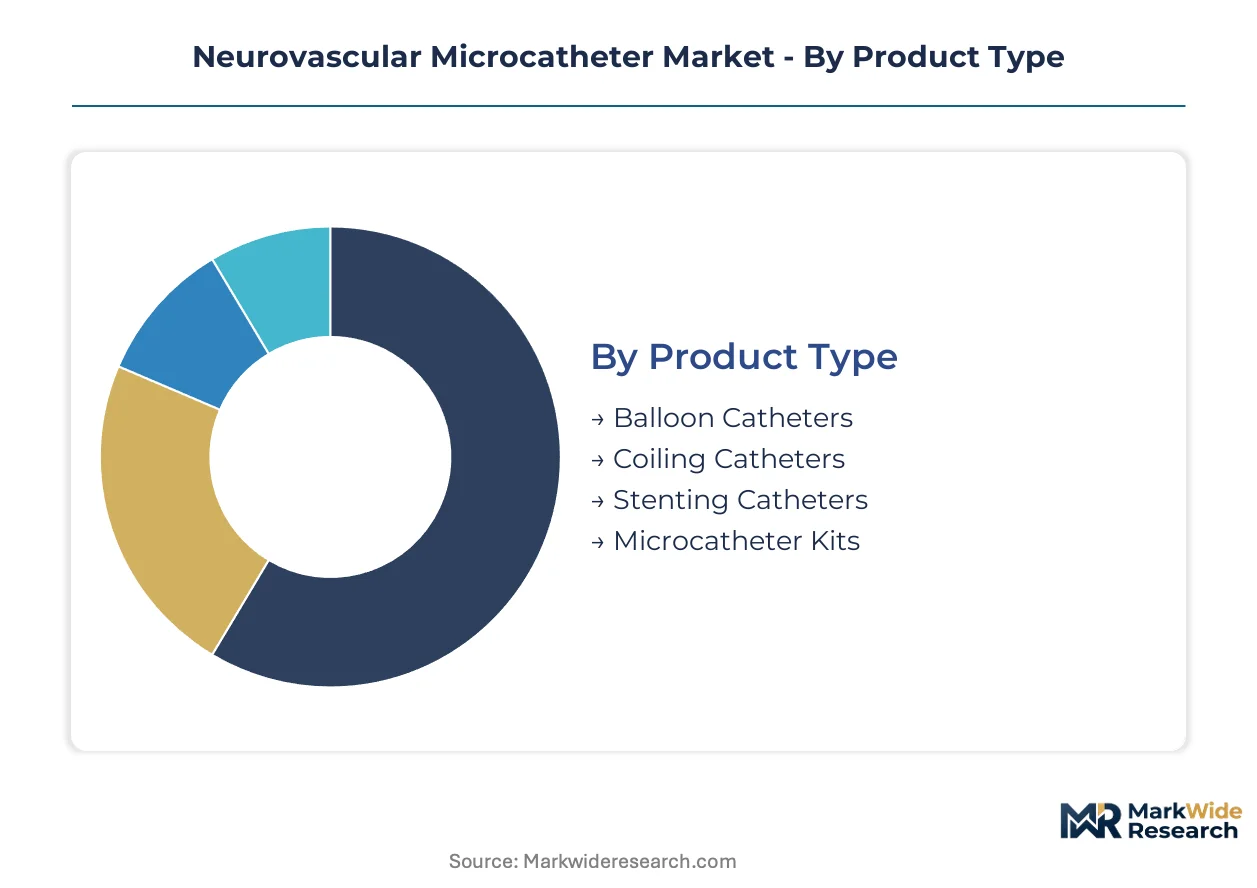
Neurovascular microcatheter purchasing decisions hinge on procedure-specific performance requirements, with upgrade cycles driven by navigation technology obsolescence and coating durability limits. Hospital procurement committees evaluate total cost of ownership across catheter lifespan, reprocessing protocols, and compatibility with installed imaging infrastructure.
Product Type:
Replacement cycles vary dramatically by catheter construction complexity, with coated delivery systems requiring more frequent refresh than bare metal platforms due to surface degradation in sterilization.
- Balloon Catheters:Dual-lumen nitinol hypotube construction enables temporary flow arrest during aneurysm coiling. Demand clusters in German stroke centers performing balloon-assisted remodeling procedures, constrained by PMDA sterilization validation requirements for reusable components.
- Coiling Catheters:Braided stainless steel shafts with distal flexibility zones achieve precise coil deployment control in tortuous middle cerebral artery bifurcations. Japanese comprehensive stroke centers generate concentrated volume for complex wide-neck aneurysm cases requiring microcatheter stability.
- Stenting Catheters:High-pushability designs navigate across intracranial stenoses for self-expanding stent delivery.
- Microcatheter Kits:Pre-packaged configurations reduce operative setup time in high-throughput United States metropolitan hospitals.
Coiling catheters sit at the top of the volume ranking, with balloon catheters climbing the fastest.
End User:
Capital intensity and case volume thresholds determine site-level purchasing authority, with institutional procurement dominating high-unit categories.
- Hospitals:Comprehensive stroke center certification mandates 24/7 neurointerventional coverage in United States urban corridors. Academic medical centers in Germany and Japan anchor technology adoption curves for electromagnetic navigation platforms.
- Specialty Clinics:Focused cerebrovascular practices in metropolitan Japan achieve procedure volumes rivaling hospital-based programs.
- Ambulatory Surgical Centers:Limited to diagnostic angiography and elective coiling in select United States markets with streamlined transfer protocols.
- Research Laboratories:Preclinical imaging studies and device validation work consume specialized microcatheter configurations.
Hospitals command the dominant procurement share, while specialty clinics expand most aggressively.
Technology:
Navigation modality selection determines capital allocation trajectories, with software licensing models reshaping recurring revenue structures.
- Fluoroscopic Guidance:Two-dimensional projection imaging remains the installed base standard across United States community hospitals. Occupational dose limits and contrast nephropathy risks drive replacement interest toward lower-exposure alternatives.
- Electromagnetic Navigation:Real-time three-dimensional catheter tip tracking reduces fluoroscopy exposure and enables procedure standardization. German academic centers deploy this platform for complex arteriovenous malformation embolizations requiring submillimeter precision.
- Magnetic Resonance Imaging:MR-conditional catheter materials enable intraoperative imaging without patient transfer.
- Optical Coherence Tomography:High-resolution vessel wall imaging guides stent apposition assessment in intracranial interventions.
Fluoroscopic guidance retains the largest installed base, with electromagnetic navigation gaining share fastest.
Application:
Procedure reimbursement differentials and clinical evidence strength shape segment prioritization in manufacturer portfolio planning.
- Intracranial Aneurysm:Endovascular coiling dominates ruptured and unruptured aneurysm management in United States comprehensive stroke centers. Coil compaction and recurrence rates sustain demand for microcatheter-based retreatment procedures.
- Ischemic Stroke:Mechanical thrombectomy expansion drives aspiration catheter and stent retriever delivery system volume in Japanese metropolitan emergency networks. Time-to-treatment metrics prioritize device reliability over cost minimization.
- Arteriovenous Malformation:Liquid embolic delivery requires specialized microcatheter compatibility with Onyx and nBCA systems.
- Intracranial Stenting:Symptomatic intracranial stenosis indications face restrictive payer coverage in United States markets.
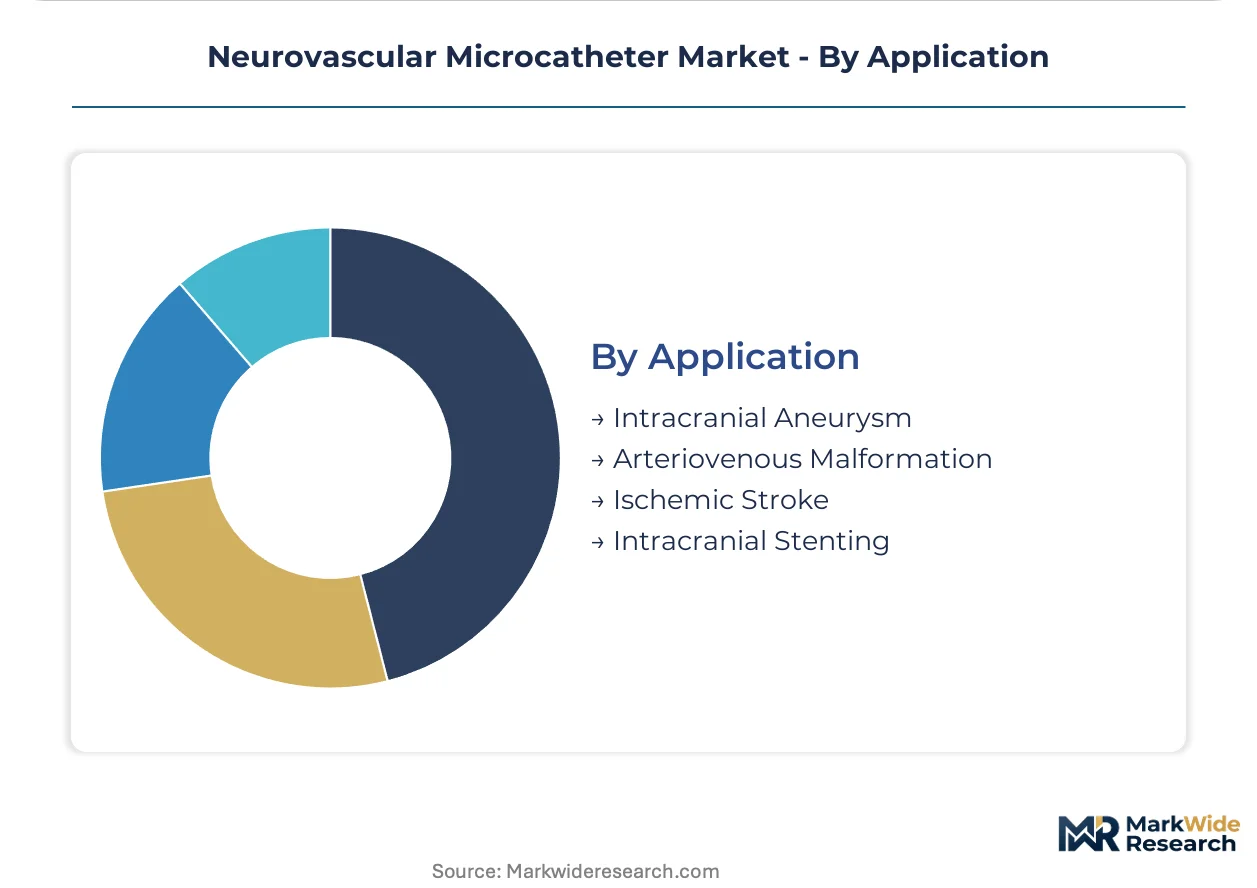
Intracranial aneurysm procedures lead volume rankings, with ischemic stroke interventions climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's comprehensive stroke center density exceeds Japan's metropolitan clustering, yet both markets concentrate catheter procurement within academic medical center networks rather than distributed community hospitals.
United States
Comprehensive stroke center certification mandates 24/7 neurointerventional coverage across urban corridors. FDA premarket notification pathways govern catheter approval timelines for devices contacting blood and neural tissue. Stroke belt counties in the Southeast exhibit aneurysm treatment rates below national benchmarks, creating distributed access opportunities through mobile stroke unit deployment.
Germany
Academic medical centers in Bavaria and Baden-Württemberg anchor technology adoption curves for electromagnetic navigation platforms. EU MDR conformity assessment timelines extend market access delays for legacy device registrations. The KBA medical device vigilance system coordinates post-market surveillance across federal state health ministries.
Japan
Metropolitan hospital clusters in Tokyo and Osaka achieve procedure volumes rivaling hospital-based programs. PMDA's sakigake designation accelerates review timelines for innovative stroke devices, compressing competitive entry windows. The Japanese Circulation Society certifies neurointerventionalists through simulator-based credentialing requirements.
China
Provincial stroke center networks in the Yangtze River Delta expand catheter-based intervention volumes as reimbursement frameworks evolve. NMPA medical device registration regulations shape product development timelines for catheter components. Shanghai and Beijing academic medical centers concentrate demand for high-trackability nitinol hypotube constructions.
Switzerland
Swissmedic's streamlined device authorization attracts catheter manufacturers seeking European market entry points. Geneva and Zurich university hospitals deploy MR-conditional catheter materials for intraoperative imaging without patient transfer. The country's precision manufacturing ecosystem supplies specialty wire drawing capacity for nitinol hypotube sourcing.
Neurovascular Microcatheter Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies commanding premium pricing in navigation-enabled platforms while component suppliers capture volume in bare metal hypotube constructions. The vendor base organizes into three tiers: diversified medtech conglomerates with neurovascular portfolios, pure-play catheter specialists, and OEM contract manufacturers serving private-label programs. Strategic moves concentrate on electromagnetic navigation software licensing and physician training ecosystem development.
Among diversified medtech conglomerates, Medtronic and Stryker Corporation exemplify integrated imaging-to-device workflow strategies, while Penumbra, Inc. occupies a position within the pure-play specialist tier emphasizing proprietary aspiration technology. These three entities anchor competitive dynamics across the United States, German, and Japanese markets respectively, with each representing distinct archetypes in portfolio breadth versus focused specialization.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| Johnson & Johnson Services, Inc. |
| Penumbra, Inc. |
| Terumo Corporation |
| Integer Holdings Corporation |
| MicroVention, Inc. |
| ASAHI INTECC CO., LTD. |
| Acandis GmbH |
| Others |
Pricing and Supply Chain Analysis
Comprehensive stroke center procurement committees in the United States concentrate purchasing authority for electromagnetic navigation platforms, anchoring contract-based pricing with multi-year service bundling. This buyer concentration feeds into tiered pricing structures that stratify across premium navigation-enabled systems, standard fluoroscopic-compatible catheters, and economy bare-metal hypotube constructions.
Pricing Analysis
Capacity additions in China's nitinol wire drawing sector are reshaping price floors for hypotube raw materials. Three-tier pricing structure across premium, standard, and economy levels differentiates electromagnetic navigation subscriptions from bare-metal transactional sales. Cost compression in the economy tier is intensifying because of superelastic alloy sourcing volatility. Academic medical centers in Germany and Japan exhibit lowest price sensitivity due to bundled training ecosystem requirements, while ambulatory surgical centers in the United States face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for electromagnetic navigation hardware create secondary market channels that compete with new equipment sales. Nitinol hypotube production draws from Switzerland, China, and Japan, with specialty wire drawing capacity concentrated in Alpine manufacturing corridors. Raw material dependencies include nickel-titanium alloys, hydrophilic polymer coatings, and braided stainless steel wire. Single-source vulnerability in superelastic alloy melting creates supply chain risk. Distribution runs through dedicated stroke care specialist teams anchored by hospital system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 120 transition timelines compound market access barriers, elevating the strategic value of regulatory-ready catheter portfolios. This regulatory compounding accelerates consolidation among manufacturers with legacy device registrations.
For Market Incumbents: Lock in electromagnetic navigation software licensing revenue through procedure-specific module tiering. Deepen backward integration into nitinol hypotube production to offset raw material volatility. Defend against pure-play aspiration catheter specialists by embedding training ecosystems within hospital system partnerships. For New Entrants and Emerging Players: PMDA's sakigake designation in Japan opens a window for simultaneous multi-regional filings that compress competitive entry timelines. Target underpenetrated stroke belt counties in the southeastern United States through mobile stroke unit deployment partnerships. Pursue OEM contract manufacturing relationships with diversified medtech conglomerates seeking private-label hypotube sourcing. For Investors and Strategic Acquirers: Diversified medtech conglomerates with neurovascular portfolios are the most active acquirers in this space. Five-to-ten year viability hinges on electromagnetic navigation platform adoption curves. Acquisition target archetypes include pure-play catheter specialists with proprietary coating technologies. Monitor FDA guidance on computational modeling for catheter performance validation as inflection indicator for preclinical submission cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Navigation Software Licensing | Medtronic's integrated imaging-to-device workflows generate recurring revenue beyond hardware replacement cycles. |
| Nitinol Hypotube Backward Integration | Stryker's captive supply of superelastic alloy components reduces exposure to Swiss and Chinese wire drawing concentration. |
| Physician Training Ecosystem Development | Penumbra's simulator-based credentialing programs compress time-to-autonomy for new neurointerventionalists. |
| Simultaneous PMDA-FDA Filing Strategy | Terumo's sakigake-designated stroke devices capture early-mover reimbursement advantages in Japanese metropolitan clusters. |
| Mobile Stroke Unit Partnership | Acandis's distributed access point deployment targets aneurysm treatment rate gaps in southeastern United States counties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included neurointerventionalists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR conformity assessment databases, PMDA approval registers, and hospital procurement contract disclosures. Bottom-up catheter shipment modeling and top-down stroke center capital expenditure estimates were triangulated against comprehensive stroke center certification tallies.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include catheter construction type, navigation technology tier, end-user facility category, and geographic regulatory cluster. CAGRs were derived from procedure volume elasticity to stroke center certification expansion and technology replacement cycle assumptions. Forecast inputs incorporated nitinol alloy price indices and electromagnetic navigation platform adoption curves.
Revisions become necessary when EU MDR clinical evidence requirements intensify, PMDA review timelines shift, or fluoroscopy dose regulations tighten. Forecasts reflect assumptions about reimbursement framework evolution and operator training pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Water Flosser Market
Medical Devices
Dysphagia Management Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Endodontic Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Tissue Expanders Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Human Anatomical Models Market