
 Propafenone Hcl Extended Release Capsules Market | 2026-2036
Propafenone Hcl Extended Release Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Propafenone Hcl Extended Release Capsules Market Insights
The divergence between premium branded formulations and commodity generic tiers is realigning procurement patterns across cardiac care channels. GSK sustains pricing power through its established brand heritage in antiarrhythmic therapy. Mylan leverages its generic manufacturing scale to capture institutional pharmacy contracts. Glenmark Pharmaceutical anchors its position through geographic dominance in emerging markets where cost sensitivity shapes prescribing behavior.
Propafenone HCl extended release capsules contain a Class IC antiarrhythmic agent formulated in a sustained-release matrix, typically dosed at 225 mg, 325 mg, or 425 mg for twice-daily administration to maintain therapeutic plasma concentrations and suppress ventricular and supraventricular arrhythmias. The generic segment dominates volume as FDA ANDA approvals erode exclusivity, while the prescription channel captures margin through controlled distribution and pharmacist counseling requirements. The cardiology therapy area leads clinical utilization, with hospital end users driving initial prescribing before patients transition to home care for maintenance therapy.
FDA bioequivalence standards for extended-release formulations shape product development timelines and manufacturing investments, while the USP dissolution methodology governs batch release criteria for market access. The Drug Enforcement Administration and state boards of pharmacy impose scheduling and dispensing controls that constrain channel flexibility for this prescription-controlled agent. Stakeholders must monitor ANDA litigation outcomes and FDA guidance on modified-release bioequivalence studies to anticipate competitive entry and portfolio repositioning requirements.
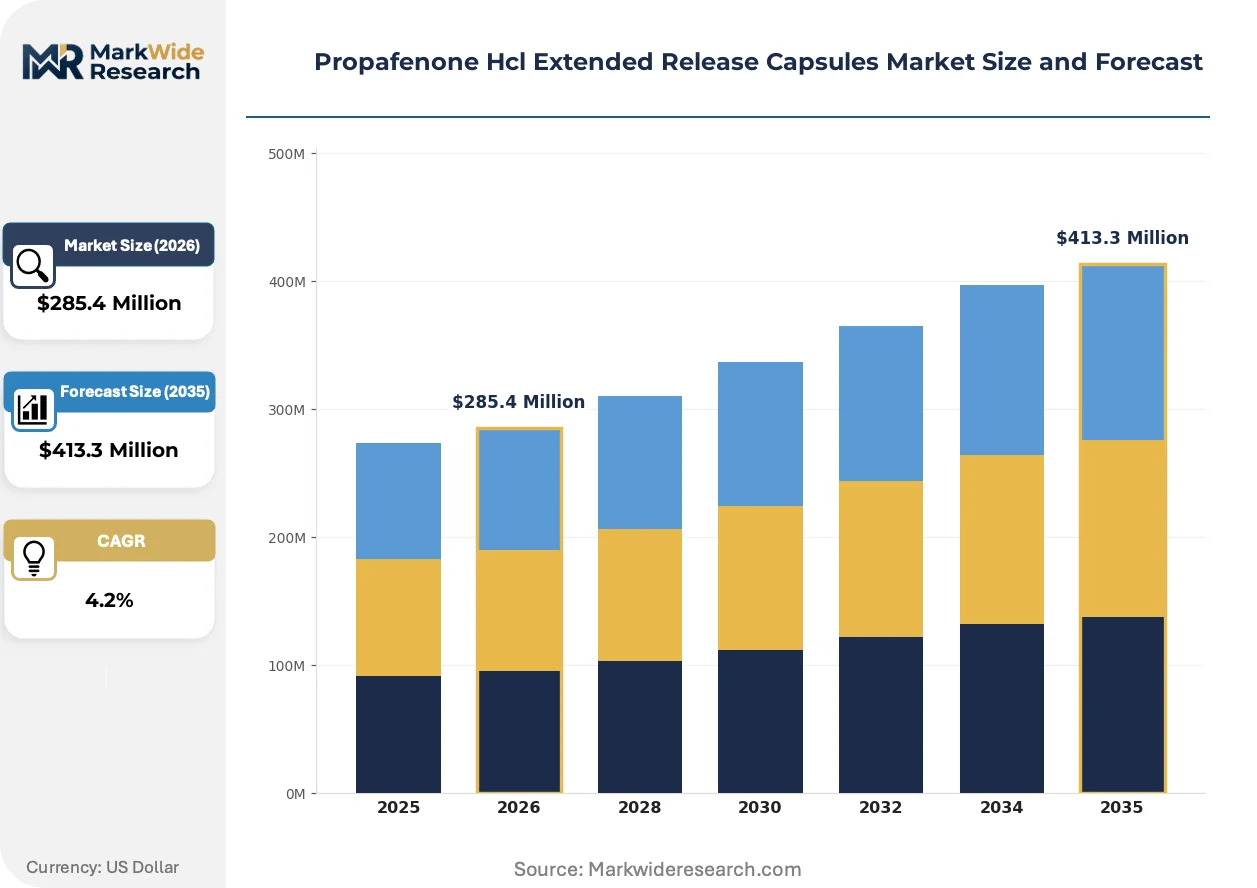
Market Dynamics
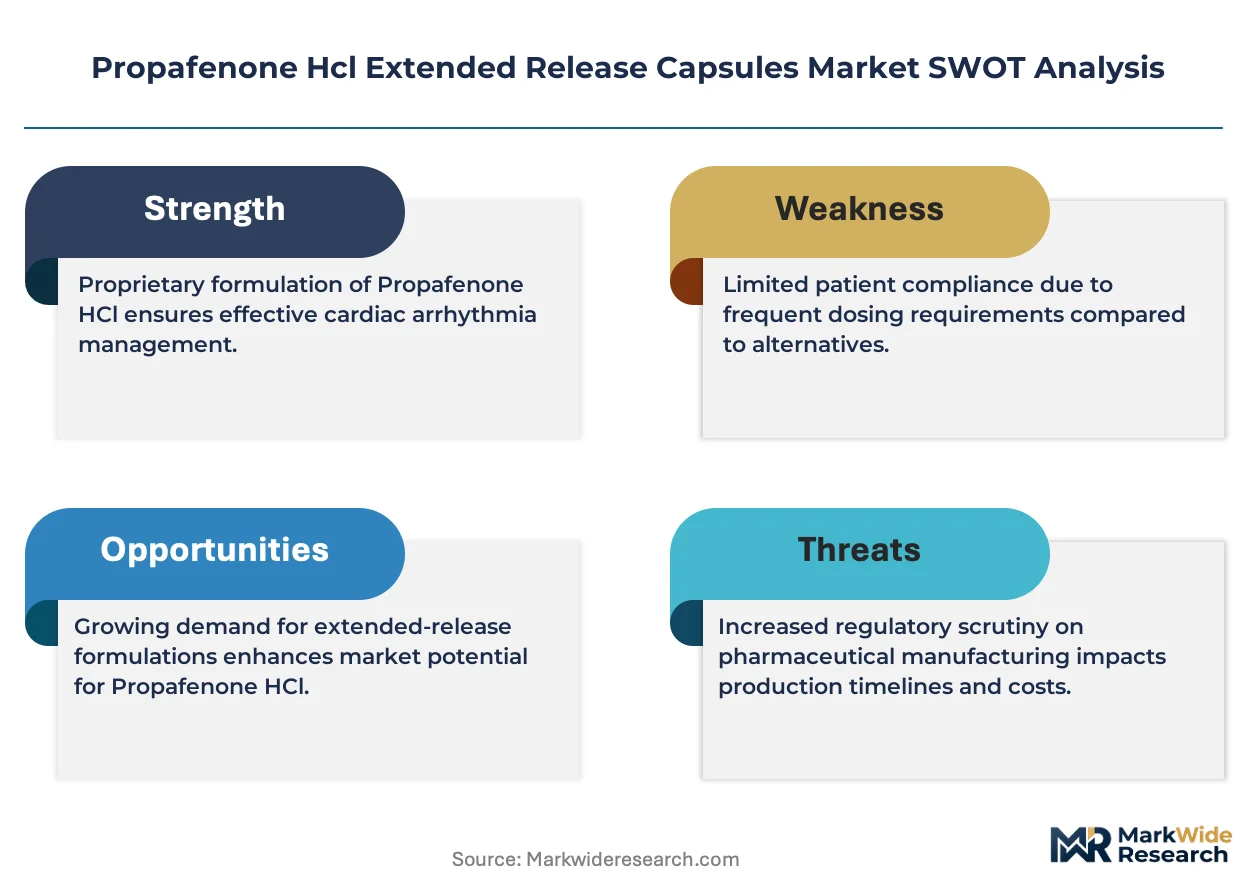
The genericization wave following FDA ANDA approvals for extended-release propafenone HCl is compressing pricing tiers and forcing incumbents to defend formulary position through manufacturing quality differentiation rather than exclusivity.
Growth Catalysts
- Medicare Part D Reimbursement:The United States federal program covers chronic cardiovascular maintenance therapy, stabilizing patient out-of-pocket exposure and sustaining prescription refill adherence for twice-daily propafenone regimens.
- Cardiac Catheterization Volume Expansion:Hospital electrophysiology labs in Germany and the United States are expanding ablation procedure throughput, generating post-procedural antiarrhythmic prescribing that transitions to outpatient maintenance.
- Modified-Release Bioequivalence Guidance:FDA publication of comparative dissolution standards for Class IC antiarrhythmics is clarifying development pathways for ANDA filers, accelerating competitive entry and volume expansion.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for propafenone HCl concentrates in Indian and Chinese chemical synthesis clusters, exposing finished dose producers to import tariff volatility and geopolitical friction.
- Dissolution Methodology Stringency:USP apparatus specifications for extended-release matrix formulations require specialized analytical equipment and trained personnel, elevating batch release costs for smaller generic entrants.
- Substitution to Catheter Ablation:Radiofrequency and cryoablation technologies for atrial fibrillation are reducing long-term pharmaceutical dependency among eligible patient populations with paroxysmal arrhythmia patterns.
Strategic Opportunities
- Institutional Pharmacy Contracts:United States hospital systems are consolidating formulary procurement through centralized pharmacy benefit managers, creating volume aggregation points for generic manufacturers with 180-day exclusivity positions.
- Pediatric Formulation Extension:FDA guidance on extrapolating adult efficacy data to adolescent populations with supraventricular tachycardia is opening label expansion pathways for sponsors with existing ANDA approvals.
- Telecardiology Integration:Remote patient monitoring platforms for implantable loop recorders are creating adherence-tracking touchpoints that generic marketers can leverage for refill optimization.
Industry Challenges
- Bioanalytical Method Transfer:Validating plasma concentration assays across contract research organizations with differing LC-MS/MS configurations is delaying ANDA submission timelines and increasing development spend.
- State-Level Dispensing Controls:Variability in prescription monitoring program requirements across United States jurisdictions is complicating direct-to-patient pharmacy fulfillment models for controlled antiarrhythmic agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Propafenone Hcl Extended Release Capsules Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $413.3 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic, Brand, OTC, Prescription Therapy Area: Cardiology, Arrhythmia, Heart Disease, Hypertension Delivery Mode: Oral, Injectable, Transdermal, Dispersible End User: Hospitals, Clinics, Pharmacies, Home Care |
| Companies Covered | GSK, Mylan, Upsher-Smith Laboratories, Par Pharmaceutical, Glenmark Pharmaceutical, Zydus Cadila, TWi Pharmaceuticals, Prasco Laboratories, Rising Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Propafenone Hcl Extended Release Capsules Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how extended-release antiarrhythmics reach chronic therapy patients, with dissolution control and channel consolidation emerging as the dominant technical and commercial vectors.
Matrix-based sustained-release technologies using hydroxypropyl methylcellulose and ethylcellulose blends are enabling tighter pharmacokinetic profiles with reduced peak-to-trough variation. United States generic sponsors are adopting these platforms to demonstrate bioequivalence against reference listed drugs with complex release kinetics. This capability is decentralizing manufacturing competence away from originator-controlled process know-how toward contract development organizations with platform formulation expertise.
EMA reflection papers on quality by design for modified-release products are mandating multivariate dissolution specifications that exceed traditional single-point USP requirements. European generic applicants must now submit design space documentation linking critical process parameters to in-vitro performance. Cardiology-focused manufacturers in Germany and Italy are responding by building in-house biopharmaceutical modeling capabilities rather than outsourcing to contract research organizations.
Hospital procurement coalitions in the United States are unbundling antiarrhythmic purchasing from broader cardiovascular therapeutic contracts, enabling direct negotiation with generic manufacturers on extended-release propafenone specifically. This disaggregation is compressing distributor margins and forcing wholesalers to compete on logistics performance rather than formulary access. The shift is most visible in Medicare Advantage plans with owned delivery networks, where 90-day dispensing through centralized mail pharmacies is displacing retail channel fulfillment.
Propafenone Hcl Extended Release Capsules Market Segmentation
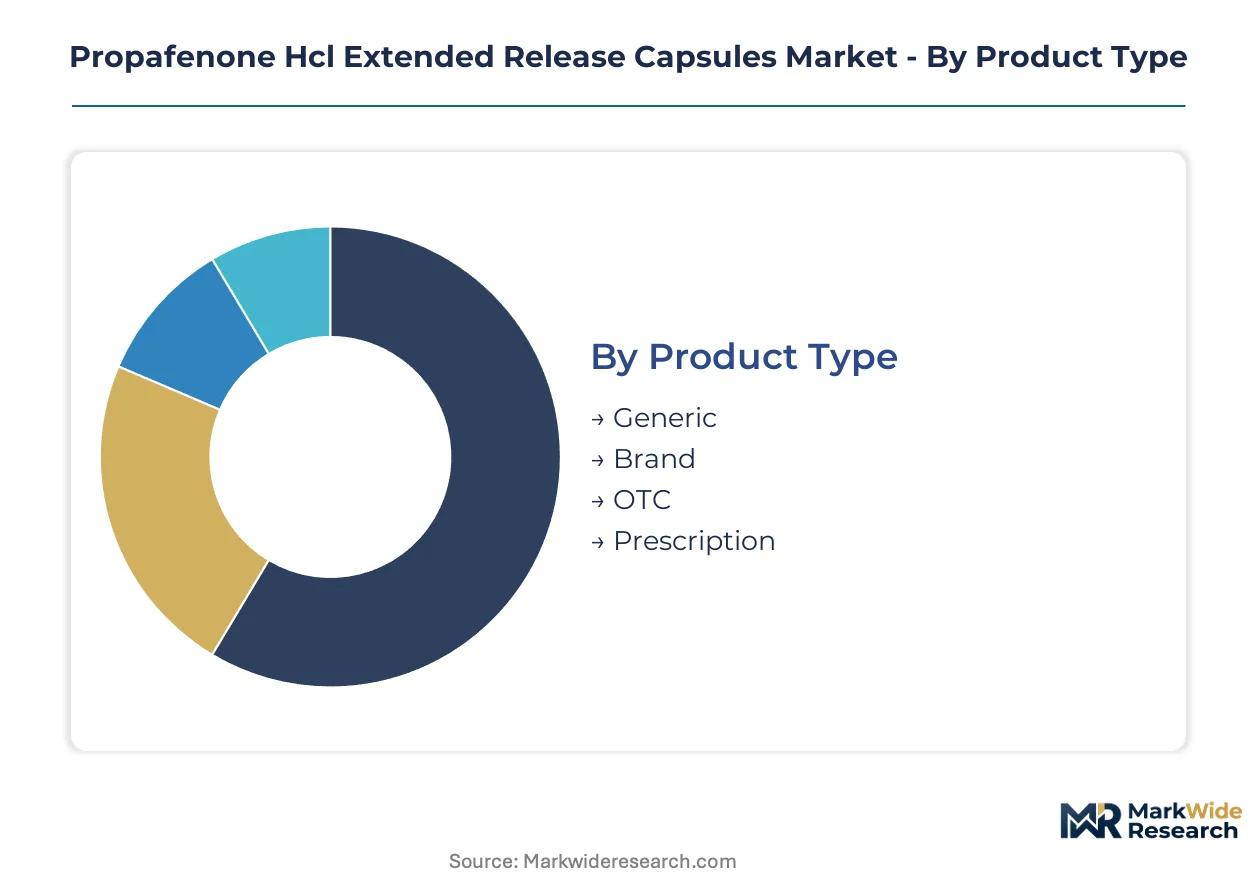
Segmentation in the propafenone HCl extended-release market exposes how reimbursement pathways and clinical settings reshape procurement priorities. Manufacturers must align formulation portfolios with distinct channel economics across generic substitution tiers and institutional purchasing coalitions.
Product Type:
Cost tier positioning determines formulary access and margin capture for each product classification.
- Generic:FDA ANDA-approved extended-release formulations dominate prescription volume through Medicare Part D reimbursement. Institutional pharmacy contracts in the United States consolidate procurement around manufacturers with demonstrated bioequivalence against reference listed drugs.
- Brand:Originators sustain pricing power through established clinical heritage and controlled distribution networks. Hospital electrophysiology departments in Germany and the United States specify branded propafenone for post-ablation protocols where therapeutic familiarity reduces liability exposure.
- OTC:Non-prescription availability remains negligible for Class IC antiarrhythmics due to DEA scheduling requirements and cardiac safety monitoring mandates.
- Prescription:Controlled dispensing through licensed pharmacies captures margin via pharmacist counseling requirements and refill adherence programs.
Generic leads volumes today; brand is gaining share fastest in hospital channels defending protocol consistency.
Therapy Area:
Clinical application specificity dictates dosing regimens and prescriber specialization requirements.
- Cardiology:General cardiologists manage chronic ventricular arrhythmia suppression with twice-daily extended-release regimens. Medicare Part D coverage stabilizes patient out-of-pocket exposure for maintenance therapy in the United States.
- Arrhythmia:Electrophysiology specialists prescribe propafenone for paroxysmal supraventricular tachycardia following catheter ablation procedures. Post-procedural prescribing in German hospital systems transitions patients to outpatient maintenance within 48 hours.
- Heart Disease:Broader cardiovascular comorbidity management incorporates propafenone alongside anticoagulation and heart failure therapies.
- Hypertension:Adjunctive use for rhythm control in hypertensive patients with concurrent atrial fibrillation occupies a narrower prescriber niche.
Arrhythmia captures the steepest expansion trajectory as ablation volumes climb; cardiology maintains the largest installed prescriber base.
Delivery Mode:
Administration route selection hinges on patient compliance economics and acute intervention requirements.
- Oral:Extended-release capsule formulations enable twice-daily dosing with sustained plasma concentration profiles. Matrix-based hydroxypropyl methylcellulose technologies from contract development organizations tighten pharmacokinetic variation.
- Injectable:Intravenous propafenone serves acute arrhythmia termination in emergency departments and cardiac catheterization labs. Hospital formulary placement depends on anesthesia and critical care committee approvals.
- Transdermal:Patch-based delivery remains investigational for Class IC antiarrhythmics due to skin permeation challenges with propafenone's molecular weight and lipophilicity.
- Dispersible:Rapid-dissolve formulations for dysphagic patients occupy a limited pediatric and geriatric niche with specialized compounding requirements.
Oral dominates current prescribing; injectable is expanding most quickly in electrophysiology lab protocols.
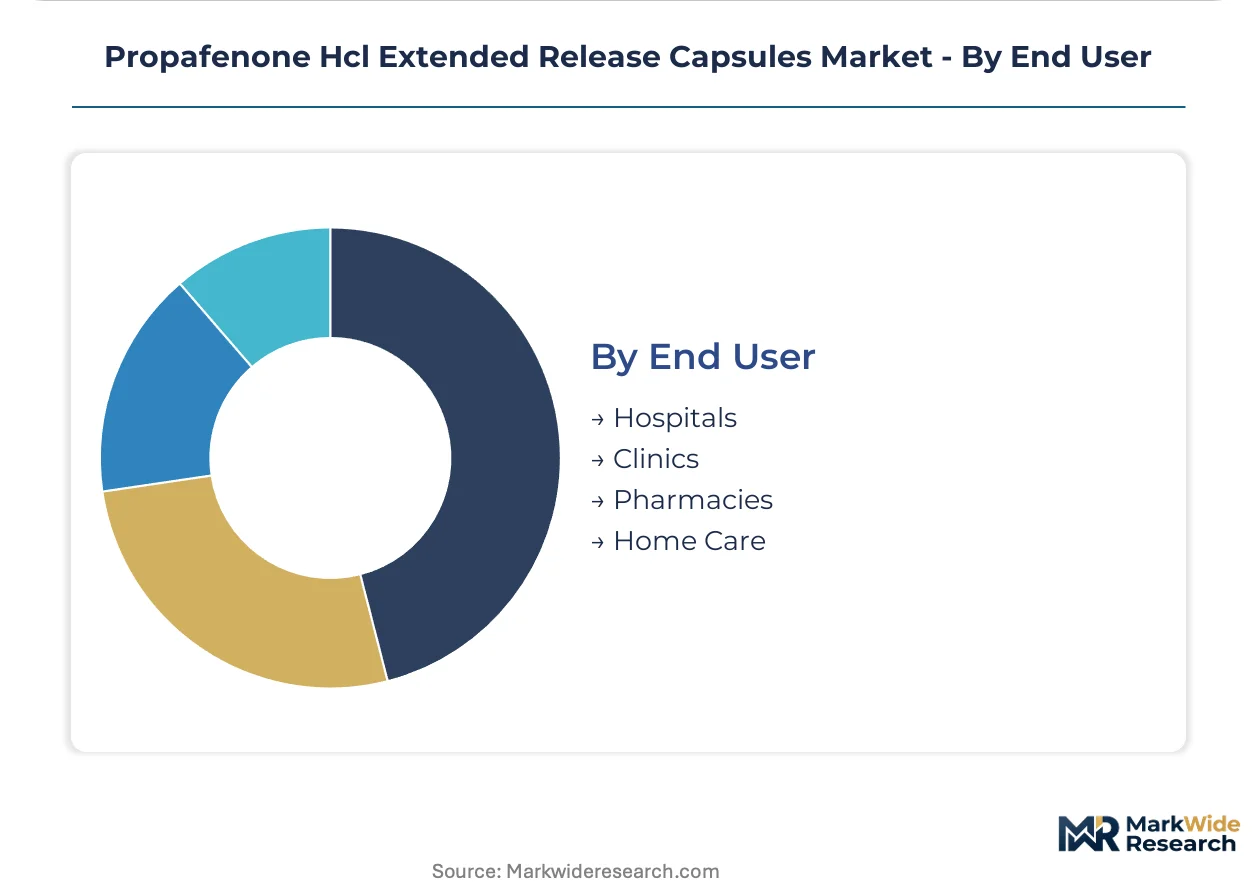
End User:
Channel consolidation patterns reshape how manufacturers allocate field force resources and contract negotiation priorities.
- Hospitals:United States health systems aggregate antiarrhythmic purchasing through centralized pharmacy benefit managers. 340B program eligibility for disproportionate share hospitals creates pricing tier complexity.
- Clinics:Outpatient cardiology practices in Medicare Advantage networks drive 90-day dispensing through owned mail pharmacies. Physician dispensing regulations vary across state jurisdictions.
- Pharmacies:Retail chains compete on generic substitution rates and adherence program sophistication. State prescription monitoring program integration constrains controlled substance dispensing workflows.
- Home Care:Infusion services for bridge-to-oral therapy occupy a narrow post-discharge niche with skilled nursing oversight requirements.
Hospitals lead institutional volume aggregation; clinics are climbing the fastest as Medicare Advantage penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular pharmacology specialists cluster in United States hospital systems and German university medical centers, anchoring demand for extended-release antiarrhythmic therapies. These concentrations shape prescribing protocols that cascade through regional procurement networks.
United States
Medicare Part D reimbursement stabilizes patient out-of-pocket exposure for chronic propafenone maintenance therapy. FDA bioequivalence standards for extended-release Class IC antiarrhythmics govern ANDA approval pathways for generic sponsors. Hospital procurement coalitions in the Northeast Corridor and Texas Medical Center aggregate volume through centralized pharmacy benefit managers.
Germany
Electrophysiology labs in university hospitals drive post-ablation antiarrhythmic prescribing that transitions to ambulatory care within 48 hours. EMA reflection papers on quality by design for modified-release products mandate multivariate dissolution specifications exceeding traditional USP requirements. Manufacturing competence clusters in Baden-Württemberg and North Rhine-Westphalia as cardiology-focused firms build in-house biopharmaceutical modeling capabilities.
India
Active pharmaceutical ingredient synthesis for propafenone HCl concentrates in Gujarat and Maharashtra chemical manufacturing corridors. CDSCO regulatory pathways for extended-release formulations align with WHO prequalification standards for export-oriented production. Hyderabad and Mumbai-based contract development organizations serve ANDA filers with platform formulation expertise in hydroxypropyl methylcellulose matrix technologies.
China
Domestic demand for antiarrhythmic maintenance therapy expands as provincial health insurance catalogs broaden cardiovascular drug reimbursement. NMPA dissolution methodology requirements for extended-release capsules align with USP apparatus specifications, enabling parallel filing strategies. Yangtze River Delta pharmaceutical clusters in Jiangsu and Zhejiang specialize in sustained-release matrix manufacturing for export markets.
Japan
PMDA consultations on bioequivalence study design for narrow therapeutic index antiarrhythmics extend development timelines for generic entrants. Aging demographics in Kanto and Kansai regions sustain prescription volume for chronic atrial fibrillation management. Osaka-based pharmacology research institutes collaborate with PMDA on modified-release bioequivalence guidance for Class IC agents.
Propafenone Hcl Extended Release Capsules Market Competitive Landscape
Top-tier vendors anchor hospital formulary contracts, while mid-scale generic manufacturers compete on institutional pharmacy pricing and bioequivalence documentation quality. The market exhibits tiered concentration around originator heritage brands, high-volume ANDA filers with 180-day exclusivity positions, and emerging-market specialists with cost-optimized manufacturing platforms. Dominant competitive moves include geographic expansion through regional distribution partnerships and portfolio diversification into complementary cardiovascular therapies.
Within the originator heritage tier, GSK occupies a position representing established clinical familiarity in electrophysiology protocols. Among high-volume generic manufacturers, Mylan exemplifies scale-driven institutional contract capture, while Glenmark Pharmaceutical anchors emerging-market positioning where cost sensitivity shapes procurement decisions. These three entities represent the strategic archetypes—heritage brand defense, volume-scale generic production, and geographic cost leadership—that define competitive positioning across cardiac care channels.
| Leading Market Players |
|---|
| GSK |
| Mylan |
| Upsher-Smith Laboratories |
| Par Pharmaceutical |
| Glenmark Pharmaceutical |
| Zydus Cadila |
| TWi Pharmaceuticals |
| Prasco Laboratories |
| Rising Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient spot pricing for propafenone HCl intermediates cascades through Indian and Chinese chemical synthesis clusters into finished dose procurement tiers, compressing margins for generic manufacturers while originators defend premium positioning through controlled distribution networks.
Pricing Analysis
The bundled-vs-unbundled service split separates institutional pharmacy contracts with 90-day dispensing and adherence programs from unbundled retail channel fulfillment. Three-tier pricing structure across premium, standard, and economy levels stratifies by bioequivalence documentation quality and manufacturing site FDA inspection history. Cost compression in the generic tier intensifies as 180-day exclusivity holders undercut subsequent ANDA filers on hospital formulary bids. Medicare Advantage plans with owned delivery networks exhibit lowest price sensitivity; cash-pay channels in emerging markets show highest elasticity.
Supply Chain Analysis
Propafenone HCl API supply rests on specialty chemical producers concentrated in Gujarat and Maharashtra, India, and Jiangsu province, China. Finished dose manufacturing draws from hydroxypropyl methylcellulose matrix polymers sourced from European excipient suppliers and ethylcellulose from North American chemical producers. Single-source vulnerability in Indian API synthesis exposes finished dose producers to import tariff volatility and geopolitical friction. Distribution runs through United States wholesale distributors with 340B program eligibility tracking for disproportionate share hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electrophysiology lab protocol standardization shifts demand toward manufacturers with demonstrated batch-to-batch dissolution consistency and FDA establishment inspection history.
For Market Incumbents: To counter catheter ablation substitution for paroxysmal arrhythmia patients, GSK and heritage brand holders should anchor hospital electrophysiology protocols through post-ablation prescribing guidelines and backward integration into specialized analytical equipment for in-house dissolution testing. Mylan and high-volume generic manufacturers must defend 180-day exclusivity positions by locking institutional pharmacy contracts with Medicare Advantage owned-delivery networks before subsequent ANDA filers achieve bioequivalence approval. For New Entrants and Emerging Players: Capture white-space in pediatric formulation extensions for adolescent supraventricular tachycardia populations where FDA guidance permits efficacy extrapolation from adult data. Geographic entry should target German university hospital electrophysiology departments seeking second-source generic options for post-ablation protocols. Go-to-market positioning emphasizes telecardiology platform integration for remote adherence monitoring that distinguishes from commodity generic suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with contract development organizations possessing platform formulation expertise in hydroxypropyl methylcellulose matrix technologies and established FDA bioequivalence study track records. Long-term viability over the extended pharmaceutical investment horizon favors targets with demonstrated ANDA approval velocity and European EMA quality-by-design documentation capabilities. Watch FDA ANDA litigation outcomes and modified-release bioequivalence guidance publications as inflection indicators for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Extension | FDA guidance on adolescent efficacy extrapolation opens label expansion pathways for ANDA holders. |
| Telecardiology Platform Integration | Remote monitoring capabilities for implantable loop recorders enable refill optimization touchpoints. |
| Institutional Pharmacy Contract Consolidation | Medicare Advantage owned-delivery networks aggregate volume through centralized pharmacy benefit managers. |
| Quality-by-Design Documentation Investment | EMA reflection papers mandate multivariate dissolution specifications exceeding traditional USP requirements. |
| Backward Integration into Analytical Equipment | In-house biopharmaceutical modeling capabilities reduce dependency on contract research organizations. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists combined with secondary validation against FDA ANDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare Part D claims data. Cross-referencing manufacturer batch release records with USP dissolution methodology specifications enabled supply-side triangulation against demand-side prescription volume patterns.
Input-output matrix framing links active pharmaceutical ingredient synthesis capacity in Indian and Chinese chemical corridors to finished dose production volumes and downstream channel fulfillment. Segmentation dimensions modeled include product type, therapy area, delivery mode, and end user across the projection horizon. CAGRs were derived from regression analysis of historical prescription refill patterns and cardiac catheterization volume trajectories, incorporating FDA bioequivalence approval timelines and ANDA litigation outcomes as industry-specific forecast inputs.
ANDA approval delays, catheter ablation volume acceleration, and API import tariff escalation are the dominant revision risks to the forecast framework. Forecasts reflect assumptions regarding Medicare Part D reimbursement stability and electrophysiology lab expansion rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mitotane Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Global Plasma Derived Therapy Market