
 Fertility Treatments Market | 2026-2036
Fertility Treatments Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Treatments Market Insights
Project finance and pay-per-cycle leasing models is tilting competitive dynamics toward asset-light clinic networks that avoid heavy embryology lab capex. CooperSurgical Inc. leverages its vertically integrated portfolio of media, devices, and consumables to sustain pricing power across the IVF workflow. Vitrolife AB anchors its position through advanced time-lapse incubation systems that dominate premium clinic segments in Western Europe.
Fertility treatments encompass assisted reproductive technologies that manipulate gametes or embryos outside the body, typically requiring controlled ovarian stimulation with recombinant gonadotropins, laboratory culture in pH-buffered media at 37°C with 5-6% CO2, and ultrasound-guided embryo transfer to achieve conception. The primary commercial purpose is overcoming tubal, male-factor, or unexplained infertility when conventional interventions fail. IVF procedures command the largest revenue share within product type categories, reflecting higher per-cycle economics and consumable intensity than IUI or sperm donation alternatives. Hormonal disorders and PCOS dominate the therapy area landscape, while specialized fertility centers capture disproportionate margins by bundling consultation, diagnostics, and retrieval services under single-site ownership.
FDA oversight of culture media and genetic screening technologies shapes product development timelines and clinical validation requirements for US market entry, while EMA's MDR framework imposes parallel conformity pressures on European manufacturers. The EU AI Act introduces emerging compliance dimensions for embryo assessment algorithms and automated grading systems deployed in time-lapse platforms. Stakeholders must monitor how reimbursement policy divergence between national health systems and private payers reshapes geographic deployment priorities for new service formats.
Market Dynamics
Employer-sponsored fertility benefits are restructuring access patterns across metropolitan hospital networks, shifting financial risk from patients to commercial payers and accelerating clinic consolidation.
Growth Catalysts
- Time-lapse incubation systems:Advanced embryo monitoring platforms enable continuous morphokinetic assessment without culture disruption. Premium fertility centers in Western Europe deploy these systems to differentiate cycle outcomes.
- IRA fertility coverage mandates:US employer benefit expansion normalizes IVF access through pre-tax health savings structures. Large self-insured employers now bundle egg freezing into standard health packages.
- Elective fertility preservation:Younger patient segments pursue proactive gamete banking before age-related decline. North American clinics report rising demand from unmarried professionals under 35.
Market Restraints
- Recombinant gonadotropin cost volatility:Controlled ovarian stimulation depends on biologic hormone supplies concentrated among three European manufacturers. Price fluctuations directly compress clinic margins per retrieval cycle.
- Embryology lab capex concentration:ISO 5 cleanroom standards and time-lapse platform investments favor multi-site networks over independent practices. Asset-heavy infrastructure requirements exclude smaller regional entrants.
- Genetic screening validation timelines:FDA premarket review of PGT-A algorithms extends product development cycles. Manufacturers face parallel EMA MDR conformity assessments for EU commercialization.
Strategic Opportunities
- Pay-per-cycle leasing models:Asset-light clinic networks avoid embryology lab ownership through equipment-as-a-service arrangements. Third-party laboratory operators capture recurring revenue from independent physicians.
- AI-assisted embryo grading:Machine vision algorithms automate morphological assessment, reducing inter-observer variability. EU AI Act compliance frameworks create first-mover advantages for validated systems.
- Cross-border reproductive tourism:Cost differentials between national health systems drive patient mobility. Eastern European jurisdictions attract German and Italian couples seeking lower per-cycle fees.
Industry Challenges
- Embryologist certification bottlenecks:Specialized training programs for complex micromanipulation techniques produce insufficient qualified personnel. Accredited fellowship positions fail to match clinic expansion rates.
- Legacy EMR integration complexity:Time-lapse platforms and genetic screening databases require interoperability with established hospital information systems. Custom API development delays technology deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Treatments Market |
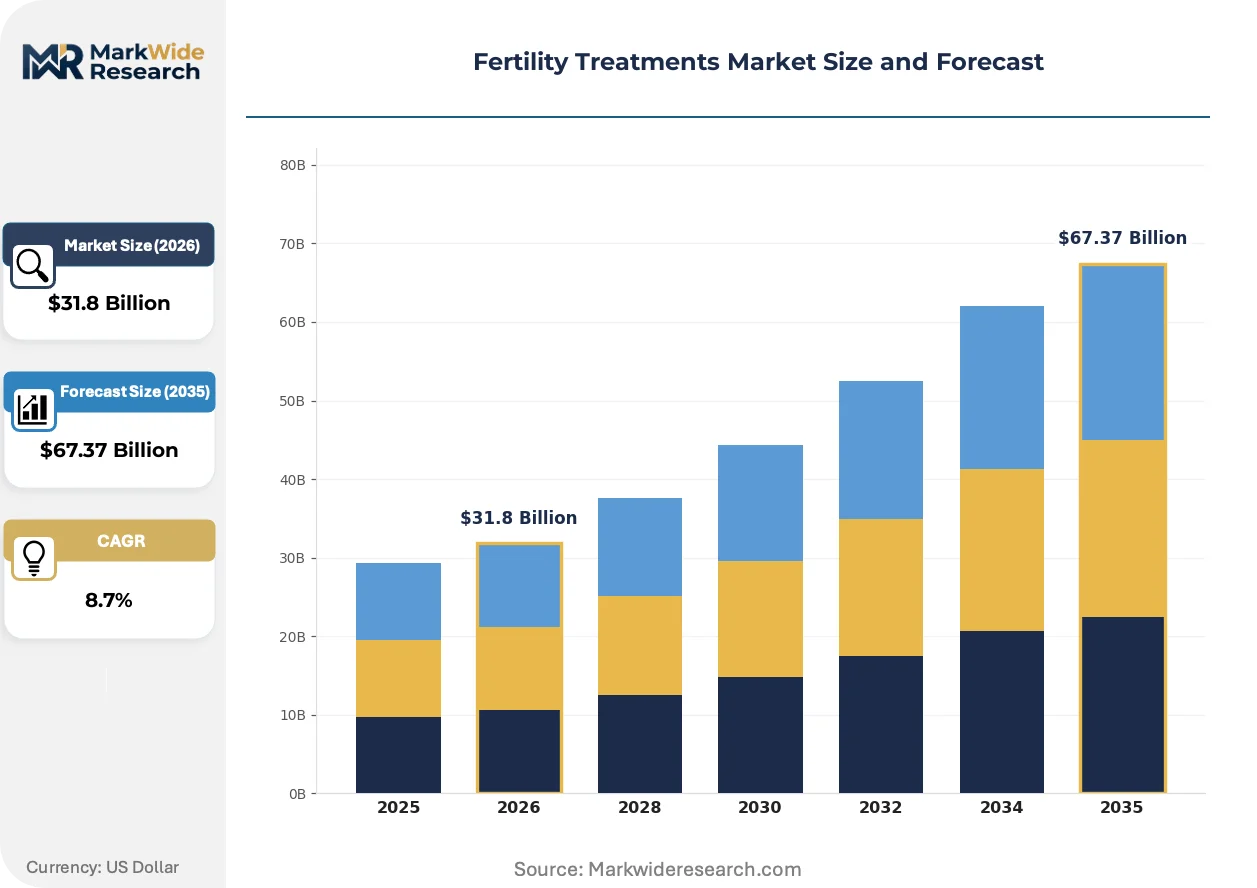
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $67.37 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IVF, IUI, Egg Freezing, Sperm Donation Therapy Area: Hormonal Disorders, PCOS, Endometriosis, Male Infertility Service Type: Consultation, Diagnostics, Egg Retrieval, Embryo Transfer End User: Clinics, Hospitals, Specialized Fertility Centers, Research Institutions |
| Companies Covered | CooperSurgical Inc., Vitrolife AB, Merck KGaA, Ferring Pharmaceuticals, Thermo Fisher Scientific Inc., FUJIFILM Irvine Scientific, Cook Group Inc., Hamilton Thorne Ltd., Esco Micro Pte. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Treatments Market Trends and Innovations
Digital infrastructure is compressing the physical footprint of embryology operations while regulatory frameworks scramble to keep pace with automated assessment tools.
Artificial intelligence-based morphokinetic analysis is virtualizing traditional manual embryo grading workflows. High-volume fertility centers in the United States and Denmark deploy these systems to standardize selection decisions across multiple embryologists. The technology is virtualizing quality control processes that previously required senior specialist oversight, enabling network expansion without proportional staffing increases.
EU AI Act risk classification rules now categorize embryo assessment algorithms as high-risk medical devices requiring notified body conformity assessment. European manufacturers must demonstrate algorithmic transparency and bias mitigation before CE marking. Time-lapse platform vendors face compressed development timelines to meet MDR technical documentation requirements alongside emerging AI governance standards.
Subscription-based consumable purchasing is displacing spot-market procurement in multi-site clinic networks. Large US hospital systems negotiate multi-year media and device supply agreements with single-source vendors. This concentration is most visible in metropolitan markets where employer-sponsored benefits have standardized treatment protocols across formerly independent practices.
Fertility Treatments Market Segmentation
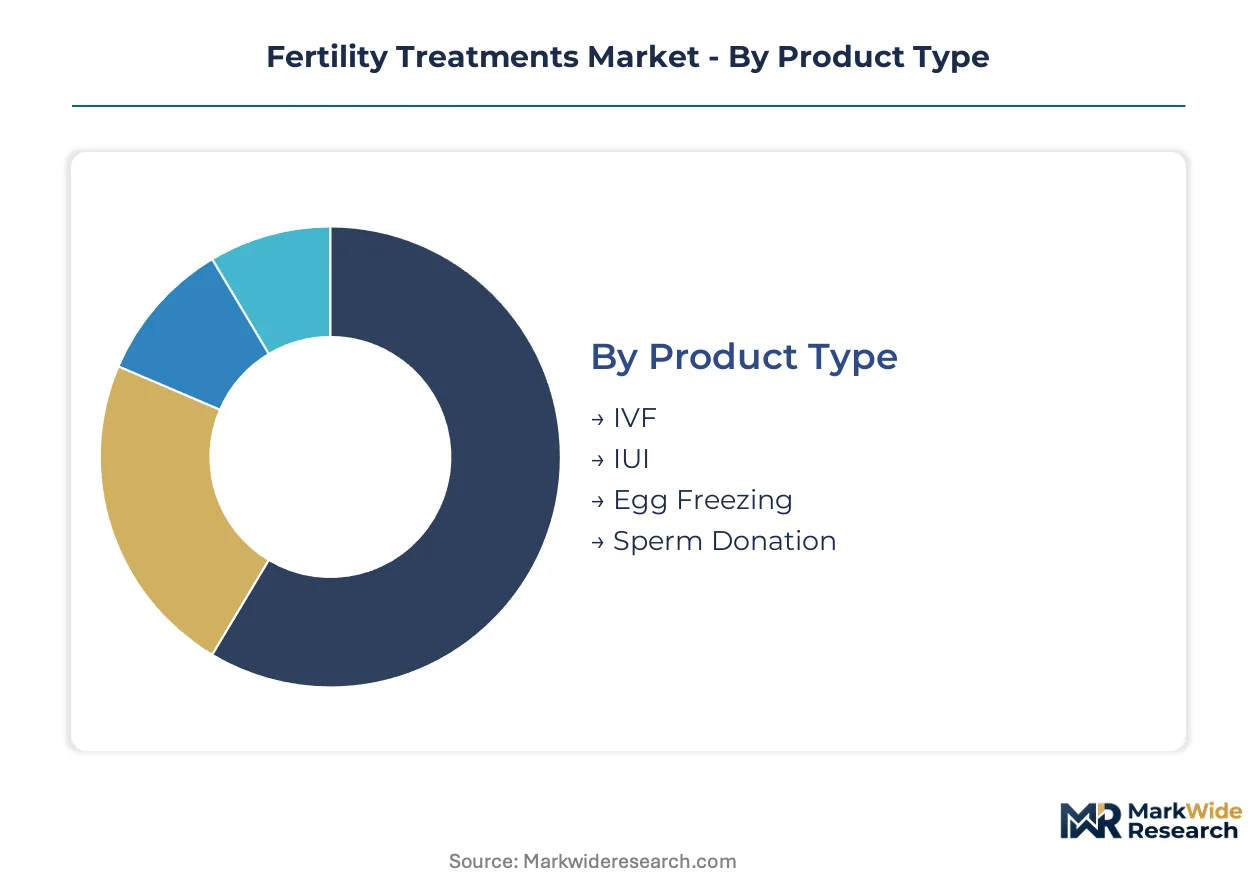
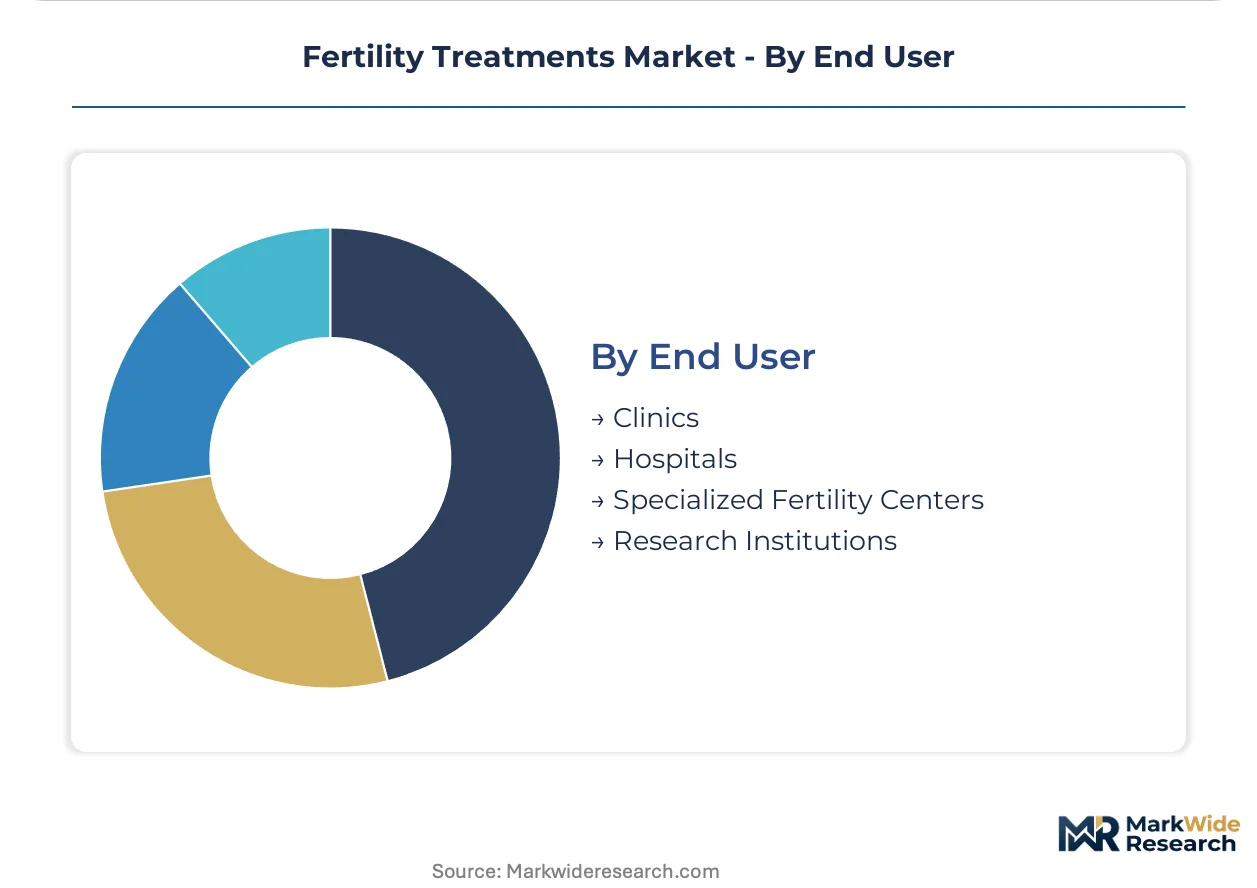
The fertility treatments market segments across four distinct dimensions that shape procurement patterns and margin structures. Product type determines consumable intensity and per-cycle economics. Service type and end user configuration dictate capital deployment strategies and regulatory exposure.
Product Type:
Use-case spectrum spans high-intervention surgical retrieval to minimally invasive insemination and elective preservation services.
- IVF:Controlled ovarian stimulation, oocyte retrieval, laboratory fertilization, and embryo transfer constitute the most consumable-intensive workflow. United States metropolitan hospital networks concentrate demand as employer-sponsored benefits normalize multi-cycle treatment paths.
- Egg Freezing:Elective cryopreservation of oocytes for deferred reproduction involves stimulation protocols without immediate fertilization. North American clinics report rising uptake among unmarried professionals under 35 seeking age-related fertility decline mitigation.
- IUI:Intrauterine insemination places processed sperm directly into the uterine cavity during ovulation windows. Lower per-cycle costs attract initial intervention candidates before escalation to IVF.
- Sperm Donation:Third-party gamete provision supports single-parent-by-choice and same-sex couple conception pathways. Cryobank networks manage donor screening, genetic testing, and distribution logistics.
Established volume favors IVF; emerging adoption favors egg freezing.
Therapy Area:
Patient presentation determines stimulation protocol selection and laboratory workflow complexity.
- Hormonal Disorders:Hypothalamic-pituitary-ovarian axis dysfunction requires customized gonadotropin dosing algorithms. European manufacturers supply recombinant FSH and LH analogs that dominate ovarian stimulation regimens.
- PCOS:Polycystic ovary syndrome presents insulin resistance and anovulation challenges demanding metformin adjuncts and careful hyperstimulation monitoring. Specialized fertility centers capture disproportionate margins through bundled diagnostic and retrieval services.
- Endometriosis:Ectopic endometrial tissue compromises oocyte quality and implantation capacity, often necessitating surgical intervention prior to ART. Laparoscopic expertise concentration shapes referral patterns to academic medical centers.
- Male Infertility:Azoospermia and severe oligospermia drive demand for surgical sperm retrieval techniques including micro-TESE. Andrology laboratory capabilities determine clinic network competitiveness for this segment.
PCOS and hormonal disorders anchor current procedure volumes; male infertility represents the steepest expansion trajectory as diagnostic thresholds broaden.
Service Type:
Margin distribution follows the progression from information services through surgical intervention.
- Consultation:Initial reproductive endocrinology assessment establishes treatment candidacy and protocol selection. Telemedicine platforms are compressing geographic access constraints for preliminary evaluations.
- Diagnostics:Hormone panels, semen analysis, hysterosalpingography, and ovarian reserve testing inform prognosis and pathway selection. Third-party laboratory operators capture recurring revenue from independent physician practices.
- Egg Retrieval:Transvaginal ultrasound-guided follicular aspiration requires anesthesia support and ISO 5 cleanroom infrastructure. Asset-heavy requirements favor multi-site networks over independent entrants.
- Embryo Transfer:Catheter-based uterine cavity placement concludes IVF cycles with cryopreserved or fresh embryo deployment. Time-lapse incubation systems enable morphokinetic selection prior to this final procedural step.
Procedure revenue concentrates in retrieval and transfer; diagnostics and consultation are gaining share fastest through platform unbundling.
End User:
Capital intensity and regulatory burden stratify across facility types.
- Specialized Fertility Centers:Single-site or multi-location dedicated practices own complete embryology laboratory infrastructure and specialist staffing. Western European premium segments deploy advanced time-lapse incubation platforms as competitive differentiators.
- Hospitals:Academic medical centers and metropolitan hospital networks integrate fertility services within broader women's health portfolios. Employer-sponsored benefit expansion across United States metropolitan markets accelerates hospital network consolidation.
- Clinics:Independent or small-group practices without captive laboratory capacity refer complex cases to third-party embryology operators. Pay-per-cycle leasing models enable asset-light participation.
- Research Institutions:University-affiliated centers conduct clinical trials for culture media formulations, genetic screening algorithms, and cryopreservation techniques. FDA and EMA validation pathways originate from this segment.
Specialized fertility centers dominate current capacity; hospital network expansion is climbing the fastest as benefit structures reshape referral patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and Danish clinic networks where premium time-lapse incubation platforms command cycle premiums, while Spanish and Czech jurisdictions compete on cost-accessible retrieval services. This asymmetry drives patient mobility patterns across European borders. National reimbursement frameworks and employer benefit structures reshape where capital deploys.
United States
Employer-sponsored fertility benefits now cover over half of large self-insured corporations, normalizing multi-cycle IVF access across metropolitan hospital networks. FDA oversight of PGT-A algorithms and culture media formulations extends validation timelines for new market entrants. Boston and San Francisco clusters concentrate academic medical center capacity where research institutions originate clinical trial pathways.
Germany
Statutory health insurance covers three IVF cycles for women under 40, creating predictable demand volume for specialized fertility centers. EMA MDR framework imposes conformity assessment requirements on time-lapse platform manufacturers seeking CE marking. Munich and Hamburg metropolitan areas host multi-site clinic networks deploying advanced embryo monitoring systems as competitive differentiators.
Denmark
Public funding for fertility treatments achieves near-universal access, supporting high per-capita procedure rates and concentrated embryology expertise. EU AI Act risk classification rules categorize automated embryo grading algorithms as high-risk devices requiring notified body validation. Copenhagen anchors Nordic reproductive tourism flows with centralized laboratory infrastructure serving cross-border patients.
Spain
Liberal donor gamete regulations and cost-competitive cycle economics attract German, Italian, and UK couples seeking treatment accessibility. National quality accreditation programs for assisted reproduction laboratories standardize cleanroom infrastructure requirements. Barcelona and Madrid fertility clusters specialize in donor oocyte programs with shortened waiting periods versus Northern European alternatives.
Japan
Government subsidies for infertility treatment expand coverage to six cycles annually, reducing out-of-pocket burdens for aging demographic segments. PMDA regulatory pathways for genetic screening technologies require domestic clinical validation studies. Tokyo and Osaka metropolitan areas concentrate private clinic networks investing in time-lapse platform deployment to differentiate cycle outcomes.
Fertility Treatments Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in media, devices, and consumables. The vendor base stratifies between full-workflow owners and single-product suppliers. Three archetypes dominate: vertically integrated laboratory system providers, recombinant hormone manufacturers with captive distribution, and third-party laboratory operators leasing embryology capacity. Consolidation accelerates through multi-year consumable supply agreements and asset-light clinic network partnerships.
Within the integrated system tier, CooperSurgical Inc. and Vitrolife AB exemplify contrasting geographic anchoring—US-based and Swedish respectively—while Merck KGaA represents the pharmaceutical-specialist archetype concentrated in recombinant gonadotropin supply. These three occupy positions spanning the workflow from stimulation protocols through embryo culture, with each anchoring different margin capture points.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| Vitrolife AB |
| Merck KGaA |
| Ferring Pharmaceuticals |
| Thermo Fisher Scientific Inc. |
| FUJIFILM Irvine Scientific |
| Cook Group Inc. |
| Hamilton Thorne Ltd. |
| Esco Micro Pte. Ltd. |
| Others |
Pricing and Supply Chain Analysis
European recombinant gonadotropin manufacturers anchor upstream supply, concentrating pricing power with three specialized hormone suppliers whose biologic production constraints cascade into clinic margin compression downstream. This upstream bottleneck shapes how fertility networks allocate capital between consumable procurement and technology infrastructure.
Pricing Analysis
Configured-to-order pricing for customized stimulation protocols commands substantial premiums over standardized cycle packages at multi-site networks. Three-tier pricing structure across premium, standard, and economy levels separates time-lapse platform-enabled cycles from conventional incubation and from basic IUI alternatives. Price differentiation hinges on embryo monitoring technology tier and ISO certification grade of laboratory facilities. Cost compression in standard IVF tiers is intensifying because employer benefit administrators negotiate volume-based discounts with metropolitan hospital networks. Independent clinics without captive embryology capacity exhibit highest price sensitivity; premium fertility centers in Western Europe demonstrate least sensitivity due to differentiated outcome positioning.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities enable smaller clinic networks to access recombinant hormone inventories without immediate capital outlay. Manufacturing concentrates in Denmark, Switzerland, and Germany for biologic stimulation drugs, with media formulations sourcing from US and Swedish specialty chemical producers. Raw material dependencies include recombinant FSH analogs, pH-buffered culture media, and cryopreservation cryoprotectants. Single-source vulnerability characterizes gonadotropin supply given regulatory validation barriers for alternative manufacturers. Distribution runs through GPO-negotiated contracts with multi-site hospital systems and direct procurement relationships for independent specialized fertility centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Employer-sponsored benefit expansion functions as a substitute threat to traditional out-of-pocket fertility spending, forcing incumbents to defend service positioning against benefit administrators who commoditize cycle pricing.
For Market Incumbents: Build captive embryology capacity moats through ISO 5 cleanroom infrastructure ownership that third-party laboratory operators cannot replicate. Consolidate independent practices into multi-site networks to secure GPO-negotiated consumable pricing and defend against pay-per-cycle leasing entrants. Vertical integration into culture media formulation insulates margin pools from European hormone supplier concentration.
For New Entrants and Emerging Players: Eastern European jurisdictions with liberal donor gamete regulations and cost-accessible cycle economics offer the most penetrable geographic entry points. Target asset-light clinic partnerships in German and Italian source markets seeking cross-border treatment alternatives. Deploy AI-assisted embryo grading platforms as differentiated service offerings to bypass embryologist certification bottlenecks that constrain incumbent expansion.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pay-per-cycle leasing sub-segments as equipment-as-a-service models displace laboratory ownership. Long-term viability favors platform integrators with consumable recurring revenue over standalone device manufacturers. Acquisition target archetype: third-party laboratory operators with established GPO contracts and validated AI grading systems. Signal to watch: FDA premarket review timeline compression for PGT-A algorithms indicating regulatory pathway maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR conformity assessment unlocks EU commercialization for time-lapse platform vendors seeking Western European clinic penetration. |
| Hospital System Partnership | Metropolitan network integration captures employer-sponsored benefit volume as self-insured corporations standardize fertility coverage. |
| Software Companion Development | AI-assisted embryo grading algorithms automate morphokinetic assessment while navigating EU AI Act high-risk device classification. |
| Reimbursement Strategy | National health system contracting secures predictable demand volume in Germany and Denmark versus volatile private-pay markets. |
| FDA Submission | Premarket review pathway for PGT-A technologies shapes competitive timelines for genetic screening market entry. |
Research Methodology
Cross-validation between primary interviews with reproductive endocrinologists, embryology laboratory directors, hospital procurement managers, and benefit administrators anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and clinical trial registries for fertility intervention outcomes. Bottom-up procedure volume estimates from specialized fertility center networks triangulate against top-down national reimbursement data from statutory health insurance programs.
Calibration against historical cycle volume trajectories and regulatory approval timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type intensity, therapy area prevalence, service type margin distribution, and end-user facility configuration. CAGRs derive from fitted growth curves incorporating employer benefit expansion rates, embryology lab capacity constraints, and cross-border patient mobility patterns.
Practitioners should monitor reimbursement policy divergence between national health systems and private payers for early signals of geographic demand shift. Forecasts reflect assumptions regarding regulatory pathway stability, hormone supply continuity, and AI governance framework implementation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reproductive Health
Ovum Egg Banking Market
Reproductive Health
US Contraceptive Market
Reproductive Health
Assisted Reproductive Technology (ART) Market
Reproductive Health
Vaginal Exam Specula Market
Reproductive Health
Asia-Pacific in Vitro Fertilization (IVF) Market
Reproductive Health
UK in Vitro Fertilization (IVF) Market
Reproductive Health
US Sexual and Reproductive Health Clinics Market
Reproductive Health
Contraceptives Market
Reproductive Health
US Birth Centers Market
Reproductive Health
Cervical Dysplasia Treatment Market
Reproductive Health
Global Gynecology Drugs Market
Reproductive Health
Global Male Infertility Market
Reproductive Health
Europe in Vitro Fertilization (IVF) Market
Reproductive Health
Egg Donation Market
Reproductive Health
Pregnancy Care Products Market
Reproductive Health
Surrogacy Market