
 Japan Ultrasound Devices Market | 2026-2036
Japan Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Ultrasound Devices Market Foresight
The gap between premium imaging suites and handheld point-of-care units is repositioning procurement standards across Japanese healthcare networks. Canon Medical Systems Corporation leverages its domestic manufacturing base to sustain rapid fulfillment cycles for tier-one hospitals. Siemens Healthineers AG competes through specialized cardiovascular imaging protocols that anchor its installed base in university medical centers. Koninklijke Philips NV differentiates via integrated informatics platforms that control workflow efficiency across multi-site hospital groups.
Japan ultrasound devices generate anatomical and functional images through piezoelectric crystal arrays operating at frequencies between two and fifteen megahertz, with beamforming algorithms processing reflected acoustic signals into real-time grayscale or Doppler maps for diagnostic and interventional guidance. Diagnostic ultrasound systems dominate current revenue pools due to established reimbursement codes, while portable ultrasound segments exhibit the fastest expansion as clinics and emergency departments prioritize bedside accessibility. Three-dimensional ultrasound technology captures concentrated R&D investment from vendors seeking to displace conventional 2D systems in obstetric and cardiac applications.
PMDA's device approval pathways and METI's industrial standards frameworks shape product development timelines and clinical validation requirements for all marketed systems. JIS standards for electromagnetic compatibility and acoustic output safety constrain design choices while reinforcing quality benchmarks that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how Japan's reimbursement revision cycles and regional medical consolidation initiatives redistribute purchasing authority between independent clinics and hospital networks.
Market Dynamics
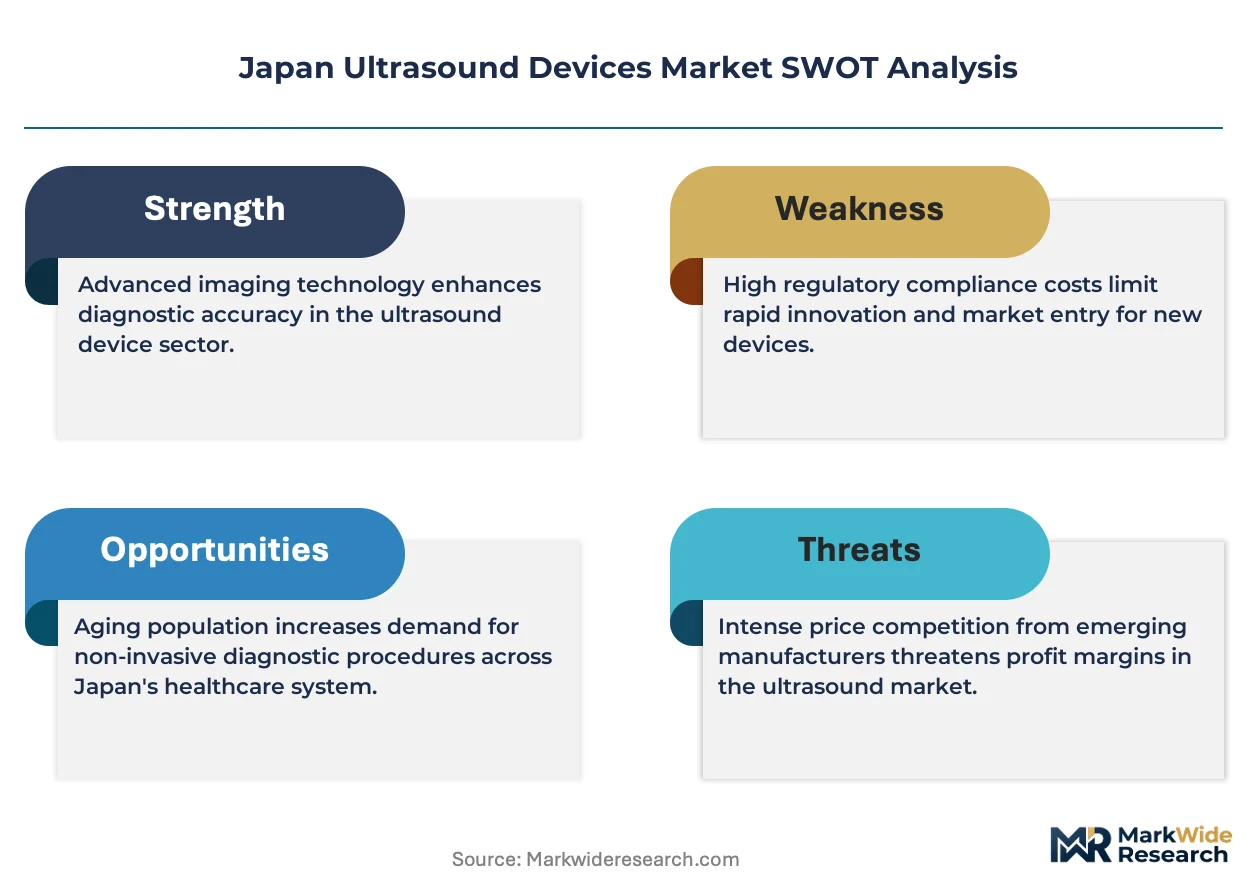
Japan's ultrasound device sector faces structural compression from METI's accelerated reimbursement revision cycles, which compress vendor margins while forcing rapid product refresh timelines across domestic manufacturers.
Growth Catalysts
- Point-of-care imaging protocols:Emergency departments and rural clinics in Hokkaido and Kyushu prioritize bedside diagnostic accessibility, expanding portable system deployment beyond traditional radiology suites.
- PMDA's priority review pathway:Streamlined approval timelines for AI-assisted diagnostic algorithms reduce time-to-market for software-enhanced imaging platforms.
- Obstetric screening mandates:Prefecture-level maternal health initiatives in Kanagawa and Osaka drive recurring system upgrades for fetal anomaly detection protocols.
Market Restraints
- Piezoelectric crystal supply concentration:Domestic sourcing of high-frequency transducer materials depends on limited specialty ceramic suppliers in Nagoya industrial clusters.
- JIS electromagnetic compatibility testing:Extended validation timelines for acoustic output safety certification delay product launches by 8-14 months versus comparable FDA pathways.
- CT and MRI substitution pressure:Tertiary hospitals in Tokyo increasingly favor cross-sectional imaging for complex cardiovascular assessments, constraining premium ultrasound expansion.
Strategic Opportunities
- Rural clinic digitization subsidies:METI's regional healthcare infrastructure grants fund portable system acquisition in underpenetrated Shikoku and Tohoku prefectures.
- Interventional guidance convergence:Integration of real-time ultrasound with minimally invasive surgical robotics creates new procedural revenue streams for university medical centers.
- Telemedicine-enabled remote interpretation:Cloud-based image transmission to centralized diagnostic hubs addresses specialist shortages in island communities.
Industry Challenges
- Sonographer workforce constraints:Japan Society of Ultrasonics in Medicine certification requirements outpace training program output, creating operational bottlenecks for high-volume screening facilities.
- Legacy PACS integration friction:Hospital information system vendors maintain proprietary data formats, complicating multi-manufacturer workflow standardization.
- Patent thickets in beamforming algorithms:Cross-licensing negotiations between semiconductor IP holders and device manufacturers extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Ultrasound Devices Market |
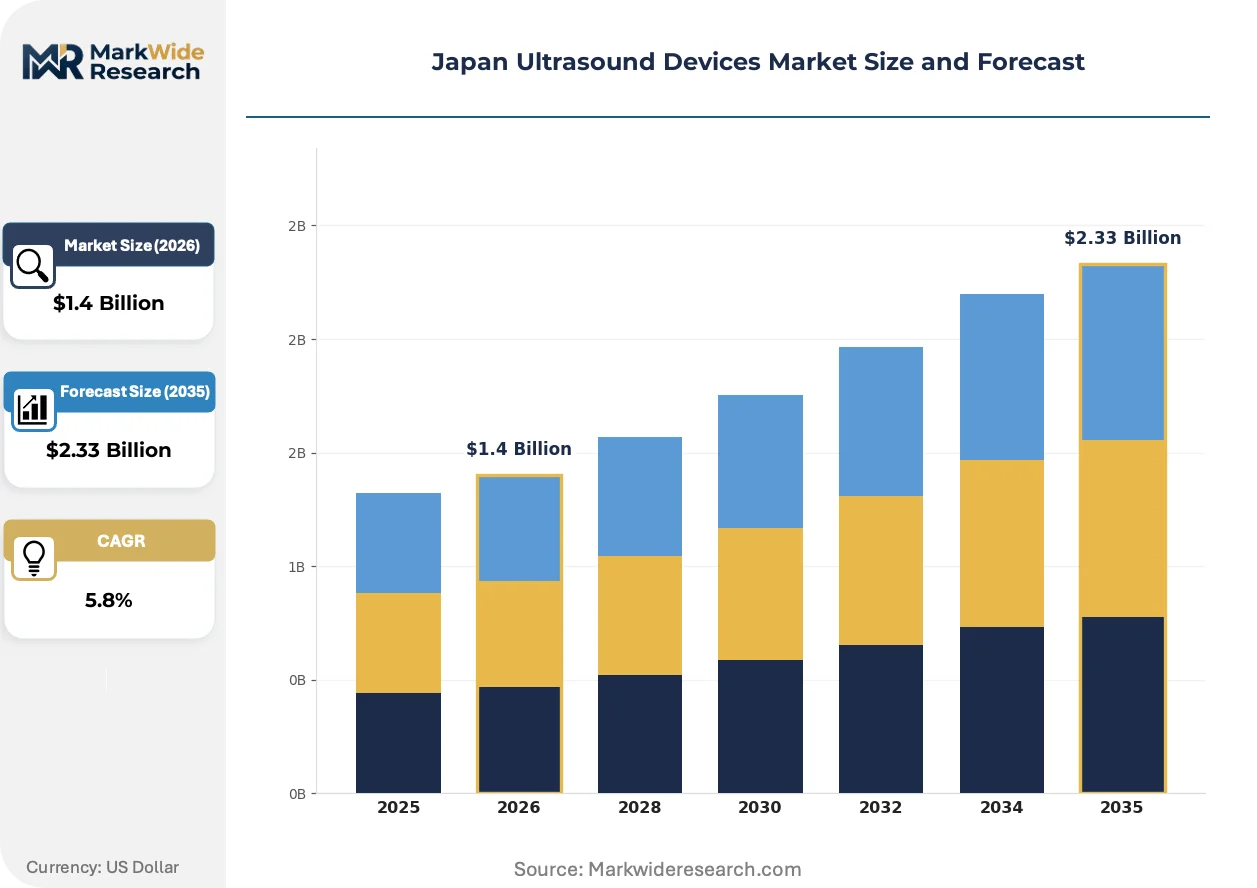
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 2D Ultrasound Application: Obstetrics, Cardiology, Abdominal Imaging, Musculoskeletal Imaging End User: Hospitals, Clinics, Imaging Centers, Research Institutions Technology: Digital Ultrasound, Analog Ultrasound, 3D Ultrasound, Doppler Ultrasound |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers AG, FUJIFILM Holdings Corporation, GE Healthcare, Koninklijke Philips NV, Hitachi Ltd., Hologic Japan Inc., Samsung Medison, Konica Minolta Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Ultrasound Devices Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into ultrasound hardware, compressing diagnostic decision timelines while reducing operator dependency across Japanese healthcare networks.
Shear wave elastography is integrating quantitative tissue stiffness mapping into routine abdominal and breast examinations. Community hospitals in Aichi and Fukuoka prefectures adopt these platforms to reduce unnecessary biopsy referrals. The technology is integrating automated stiffness scoring that bypasses operator interpretation variability, standardizing diagnostic thresholds across facilities with uneven specialist density.
METI's Medical Device Industry Vision 2025 mandates domestic production quotas for critical diagnostic equipment, accelerating local manufacturing investment. Component suppliers in Kansai industrial corridors expand cleanroom capacity for transducer assembly. Domestic vendors now prioritize JIS-certified supply chains over lower-cost offshore alternatives, reshaping procurement evaluation criteria for public hospital tenders.
Subscription-based equipment access models displace traditional capital purchase contracts among independent clinics in metropolitan peripheries. Leasing providers bundle maintenance, software updates, and remote technical support into per-procedure fee structures. Chiba and Saitama prefecture clinics demonstrate highest uptake, where liquidity constraints and unpredictable patient volumes favor operational expenditure over asset ownership.
Japan Ultrasound Devices Market Segmentation
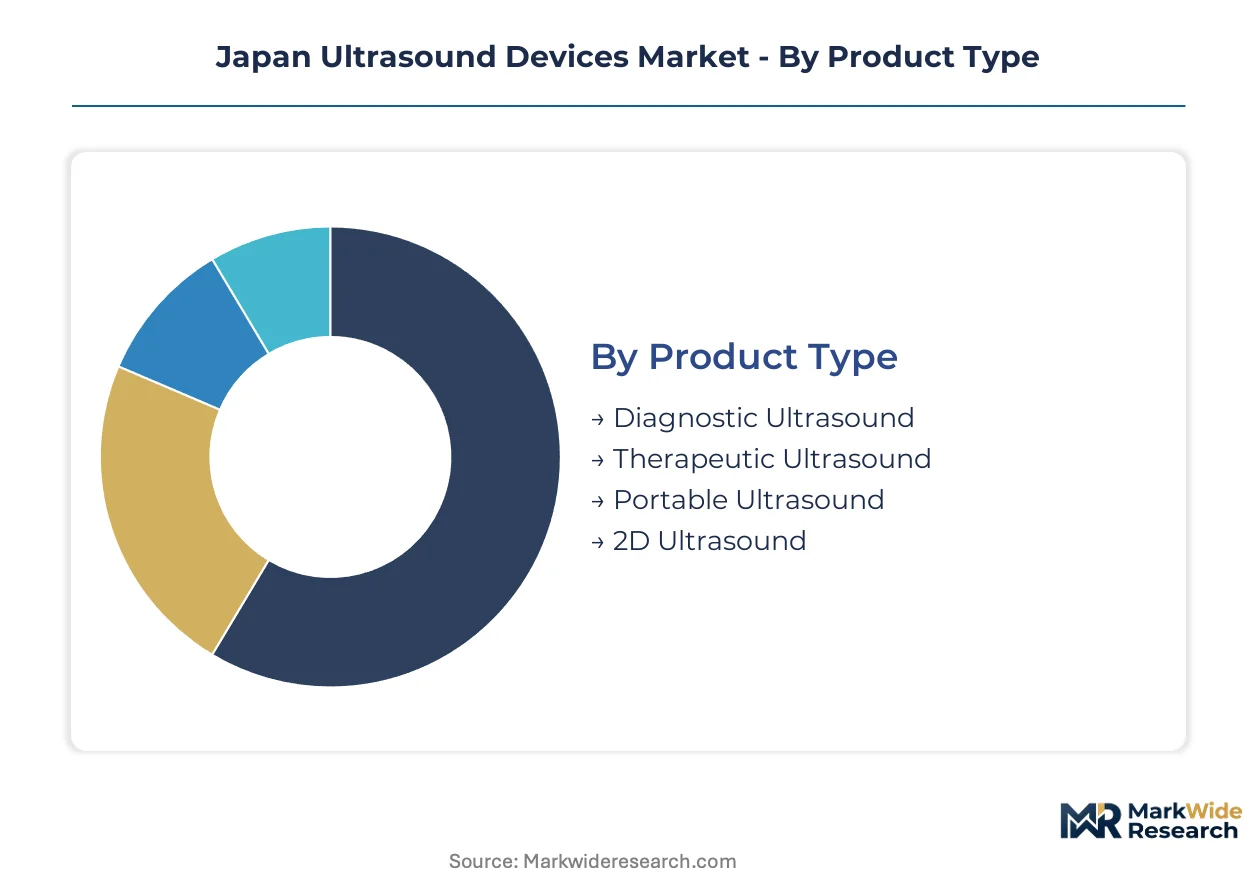
Ultrasound device segmentation in Japan reveals distinct procurement patterns across clinical settings. METI reimbursement tiers and JIS certification requirements create divergent upgrade cycles for each category. Understanding these segment boundaries clarifies where vendors must align product specifications with facility-level purchasing authority.
Product Type:
Replacement cycles vary sharply across product categories, with reimbursement eligibility driving hospital refresh timelines.
- Diagnostic Ultrasound:Stationary systems with 256-element transducer arrays and harmonic imaging capabilities anchor radiology department workflows. Tokyo and Osaka tertiary hospitals prioritize these platforms for high-throughput screening programs, though METI's biannual reimbursement revisions compress capital planning windows.
- Portable Ultrasound:Battery-powered units under 5kg with wireless DICOM transmission enable bedside and field deployment. Rural clinics in Hokkaido and Kyushu accelerate acquisition as prefectural digitization subsidies expand, bypassing traditional radiology infrastructure investments.
- Therapeutic Ultrasound:Focused acoustic delivery systems for physiotherapy and lithotripsy applications.
- 2D Ultrasound:Conventional grayscale imaging platforms with established reimbursement codes in obstetric screening.
Volume placements concentrate in Diagnostic Ultrasound; the faster expansion belongs to Portable Ultrasound.
Application:
Clinical application segments map directly to Japan's disease burden distribution and specialist availability patterns.
- Obstetrics:Fetal biometry and anomaly detection protocols dominate prefectural maternal health mandates. Kanagawa and Osaka facilities upgrade systems to meet enhanced nuchal translucency measurement standards, with PMDA streamlining approvals for AI-assisted gestational age estimation.
- Cardiology:Transthoracic and transesophageal echocardiography systems with strain imaging capabilities. University medical centers in Tokyo prioritize these platforms for heart failure monitoring, though CT coronary angiography substitution constrains premium ultrasound expansion in tertiary settings.
- Abdominal Imaging:Hepatic, renal, and pancreatic assessment protocols for general diagnostic screening.
- Musculoskeletal Imaging:Tendon, ligament, and joint evaluation for sports medicine and rheumatology clinics.
Obstetrics claims the largest installed base; Cardiology demonstrates the steepest technology refresh rate.
End User:
Facility type determines procurement channel access and capital availability under Japan's regional healthcare consolidation.
- Hospitals:Multi-department networks with centralized purchasing authority and dedicated biomedical engineering staff. Metropolitan corridor facilities in the Tokyo-Osaka axis drive premium system demand, leveraging economies of scale in maintenance contracting.
- Clinics:Independent practices and small group practices with constrained capital budgets. Chiba and Saitama prefecture clinics increasingly adopt subscription-based equipment access to convert capital expenditure into operational outflows.
- Imaging Centers:Dedicated diagnostic facilities with high patient throughput and rapid turnaround requirements.
- Research Institutions:Academic medical centers with prototype evaluation mandates and experimental protocol development.
Hospitals maintain procurement volume leadership; Clinics are gaining share fastest through alternative financing structures.
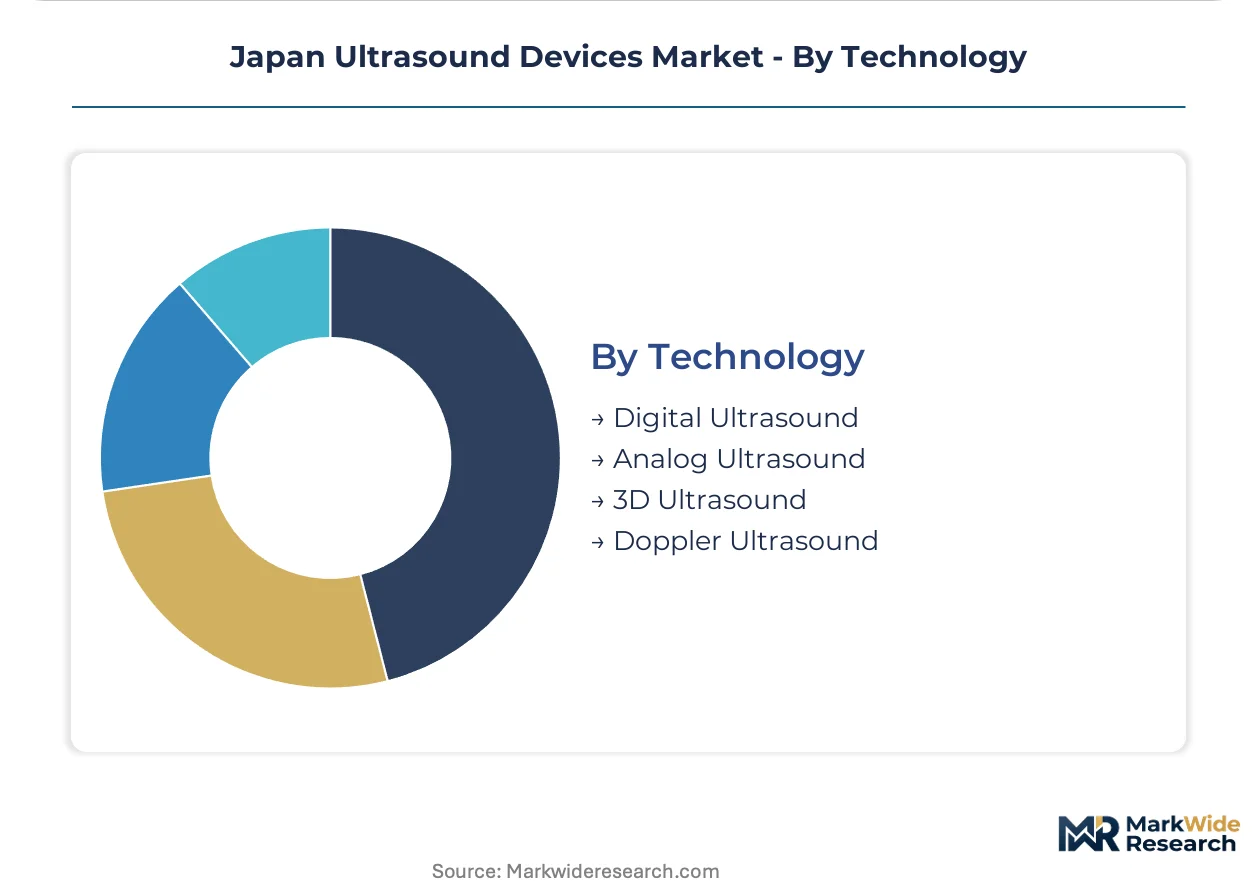
Technology:
Technology segmentation reflects the transition from analog legacy systems to software-defined imaging architectures.
- 3D Ultrasound:Volume rendering and multiplanar reconstruction capabilities for fetal facial imaging and cardiac structural assessment. Vendors concentrate R&D investment here to displace conventional 2D platforms in high-value obstetric and cardiac applications.
- Digital Ultrasound:FPGA-based beamforming with programmable frequency compounding and speckle reduction algorithms. These platforms dominate new installations as JIS electromagnetic compatibility standards phase out analog architectures.
- Analog Ultrasound:Legacy discrete component systems with fixed hardware signal paths.
- Doppler Ultrasound:Pulsed-wave and continuous-wave spectral analysis for vascular flow quantification.
Digital Ultrasound captures dominant placement share; 3D Ultrasound climbs the fastest as vendors target premium displacement opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors Japan's ultrasound device procurement, with metropolitan corridor hospitals driving premium system demand through concentrated aging patient populations and tier-one medical infrastructure.
Kanto/Tokyo
University medical centers and tertiary hospitals in Tokyo and Yokohama prioritize AI-enhanced imaging platforms for cardiovascular and obstetric applications. METI's reimbursement revision cycles compress capital planning windows to biannual refresh schedules. The Keihin industrial belt hosts concentrated biomedical engineering talent pools that accelerate PMDA regulatory submission preparation.
Kansai/Osaka
Prefecture-level maternal health mandates in Osaka and Kobe drive recurring ultrasound upgrades for fetal anomaly detection protocols. JIS electromagnetic compatibility certification requirements extend validation timelines for new product launches. The Hanshin manufacturing corridor sustains domestic transducer assembly operations with expanded cleanroom capacity.
Chubu/Nagoya
Piezoelectric crystal supply concentration in Nagoya industrial clusters creates procurement dependencies for high-frequency transducer materials. METI's Medical Device Industry Vision 2025 production quotas accelerate local manufacturing investment. Specialty ceramic suppliers in Aichi prefecture face capacity constraints as domestic sourcing mandates tighten.
Kyushu
Rural clinics in Fukuoka and surrounding prefectures accelerate portable ultrasound acquisition through METI regional healthcare infrastructure grants. Emergency departments prioritize bedside diagnostic accessibility over traditional radiology suite investments. Island communities adopt telemedicine-enabled remote interpretation to address specialist shortages.
Hokkaido
Remote healthcare facilities in Sapporo and northern prefectures deploy battery-powered portable units with wireless DICOM transmission capabilities. Prefectural digitization subsidies bypass conventional imaging infrastructure requirements. Sonographer workforce constraints create operational bottlenecks for high-volume screening programs.
Japan Ultrasound Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-certification matrix, with JIS-compliant domestic manufacturers commanding price premiums over import-dependent competitors. The vendor base stratifies into three tiers: integrated conglomerates with captive semiconductor supply, specialized imaging equipment pure-plays, and regional distributors with service-centric business models. Strategic moves concentrate on backward integration into transducer crystal production and software-defined imaging platform development.
Within the integrated conglomerate tier, Canon Medical Systems Corporation and Hitachi Ltd. exemplify domestic manufacturing scale advantages that compress fulfillment cycles for public hospital tenders. Siemens Healthineers AG anchors the European-origin specialist position, while Koninklijke Philips NV occupies a position emphasizing informatics-integrated workflow platforms. These three represent divergent archetypes: domestic vertical integration, protocol specialization, and software-ecosystem control.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers AG |
| FUJIFILM Holdings Corporation |
| GE Healthcare |
| Koninklijke Philips NV |
| Hitachi Ltd. |
| Hologic Japan Inc. |
| Samsung Medison |
| Konica Minolta Inc. |
| Others |
Supply & Pricing Matrix
Piezoelectric ceramic wafer costs cascade through three pricing tiers as specialty ceramic suppliers in Nagoya industrial clusters constrain upstream capacity. METI's domestic sourcing mandates force manufacturers to absorb premium JIS-certified material costs rather than offshore to lower-cost alternatives, compressing margins at the standard tier while insulating premium positions.
Pricing Analysis
Throughput-linked equipment leasing anchors value-based pricing for portable ultrasound deployments across Chiba and Saitama prefecture clinics. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced cardiovascular platforms from conventional grayscale systems and refurbished legacy units. Price differentiation hinges on JIS electromagnetic compatibility certification grade and bundled remote technical support tiers. Cost compression in the economy tier is intensifying because subscription-based per-procedure models displace capital purchase contracts. Independent clinics demonstrate highest price sensitivity; university medical centers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Direct-to-hospital channels handle tier-one procurement from Tokyo-Osaka corridor facilities, while regional distributors serve rural clinic networks in Kyushu and Hokkaido. Manufacturing concentration centers on Japan, Germany, and the Netherlands for beamforming semiconductors and FPGA signal processors. Raw material dependencies include lead zirconate titanate crystals, high-purity alumina substrates, and medical-grade silicone encapsulants. Single-source vulnerability in Nagoya-based specialty ceramic suppliers creates procurement bottlenecks during capacity expansion cycles. Distribution runs through authorized service organizations with JIS-certified biomedical engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric crystal cleanroom capacity constraints prop pricing power for domestic vendors with captive transducer production. Supply scarcity in high-frequency ceramic arrays prevents price erosion despite METI's reimbursement compression cycles.
For Market Incumbents: Anticipate CT coronary angiography substitution pressure in Tokyo tertiary hospitals by accelerating shear wave elastography R&D for abdominal applications. Backward integration into transducer crystal production secures supply continuity against Nagoya supplier capacity constraints. Defend installed base through PACS integration partnerships that complicate multi-manufacturer workflow standardization for competitors. For New Entrants and Emerging Players: The mid-tier pricing gap between premium AI-enhanced platforms and economy refurbished units creates entry space for digital beamforming specialists with FPGA-based architectures. Rural clinic digitization subsidies in Shikoku and Tohoku prefectures offer the most penetrable geography with streamlined procurement pathways. Target subscription-based equipment access models with bundled sonographer training to bypass capital budget constraints. For Investors and Strategic Acquirers: METI's Medical Device Industry Vision 2025 production quota announcements are the leading indicator that domestic manufacturing scale advantages will consolidate procurement share. Long-term viability favors integrated conglomerates with captive semiconductor supply and JIS regulatory affairs expertise. Acquisition targets should display cleanroom transducer assembly capabilities and established GPO contracts with metropolitan hospital networks. Watch for PMDA priority review pathway expansion for AI-assisted diagnostic algorithms as the inflection signal for software-enhanced platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | Accelerates PMDA approval timelines and unlocks public hospital tender eligibility. |
| Backward Integration into Transducer Production | Captures Nagoya ceramic supplier margins and insulates against capacity bottlenecks. |
| Software Companion Development | Positions platforms for METI's AI-assisted diagnostic reimbursement tier expansion. |
| Hospital System Partnership | Secures multi-year maintenance contracts across Tokyo-Osaka corridor networks. |
| Reimbursement Strategy Alignment | Aligns product refresh cycles with METI's biannual revision calendar. |
Research Methodology
Hospital procurement databases, PMDA device approval filings, and METI industrial statistics formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and sonography department heads validated installation data and refresh cycle assumptions. Bottom-up triangulation across facility-level procurement records and top-down reconciliation against vendor shipment disclosures anchored volume estimates.
Bottom-up modeling of installed base by product type, application, and end-user facility tier generated segment-level projections across the analysis window. Segmentation dimensions included technology architecture, clinical application, and regional prefecture clustering. CAGRs derived from regression analysis of historical replacement cycles against reimbursement revision timing. Forecast inputs incorporated METI regional healthcare infrastructure grant disbursement patterns and PMDA priority review pathway expansion indicators.
Inputs from hospital procurement databases and vendor regulatory filings were available through the study window; gaps in real-time sonographer workforce training program output introduce uncertainty bands around portable system adoption velocity. Forecasts reflect assumptions regarding reimbursement stability and ceramic supplier capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ventilator Accessories Market
Medical Devices
EEG Electrodes Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Interlaminar Device Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
South Korea Ophthalmic Devices Market