
 LASIK Eye Surgery Devices Market | 2026-2036
LASIK Eye Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
LASIK Eye Surgery Devices Market Analysis
Wavefront-guided precision tier is reorganizing competitive dynamics in LASIK device procurement. Alcon, Inc. leverages its integrated excimer-femtosecond platform to dominate premium clinic installations across North America. SCHWIND eye-tech-solutions GmbH anchors its position through specialized topography-linked ablation software that differentiates European refractive centers. NIDEK CO., LTD. competes on manufacturing scale, sustaining cost advantages in Asia-Pacific ambulatory settings.
LASIK eye surgery devices comprise laser systems that reshape corneal stroma through programmed photoablation, typically operating at 193 nm wavelength with pulse durations under 500 femtoseconds for flap creation and tissue removal. These instruments correct refractive errors by altering corneal curvature to focus light precisely on the retina, serving myopia, hyperopia, and astigmatism patients in outpatient ophthalmology. Femtosecond laser systems command the largest installed base among device types, while wavefront-guided laser configurations capture the fastest expansion as clinics upgrade from standard LASIK technology toward customized ablation profiles. Blade-free technology segments attract disproportionate margin pools because patients self-select premium pricing for all-laser procedural safety positioning.
FDA premarket notification requirements govern device commercialization in the United States, while EMA medical device regulations and CE marking directives shape European market access for excimer and femtosecond platforms. Japan's PMDA enforces stringent clinical trial standards that delay entry but validate long-term safety profiles for domestic ophthalmology adoption. Stakeholders must monitor evolving reimbursement rulings from national health technology assessment bodies, as these determinations increasingly dictate whether wavefront-guided and custom LASIK technologies receive covered status versus out-of-pocket patient payment.
Market Dynamics
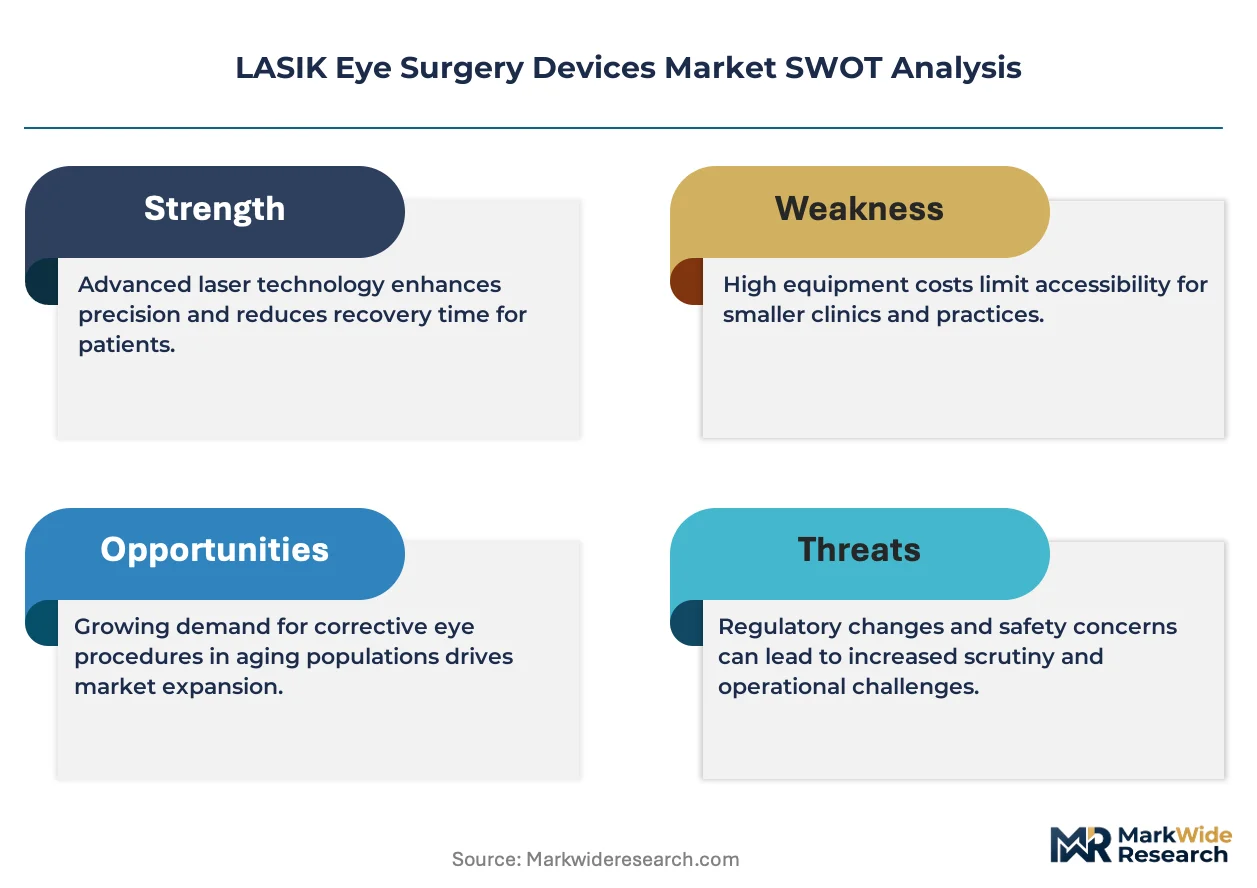
Wavefront-guided ablation platforms are compressing margins on standard excimer systems while expanding addressable patient pools through expanded myopia range correction. Clinics face simultaneous pressure to upgrade femtosecond flap creation hardware and absorb extended FDA 510(k) review timelines for software-enabled topography integration.
Growth Catalysts
- FDA streamlined review pathways:The 510(k) premarket notification framework accelerates clearance for iterative excimer laser software updates, reducing time-to-market for topography-linked ablation algorithms in United States refractive centers.
- Femtosecond precision adoption:Blade-free flap creation technology eliminates microkeratome-related complications, driving patient self-selection toward premium-priced all-laser procedures in ambulatory surgery settings.
- South Korea's health technology assessment integration:National reimbursement rulings from the Health Insurance Review and Assessment Service validate wavefront-guided platforms for covered vision correction, expanding clinic procurement budgets.
Market Restraints
- Excimer laser consumable cost concentration:High-purity argon-fluoride gas supply chains cluster in German and Japanese specialty chemical producers, creating input price volatility for 193 nm wavelength system operators.
- PMDA clinical trial duration:Japan's Pharmaceuticals and Medical Devices Agency mandates extended 24-month follow-up studies for novel ablation profiles, delaying market entry and freezing capital in regulatory compliance.
- Phakic intraocular lens substitution:Implantable collamer lenses attract high-myopia patients excluded from LASIK candidacy, siphoning volume from corneal reshaping procedures in Asian markets.
Strategic Opportunities
- India's refractive surgery infrastructure gap:Underpenetrated tier-2 cities lack femtosecond laser density, creating first-mover advantage for equipment-lease models targeting ophthalmology chains in Maharashtra and Karnataka.
- Topography-guided wavefront convergence:Integration of Scheimpflug imaging with Hartmann-Shack aberrometry enables single-platform custom ablation, reducing capital footprint for mid-sized European clinics.
- European Union Medical Device Regulation incentive alignment:MDR Article 83 post-market surveillance requirements favor manufacturers with embedded real-time treatment tracking, rewarding connected-device architectures.
Industry Challenges
- Corneal biomechanics specialist scarcity:Interpretation of tomographic ectasia risk indicators requires advanced training that outpaces fellowship program output in United States academic medical centers.
- Excimer-femtosecond platform integration complexity:Synchronization of flap creation depth with ablation profile demands proprietary software bridges that fragment service protocols across multi-vendor installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LASIK Eye Surgery Devices Market |
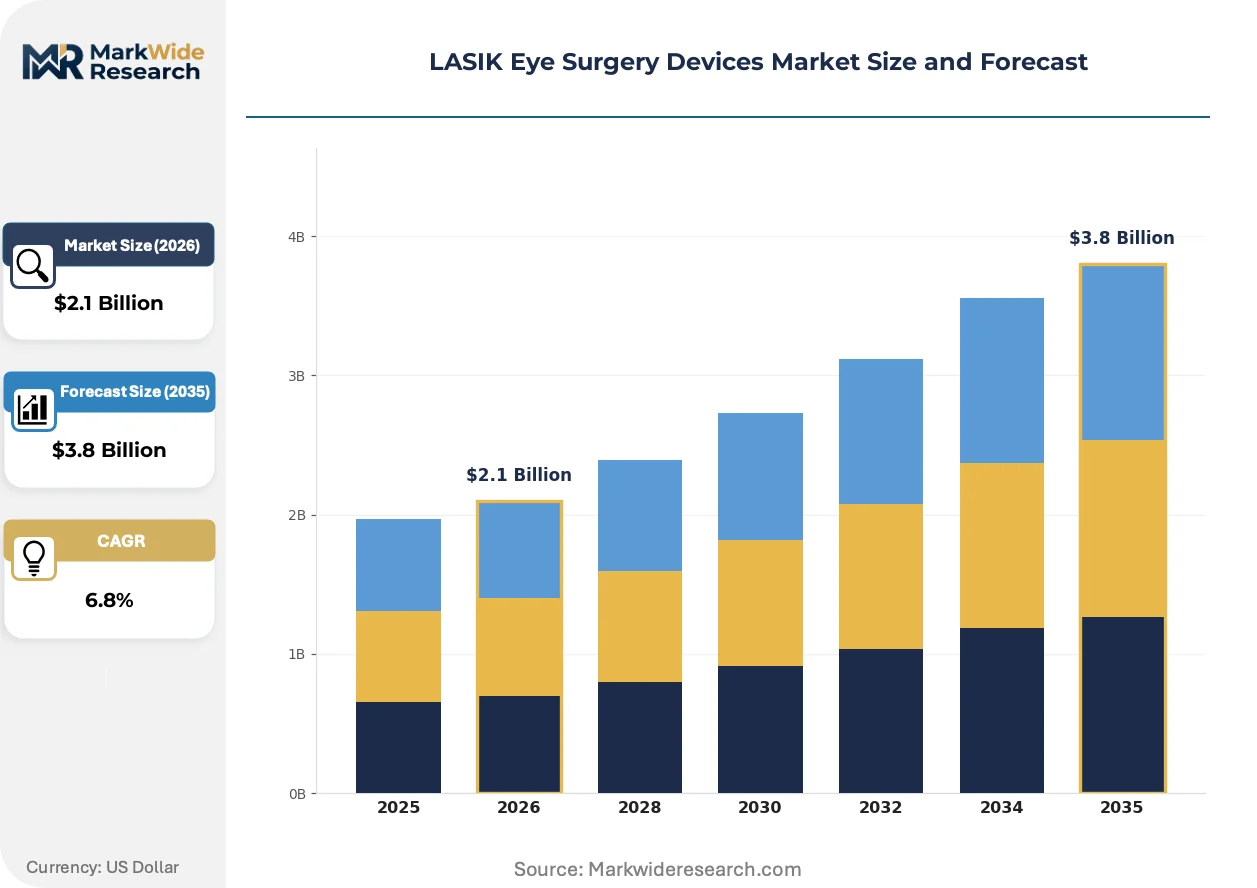
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Femtosecond Laser, Excimer Laser, Wavefront-Guided Laser, Laser System Application: Myopia, Hyperopia, Astigmatism, Presbyopia End User: Hospitals, Clinics, Ambulatory Surgical Centers, Eye Care Centers Technology: Blade-Free Technology, Custom LASIK Technology, Standard LASIK Technology, Laser-Assisted Technology |
| Companies Covered | Bausch + Lomb, SCHWIND eye-tech-solutions GmbH, Alcon, Inc., Topcon Corporation, Ziemer Ophthalmic Systems AG, Carl Zeiss Meditec AG, NIDEK CO., LTD., Lumenis Ltd., Johnson & Johnson Vision Care, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LASIK Eye Surgery Devices Market Emerging Trajectories
Digital diagnostic integration is collapsing the boundary between preoperative screening and surgical planning, enabling real-time ablation adjustments. This convergence demands new data governance frameworks and reshapes competitive advantage toward software-driven precision.
Femtosecond laser technology is bifurcating the installed base between premium all-laser suites and legacy microkeratome-compatible excimer systems. High-volume United States ambulatory surgery centers adopt integrated platforms for throughput optimization, while independent European practices retain modular configurations for cost flexibility. This technology is bifurcating service revenue streams between hardware maintenance contracts and per-procedure software licensing.
European Union Medical Device Regulation (MDR) Class IIb reclassification requirements impose clinical evidence burdens on excimer laser software updates. Manufacturers must submit post-market performance data for topography-guided algorithms, extending development cycles by 12-18 months. German refractive centers respond by consolidating procurement around established vendors with robust quality management systems.
Patient acquisition channels are fragmenting from ophthalmologist referrals toward direct-to-consumer digital platforms. Aggregator websites in South Korea and Spain now bundle preoperative screening, financing, and surgeon matching, compressing traditional clinic marketing budgets. This disintermediation concentrates volume in platform-affiliated practices while marginalizing independent operators lacking digital infrastructure investment.
LASIK Eye Surgery Devices Market Segmentation
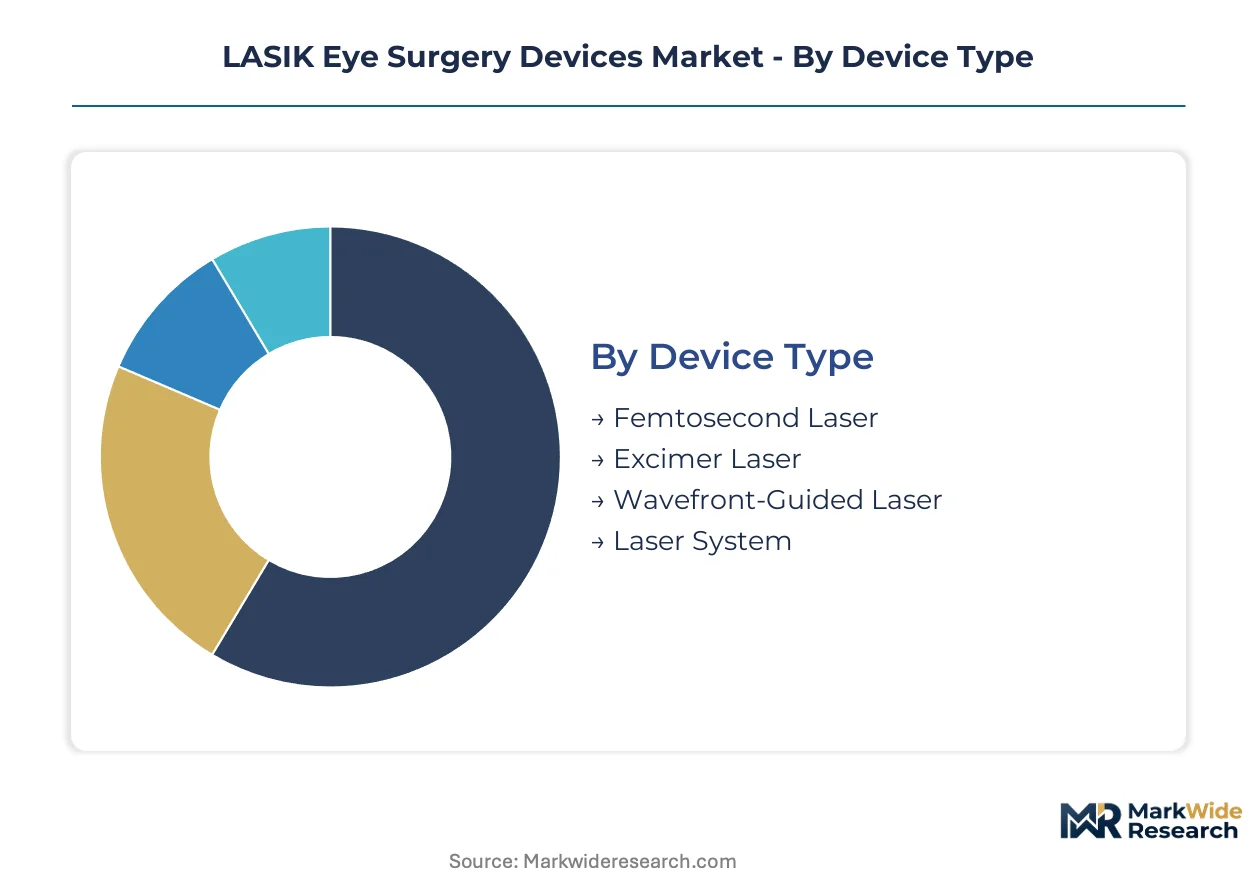
Device categorization in LASIK markets determines capital allocation patterns across refractive surgery providers. Procurement decisions hinge on technology maturity, regulatory clearance status, and reimbursement alignment for specific vision correction modalities.
Device Type:
Femtosecond laser systems dominate domestic installations in the United States and Germany, while excimer platforms retain stronger export orientation toward emerging markets. Wavefront-guided configurations concentrate demand in South Korea and Japan where health technology assessment bodies validate premium pricing.
- Femtosecond Laser:Operating at pulse durations under 500 femtoseconds, these systems create corneal flaps through photodisruption rather than mechanical cutting. United States ambulatory surgery centers prioritize blade-free platforms for patient safety positioning and premium pricing capture.
- Wavefront-Guided Laser:Hartmann-Shack aberrometry enables customized ablation profiles mapped to individual optical aberrations. South Korea's Health Insurance Review and Assessment Service reimbursement rulings accelerate clinic procurement cycles for these advanced configurations.
- Excimer Laser:193 nm argon-fluoride gas discharge systems remain the workhorse for stromal photoablation.
- Laser System:Integrated platforms combining diagnostic imaging with treatment delivery reduce capital footprint for mid-volume practices.
Femtosecond laser systems hold the largest share; momentum sits with wavefront-guided configurations.
Application:
Cost tier stratification separates premium custom ablation for complex refractive errors from standard procedures for straightforward myopia correction. Insurance coverage gaps drive out-of-pocket payment concentration in hyperopia and presbyopia segments.
- Myopia:Corneal flattening through central tissue removal corrects nearsightedness across the widest patient eligibility range. Asian markets concentrate procedure volume, though phakic intraocular lens substitution siphons high-diopter cases exceeding safe tissue removal thresholds.
- Astigmatism:Toric ablation profiles address corneal asymmetry through selective steep-axis tissue removal. European refractive centers report strong patient self-selection toward topography-guided platforms for mixed astigmatism cases.
- Hyperopia:Peripheral corneal steepening requires deeper ablation zones with extended healing protocols.
- Presbyopia:Monovision or multifocal ablation strategies target accommodation loss in patients over 40.
Myopia correction commands the largest procedure volume; presbyopia applications are climbing the fastest as demographic aging expands candidacy pools.
End User:
Volume concentration varies sharply by facility type, with high-throughput ambulatory centers achieving equipment utilization rates that independent practices cannot match. Customer type determines service contract structures and software licensing terms.
- Ambulatory Surgical Centers:Dedicated ophthalmology facilities optimize femtosecond laser throughput through scheduled procedure blocks and dedicated nursing staff. United States Medicare reimbursement differentials favor these settings over hospital outpatient departments.
- Clinics:Independent refractive practices prioritize modular device configurations preserving vendor flexibility. German clinic chains consolidate procurement around established excimer-femtosecond platform vendors to simplify service protocols.
- Hospitals:Academic medical centers balance research mandates against commercial procedure volume.
- Eye Care Centers:Optometry-ophthalmology integrated models capture preoperative screening and postoperative care revenue.
Ambulatory surgical centers hold the largest share; momentum sits with specialized eye care centers pursuing vertical integration into surgical services.
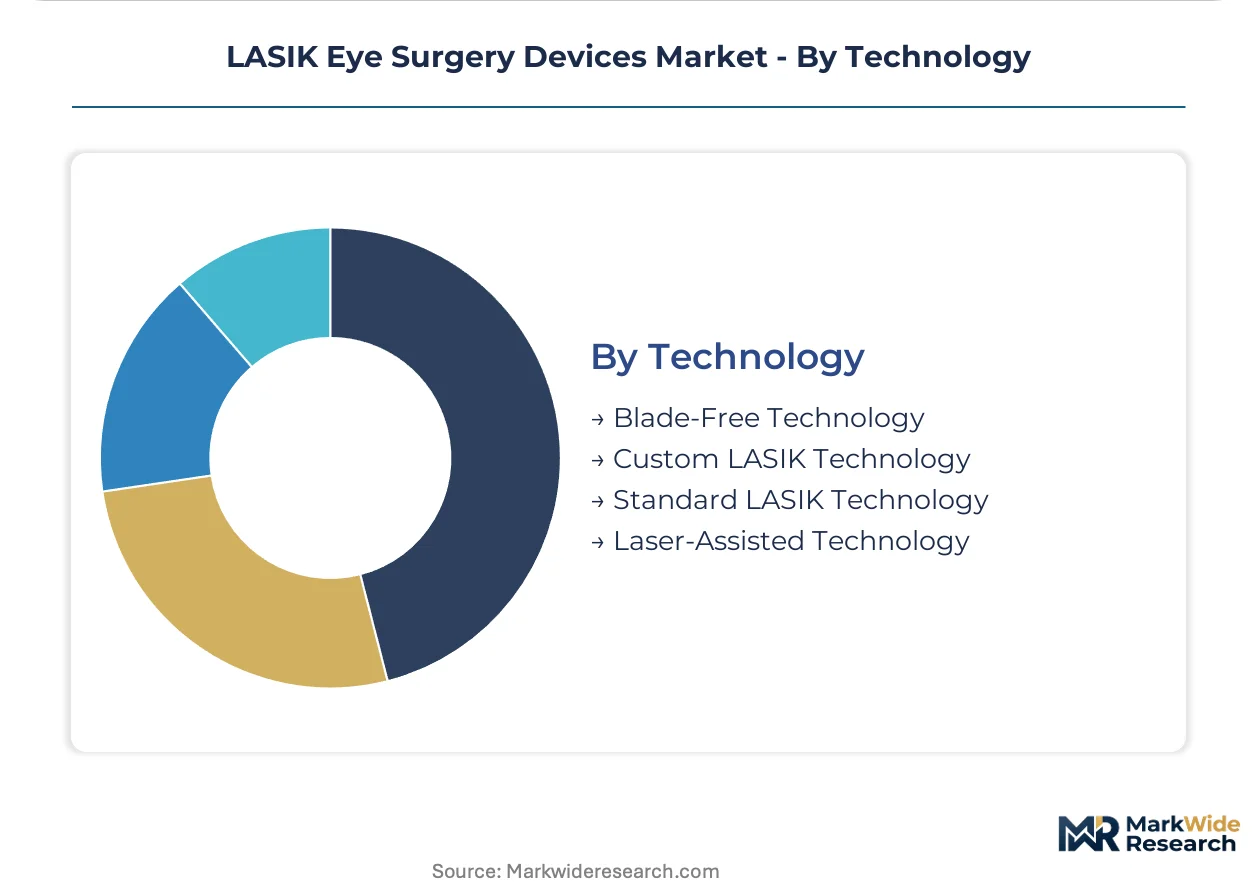
Technology:
Supply concentration in laser source manufacturing creates margin pressure differential across technology tiers. German and Japanese specialty gas producers dominate argon-fluoride supply chains for excimer systems.
- Blade-Free Technology:All-laser procedural positioning eliminates microkeratome mechanical failure modes and expands patient self-selection toward premium pricing tiers. FDA 510(k) streamlined review pathways accelerate iterative femtosecond platform clearances.
- Custom LASIK Technology:Wavefront and topography integration enables aberration-specific tissue removal beyond conventional spherocylindrical correction. European Union Medical Device Regulation post-market surveillance requirements extend software update cycles for these algorithm-dependent systems.
- Standard LASIK Technology:Conventional excimer ablation with microkeratome flap creation retains cost advantages in price-sensitive markets.
- Laser-Assisted Technology:Broad category encompassing femtosecond-enabled procedures across multiple laser platforms.
Blade-free technology holds the largest share; momentum sits with custom LASIK configurations as clinics upgrade diagnostic integration capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German excimer laser manufacturers export precision optical systems to refractive surgery clinics across South Korea and Japan, while United States femtosecond platforms flow into ambulatory centers throughout North America and select European markets.
United States
FDA 510(k) streamlined review pathways accelerate iterative software clearances for topography-linked ablation algorithms. Medicare reimbursement differentials favor ambulatory surgery centers over hospital outpatient departments for refractive procedures. High-volume LASIK chains in Florida and Texas optimize femtosecond laser throughput through scheduled procedure blocks.
Germany
EMA medical device regulations and CE marking directives govern excimer and femtosecond platform commercialization across European markets. EU MDR Class IIb reclassification requirements impose clinical evidence burdens on laser software updates. Refractive surgery clusters in Bavaria and Baden-Württemberg consolidate procurement around established vendors with robust quality management systems.
South Korea
Health Insurance Review and Assessment Service reimbursement rulings validate wavefront-guided platforms for covered vision correction, expanding clinic procurement budgets. Domestic health technology assessment bodies shape patient access to advanced ablation technologies. Seoul Capital Area ophthalmology chains drive premium technology adoption through direct-to-consumer digital patient acquisition platforms.
Japan
PMDA mandates extended 24-month follow-up studies for novel ablation profiles, delaying market entry but validating long-term safety profiles. Stringent clinical trial standards create regulatory barriers that favor established manufacturers with compliant quality systems. Kanto region academic medical centers balance research mandates against commercial procedure volume for excimer-femtosecond platforms.
India
Underpenetrated tier-2 cities lack femtosecond laser density, creating first-mover advantage for equipment-lease models targeting ophthalmology chains. CDSCO medical device regulations govern import and commercialization of laser surgical equipment. Maharashtra and Karnataka refractive surgery markets show concentration of diagnostic-integrated platform installations in Mumbai and Bangalore metropolitan clusters.
LASIK Eye Surgery Devices Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and software integration capabilities. The vendor base organizes around three tiers: diversified ophthalmology conglomerates with integrated diagnostic-surgical platforms, specialized laser manufacturers with proprietary ablation algorithms, and regional equipment distributors with service-centric business models. Dominant competitive moves include strategic partnerships for diagnostic software integration and geographic expansion through equipment-lease financing structures.
Within the integrated platform tier, Alcon, Inc. and Carl Zeiss Meditec AG exemplify diversified ophthalmology conglomerates with broad refractive surgery portfolios. SCHWIND eye-tech-solutions GmbH occupies a position among specialized European laser manufacturers with topography-linked software differentiation. NIDEK CO., LTD. represents manufacturing-scale specialists competing on cost advantages in Asia-Pacific ambulatory settings.
| Leading Market Players |
|---|
| Bausch + Lomb |
| SCHWIND eye-tech-solutions GmbH |
| Alcon, Inc. |
| Topcon Corporation |
| Ziemer Ophthalmic Systems AG |
| Carl Zeiss Meditec AG |
| NIDEK CO., LTD. |
| Lumenis Ltd. |
| Johnson & Johnson Vision Care, Inc. |
| Others |
Supply Flow & Price Mechanics
Six-to-nine month order-to-delivery cycles for femtosecond laser platforms concentrate pricing power with German and Japanese OEMs while compressing procurement flexibility for United States ambulatory surgery centers negotiating capital equipment budgets. This lead-time structure reinforces premium positioning for integrated diagnostic-surgical systems against modular alternatives.
Pricing Analysis
Industrial OEM buyers anchor equipment-lease pricing structures across mid-volume refractive practices seeking to preserve capital flexibility. Pricing stratifies across premium integrated platforms, standard modular configurations, and economy-tier refurbished systems based on FDA clearance tier and service bundling depth. Cost compression in standard excimer segments is intensifying because wavefront-guided upgrades capture disproportionate margin pools. Price-sensitive independent European clinics defer procurement during reimbursement uncertainty, while least-sensitive high-volume United States chains absorb premium positioning for throughput optimization.
Supply Chain Analysis
Germany and Japan anchor precision optical component fabrication for excimer and femtosecond laser sources, while United States manufacturers concentrate on software-enabled diagnostic integration modules. High-purity argon-fluoride gas feeds from German and Japanese specialty chemical producers, with precision motion control hardware sourcing from Swiss and Taiwanese suppliers. Single-source vulnerability concentrates in argon-fluoride supply chains subject to export licensing friction. Distribution runs through authorized dealer networks with embedded field service engineering rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wavefront-guided platform proliferation constitutes a high-growth disruption as FDA streamlined review pathways compress software update cycles and health technology assessment bodies validate premium reimbursement tiers.
For Market Incumbents: Consolidate diagnostic-surgical platform integration through proprietary software bridges that synchronize femtosecond flap creation with topography-linked ablation algorithms, neutralizing multi-vendor service fragmentation. Deepen backward integration into argon-fluoride gas supply through long-term offtake agreements with German and Japanese specialty chemical producers, mitigating input price volatility that threatens standard excimer system margins. For New Entrants and Emerging Players: Anchor in India's underpenetrated tier-2 cities where Maharashtra and Karnataka ophthalmology chains lack femtosecond laser density and equipment-lease models unlock first-mover positioning. Target presbyopia correction applications climbing fastest as demographic aging expands candidacy pools, deploying direct-to-consumer digital patient acquisition platforms that bypass traditional ophthalmologist referral channels. For Investors and Strategic Acquirers: Long-term, this sits as a software-driven precision play because diagnostic-surgical convergence rewards connected-device architectures with embedded real-time treatment tracking that satisfy EU MDR post-market surveillance requirements. Monitor health technology assessment reimbursement rulings from South Korea's Health Insurance Review and Assessment Service and analogous bodies as the critical signal for wavefront-guided platform adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlined Submission | Accelerates topography-linked ablation algorithm clearances for United States refractive centers. |
| Equipment-Lease Financing Structure | Unlocks capital-constrained clinic procurement in India's underpenetrated tier-2 metropolitan clusters. |
| Diagnostic-Surgical Platform Integration | Reduces capital footprint for mid-sized European clinics through single-vendor service protocols. |
| Health Technology Assessment Alignment | Validates wavefront-guided reimbursement coverage through South Korean national payer integration. |
| Real-Time Treatment Tracking Architecture | Satisfies EU MDR Article 83 post-market surveillance requirements for software-enabled systems. |
Methodological Framework
A spread of perspectives from femtosecond laser OEM product managers, refractive surgery clinic procurement directors, hospital biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning demand forecasts. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and national health technology assessment body rulings. Bottom-up equipment installation tracking and top-down refractive procedure volume estimates were triangulated to anchor market sizing.
Segmentation dimensions modeled span device type, application, end-user facility category, and technology tier across the projection horizon. CAGRs were derived from procedure volume elasticity to reimbursement access, equipment replacement cycles, and technology upgrade adoption curves. Forecast inputs incorporated wavefront-guided platform penetration rates, phakic intraocular lens substitution effects in high-myopia segments, and femtosecond laser installed base expansion trajectories.
Material uncertainties — regulatory delays in PMDA clinical trial timelines, argon-fluoride supply disruptions, and health technology assessment reimbursement reversals — sit outside the modeled envelope. Forecasts reflect assumptions about continued FDA streamlined review pathway availability and stable European Union Medical Device Regulation enforcement intensity. Recalibration cycles align with material shifts in national reimbursement rulings and specialty gas supply chain configuration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Single-Use Assemblies Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Global Thermodilution Catheter Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Slip Disc Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Pocket Otoscope Market