
 Wireless Neurofeedback Device Market | 2026-2036
Wireless Neurofeedback Device Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Neurofeedback Device Market Insights
US semiconductor foundry allocation for biosignal processing chips is hardening as wearable EEG demand outstrips specialty wafer supply. EMOTIV leverages vertically integrated hardware-software stacks to sustain design-to-shipment velocity. NeuroSky anchors its position through low-cost sensor modules that dominate consumer price tiers. Myndlift Ltd. competes by specializing in remote therapeutic monitoring protocols for licensed clinicians.
Wireless neurofeedback devices combine non-invasive brain activity sensors with real-time signal processing and Bluetooth or Wi-Fi transmission to deliver operant conditioning protocols. EEG headsets typically sample cortical electrical activity at 256–512 Hz, apply artifact rejection algorithms, and render feedback through auditory, visual, or haptic modalities to modulate attention, arousal, or affective states. Wearable headsets command the dominant value share due to hardware margin concentration and recurring software subscription attach rates. Mobile applications represent the fastest-expanding delivery mode as smartphone computational power eliminates dedicated base station requirements. Software platforms concentrate margin pools through longitudinal data analytics and clinician dashboard licensing.
FDA 510(k) clearance requirements for medical-grade EEG devices shape product architecture decisions and predicate device selection for manufacturers targeting clinical channels. The EU Medical Device Regulation and FCC Part 15 emissions standards jointly determine antenna design, biocompatibility materials, and electromagnetic compatibility testing burdens for cross-border commercialization. Stakeholders must monitor evolving HIPAA interoperability rules and GDPR health data classifications as cloud-based neurofeedback platforms expand remote patient monitoring footprints.
Market Dynamics
Semiconductor foundry allocation for biosignal processing chips is hardening as wearable EEG demand outstrips specialty wafer supply, compressing product development timelines and forcing architecture trade-offs between sampling fidelity and power consumption.
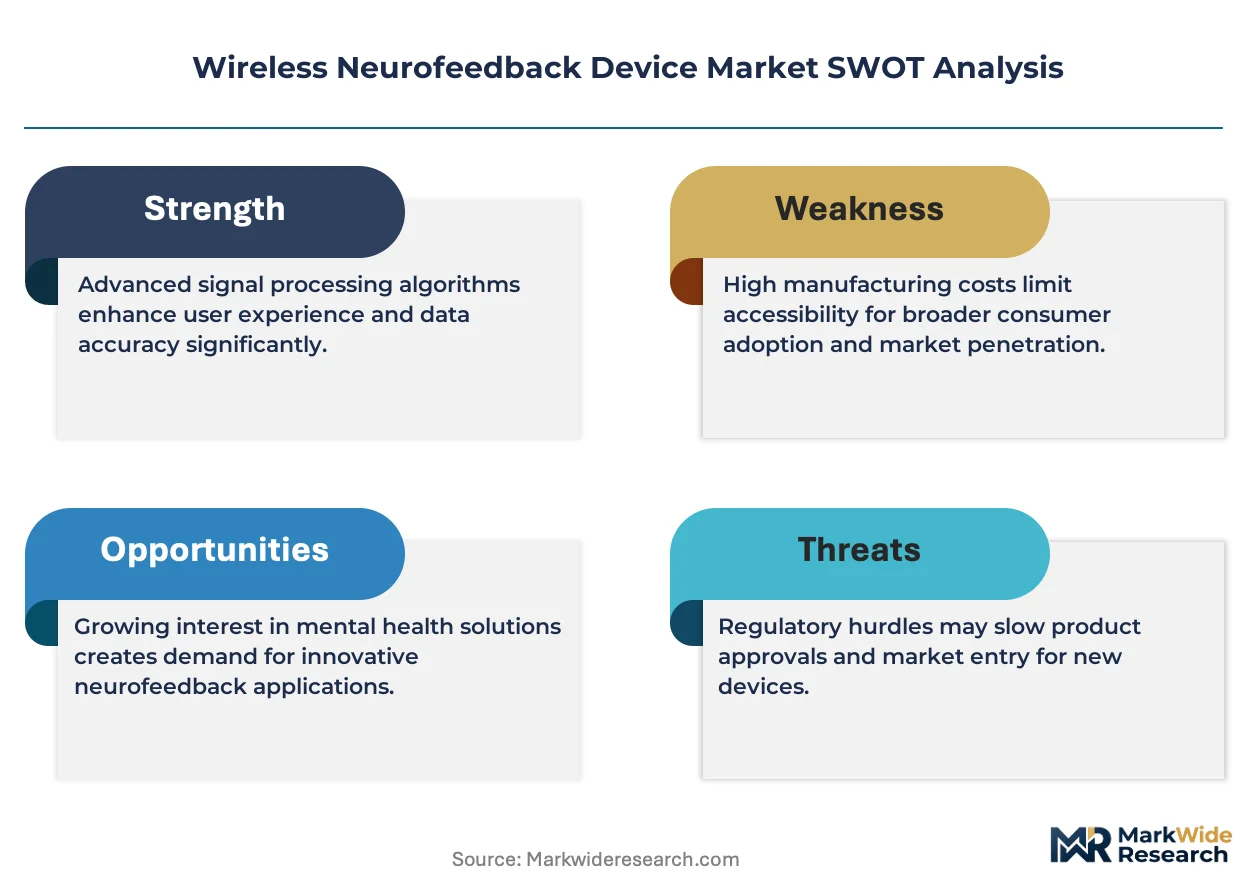
Growth Catalysts
- FDA 510(k) clearance frameworks:Streamlined predicate device pathways accelerate clinical channel entry for medical-grade EEG wearables, reducing time-to-revenue for manufacturers targeting mental health clinics.
- Remote therapeutic monitoring protocols:Licensed clinicians in the United States are integrating cloud-based neurofeedback platforms into longitudinal patient care, driving recurring software subscription attach rates.
- Bluetooth Low Energy 5.3:Enhanced throughput and reduced latency enable real-time operant conditioning without dedicated base stations, expanding deployment in mobile and home-use settings.
Market Restraints
- Specialty wafer supply concentration:Taiwan-based foundries control advanced biosignal processing chip fabrication, creating single-source vulnerability for hardware manufacturers.
- EU Medical Device Regulation compliance burdens:Biocompatibility materials testing and electromagnetic compatibility certification add fixed costs that disproportionately impact mid-tier entrants.
- Optical fNIRS substitutes:Functional near-infrared spectroscopy devices offer comparable hemodynamic feedback without gel-based electrode maintenance, capturing price-sensitive consumer segments.
Strategic Opportunities
- German academic medical centers:Neurotechnology investment clusters around Munich and Berlin create concentrated demand for research-grade wireless EEG systems with open API architectures.
- Japan's PMDA fast-track designation:Accelerated review pathways for digital therapeutics enable earlier market entry for neurofeedback platforms targeting attention-deficit indications.
- Smartphone computational offloading:Edge AI processing on iOS and Android devices eliminates hardware base station requirements, opening direct-to-consumer distribution through app marketplaces.
Industry Challenges
- EEG signal processing expertise scarcity:Artifact rejection algorithm development requires specialized biomedical engineering talent concentrated in Boston and San Diego metro areas.
- HIPAA-GDPR interoperability friction:Cloud-based platforms storing cross-border patient neural data face conflicting health data classification requirements between United States and European jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Neurofeedback Device Market |
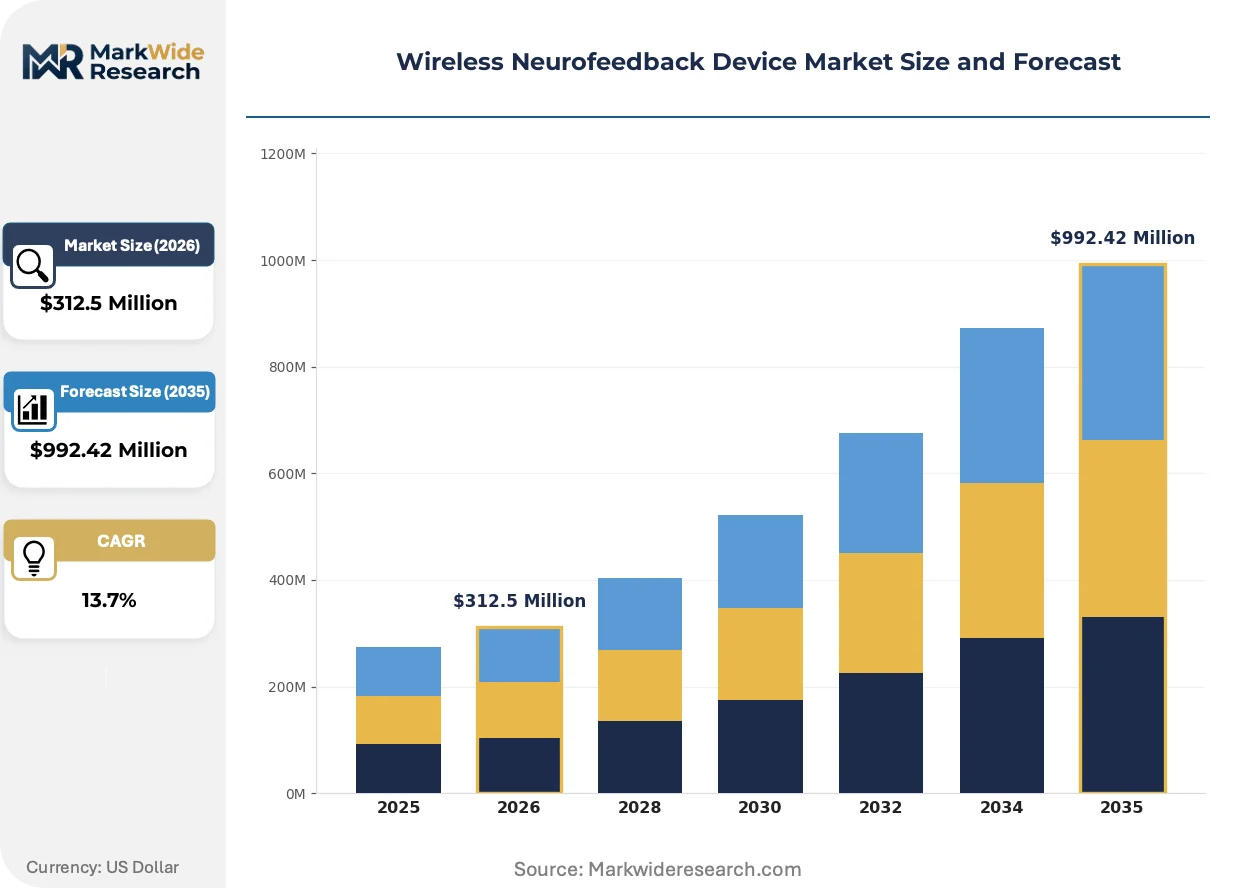
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Software Platforms, Headsets End User: Clinics, Research Institutions, Wellness Centers, Individual Users Application: Stress Management, Cognitive Enhancement, Mental Health Treatment, Performance Optimization Technology: EEG, fNIRS, Biofeedback, Wireless Communication |
| Companies Covered | EMOTIV, NeuroSky, Myndlift Ltd., Muse, Sens.ai, Narbis, Mendi, BrainMaster Technologies, Neurable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Neurofeedback Device Market Trends and Innovations
Dry electrode materials and onboard edge processing are converging to eliminate conductive gel dependencies while preserving signal fidelity, fundamentally altering the wearable form factor and maintenance burden for end-users.
Dry polymer-silver chloride hybrid electrodes are absorbing the functional role of traditional wet electrodes in consumer-tier headsets, enabling same-session deployment without skin preparation. Mental health clinics in the United States are piloting these systems for high-throughput patient intake workflows. The technology is absorbing margin pressure from disposables while compressing session setup time from fifteen minutes to under ninety seconds.
EU Medical Device Regulation Class IIa reclassification is elevating quality management system requirements for EEG-based therapeutic claims, forcing firmware documentation and post-market surveillance investments. Manufacturers targeting European clinical channels are restructuring technical file architectures to accommodate notified body scrutiny cycles. German and French regulators are prioritizing cybersecurity validation for cloud-connected neurofeedback platforms, creating compliance differentiation between established and emerging vendors.
Subscription-based software licensing is displacing perpetual hardware margins as the primary revenue architecture across clinical and consumer segments. Mental health clinics in Japan are unbundling hardware acquisition from longitudinal analytics dashboards, shifting capital expenditure to operational expenditure models. This pattern is most visible in United States telehealth integrations, where platform fees scale with active patient monitoring seats rather than device shipment volumes.
Wireless Neurofeedback Device Market Segmentation
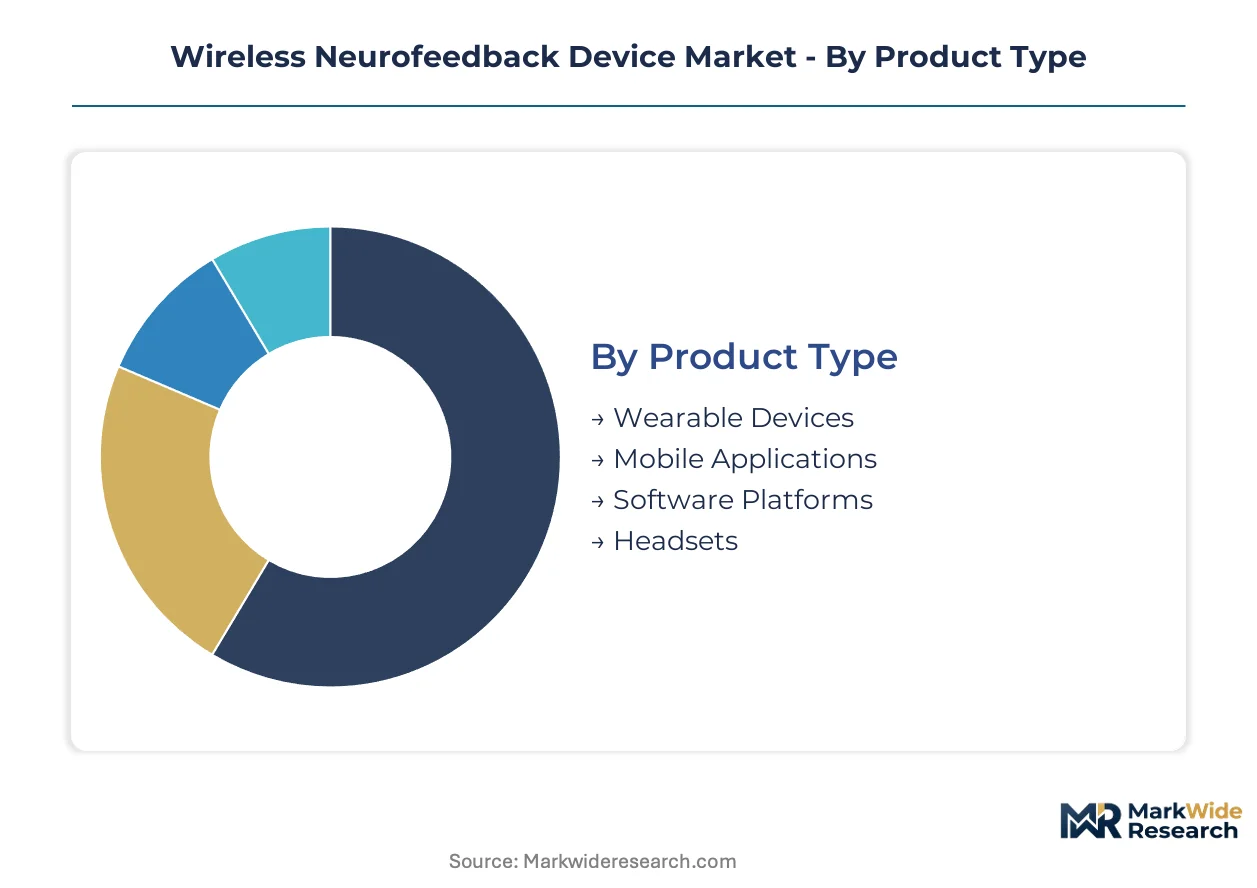
Segmentation in wireless neurofeedback devices reveals divergent margin architectures across hardware and software delivery modes. Product type stratification separates capital-intensive headset manufacturers from recurring-revenue platform operators, while end-user concentration in clinical channels shapes regulatory compliance investments.
Product Type:
Wearable headsets capture hardware margin pools through premium positioning, while software platforms extract recurring value from longitudinal data analytics.
- Wearable Devices:Dry electrode headsets with 256–512 Hz sampling rates and Bluetooth Low Energy 5.3 transmission dominate United States mental health clinic procurement. FDA 510(k) clearance requirements compress design-to-shipment velocity for clinical-grade units.
- Software Platforms:Cloud-based neurofeedback dashboards with clinician-facing analytics and patient remote monitoring modules scale through per-seat subscription licensing. HIPAA interoperability rules and GDPR health data classifications impose cross-border architecture constraints.
- Mobile Applications:Smartphone-native operant conditioning protocols leverage iOS and Android edge AI processing to eliminate dedicated base station hardware.
- Headsets:Gel-free electrode configurations with onboard artifact rejection algorithms target consumer price tiers through reduced maintenance burden.
Today's leader: Wearable Devices. Tomorrow's challenger: Software Platforms.
End User:
Clinical channel concentration drives medical-grade certification investments, while individual user segments prioritize cost accessibility over therapeutic claims.
- Clinics:Licensed mental health practitioners in Germany and Japan deploy research-grade EEG systems with open API architectures for longitudinal patient monitoring. Reimbursement framework evolution in the United States accelerates platform adoption.
- Research Institutions:Academic medical centers in Munich, Berlin, and Boston metro areas concentrate demand for high-fidelity biosignal processing with customizable stimulation protocols. EU MDR Class IIa reclassification elevates quality management system documentation burdens.
- Wellness Centers:Non-therapeutic cognitive enhancement applications in corporate and athletic training environments favor lower-cost dry electrode systems without clinical claims.
- Individual Users:Direct-to-consumer distribution through app marketplaces targets attention-deficit and stress management indications with smartphone-integrated headsets.
Clinics anchor current revenue concentration. Individual users present the steepest expansion trajectory as smartphone computational offloading eliminates hardware barriers.
Application:
Therapeutic indications command premium pricing through medical-grade certification, while wellness applications compete on accessibility and convenience.
- Mental Health Treatment:FDA-cleared neurofeedback protocols for anxiety and depression indications integrate into United States telehealth reimbursement codes. PMDA fast-track designation in Japan accelerates digital therapeutic pathways for attention-deficit indications.
- Stress Management:Real-time arousal modulation through auditory and haptic feedback targets corporate wellness programs and high-performance occupational settings.
- Cognitive Enhancement:Attention and working memory training applications compete with pharmaceutical interventions in academic and professional optimization markets.
- Performance Optimization:Athletic and creative performance protocols leverage operant conditioning for flow state induction without clinical therapeutic claims.
Mental Health Treatment commands the highest per-unit value. Stress Management is gaining share fastest as employer-sponsored wellness budgets expand.
Technology:
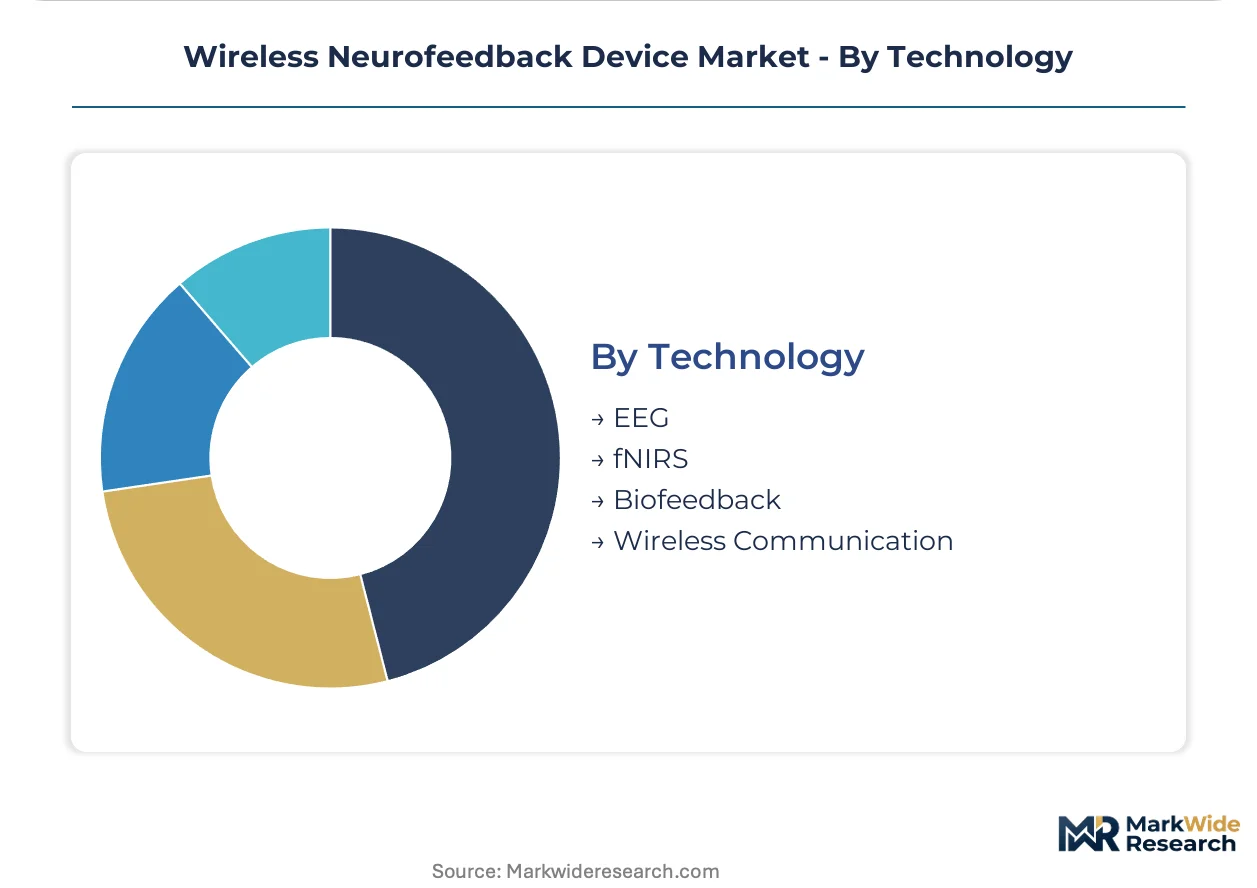
EEG-based electrical signal processing maintains functional leadership against optical hemodynamic alternatives that eliminate electrode maintenance requirements.
- EEG:Cortical electrical activity sampling at 256–512 Hz with real-time artifact rejection algorithms constitutes the dominant technical architecture. Semiconductor foundry allocation constraints for biosignal processing chips compress development timelines.
- fNIRS:Functional near-infrared spectroscopy devices measure hemodynamic responses without conductive gel dependencies, capturing price-sensitive consumer segments in wellness applications.
- Biofeedback:Peripheral physiological signals including heart rate variability and galvanic skin resistance integrate with neural data for multimodal conditioning protocols.
- Wireless Communication:Bluetooth Low Energy 5.3 and Wi-Fi transmission standards determine antenna design, electromagnetic compatibility testing, and FCC Part 15 emissions compliance burdens.
EEG retains technology leadership. fNIRS emerges as the primary substitution threat in consumer-tier price bands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks mature faster than Japanese regulatory pathways, yet both markets concentrate neurotechnology investment around academic medical centers with distinct procurement patterns.
United States
Mental health clinics in Massachusetts and California drive FDA 510(k) cleared device procurement as telehealth reimbursement codes expand. HIPAA interoperability rules reshape cloud-based platform architectures for cross-state patient monitoring. Boston and San Diego metro areas concentrate biomedical engineering talent for artifact rejection algorithm development.
Germany
Neurotechnology investment clusters around Munich and Berlin academic medical centers demanding research-grade EEG systems with open API architectures. EU Medical Device Regulation Class IIa reclassification elevates quality management system documentation burdens for therapeutic claims. Bavarian regulators prioritize cybersecurity validation for cloud-connected platforms.
Japan
PMDA fast-track designation for digital therapeutics accelerates market entry for attention-deficit neurofeedback indications. METI funding programs support smartphone-integrated headset development for home-use deployment. Tokyo and Osaka metropolitan areas concentrate demand for longitudinal patient monitoring subscriptions.
United Kingdom
NHS digital therapy procurement frameworks create concentrated demand for remote therapeutic monitoring protocols. MHRA alignment with EU MDR standards shapes biocompatibility materials testing requirements for cross-border commercialization. London and Cambridge neurotechnology clusters drive open-architecture research system adoption.
Canada
Health Canada medical device licensing pathways attract US manufacturers seeking predicate device expansion into North American clinical channels. Provincial reimbursement variation creates patchwork adoption patterns across mental health clinic networks. Toronto and Montreal academic centers concentrate demand for multimodal biofeedback integration.
Wireless Neurofeedback Device Market Competitive Landscape
United States producers anchor the premium clinical tier; Asian specialists hold consumer price bands through sensor module cost leadership. The vendor base separates into three strata: vertically integrated hardware-software stacks, low-cost component suppliers, and cloud-native platform operators. Strategic differentiation concentrates on FDA clearance velocity, dry electrode material science, and clinician dashboard licensing depth. Dominant competitive moves include strategic partnerships with academic medical centers and portfolio diversification into smartphone-native delivery modes.
Within the vertically integrated tier, EMOTIV and NeuroSky occupy positions reflecting distinct geographic and structural approaches. EMOTIV exemplifies design-to-shipment velocity through captive hardware-software development. NeuroSky anchors the consumer tier through sensor module cost leadership. Myndlift Ltd. represents the platform-native archetype specializing in remote therapeutic monitoring protocols for licensed clinicians.
| Leading Market Players |
|---|
| EMOTIV |
| NeuroSky |
| Myndlift Ltd. |
| Muse |
| Sens.ai |
| Narbis |
| Mendi |
| BrainMaster Technologies |
| Neurable |
| Others |
Pricing and Supply Chain Analysis
Venture-backed neurotechnology specialists with serial financing rounds are consolidating component sourcing relationships to secure biosignal processing chip allocation, compressing procurement timelines while extracting volume-tier pricing concessions from Taiwan-based foundries.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for dry electrode materials, forcing incumbent manufacturers to recalibrate hardware margin structures. Three-tier pricing structure across premium clinical-grade, standard wellness-tier, and economy consumer-tier levels separates FDA-cleared systems from unregulated alternatives. Pricing pressure stems from fNIRS substitutes capturing price-sensitive wellness segments. Individual users exhibit highest price sensitivity, while German academic medical centers demonstrate lowest elasticity due to research grant funding.
Supply Chain Analysis
Refurbishment flows for clinical-grade headsets are creating secondary supply channels, extending hardware lifecycles and pressuring new unit demand. Taiwan, South Korea, and the United States concentrate biosignal processing chip fabrication, with dry polymer-silver chloride electrodes sourcing from Japanese and German specialty chemical suppliers. Single-source vulnerability in Taiwan-based foundry allocation creates structural risk for hardware manufacturers. Distribution runs through mental health clinic procurement committees, research institution grant administrators, and direct-to-consumer app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry electrode material science advances are driving cost-down trajectories, while clinical-grade certification premiums expand margin capture for FDA-cleared platforms.
For Market Incumbents: Hedge against optical fNIRS substitution by accelerating dry electrode deployment timelines and deepening clinician dashboard licensing depth. Secure captive foundry allocation through multi-year wafer supply agreements. Prioritize EU MDR Class IIa technical file documentation to defend European clinical channel access against emerging entrants. For New Entrants and Emerging Players: Begin with smartphone-native operant conditioning protocols that leverage iOS and Android edge AI processing, bypassing dedicated hardware development costs. Target United States individual user segments through app marketplace distribution with attention-deficit wellness claims. Pursue strategic partnerships with telehealth platforms for patient monitoring seat expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among cloud-native platform operators with recurring subscription architectures and limited hardware exposure. Five-to-ten-year viability favors vendors with FDA 510(k) clearance velocity and open API research-grade system adoption. Monitor PMDA fast-track designation announcements for Japanese digital therapeutic inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates clinical channel entry and predicates reimbursement eligibility for mental health clinics. |
| Dry Electrode Material Science Investment | Eliminates conductive gel dependencies while preserving signal fidelity for same-session deployment. |
| Cloud Platform Integration Partnership | Enables per-seat subscription scaling with telehealth providers and longitudinal patient monitoring. |
| Academic Medical Center Collaboration | Secures research-grade system validation and open API architecture adoption in Munich and Boston clusters. |
| Smartphone Computational Offloading | Removes hardware base station requirements and opens direct-to-consumer distribution through app marketplaces. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Canada, with primary inputs from each market cluster. The study combines structured interviews with neurotechnology product managers, FDA regulatory consultants, hospital biomedical engineers, mental health clinic purchasing committees, and semiconductor foundry account executives. Secondary validation draws from FDA 510(k) clearance databases, EU MDR notified body technical file registries, PMDA digital therapeutic fast-track announcements, and CMS telehealth reimbursement code updates. Bottom-up device shipment estimates triangulate against top-down neurotechnology investment flow analysis.
Granularity-level modeling operates at product type, end user, application, and technology dimensions across the projection horizon. The analytical framework segments wearable headsets, software platforms, mobile applications, and gel-free electrode configurations with distinct margin architecture assumptions. CAGRs derive from semiconductor foundry capacity allocation trajectories, reimbursement framework evolution patterns, and dry electrode material adoption curves. Biosignal processing chip supply constraints and HIPAA-GDPR interoperability rule changes constitute industry-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including pharmaceutical neurostimulation device convergence and invasive implantable BCI competitive dynamics. Forecasts reflect documented assumptions about Bluetooth Low Energy 5.3 adoption timelines and cloud platform cybersecurity validation cycles. Practitioners should monitor EU MDR Class IIa reclassification enforcement intensity and Taiwan foundry allocation policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Global Nebuliser Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Wheelchair Market
Medical Devices
Cryoablation System Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Global Nerve Monitoring System Market