
 Mining Drill Bits Market | 2026-2036
Mining Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Drill Bits Market Analysis
A shortage of certified hard-rock drill technicians is redrawing competitive boundaries across the mining drill bits supply base. Sandvik AB leverages its captive metallurgy expertise to produce proprietary cemented carbide substrates in-house. Epiroc AB anchors its position through integrated automation packages that pair drill bits with autonomous rig controls. Boart Longyear Corporation specializes in coring systems for deep mineral exploration programs where sample integrity commands premium pricing.
Mining drill bits are cutting tools engineered to fracture and excavate rock formations, typically constructed from tungsten carbide inserts or synthetic diamond compacts bonded to steel bodies and rated for specific compressive strength thresholds and rotational speed tolerances. Their primary purpose is to sustain penetration rates and tool life in abrasive downhole conditions where replacement costs dominate operational economics. Carbide-based percussion bits retain the largest installed base in surface mining, though diamond bits are gaining share in deep-hole geothermal and mineral exploration where single-run longevity reduces tripping time. Steel-bodied tricone designs occupy the mid-tier segment for water well and geotechnical applications where capital constraints limit adoption of premium materials.
OSHA respirable silica standards and EPA mine tailings rules are tightening permissible exposure limits, forcing operators to specify dust-suppression drill bit geometries and wet-cutting configurations. REACH compliance in Europe restricts certain cobalt binder chemistries, redirecting R&D toward nickel and iron-based matrix alternatives. Stakeholders must monitor how ISO 18758 performance testing protocols evolve, as standardized wear-rate benchmarks will increasingly determine contract eligibility and OEM qualification status across procurement frameworks.
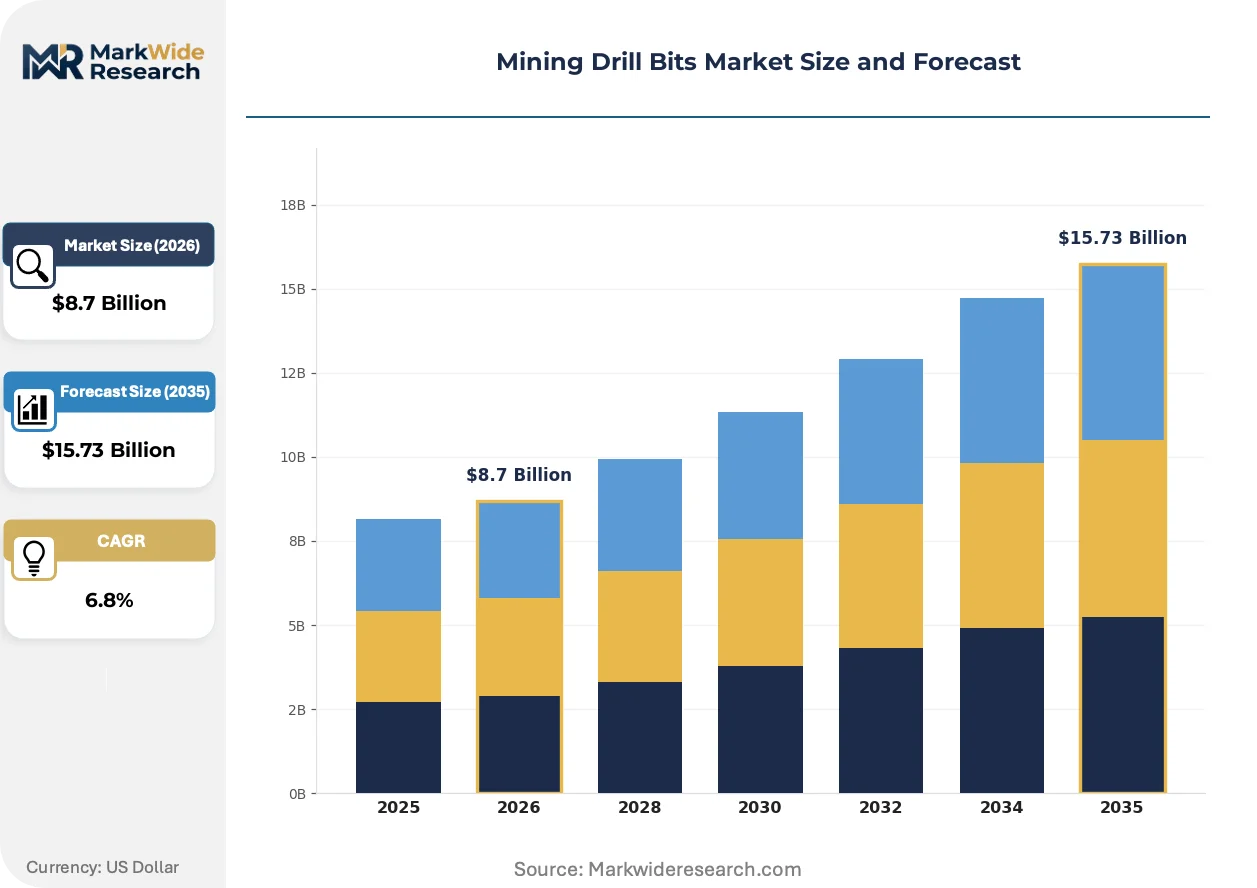
Market Dynamics
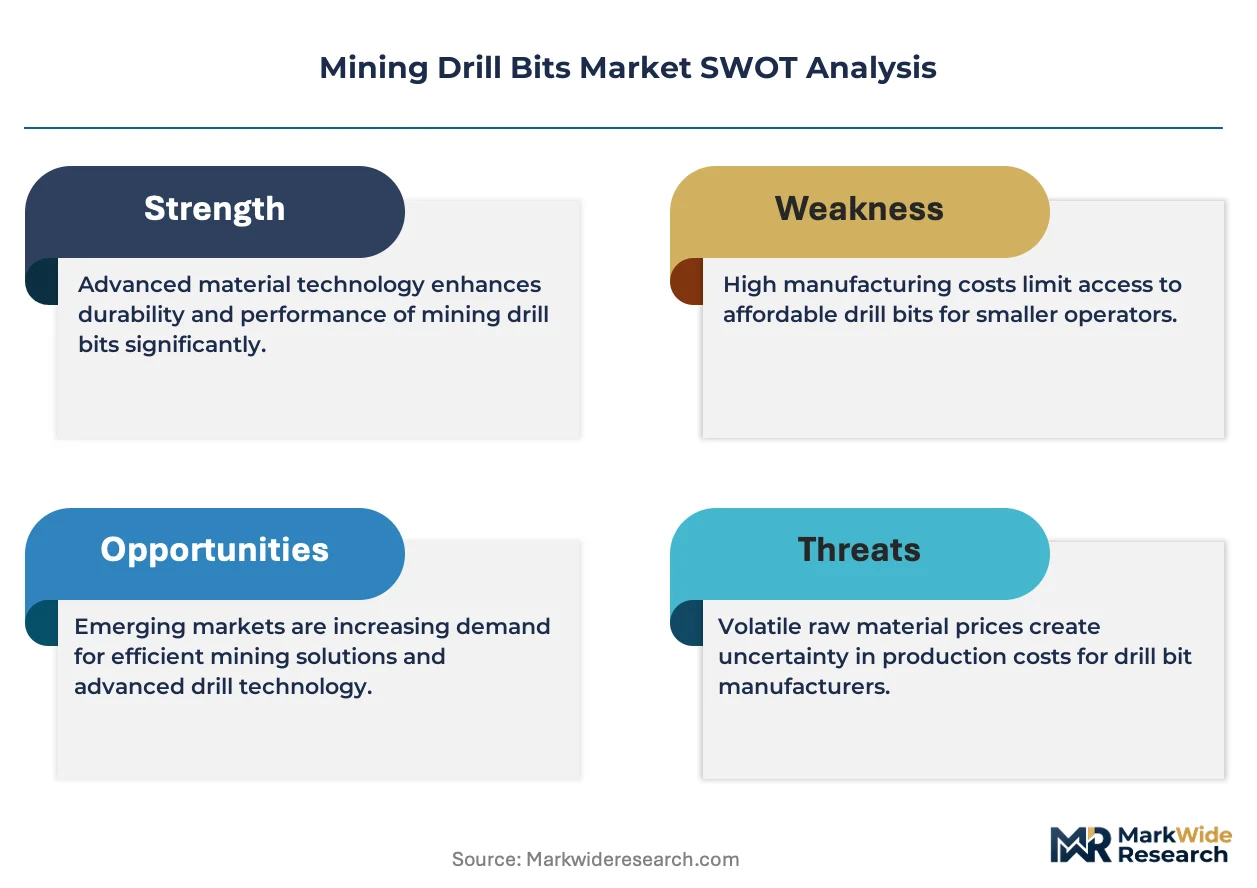
Declining ore grades across mature mining districts are forcing operators to drill deeper, harder rock formations, intensifying wear on conventional carbide tools and accelerating procurement of polycrystalline diamond compact systems that sustain penetration rates in abrasive conditions.
Growth Catalysts
- Pilbara Deepening Operations:Western Australian iron ore producers are extending pit depths below water tables, requiring sealed bearing tricone bits and high-pressure mud motors that tolerate flooded hole conditions without premature seal failure.
- EU F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon refrigerants used in underground climate control is pressuring mine operators to adopt higher-efficiency drilling systems that reduce ventilation energy loads and compressor runtime.
- Geothermal Exploration:Enhanced geothermal systems developers are repurposing oilfield diamond drill bit architectures for crystalline basement drilling, creating cross-industry demand for thermally stable polycrystalline cutters rated above 175 degrees Celsius.
Market Restraints
- Tungsten Carbide Powder Concentration:Over 80 percent of global tungsten ore processing concentrates in Chinese smelters, exposing bit manufacturers to export quota volatility and forced stockpiling during supply disruptions.
- Cobalt Binder Restrictions:REACH Annex XVII limitations on cobalt dust exposure are forcing reformulation of cemented carbide matrices, with nickel and iron substitutes delivering inferior fracture toughness in percussive applications.
- Extended Replacement Cycles:Diamond-impregnated core bits now achieve 3,000+ meter single-run longevity in homogeneous formations, compressing aftermarket volume for steel-body bit suppliers dependent on frequent replacement revenue.
Strategic Opportunities
- Underexplored Greenstone Belts:Canada's Abitibi region and Western Australia's Yilgarn Craton host underdrilled Archean terranes where deep directional drilling programs require specialized coring bits with face-discharge flushing geometries.
- Autonomous Rig Integration:Bit-to-rig data telemetry enabling real-time wear prediction and automated pull decisions is converging with machine vision systems that optimize weight-on-bit parameters without human intervention.
- US Inflation Reduction Act:Critical mineral production tax credits are incentivizing domestic lithium and rare earth exploration, expanding demand for wireline coring systems that deliver HQ-size core samples for metallurgical testing.
Industry Challenges
- Certified Hard-Rock Technician Scarcity:Underground jumbo drill operators require MSHA Part 46 training plus manufacturer-specific bit maintenance certification, with completion timelines stretching 18-24 months and attrition rates exceeding 15 percent annually.
- Legacy Rig Retrofit Complexity:Older hydraulic longhole drills lack the sensor infrastructure and feedback controls necessary to exploit advanced bit designs, forcing contractors into costly platform replacements or suboptimal tool performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Drill Bits Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Bits, Percussion Bits, Diamond Bits, Tricone Bits Material: Carbide, Steel, Diamond, Composite Application: Mineral Exploration, Oil & Gas Drilling, Geotechnical Investigation, Water Well Drilling End User: Mining Companies, Construction Firms, Oil & Gas Industry, Environmental Agencies |
| Companies Covered | Boart Longyear Corporation, Robit plc, Sandvik AB, Rockmore International Inc., Changsha Heijingang Industrial Co. Ltd., Epiroc AB, Mitsubishi Materials Corporation, Brunner and Lay Inc., Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Drill Bits Market Emerging Trajectories
Material science advances and digital integration are redefining tool performance benchmarks, with synthetic diamond technologies and real-time condition monitoring displacing empirical wear estimation and scheduled replacement protocols.
Thermally stable polycrystalline diamond cutters rated for 200-degree Celsius bottom-hole temperatures are supplanting conventional PDC designs in deep geothermal and mineral exploration holes where conductive heat degradation previously limited run lengths. Geothermal developers in Nevada's Basin and Range and Cornwall's United Downs project are specifying these cutters for granite and gneiss intervals where abrasive silica content exceeds 65 percent. The shift is compressing market space for surface-set diamond bits that require multiple tripping cycles to complete comparable hole depths.
The US Mine Safety and Health Administration's 2023 respirable silica enforcement directive is mandating wet-cutting configurations and dust-suppression bit geometries across all metal and non-metal underground operations. Drill bit OEMs must now certify flushing channel designs that maintain 95 percent capture efficiency at 2.5 meter-per-minute penetration rates. Western US copper producers in Arizona and New Mexico are retrofitting entire jumbo fleets to comply, creating specification divergence between North American and export product lines.
Consolidated mining houses are unbundling after-sales service contracts from original equipment procurement, creating standalone bit reconditioning and inventory management markets. Contractors in Chile's Athenas copper district and South Africa's Bushveld platinum mines now engage third-party bit grinding shops for cutter refurbishment rather than factory return programs. The disintermediation is most pronounced in mid-tier operations where capital constraints favor service unbundling over integrated premium pricing.
Mining Drill Bits Market Segmentation
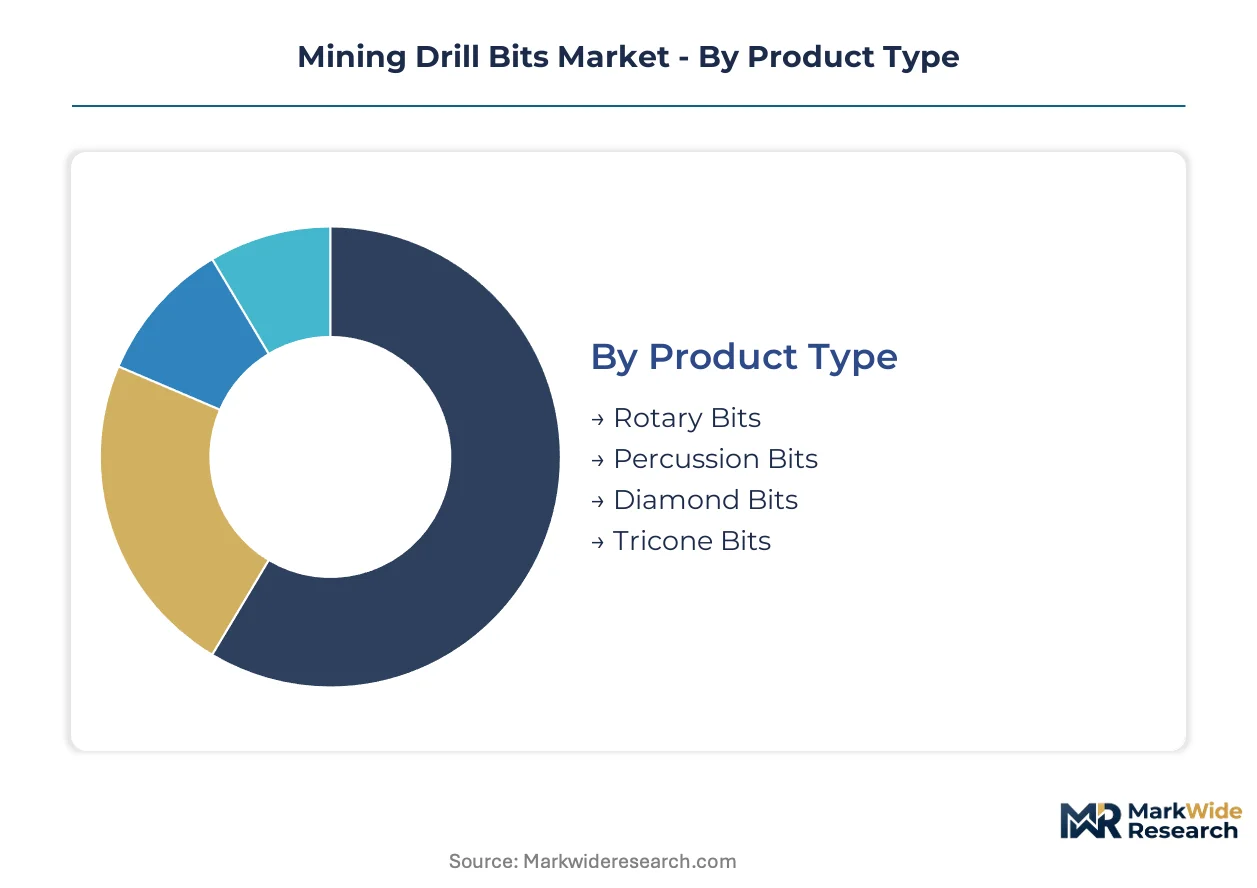
Drill bit procurement patterns diverge sharply across material grades and operational contexts, with premium diamond configurations commanding outsized margins in deep-hole geothermal while carbide percussion tools dominate volume-driven surface mining contracts.
Product Type:
Margin concentration pools in diamond-impregnated systems where single-run longevity justifies premium pricing, while rotary and percussion formats compete on replacement frequency and inventory velocity.
- Rotary Bits:These tools employ rolling cone mechanisms with tungsten carbide inserts to crush rock through combined rotation and weight-on-bit pressure. Western Australian iron ore operators in the Pilbara specify sealed bearing rotary configurations for pit deepening below water tables, where flooded hole conditions demand enhanced seal integrity.
- Percussion Bits:Designed for top-hammer and down-the-hole drilling, these tools transmit impact energy directly to the rock face via high-frequency piston strikes. Underground jumbo operations in Chile's El Teniente copper mine deploy button-bit percussion designs for development headings where penetration rate consistency governs shift productivity metrics.
- Diamond Bits:Synthetic or natural diamond cutting structures bonded to matrix bodies for abrasive formation drilling. Nevada geothermal developers specify thermally stable polycrystalline variants for granite basement intervals exceeding 175 degrees Celsius.
- Tricone Bits:Three-cone roller assemblies with milled tooth or insert configurations for soft-to-medium formations. Water well contractors in the Great Artesian Basin favor steel-bodied tricone designs where capital constraints limit adoption of premium materials.
Rotary bits hold installed capacity across surface mining fleets. Diamond bits are rotating up the share rankings in deep directional programs.
Material:
Cost tier stratification separates captive carbide substrate producers from steel fabricators exposed to commodity volatility, with diamond composite suppliers occupying the premium tier.
- Carbide:Cemented tungsten carbide matrices with cobalt or nickel binders deliver fracture toughness for percussive applications. Sandvik AB's in-house metallurgy operations in Sandviken, Sweden supply proprietary substrate grades to capture margin upstream.
- Steel:Alloy steel bodies provide economical platforms for tricone and drag bit assemblies where tool life expectations remain modest. Chinese forging shops dominate volume production for mid-tier water well and geotechnical segments.
- Diamond:Polycrystalline diamond compacts and impregnated matrices achieve 3,000+ meter run lengths in homogeneous crystalline formations. Enhanced geothermal developers in Cornwall's United Downs project specify these for silica-rich gneiss intervals.
- Composite:Hybrid constructions combining steel bodies with diamond-enhanced cutting structures balance cost and performance. Exploration contractors in Canada's Abitibi greenstone belt deploy composite coring bits for deep directional programs requiring sample integrity.
Carbide maintains volume leadership across installed base. Diamond composites are climbing the fastest in geothermal and deep mineral exploration specifications.
Application:
Customer type concentration separates capital-constrained water well municipalities from resource-backed mining houses willing to specify premium configurations.
- Mineral Exploration:Wireline coring systems deliver HQ-size core samples for metallurgical testing and resource estimation. US lithium explorers in Nevada's Clayton Valley deploy diamond impregnated bits to satisfy JORC-compliant sample recovery standards.
- Oil & Gas Drilling:Polycrystalline diamond compact bits repurposed from oilfield architectures now penetrate crystalline basement for geothermal development. Permian Basin service companies are cross-selling these configurations to geothermal developers in Utah's FORGE project.
- Geotechnical Investigation:Rotary percussion tools acquire soil and rock samples for foundation engineering and tunnel design. Mumbai Metro contractors specify triple-tube coring systems for basaltic Deccan Traps characterization.
- Water Well Drilling:Tricone and drag bits access aquifers for agricultural and municipal supply. Great Artesian Basin operators in Queensland favor steel-bodied configurations where drilling depths rarely exceed 500 meters.
Mineral exploration commands premium pricing per meter drilled. Geothermal applications are gaining share fastest as oilfield technology transfers to renewable energy.
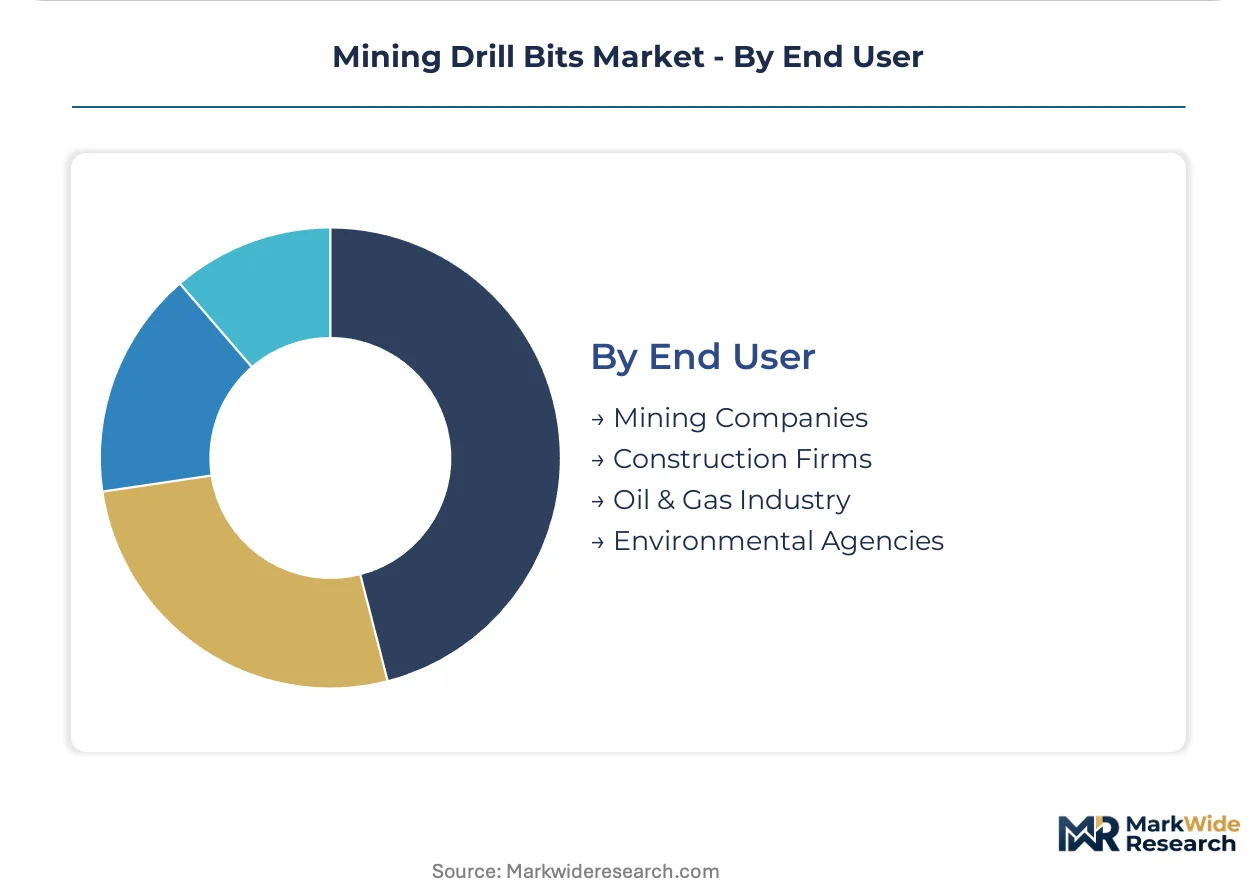
End User:
Procurement sophistication varies dramatically, with tier-one mining houses unbundling service contracts while environmental agencies prioritize compliance-certified configurations.
- Mining Companies:Integrated operators and contractors specify bits through centralized procurement frameworks with performance-based contracting. BHP's Pilbara operations mandate ISO 18758-certified wear rate benchmarks for tricone bit eligibility.
- Construction Firms:Infrastructure developers acquire bits through equipment rental channels for temporary foundation and anchoring work. Mumbai Metro joint ventures source rotary percussion tools through Sandvik and Epiroc rental fleets.
- Oil & Gas Industry:Exploration and production companies specify bits through integrated drilling contracts where tool performance ties to rate-of-penetration guarantees. Permian Basin operators are transferring PDC specifications to geothermal contractors.
- Environmental Agencies:Regulators and remediation contractors prioritize dust-suppression geometries and wet-cutting configurations to satisfy OSHA silica exposure limits. Arizona Department of Environmental Quality mandates MSHA-compliant bit specifications for groundwater monitoring well installation.
Mining companies anchor procurement volume. Environmental agencies are rotating up the specification influence as silica enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA respirable silica standards and EPA mine tailings protocols anchor North American procurement specifications, while Western Australia's Pilbara iron ore deepening and the EU F-Gas Regulation reshape regional demand patterns for higher-efficiency drilling systems.
Australia
Western Australian iron ore producers in the Pilbara region are extending pit depths below water tables, requiring sealed bearing tricone bits and high-pressure mud motors. The country's national mining safety regulator mandates dust-suppression drill bit geometries for underground operations. Perth-based procurement offices for BHP and Rio Tinto centralize specifications through ISO 18758-certified wear rate benchmarks.
United States
Nevada lithium explorers in Clayton Valley deploy diamond-impregnated wireline coring systems to satisfy JORC-compliant sample recovery standards. The US Inflation Reduction Act's critical mineral production tax credits incentivize domestic exploration. Arizona copper producers retrofit entire jumbo fleets to comply with MSHA's 2023 respirable silica enforcement directive.
Chile
Underground jumbo operations at El Teniente copper mine deploy button-bit percussion designs for development headings where penetration rate consistency governs productivity. The country's environmental assessment service tightens tailings management protocols. Contractors in the Athenas copper district engage third-party bit grinding shops for cutter refurbishment rather than factory return programs.
Sweden
Sandvik AB's in-house metallurgy operations in Sandviken supply proprietary cemented carbide substrate grades to capture margin upstream. The EU F-Gas Regulation pressures mine operators across the Nordic region to adopt higher-efficiency drilling systems that reduce ventilation energy loads. Stockholm-headquartered Epiroc AB anchors its position through integrated automation packages pairing drill bits with autonomous rig controls.
Canada
Exploration contractors in the Abitibi greenstone belt deploy composite coring bits for deep directional programs requiring sample integrity. The country's national mining regulator aligns provincial standards with ISO 18758 performance testing protocols. Vancouver-based procurement teams for mid-tier gold operators favor service unbundling over integrated premium pricing.
Mining Drill Bits Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the mining drill bits supply base. The upper tier commands specification influence through captive substrate production and automation integration, while mid-tier fabricators compete on replacement frequency and inventory velocity. Strategic archetypes include integrated metallurgy specialists, autonomous rig integrators, and regional reconditioning service providers. Competitive moves center on backward integration into carbide substrate supply and portfolio diversification toward geothermal exploration configurations.
Among Swedish-based integrated manufacturers, Sandvik AB and Epiroc AB exemplify divergent positioning archetypes. Sandvik occupies a position emphasizing captive metallurgy expertise and proprietary cemented carbide production, while Epiroc represents the automation-integrated vector pairing tooling with autonomous rig controls. Finnish-listed Robit plc sits within the specialist tier as a publicly traded pure-play, its corporate structure reflecting focused exposure to drilling consumables rather than diversified mining equipment portfolios.
| Leading Market Players |
|---|
| Boart Longyear Corporation |
| Robit plc |
| Sandvik AB |
| Rockmore International Inc. |
| Changsha Heijingang Industrial Co. Ltd. |
| Epiroc AB |
| Mitsubishi Materials Corporation |
| Brunner and Lay Inc. |
| Atlas Copco AB |
| Others |
Supply Flow & Price Mechanics
Carbide substrate production at scale anchors price floors across the mining drill bits supply base, with captive metallurgy operations in Sweden and China determining margin capture upstream while downstream fabricators absorb commodity volatility. Western Australian iron ore procurement offices centralize specifications through ISO 18758-certified wear rate benchmarks, compressing price negotiation space for mid-tier suppliers lacking certification credentials.
Pricing Analysis
Chinese forging shops quote steel-bodied tricone configurations at 40-60% discounts to European captive producers, yet Australian and Chilean mining houses pay premiums for sealed bearing rotary bits rated for flooded hole conditions. Pricing stratifies across premium diamond-impregnated systems, standard carbide percussion tools, and economy steel drag bits. Cost compression in the carbide tier intensifies because tungsten powder export quotas force inventory stockpiling. Water well contractors in Queensland exhibit highest price sensitivity, while geothermal developers in Nevada accept premium positioning for thermally stable polycrystalline cutters.
Supply Chain Analysis
Inventory cycles for cemented carbide substrates stretch 16-24 weeks from ore concentrate to finished bit, exposing fabricators to tungsten price swings between contract awards and delivery. Manufacturing concentrates in China, Sweden, and Finland, with over 80% of global tungsten ore processing feeding Chinese smelters. Raw material flows draw from Wolframite concentrate, cobalt binder powders, and synthetic diamond feedstock. Single-source vulnerability concentrates in Chinese tungsten processing capacity. Distribution runs through OEM direct sales for tier-one mining houses, rental fleet channels for construction contractors, and third-party grinding shops for mid-tier reconditioning demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the mining drill bits supply base creates entry niches as autonomous rig integration and geothermal exploration specifications diverge procurement requirements away from standardized carbide tools.
For Market Incumbents: Secure captive supply of cemented carbide substrates through backward integration into tungsten powder metallurgy, insulating margin capture from Chinese export quota volatility. Defend specification influence by embedding bit-to-rig telemetry systems that automate weight-on-bit optimization, raising switching costs for contractors operating Sandvik or Epiroc autonomous fleets. Prioritize ISO 18758 certification investment to maintain eligibility in BHP and Rio Tinto centralized procurement frameworks. For New Entrants and Emerging Players: Differentiate on thermally stable polycrystalline cutter architectures repurposed from oilfield designs for Nevada and Cornwall geothermal developers, where incumbent mining-focused portfolios lack specialized heat-rated configurations. Target Canada's Abitibi greenstone belt exploration contractors with composite coring bits combining steel economy and diamond performance for deep directional programs. Pursue third-party reconditioning service contracts in Chile's Athenas copper district, where mining houses unbundle aftermarket grinding from factory return programs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallurgy specialists with in-house carbide substrate production and automation-integrated bit-to-rig data platforms over pure-play fabricators exposed to commodity steel and diamond feedstock volatility. Long-term viability hinges on exposure to geothermal exploration growth and critical mineral drilling demand incentivized by US Inflation Reduction Act tax credits. Monitor MSHA silica enforcement expansion as signal for dust-suppression bit geometry specification shifts that favor certified OEMs over unbranded imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Substrates | Captive tungsten powder metallurgy insulates Sandvik's margin from Chinese export quota disruptions. |
| Autonomous Rig Telemetry Integration | Epiroc's bit-to-rig data platforms embed switching costs for Pilbara iron ore contractors. |
| Geothermal Cutter Architecture Development | Thermally stable polycrystalline designs open Nevada Basin and Range exploration demand. |
| Third-Party Reconditioning Service Expansion | Unbundled grinding contracts in Chile's Athenas district capture mid-tier aftermarket volume. |
| ISO 18758 Certification Investment | Standardized wear-rate benchmarks determine OEM eligibility in Australian centralized procurement. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, combining structured interviews with maintenance directors at underground jumbo operations, OEM procurement teams for tier-one mining houses, aftermarket service heads at rental fleet providers, and plant engineers at carbide substrate foundries with secondary validation from SEC 10-K filings, customs and trade data for tungsten concentrate flows, ISO certification registries, and MSHA enforcement directive documentation. Bottom-up bit shipment estimates by product type and material grade were triangulated against top-down mining capital expenditure forecasts by commodity.
Across the analysis window, the forecasting framework models volume and value outputs through segmentation across product type, material composition, application context, and end-user procurement sophistication, with additional dimensional modeling for autonomous rig compatibility tiers and silica compliance certification status. CAGRs were derived from fitted growth curves calibrated to historical penetration rate data and replacement cycle compression observed in diamond-impregnated core bit deployments. Industry-specific forecast inputs include Pilbara pit deepening schedules, EU F-Gas Regulation implementation timelines, and US critical mineral exploration permit issuance rates.
The analysis sits within stated boundaries; outcomes outside sustained commodity price levels, regulatory enforcement intensity, or geothermal project development pace would require recalibration of replacement cycle and penetration rate assumptions. Forecasts reflect documented assumptions regarding ore grade decline trajectories and automation adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Mining Tester Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Surface Mining Equipment Market