
 Rock Drill Shank Adaptor Market | 2026-2036
Rock Drill Shank Adaptor Market Size, Share, and Industry Trends Forecast 2026-2036
Rock Drill Shank Adaptor Market Insights
Tungsten carbide is expanding its share in shank adaptor construction as mines prioritize wear resistance over first-cost economics. Sandvik leverages captive metallurgy capabilities to control alloy formulation from powder to finished tool. Zhuzhou Old Craftsman Precision Alloy anchors supply for Chinese tunnel boring projects through specialized carbide grades. Maxdrill Rock Tools competes on price-adjusted performance across African and Southeast Asian contract drilling markets.
A rock drill shank adaptor is a threaded or tapered coupling component that transmits percussive energy from the drill rig to the drill string, typically machined from chromium-molybdenum steel or tungsten carbide composites to withstand cyclic impact loads exceeding 200 Joules per blow. Its primary purpose is to maintain axial alignment and torque transfer while permitting rapid bit changes in blasthole, exploration, and production drilling. Threaded adaptors dominate mining applications where depth and deviation control matter most, while tapered variants retain share in shallow quarrying where coupling speed outweighs precision. Carbide material adoption outpaces steel alloy growth in hard-rock belts, though steel retains volume leadership in softer formations and developing markets.
ISO 18758 governs dimensional interchangeability and fatigue testing protocols for rock drilling tools, while MEE enforcement of dual carbon goals in China pressures domestic foundries toward cleaner alloy production. The EU Green Deal's embodied carbon tracking requirements are beginning to shape import specifications for European extraction companies sourcing Asian-manufactured adaptors. Stakeholders must weigh material substitution timelines against certification lag and smelter energy provenance.
Market Dynamics
Carbide-tipped shank adaptors are compressing replacement cycles in hard-rock mining as operators prioritize tool longevity over first-cost economics, forcing steel-alloy suppliers to defend position through price-adjusted performance or risk volume erosion in premium applications.
Growth Catalysts
- Dual carbon goals enforcement:MEE pressure on Chinese foundries is accelerating cleaner alloy production methods, creating certification advantages for compliant suppliers in export markets.
- Deep ore body extraction:Latin American copper-gold belts require harder-wearing tooling as operations descend into more abrasive formations, pulling carbide-composite demand upward.
- Threaded adaptor precision:Underground mining in Australia and Chile demands deviation-controlled drilling for resource definition, favoring threaded coupling systems over tapered alternatives.
Market Restraints
- Tungsten supply concentration:Primary tungsten ore processing concentrates in Chinese smelters, exposing carbide-dependent manufacturers to input volatility and geopolitical friction.
- Capital intensity of carbide conversion:Powder metallurgy and sintering equipment require substantial fixed investment, limiting supplier entry and maintaining incumbent pricing power.
- Steel-alloy substitution in soft formations:Quarrying and shallow drilling operations retain conventional chromium-molybdenum adaptors where rock abrasiveness does not justify carbide premiums.
Strategic Opportunities
- EU Green Deal embodied carbon tracking:European extraction companies are beginning to specify import tools with verified smelter energy provenance, creating first-mover advantage for certified Asian manufacturers.
- Tunnel boring machine integration:Chinese infrastructure projects demand specialized carbide grades for continuous boring operations, opening adjacent application volume beyond percussive drilling.
- Aftermarket service unbundling:Contract drilling operators in Africa and Southeast Asia are separating tool supply from maintenance contracts, enabling direct manufacturer relationships and margin capture.
Industry Challenges
- ISO 18758 fatigue testing compliance:Certification timelines lag material substitution cycles, forcing suppliers to maintain dual inventory of certified and pre-certified stock.
- Powder metallurgy skill scarcity:Captive carbide production requires specialized sintering technicians and alloy formulation chemists that mining-tool suppliers must develop internally or poach from cutting-tool industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rock Drill Shank Adaptor Market |
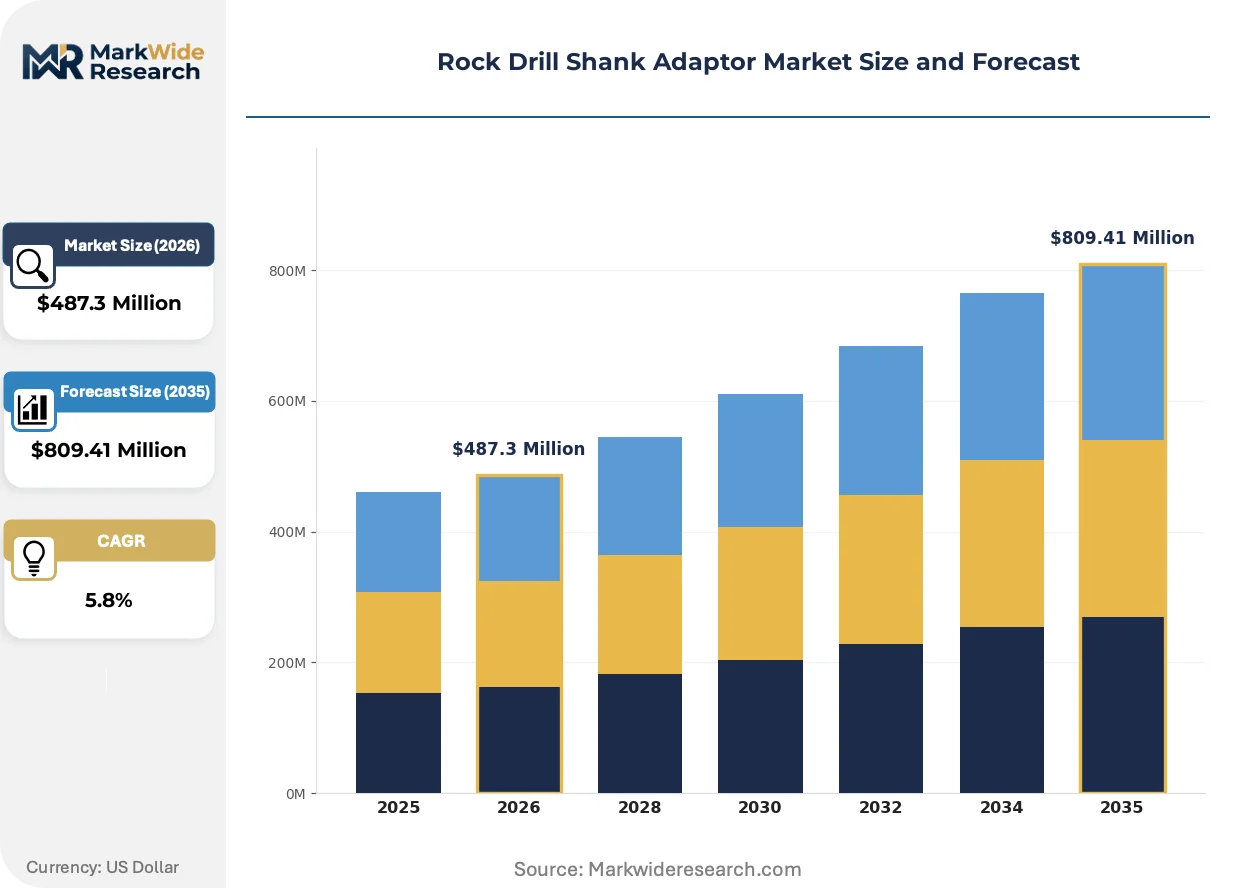
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Threaded, Smooth, Tapered, Welded Material: Steel Alloy, Titanium, Carbide, Composite Application: Mining, Quarrying, Tunnel Boring, Construction End User Industry: Extraction Companies, Civil Engineering Firms, Infrastructure Developers, Contract Drillers |
| Companies Covered | Epiroc, Sandvik, Furukawa Rock Drill, Boart Longyear, Hunan Nonferrous Chenzhou Drill Tools, Changsha Heijingang Industrial, Zhuzhou Old Craftsman Precision Alloy, Maxdrill Rock Tools, Litian Heavy Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rock Drill Shank Adaptor Market Trends and Innovations
Automation of drilling parameter optimization is compressing the performance gap between operator skill levels, while regulatory carbon accounting and procurement model fragmentation are simultaneously reshaping supplier-customer relationships across extraction verticals.
Sensor-integrated shank adaptors are automating real-time wear monitoring and predictive replacement scheduling. Underground mining contractors in Chile and Australia are piloting these systems to eliminate unplanned downtime during production drilling campaigns. The technology is automating maintenance decision-making that previously relied on manual inspection intervals, compressing total cost of ownership calculations for premium carbide tooling.
EU Green Deal embodied carbon tracking requirements are beginning to shape import specifications for European extraction companies sourcing Asian-manufactured adaptors. The regulation mandates disclosure of smelter energy provenance and alloy production emissions intensity, creating compliance friction for uncertified suppliers. Hard-rock mining operations in Scandinavia and Iberian copper districts are responding by dual-sourcing from certified European mills and verified Asian foundries.
Contract drilling operators are unbundling tool supply from maintenance service agreements, shifting procurement toward direct manufacturer relationships. African and Southeast Asian mining services companies are leading this pattern, replacing integrated rental models with separate capital purchases and third-party maintenance. The shift is most visible in copper-gold exploration camps where drilling intensity fluctuates and asset ownership flexibility outweighs bundled convenience.
Rock Drill Shank Adaptor Market Segmentation
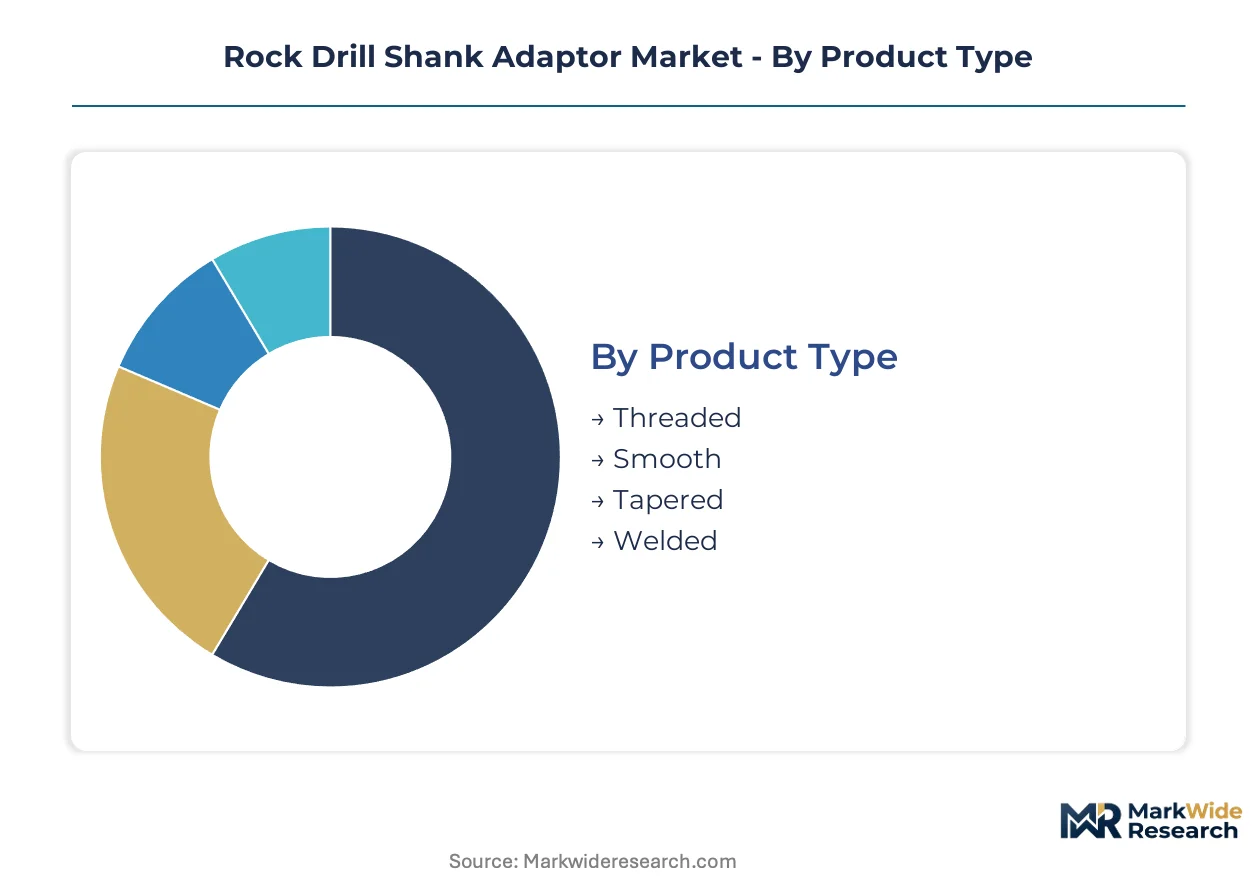
Shank adaptor procurement patterns diverge sharply across material grades and coupling geometries. Mining operators select specifications based on rock abrasiveness, hole depth requirements, and total cost of ownership calculations over replacement cycles.
Product Type:
Threaded and tapered designs anchor the specification matrix, with selection driven by deviation tolerance and coupling speed requirements.
- Threaded:Precision-machined coupling systems maintain axial alignment across extended drill strings. Underground copper-gold operations in Chile and Australia specify threaded adaptors for resource definition drilling where deviation control determines ore body modeling accuracy.
- Tapered:Conical friction-fit couplings enable rapid bit changes without thread engagement. Surface quarrying in Brazil and Indonesia retains tapered systems where drilling depth stays shallow and penetration speed outweighs precision requirements.
- Smooth:Non-coupling shank profiles serve specialized hydraulic drifter configurations. Chinese tunnel boring projects integrate smooth adaptors for continuous boring head assemblies.
- Welded:Permanent fusion-bonded joints eliminate coupling points in high-vibration applications. Russian iron ore open pits deploy welded adaptors for production drilling with minimal bit change frequency.
Mature deployment sits with Tapered systems. Newer deployment is concentrated in Threaded precision applications.
Material:
Material selection trades first-cost outlay against wear resistance, with powder metallurgy capabilities determining supplier competitiveness.
- Carbide:Tungsten carbide composites withstand cyclic impact loads exceeding 200 Joules per blow in abrasive formations. Latin American deep ore extraction drives carbide specification as operations descend into harder rock belts where tool longevity compresses total drilling costs.
- Steel Alloy:Chromium-molybdenum formulations dominate volume through lower unit economics. African contract drilling markets and Southeast Asian limestone quarrying specify steel alloy where rock abrasiveness does not justify carbide premiums.
- Titanium:Lightweight corrosion-resistant grades serve offshore and high-moisture environments. Norwegian coastal infrastructure projects specify titanium adaptors for marine tunneling applications.
- Composite:Hybrid material systems combine ceramic reinforcement with metallic matrices. Australian underground trials test composite adaptors for reduced weight and vibration damping.
Volume leadership remains with Steel Alloy. Technology investment is concentrating in Carbide powder metallurgy.
Application:
Application segmentation tracks extraction methodology, with percussive drilling intensity determining specification grade.
- Mining:Hard-rock metal extraction demands premium carbide-tipped adaptors for blasthole and production drilling. Peruvian copper porphyry operations and South African platinum mines specify threaded carbide systems for vertical crater retreat and longhole stoping.
- Tunnel Boring:Continuous excavation requires specialized carbide grades for cutter head integration. Chinese high-speed rail and urban metro projects drive demand for large-diameter boring adaptors.
- Quarrying:Dimension stone and aggregate extraction favors tapered steel alloy for rapid coupling cycles. Italian Carrara marble and Rajasthan granite operations deploy quarry-specific adaptor geometries.
- Construction:Foundation drilling and rock anchoring applications span specification tiers. UAE skyscraper piling and Saudi NEOM infrastructure projects source mixed material grades based on subsurface conditions.
Revenue concentration sits with Mining. Infrastructure expansion is accelerating Tunnel Boring specification fastest.
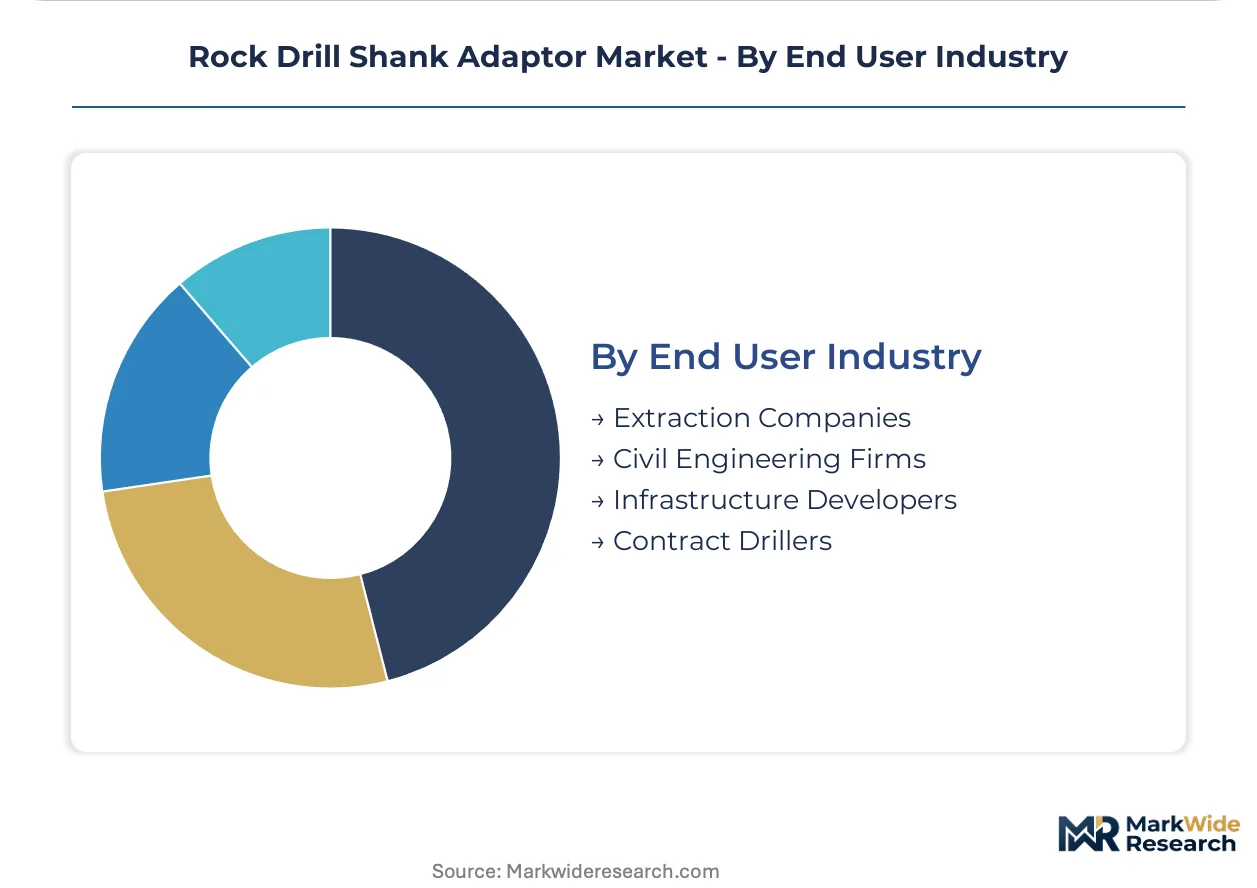
End User Industry:
Procurement authority is fragmenting as contract drilling unbundles tool supply from integrated service agreements.
- Extraction Companies:Integrated mining houses specify directly for captive operations. BHP and Codelco maintain qualified supplier lists with metallurgical certification requirements.
- Contract Drillers:Independent drilling services purchase adaptors as capital equipment. African and Southeast Asian exploration contractors are separating tool ownership from maintenance contracts.
- Civil Engineering Firms:Infrastructure specialists source for tunnel and foundation projects. European consortiums bidding on Alpine base tunnels specify EU Green Deal compliant material provenance.
- Infrastructure Developers:Project owners increasingly specify tooling standards in EPC contracts. Saudi PIF-backed developments mandate supplier certification for giga-project drilling packages.
Direct procurement sits with Extraction Companies. Contract Drillers are gaining procurement autonomy fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's mining special economic zones concentrate threaded adaptor demand as copper-gold extraction descends into harder formations. Australia's underground operations accelerate replacement cycles through automation adoption. China's tunnel infrastructure drives specialized carbide specifications beyond traditional mining applications.
Australia
Underground copper-gold operations in Western Australia and Queensland specify threaded carbide adaptors for deviation-controlled resource definition drilling. The country's Minerals Research Institute enforces fatigue testing protocols aligned with ISO 18758. Perth-based drilling contractors pilot sensor-integrated adaptors for predictive maintenance scheduling in Pilbara iron ore and Olympic Dam operations.
Chile
Deep ore extraction in the Atacama and Coquimbo copper belts drives carbide-tipped adaptor specification as formations grow more abrasive. The National Mining Society coordinates supplier certification programs for environmental compliance in extraction zones. Santiago procurement offices for Codelco and BHP specify qualified supplier lists with metallurgical traceability requirements for El Teniente and Chuquicamata operations.
China
High-speed rail and urban metro tunneling projects demand specialized carbide grades for continuous boring head assemblies. MEE enforcement of dual carbon goals pressures domestic foundries toward cleaner alloy production with verified smelter energy provenance. Zhuzhou in Hunan Province anchors carbide powder metallurgy supply for domestic tunnel boring machine integration and export markets.
Peru
Copper porphyry operations in the Andean cordillera specify threaded carbide systems for vertical crater retreat and longhole stoping in deeper ore bodies. The Ministry of Energy and Mines mandates environmental impact assessments for extraction tooling supply chains. Arequipa and Cusco mining clusters drive specification for wear-resistant adaptors as open-pit transitions underground at Cerro Verde and Antamina.
United States
Nevada gold operations and Arizona copper districts specify premium carbide adaptors for blasthole drilling in hard-rock formations. EPA enforcement of embodied carbon disclosure shapes procurement specifications for imported tooling. Elko and Tucson mining services clusters concentrate drilling contractor activity with unbundled tool supply models replacing integrated rental agreements.
Rock Drill Shank Adaptor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated metallurgy capabilities determining premium positioning. The supplier base concentrates around powder metallurgy expertise and captive alloy formulation control. Three archetypes dominate: vertically integrated mining equipment houses with captive tool divisions, specialized carbide metallurgists serving multiple end-markets, and regional fabricators competing on price-adjusted delivery. Capacity expansion in Asian powder metallurgy and strategic partnerships for sensor integration represent the dominant competitive vectors.
Among European-integrated mining equipment suppliers, Sandvik and Epiroc exemplify the captive metallurgy archetype through in-house alloy control from powder to finished tool. Zhuzhou Old Craftsman Precision Alloy occupies a position within the specialized carbide metallurgist tier, anchoring supply for Chinese infrastructure tunneling projects. These three represent distinct strategic postures: backward integration into raw material control, equipment-to-consumables bundling, and focused carbide grade specialization for adjacent industrial applications.
| Leading Market Players |
|---|
| Epiroc |
| Sandvik |
| Furukawa Rock Drill |
| Boart Longyear |
| Hunan Nonferrous Chenzhou Drill Tools |
| Changsha Heijingang Industrial |
| Zhuzhou Old Craftsman Precision Alloy |
| Maxdrill Rock Tools |
| Litian Heavy Industry |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied carbon tracking mandates are forcing European extraction companies to specify verified smelter energy provenance, compelling Asian foundries to invest in certification infrastructure and passing compliance premiums through to carbide-tipped adaptor pricing.
Pricing Analysis
Short lead-time premiums dominate transactional pricing as Australian underground contractors pay surcharges for ISO 18758-certified threaded adaptors delivered within compressed windows. Three-tier pricing structure across premium certified, standard compliant, and economy uncertified levels separates Sandvik's captive-alloy positioning from regional fabricators competing on spot availability. Cost compression in steel-alloy segments is intensifying as Chinese suppliers defend volume against carbide substitution in African contract drilling markets. Contract drillers in Southeast Asia exhibit highest price sensitivity, while integrated mining houses in Chile prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Refurbishment flows from Chilean copper-gold operations back to certified reconditioning facilities in Peru are creating reverse-logistics revenue streams for adaptor specialists. Primary tungsten ore processing concentrates in Chinese smelters, with secondary carbide sintering capacity anchored in Zhuzhou and export-oriented finishing distributed across Taiwan and South Korea. Supply chain risk centers on single-source vulnerability in tungsten concentrate from Chinese state-controlled mining concessions. Distribution runs through qualified supplier lists maintained by BHP and Codelco procurement offices, with spot market penetration limited to African exploration contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbide-tipped sensor-integrated adaptors are displacing conventional steel-alloy tooling in hard-rock extraction, compressing the technology-transition window for suppliers to reposition metallurgy capabilities.
For Market Incumbents: Hedge against tungsten supply concentration by securing alternative concentrate offtake from Vietnamese and Russian mining operations, while accelerating captive powder metallurgy capacity to defend margin position against emerging Asian carbide specialists. Certification investment in MEE-compliant smelter energy provenance creates compliance advantages for EU Green Deal procurement specifications. For New Entrants and Emerging Players: Capture unbundled aftermarket service contracts from African and Southeast Asian contract drillers separating tool supply from maintenance agreements, where direct manufacturer relationships enable margin capture absent in integrated rental models. Target quarrying segments in Brazil and Indonesia with tapered steel-alloy adaptors where rock abrasiveness does not justify carbide premiums and coupling speed drives specification. For Investors and Strategic Acquirers: The window for entry favors specialized carbide metallurgists with tunnel boring machine integration capabilities, as Chinese infrastructure expansion pulls adjacent application volume beyond traditional percussive drilling. Powder metallurgy skill scarcity and captive alloy formulation control represent durable moats. Monitor MEE enforcement intensity and EU carbon border adjustment mechanism implementation as inflection indicators for certified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Concentrate | Secures input supply against Chinese smelter concentration for carbide-dependent manufacturers. |
| ISO 18758 Certification Investment | Unlocks qualified supplier status with BHP and Codelco procurement offices in Chile and Australia. |
| Sensor-Integrated Adaptor Development | Automates predictive maintenance scheduling for Chilean underground copper-gold contractors. |
| Tunnel Boring Machine Grade Specialization | Captures Chinese high-speed rail and urban metro infrastructure specification outside mining. |
| EU Green Deal Compliance Program | Enables verified smelter energy provenance disclosure for European extraction company procurement. |
Research Methodology
Trade statistics from customs authorities, mining equipment association shipment reports, and tungsten concentrate import records formed the secondary backbone, cross-referenced against primary interviews with procurement managers at Chilean copper operations, maintenance directors at Australian underground contractors, and powder metallurgy specialists at Chinese carbide producers. Bottom-up and top-down triangulation validated segment sizing across material grades and coupling geometries.
Bottom-up modeling aggregated country-level mining activity, drilling intensity metrics, and replacement cycle frequencies into volume estimates, while top-down approaches triangulated against equipment manufacturer revenue disclosures and aftermarket service reports. Segmentation dimensions included material type, coupling geometry, application methodology, and end-user procurement authority. CAGRs derived from trend extrapolation of carbide substitution rates and infrastructure project pipelines across the analysis window, with specific inputs from tunnel boring machine deployment schedules and copper-gold exploration camp activation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese tungsten export policy shifts and EU carbon border adjustment mechanism implementation timelines. Forecasts reflect documented assumptions regarding carbide penetration rates and certification adoption curves. Practitioners should monitor MEE enforcement intensity, ISO 18758 revision schedules, and contract drilling unbundling velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Latin America Mining Equipment Market