
 Mining Tester Market | 2026-2036
Mining Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Tester Market Outlook
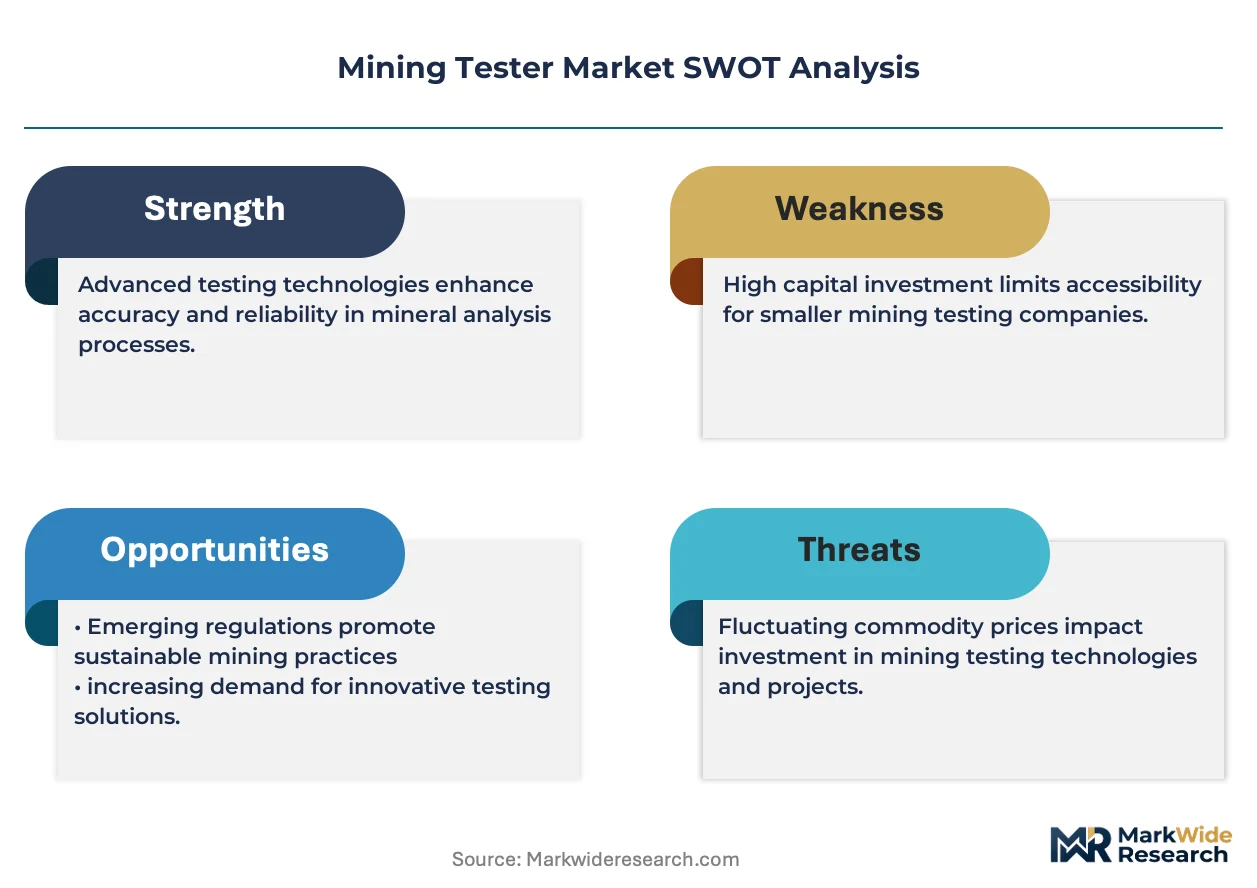
ISO/IEC 17025 accreditation for analytical laboratories is bifurcating the competitive landscape between certified and non-certified equipment suppliers. Bruker leverages its mass spectrometry heritage to sustain premium positioning in sample analyzer segments. Hitachi High-Tech Corporation anchors its presence through handheld XRF systems that dominate portable field assays. Thermo Fisher Scientific competes by extending its life sciences instrumentation expertise into mining-specific elemental analysis workflows.
A mining tester is an instrument or system engineered to measure mineral composition, rock mechanical properties, or geophysical characteristics under field or laboratory conditions, typically operating across temperature ranges from minus 40 to plus 50 degrees Celsius and pressure ratings suited to deep-earth simulation. Its primary commercial purpose is to reduce exploration risk, optimize extraction economics, and ensure regulatory compliance across the mine lifecycle. Sample analyzers command the deepest margin pools due to recurring consumables and software service contracts, while remote sensing technology is displacing conventional grid-based sampling programs in greenfield exploration. Mining companies represent the most concentrated buyer segment, though environmental agencies are emerging as a faster-growing demand channel driven by post-closure monitoring mandates.
ISO standards, EPA methods for hazardous waste characterization, and Australia's Dam Safety Regulations collectively shape equipment specifications, calibration protocols, and market access requirements for suppliers seeking multi-jurisdictional deployment. The EPA's TCLP methodology directly determines leachate testing instrument configurations sold into North American base and precious metal operations. Stakeholders must monitor how interoperability standards between automation platforms and legacy geological databases evolve, as this interface will determine replacement cycles and vendor stickiness across installed bases.
Market Dynamics
Real-time ore analyzers are compressing exploration timelines while forcing legacy assay laboratories into defensive consolidation. Equipment vendors now compete on integration speed with automation platforms rather than standalone accuracy metrics.
Growth Catalysts
- ISO/IEC 17025 accreditation mandates:Australian and Canadian jurisdictions now require certified analytical workflows for tailings dam monitoring. This compels mine operators to replace uncertified field equipment.
- Lithium extraction precision requirements:Western Australia's Pilbara region demands sub-percent-grade resolution for spodumene sorting. Real-time analyzers reduce downstream processing waste.
- Automation platform integration:Mine operators are embedding testers directly into autonomous haulage and processing control loops. This eliminates manual sampling bottlenecks.
Market Restraints
- Sensor component concentration:High-purity scintillation crystals and X-ray tube anodes concentrate supply among three Japanese and German specialty material suppliers.
- Deep-earth simulation capex:Triaxial rock testing systems capable of replicating 5 km depth conditions require pressure vessel investments that mid-tier exploration firms cannot underwrite.
- EPA TCLP methodological rigidity:North American hazardous waste characterization rules lock instrument configurations to specific leachate testing protocols, limiting hardware adaptability.
Strategic Opportunities
- Post-closure environmental monitoring:Brazil's ANVISA and state environmental agencies are mandating decades-long groundwater and tailings chemistry tracking at shuttered sites.
- Handheld XRF plus cloud analytics convergence:Field assay devices paired with real-time geostatistical modeling platforms enable on-the-spot ore body delineation without laboratory turnaround.
- Direct-to-mine rental channels:Equipment-as-a-service models bypass distributor markups for junior exploration companies in Chile's Atacama and Canada's Yukon.
Industry Challenges
- Geotechnical calibration expertise scarcity:Certified technicians capable of validating triaxial and direct shear apparatus against ASTM and ISRM standards are concentrated among retiring specialists in South Africa and Australia.
- Legacy database integration friction:Mine-site geological information systems built on 1990s-era formats resist API connections to modern IoT-enabled testers, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Tester Market |
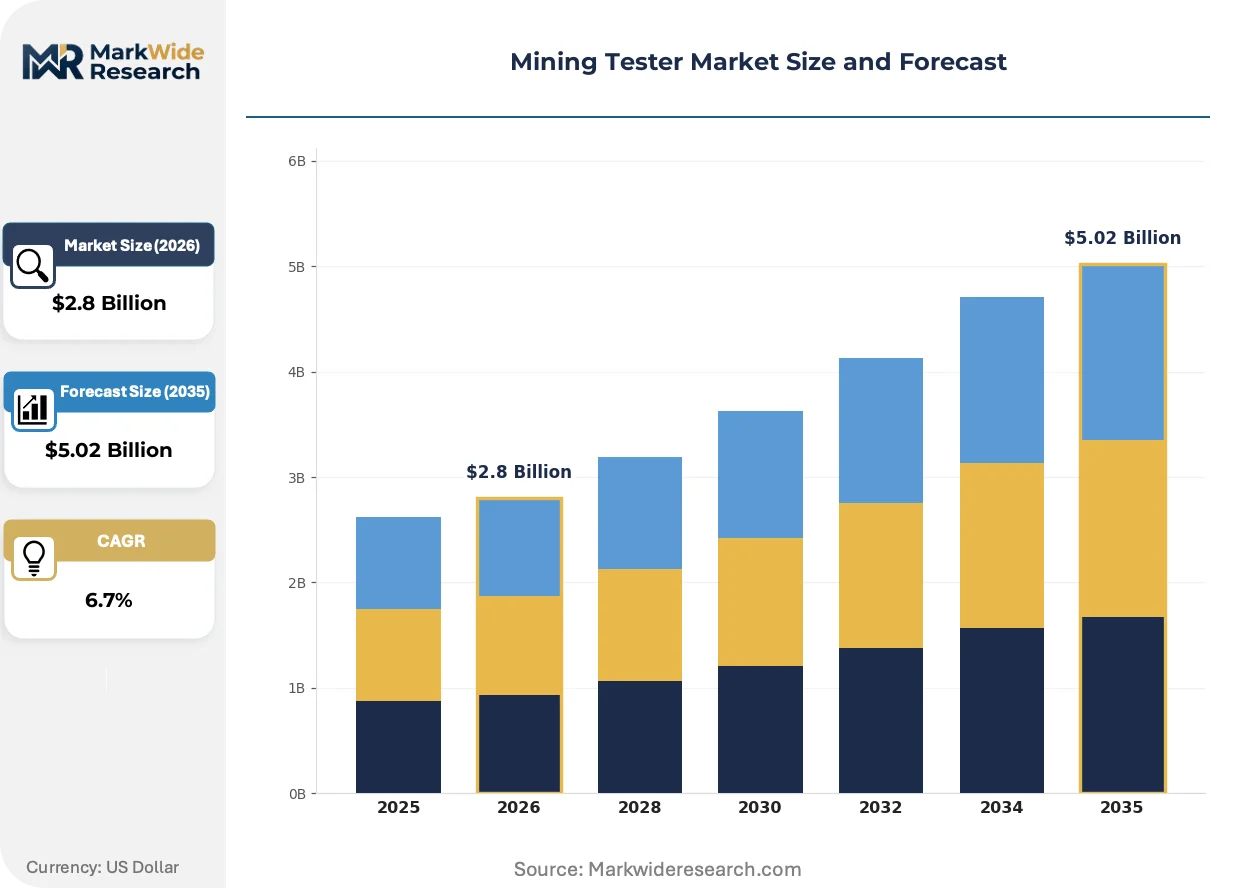
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Bits, Geophysical Equipment, Sample Analyzers, Rock Tests End User: Mining Companies, Geological Surveys, Environmental Agencies, Consultants Technology: Conventional Methods, Remote Sensing, Digital Imaging, Automation Application: Mineral Exploration, Site Assessment, Environmental Monitoring, Quality Control |
| Companies Covered | AMETEK, Qualitest International, Bruker, Olympus Corporation, Hitachi High-Tech Corporation, Thermo Fisher Scientific, Oxford Instruments, SGS SA, Bureau Veritas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Tester Market Strategic Shifts
Sensor fusion and edge computing are collapsing the distinction between field-portable and laboratory-grade instrumentation. Vendors now optimize for harsh-environment durability and wireless telemetry rather than benchtop precision alone.
LIBS technology is miniaturizing. Laser-induced breakdown spectroscopy units now fit handheld form factors for immediate light-element detection at blast faces. Major iron ore producers in Western Australia are deploying these units for real-time silica monitoring. The technology is compressing conventional sample-to-decision cycles from days to minutes.
REACH substance restrictions are reshaping consumables supply chains. The European Chemicals Agency's candidate list now captures several rare-earth phosphors used in scintillation detectors. Manufacturers are reformulating sensor arrays to eliminate restricted materials. German and Finnish analytical instrument makers are accelerating alternative phosphor qualification programs.
Service unbundling is fragmenting buyer-vendor relationships. Mining companies are separating hardware procurement from calibration and maintenance contracts, soliciting third-party metrology specialists for ISO 17025 compliance. This pattern is most pronounced among mid-tier gold and copper operators in Chile and Peru seeking to reduce captive service premiums.
Mining Tester Market Segmentation
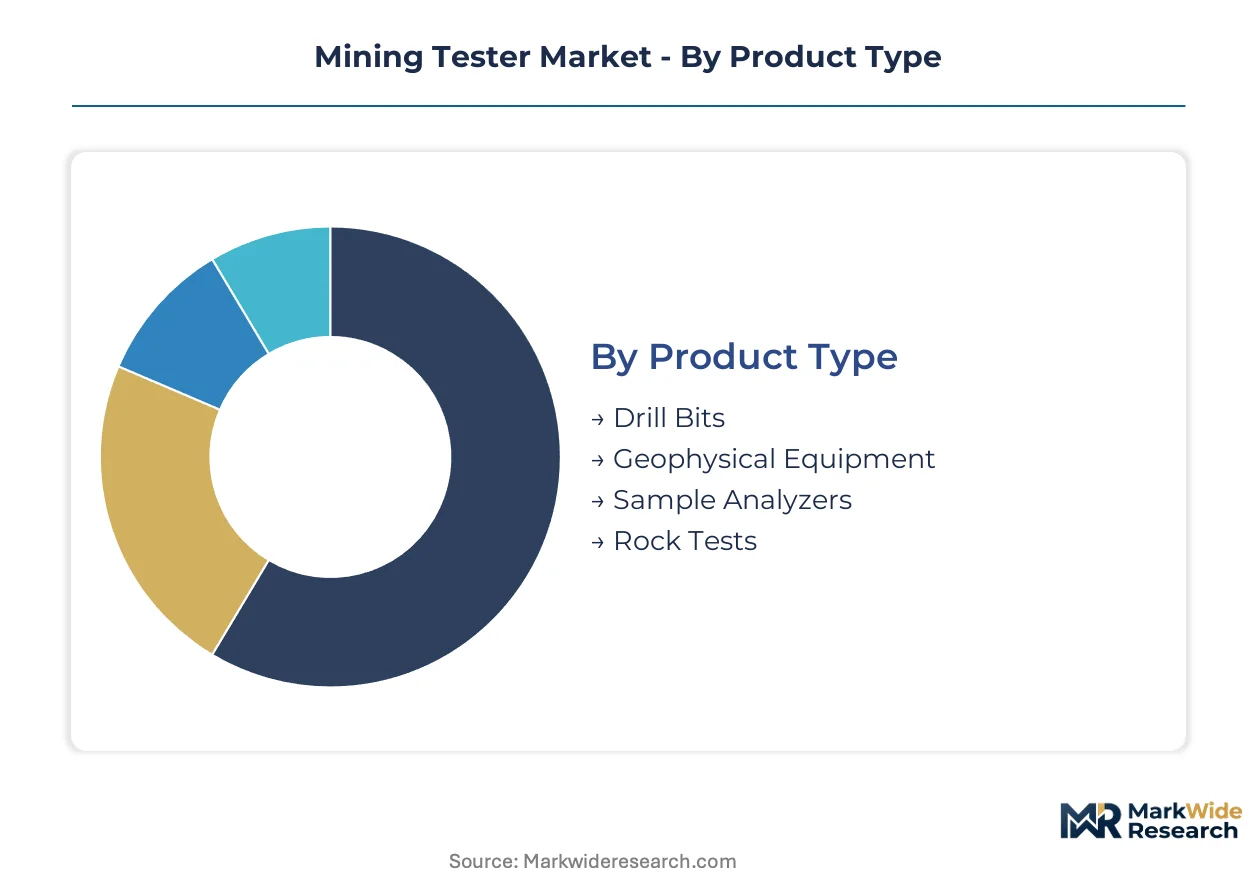
Equipment procurement channels diverge sharply by segment sophistication. Sample analyzers flow through certified distributor networks with service contracts attached, while geophysical equipment increasingly routes through direct-to-mine rental platforms.
Product Type:
Channel economics split between consumables-heavy segments and capital-intensive systems. Rental penetration runs highest where mobility requirements clash with balance-sheet constraints.
- Sample Analyzers:XRF and mass spectrometry systems dominate margin pools through recurring consumables and ISO 17025 calibration contracts. Western Australia's Pilbara iron ore and lithium corridors drive procurement at scale, with real-time silica and spodumene grade resolution commanding premium positioning.
- Geophysical Equipment:Seismic and electromagnetic survey systems anchor exploration budgets for greenfield delineation. Demand concentrates in Canada's Athabasca Basin and Nevada's Carlin Trend, where deep-target resolution justifies airborne and ground-based platform deployment.
- Rock Tests:Triaxial and direct shear apparatus validate geotechnical parameters for tailings dam design.
- Drill Bits:Core and reverse circulation tooling represent high-velocity consumables with localized supply chains.
Sample analyzers dominate installed base. Geophysical equipment is where expansion concentrates.
End User:
Buyer sophistication tiers determine specification rigor and contract structure. Certification mandates reshape procurement authority across organizational boundaries.
- Mining Companies:Integrated operators and mid-tier producers constitute the volume anchor, with procurement centralized under chief geoscientists. Western Australian iron ore majors and Chilean copper conglomerates specify automation-ready instrumentation with API compatibility for legacy geological databases.
- Environmental Agencies:Post-closure monitoring mandates in Brazil and Canada are accelerating demand for groundwater chemistry and tailings seepage tracking. ANVISA and provincial Canadian regulators now require decades-long surveillance protocols at shuttered sites.
- Geological Surveys:National mapping programs fund systematic regional coverage with standardized methodologies.
- Consultants:Junior exploration firms and engineering advisory practices favor rental and third-party assay services to preserve capital flexibility.
Mining companies anchor procurement volume. Environmental agencies are climbing the fastest.
Technology:
Adoption curves diverge by data latency tolerance and capital availability. Legacy assay workflows face displacement where real-time feedback loops justify sensor investment.
- Remote Sensing:Hyperspectral imaging and LiDAR platforms collapse greenfield exploration timelines from months to weeks. Deployment concentrates in Canada's Northwest Territories and Mongolia's South Gobi, where infrastructure absence makes airborne platforms economically decisive.
- Automation:IoT-enabled testers embedded in autonomous haulage and processing control loops eliminate manual sampling bottlenecks. Western Australian iron ore operations lead integration, with real-time ore sorting feeding directly into crusher and concentrator setpoints.
- Digital Imaging:Automated core logging and photogrammetric fracture mapping accelerate geological interpretation.
- Conventional Methods:Laboratory assay and manual geotechnical testing retain share where certification requirements or low throughput favor established workflows.
Conventional methods dominate installed base. Automation is where expansion concentrates.
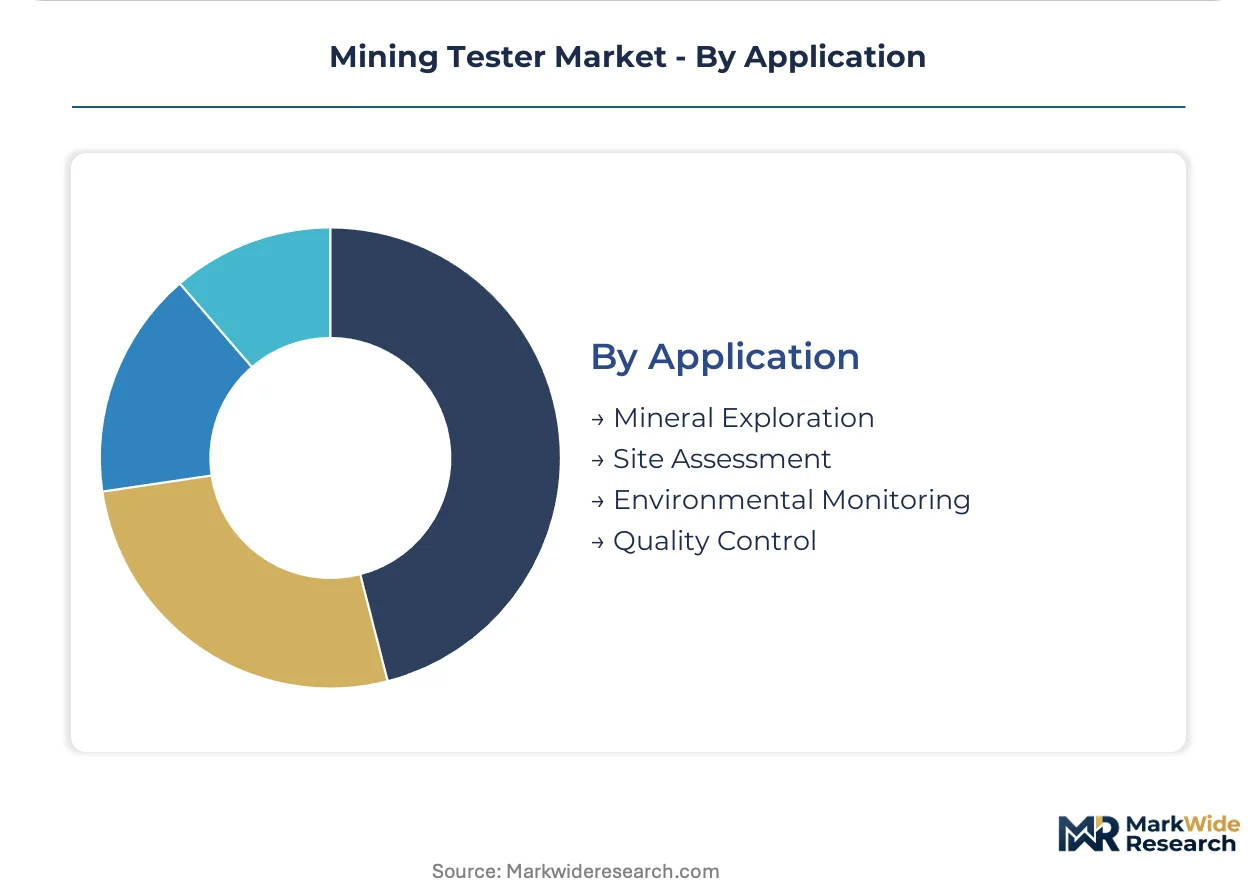
Application:
Work phase determines equipment mobility requirements and analytical precision thresholds. Early-cycle applications prioritize speed; late-cycle applications demand regulatory defensibility.
- Mineral Exploration:Greenfield and brownfield target delineation drives the highest equipment velocity, with portable XRF and LIBS units replacing grid-based sampling programs. Pilbara lithium and Nevada gold corridors concentrate handheld device deployment.
- Environmental Monitoring:Post-closure groundwater and tailings chemistry tracking now spans multi-decade mandates. Brazil's ANVISA and Canadian provincial agencies specify automated sampling stations with telemetry for remote site surveillance.
- Site Assessment:Pre-production geotechnical characterization and resource validation support feasibility studies and financing.
- Quality Control:Process plant feed monitoring and product certification require continuous or high-frequency assay throughput.
Mineral exploration dominates installed base. Environmental monitoring is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore majors in Western Australia and copper conglomerates in Chile anchor procurement volume for real-time analyzers and geotechnical systems. Environmental agencies in Brazil and Canada are climbing fastest as post-closure monitoring mandates extend instrument deployment timelines.
Australia
Pilbara iron ore operations and lithium spodumene projects drive demand for sub-percent-grade resolution analyzers. The country's Dam Safety Regulations compel operators to upgrade geotechnical testing programs for tailings facilities. Perth-based procurement clusters concentrate real-time silica monitoring deployments across Western Australian mine sites.
Chile
Atacama copper operations and junior exploration firms require portable field assay capabilities and rental service models. The national mining regulator enforces progressive closure planning that extends instrument lifecycles into post-production phases. Santiago procurement offices coordinate automation-ready instrumentation for integration with autonomous haulage systems.
Canada
Athabasca Basin uranium exploration and Nevada-adjacent gold corridors sustain demand for deep-target geophysical platforms. Provincial environmental agencies mandate decades-long groundwater surveillance at shuttered base metal sites. Vancouver and Toronto serve as procurement hubs linking exploration budgets to certified distributor networks.
Brazil
Iron ore majors in Minas Gerais and post-closure monitoring mandates at depleted sites accelerate environmental agency procurement. ANVISA regulations specify automated sampling stations with telemetry for tailings seepage tracking. Belo Horizonte engineering clusters coordinate multi-decade surveillance protocol implementation.
United States
Nevada's Carlin Trend gold operations and Arizona copper porphyry systems require grid-based sampling displacement through portable LIBS units. EPA TCLP methodology locks leachate testing configurations for hazardous waste characterization. Denver and Reno exploration offices concentrate greenfield delineation technology deployment.
Mining Tester Market Competitive Environment
Player mix skews toward diversified analytical instrument conglomerates with mass spectrometry and elemental analysis heritage. The competitive structure concentrates around three strategic tiers: premium-certified laboratories, field-portable specialists, and integrated automation platform vendors. Dominant moves include ISO 17025 accreditation pursuit for laboratory workflow capture and API compatibility development for legacy geological database integration.
Within the premium-certified tier, Bruker and Thermo Fisher Scientific exemplify positioning anchored in analytical precision and recurring service contract structures. Hitachi High-Tech Corporation occupies a distinct field-portable position through handheld XRF system concentration. These three entities represent the archetype spectrum from laboratory-grade certification dependency to mobility-optimized deployment models.
| Leading Market Players |
|---|
| AMETEK |
| Qualitest International |
| Bruker |
| Olympus Corporation |
| Hitachi High-Tech Corporation |
| Thermo Fisher Scientific |
| Oxford Instruments |
| SGS SA |
| Bureau Veritas |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay service contracts spanning five-to-seven year terms lock in both scintillation crystal supply from Japanese specialty material houses and predictable calibration revenue for ISO 17025-certified laboratories. This structure gives Bruker and Thermo Fisher Scientific forward price visibility while exposing mid-tier exploration firms to minimum volume commitments they cannot absorb during commodity downturns.
Pricing Analysis
Cost-plus contracts indexed to rare-earth phosphor spot markets dominate consumables-heavy segments. Price differentiation hinges on ISO 17025 certification tier and after-sales bundling intensity. Cost compression in handheld XRF rentals is intensifying because Chilean junior miners are unbundling hardware from service contracts. Environmental agencies show least price sensitivity due to multi-decade regulatory mandates, while Atacama exploration startups negotiate aggressively on lease rates.
Supply Chain Analysis
Inventory cycles for high-purity scintillation crystals stretch eighteen to twenty-four months due to single-source concentration in Japan and Germany. Manufacturing draws from rare-earth phosphors, X-ray tube anodes, and precision optical substrates. Single-source vulnerability concentrates in Japanese scintillation crystal production. Distribution runs through certified distributor networks for laboratory-grade systems and direct-to-mine rental platforms for portable field units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time ore analyzer deployment is compressing assay laboratory timelines from days to minutes, creating displacement pressure that rewards vendors with automation-ready API architectures. ANVISA's post-closure monitoring mandates in Brazil extend instrument deployment into multi-decade horizons.
For Market Incumbents: Consolidate calibration and metrology service capabilities to capture ISO 17025 compliance workflows that mid-tier miners are unbundling from hardware contracts. Acquire API compatibility layers for 1990s-era geological databases to defend against middleware startups threatening replacement cycles. Threat: sensor fusion startups collapsing field-laboratory grade distinctions. Lever: vertical integration into scintillation crystal qualification programs. For New Entrants and Emerging Players: Post-closure environmental monitoring service gaps expose white-space where incumbent laboratories lack telemetry-enabled automated sampling stations. Target Brazil's ANVISA-mandated tailings surveillance programs and Canadian provincial groundwater tracking mandates. Go-to-market angle: equipment-as-a-service rentals bypassing distributor markups for Yukon and Atacama junior explorers. For Investors and Strategic Acquirers: Capital is best deployed toward handheld LIBS specialists with cloud analytics integration and proven Western Australian iron ore site deployments. Long-term viability rests on displacement of grid-based sampling programs in greenfield exploration. Signal to watch: interoperability standard adoption between automation platforms and legacy geological databases as inflection indicator for vendor stickiness.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Pursuit | Captures laboratory workflow mandates from Australian Dam Safety Regulations and Canadian tailings protocols. |
| API Compatibility Development | Reduces middleware friction for 1990s-era geological database integration in Western Australian iron ore operations. |
| Equipment-as-a-Service Launch | Bypasses distributor markups for capital-constrained junior explorers in Chile's Atacama and Canada's Yukon. |
| Alternative Phosphor Qualification | Addresses REACH substance restrictions on rare-earth phosphors used in scintillation detectors. |
| Cloud Analytics Platform Integration | Enables real-time geostatistical modeling for on-the-spot ore body delineation without laboratory turnaround. |
Study Parameters
Initial hypotheses were tested against primary input from mine site geoscientists, chief metallurgists at Western Australian iron ore majors, environmental compliance officers at Brazilian state agencies, and aftermarket service directors at certified distributor networks, then refined against customs data for scintillation crystal imports, EPA method documentation for TCLP configurations, ISO 17025 accreditation registries, and SEC filings from analytical instrument conglomerates. Bottom-up equipment procurement tracking and top-down market sizing triangulated volume estimates.
Variance decomposition across product type, end user sophistication tier, technology adoption curve, and application work phase shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level equipment replacement cycles and regulatory mandate timelines. Forecast inputs included lithium extraction precision requirements in Western Australia's Pilbara and post-closure monitoring mandate expansion in Brazil and Canada.
Forecasts assume regulatory continuity in Australian Dam Safety Regulations, Canadian provincial environmental statutes, and Brazil's ANVISA tailings surveillance protocols; material policy shifts would require re-modeling. Commodity price volatility, sensor component supply disruptions, and interoperability standard delays constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
DTH Drill Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
North America Mining Equipment Market