
 North America Mining Equipment Market | 2026-2036
North America Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mining Equipment Market Outlook
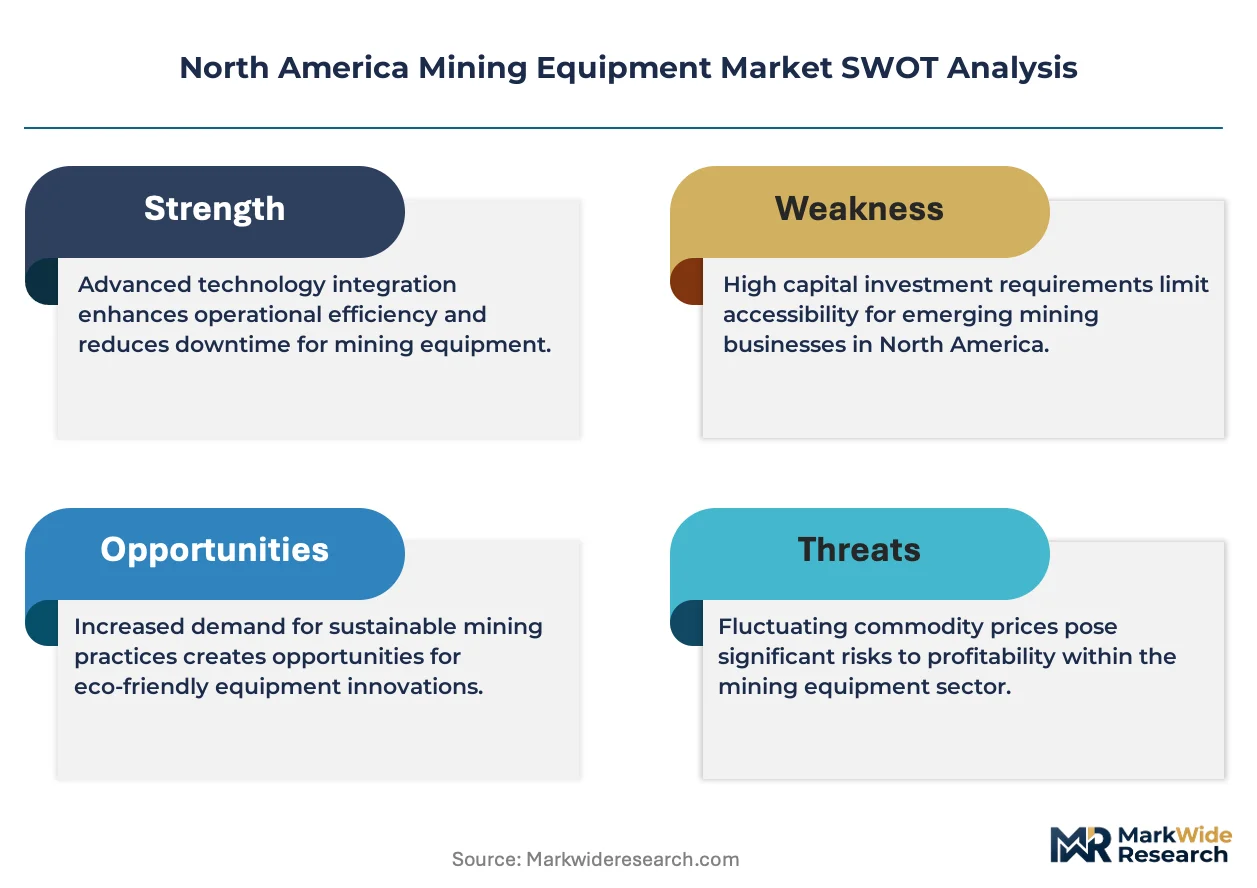
ISO 19434 safety classification for autonomous mining machinery is redrawing competitive entry barriers across North America. Caterpillar Inc. leverages its integrated autonomy stack to anchor large-scale deployment in Arizona copper operations. Komatsu Ltd. competes through its Command remote-control platform, sustaining technology leadership in haulage applications. Epiroc AB specializes in battery-electric underground loaders, differentiating its portfolio from diesel-dependent rivals as zero-emission mandates tighten.
North America mining equipment encompasses heavy-duty machinery engineered for mineral extraction, earthmoving, and material processing with operating weights exceeding 100 metric tons and power ratings above 750 kW. These systems perform drilling, loading, hauling, and crushing functions essential to surface and underground ore production. Excavators and loaders dominate capital expenditure flows due to their universal deployment across metal and coal mining applications. Automated equipment commands premium positioning as labor shortages and safety targets push tier-1 mining companies toward remote-operated fleets. Conventional machinery retains substantial installed-base relevance in quarrying segments where capital constraints limit technology upgrades.
MSHA ventilation and diesel particulate rules, EPA Tier 4 Final emissions standards, and Canadian provincial carbon pricing frameworks collectively force equipment redesign toward electrified powertrains and exhaust after-treatment systems. Compliance costs filter through procurement budgets, favoring suppliers with certified clean-diesel and battery-electric platforms already in commercial production. Stakeholders must weigh electrification roadmaps against residual value risks in fossil-fuel-dependent mining districts before committing to fleet transformation strategies.
Market Dynamics
EPA Tier 4 Final emissions standards and MSHA diesel particulate mandates are forcing synchronous fleet replacement across southwestern US copper and lithium operations, compressing capital deployment timelines while elevating electrified powertrain procurement priority.
Growth Catalysts
- Battery supply chain localization:Domestic lithium extraction in Nevada and Arizona is accelerating demand for specialized hauling and processing equipment to serve EV manufacturing commitments from Detroit automakers.
- MSHA ventilation modernization:Underground metal mines are retrofitting diesel fleets with exhaust after-treatment systems to meet enhanced air quality thresholds, triggering replacement cycles for loaders and haul trucks.
- Copper electrification demand:Grid infrastructure expansion and renewable energy buildouts are sustaining high-grade copper ore throughput requirements across Arizona's porphyry deposits.
Market Restraints
- Steel and alloy input volatility:Specialized high-strength plate and wear-resistant components face price instability from scrap metal supply fluctuations, compressing fabrication margins for OEMs.
- Canadian provincial carbon pricing:Alberta and British Columbia mining operations face layered compliance costs that delay electrification investments in fossil-fuel-dependent oil sands and coal districts.
- Battery energy density limitations:Current lithium-ion cell configurations restrict continuous operation cycles for underground loaders below eight hours, constraining productivity in deep-vein extraction.
Strategic Opportunities
- Mexican mineral corridor development:Sonora lithium clay deposits and Zacatecas silver districts present underpenetrated demand for surface excavation and material handling systems.
- Autonomous haulage convergence:Integration of perception sensors with 5G private networks enables remote operation centers to manage multi-pit fleets across dispersed Nevada gold-silver properties.
- US Inflation Reduction Act critical minerals incentives:Domestic content requirements for battery materials are redirecting capital toward US-based extraction, elevating equipment procurement from North American suppliers.
Industry Challenges
- Electrification technician scarcity:Mines lack personnel trained in high-voltage battery management and thermal runaway containment, slowing deployment of electric underground fleets.
- ISO 19434 certification timelines:Autonomous machinery safety validation requires extended field testing periods that delay commercial deployment and revenue recognition.
- Legacy diesel fleet residual value collapse:Accelerated regulatory phase-out schedules are stranding conventional underground equipment before depreciation cycles complete, compressing asset recovery rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mining Equipment Market |
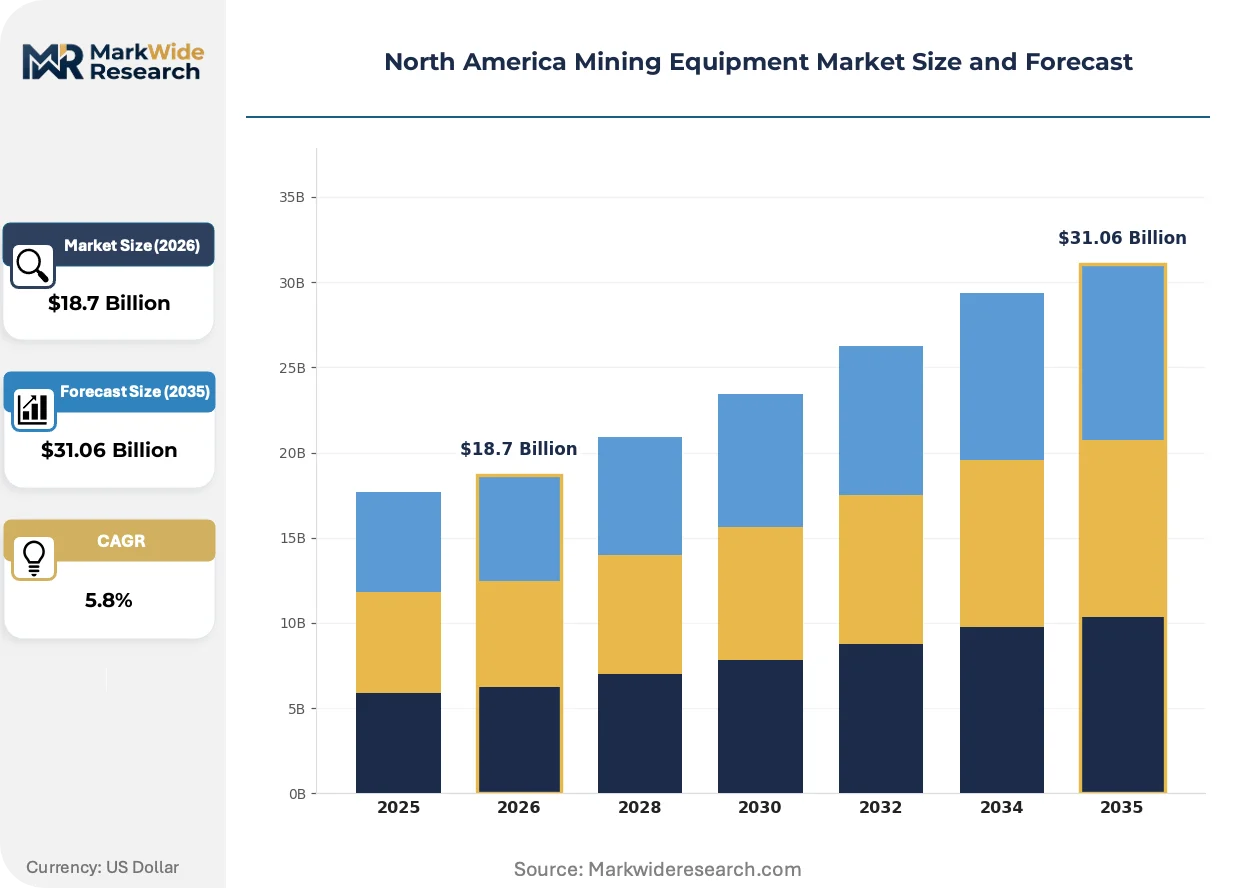
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Drills, Crushers Application: Metal Mining, Mineral Mining, Coal Mining, Quarrying Technology: Automated Equipment, Remote Operated Machinery, Hybrid Systems, Conventional Machinery End User: Mining Companies, Contractors, Tier-1 Suppliers, Service Providers |
| Companies Covered | Sandvik AB, Hitachi Construction Machinery Co., Ltd., Caterpillar Inc., Metso Corporation, Volvo Construction Equipment Ltd., Komatsu Ltd., Liebherr Group, Terex Corporation, Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mining Equipment Market Strategic Shifts
Powertrain electrification and autonomous operation are converging to redefine equipment lifecycle economics across North American extraction operations, with regulatory pressure acting as the primary adoption accelerant rather than voluntary efficiency gains.
Battery-electric underground loaders are bifurcating fleet procurement strategies between zero-emission mandates in Arizona copper operations and continued diesel reliance in cost-constrained quarrying segments. Tier-1 miners with balance sheet capacity are absorbing premium capital costs for electrified units, while mid-tier surface operators extend conventional equipment service intervals. This technology split is compressing supplier R&D allocation toward dual-platform development rather than single-architecture optimization.
EPA Tier 4 Final non-road diesel standards are compelling exhaust after-treatment retrofits or full powertrain replacements for underground machinery operating in confined ventilation environments. Equipment OEMs must certify selective catalytic reduction and diesel particulate filter integrations that maintain MSHA-approved engine envelope dimensions. Underground metal mining segments in Idaho and Montana are absorbing compliance premiums most acutely due to older installed base age profiles.
Consolidated procurement through integrated mine operators is displacing fragmented equipment purchasing across independent contractors in Nevada gold extraction. Large-scale operators are centralizing fleet standardization decisions and negotiating enterprise service agreements that bundle maintenance, parts, and technology upgrades. This buyer concentration shift is most visible in the Carlin and Cortez trends where single operators control multiple adjacent deposits.
North America Mining Equipment Market Segmentation
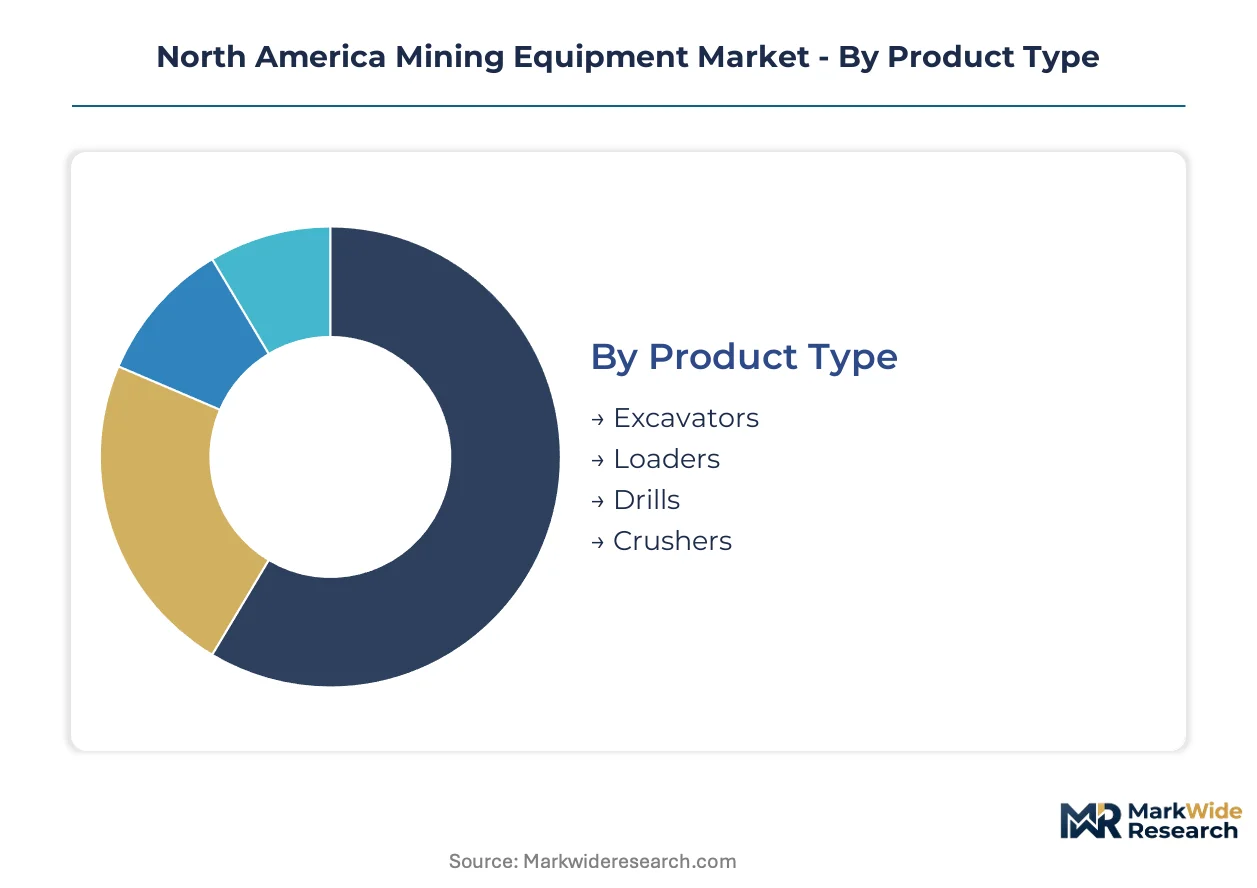
Equipment procurement patterns across North American mining operations fragment sharply between regulatory compliance mandates and capital availability constraints. Segment boundaries determine supplier R&D allocation, aftermarket service bundling, and residual value risk exposure for fleet operators.
Product Type:
EPA Tier 4 Final and MSHA diesel particulate rules are compressing replacement timelines most acutely for underground-capable equipment categories with confined-space ventilation requirements.
- Excavators:Hydraulic crawler units with operating weights above 200 metric tons dominate surface copper and lithium extraction in Arizona and Nevada. Arizona's porphyry copper deposits absorb the heaviest crawler deployments as open-pit depths extend below 1,000 feet.
- Loaders:Underground wheel loaders face the steepest electrification pressure from MSHA ventilation modernization mandates. Battery-electric variants from specialized OEMs are displacing diesel units in Idaho and Montana metal mines where exhaust after-treatment retrofits prove dimensionally impractical.
- Drills:Rotary and percussion drilling rigs serve blasthole preparation across Nevada gold-silver trends.
- Crushers:Primary gyratory and cone crushing systems process high-throughput copper ore streams.
Excavators handle the majority of throughput; loaders are expanding most quickly on share as electrification mandates tighten.
Application:
Capital deployment intensity varies directly with ore grade economics and energy transition mineral demand concentration.
- Metal Mining:Copper, gold, and silver extraction commands premium equipment specifications across Arizona and Nevada. The Inflation Reduction Act's domestic content requirements for battery materials are redirecting capital toward US-based copper and lithium projects, elevating fleet procurement from North American suppliers.
- Mineral Mining:Lithium clay and potash operations in Nevada and Saskatchewan require specialized bulk material handling systems with corrosion-resistant components.
- Coal Mining:Appalachian and Powder River Basin operations face accelerated depreciation schedules from carbon pricing exposure.
- Quarrying:Aggregate producers in Texas and California extend conventional equipment service intervals due to capital constraints.
Metal mining absorbs the dominant capital share; mineral mining shows the steepest expansion trajectory from EV supply chain localization.
Technology:
Automation certification timelines and technician availability are bifurcating procurement between balance-sheet-capable tier-1 miners and cost-constrained mid-tier operators.
- Automated Equipment:Autonomous haul trucks with ISO 19434 safety classification are anchoring large-scale deployment in Arizona copper operations. Perception sensor integration with 5G private networks enables remote operation centers to manage multi-pit fleets across dispersed Nevada properties.
- Remote Operated Machinery:Line-of-sight and tele-remote systems bridge the gap between full autonomy and conventional operation in hazardous underground environments.
- Hybrid Systems:Diesel-electric powertrains offer transitional compliance for mines lacking high-voltage infrastructure.
- Conventional Machinery:Human-operated diesel equipment retains installed-base relevance in quarrying segments where technology upgrade capital is unavailable.
Automated equipment commands premium positioning; remote operated machinery is gaining share fastest as a lower-capital pathway to labor reduction.
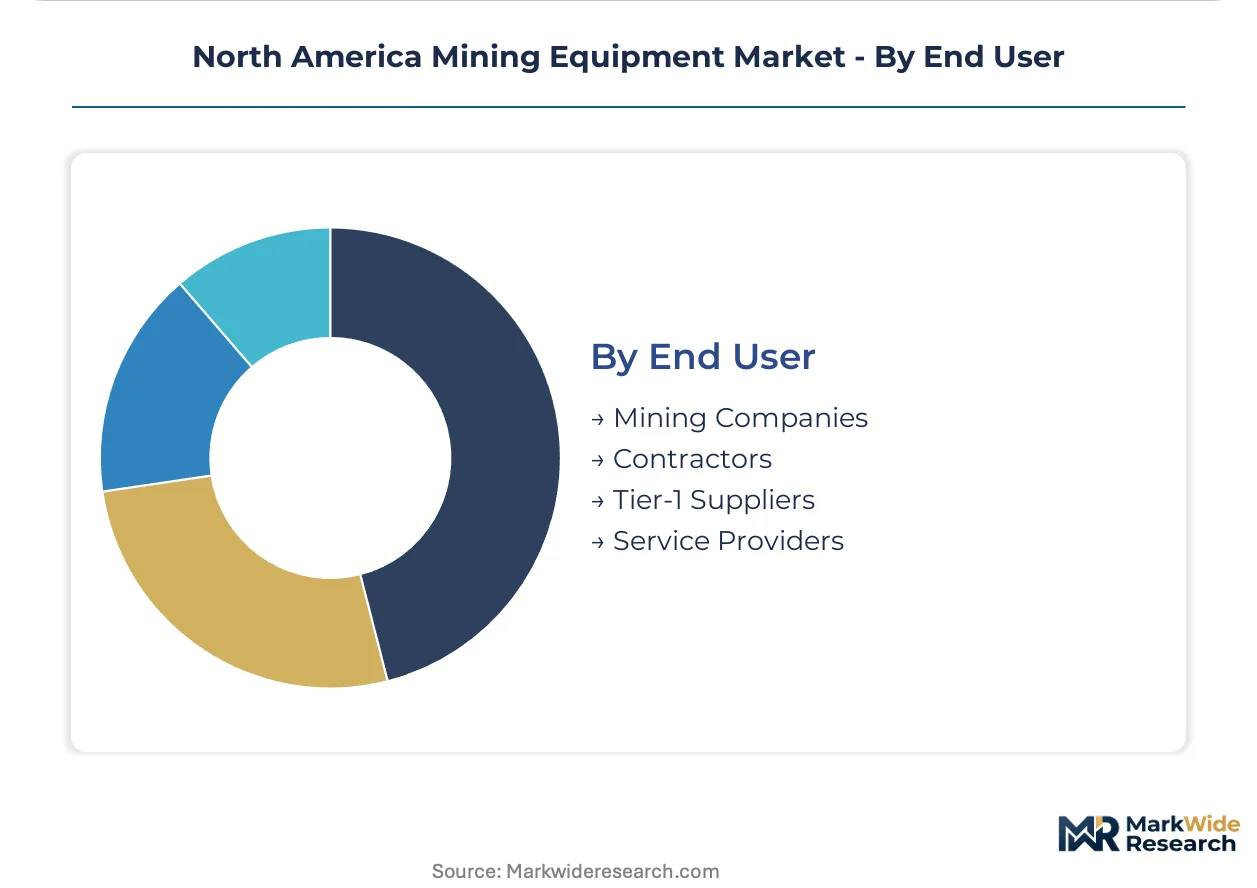
End User:
Fleet standardization authority is concentrating through integrated mine operators, displacing fragmented procurement across independent contractor networks.
- Mining Companies:Large-scale operators centralize fleet decisions and negotiate enterprise service agreements bundling maintenance, parts, and technology upgrades. Consolidated procurement is most visible in Nevada's Carlin and Cortez trends where single operators control multiple adjacent deposits.
- Contractors:Independent mining services face margin compression from buyer concentration and equipment standardization requirements.
- Tier-1 Suppliers:OEM captive finance arms and authorized distributors provide bundled equipment and service packages.
- Service Providers:Aftermarket maintenance and rebuild specialists serve aging installed bases in cost-constrained segments.
Mining companies direct the majority of procurement volume; tier-1 suppliers are climbing fastest on share through vertical service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Inflation Reduction Act critical minerals incentives are redirecting capital toward domestic copper and lithium extraction, compressing equipment procurement timelines across southwestern deposits while Canadian carbon pricing and Mexican energy reform create divergent investment climates.
United States
Arizona's porphyry copper belt and Nevada's lithium clay deposits are absorbing the heaviest equipment deployments as battery supply chain localization accelerates. EPA Tier 4 Final emissions standards and MSHA ventilation mandates are forcing synchronous fleet replacement in underground metal mines across Idaho and Montana. The Carlin and Cortez gold-silver trends concentrate autonomous haulage adoption where single operators control multiple adjacent deposits.
Canada
Alberta oil sands and British Columbia coal operations face layered compliance costs from provincial carbon pricing frameworks that delay electrification investments. Saskatchewan potash mines require specialized bulk material handling systems with corrosion-resistant components for high-throughput extraction. Ontario's Sudbury Basin nickel-copper operations anchor battery-electric underground loader trials as zero-emission mandates tighten.
Mexico
Sonora's lithium clay deposits and Zacatecas silver districts present underpenetrated demand for surface excavation systems as energy reform opens mineral corridors to foreign investment. The country's national mining regulator has streamlined permitting for strategic minerals to align with nearshoring objectives. Northern border states concentrate hauling equipment procurement to serve US-based processing facilities.
North America Mining Equipment Market Competitive Environment
Player mix skews toward integrated full-line suppliers with captive autonomy stacks and specialized electrification pioneers with battery-electric underground portfolios. Market structure concentrates procurement authority through tier-1 mining companies negotiating enterprise service agreements that bundle maintenance, parts, and technology upgrades. Two strategic archetypes dominate: diversified industrials with integrated finance arms and focused mining specialists with certified zero-emission platforms. Competitive moves center on strategic partnerships for 5G private network deployment and portfolio diversification into battery-electric powertrains.
Within the integrated supplier tier, Caterpillar Inc. and Komatsu Ltd. occupy positions anchoring large-scale autonomous deployment across Arizona copper operations. Epiroc AB exemplifies the electrification specialist archetype with certified battery-electric underground loaders that differentiate against diesel-dependent rivals. These three companies represent the competitive spectrum from full-line autonomy integration to focused zero-emission specialization as regulatory pressure bifurcates procurement strategies.
| Leading Market Players |
|---|
| Sandvik AB |
| Hitachi Construction Machinery Co., Ltd. |
| Caterpillar Inc. |
| Metso Corporation |
| Volvo Construction Equipment Ltd. |
| Komatsu Ltd. |
| Liebherr Group |
| Terex Corporation |
| Epiroc AB |
| Others |
Value Chain & Pricing Dynamics
Scale economies in high-strength steel fabrication and battery pack assembly are concentrating procurement leverage among tier-1 mining operators with multi-site fleet standardization authority, compressing margin recovery for mid-tier OEMs while elevating price floors for certified zero-emission platforms.
Pricing Analysis
Certification level creates the primary spread across the equipment landscape, with ISO 19434 autonomous safety validation and MSHA diesel particulate compliance commanding substantial premiums over conventional machinery. Three-tier pricing structure across premium, standard, and economy levels segments buyers by balance sheet capacity and regulatory exposure, with Arizona copper operators absorbing electrified premiums while quarrying segments extend legacy diesel service intervals. Cost compression in battery-electric underground loaders is intensifying because lithium cell supply constraints and high-voltage technician scarcity inflate service bundling costs. Independent contractors exhibit highest price sensitivity due to margin compression from buyer concentration, whereas integrated mining companies with captive finance access show lowest sensitivity to capital cost premiums.
Supply Chain Analysis
Inbound logistics costs from East Asian component hubs through West Coast ports are elevating working capital requirements for North American OEMs assembling electrified powertrains. Manufacturing concentration centers on the United States, Japan, and Sweden for autonomous system integration and battery-electric platform final assembly. Specialized high-strength plate and wear-resistant alloys draw from scrap metal recovery networks and primary steel producers in Canada and Mexico. Single-source vulnerability in lithium-ion cell supply creates exposure to cathode active material constraints from South Korean and Japanese chemical producers. Distribution runs through OEM captive finance arms and authorized dealer networks serving consolidated procurement decisions at integrated mine operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America mining equipment sits in early-cycle expansion as IRA critical minerals incentives redirect capital toward domestic copper and lithium extraction, compressing fleet replacement timelines before regulatory phase-out schedules mature.
For Market Incumbents: Shield installed-base service revenue through captive aftermarket parts and rebuild programs as electrification roadmaps strand legacy diesel fleets before depreciation cycles complete. Deepen backward integration into battery pack assembly and high-voltage thermal management systems to capture margin migrating from mechanical drivetrains. Prioritize ISO 19434 certification investment to maintain entry barriers against autonomy-stack challengers. For New Entrants and Emerging Players: Aftermarket electrification retrofit capabilities represent the most penetrable white-space as tier-1 OEMs prioritize new-build battery-electric platforms over legacy fleet conversions. Mexican mineral corridor development in Sonora lithium deposits offers geographic entry with lower incumbent saturation than Arizona-Nevada clusters. Pursue joint-venture structures with established component suppliers to bypass capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrification specialists with certified underground loader platforms and long-term service agreements. Five-to-ten year viability favors suppliers with dual-platform R&D roadmaps spanning diesel-electric transitional compliance and full battery-electric architectures. Monitor MSHA ventilation rulemaking timelines as inflection indicator for accelerated replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Deployment | Enables remote operation centers to manage multi-pit autonomous fleets across dispersed Nevada gold-silver properties. |
| Battery-Electric Platform Certification | MSHA and EPA Tier 4 Final compliance secures procurement eligibility in zero-emission mandate jurisdictions. |
| Backward Integration into Battery Assembly | Captive cell pack production reduces exposure to South Korean and Japanese cathode supply constraints. |
| Enterprise Service Agreement Bundling | Integrated maintenance, parts, and technology upgrade contracts lock in multi-year revenue from tier-1 mining operators. |
| Mexican Mineral Corridor Partnership | Sonora lithium and Zacatecas silver development aligns with nearshoring objectives and US processing facility demand. |
Study Parameters
Initial hypotheses were tested against primary input from maintenance directors at integrated copper operations, OEM procurement teams, aftermarket service heads, and MSHA compliance officers, and refined through secondary validation against SEC 10-K filings, EIA energy consumption data, customs and trade records, and Canadian provincial carbon pricing disclosures. Bottom-up equipment unit economics were triangulated with top-down mineral extraction capital expenditure flows across the analysis window.
Variance decomposition across product type, application, technology tier, and end-user concentration shaped the analytical framework, with CAGRs derived from regression against copper and lithium price trajectories, regulatory compliance timeline acceleration, and fleet age profile replacement schedules. Modeled inputs incorporated EPA Tier 4 Final adoption curves, MSHA ventilation modernization spend patterns, and IRA domestic content requirement phase-ins.
Forecasts assume regulatory continuity in EPA emissions standards and MSHA safety mandates; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
DTH Drill Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Rock Duster Market
Mining Equipment
Drilling Stabilizers Market