
 North America Drill Pipe Market | 2026-2036
North America Drill Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drill Pipe Market Analytics
Modular drill string configurations is pivoting procurement patterns as operators bundle heavyweight drill pipe with premium connections to reduce non-productive time. Tenaris SA leverages integrated seamless pipe mills across the region to control alloy sourcing. National Oilwell Varco, Inc. sustains aftermarket threading and inspection services that extend pipe life cycles. U.S. Steel Corporation anchors domestic flat-rolled supply for standard-grade production.
Drill pipe comprises hollow, thick-walled steel tubes with tool-jointed ends, typically manufactured from AISI 4145H modified alloy steel through rotary piercing and heat-treating to yield strengths exceeding 135 ksi, designed to transmit torque and convey drilling fluid in hydrocarbon extraction. Standard drill pipe occupies the mature volume tier where price competition compresses margins across commodity-grade tenders. Heavyweight drill pipe captures expanding share in extended-reach horizontal applications where fatigue resistance commands premium positioning. Lined drill pipe remains a niche growth category as corrosion-resistant cladding penetrates sour-gas basins.
API 5DP standards govern dimensional and mechanical specifications, while EPA methane regulations and BSEE well-control rules shape operational duty cycles that accelerate replacement demand. OSHA pipe-handling directives and DOT hazardous materials frameworks influence logistics and field safety protocols. Stakeholders must monitor API specification revision timelines and state-level flaring restrictions that alter drilling economics and pipe utilization intensity.
Market Dynamics
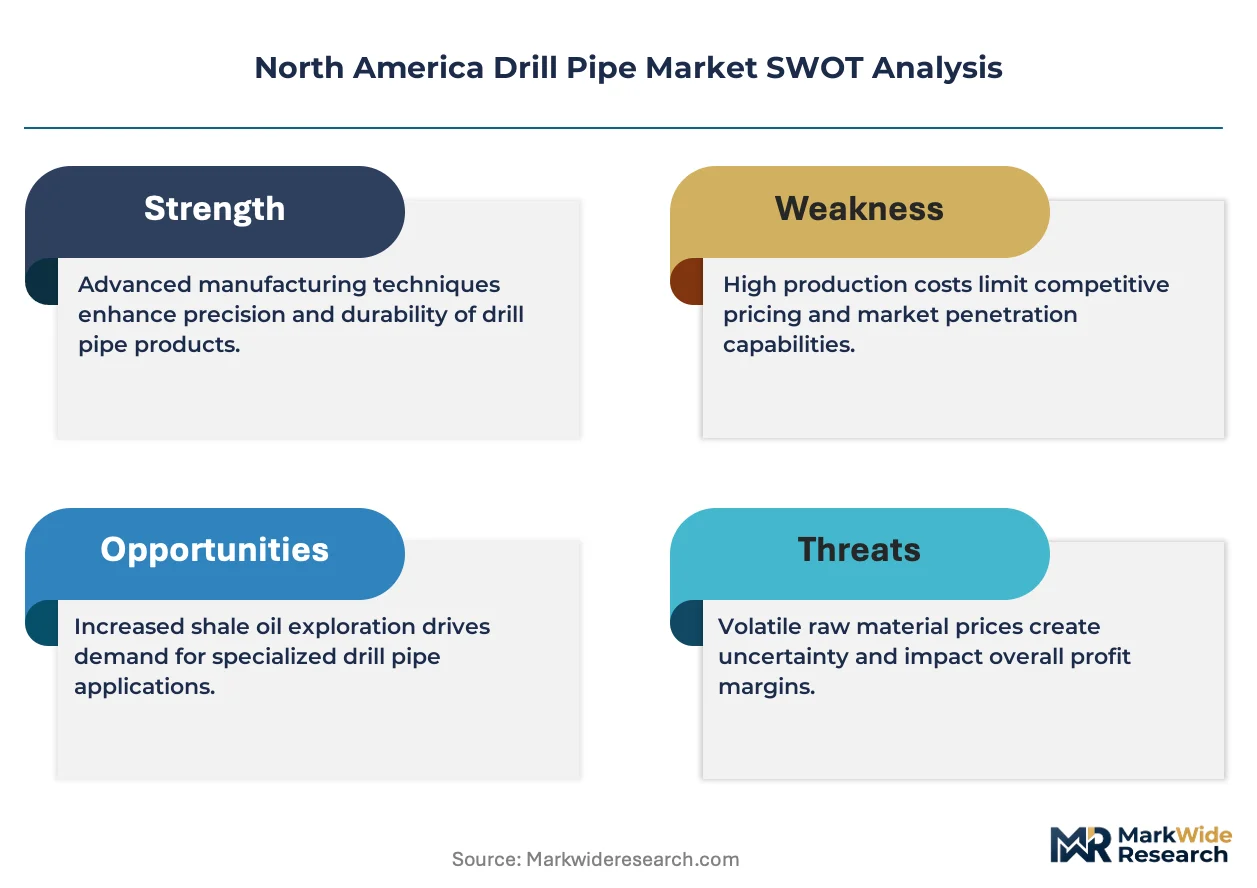
Horizontal drilling intensity in the Permian Basin and Appalachian shale plays is compressing drill pipe replacement cycles and elevating sour-service grade specifications as the dominant market-shaping force.
Growth Catalysts
- EPA methane regulations:Tighter emission controls accelerate wellhead replacement schedules, forcing operators to refresh pipe strings more frequently to maintain compliance.
- Extended-reach horizontal drilling:Shale operators in Texas and New Mexico deploy longer laterals that demand premium-grade pipe with enhanced fatigue resistance.
- API 5DP specification updates:Revised material standards tighten quality thresholds, disqualifying older inventory and stimulating upgrade demand across the region.
Market Restraints
- Alloy steel input volatility:AISI 4145H modified alloy pricing fluctuates with scrap metal and molybdenum markets, compressing fabrication margins unpredictably.
- Seamless mill concentration:Domestic seamless pipe capacity clusters in Texas and Ohio, creating geographic supply risk during regional logistics disruptions.
- Technical fatigue limits:Standard-grade pipe faces hard performance ceilings in ultra-deep formations beyond 20,000 feet, restricting addressable reservoir scope.
Strategic Opportunities
- Sour-gas basins in Alberta:Corrosion-resistant cladding penetration remains underdeveloped in Canadian shale formations, creating white space for lined pipe specialists.
- BSEE well-control rules:Strengthened blowout prevention mandates incentivize premium connection upgrades that reduce failure risk in high-pressure zones.
- Digital thread inspection:Convergence of ultrasonic testing with real-time telemetry enables predictive maintenance contracts that extend pipe life cycles.
Industry Challenges
- API recertification timelines:Third-party inspection backlogs delay field deployment, forcing operators to carry excess inventory buffers.
- Specialized welding expertise:Tool-joint hardbanding and repair require certified technicians that remain scarce in the Permian and Bakken field clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drill Pipe Market |
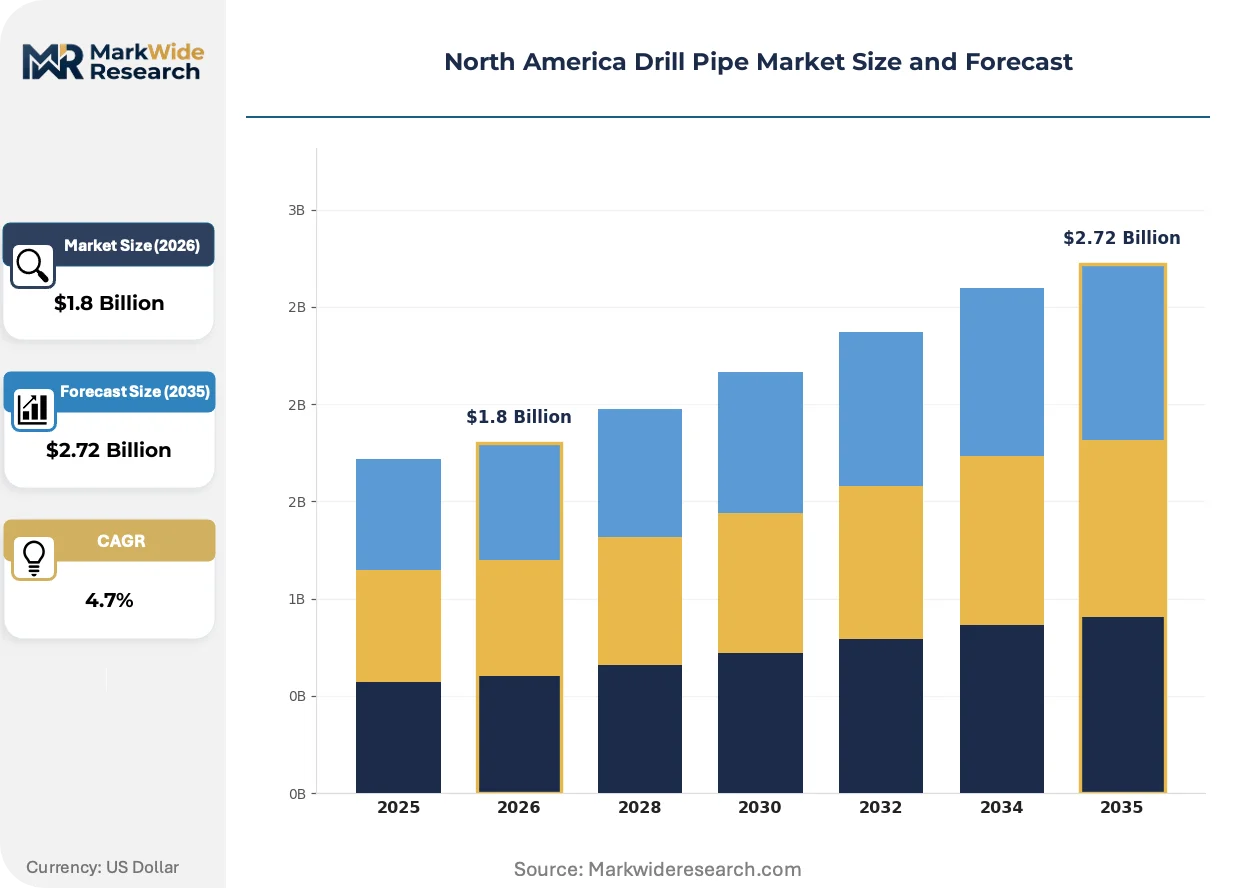
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavyweight Drill Pipe, Standard Drill Pipe, Lined Drill Pipe, Coiled Tubing Material: Steel, Composite, Aluminum, Alloy End User: Oil & Gas Exploration, Mining, Geological Survey, Utilities Application: Exploratory Drilling, Horizontal Drilling, Vertical Drilling, Offshore Operations |
| Companies Covered | Tenaris SA, U.S. Steel Corporation, National Oilwell Varco, Inc., Tejas Tubular Products, Inc., Texas Steel Conversion, Inc., Hilong Holding Ltd, Hunting PLC, Drill Pipe International LLC, TMK Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drill Pipe Market Evolving Landscape
Material science advances and inspection digitization are compressing traditional equipment lifecycles while elevating performance thresholds across North American drilling operations.
Corrosion-resistant alloy cladding is electrifying sour-service applications by extending pipe longevity in hydrogen sulfide environments. Appalachian Basin operators facing high-H2S formations are specifying cladded strings at accelerating rates. This metallurgical shift is electrifying competitive positioning among fabricators capable of in-house overlay welding.
OSHA pipe-handling directives mandate automated lifting systems and remote-operated racking equipment on newbuild rigs. These safety frameworks increase capital intensity for drilling contractors but reduce injury liability exposure. Gulf of Mexico offshore operators have adapted fastest, with onshore Permian fleets trailing by 18-24 months in compliance rollout.
Life-cycle service contracting now bundles inspection, rethreading, and recertification into multi-year agreements rather than transactional spot purchases. Independent drilling contractors in the Anadarko Basin favor this model to smooth capital outlays. Texas-based service hubs are consolidating to capture this recurring revenue stream, displacing fragmented local repair shops.
North America Drill Pipe Market Segmentation
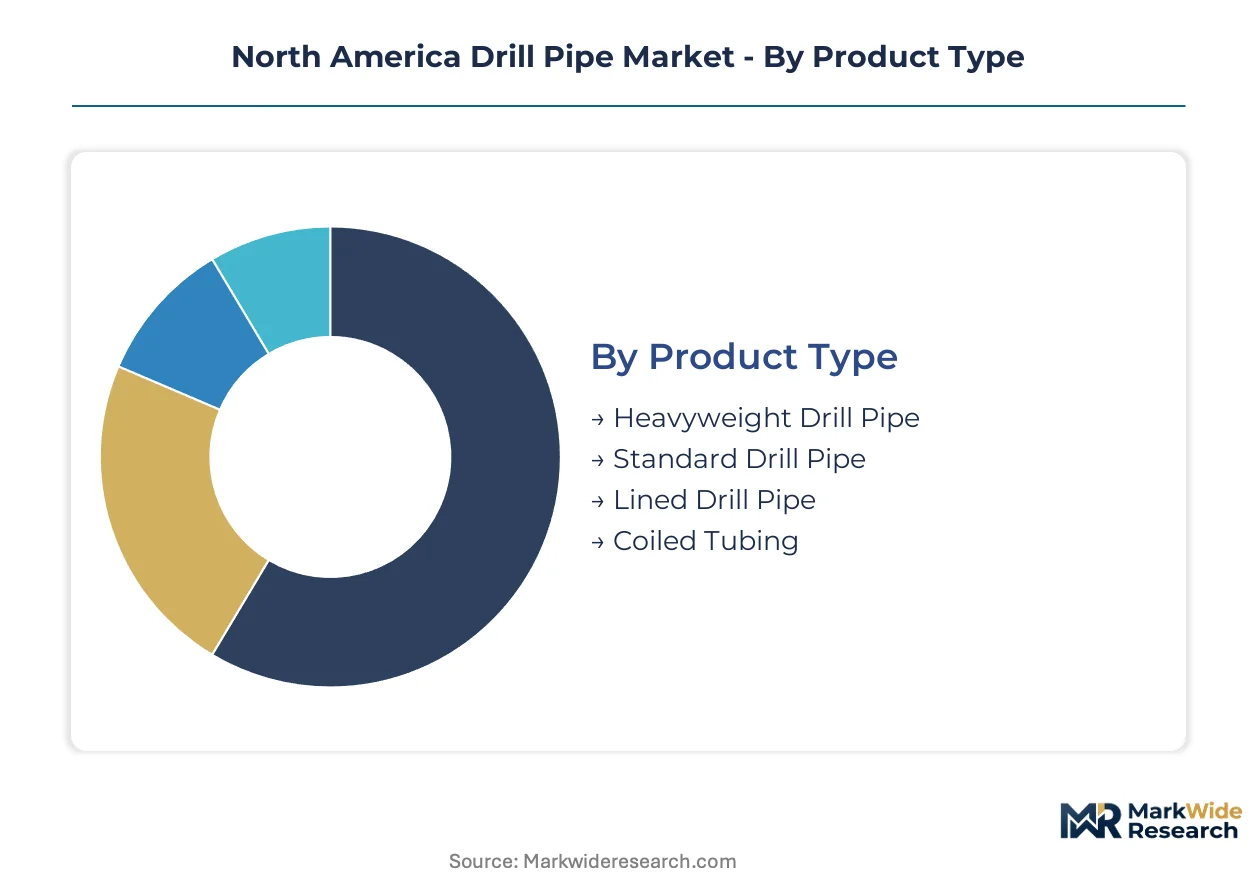
Drill pipe procurement patterns diverge sharply across product grades, material specifications, and operational contexts. Understanding these fault lines exposes where premium pricing power concentrates versus where commodity competition erodes margins.
Product Type:
Cost tier separates buyers seeking replacement volume from those investing in extended-reach performance.
- Heavyweight Drill Pipe:Thick-walled tubes with enhanced torsional rigidity engineered for high-stress horizontal laterals. Permian Basin operators deploying 15,000-foot laterals specify these strings to combat fatigue failure in extended-reach applications.
- Standard Drill Pipe:Conventional API 5DP-compliant tubes serving vertical and short-radius drilling programs. Texas conventional rig fleets consume this volume tier where price sensitivity dominates procurement negotiations.
- Lined Drill Pipe:Corrosion-resistant cladding applied to interior surfaces for sour-gas environments. Appalachian Basin high-H2S formations drive specification upgrades.
- Coiled Tubing:Continuous milled tubing deployed for workover and intervention operations rather than primary drilling. Completion-focused service companies in Oklahoma and Louisiana represent concentrated demand.
Standard drill pipe leads volumes today; heavyweight drill pipe is gaining share fastest.
Material:
Application severity dictates material selection between fatigue resistance, corrosion tolerance, and weight reduction priorities.
- Steel:AISI 4145H modified alloy remains the workhorse specification for land-based drilling. Domestic seamless mills in Texas and Ohio control primary supply.
- Alloy:Enhanced molybdenum and chromium formulations meeting sour-service grades under API 5DP updates. Canadian operators in Alberta's sour-gas basins specify these strings at accelerating rates.
- Composite:Fiber-reinforced polymer constructions reducing string weight for ultra-deep offshore deployments. Gulf of Mexico deepwater trials validate performance thresholds.
- Aluminum:Lightweight alternatives for corrosive environments where magnetic interference must be minimized. Geological survey applications in the Rocky Mountain region represent niche uptake.
Steel dominates installed base; alloy formulations are climbing the fastest.
End User:
Volume scale and replacement frequency separate capital-intensive exploration programs from intermittent survey work.
- Oil & Gas Exploration:Integrated and independent operators running continuous drilling programs across shale basins. Texas and New Mexico rig activity concentrates procurement scale.
- Mining:Mineral extraction operators deploying blast-hole and core drilling equipment. Nevada and Arizona copper-gold projects sustain regional demand.
- Geological Survey:Government and academic research programs with sporadic, specification-intensive procurement cycles. USGS and state geological agencies in the Mountain West represent fragmented demand.
- Utilities:Geothermal and water well drilling contractors with moderate volume but high durability requirements. California geothermal developers in the Salton Sea region specify premium connections.
Oil and gas exploration leads volumes today; mining applications are expanding most quickly.
Application:
Well geometry and pressure environment determine connection grade and inspection intensity requirements.
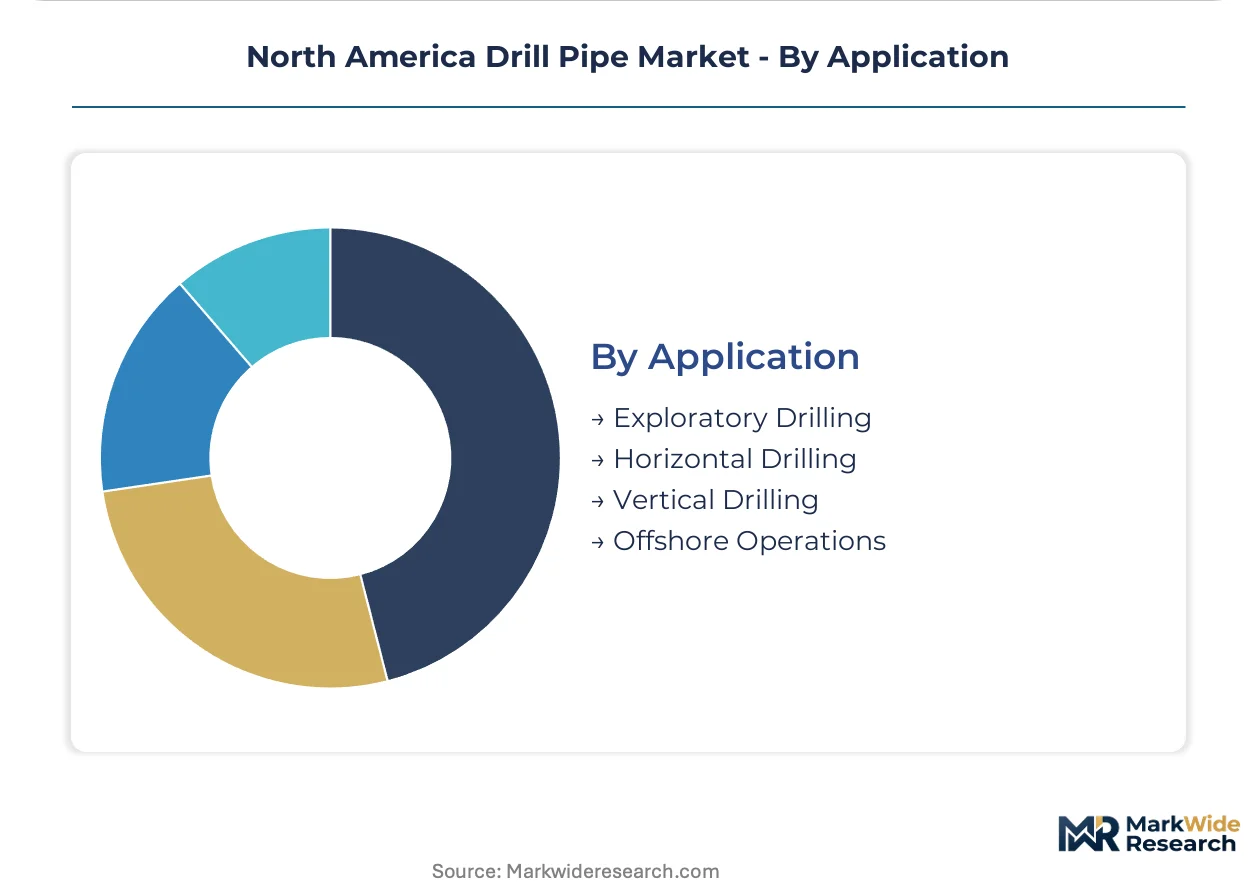
- Horizontal Drilling:Extended-reach laterals demanding premium connections and enhanced fatigue resistance. Permian and Appalachian shale operators drive specification escalation.
- Vertical Drilling:Conventional wellbores with standardized API connections and routine inspection intervals. Mature conventional fields in Louisiana and Kansas represent stable replacement demand.
- Exploratory Drilling:Wildcat and step-out wells with uncertain formation pressures requiring conservative string design. Alaska North Slope and offshore Atlantic margin programs concentrate risk capital.
- Offshore Operations:BSEE-regulated environments with blowout prevention and material traceability mandates. Gulf of Mexico shelf and deepwater developments sustain premium pricing.
Vertical drilling leads volumes today; horizontal drilling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American drill pipe industry traces its commercial roots to the 1901 Spindletop discovery in Texas, where standardized steel tubulars enabled the modern rotary drilling era. Domestic seamless mills subsequently clustered along Gulf Coast petrochemical corridors and Midwest steel belts to serve expanding continental production.
United States
EPA methane regulations and BSEE well-control mandates compress replacement cycles across Permian Basin and Appalachian shale plays. Texas rig counts exceed all other state jurisdictions combined, with Midland-Odessa service hubs commanding national procurement volumes. Houston anchors the continent's largest concentration of threading, inspection, and recertification facilities.
Canada
Alberta's sour-gas basins drive specification escalation toward corrosion-resistant alloy grades under provincial energy regulator directives. Federal methane reduction frameworks accelerate wellhead refresh schedules across the Western Canadian Sedimentary Basin. Calgary-based procurement offices coordinate cross-border inventory movements with Montana and North Dakota field operations.
Mexico
Constitutional energy reforms reopened upstream investment to international operators, stimulating tender activity for premium connection strings in offshore Gulf prospects. ASEA environmental standards govern material traceability for deepwater deployments. Ciudad del Carmen service bases support Campeche Bay development programs with growing pipe handling and inspection capacity.
North America Drill Pipe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification intensity and service bundling dimensions. The vendor base stratifies into integrated seamless producers, independent threading specialists, and aftermarket service consolidators. Three archetypes dominate: mill-integrated fabricators controlling alloy sourcing, connection technology licensors commanding specification premiums, and regional service hubs capturing inspection and recertification recurring revenue. Capacity expansion and life-cycle service contracting represent the dominant competitive vectors reshaping procurement relationships.
Among mill-integrated fabricators, Tenaris SA and U.S. Steel Corporation occupy positions that exemplify backward integration into seamless production and flat-rolled supply respectively. National Oilwell Varco, Inc. sits within the technology-licensor tier, representing the aftermarket service and connection specialization archetype that extends pipe life cycles through inspection and rethreading capabilities.
| Leading Market Players |
|---|
| Tenaris SA |
| U.S. Steel Corporation |
| National Oilwell Varco, Inc. |
| Tejas Tubular Products, Inc. |
| Texas Steel Conversion, Inc. |
| Hilong Holding Ltd |
| Hunting PLC |
| Drill Pipe International LLC |
| TMK Group |
| Others |
Value Network & Pricing Analysis
AISI 4145H modified alloy steel pricing cascades through North American drill pipe manufacturing, with molybdenum content volatility in scrap metal markets compressing fabrication margins at premium-grade tiers while standard-grade producers absorb cost shocks through volume throughput to Texas rig operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with fatigue-resistant heavyweight strings commanding specification premiums from Permian Basin horizontal operators while commodity-grade tenders face price compression. Price differentiation hinges on API 5DP certification tier and sour-service grade compliance. Cost compression in standard-grade segments is intensifying because alloy input volatility erodes fixed-contract margins. Independent drilling contractors in the Anadarko Basin exhibit highest price sensitivity, whereas Gulf of Mexico offshore operators prioritize performance over unit cost.
Supply Chain Analysis
Seamless pipe supply rests on domestic mill concentration in Texas and Ohio, with rotary piercing capacity clustering along Gulf Coast petrochemical corridors. Raw material feeds draw from scrap metal recyclers, molybdenum additive suppliers, and flat-rolled steel producers. Single-source vulnerability persists in premium connection threading, where certified hardbanding technicians remain scarce in Permian and Bakken field clusters. Distribution runs through Houston-based service hubs that coordinate inspection, recertification, and just-in-time field delivery to Midland-Odessa and Appalachian basin operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American drill pipe demand has shifted decisively toward premium specifications as extended-reach horizontal drilling compresses replacement cycles and elevates fatigue-resistance requirements.
For Market Incumbents: Cement backward integration into seamless alloy production to insulate margins from scrap metal volatility. Capture recurring revenue through multi-year life-cycle service contracts bundling inspection, rethreading, and recertification. Threat substitution from composite alternatives in ultra-deep offshore applications demands accelerated R&D in corrosion-resistant cladding formulations. For New Entrants and Emerging Players: Alberta sour-gas basin operators represent an underserved buyer archetype with accelerating specification escalation toward corrosion-resistant grades. Canadian shale formations offer the most penetrable geography, with provincial energy regulator directives driving upgrade demand. A go-to-market angle anchored in lined pipe specialization and in-house overlay welding capability bypasses incumbent mill-integrated fabricators. For Investors and Strategic Acquirers: Consolidation pressure builds where inspection and recertification capacity fragments across regional repair shops. Long-term viability favors service hub consolidation plays with captive threading facilities and digital inspection telemetry. Acquisition target archetype: regional threading specialists with API-licensed connection technology and established field service relationships. The signal to watch is BSEE well-control rule implementation timelines, which accelerate premium connection upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seamless Production | Captive alloy sourcing insulates Tenaris SA and U.S. Steel from scrap volatility. |
| Life-Cycle Service Contracting | Multi-year inspection agreements smooth capital outlays for Anadarko Basin independents. |
| Corrosion-Resistant Cladding Investment | In-house overlay welding capability penetrates Appalachian high-H2S formations. |
| Digital Thread Inspection Deployment | Ultrasonic telemetry integration enables predictive maintenance revenue streams. |
| Alberta Market Development | Calgary-based procurement coordination captures Canadian sour-gas specification escalation. |
Research Methodology
Bottom-up rig count modeling reconciled against top-down seamless mill capacity tracking forms the analytical core. Primary interviews with drilling contractors, procurement managers at integrated operators, threading facility engineers, and API certification inspectors combined with secondary validation from EIA drilling statistics, BSEE incident reports, state-level flaring restriction filings, and customs trade data. Triangulation across supply-side capacity utilization and demand-side replacement cycle intensity anchors volume estimates.
Input-output matrices map alloy steel throughput to finished pipe deployment across product grade, material specification, end-user category, and application type dimensions. CAGRs derive from rig activity trajectories, lateral length extension rates, and regulatory-driven replacement acceleration. Forecast inputs incorporate EPA methane compliance timelines, API 5DP specification revision schedules, and provincial energy regulator directives in Alberta over the projection horizon.
Underlying measurement precision varies by segment; heavyweight drill pipe and lined pipe categories carry tighter precision than standard-grade volume tiers due to concentrated supplier disclosure. Forecasts reflect documented assumptions regarding lateral length evolution, alloy price trajectories, and regulatory implementation pacing. Specific revision triggers include BSEE rulemaking acceleration, seamless mill capacity additions, and breakthrough composite validation in Gulf of Mexico deepwater trials. A small set of regulatory and technology triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Rock Duster Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Global Dozers Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
DTH Drill Market