
 Barite Crusher Market | 2026-2036
Barite Crusher Market Size, Share, and Industry Trends Forecast 2026-2036
Barite Crusher Market Analytics
Specialized crusher technician availability is bifurcating the competitive landscape, as OEMs with in-house training programs capture maintenance contracts that smaller distributors cannot service. Metso leverages its global parts logistics network to secure long-term service agreements with mining enterprises across North America. Sandvik competes through connected crushing analytics that reduce unplanned downtime for oil field services operators in the Permian Basin. Weir anchors its position through alloy metallurgy expertise that extends jaw liner life in high-silica barite deposits.
A barite crusher reduces barium sulfate ore to specified particle distributions for industrial applications, typically processing feed material through compression or impact mechanisms to achieve 74-micron fineness for API drilling-grade specifications. Jaw crushers dominate the installed base for primary reduction of run-of-mine barite, while cone crushers command premium positioning in tertiary circuits where particle shape affects fluid rheology in drilling mud formulations. Oil field services represent the highest-margin application segment, as API Specification 13A compliance requirements create qualification barriers that chemical processing buyers rarely impose.
EPA National Emission Standards for Hazardous Air Pollutants for mineral processing facilities mandate particulate matter controls that reshape crusher enclosure and ventilation investments. OSHA silica exposure limits in mining operations drive demand for wet suppression systems integrated at the crusher feed point. MSHA dust sampling protocols influence equipment specification criteria for underground barite crushing circuits. Stakeholders must weigh capital allocation between automated process controls that reduce labor dependency and modular plant designs that permit rapid relocation between Texas, Nevada, and Missouri barite districts as drilling economics shift.
Market Dynamics
Horizontal drilling intensity in the Permian Basin and Bakken formation is compressing crusher deployment cycles, forcing OEMs to prioritize modular plant designs that relocate between Texas, Nevada, and Missouri barite districts as rig economics shift.
Growth Catalysts
- EPA NESHAP compliance mandates:Mineral processing facilities must install enclosed crushing systems with baghouse dust collection, creating replacement demand for legacy open-circuit equipment across Texas and New Mexico oil field services operations.
- API Specification 13A qualification barriers:Drilling-grade barite requiring specific gravity above 4.2 forces operators to invest in tertiary cone crushers capable of precise particle shape control for fluid rheology optimization.
- Permian Basin drilling activity:High-pressure well completions in West Texas and southeastern New Mexico concentrate weighting-agent demand, pulling specialized grinding capacity expansions from oil field services firms.
Market Restraints
- High-silica deposit abrasion:Jaw liner replacement frequency in Nevada and Missouri barite mines elevates consumables costs beyond chemical processing applications with softer feedstock.
- Texas-New Mexico demand concentration:Geographic clustering of oil field services procurement exposes equipment utilization rates to Permian Basin rig count volatility.
- OSHA silica exposure limits:Wet suppression system integration at crusher feed points adds capital intensity that smaller distributors cannot finance.
Strategic Opportunities
- Underpenetrated Missouri barite districts:Relocation of modular crushing plants from Texas to the Ozark region captures chemical-grade demand as drilling economics soften.
- Connected crushing analytics convergence:Integration of sensor telemetry with predictive maintenance platforms enables unplanned downtime reduction for remote Permian Basin operations.
- MSHA dust sampling protocol alignment:Underground barite crushing circuit specifications in Nevada create qualification advantages for OEMs with pre-certified ventilation-integrated designs.
Industry Challenges
- Specialized crusher technician scarcity:OEM in-house training programs capture maintenance contracts that smaller distributors lack personnel to service, bifurcating competitive positioning.
- API-grade certification timeline compression:Third-party testing protocols for 74-micron fineness specifications extend equipment qualification cycles beyond standard industrial crusher deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barite Crusher Market |
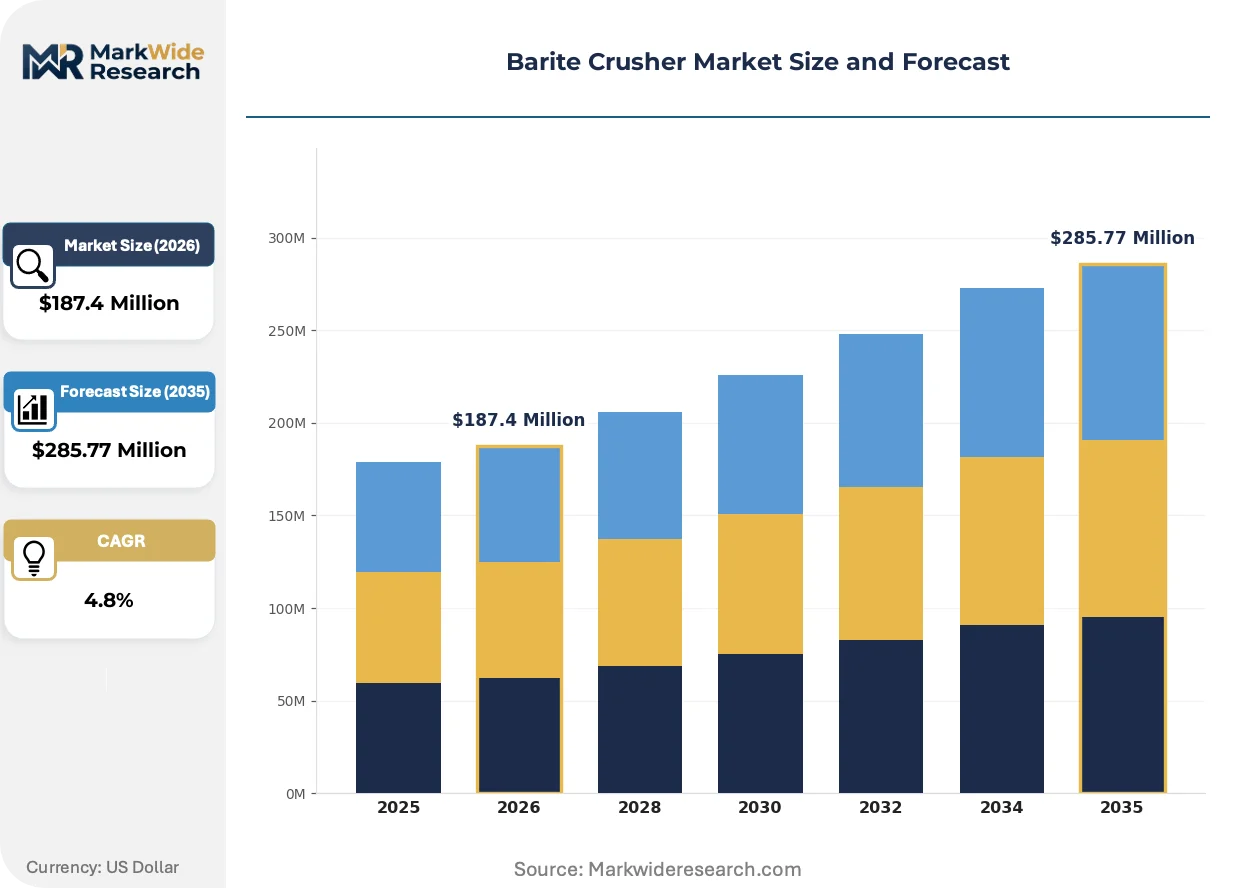
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jaw Crusher, Impact Crusher, Cone Crusher, Hammer Crusher Application: Mining, Construction, Oil & Gas, Chemical Processing End User: Construction Companies, Oil Field Services, Mining Enterprises, Chemical Manufacturers Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Metso, Sandvik, Terex, Weir, Astec Industries, Wirtgen, Excalibar Minerals LLC, Halliburton Company, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barite Crusher Market Evolving Landscape
Automation and telemetry integration is reconfiguring competitive advantage around uptime guarantees rather than equipment throughput, compressing margins for parts-only suppliers.
Connected crushing analytics is fragmenting the traditional service model. Sensor-embedded cone crushers transmit liner wear data to OEM logistics networks, enabling just-in-time parts dispatch before failure. Oil field services operators in the Permian Basin now specify predictive maintenance clauses in procurement contracts, displacing reactive service agreements.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is tightening enclosure specifications. Mineral processing plants in Texas and New Mexico must demonstrate continuous particulate matter monitoring, pushing operators toward integrated baghouse-crusher packages rather than retrofitted legacy equipment. This regulatory pressure favors OEMs with pre-engineered dust collection systems.
Buyer consolidation among oil field services firms is compressing vendor counts. Large Permian Basin operators now mandate single-source accountability for crushing, grinding, and materials handling equipment, displacing multi-vendor procurement. This concentration demands OEMs expand service capabilities beyond component supply to full circuit optimization.
Barite Crusher Market Segmentation
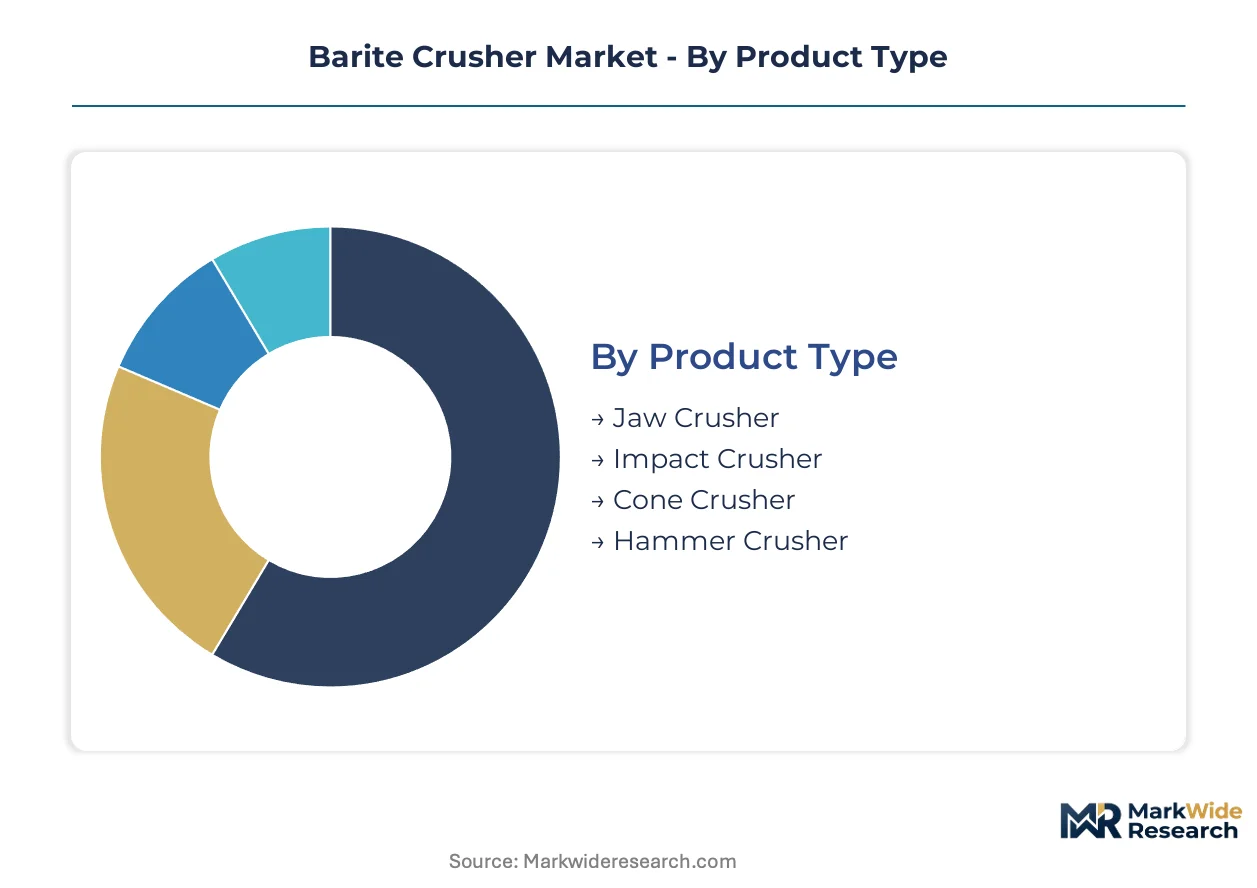
Barite crusher procurement patterns diverge sharply across product types and end-use verticals, with oil field services imposing API-grade qualification barriers that chemical processing buyers rarely enforce. Equipment specification criteria compress vendor margins in mining applications while creating premium positioning opportunities in drilling-grade segments.
Product Type:
Jaw crushers face intensifying substitution pressure from cone crusher systems capable of precise particle shape control for API Specification 13A compliance, while hammer crusher architectures struggle against impact crusher efficiency gains in high-silica deposits.
- Jaw Crusher:Compression-based primary reduction systems dominate run-of-mine barite processing with robust mechanical simplicity suited to Nevada and Missouri underground operations. Permian Basin oil field services operators specify jaw crushers for initial size reduction before tertiary cone circuits, though EPA NESHAP enclosure requirements elevate capital intensity versus legacy open-circuit designs.
- Cone Crusher:Tertiary crushing architectures command premium positioning through precise particle shape control that optimizes drilling fluid rheology. West Texas and southeastern New Mexico weighting-agent demand concentrates procurement of high-specificity cone systems capable of achieving 74-micron fineness specifications with minimal recirculation.
- Impact Crusher:Rotor-driven fragmentation suits softer chemical-grade barite deposits with lower silica content, reducing liner replacement frequency versus compression alternatives.
- Hammer Crusher:Attrition-based reduction remains cost-competitive for small-scale Missouri chemical processing operations with modest throughput requirements and limited capital budgets.
Jaw crushers anchor the volume base while cone crushers gain share at the steepest rate as API-grade qualification barriers tighten across Permian Basin drilling operations.
Application:
Cost tier stratification separates capital-intensive oil and gas deployments from price-sensitive construction aggregates processing, with chemical processing occupying a mid-tier position defined by specification flexibility.
- Oil & Gas:Drilling-grade barite processing commands the highest equipment margins through API Specification 13A compliance mandates requiring specific gravity above 4.2 and precise particle distribution control. Horizontal drilling intensity in the Permian Basin and Bakken formation compresses crusher deployment cycles, forcing modular plant designs that relocate as rig economics shift between Texas, Nevada, and Missouri districts.
- Mining:Run-of-mine reduction for chemical-grade barite deposits emphasizes throughput maximization over particle shape precision, with Nevada and Missouri underground operations driving demand for MSHA-compliant ventilation-integrated crushing circuits.
- Construction:Aggregates applications impose minimal specification barriers, exposing equipment suppliers to intense price competition from general-purpose crusher manufacturers.
- Chemical Processing:Intermediate purity requirements create procurement flexibility that favors refurbished equipment and shorter depreciation schedules versus oil field services standards.
Mining applications generate the largest equipment installed base while oil and gas commands the steepest expansion trajectory as horizontal drilling activity intensifies.
End User:
Customer type concentration among consolidated oil field services firms compresses vendor counts and elevates service capability requirements beyond component supply.
- Oil Field Services:Large Permian Basin operators mandate single-source accountability for crushing, grinding, and materials handling equipment, displacing multi-vendor procurement. Predictive maintenance clauses now standard in service agreements favor OEMs with connected crushing analytics and global parts logistics networks.
- Mining Enterprises:Underground barite operations in Nevada prioritize MSHA dust sampling protocol alignment, creating qualification advantages for OEMs with pre-certified ventilation-integrated designs.
- Construction Companies:Project-based procurement cycles and limited technical staffing drive preference for distributor-supported equipment with local service presence.
- Chemical Manufacturers:Missouri-based processors exhibit higher price elasticity and lower switching costs, enabling equipment relocation from Texas as drilling economics soften.
Oil field services concentrate the highest-value procurement while chemical manufacturers provide demand stability during hydrocarbon sector downturns.
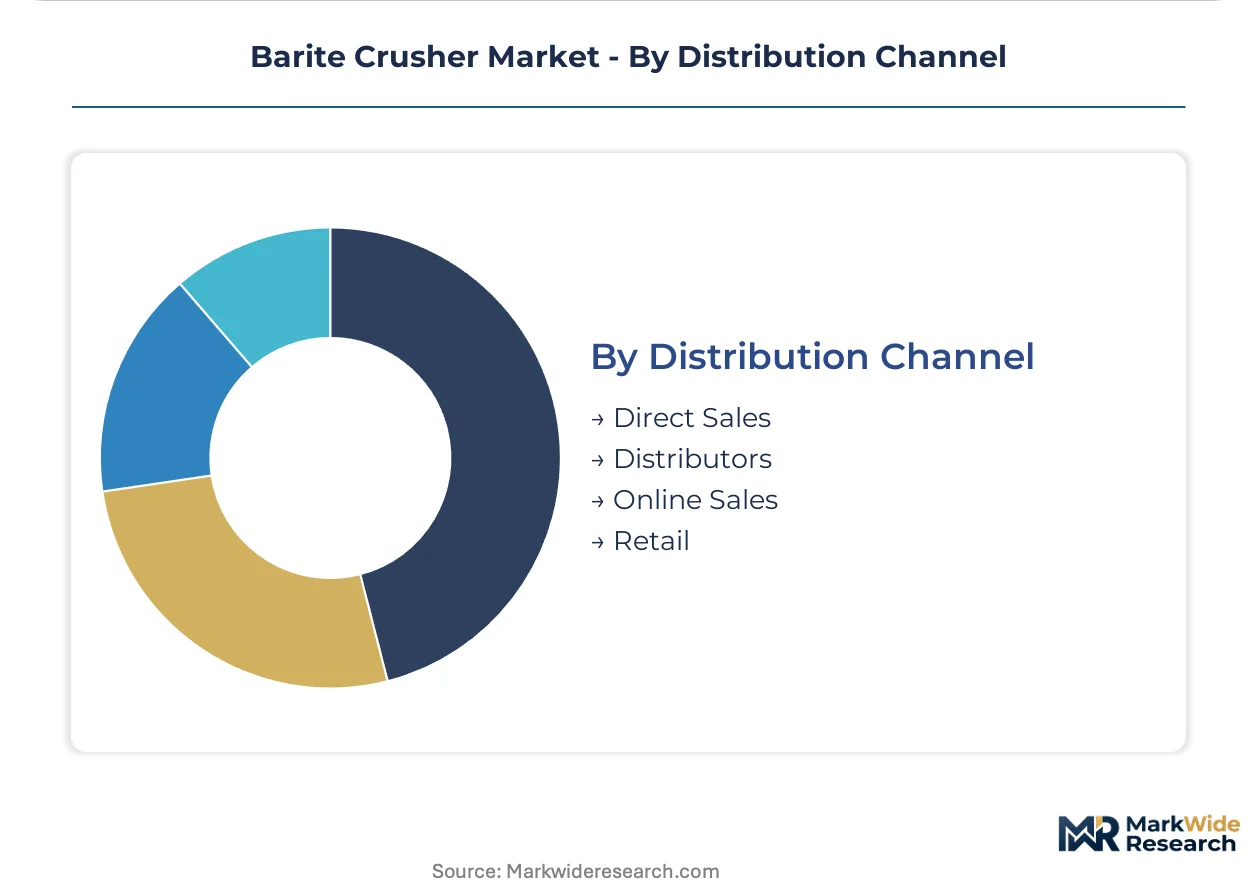
Distribution Channel:
Supply concentration among specialized crusher technicians bifurcates channel effectiveness, with direct sales capturing complex service agreements that distributor networks cannot support.
- Direct Sales:OEM field engineering teams secure long-term maintenance contracts through in-house training programs that smaller distributors lack personnel to replicate. Connected crushing analytics integration requires direct technical engagement unavailable through intermediary channels.
- Distributors:Regional inventory positioning serves construction and chemical processing segments with standardized equipment specifications and shorter sales cycles.
- Online Sales:Spare parts procurement and consumables reordering migrate to digital platforms, though capital equipment transactions remain relationship-intensive.
- Retail:Limited relevance for industrial-scale barite processing equipment; confined to small-scale aftermarket components and portable crushing accessories.
Direct sales channels capture the premium service tier while distributor networks maintain volume throughput in specification-flexible segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Permian Basin while Missouri chemical processors extract value through equipment relocation arbitrage. Texas and New Mexico operators pay premiums for API-grade certification compliance. Nevada underground mines absorb higher consumables costs from silica abrasion without equivalent price recovery.
United States
Horizontal drilling intensity in West Texas and the Bakken formation drives weighting-agent demand for high-pressure completions. EPA National Emission Standards for Hazardous Air Pollutants enforcement mandates baghouse dust collection at mineral processing facilities. The Permian Basin anchors specialized grinding capacity expansions by oil field services firms seeking API-grade barite with specific gravity above 4.2.
Mexico
Proximity to Texas drilling operations positions northern states as secondary supply sources during Permian Basin capacity constraints. Mexican environmental regulators enforce particulate matter controls at non-metallic mineral processing plants near population centers. Coahuila and Nuevo León host barite processing installations serving cross-border oil field services procurement.
China
Domestic drilling activity and export-oriented chemical processing sustain dual-demand channels for barite reduction equipment. The Ministry of Ecology and Environment implements emission controls at mining operations through GB standards compliance requirements. Sichuan and Guizhou provinces concentrate barite mining districts with growing investment in automated crushing circuits.
India
Oil and gas exploration expansion in Rajasthan and offshore basins stimulates import substitution for drilling-grade barite processing. The Bureau of Indian Standards maintains quality specifications for industrial minerals used in petroleum applications. Andhra Pradesh and Telangana house chemical processing clusters consuming lower-specification barite for paint and filler applications.
Morocco
Atlantic port access enables European chemical industry exports of processed barite products. The country's mining administration enforces environmental permitting for mineral extraction and processing operations. Oujda and Khouribga districts concentrate barite deposits with investment interest from international processing equipment suppliers.
Barite Crusher Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the barite crusher supply base. Consolidated mining equipment OEMs with global service networks capture premium maintenance contracts from large oil field services operators. Tier-one suppliers compete through connected crushing analytics and predictive maintenance platforms. Tier-two regional fabricators compete on capital cost for chemical processing applications with less stringent qualification requirements. Strategic moves center on modular plant design capabilities and technician training program expansion.
Among diversified mining equipment OEMs, Metso and Sandvik exemplify the technology-anchored archetype with integrated service networks, while Weir occupies a position emphasizing metallurgical specialization for abrasive applications. These three companies represent contrasting approaches to the Permian Basin opportunity—global logistics scale, telemetry-enabled uptime guarantees, and materials science differentiation respectively. Smaller distributors without in-house training infrastructure struggle to compete for oil field services maintenance contracts, concentrating instead on construction and chemical processing segments with shorter sales cycles and standardized specifications.
| Leading Market Players |
|---|
| Metso |
| Sandvik |
| Terex |
| Weir |
| Astec Industries |
| Wirtgen |
| Excalibar Minerals LLC |
| Halliburton Company |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for API-certified cone crusher systems concentrate pricing power with OEMs holding pre-qualified inventory in Texas and New Mexico, while standard jaw crusher configurations trade at thinner margins through distributor networks. This inventory stratification reinforces the bifurcation between oil field services procurement and chemical processing segments.
Pricing Analysis
The customization-premium spread separates configured-to-order tertiary cone systems from standard jaw crusher platforms. Project-based pricing dominates oil field services procurement, with API Specification 13A certification tier and connected analytics bundling as primary price differentiation drivers. Cost compression in standard equipment tiers is intensifying because distributor networks compete on capital cost for Missouri chemical processors. Chemical manufacturers exhibit highest price sensitivity, while Permian Basin operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Long Beach port congestion elevate landed costs for alloy liner components and sensor telemetry modules. Manufacturing concentration centers on Finland, Sweden, and China for crushing equipment fabrication, with high-manganese steel castings and industrial IoT sensors as critical input dependencies. Single-source vulnerability in specialized alloy supply creates exposure for jaw liner production. Distribution runs through OEM direct sales for complex service agreements and regional distributors for standardized equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Horizontal drilling intensity in the Permian Basin signals early-cycle expansion for API-grade processing capacity, with EPA NESHAP compliance mandates accelerating replacement demand for legacy open-circuit equipment.
For Market Incumbents: Shield service contract retention by expanding in-house technician training programs that smaller distributors cannot replicate. Deepen backward integration into alloy metallurgy for high-silica deposit applications, countering margin pressure from consumables cost inflation in Nevada and Missouri underground operations. For New Entrants and Emerging Players: API certification fast-track partnerships with third-party testing laboratories enable qualification timeline compression for 74-micron fineness specifications. Missouri chemical processing districts offer the most penetrable entry point, with refurbished equipment leasing as the primary go-to-market angle during Texas drilling economics softening. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified mining equipment conglomerates with underperforming barite-specific product lines. Long-term viability hinges on connected crushing analytics platform ownership. Watch Permian Basin rig count volatility as the inflection indicator for modular plant relocation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Plant Design Expansion | Enables rapid relocation between Texas, Nevada, and Missouri districts as drilling economics shift. |
| Connected Crushing Analytics Integration | Sensor telemetry with predictive maintenance reduces unplanned downtime for remote Permian Basin operations. |
| Technician Training Program Scaling | In-house OEM certification captures maintenance contracts that distributor networks cannot service. |
| Alloy Metallurgy R&D Investment | Extended jaw liner life addresses high-silica abrasion costs in Nevada and Missouri deposits. |
| Baghouse-Crusher Package Engineering | Pre-integrated dust collection systems satisfy EPA NESHAP mandates without retrofit complexity. |
Research Methodology
Operator-level perspectives from crusher maintenance directors, oil field services procurement managers, plant engineers at Nevada underground mines, and aftermarket service heads anchored the qualitative base. Primary interview data combined with secondary validation from MSHA dust sampling protocols, EPA NESHAP enforcement records, API Specification 13A certification databases, and SEC filings from listed mining equipment OEMs. Bottom-up equipment deployment estimates triangulated against top-down drilling activity indices.
Sensitivity analysis around rig count volatility and silica content variation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application tier, end user archetype, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and capacity expansion announcements. Forecast inputs incorporated horizontal drilling intensity indices and EPA compliance timeline assumptions.
Underlying assumptions cover sustained Permian Basin weighting-agent demand and stable alloy input pricing, with deviation risk concentrated in drilling economics downturns and MSHA regulatory tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market