
 Smart Mining Market | 2026-2036
Smart Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mining Market Analysis
A shrinking pool of certified heavy-equipment operators is unwinding traditional labor-intensive extraction models across major mining jurisdictions. Caterpillar Inc. leverages its integrated autonomy stack to anchor long-term fleet contracts with tier-one copper and iron ore producers. Komatsu Ltd. competes through backward integration into its own autonomous haulage software, reducing third-party dependency for deployment. Hexagon AB specializes in precision mine-planning software that extends from exploration through reclamation, occupying a narrow but defensible niche.
Smart mining denotes the application of networked sensors, machine learning algorithms, and robotic systems to extract, transport, and process mineral resources with minimal human intervention at the point of production. Functional parameters include sub-meter GPS positioning for haul trucks, real-time ore-grade sensing via hyperspectral imaging, and centralized remote operation centers managing multiple pit locations simultaneously. IoT Solutions and Autonomous Vehicles represent the deepest margin pools, as hardware-software bundling creates sticky multiyear service relationships. AI Analytics is expanding fastest among mid-tier miners seeking to optimize processing yields without full fleet replacement. Implementation services command premium pricing relative to maintenance contracts, reflecting the complexity of retrofitting legacy infrastructure with interoperable digital layers.
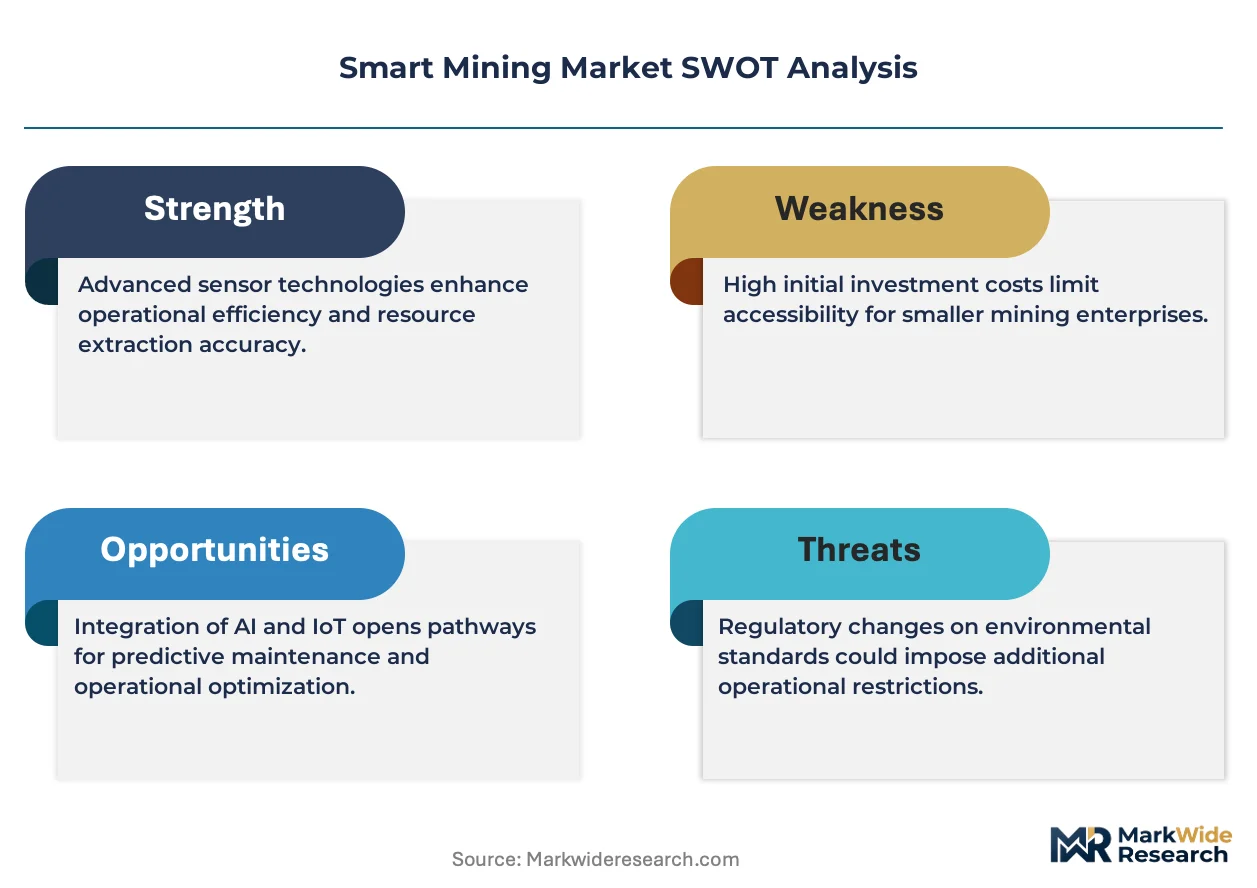
The US Mine Safety and Health Administration enforces continuous monitoring mandates for respirable dust and ground stability, directly stimulating demand for real-time environmental sensor networks. Australia's national resources regulator and Chile's mining inspectorate have both tightened autonomous equipment certification requirements, shaping product development roadmaps for suppliers seeking market access. Stakeholders must weigh the capital intensity of full autonomy against phased IoT retrofit strategies that preserve optionality as regulatory thresholds evolve.
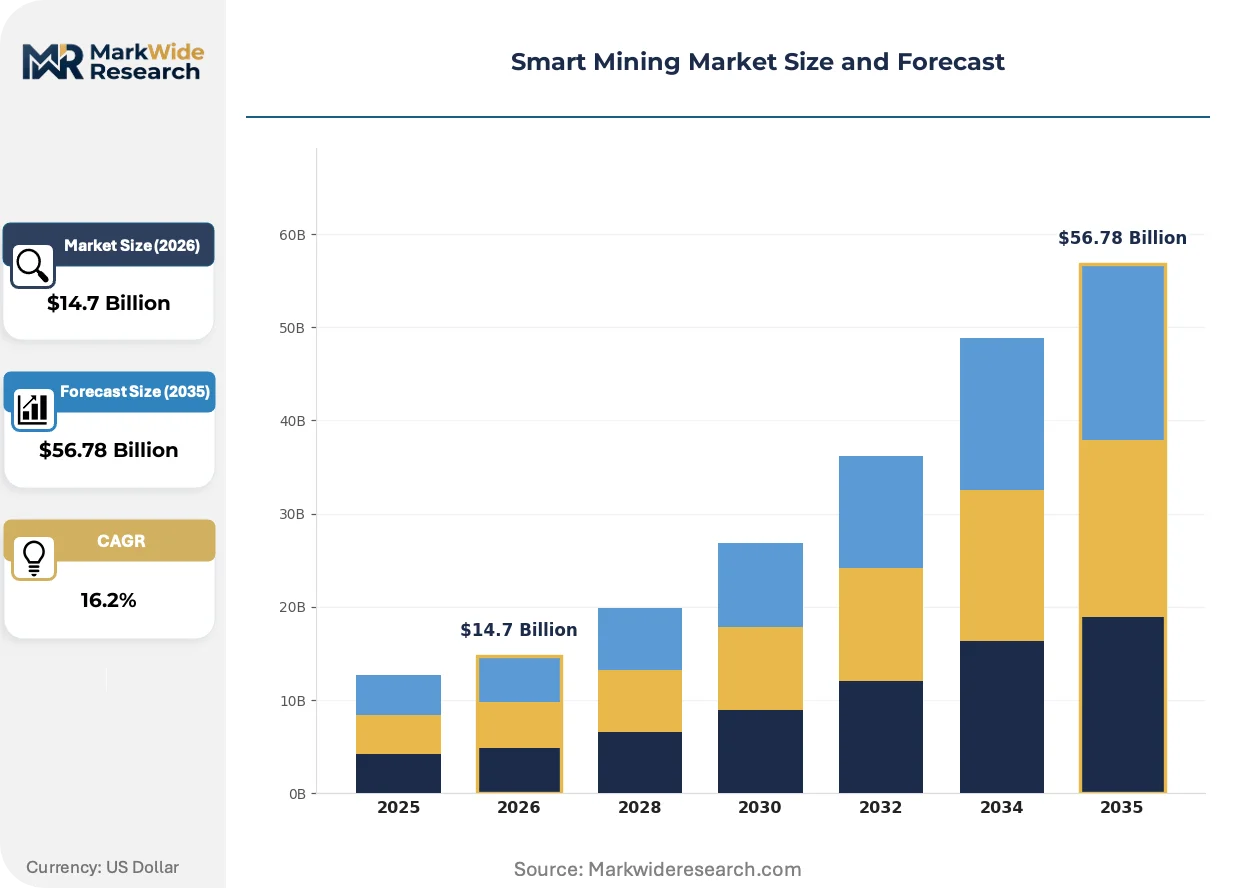
Market Dynamics
Certified operator shortages are compressing labor-intensive extraction models across major mining jurisdictions, forcing capital reallocation toward sensor-integrated machinery and remote operation centers.
Growth Catalysts
- Australia's mine safety protocol modernization:The national resources regulator mandates replacement of legacy fleets with sensor-integrated machinery, compelling operators to accelerate equipment refresh cycles.
- Hyperspectral imaging:Real-time ore-grade sensing technology enables mid-tier miners to optimize processing yields without full fleet replacement, expanding addressable market penetration.
- Chile's copper belt concentration:State-owned and private operators deploy autonomous haulage systems across aging open-pit complexes, creating sustained demand for retrofit integration services.
Market Restraints
- Capital intensity of full autonomy:Complete fleet replacement requires substantial upfront investment, forcing operators to weigh phased IoT retrofit strategies against comprehensive overhauls.
- Technical interoperability limitations:Legacy infrastructure lacks standardized digital interfaces, complicating seamless integration with modern autonomous control systems.
- Regulatory certification friction:Chile's mining inspectorate and Australia's national resources regulator impose tightened autonomous equipment certification requirements, extending product development timelines.
Strategic Opportunities
- Underpenetrated underground hard-rock operations:Connected drill rigs and remote loading systems offer substantial white space as operators offset persistent labor shortages in confined extraction environments.
- AI Analytics convergence with IoT:Machine learning algorithms layered atop sensor networks create premium service relationships without hardware-intensive capex commitments.
- US MSHA continuous monitoring mandates:Respirable dust and ground stability requirements stimulate demand for real-time environmental sensor networks in underground coal and metal operations.
Industry Challenges
- Certified equipment operator scarcity:Training pipelines fail to replenish retiring skilled labor pools, constraining operational scaling even where technology is deployed.
- Retrofit integration complexity:Interoperable digital layers require specialized implementation services commanding premium pricing relative to standard maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mining Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $56.78 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, AI Analytics, Robotics, Autonomous Vehicles Application: Exploration, Excavation, Processing, Transportation End User: Metal, Mineral, Coal, Oil & Gas Service Type: Consulting, Maintenance, Implementation, Support |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Sandvik AG, ABB Ltd, Rockwell Automation Inc., Cisco Systems Inc., Hexagon AB, Hitachi Ltd., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mining Market Emerging Trajectories
Networked sensor architectures and machine learning algorithms are compressing decision cycles from pit to processing, reconfiguring how mineral resources flow through extraction and logistics chains.
Autonomous haulage systems are displacing conventional truck-and-shovel operations in open-pit copper and iron ore complexes. Tier-one producers in Chile and Australia adopt these platforms fastest, consolidating multiple pit locations under centralized remote operation centers. This shift is displacing on-site operator roles while compressing haul cycle variability and fuel consumption.
REACH chemical safety frameworks and EU Green Deal carbon accounting requirements are reshaping supplier qualification protocols for mining equipment sold into European markets. Manufacturers must now document full lifecycle emissions and substance compliance to maintain market access. Battery-electric underground vehicles face accelerated certification timelines as the EU AI Act extends to autonomous decision systems in hazardous environments.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts across mid-tier mining operations. Buyers increasingly separate hardware procurement from software subscriptions and implementation support, pressuring OEM margin structures. This pattern concentrates most visibly in Australia's copper-gold sector and Chile's state-owned mining complexes, where procurement teams negotiate multi-vendor technology stacks.
Smart Mining Market Segmentation
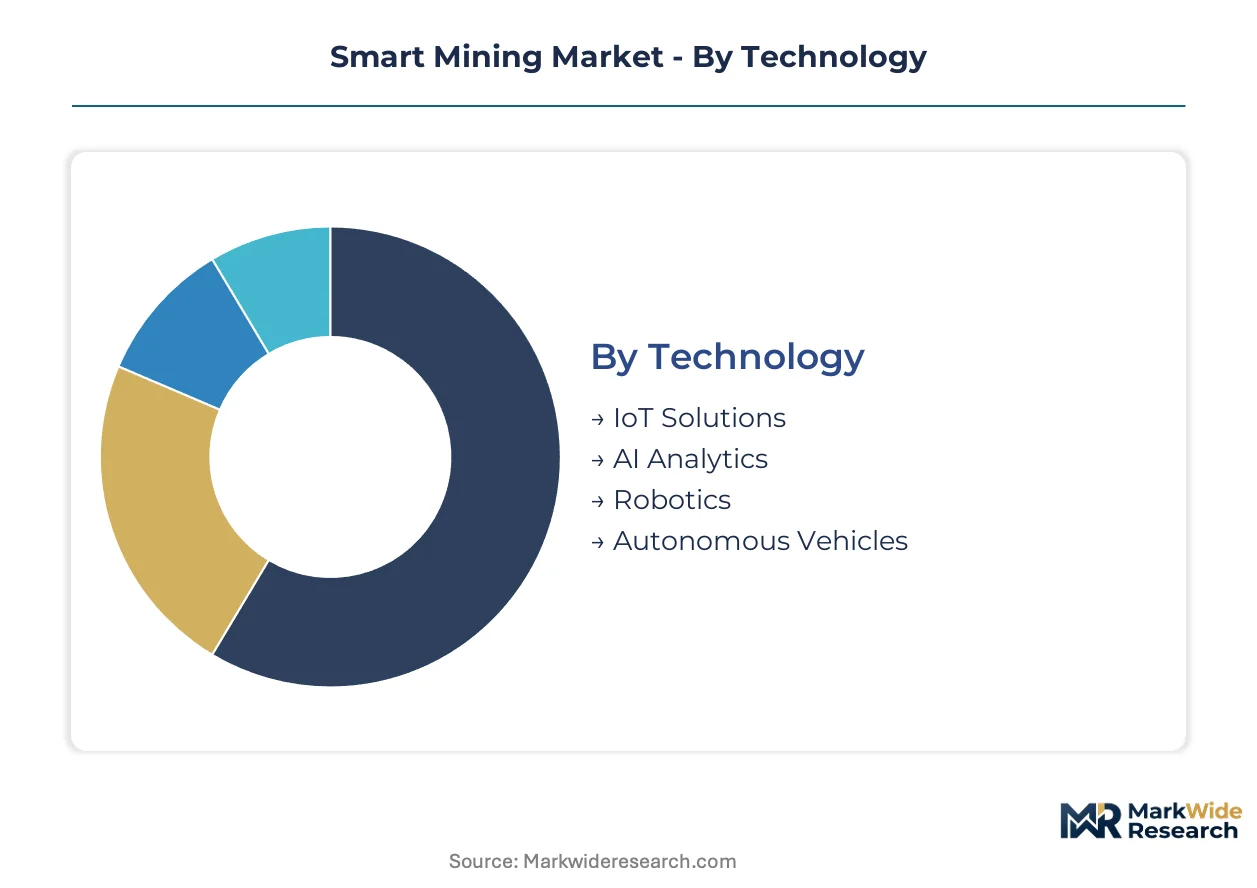
Technology selection in smart mining determines capital deployment patterns and vendor relationships across extraction operations. Segment boundaries reflect how hardware-software bundling creates divergent margin structures and customer lock-in dynamics.
Technology:
Channel flows split between bundled platform sales and unbundled component procurement, with tier-one miners favoring integrated stacks while mid-tier operators assemble multi-vendor architectures.
- IoT Solutions:Networked sensor arrays capture equipment health, environmental conditions, and ore characteristics in real time. Australian copper-gold producers and Chilean state-owned operators deploy these most aggressively to satisfy tightened safety monitoring mandates from national regulators.
- Autonomous Vehicles:Self-driving haul trucks and loading equipment eliminate on-site operator exposure while compressing cycle times. Demand concentrates in Chile's aging open-pit copper complexes where labor shortages intersect with large-scale surface operations.
- AI Analytics:Machine learning algorithms process operational data to optimize processing yields and predictive maintenance schedules.
- Robotics:Remote-controlled and semi-autonomous systems handle hazardous tasks in confined underground environments.
By volume, IoT Solutions leads. By growth pace, Autonomous Vehicles is climbing the fastest.
Application:
Cost tier segmentation separates capital-intensive full-fleet replacement from targeted retrofit investments that preserve legacy infrastructure.
- Transportation:Autonomous haulage systems and fleet management platforms dominate smart mining expenditure. Chilean copper belt operators and Australian iron ore producers anchor demand as they consolidate multiple pit locations under centralized remote operation centers.
- Excavation:Connected drill rigs and precision blasting systems reduce overbreak and improve ore recovery rates. Underground hard-rock operations in Australia accelerate adoption to offset persistent certified operator shortages in confined extraction environments.
- Processing:Real-time ore-grade sensing and automated sorting equipment optimize mill feed quality.
- Exploration:Hyperspectral imaging and drone-based survey platforms accelerate target identification.
Transportation commands the largest share of deployed capital. Processing is gaining share fastest as mid-tier miners prioritize yield optimization over full fleet replacement.
End User:
Volume concentration tracks with commodity price cycles and regulatory enforcement intensity across extraction jurisdictions.
- Metal:Copper and iron ore producers drive autonomous system deployment at scale. Tier-one operators in Chile and Australia anchor procurement volumes as they modernize aging open-pit complexes under tightened safety protocols.
- Coal:Underground coal operations in the US face MSHA continuous monitoring mandates for respirable dust and ground stability. Real-time environmental sensor networks represent the primary smart mining investment category in this segment.
- Mineral:Diverse industrial mineral extraction employs targeted IoT retrofits rather than comprehensive autonomy.
- Oil & Gas:Mining-adjacent extraction operations adopt selective automation for drilling and logistics optimization.
Metal extraction leads by absolute spend. Coal is expanding most quickly as regulatory deadlines force sensor network deployment.
Service Type:
Margin structure separates premium implementation services from recurring maintenance relationships, with procurement patterns shifting toward unbundled arrangements.
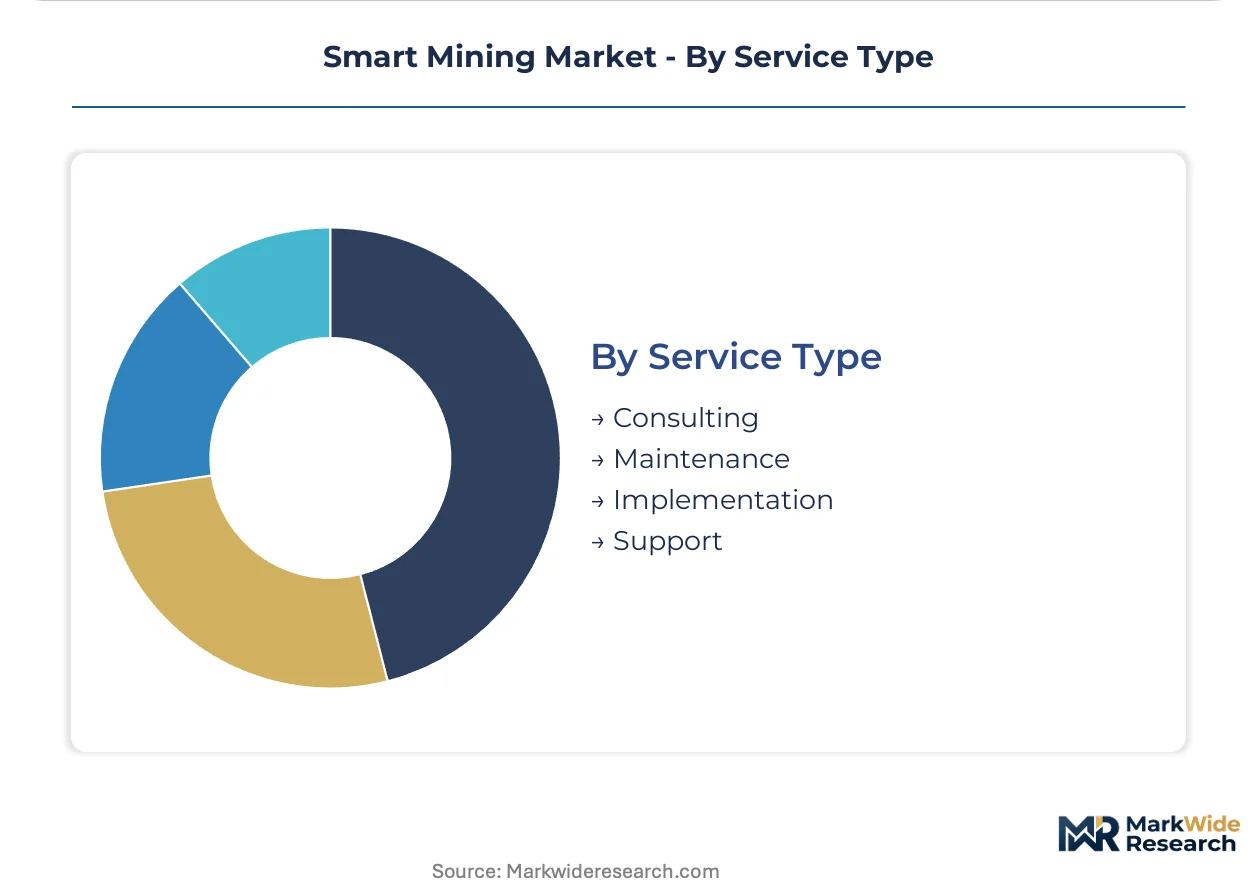
- Implementation:Specialized integration services command premium pricing relative to standard maintenance contracts. Complexity of retrofitting legacy infrastructure with interoperable digital layers drives sustained demand across Chile's copper belt and Australia's modernization programs.
- Maintenance:After-sales service unbundling fragments traditional bundled contracts. Australia's copper-gold sector and Chilean state-owned complexes increasingly separate hardware procurement from ongoing support agreements.
- Consulting:Strategic advisory services guide technology roadmaps and vendor selection processes.
- Support:Tiered helpdesk and field engineering services address operational continuity requirements.
Implementation services generate the highest margins per contract. Maintenance represents the largest recurring revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys smart mining technologies for safety compliance and labor substitution, while Chile concentrates on surface autonomy for aging copper infrastructure, and the United States emphasizes underground environmental monitoring—each geography optimizing for distinct operational pain points.
Australia
Underground hard-rock miners accelerate connected drill rig adoption to offset persistent certified operator shortages. The national resources regulator mandates replacement of legacy fleets with sensor-integrated machinery, compressing equipment refresh cycles. Western Australia's Pilbara iron ore belt hosts concentrated autonomous haulage deployment across tier-one producer operations.
Chile
State-owned and private operators deploy autonomous haulage systems across aging open-pit copper complexes to sustain output with diminished labor pools. The mining inspectorate imposes tightened autonomous equipment certification requirements, extending supplier product development timelines. The Atacama Desert copper belt anchors regional demand for retrofit integration services.
United States
Underground coal and metal operations face MSHA continuous monitoring mandates for respirable dust and ground stability. The Mine Safety and Health Administration enforces real-time environmental sensor network deployment, stimulating demand in Appalachian and Western underground basins. Implementation services command premium pricing relative to standard maintenance contracts.
China
Domestic mining groups integrate IoT sensor networks and AI analytics to optimize processing yields without full fleet replacement. MIIT standards and dual carbon goals pressure operators toward energy-efficient autonomous systems. Inner Mongolia and Shanxi coal basins concentrate smart mining pilot programs for state-owned enterprise modernization.
Canada
Precious and base metal producers in Ontario and Quebec adopt precision mine-planning software extending from exploration through reclamation. Health Canada and provincial regulators align autonomous equipment certification with international standards, shaping vendor market access requirements. The Sudbury Basin anchors underground hard-rock smart mining adoption for nickel-copper extraction.
Smart Mining Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack autonomy providers commanding long-term fleet contracts while precision software vendors occupy defensible niches. The market structure rewards hardware-software bundling that creates sticky multiyear service relationships. Two strategic archetypes dominate: integrated platform providers spanning autonomous vehicles through remote operation centers, and specialized software houses focusing on mine-planning and ore-grade optimization. Competitive moves concentrate on backward integration into proprietary autonomous control systems and geographic expansion through localized implementation partnerships.
Within the integrated platform tier, Caterpillar Inc. and Komatsu Ltd. anchor positions through captive autonomy stacks and reduced third-party dependency. Hexagon AB exemplifies the specialized software archetype, occupying a narrow but defensible niche in precision mine-planning from exploration through reclamation. These three entities represent the competitive spectrum from full-stack integration to focused functional excellence.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Sandvik AG |
| ABB Ltd |
| Rockwell Automation Inc. |
| Cisco Systems Inc. |
| Hexagon AB |
| Hitachi Ltd. |
| SAP SE |
| Others |
Supply Flow & Price Mechanics
Ninety-to-120-day lead times for autonomous haul truck sensor arrays concentrate pricing power with Tier 1 suppliers in Germany and Japan, while Australian and Chilean operators absorb premium implementation costs to satisfy tightened safety certification windows. Hardware-software bundling creates sticky multiyear relationships that resist spot-market arbitrage.
Pricing Analysis
Long-term fleet service contracts dominate procurement for tier-one copper and iron ore producers, locking in predictable revenue streams for integrated platform providers. Subscription-tiered SaaS pricing for AI analytics and remote operation center software differentiates by pit complexity and data throughput volume. Cost compression in mid-tier retrofit services intensifies as procurement teams unbundle hardware from implementation support. Price sensitivity concentrates most acutely among mid-tier miners assembling multi-vendor technology stacks, while tier-one operators prioritize interoperability assurance over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision sensor and autonomous control system manufacturing, while Australia and Chile concentrate downstream deployment and integration services. Lithium-ion battery cells, high-grade optical components, and ruggedized computing hardware feed from South Korean and Taiwanese production bases. Single-source vulnerability in hyperspectral imaging sensor supply creates exposure to export licensing delays. Distribution runs through OEM-direct channels for tier-one fleet contracts and specialized systems integrators for mid-tier retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart mining is crossing into platform-economics territory where interoperability standards determine competitive survival, with Australia's national resources regulator and Chile's mining inspectorate forcing convergence on common autonomous equipment certification protocols.
For Market Incumbents: Fortify backward integration into proprietary autonomy stacks to reduce third-party dependency for deployment. Expand captive service networks across Chile's copper belt and Western Australia's Pilbara region before emerging software specialists capture retrofit integration margins. Lock in long-term fleet contracts through performance guarantees on fuel consumption and cycle time compression.
For New Entrants and Emerging Players: Implementation service gaps in underground hard-rock operations present immediate white-space opportunity where certified operator shortages outpace incumbent deployment capacity. Target mid-tier copper-gold producers in Australia's eastern states with unbundled AI analytics subscriptions that layer atop existing IoT sensor networks. Pursue partnership-first go-to-market positioning with regional systems integrators possessing established mining operator relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because autonomous fleet contracts generate decade-plus service relationships with minimal churn. Acquisition candidates include precision mine-planning software specialists with exploration-to-reclamation workflow coverage and environmental sensor network providers with MSHA certification pathways. Monitor regulatory harmonization progress between Australia's national resources regulator and Chile's mining inspectorate as inflection signal for cross-regional platform scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Autonomy Stacks | Caterpillar and Komatsu reduce third-party software dependency, tightening grip on tier-one fleet contracts. |
| AI Analytics Platform Launch | Mid-tier miners optimize processing yields without full fleet replacement, expanding addressable market penetration. |
| Regional Implementation Partnership | Specialized integrators capture retrofit margins in Chile's Atacama Desert copper belt and Australia's hard-rock undergrounds. |
| Environmental Sensor Network Certification | MSHA-compliant providers access US underground coal and metal operations under continuous monitoring mandates. |
| Remote Operation Center Consolidation | Tier-one producers centralize multiple pit locations, displacing on-site operator roles across Chilean and Australian complexes. |
Methodological Framework
Cross-validation between primary interviews with mine operations directors, autonomous fleet procurement managers, and remote operation center supervisors and secondary validation through SEC equipment manufacturer filings, national resources regulator safety protocol documentation, and copper belt production statistics anchors the qualitative findings. Bottom-up equipment deployment tallies triangulate against top-down mining capital expenditure surveys across the analysis window.
Sensitivity analysis around regulatory certification timelines and commodity price volatility shapes the analytical framework across technology, application, end user, and service type segmentation dimensions. CAGRs derive from installed base growth curves and replacement cycle compression observed in Australian and Chilean modernization programs. Fleet autonomy penetration rates and IoT sensor network deployment velocities serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Australia's national resources regime and Chile's mining inspectorate; material policy shifts on autonomous equipment certification would require re-modeling. Technology interoperability standards and labor pool replenishment rates constitute primary revision triggers. Recalibration cycles align with material shifts in national safety protocol adoptions and tier-one fleet contract renewal windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Crawler Excavator Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Mining Drill Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Global Dozers Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Mining Machinery Market