
 Mine Scaler Market | 2026-2036
Mine Scaler Market Size, Share, and Industry Trends Forecast 2026-2036
Mine Scaler Market Outlook
Aftermarket service revenue is reshaping margin distribution across the mine scaler value chain. Jama Mining Machines leverages its Nordic service infrastructure to capture recurring maintenance contracts in Scandinavian underground mines. NPK Construction Equipment anchors its position through captive supply of hydraulic breaker attachments that integrate with scaler platforms. Normet competes by extending its battery-electric vehicle expertise into zero-emission scaling systems for ventilation-constrained operations.
A mine scaler is a specialized mobile machine equipped with a rigid or articulated boom-mounted scaling tool, typically delivering impact forces of 100-300 joules, designed to remove loose rock from underground excavation surfaces after blasting to prevent ground falls. Its primary industrial purpose is to secure worker safety and maintain production continuity in tunnel headings, stopes, and drifts before bolting or shotcrete application. Hydraulic scalers dominate installed base volumes across hard-rock underground mines, while electric scalers represent the fastest-growing product category as diesel particulate regulations tighten in confined headings. Rental deployment is gaining share among mid-tier contractors who face capital constraints on project-specific contracts, though purchase models still command the majority of revenue in owner-operator mining company fleets.
The US Mine Safety and Health Administration enforces ground control standards that mandate systematic scaling before worker entry, directly conditioning equipment procurement specifications and inspection protocols. ISO 19296 on underground mining machine safety and the EU Machinery Directive's CE marking requirements shape design compliance costs for manufacturers serving European and export markets. Stakeholders must weigh the capital intensity of electrification against the operational flexibility of dual-power platforms as regulatory timelines for diesel phase-outs crystallize across major mining jurisdictions.
Market Dynamics
The mine scaler market pivots on diesel phase-out mandates tightening across underground mining jurisdictions, forcing capital redeployment toward battery-electric and hydraulic platforms in ventilation-constrained operations.
Growth Catalysts
- EU F-Gas Regulation:The European Union's fluorinated gas restrictions accelerate replacement of diesel-powered equipment with electric alternatives in continental hard-rock mines.
- Declining ore grades:Chilean copper operators expand mechanized ground support fleets as extraction depths increase and manual scaling becomes uneconomical.
- Labor shortages:Australian gold and nickel provinces drive automated scaling adoption where skilled underground workers are increasingly scarce.
Market Restraints
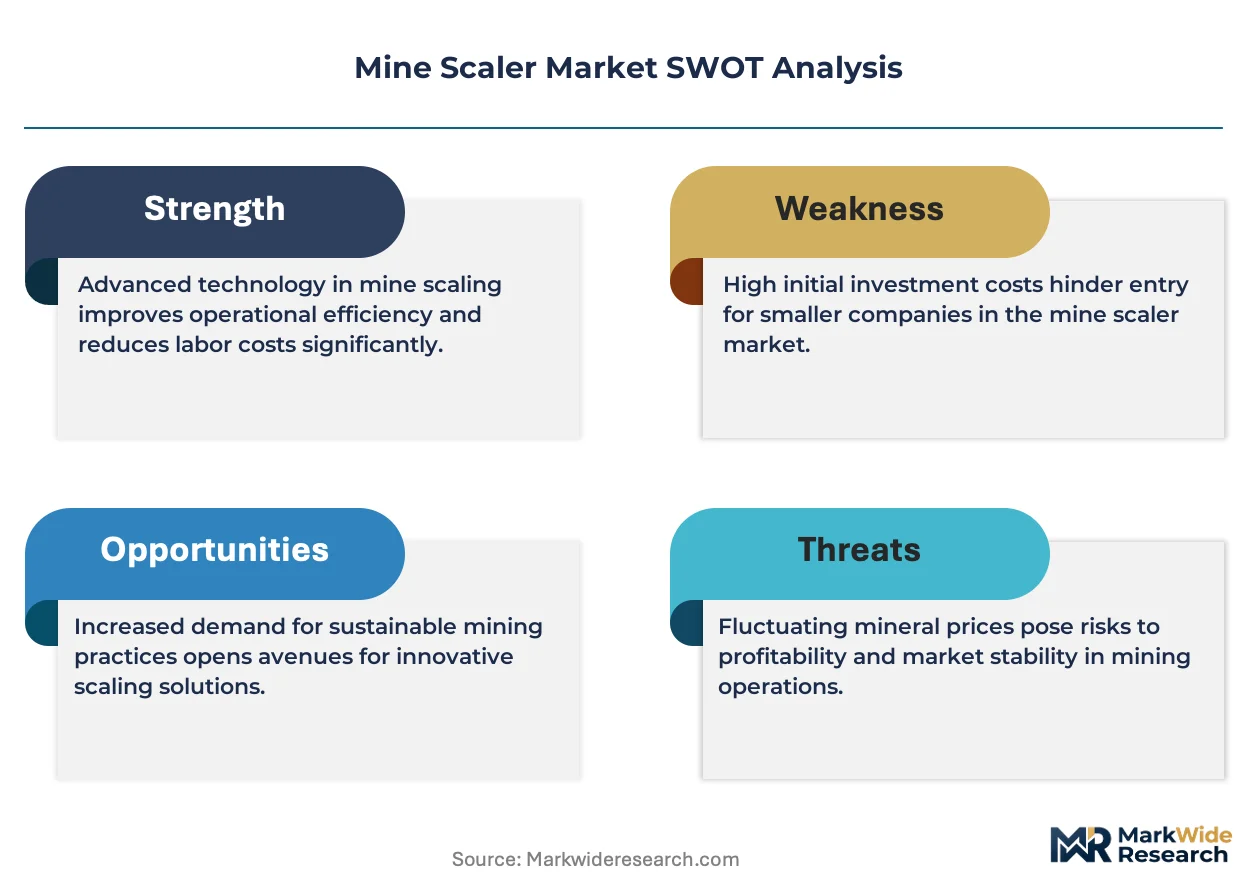
- Battery cost volatility:Lithium-ion cell prices and raw material supply uncertainty inflate total cost of ownership for electric scaler platforms versus hydraulic alternatives.
- Technical limitation:Energy density constraints in current battery chemistries limit continuous operating cycles in deep, hot headings where ventilation is restricted.
- Substitution threat:Remote-controlled and semi-autonomous drilling jumbos with integrated scaling attachments capture share in narrow-vein applications.
Strategic Opportunities
- Underpenetrated geography:Indonesian nickel-cobalt underground operations present untapped demand as the country expands battery mineral extraction capacity.
- Regulatory tailwind:Canada's provincial carbon pricing mechanisms and federal clean fuel standards create incentive structures for zero-emission equipment procurement.
- Technology convergence:Integration of lidar-based rock mass characterization with scaler boom positioning systems enables precision removal and reduces overbreak.
Industry Challenges
- Skill gap in battery-electric maintenance:Underground mine maintenance crews lack training in high-voltage systems and thermal runaway protocols, slowing fleet conversion timelines.
- Capex intensity of dual-power platforms:Manufacturers must engineer modular powertrain architectures that accommodate both diesel and electric configurations without full redesign.
- ISO 19296 compliance timeline:Certification requirements for underground mining machine safety extend product development cycles and delay market entry for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine Scaler Market |
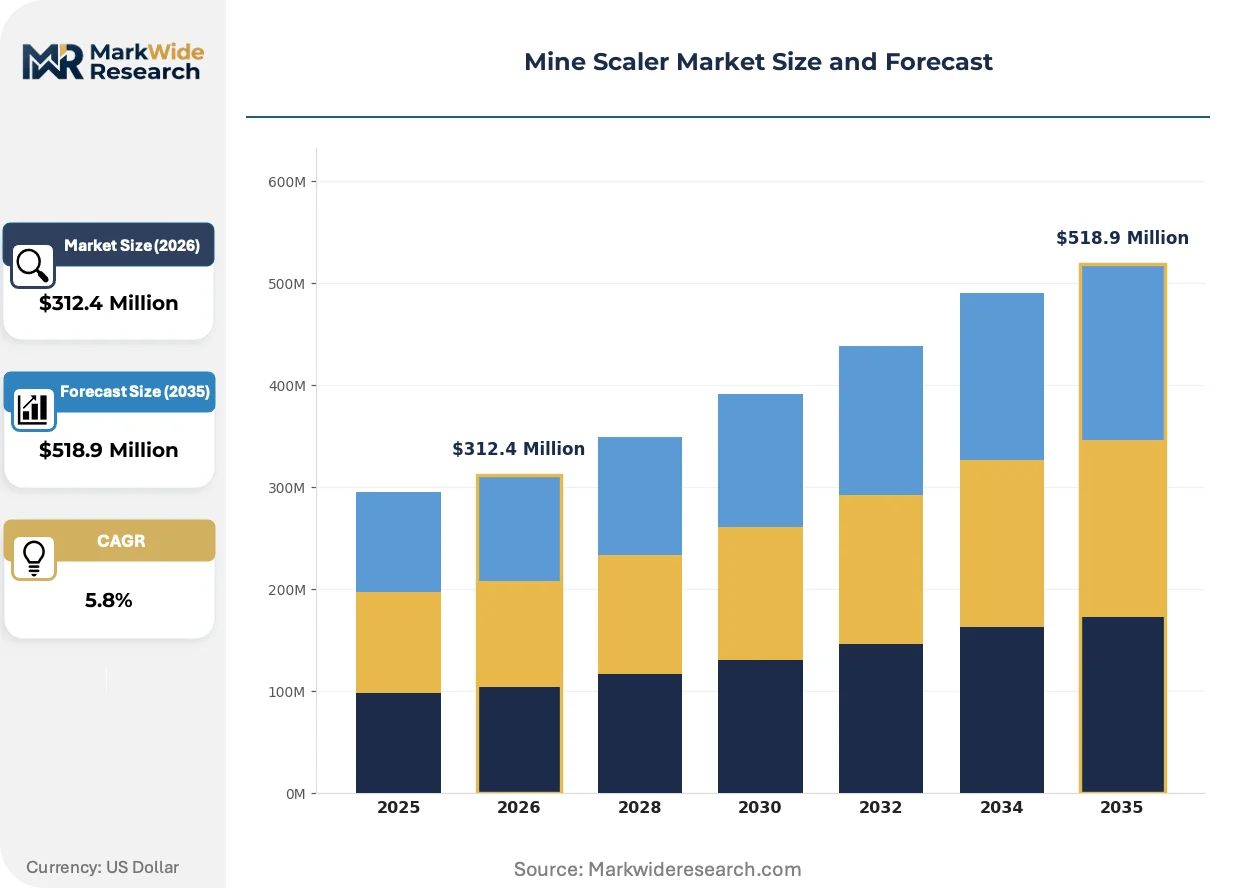
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Scalers, Pneumatic Scalers, Electric Scalers, Gas Scalers Application: Underground Mining, Tunneling, Surface Mining, Rock Excavation End User: Mining Companies, Construction Firms, Contractors, Quarry Operators Deployment: On-site, Off-site, Rental, Purchase |
| Companies Covered | Jama Mining Machines, NPK Construction Equipment, Astec Industries, Fermel, Getman Corporation, Alamo Group, Breaker Technology, Normet, Ergo Développement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine Scaler Market Strategic Shifts
Scaling technology is converging with autonomous navigation and electrification, reshaping equipment specifications and procurement criteria across hard-rock underground operations.
Battery-electric powertrains are migrating from niche ventilation-critical applications toward mainstream deployment in base metal and precious metal mines. Tier-one operators in Canada and Scandinavia now specify electric platforms as default for new headings. This migration from diesel-dominant fleets is compressing the addressable market for conventional hydraulic scalers and accelerating aftermarket service model transformation.
The EU F-Gas Regulation and national diesel particulate exposure limits in Germany, Sweden, and Finland mandate systematic equipment replacement schedules. These frameworks force owner-operators to accelerate capital planning cycles and favor rental or lease structures that transfer technology obsolescence risk. Battery-electric scaler categories capture disproportionate specification attention in European tender documents.
Contractor procurement patterns favor performance-based equipment availability agreements over outright purchase. Mid-tier mining services firms in Australia and Chile now demand guaranteed uptime metrics with OEM-managed maintenance. This shift compresses manufacturer margin structures while expanding recurring service revenue pools and locking in multi-year spare parts commitments.
Mine Scaler Market Segmentation
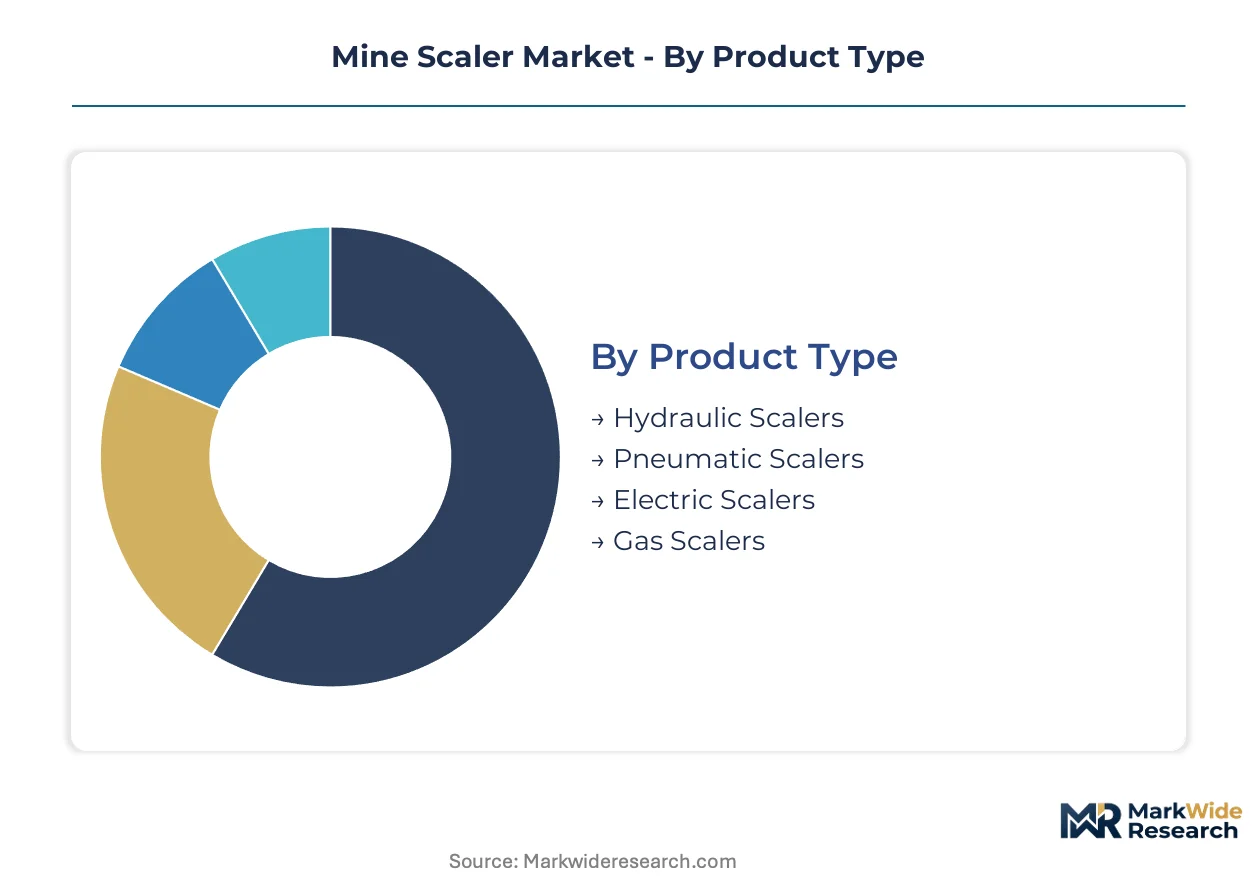
Mine scaler procurement patterns diverge sharply across powertrain technologies and deployment models. Equipment specifications must reconcile ventilation constraints, ground conditions, and capital availability in each operational context.
Product Type:
Powertrain technology determines operational envelope, emissions profile, and maintenance complexity in underground headings.
- Hydraulic Scalers:These systems leverage high-pressure fluid circuits to deliver consistent impact force across variable rock hardness. Hydraulic platforms retain dominance in Chilean copper operations where established service infrastructure and technician familiarity sustain fleet continuity despite electrification pressures.
- Electric Scalers:Battery-electric architectures eliminate diesel particulate emissions and reduce ventilation requirements in confined drifts. Australian hard-rock gold mines specify electric platforms as default for new headings where labor shortages intensify automation priorities.
- Pneumatic Scalers:Compressed-air systems operate without combustion or electrical hazards in gassy mine environments.
- Gas Scalers:LPG and natural gas variants serve transitional deployments where diesel phase-out timelines allow interim compliance.
Hydraulic scalers command the established base. The steepest expansion runs through electric platforms.
Application:
Ground support requirements vary with excavation geometry, rock mass quality, and production sequencing intensity.
- Underground Mining:Mechanized scaling secures tunnel headings, stopes, and drifts before bolting or shotcrete application in base and precious metal extraction. Declining ore grades in Chile's copper belt expand fleet deployment as manual scaling becomes uneconomical at increasing depths.
- Tunneling:Infrastructure projects demand rapid cycle times between excavation and ground support in civil headings. Urban metro expansions in Scandinavia specify zero-emission scaling equipment to comply with strict ventilation and emissions protocols.
- Surface Mining:Open-pit highwall scaling addresses rockfall hazards in bench and ramp configurations.
- Rock Excavation:Specialized civil and quarry applications require mobile scaling for slope stabilization and portal security.
Underground mining anchors equipment demand volumes. Tunneling applications are gaining share fastest as infrastructure investment accelerates.
End User:
Customer organizational structure shapes procurement authority, maintenance capability, and equipment financing preferences.
- Mining Companies:Owner-operators with captive maintenance infrastructure favor outright purchase and long-term fleet standardization. Tier-one base metal producers in Canada specify battery-electric platforms as corporate decarbonization commitments harden procurement criteria.
- Contractors:Mining services firms face project-specific capital constraints and demand performance-based availability agreements. Australian mid-tier contractors increasingly specify rental structures that transfer technology obsolescence risk to OEMs.
- Construction Firms:Civil tunneling specialists integrate scaling equipment with broader ground support fleets.
- Quarry Operators:Aggregate producers deploy scaled-down hydraulic platforms for intermittent highwall maintenance.
Mining companies retain the largest installed base. Contractors represent the most dynamic expansion channel as outsourcing deepens.
Deployment:
Equipment access models reflect capital intensity, project duration, and technology uncertainty in procurement decisions.
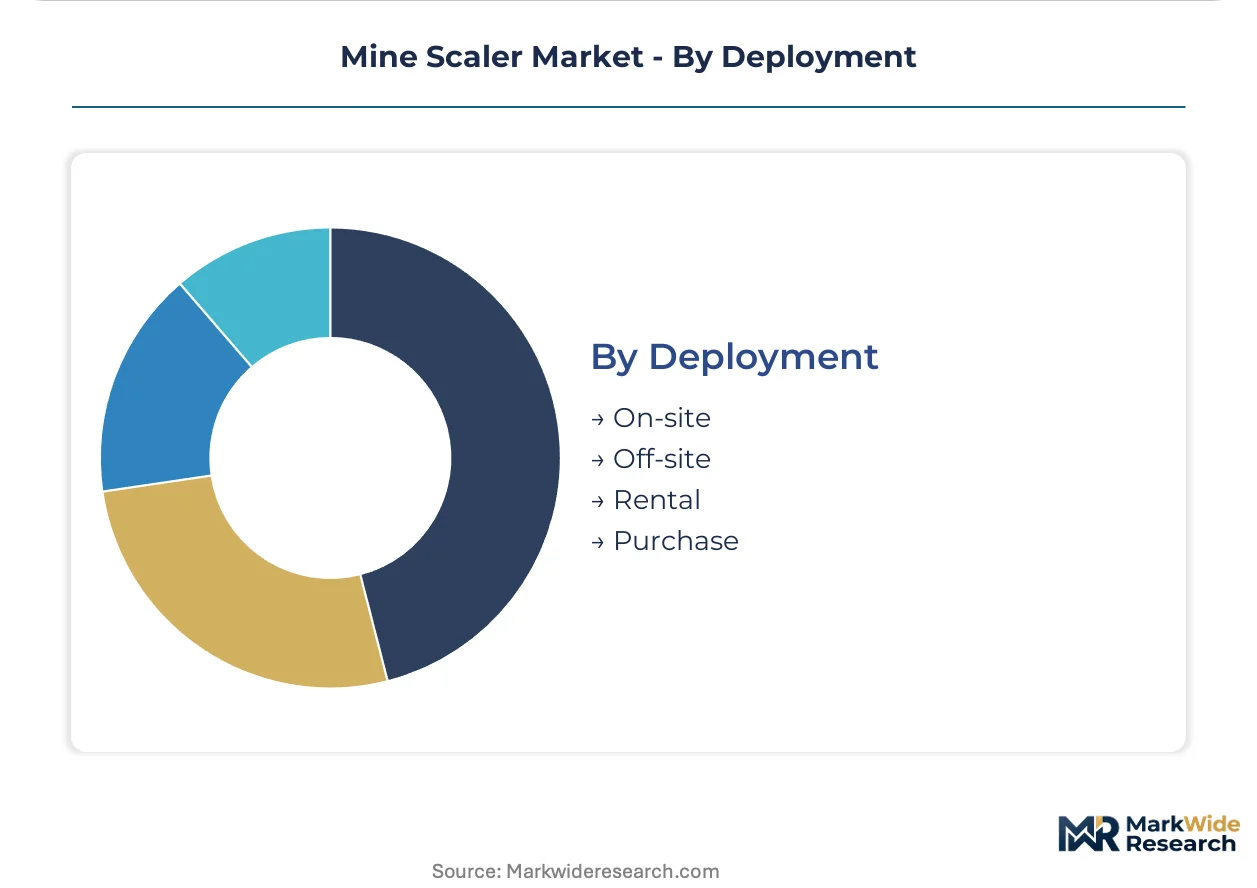
- Purchase:Owner-operators with multi-year production horizons amortize capital across extended utilization cycles. Fleet standardization in Scandinavian underground mines locks in multi-year spare parts commitments and OEM service contracts.
- Rental:Project-specific contracts and technology transition periods favor equipment leasing with maintenance inclusion. Chilean copper contractors deploy rental scalers to match fleet size to variable stope development schedules without balance sheet commitment.
- On-site:Dedicated equipment assignment to specific headings or mine sections.
- Off-site:Centralized fleet pooling across multiple operations or contractor mobilization.
Purchase models dominate revenue in owner-operator fleets. Rental deployment is expanding most quickly among capital-constrained contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Chile and Australia exhibit low price elasticity as labor shortages and ore grade decline force mechanization regardless of capital cost. European and Indonesian operators show higher sensitivity, prioritizing lease structures and technology transfer over outright purchase.
Australia
Western Australia's Kalgoorlie-Norseman gold belt and Kambalda nickel district drive electric scaler demand as skilled underground labor availability tightens. The country's diesel particulate exposure standard mandates systematic equipment replacement in ventilation-constrained headings. Perth-based contractor fleets increasingly specify performance-based availability agreements with OEM-managed maintenance.
Chile
Collahuasi, El Teniente, and Los Bronces copper operations expand mechanized ground support fleets as extraction depths exceed 1,000 meters. The Superintendencia del Medio Ambiente enforces emissions compliance timelines that accelerate diesel phase-out planning. Antofagasta and Santiago procurement offices now specify battery-electric platforms as default for new stope development.
Canada
Ontario's Sudbury Basin and Quebec's Abitibi gold belt anchor North American demand for zero-emission scaling systems. Federal clean fuel standards and provincial carbon pricing mechanisms create direct procurement incentives for electrified fleets. Toronto and Vancouver headquarters of tier-one base metal producers harden corporate decarbonization commitments into equipment specifications.
Indonesia
Sulawesi and Halmahera nickel-cobalt underground operations present underpenetrated demand as battery mineral extraction capacity expands. The country's Ministry of Energy and Mineral Resources promotes downstream processing investment that requires mechanized ground support infrastructure. Jakarta-based mining services firms face capital constraints that favor rental deployment models.
Sweden
Kiruna and Malmberget iron ore operations in Swedish Lapland specify zero-emission scaling equipment under corporate sustainability mandates. The EU F-Gas Regulation and national diesel particulate limits enforce systematic replacement schedules. Stockholm and Luleå procurement offices favor multi-year service contracts that transfer technology obsolescence risk to manufacturers.
Mine Scaler Market Competitive Environment
Full-line mining equipment manufacturers and specialized ground support specialists split the market into distinct competitive spheres. The installed base concentrates among Nordic and North American OEMs with established underground service infrastructure. Three archetypes dominate: diversified mining equipment conglomerates with captive scaler portfolios, dedicated ground support specialists with regional service density, and attachment-focused manufacturers integrating breaker technology with scaler platforms. Competitive moves center on electrification R&D partnerships and aftermarket service contract capture.
Within the dedicated specialist tier, Jama Mining Machines and Normet exemplify Nordic-origin players with battery-electric vehicle expertise extending into zero-emission scaling systems. NPK Construction Equipment represents the attachment-integrated archetype, leveraging hydraulic breaker supply relationships to anchor scaler platform positioning. These three companies illustrate how regional service infrastructure and powertrain specialization determine competitive differentiation in procurement decisions.
| Leading Market Players |
|---|
| Jama Mining Machines |
| NPK Construction Equipment |
| Astec Industries |
| Fermel |
| Getman Corporation |
| Alamo Group |
| Breaker Technology |
| Normet |
| Ergo Développement |
| Others |
Value Chain & Pricing Dynamics
Antofagasta-Santiago freight corridors govern landed cost differentials for hydraulic assemblies and battery modules, concentrating margin pressure on OEMs serving Chilean copper operators while enabling Nordic manufacturers to command premium positioning through integrated service bundling.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across the mine scaler value chain. Equipment pricing stratifies across premium, standard, and economy tiers based on powertrain architecture and OEM service infrastructure density. Cost compression in battery-electric platforms intensifies as lithium-ion cell volatility feeds through to total cost of ownership calculations. Contractor fleets in Australia exhibit highest price sensitivity, while owner-operators in Scandinavian iron ore operations prioritize availability guarantees over capital expenditure minimization.
Supply Chain Analysis
Export-control restrictions on high-voltage power electronics and rare-earth permanent magnets constrain component flows into battery-electric scaler manufacturing. Supply concentration centers on Finland and Sweden for boom fabrication, Germany for hydraulic systems, and South Korea for lithium-ion cell supply. Raw material dependencies rest on copper busbars, high-strength steel alloys, and thermal management ceramics. Single-source vulnerability in battery management system semiconductors poses structural risk. Distribution runs through OEM-direct channels for fleet sales and specialized mining equipment distributors for contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mine scaler market demands substitution defense against remote-controlled drilling jumbos with integrated scaling attachments that threaten narrow-vein applications.
For Market Incumbents: Pre-empt share erosion by deepening captive supply of hydraulic breaker attachments and accelerating battery-electric platform certification under EU F-Gas Regulation timelines. Secure multi-year service contracts in Chilean copper operations to lock out rental-focused competitors. Prioritize technician training infrastructure to address skill gaps in high-voltage maintenance. For New Entrants and Emerging Players: Indonesian nickel-cobalt underground operations with capital-constrained mining services firms represent the most penetrable entry point for rental-first deployment models. Target Australian mid-tier contractors with performance-based availability agreements that transfer technology obsolescence risk. Partner with established hydraulic component suppliers to bypass vertical integration barriers. For Investors and Strategic Acquirers: Regional aftermarket service specialists with dense Nordic or Canadian maintenance infrastructure offer compelling acquisition profiles for long-term exposure to electrification tailwinds. Monitor diesel phase-out mandate acceleration across Canadian provincial jurisdictions as the critical inflection signal for fleet conversion velocity and electric platform demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Certification | EU F-Gas Regulation compliance unlocks specification access in ventilation-constrained Scandinavian and German headings. |
| Aftermarket Service Contract Expansion | Multi-year maintenance agreements with Chilean copper operators secure recurring revenue against rental competitors. |
| Hydraulic Breaker Attachment Integration | Captive supply relationships anchor scaler platform positioning in hard-rock ground support procurement decisions. |
| Technician Training Infrastructure Buildout | High-voltage system certification programs address skill gaps slowing battery-electric fleet conversion timelines. |
| Performance-Based Availability Agreements | Uptime guarantees transfer technology obsolescence risk to OEMs and capture Australian contractor procurement preference. |
Study Parameters
A spread of perspectives from mine maintenance directors, OEM procurement teams, underground operations engineers, and aftermarket service heads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade records, SEC equipment manufacturer filings, and national mining safety regulator disclosures. Bottom-up equipment deployment counts triangulated against top-down mineral production forecasts across the analysis window.
Demand-supply-balance modeling anchored volume projections across powertrain technology, deployment model, and end-user archetype dimensions. Segmentation analysis tracked hydraulic, electric, pneumatic, and gas platform categories against underground mining, tunneling, surface mining, and rock excavation applications. CAGR derivation rested on equipment replacement cycle analysis, regulatory mandate timelines, and labor availability indices without year-specific anchoring.
Practitioners should monitor battery cost volatility, diesel phase-out mandate acceleration, and integrated drilling-scaling substitution threats for early signals of forecast deviation. Material shifts in lithium-ion supply chain configuration or EU F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Rock Duster Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mining Drill Market
Mining Equipment
Smart Mining Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Underground Mining Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Latin America Mining Equipment Market