
 Borehole Equipment Market | 2026-2036
Borehole Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Borehole Equipment Market Intelligence
Multi-source procurement for critical drill string components is recalibrating how mining operators manage fleet availability and capital deployment. Epiroc leverages its automation portfolio to differentiate in remote-site drilling contracts. Sandvik anchors its position through carbide insert technology and aftermarket parts density. Boart Longyear sustains market presence via specialized mineral exploration services and geotechnical data delivery.
Borehole equipment encompasses mechanized systems engineered to penetrate subsurface formations, typically achieving depths from tens to thousands of meters using rotary, percussion, or sonic force transmission through drill rods, bits, and casing assemblies. The equipment serves to extract groundwater, recover geological samples, install geothermal loops, or construct foundation piers with specified load-bearing capacity. Drilling rigs and drill bits together command the dominant share of product-type revenue due to replacement frequency and technology intensity. Directional drilling and sonic drilling represent the fastest-expanding technology categories, driven by precision requirements in environmental monitoring and geothermal energy applications where straight-hole deviation tolerances and undisturbed sample integrity determine project viability.
EPA groundwater protection standards in the United States, the EU Water Framework Directive, and ISO 18758 drilling machinery safety specifications collectively elevate compliance costs while filtering out non-certified suppliers. Australia's state-level mining safety regulators and China's GB standards for drilling equipment further fragment certification requirements across export markets. Stakeholders must weigh regulatory divergence against standardization economies when configuring product portfolios for cross-border deployment.
Market Dynamics
Sonic drilling technology is compressing project timelines in environmental monitoring while simultaneously elevating capital requirements for fleet operators seeking to compete in precision-sensitive contract categories.
Growth Catalysts
- Groundwater access mandates:Sub-Saharan African water utilities are scaling mechanized borehole programs to close infrastructure gaps in rural distribution networks.
- REACH chemical compliance:European environmental sampling protocols now require undisturbed core integrity that sonic methods uniquely deliver.
- Geothermal loop installation:Residential and commercial building codes in Germany and France are embedding vertical ground-source heat exchangers as default HVAC configurations.
Market Restraints
- Carbide supply concentration:Drill bit insert fabrication depends on tungsten carbide feedstock where Chinese refiners control upstream processing.
- ISO 18758 certification costs:Machinery safety testing and documentation requirements filter out smaller rig fabricators from export markets.
- Rotary rig asset stranding:Conventional fleet owners face write-down pressure as sonic contracts capture premium environmental monitoring volumes.
Strategic Opportunities
- Lithium corridor infrastructure:Western Australian Pilbara operators require deeper, more durable borehole networks for hard-rock spodumene extraction.
- Remote-site automation bundles:Unmanned rig operation paired with real-time telemetry opens contracts in hazardous or inaccessible terrain.
- US IRA clean energy credits:Geothermal drilling qualifies for production tax incentives that expand addressable project economics.
Industry Challenges
- Sonic drillhead maintenance specialization:Resonance frequency calibration requires technicians with physics backgrounds that traditional rig crews lack.
- Multi-jurisdiction certification stacking:Export manufacturers must sequence EPA, EU machinery directive, and GB standard approvals before delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Borehole Equipment Market |
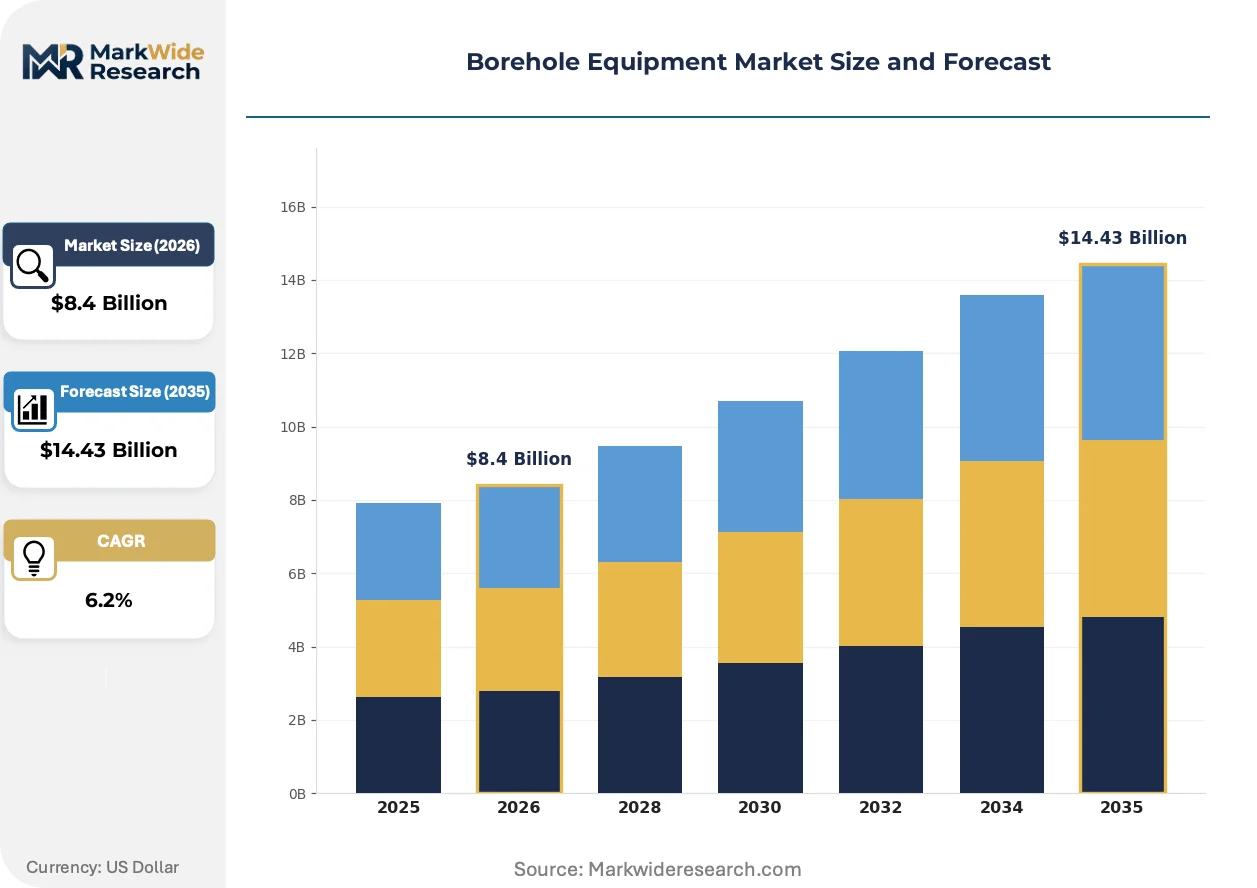
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Rigs, Casing Pipes, Submersible Pumps, Wellhead Equipment, Drill Bits, Mud Pumps Technology: Rotary Drilling, Percussion Drilling, Directional Drilling, Cable Tool Drilling, Sonic Drilling, Hydraulic Drilling Application: Water Extraction, Geothermal Energy, Mining Exploration, Environmental Monitoring, Agricultural Irrigation, Construction End User: Water Utilities, Mining Firms, Environmental Consultants, Agricultural Enterprises, Construction Companies, Research Institutions |
| Companies Covered | Epiroc, Sandvik, Boart Longyear, Drillmec, Caterpillar, Major Drilling, Atlas Copco, SANY Group, Foraco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Borehole Equipment Market Strategic Shifts & Innovations
Equipment intelligence and regulatory precision are converging to redefine competitive advantage across drilling service tiers.
Autonomous rig control systems are automating rod handling, depth logging, and deviation correction in Australia's iron ore provinces. Mining contractors deploy these configurations to reduce labor exposure in fly-in-fly-out operations while compressing shift-to-shift continuity losses. The technology is automating workforce requirements out of remote-site contracts and reallocating margin toward capital-heavy operators.
The EU Water Framework Directive's groundwater quality monitoring mandates are forcing sampling density increases across member states' agricultural and industrial zones. National environmental agencies now specify continuous core recovery methods that exclude conventional mud-rotary techniques. German and Dutch drilling contractors are retooling fleets to capture this specification-driven demand rotation.
Service unbundling is fragmenting traditional rig-plus-operator contracts into discrete equipment lease, technical supervision, and data interpretation components. Mining majors in Western Australia are piloting this model to internalize operational control while outsourcing capital ownership. The shift concentrates purchasing authority with procurement functions rather than site engineering teams.
Borehole Equipment Market Segmentation
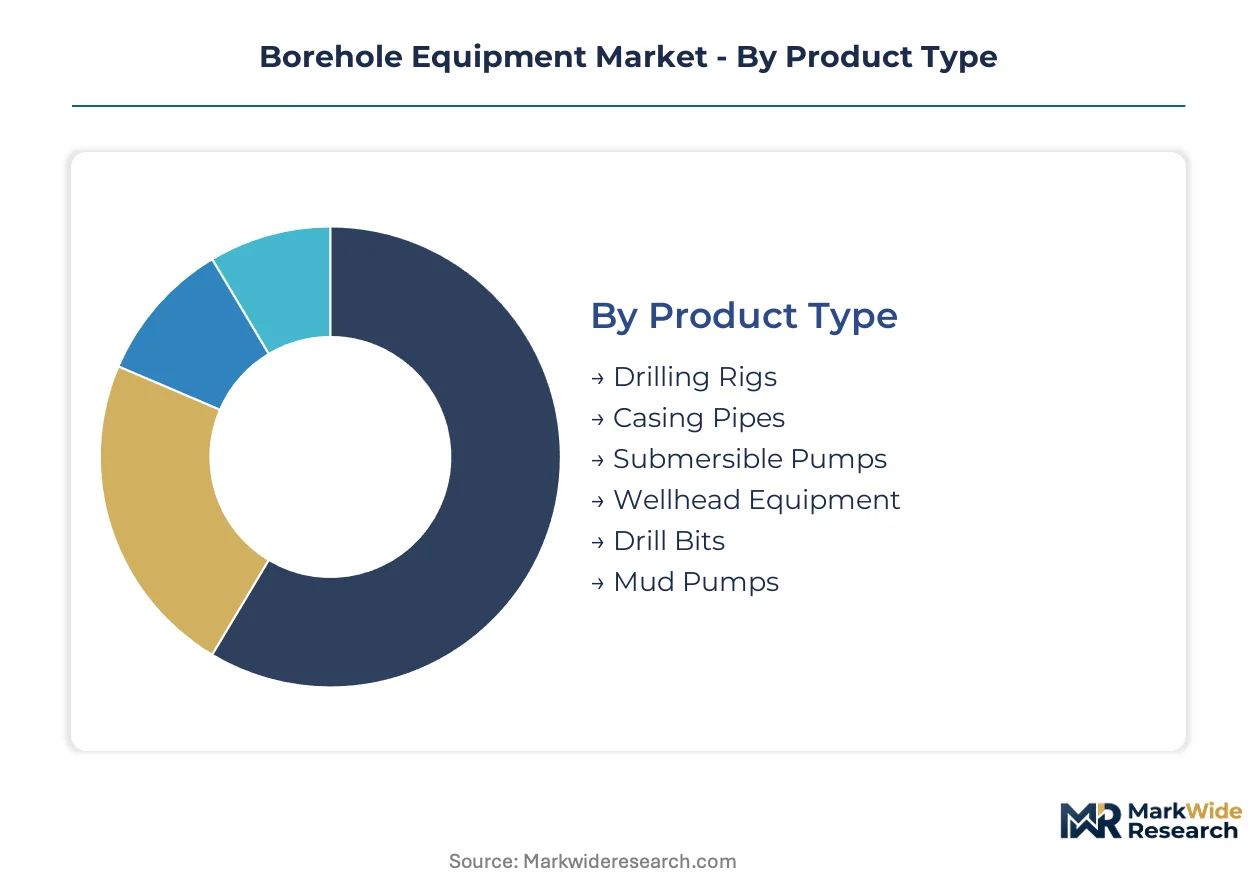
Segmentation in borehole equipment reveals how capital deployment, technology intensity, and regulatory exposure stratify across use cases. Equipment categories differ sharply in replacement cycles and aftermarket dependency, while technology choices determine which contractors can access premium environmental and geothermal contracts.
Product Type:
Standalone capital equipment dominates procurement budgets, whereas consumable and embedded components generate recurring revenue through replacement demand and wear-part contracts.
- Drilling Rigs:Self-propelled or skid-mounted mast assemblies delivering rotary, percussion, or sonic force to the drill string. Australian iron ore provinces and Western Australian lithium corridors anchor demand, where fleet utilization rates and automation integration determine contract awards. Rigs command the largest single capital outlay in project budgets and set the operational envelope for all downstream equipment choices.
- Drill Bits:Cutting structures incorporating tungsten carbide inserts, PDC cutters, or diamond-impregnated matrices tailored to formation hardness. Mining exploration programs in the Pilbara and environmental sonic drilling contracts drive specification diversity, with bit replacement frequency directly tracking meters drilled and formation abrasiveness.
- Casing Pipes:Steel or PVC tubulars stabilizing borehole walls and isolating aquifers or hydrocarbon zones.
- Submersible Pumps:Electric or hydraulic downhole units lifting groundwater to surface distribution networks.
- Wellhead Equipment:Surface assemblies controlling pressure, flow, and access for maintenance operations.
- Mud Pumps:Reciprocating positive-displacement units circulating drilling fluid to cool bits and transport cuttings.
Volume placements concentrate in drilling rigs and drill bits; the faster expansion belongs to sonic-capable rig configurations and specialized bit geometries for hard-rock lithium exploration.
Technology:
Technology selection locks contractors into specific contract categories, with precision methods commanding premium pricing and conventional approaches facing asset stranding pressure.
- Sonic Drilling:Resonance-frequency penetration achieving continuous core recovery with minimal fluid invasion. German and Dutch environmental contractors are retooling fleets to meet EU Water Framework Directive sampling specifications that exclude mud-rotary alternatives. The method compresses project timelines in contaminated-site characterization while elevating capital barriers for fleet operators.
- Directional Drilling:Steerable bottom-hole assemblies deviating borehole trajectories to target specific subsurface zones. Geothermal loop installation in Germany and France leverages this capability to maximize heat exchanger contact with conductive formations beneath built environments.
- Rotary Drilling:Conventional rotation of tricone or PDC bits with fluid circulation for cuttings removal.
- Percussion Drilling:Down-the-hole hammer systems transmitting impact energy through the drill string.
- Cable Tool Drilling:Reciprocating chisel-and-bit method for shallow water wells in consolidated formations.
- Hydraulic Drilling:High-pressure fluid jetting as primary or auxiliary rock removal mechanism.
Contractor margins concentrate in sonic and directional methods; the steepest adoption curve belongs to sonic technology as environmental monitoring specifications tighten across European member states.
Application:
Application segmentation maps directly to regulatory exposure and project financing structures, with public infrastructure and clean energy applications accessing concessional capital.
- Water Extraction:Mechanized borehole programs addressing rural distribution deficits across Sub-Saharan African utilities. National water authorities in Kenya, Nigeria, and Ethiopia are scaling procurement of diesel and solar-powered rig packages to close infrastructure gaps in unserved districts.
- Geothermal Energy:Vertical ground-source heat exchanger installation driven by building code mandates in Germany and France. The US Inflation Reduction Act production tax credits expand project economics for residential and commercial drilling contractors.
- Mining Exploration:Deep penetration for ore body delineation and resource definition.
- Environmental Monitoring:Contaminated-site characterization and groundwater quality surveillance.
- Agricultural Irrigation:Shallow borehole networks supporting intensified cultivation in water-stressed regions.
- Construction:Foundation piers and ground improvement for structural load transfer.
Public procurement volumes concentrate in water extraction; the fastest share gain belongs to geothermal energy as European building codes embed ground-source HVAC as default configuration.
End User:
End-user structure determines purchasing authority, with mining majors internalizing operational control and water utilities outsourcing to drilling contractors.
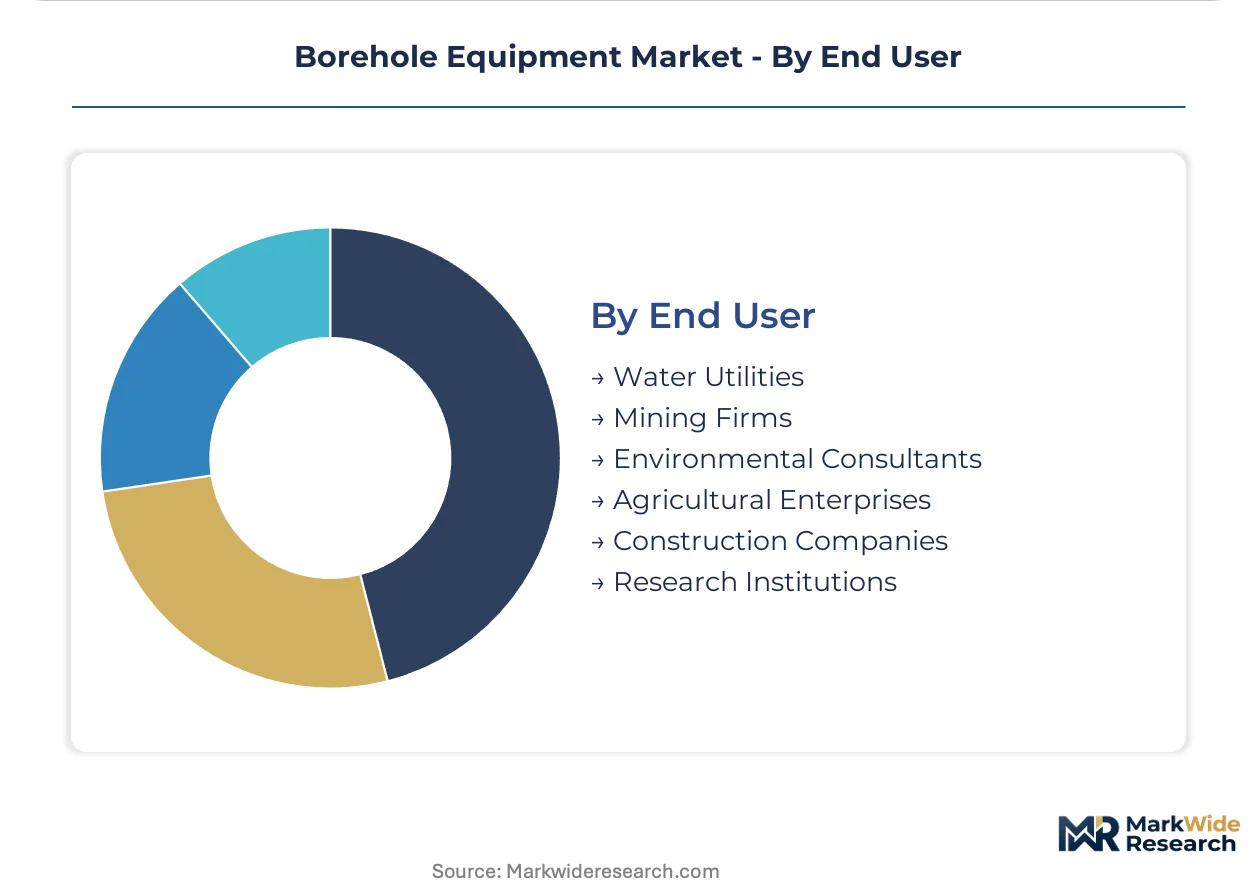
- Mining Firms:Integrated and junior miners operating exploration programs in Western Australia's Pilbara and lithium provinces. Service unbundling pilots are fragmenting traditional rig-plus-operator contracts into discrete equipment lease and technical supervision components, concentrating purchasing authority with procurement functions.
- Water Utilities:State and municipal authorities managing rural distribution network expansion. Sub-Saharan African utilities are scaling mechanized borehole programs with multi-year procurement frameworks that prioritize fleet availability and spare parts density.
- Environmental Consultants:Specialized firms delivering contaminated-site characterization and regulatory compliance documentation.
- Agricultural Enterprises:Large-scale farming operations and irrigation cooperatives.
- Construction Companies:General contractors and foundation specialists.
- Research Institutions:Universities and geological surveys conducting academic and baseline resource assessment.
Capital deployment concentrates with mining firms and water utilities; the most rapid purchasing authority shift belongs to mining procurement functions as service unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten carbide feedstock from Chinese refiners anchors supply-side concentration for drill bit fabrication, while mechanized borehole deployment concentrates in mining corridors and groundwater-stressed regions across five distinct national markets.
Australia
Iron ore provinces in Western Australia and lithium corridors in the Pilbara drive demand for deeper, more durable borehole infrastructure. State-level mining safety regulators mandate automation-ready rig specifications for fly-in-fly-out operations. Perth-based contractors deploy autonomous rod-handling systems to compress shift continuity losses in remote terrain.
Germany
Building code mandates embed vertical ground-source heat exchangers as default HVAC configurations in residential and commercial construction. The EU Water Framework Directive forces sampling density increases that exclude conventional mud-rotary techniques. Environmental contractors in the Ruhr and Rhine-Ruhr metropolitan regions retool fleets to capture specification-driven demand for continuous core recovery.
United States
EPA groundwater protection standards elevate compliance costs while filtering out non-certified suppliers from environmental monitoring contracts. The Inflation Reduction Act production tax credits expand project economics for geothermal drilling contractors. Texas and California anchor deployment volumes, with Permian Basin operators and Central Valley agricultural districts scaling mechanized programs.
China
GB standards for drilling equipment fragment certification requirements for export-bound fabricators. Domestic mining exploration in Inner Mongolia and Shanxi Province sustains rotary rig demand even as environmental applications lag. Zhengzhou and Xuzhou manufacturing clusters supply rig assemblies across Belt and Road infrastructure corridors.
Kenya
National water authorities scale mechanized borehole programs to close infrastructure gaps in unserved rural districts. Multi-year procurement frameworks prioritize fleet availability and spare parts density over unit cost. Nairobi-based contractors coordinate diesel and solar-powered rig packages for distribution network expansion in the Rift Valley and northeastern arid counties.
Borehole Equipment Market Key Industry Players
Strategic partnerships dominate the current landscape as rig manufacturers align with automation specialists and telemetry providers to bundle remote-site capabilities. The vendor base stratifies across three tiers: diversified mining equipment conglomerates with full automation portfolios, specialized drilling contractors with regional fleet density, and emerging Asian fabricators competing on capital cost. Two archetypes define competitive positioning: technology-integrated solution providers capturing premium environmental contracts, and scale-driven operators defending share in commodity exploration. Geographic expansion into lithium corridors and technology licensing for sonic drillhead calibration represent the dominant competitive moves.
Within the technology-integrated tier, Epiroc and Sandvik occupy positions anchored by automation portfolios and carbide insert technology respectively. Boart Longyear exemplifies the specialized contractor archetype, sustaining market presence through geotechnical data delivery capabilities. SANY Group represents scale-driven fabrication from Chinese manufacturing bases. These three companies collectively illustrate how competitive advantage converges on equipment intelligence, aftermarket parts density, and remote-site operational control.
| Leading Market Players |
|---|
| Epiroc |
| Sandvik |
| Boart Longyear |
| Drillmec |
| Caterpillar |
| Major Drilling |
| Atlas Copco |
| SANY Group |
| Foraco |
| Others |
Cost & Logistics Intelligence
Tungsten carbide feedstock indices from Chinese refiners cascade through three distinct pricing tiers for drill bit assemblies, compressing margins for European fabricators while elevating cost-plus premiums for ISO 18758-certified rig manufacturers serving Australian mining corridors.
Pricing Analysis
Warranty bundling separates premium rig contracts from unbundled equipment lease arrangements where maintenance risk transfers to operators. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and automation integration density. Cost compression in standard-tier rotary rigs is intensifying because asset stranding pressure forces fire-sale disposals by fleet operators losing environmental monitoring contracts to sonic-capable competitors. Water utilities in Sub-Saharan Africa exhibit highest price sensitivity due to concessional financing constraints, while Australian mining majors demonstrate lowest sensitivity where uptime guarantees dominate procurement scoring.
Supply Chain Analysis
Australia's state-level local-content mandates for mining safety equipment are reshaping sourcing patterns for automation-ready rig assemblies. Tungsten carbide feedstock draws from Chinese refiners in Hunan and Jiangxi provinces, while high-grade steel casting rests on German and Japanese foundry capacity. Single-source vulnerability concentrates in resonance-frequency electronics for sonic drillheads sourced from South Korean component specialists. Distribution runs through Perth-based contractor networks for Australian mining provinces and Nairobi-based logistics hubs for East African water utility programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 18758 certification costs and sonic technology capital barriers are consolidating the vendor base, forcing smaller rig fabricators into distressed exits or acquisition by diversified mining equipment conglomerates.
For Market Incumbents: Hedge against rotary rig asset stranding by accelerating sonic fleet conversion in German and Dutch environmental contracting markets. Backward integration into tungsten carbide insert fabrication through offtake agreements with Australian hard-rock mining operators secures supply continuity. Certification investment in multi-jurisdiction machinery safety approvals filters out Asian competitors from European environmental monitoring tenders. For New Entrants and Emerging Players: Launch via equipment lease-to-own models targeting Kenyan water utilities scaling mechanized borehole programs under multi-year procurement frameworks. Solar-powered rig configurations for Rift Valley distribution networks represent the most penetrable white space. Technical supervision unbundling allows capital-light entry without full fleet ownership burden. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized sonic drilling contractors with EU Water Framework Directive contract books in Germany's Ruhr metropolitan region. Five-to-ten year viability hinges on environmental regulation tightening trajectory across European member states. The signal to watch is REACH chemical compliance protocol expansion into agricultural groundwater surveillance mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Feedstock | Captive tungsten supply from Chinese refiners insulates Australian mining fleet operators against export restriction volatility. |
| Sonic Fleet Conversion Program | Retooling rotary configurations for EU Water Framework Directive contracts captures specification-driven demand rotation in Germany. |
| Remote-Site Automation Bundle | Unmanned rod-handling systems paired with real-time telemetry penetrate Western Australian fly-in-fly-out operation contracts. |
| Multi-Jurisdiction Certification Stacking | Sequencing EPA, EU machinery directive, and GB standard approvals accelerates cross-border deployment for export-bound fabricators. |
| Service Unbundling Pilot | Fragmenting rig-plus-operator contracts into discrete equipment lease components concentrates purchasing authority with mining procurement functions. |
Research Approach
Document review covered trade association drilling activity databases, national mining safety regulator filings, and customs export records for rig assemblies, complemented by interviews with fleet operations directors at Australian mining contractors, procurement managers at Kenyan water utilities, technical supervisors at German environmental drilling firms, and aftermarket parts specialists at Perth-based equipment distributors. Bottom-up rig deployment counts across Pilbara iron ore provinces and top-down capital expenditure triangulation from mining major disclosures validated volume estimates.
Cross-referencing historical fleet replacement cycles against primary panel input from rig manufacturers established the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, product category, application vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating lithium corridor infrastructure buildout assumptions and geothermal building code mandate penetration rates in Germany and France.
Commodity price volatility in tungsten carbide feedstock, regulatory divergence in machinery safety certification timelines, and technology substitution velocity from rotary to sonic methods are the dominant revision risks to deployment forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Logging Cable Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Underground Mining Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Continuous Miners Market