
 Digger Machinery Market | 2026-2036
Digger Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Digger Machinery Market Analytics
Multi-source procurement for critical hydraulic systems is decoupling from the long-standing single-vendor model that dominated digger machinery supply chains. Caterpillar sustains its position through captive production of high-displacement engines and drive trains across North American and European facilities. Komatsu competes by leveraging integrated sensor-to-cloud architectures that reduce aftermarket service dependencies for mining clients in Australia and Indonesia.
Digger machinery encompasses tracked and wheeled earthmoving equipment engineered around hydraulic circuits delivering breakout forces from 50 kN in compact units to over 2,000 kN in super-large mining excavators, purpose-built for excavation, trenching, and material handling across mineral extraction and civil infrastructure projects. Hydraulic technology still anchors the installed base, though electric and hybrid architectures are capturing the fastest replacement cycles in European urban construction where noise ordinances and diesel bans restrict equipment access. The compact size tier has matured into a margin-dense segment driven by landscaping and utility contractors requiring trailer-transportable units, while super-large machines concentrate value in mining applications where hour-meter economics favor premium durability.
The EPA's Tier 4 Final standards and the EU's Stage V regulations are forcing engine redesigns and after-treatment integration that add cost but also create replacement demand as pre-compliant fleets age out of permitted zones. China's MIIT enforces GB national standards on construction machinery emissions, shaping domestic manufacturers' export competitiveness into Southeast Asian and African markets. Stakeholders must monitor how autonomous technology integration reshapes fleet ownership models and whether regulatory divergence between emissions zones fragments product platform strategies.
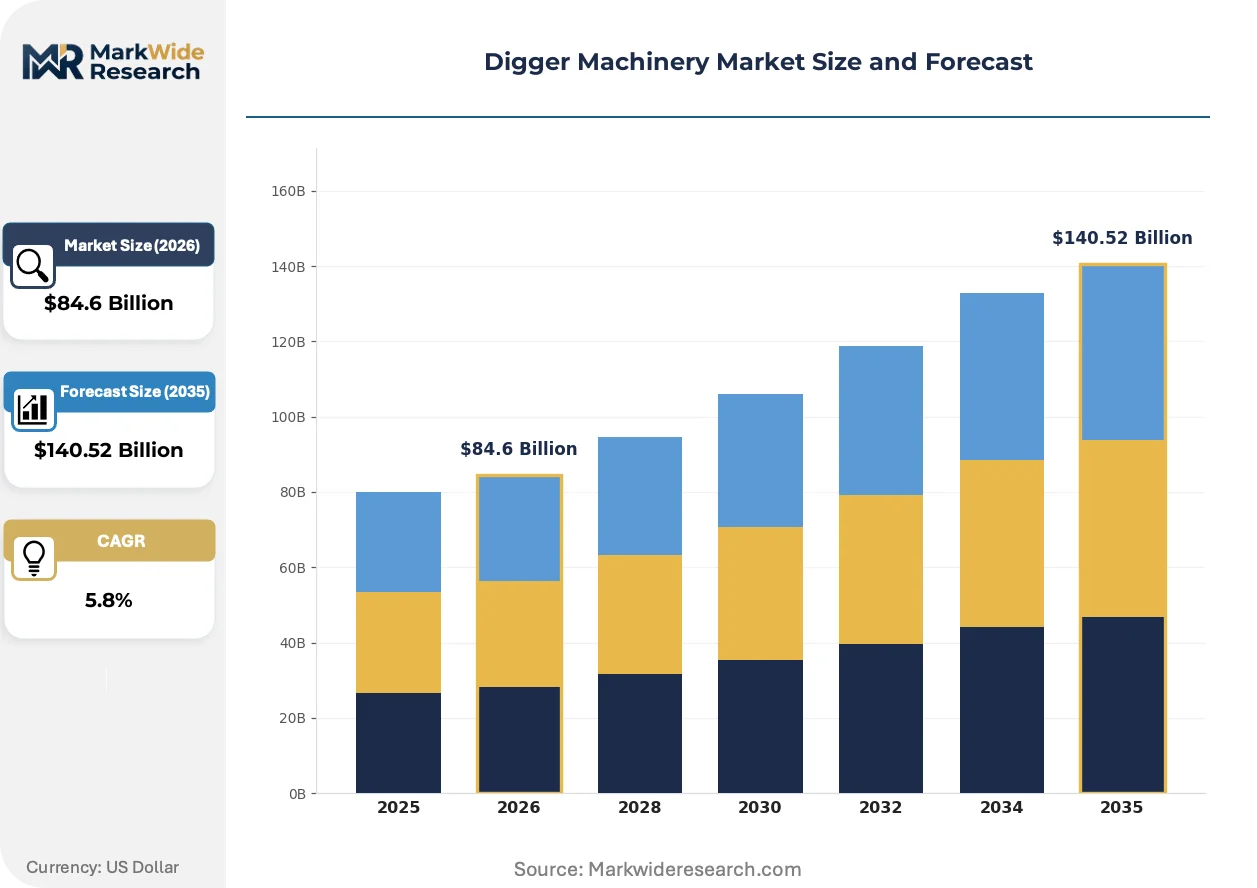
Market Dynamics
Emissions compliance deadlines across Australia, Chile, and China's western provinces are compressing replacement cycles for hydraulic excavator fleets as operators face exclusion from permitted work zones without Tier 4 Final or Stage V engine upgrades.
Growth Catalysts
- Emissions rule enforcement:Australia's mining regulators are accelerating fleet turnover by restricting pre-Tier 4 Final equipment access to extraction sites, forcing capital deployment toward compliant super-large excavators.
- Hydropower infrastructure expansion:China's western provinces require super-large excavator deployments for dam construction and transport corridor development, concentrating demand in Sichuan and Yunnan.
- Telematics integration:Sensor-to-cloud architectures reduce aftermarket service dependencies for mining operators, lowering total cost of ownership and shortening replacement decision timelines.
Market Restraints
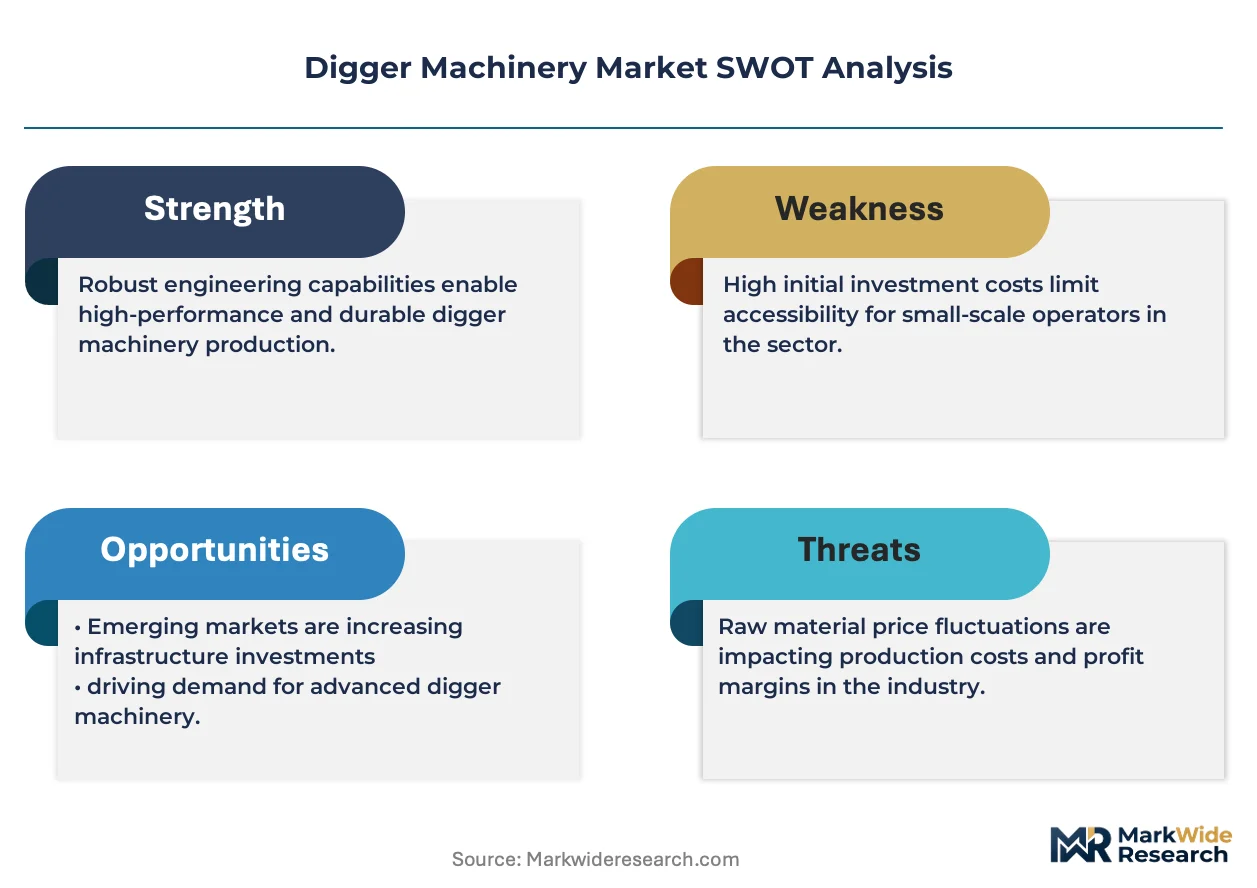
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add material cost to engine packages, compressing margins on compact equipment where price sensitivity dominates.
- Hydraulic component supply concentration:Precision pumps and high-pressure valves depend on specialized German and Japanese suppliers, exposing OEMs to allocation constraints during demand surges.
- Electric powertrain range limitations:Battery energy density constraints restrict electric excavator operating hours in remote mining applications where charging infrastructure is absent.
Strategic Opportunities
- Urban electrification mandates:European city diesel bans create replacement demand for electric and hybrid compact excavators in Berlin, Paris, and Amsterdam construction markets.
- Autonomous fleet integration:Mining operators in Western Australia are piloting operator-free excavation systems, opening service revenue streams for remote monitoring and fleet optimization.
- Used equipment export channels:Pre-Tier 4 Final machines excluded from Australian and Chilean mines find resale markets in Southeast Asian infrastructure projects with lagging emissions enforcement.
Industry Challenges
- Certification timeline compression:Engine redesigns for Stage V compliance require extended validation cycles, delaying product launches and narrowing competitive response windows.
- Hydraulic technician scarcity:Specialized repair capabilities for high-pressure circuits concentrate in aging workforces, constraining aftermarket service expansion in remote mining regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digger Machinery Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Backhoe Loaders, Mini Diggers, Attachments End User: Construction, Mining, Agriculture, Landscaping Technology: Hydraulic, Electric, Hybrid, Autonomous Size: Compact, Standard, Large, Super Large |
| Companies Covered | Caterpillar, Komatsu, Hitachi Construction Machinery, Volvo Construction Equipment, Liebherr, SANY, John Deere, Hyundai Construction Equipment, Doosan Infracore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digger Machinery Market Evolving Landscape
Electrification architectures and autonomous control systems are restructuring equipment value chains, shifting competitive advantage from mechanical durability to software-defined performance optimization and energy management.
Hybrid powertrains combining downsized diesel engines with electric boost systems are absorbing operating-hour volatility in European urban construction where intermittent duty cycles favor regenerative braking recovery. Municipal contractors in German and Dutch cities are specifying these configurations to meet noise ordinances while maintaining breakout force for utility trenching. The technology is absorbing market share from conventional diesel compact excavators in emission-restricted zones.
Stage V regulations enforced by EU member state authorities are mandating real-driving emissions monitoring for non-road mobile machinery, requiring onboard diagnostic systems that log actual operating conditions rather than laboratory test cycles. OEMs must now engineer engine calibrations that maintain compliance across altitude and temperature variations encountered in Alpine and Nordic construction sites. This regulatory architecture most affects compact equipment manufacturers serving mixed urban-rural contractor fleets.
Equipment-as-a-service contracting is displacing outright purchase for mid-size excavator fleets among European rental companies and Australian mining services firms. Hourly-rate agreements bundle maintenance, telematics, and upgrade pathways, transferring residual value risk from operator to manufacturer. This model concentrates in German-speaking markets and Western Australian iron ore operations where fleet standardization simplifies remote support logistics.
Digger Machinery Market Segmentation
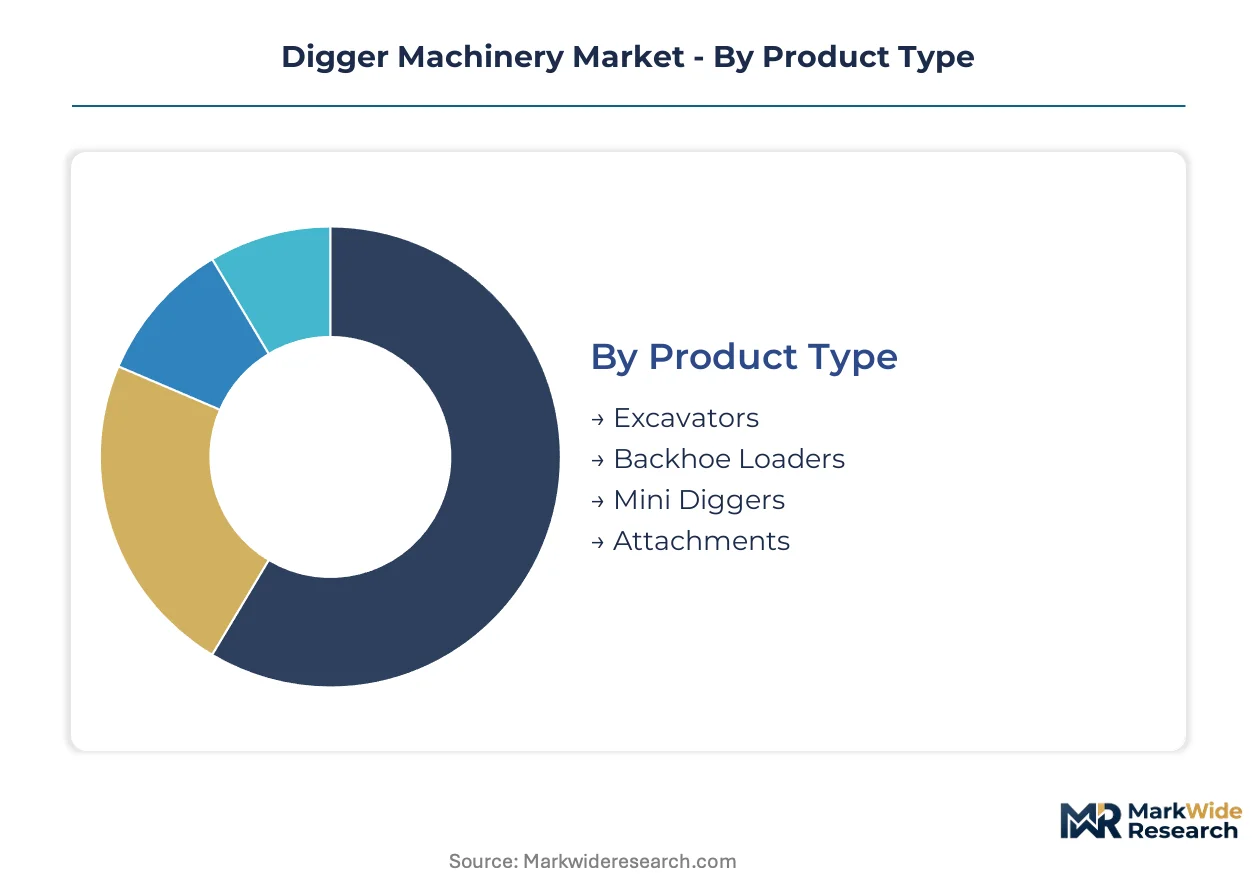
Segmentation in digger machinery reveals how emissions deadlines and duty-cycle requirements split demand across radically different equipment specifications. Fleet operators select configurations based on hour-meter economics, site access restrictions, and technician availability rather than upfront capital alone.
Product Type:
Replacement cycles accelerate where Tier 4 Final and Stage V engine upgrades force premature retirement of pre-compliant hydraulic architectures.
- Excavators:Tracked and wheeled units with boom-arm-bucket kinematics dominate mining and heavy civil applications. Australian iron ore operators in the Pilbara region are standardizing on 400-tonne class super-large models to maximize cubic-meter economics against tightening fuel efficiency benchmarks.
- Backhoe Loaders:Dual-function loader-excavator configurations serve utility contractors requiring rapid tool switching. Demand clusters in India's rural road programs and Brazilian municipal infrastructure where multi-purpose fleets reduce capital deployment.
- Mini Diggers:Sub-6-tonne units with zero-tail-swing designs access confined urban corridors. German rental fleets are absorbing electric variants ahead of Berlin and Munich diesel bans.
- Attachments:Quick-coupler buckets, hydraulic breakers, and grapples extend machine utilization rates. Wear-part replacement cycles concentrate aftermarket revenue in high-abrasion mining environments.
Excavators sit at the top of the volume ranking, with mini diggers climbing the fastest.
End User:
Cost tier stratification separates premium-specification mining fleets from price-sensitive agricultural and landscaping deployments.
- Construction:General contractors and specialty trades drive the largest equipment population. Chinese state-owned enterprises in Sichuan and Yunnan provinces are deploying super-large excavators for hydropower dam construction and mountain corridor highways.
- Mining:Surface extraction operators prioritize hour-meter durability and telematics integration. Chilean copper mines are accelerating fleet turnover to meet emissions compliance deadlines while maintaining 24-hour production schedules.
- Agriculture:Drainage ditching and land leveling applications favor compact and standard-size backhoe loaders. Brazilian soybean operations in Mato Grosso specify mid-range hydraulic excavators for seasonal wetland conversion.
- Landscaping:Trailer-transportable mini diggers serve residential and commercial groundworks. Dutch and Belgian contractors are specifying electric compact units to meet municipal noise ordinances in dense urban zones.
Construction commands the largest installed base, though mining exhibits the steepest expansion trajectory for super-large equipment categories.
Technology:
Application context determines whether mature hydraulic systems or emerging electric and autonomous architectures deliver superior total cost of ownership.
- Hydraulic:Open and closed-loop circuits with axial piston pumps remain the installed base standard. German and Japanese precision component suppliers constrain OEM output during demand surges.
- Electric:Battery-electric powertrains eliminate exhaust emissions for indoor demolition and tunneling. Amsterdam and Paris construction bans on diesel equipment are forcing rental fleet conversions.
- Hybrid:Downsized diesel engines with electric boost and regenerative braking recover energy from intermittent duty cycles. German municipal contractors specify these for utility trenching where noise limits apply.
- Autonomous:Sensor fusion and fleet management software enable operator-free excavation in controlled mining environments. Western Australian iron ore pilots are testing remote monitoring revenue models.
Hydraulic systems retain volume leadership, with electric configurations gaining share fastest in European urban markets.
Size:
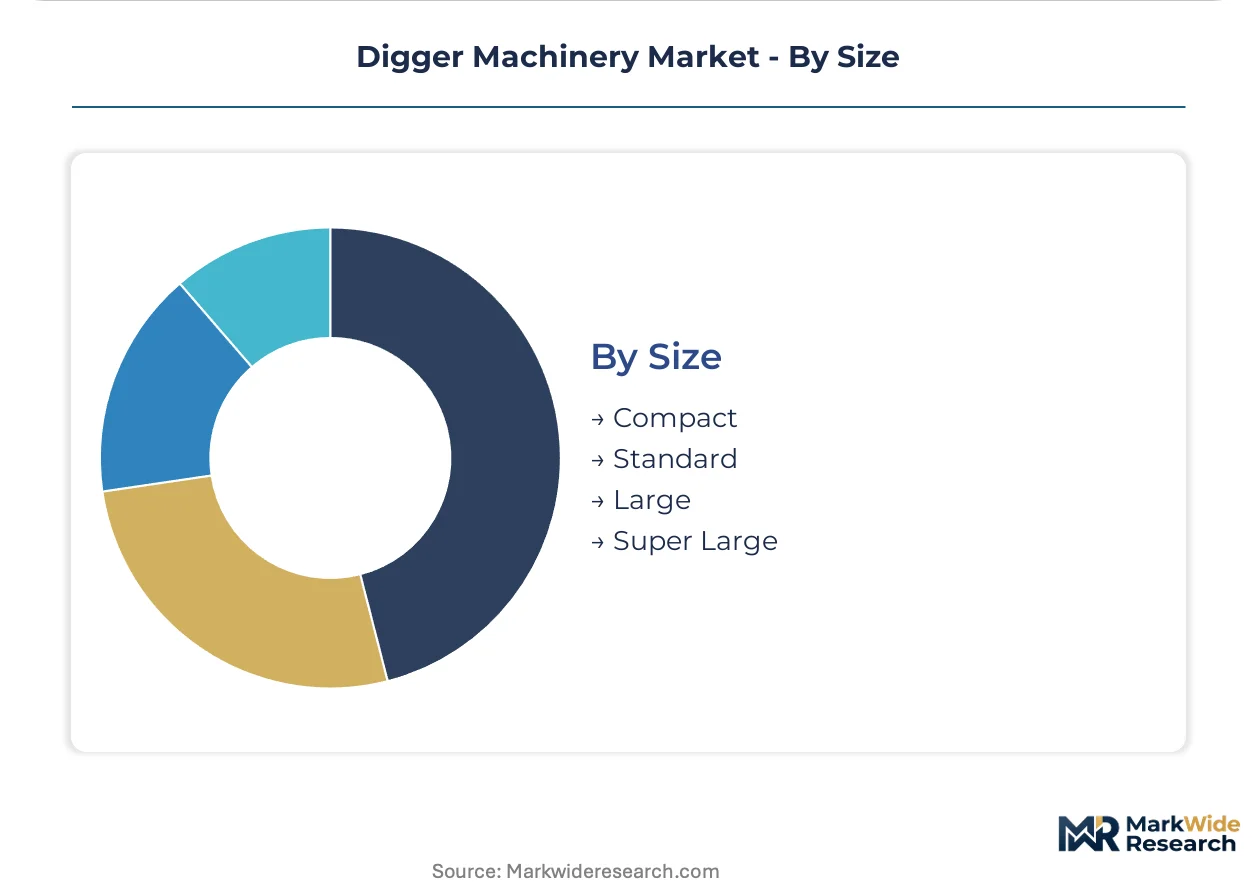
Margin concentration inversely correlates with unit volume across the size spectrum.
- Compact:Sub-10-tonne units with rubber tracks or wheeled undercarriages serve utility and landscaping trades. Trailer transportability defines procurement criteria for German and Dutch rental operators.
- Standard:10-45-tonne hydraulic excavators balance breakout force with mobility for general construction. Chinese infrastructure contractors in western provinces specify this tier for road and rail projects.
- Large:45-200-tonne machines dominate quarry and mass excavation applications. Australian mining services firms are renewing fleets ahead of emissions exclusion deadlines.
- Super Large:200-tonne-plus mining excavators with 2,000-plus kN breakout forces concentrate value in hour-meter economics. Chilean copper operators are standardizing on this tier for pit expansion programs.
Standard-size equipment leads unit shipments, while super-large machines capture the highest value-per-unit trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara mining operators anchor super-large excavator procurement as Australian iron ore producers accelerate fleet renewals ahead of emissions exclusion deadlines. Chilean copper mines and Chinese western province contractors concentrate parallel demand waves for compliant heavy machinery.
Australia
Western Australian iron ore operators in the Pilbara region are standardizing on 400-tonne class super-large excavators to maximize cubic-meter economics against tightening fuel efficiency benchmarks. The country's mining regulators restrict pre-Tier 4 Final equipment access to extraction sites, forcing capital deployment toward compliant fleets. Queensland coal operators are simultaneously renewing standard-size hydraulic fleets to maintain 24-hour production schedules.
Chile
Copper pit expansion programs in the Atacama Desert are driving super-large excavator deployments as operators balance emissions compliance with extraction volume targets. The country's mining ministry enforces progressive equipment retirement timelines for diesel machinery operating above 2,500 meters altitude. Antofagasta-based mining services firms are consolidating rental fleets around telematics-integrated architectures.
China
Sichuan and Yunnan province contractors are deploying super-large excavators for hydropower dam construction and mountain corridor highway development across the Tibetan Plateau edge. MIIT enforces GB national standards on construction machinery emissions, shaping domestic manufacturers' export competitiveness into Southeast Asian markets. XCMG and SANY production facilities in Jiangsu and Hunan provinces are scaling output for western infrastructure contracts.
Germany
Municipal contractors in Berlin, Munich, and Hamburg are specifying hybrid compact excavators to meet noise ordinances while maintaining utility trenching breakout force. The country's KBA enforces Stage V real-driving emissions monitoring requirements for non-road mobile machinery operating across altitude-variable Alpine construction sites. Bavarian rental fleets are absorbing electric mini digger variants ahead of diesel ban implementation.
United States
Texas Permian Basin oilfield services operators are renewing standard-size excavator fleets for pipeline trenching and pad construction as EPA Tier 4 Final enforcement tightens in non-attainment zones. Appalachian mining contractors face parallel pressure to retire pre-compliant hydraulic architectures from permitted work sites. Illinois and Ohio-based general contractors are concentrating procurement around telematics-enabled mid-size units for urban infrastructure rehabilitation.
Digger Machinery Market Competitive Landscape
Global majors compete with regional champions across engine technology and aftermarket service integration, producing a tiered structure where captive powertrain production separates premium-positioned OEMs from assembly-dependent competitors. Market concentration reflects emissions compliance capability and hydraulic component supply security rather than scale alone. Two strategic archetypes dominate: integrated engine-drive-train manufacturers and sensor-to-cloud platform specialists. Competitive moves center on multi-source procurement partnerships for critical hydraulic systems and equipment-as-a-service contracting models that transfer residual value risk.
Within the integrated powertrain tier, Caterpillar and Komatsu exemplify divergent approaches to emissions-era positioning. Caterpillar occupies a position anchored by captive production of high-displacement engines across North American and European facilities. Komatsu sits within the connected-fleet archetype, representing sensor-to-cloud architecture deployment that reduces aftermarket service dependencies for mining clients. Hitachi Construction Machinery anchors a third positioning vector among Japanese-headquartered OEMs with established presence in Australian and Indonesian mining markets.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Liebherr |
| SANY |
| John Deere |
| Hyundai Construction Equipment |
| Doosan Infracore |
| Others |
Value Network & Pricing Analysis
Captive engine production across North American and European facilities anchors Caterpillar's pricing power while compressing margin headroom for assembly-dependent OEMs sourcing powertrains externally. This integration choice separates premium-positioned manufacturers from competitors exposed to after-treatment cost inflation and hydraulic component allocation constraints during demand surges.
Pricing Analysis
Input-cost pass-through from German and Japanese precision hydraulic suppliers runs through to super-large excavator list prices with minimal absorption by OEMs. Three-tier pricing structure across premium, standard, and economy levels separates Tier 4 Final compliant fleets from pre-compliant equipment and electric compact variants. Price differentiation hinges on certification grade and telematics integration depth. Cost compression in the compact tier intensifies because after-treatment systems consume disproportionate material budgets against lower absolute equipment values. Landscaping contractors exhibit highest price sensitivity, while Australian mining operators prioritize hour-meter durability over capital outlay.
Supply Chain Analysis
Precision axial piston pump supply rests on German and Japanese specialty manufacturers, constraining OEM output during demand surges in Australian and Chilean mining markets. High-pressure valve castings and electronic control modules draw from concentrated production clusters in Germany, Japan, and South Korea. Single-source vulnerability for critical hydraulic architectures exposes fleet delivery timelines to allocation decisions at specialty component suppliers. Distribution runs through authorized dealer networks with captive service infrastructure for mining clients, while rental fleet procurement channels concentrate volume in European urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digger Machinery Market functions as a stable compounder where emissions compliance deadlines generate predictable replacement cycles across mining and infrastructure end uses.
For Market Incumbents: Anticipate accelerated fleet turnover in Australian and Chilean mining regions by securing multi-year allocation agreements with German and Japanese hydraulic component suppliers before demand surges compress availability. Defend margin position through captive after-treatment system integration rather than outsourced engine packaging. Prioritize telematics platform standardization to capture equipment-as-a-service revenue streams displacing outright purchase in Western Australian iron ore operations.
For New Entrants and Emerging Players: Mining services firms in Southeast Asian markets represent the most penetrable channel partner type for pre-Tier 4 Final equipment excluded from Australian and Chilean emissions zones. Target electric compact excavator white space in Dutch and Belgian municipal contracting where diesel bans force rental fleet conversions ahead of German implementation timelines. Pursue attachment specialization strategies bypassing capital-intensive complete machine assembly.
For Investors and Strategic Acquirers: Roll-up economics work for regional hydraulic component distributors because OEM multi-sourcing mandates are fragmenting long-standing single-vendor procurement relationships. Five-to-ten year viability concentrates in service-integrated rental platforms capturing hourly-rate contracting growth in European urban construction. Monitor Stage V certification timeline compression as inflection indicator for distressed asset availability among compliance-lagged manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Hydraulic Procurement | Reduces allocation risk from German and Japanese precision component suppliers during demand surges. |
| Telematics Platform Standardization | Enables equipment-as-a-service contracting with Australian mining operators reducing aftermarket dependencies. |
| Electric Compact Product Line Expansion | Captures replacement demand from Berlin and Amsterdam diesel bans ahead of broader European adoption. |
| Used Equipment Export Channel Development | Monetizes pre-Tier 4 Final fleet retirements through Southeast Asian infrastructure project resale. |
| Autonomous Fleet Integration Partnership | Opens remote monitoring revenue streams with Western Australian iron ore pilot programs testing operator-free excavation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mining fleet managers, OEM procurement directors, hydraulic component suppliers, rental company operations heads, and aftermarket service technicians with secondary validation. Customs trade data, SEC filings from publicly traded construction equipment manufacturers, emissions compliance databases from EPA and EU member state authorities, and mining production statistics anchored volume estimates. Bottom-up equipment shipment tallies triangulated against top-down infrastructure investment flows.
Historical reference periods spanning pre-pandemic baselines through recent emissions rule implementation phases anchored the forecast window. Segmentation modeling captured product type, size tier, technology architecture, and end-use industry dimensions across the projection horizon. CAGRs derived from equipment replacement cycle analysis, regulatory deadline mapping, and hour-meter economics modeling. Mining production schedules in the Pilbara and Atacama regions, plus hydropower construction timelines in Sichuan and Yunnan provinces, fed demand-side inputs.
Revisions become necessary when regulatory enforcement timelines shift, battery energy density breakthroughs alter electric excavator duty-cycle viability, or autonomous technology pilots accelerate fleet ownership model transformation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Underground Mining Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Geology and Mine Planning Solution Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Mine Ventilation System Market