
 Rebar Cutter Market | 2026-2036
Rebar Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Rebar Cutter Market Analytics
ISO 9001 certification cycles is unwinding competitive density among rebar cutter manufacturers, forcing smaller fabricators to absorb compliance costs or exit tender pools. Makita Corporation leverages its cordless battery ecosystem to anchor premium positioning in electric cutter lines. Hilti Group sustains direct channel control through jobsite service fleets that reduce contractor downtime. Bosch Power Tools competes on modular platform compatibility across its power tool portfolio.
A rebar cutter is a mechanical or electro-hydraulic device engineered to sever steel reinforcing bars ranging from 4 mm to 40 mm diameter, employing hardened alloy blades rated for 1,200 MPa tensile strength material. Its primary industrial purpose is to deliver clean, cold cuts on construction sites without generating sparks that would violate hot-work restrictions. Hydraulic cutter units dominate rental fleet allocations due to superior force density for #11 bar and above, while electric cutter adoption accelerates among residential contractors seeking plug-and-play portability. Diamond coated blade technology commands the highest replacement part margins despite slower volume turnover. Infrastructure projects generate the most predictable demand cadence through multi-year government procurement schedules.
OSHA lockout/tagout rules and EPA particulate standards shape electric cutter design priorities in the United States, while CE marking under the EU Machinery Directive gates European market access for hydraulic units. India's BIS certification for construction equipment is tightening import pathways for Chinese-origin manual cutters. Stakeholders must monitor how battery platform standardization across tool OEMs will redistribute aftermarket blade and service revenue pools.
Market Dynamics
Battery platform standardization is compressing aftermarket revenue pools as tool OEMs lock contractors into proprietary blade ecosystems, while OSHA compliance tightening in commercial high-rise construction reshapes procurement specifications toward certified electric units.
Growth Catalysts
- OSHA Lockout/Tagout Mandates:United States commercial contractors face escalating jobsite safety audits, accelerating replacement of unguarded manual cutters with compliant electric platforms that integrate automatic blade braking.
- India Infrastructure Budget Expansion:Government procurement schedules for metro rail and highway projects generate multi-year demand visibility, with state public works departments specifying hydraulic cutter fleets for #11 bar applications.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements enable cordless cutters to sever 32 mm rebar on single charges, eroding the portability advantage that corded units held in remote construction zones.
Market Restraints
- Hardened Alloy Blade Supply Concentration:Japanese and German specialty steel mills control 1,200 MPa tensile-rated blade substrate, exposing cutter OEMs to nickel price volatility and extended lead times during alloy allocation periods.
- CE Marking Compliance Burden:EU Machinery Directive technical file requirements impose documentation costs that exclude smaller fabricators from tender pools for German and French infrastructure projects.
- Plasma Cutting Substitution:Fabrication shops with existing CNC plasma tables extend cutting capacity to rebar for precast concrete elements, compressing addressable market for standalone cutter units in stationary applications.
Strategic Opportunities
- Brazilian Residential Vertical Growth:Minha Casa Minha Vida housing program volumes create first-time demand among small contractors for portable electric cutters priced below hydraulic rental alternatives.
- Battery Platform Convergence:Cross-brand adapter systems that bridge Makita, DeWalt, and Milwaukee battery docks unlock aftermarket blade sales to mixed-fleet contractors seeking interoperability.
- India BIS Certification Pathway:Stricter import standards for Chinese-origin manual cutters create vacuum for domestic assemblers with certified electric product lines to capture price-sensitive tier-2 city demand.
Industry Challenges
- Electro-Hydraulic Technician Scarcity:Maintenance of combined battery-pump systems requires fluid power and electronics cross-training that vocational programs have not scaled to match fleet growth.
- ISO 9001 Certification Timeline Compression:Smaller fabricators face 12-18 month audit cycles to enter European tender pools, straining working capital before revenue recognition.
- Legacy Corded Fleet Stranding:Contractors with sunk investment in pneumatic infrastructure resist full electrification, forcing OEMs to maintain dual-platform SKUs that fragment production economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rebar Cutter Market |
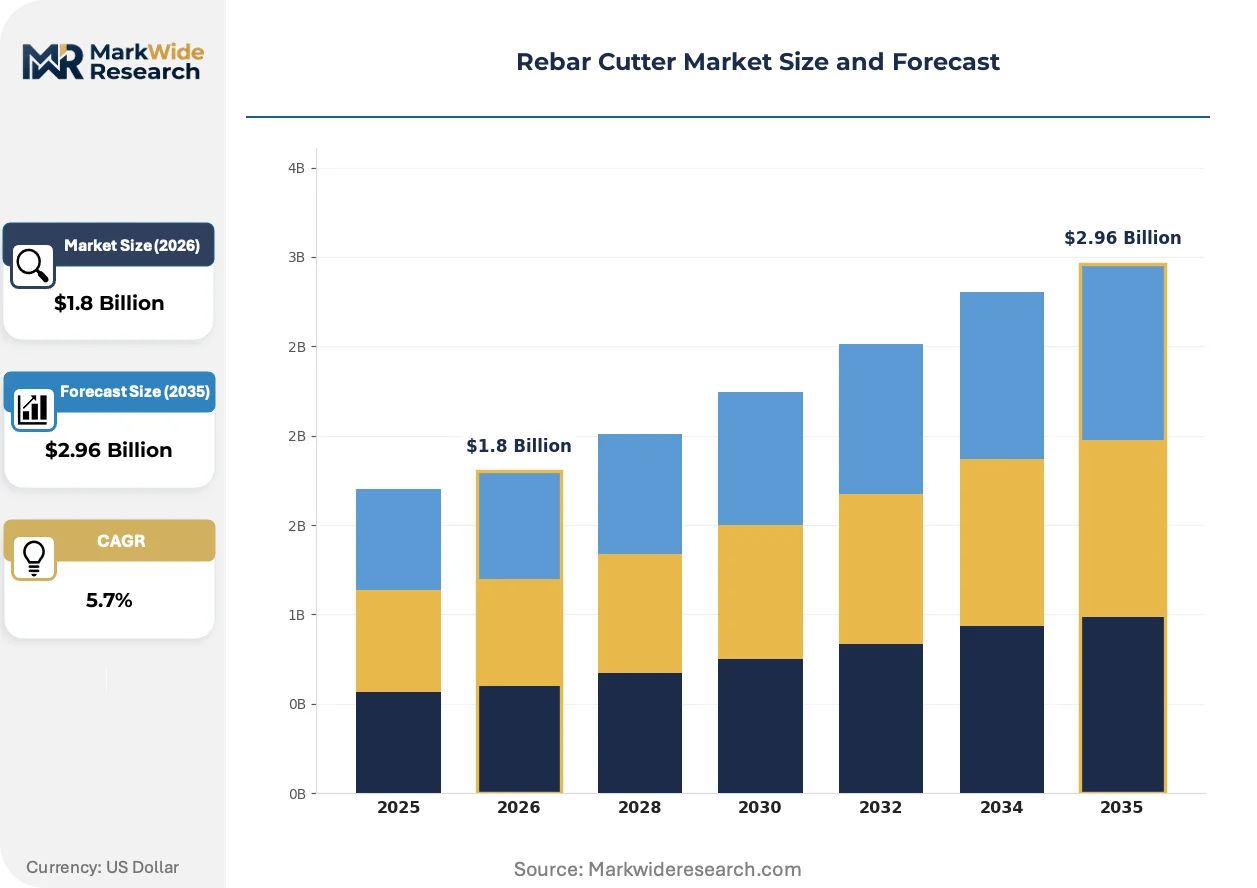
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Cutter, Electric Cutter, Manual Cutter, Pneumatic Cutter Technology: Cutting Blade, Cutting Wheel, High-Speed Steel, Diamond Coated End User: Construction Industry, Manufacturing Industry, Infrastructure Projects, Demolition Services Size: Small, Medium, Large, Extra Large |
| Companies Covered | Makita Corporation, Bosch Power Tools, Hilti Group, Stanley Black & Decker, BN Products, Happybuy, Anbull, VEVOR, HK Porter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rebar Cutter Market Evolving Landscape
Rebar cutter evolution centers on three vectors: powertrain electrification, safety system integration, and procurement model rationalization. Each trajectory carries distinct competitive implications for equipment manufacturers and rental fleet operators.
Brushless motor architecture is displacing brushed DC systems in mid-tier electric cutters by eliminating commutator maintenance intervals. Residential contractors in United States sunbelt markets adopt these units for slab-on-grade foundations where runtime demands are moderate. The shift compresses aftermarket service revenue that OEMs historically captured through armature replacement programs.
EPA particulate standards for construction equipment are tightening permissible emissions from gasoline-powered hydraulic power packs. Rental fleet operators in California and Texas face retrofit deadlines that favor full battery migration over catalytic converter upgrades. Compliance-driven replacement cycles concentrate in Q2-Q3 procurement windows tied to fiscal year capital releases.
Outcome-based blade subscription models are emerging among German commercial contractors who bundle cutting consumables with equipment leases. Hilti Group and Bosch Power Tools pilot per-cut pricing that transfers inventory risk from jobsite managers to OEM balance sheets. This restructuring is most visible in Munich and Frankfurt high-rise clusters where material tracking requirements favor predictable cost accounting over capital ownership.
Rebar Cutter Market Segmentation
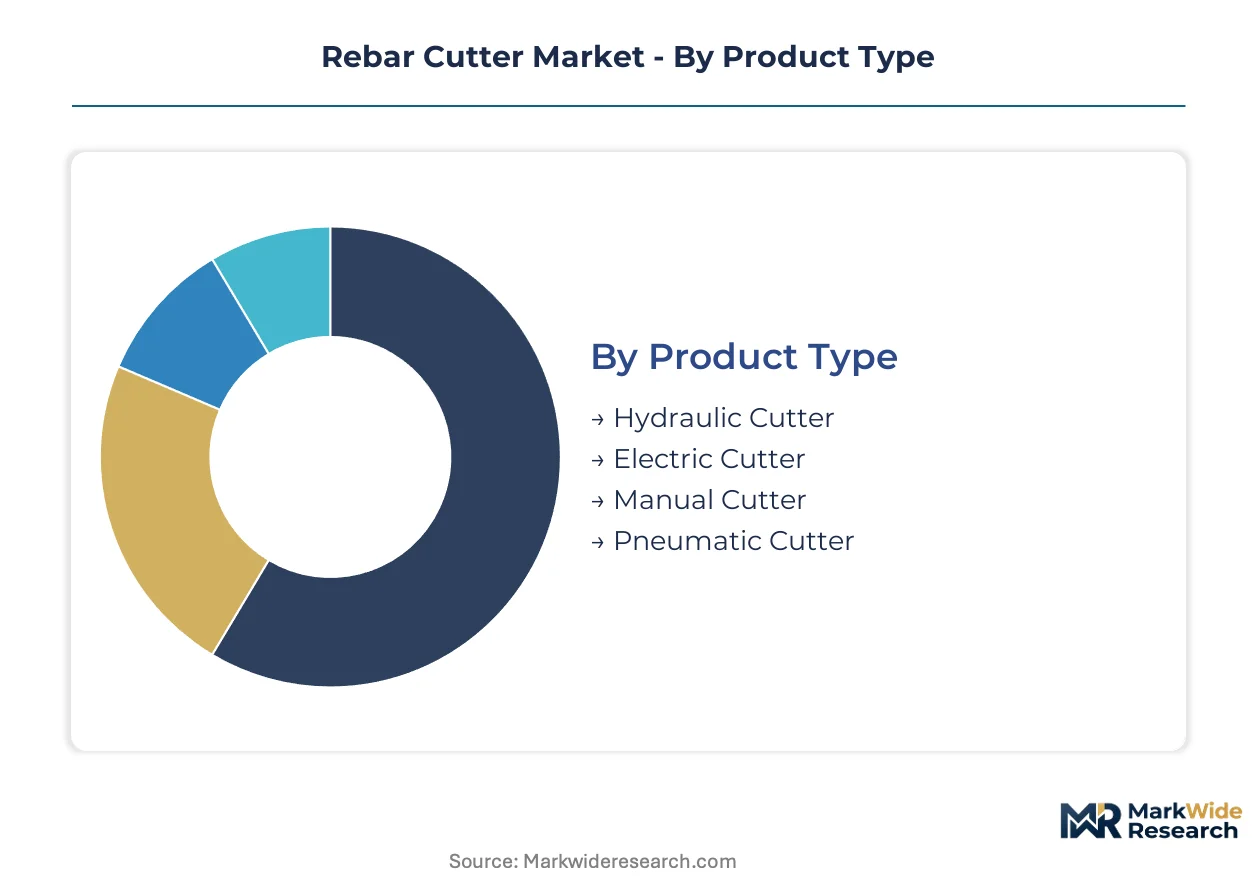
Rebar cutter procurement patterns diverge sharply across product architectures and end-use environments. Contractors match cutter specifications to bar diameter ranges, jobsite power availability, and OSHA compliance mandates governing spark-generating equipment.
Product Type:
Domestic assembly lines in India and Brazil feed price-sensitive manual and electric categories, while German and Japanese OEMs dominate hydraulic and pneumatic exports through certified distribution networks.
- Hydraulic Cutter:Electro-hydraulic systems generate force density exceeding 20 tons for #11 bar and above. Infrastructure contractors in India specify these units for metro rail and highway projects where government procurement schedules mandate fleet durability ratings.
- Electric Cutter:Cordless lithium-ion platforms sever 32 mm rebar on single charges, eliminating pneumatic hose infrastructure. United States residential contractors in sunbelt markets adopt brushless motor variants for slab-on-grade foundations where runtime demands remain moderate.
- Manual Cutter:Ratchet-action leverage mechanisms target small-diameter rebar in price-sensitive tier-2 Indian cities. BIS certification tightening on Chinese imports creates vacuum for domestic assemblers.
- Pneumatic Cutter:Compressed-air systems persist in legacy fleet installations where contractors resist full electrification. Dual-platform SKU maintenance fragments OEM production economies.
Hydraulic cutters command the established base. The steepest expansion runs through electric cordless platforms.
Technology:
Blade substrate sourcing concentrates in Japanese and German specialty steel mills, exposing cutter OEMs to nickel price volatility and extended alloy allocation lead times.
- Cutting Blade:Hardened alloy blades rated for 1,200 MPa tensile strength deliver cold cuts without spark generation. Replacement part margins peak in certified aftermarket channels serving OSHA-audit-facing contractors.
- Cutting Wheel:Rotary abrasive discs suit thin rebar sections in demolition services where cut precision matters less than speed. Dust generation triggers EPA particulate compliance burdens in California retrofit windows.
- High-Speed Steel:M2 and M4 grade substrates balance wear resistance against chipping in medium-duty construction applications. Heat treatment consistency determines batch-to-batch performance variance.
- Diamond Coated:Chemical vapor deposition layers extend blade life fivefold in reinforced concrete demolition. Highest replacement margins accompany slowest volume turnover in specialized rental fleets.
Cutting blades anchor current revenue pools. Diamond coated technology is climbing the fastest on infrastructure durability specifications.
End User:
Procurement authority splits between capital-owning contractors and rental fleet operators, with outcome-based subscription models emerging among German commercial high-rise clusters.
- Construction Industry:Commercial high-rise contractors face tightening OSHA lockout/tagout audits, accelerating replacement of unguarded manual units with electric platforms integrating automatic blade braking.
- Manufacturing Industry:Precast concrete element fabricators extend existing CNC plasma capacity to rebar cutting, compressing addressable market for standalone cutter units in stationary shop environments.
- Infrastructure Projects:Multi-year government procurement schedules generate predictable demand cadence. State public works departments in India specify hydraulic fleets for #11 bar applications in metro rail expansion.
- Demolition Services:Spark-free cold cutting mandates govern reinforced concrete dismantling in petrochemical and maritime decommissioning. Diamond coated blade rentals dominate this specification-heavy segment.
Construction industry volumes anchor the installed base. Infrastructure projects are gaining share fastest on budget visibility and fleet standardization.
Size:
Physical cutter dimensions correlate directly with bar diameter capacity and transport logistics, shaping rental versus purchase economics across contractor scale tiers.
- Small:Handheld units below 10 kg sever rebar up to 16 mm. Residential slab contractors in Brazil's Minha Casa Minha Vida program drive first-time demand for portable electric alternatives to hydraulic rental.
- Medium:Bench-mounted systems handle 20-32 mm bar in light commercial foundations. United States sunbelt markets show concentration here on brushless motor adoption.
- Large:Mobile cart units with electro-hydraulic pumps target 32-40 mm infrastructure-grade bar. Indian public works departments standardize fleet allocations at this capacity tier.
- Extra Large:Stationary shear systems process bundled rebar in precast manufacturing and bridge deck fabrication. Plasma cutting substitution pressures this segment in fabrication shop environments.
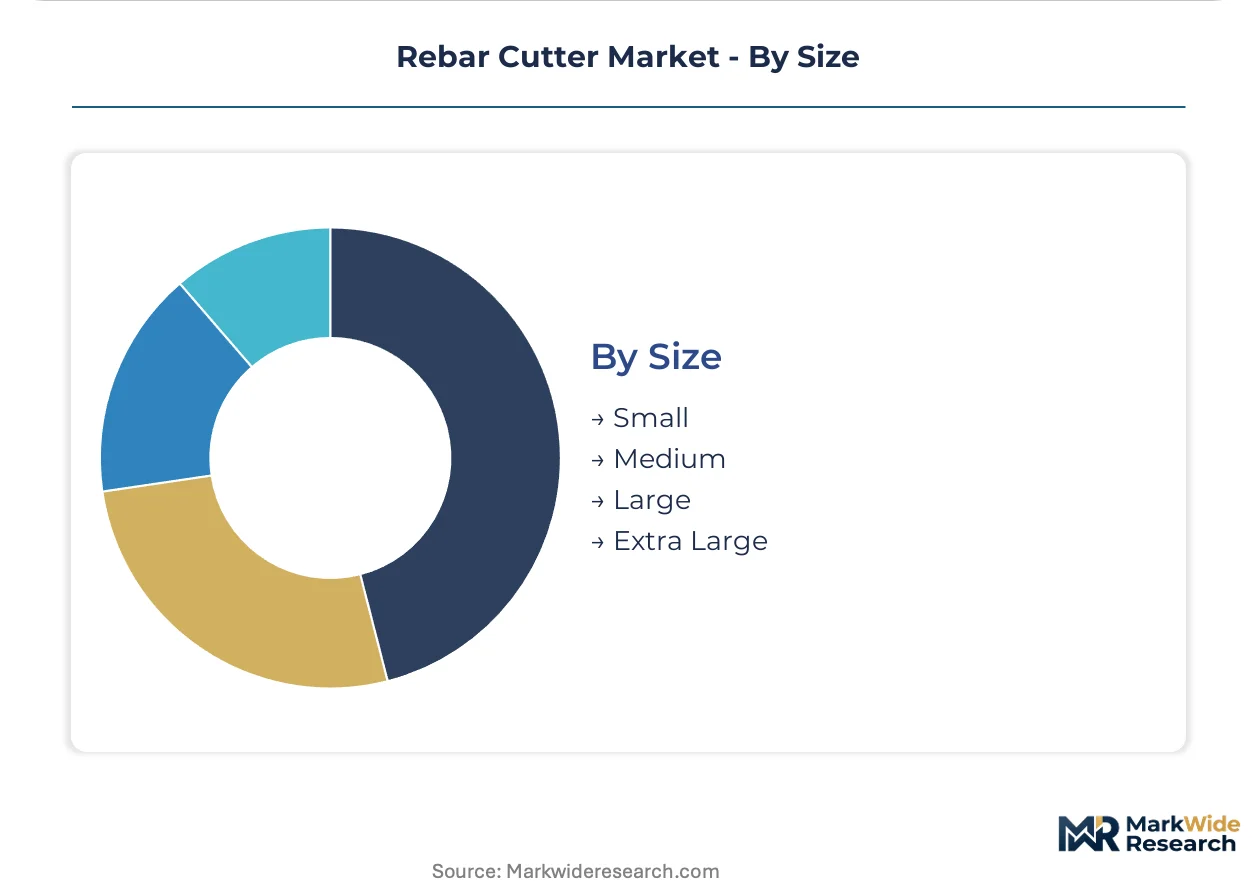
Medium cutters anchor contractor ownership models. Small portable units are expanding most quickly on battery platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure budget allocations and jobsite safety mandates are redirecting procurement flows across national construction markets, with government procurement schedules and certification requirements determining competitive access.
United States
Commercial high-rise contractors in New York and Chicago face intensifying OSHA lockout/tagout audits, accelerating fleet replacement toward electric platforms with automatic blade braking. EPA particulate standards tighten permissible emissions from gasoline-powered hydraulic packs, concentrating rental fleet upgrades in California and Texas during Q2-Q3 fiscal windows. Miami and Phoenix sunbelt markets show brushless motor adoption for slab-on-grade residential foundations.
Germany
CE marking under the EU Machinery Directive gates market access for hydraulic cutter imports, imposing documentation burdens that exclude smaller fabricators from Munich and Frankfurt infrastructure tenders. Outcome-based blade subscription models pilot among commercial contractors in these high-rise clusters, bundling consumables with equipment leases. Bavarian public works departments specify certified electric units for metro expansion projects.
India
State public works departments in Maharashtra and Karnataka generate multi-year demand visibility through metro rail and highway procurement schedules, standardizing hydraulic fleets for #11 bar applications. BIS certification tightening on Chinese-origin manual cutters creates vacuum for domestic assemblers in tier-2 cities like Pune and Ahmedabad. Battery platform adoption accelerates among residential contractors seeking alternatives to hydraulic rental.
Brazil
Minha Casa Minha Vida housing program volumes in São Paulo and Rio de Janeiro create first-time demand among small contractors for portable electric cutters priced below hydraulic rental alternatives. State-level infrastructure auctions for highway maintenance specify durable cutter allocations, favoring certified units with documented service networks. Domestic assembly lines feed price-sensitive manual and electric categories.
Japan
Specialty steel mills in Osaka and Nagoya control 1,200 MPa tensile-rated blade substrate, exposing cutter OEMs to nickel price volatility and extended alloy allocation lead times. METI industrial standards shape domestic procurement specifications for infrastructure-grade equipment. Tokyo and Yokohama commercial construction clusters prioritize OSHA-equivalent safety ratings on imported electric platforms.
Rebar Cutter Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel control dimensions, producing a tiered structure where scale-driven portfolios intersect with service-intensive positioning. Japanese and German publicly traded tool manufacturers anchor premium cordless ecosystems, while private fabricators in China and India compete on domestic assembly cost. Three archetypes dominate: battery platform integrators, direct-channel service operators, and price-focused volume assemblers. M&A activity concentrates on regional distributor networks, with technology licensing agreements bridging proprietary blade ecosystems.
Within the battery platform integrator tier, Makita Corporation and Bosch Power Tools exemplify ecosystem lock-in strategies that bundle cordless cutter lines with existing contractor fleet investments. Hilti Group occupies a distinct position as a direct-channel service operator, anchoring premium positioning through jobsite fleet maintenance capabilities. These three companies represent divergent competitive vectors—proprietary battery compatibility, modular cross-portfolio integration, and outcome-based subscription pricing—each capturing distinct contractor procurement preferences across commercial high-rise and infrastructure segments.
| Leading Market Players |
|---|
| Makita Corporation |
| Bosch Power Tools |
| Hilti Group |
| Stanley Black & Decker |
| BN Products |
| Happybuy |
| Anbull |
| VEVOR |
| HK Porter |
| Others |
Value Network & Pricing Analysis
OSHA lockout/tagout compliance gates both supplier qualification and price differentiation in the United States rebar cutter market, with certified electric platforms commanding premiums over unguarded manual alternatives while Japanese and German specialty steel mills constrain blade substrate availability. This regulatory-certification nexus compresses margins for non-compliant fabricators and redistributes pricing power toward OEMs with documented safety system integration.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with CE-marked hydraulic units and OSHA-compliant electric platforms separating from economy manual cutters on documented safety system integration. Three-tier pricing structure across premium, standard, and economy levels reflects blade substrate grade, battery platform compatibility, and after-sales service bundling. Cost compression in economy manual tiers intensifies because BIS certification tightening on Chinese imports forces price-sensitive Indian contractors toward domestic assemblers. Infrastructure contractors in India and Germany show lowest price sensitivity due to multi-year procurement schedules, while Brazilian residential contractors in the Minha Casa Minha Vida program exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Just-in-time blade replacement preferences dominate among United States commercial contractors facing OSHA audit timelines, while Indian infrastructure projects maintain strategic stockpiles of hardened alloy consumables tied to government procurement schedules. Supply concentrates in Japan and Germany for 1,200 MPa tensile-rated blade substrate, with domestic assembly lines in India and Brazil feeding price-sensitive electric and manual categories. Raw material dependencies center on nickel-alloy steel, lithium-ion cells, and hydraulic pump components. Single-source vulnerability in Japanese specialty steel mills exposes OEMs to extended alloy allocation lead times. Distribution runs through certified dealer networks in Germany and the United States, direct jobsite service fleets for premium OEMs, and open-market channels for price-tier imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among infrastructure procurement departments in India and Germany with multi-year fleet standardization mandates, fragmenting contractor-level purchasing authority and compressing vendor negotiation leverage for non-certified products.
For Market Incumbents: Shield premium positioning by deepening backward integration into blade substrate supply through captive relationships with Japanese specialty steel mills, countering nickel price volatility that erodes margin stability. Fortify channel control through expanded jobsite service fleet coverage in United States commercial high-rise clusters, reducing contractor downtime exposure that drives switching behavior. Certification investment in BIS-compliant electric platforms for tier-2 Indian cities captures vacuum from excluded Chinese manual imports. For New Entrants and Emerging Players: Aftermarket blade interoperability gaps where Makita, DeWalt, and Milwaukee battery ecosystems remain proprietary create entry points for cross-brand adapter systems. Target Brazilian residential contractors in São Paulo and Rio de Janeiro with portable electric units priced below hydraulic rental alternatives, leveraging domestic assembly cost advantages. Go-to-market through equipment leasing partnerships with regional construction cooperatives reduces capital barrier friction for first-time buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial tool parents with under-optimized rebar cutter portfolios lacking battery platform integration or direct service infrastructure. Long-term viability centers on OEMs capturing recurring blade subscription revenue rather than transactional equipment sales, with infrastructure project visibility providing cash flow predictability. Monitor battery platform standardization announcements across tool OEMs as inflection indicator for aftermarket revenue pool redistribution toward interoperable blade suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-brand adapter development unlocks blade sales to mixed-fleet contractors in United States sunbelt markets. |
| Backward Integration into Blade Substrate | Captive supply of 1,200 MPa hardened alloy reduces exposure to Japanese mill allocation cycles and nickel volatility. |
| Outcome-Based Subscription Launch | Per-cut pricing models transfer inventory risk from German commercial contractors to OEM balance sheets in Munich and Frankfurt. |
| BIS Certification Pathway Investment | Domestic Indian assemblers capture tier-2 city demand vacuum created by excluded Chinese manual cutter imports. |
| Jobsite Service Fleet Expansion | Direct channel control through maintenance capabilities reduces contractor downtime and anchors premium positioning against rental alternatives. |
Research Methodology
The analysis maps hydraulic, electric, manual, and pneumatic cutter sub-sectors, each validated through maintenance directors at commercial construction firms, procurement leads at Indian public works departments, aftermarket service heads at rental fleet operators, and plant engineers at precast concrete fabricators. Primary interview insights triangulate against customs and trade data for blade substrate flows, SEC filings for listed tool manufacturers, infrastructure procurement databases for government project schedules, and OSHA compliance audit records. Bottom-up unit economics and top-down market sizing reconcile through cross-validation against disclosed fleet allocations and replacement cycle patterns.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon, with modeled segmentation spanning product architecture, blade technology, end-user industry, and physical size tier. CAGRs derive from fitted growth curves calibrated to infrastructure budget trajectories, regulatory compliance deadlines, and battery energy density improvement curves. Industry-specific forecast inputs incorporate lithium-ion cell chemistry advancement rates and alloy steel price volatility bands.
Underlying assumptions cover infrastructure budget continuity, certification regime stability, and battery platform convergence pace, with deviation risk concentrated in nickel price spikes, trade restriction escalations, and plasma cutting substitution acceleration in fabrication shops. Revision becomes warranted when OSHA enforcement intensity or BIS certification timelines cross thresholds that alter replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mortiser Market
Tools
Impact Wrenches Market
Tools
Painting Tools Market
Tools
Rotary Hammer Drill Market
Tools
Tool Boxes Market
Tools
Aluminum Folding Ladders Market
Tools
Gouging Torch Market
Tools
Wood Floor Grinding Machine Market
Tools
Trim Press Market
Tools
Hand Saw Market
Tools
End Milling Machine Market
Tools
Total Station Market
Tools
Telescopic Tool Boxes Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Workholding Tools Market
Tools
Thread Milling Machine Market