
 Stone Mining and Quarrying Market | 2026-2036
Stone Mining and Quarrying Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Mining and Quarrying Market Outlook
Infrastructure end-use is rebalancing toward large-scale transportation and energy projects, pulling aggregate demand away from purely residential construction. Vulcan Materials Company dominates the southeastern United States through its dense network of quarries and distribution terminals. Martin Marietta anchors Texas and Carolinas markets with deep reserves of high-specification limestone. CRH Americas extends its position across the Great Lakes and Northeast through integrated aggregate-asphalt-concrete operations.
Stone mining and quarrying encompasses the extraction of solid rock formations including granite, limestone, marble, and sandstone through mechanical drilling, blasting, crushing, and screening to produce dimension stone or construction aggregate with specified gradation and compressive strength. Open pit extraction leads volume output due to lower stripping ratios and economies of scale in shallow deposits, while block caving captures margin in deep, homogeneous granite and marble formations where surface methods prove uneconomical. Infrastructure end-use commands the largest share of crushed stone consumption, driven by road base, rail ballast, and airport runway specifications, while landscaping applications show faster growth in premium dimension stone for urban hardscaping.
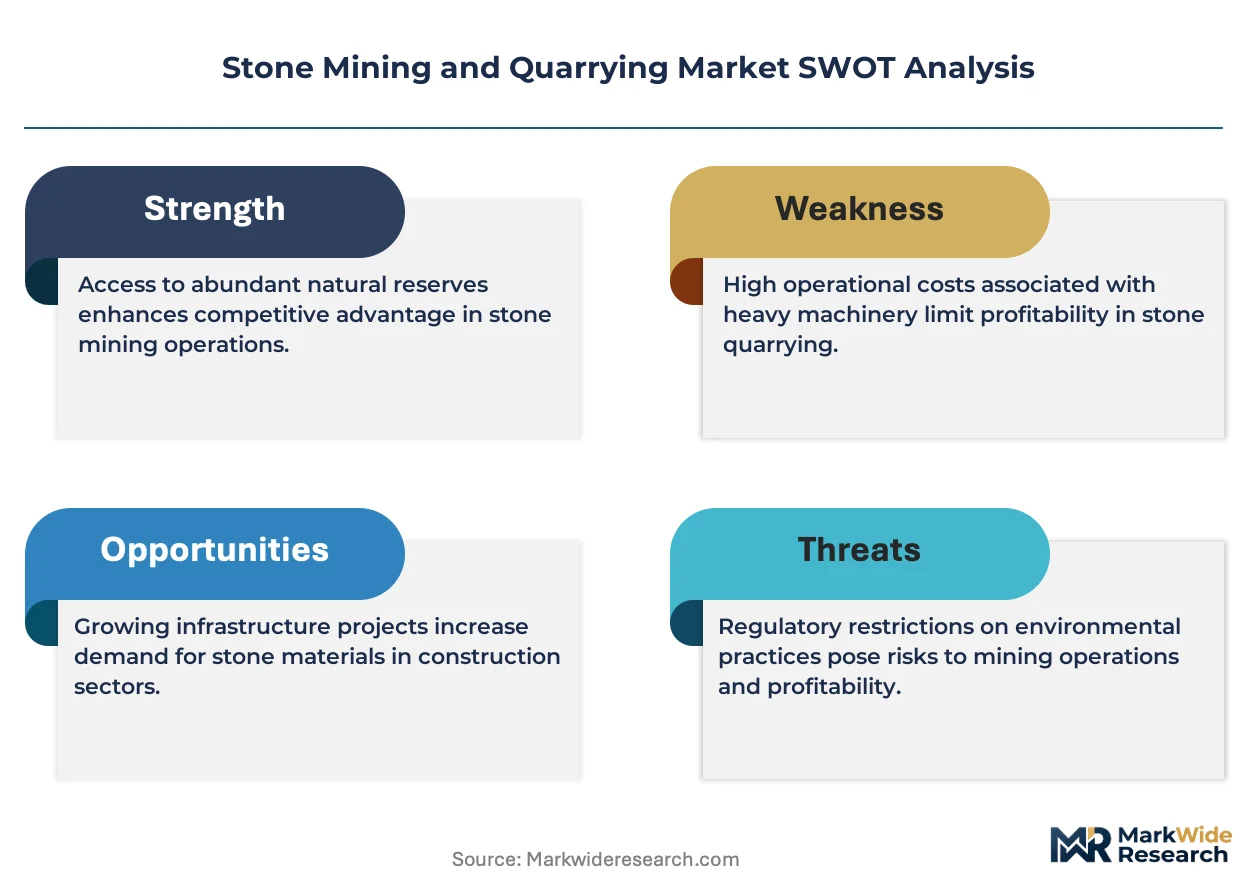
EPA enforces National Ambient Air Quality Standards at quarry sites, compelling operators to install particulate controls and water suppression systems that raise capital intensity but also consolidate production toward larger, compliant facilities. OSHA enforces permissible exposure limits for respirable crystalline silica, reshaping workplace practices and accelerating automation in cutting and crushing operations. State mining reclamation bonds and progressive closure requirements add further compliance layers that favor operators with long reserve horizons and integrated land restoration capabilities. Stakeholders must monitor evolving EPA enforcement patterns and state-level aggregate taxation proposals that could restructure competitive cost curves across regional markets.
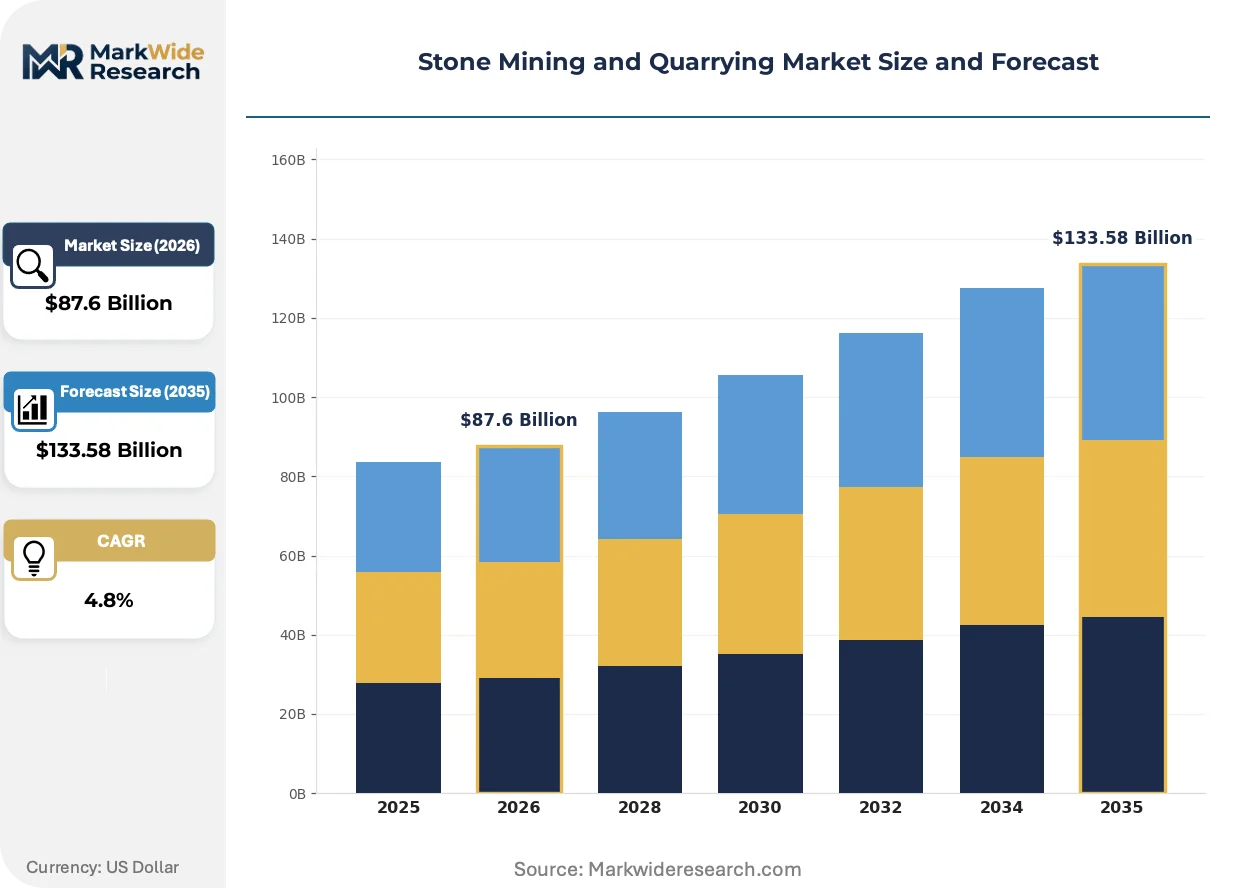
Market Dynamics
EPA quarry emissions guidelines and OSHA silica exposure limits are compressing operational margins while simultaneously consolidating production toward larger, compliant facilities with capital reserves for particulate controls and automation.
Growth Catalysts
- Federal infrastructure spending:Highway and transportation projects across the United States sustain aggregate consumption volumes. State-level road programs extend demand visibility for crushed stone suppliers.
- Urban hardscaping specification:Landscape architects specify premium dimension stone for public plazas and commercial developments. Municipal design standards increasingly favor natural stone over concrete alternatives.
- Mechanized block extraction:Diamond wire sawing and CNC profiling expand recoverable yields from deep granite formations. These technologies reduce labor intensity in dimension stone production.
Market Restraints
- Diesel fuel cost volatility:Haulage and mobile crushing operations remain exposed to petroleum price swings. Remote quarry locations amplify transportation energy costs.
- Permitting timeline extension:State mining reclamation bonds and progressive closure requirements stretch pre-production capital lockup periods. Greenfield site approval now spans multiple regulatory review cycles.
- Recycled concrete aggregate substitution:Demolition waste processing plants divert construction debris from virgin aggregate demand. Urban markets with established recycling infrastructure show compression in traditional quarry offtake.
Strategic Opportunities
- Carbon capture integration:Limestone quarries with adjacent geological formations can host direct air capture or mineralization projects. Federal tax credits under the Inflation Reduction Act incentivize this operational pivot.
- Integrated land restoration:Operators with long reserve horizons monetize post-extraction sites for solar development or water storage. Progressive rehabilitation creates asset value beyond mineral extraction.
- Drone-based inventory surveying:Unmanned aerial systems with photogrammetry reduce stockpile measurement costs. Mid-sized quarries gain access to precision volume tracking previously limited to major producers.
Industry Challenges
- Respirable crystalline silica compliance:OSHA permissible exposure limits demand upgraded ventilation and remote operation of cutting equipment. Workforce training and PPE protocols require ongoing investment.
- Legacy equipment retrofit complexity:Older crushing circuits lack the sensor infrastructure for real-time dust suppression activation. Capital allocation debates stall automation timelines at family-owned operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Mining and Quarrying Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $133.58 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite, Limestone, Marble, Sandstone Extraction Method: Open Pit, Underground, Sequential Extraction, Block Caving End User: Construction, Landscaping, Roadwork, Infrastructure Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | Lehigh Hanson, Carmeuse, Vulcan Materials Company, Tarmac, Cemex, Martin Marietta, Adbri Limited, Oldcastle, CRH Americas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Mining and Quarrying Market Strategic Shifts
Mechanization and environmental compliance technologies are restructuring cost curves across extraction, processing, and distribution. Operators face pressure to modernize while defending margin positions against input cost volatility.
Autonomous haul trucks with LiDAR collision avoidance are automating pit-to-crusher material movement. Large aggregate producers in the United States deploy these systems across extended shift schedules. The technology is automating labor scheduling while compressing incident-related downtime and insurance premiums.
EPA National Ambient Air Quality Standards enforcement is tightening particulate matter thresholds at quarry perimeters. Operators install continuous emissions monitoring and automated water suppression cannons. Crushed stone facilities in California and the Northeast face the most stringent compliance timelines and capital requirements.
Buyers increasingly specify certified sustainable sourcing for public infrastructure contracts. State departments of transportation embed recycled content and local procurement mandates into bid evaluations. This preference shift concentrates contract awards with quarries demonstrating chain-of-custody documentation and third-party environmental accreditation.
Stone Mining and Quarrying Market Segmentation
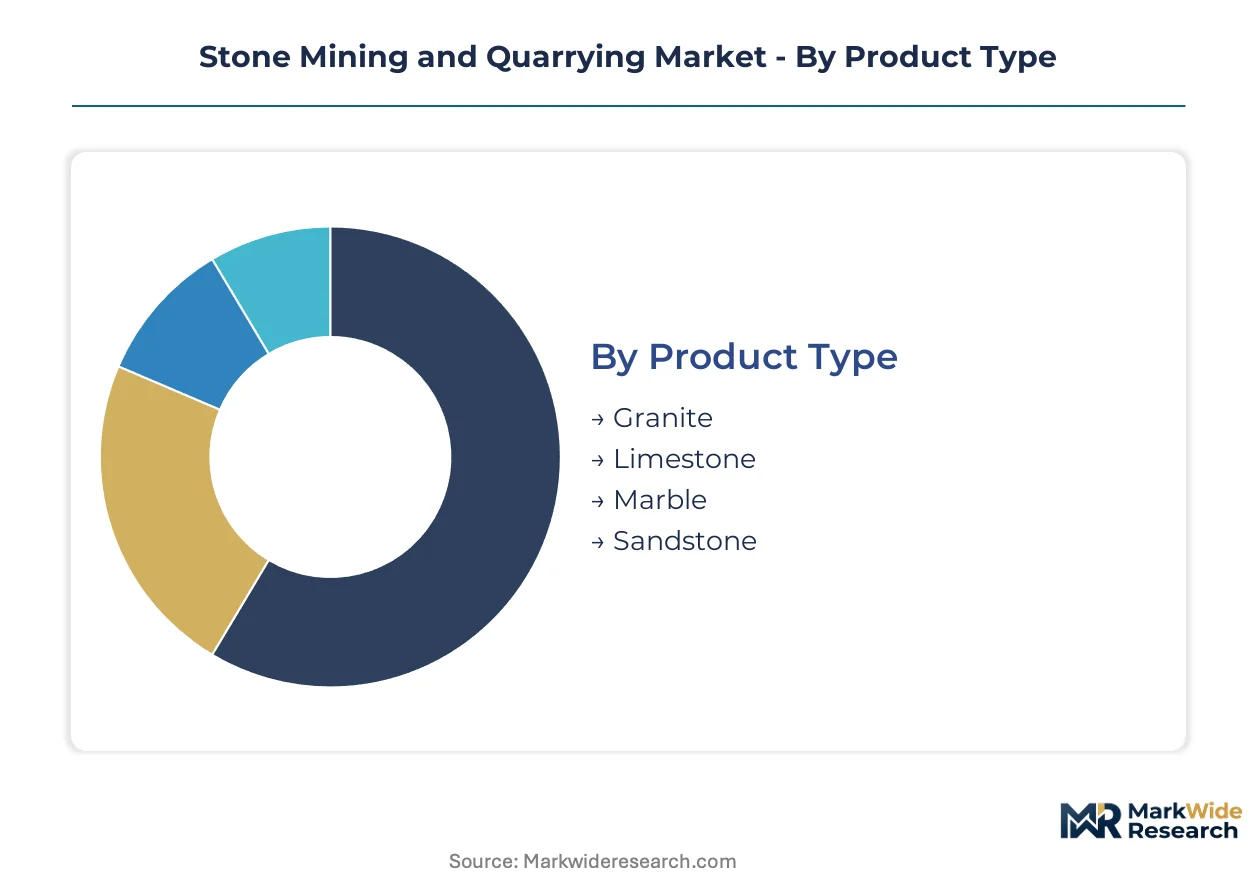
Stone mining and quarrying operators configure asset portfolios around reserve geology, extraction economics, and customer specification requirements. Segment boundaries determine capital deployment priorities and margin defense strategies across heterogeneous deposit types and end-use markets.
Product Type:
Capital intensity varies sharply across rock formations, with dimension stone requiring specialized cutting equipment and crushed aggregate demanding high-throughput crushing circuits.
- Granite:Igneous rock with high compressive strength serves structural and decorative applications. Dimension-grade blocks from Vermont and Georgia quarries supply memorial and building facade markets where ASTM specification compliance commands price premiums.
- Limestone:Sedimentary carbonate dominates construction aggregate volumes due to favorable crushability and cement compatibility. High-calcium deposits in the Midwest and South feed flue gas desulfurization and chemical manufacturing alongside road base applications.
- Marble:Metamorphic limestone valued for aesthetic veining requires diamond wire extraction and resin reinforcement. Italian and Greek import competition constrains domestic dimension stone pricing.
- Sandstone:Clastic sedimentary rock with natural bedding planes suits architectural cladding and landscaping. Permeability characteristics limit structural load-bearing specifications.
Most installed capacity flows through Limestone. Expansion is steepest in Granite as mechanized block extraction improves recoverable yields from deep formations.
Extraction Method:
Volume throughput and labor exposure differentiate operational approaches, with surface methods scaling efficiently and underground techniques accessing premium dimension stone reserves.
- Open Pit:Surface bench mining with drilling and blasting achieves lowest unit costs in shallow, horizontal deposits. Stripping ratios below 3:1 sustain margin in aggregate-focused operations across Texas and Florida limestone belts.
- Underground:Room-and-pillar extraction protects surface land use while accessing deep, homogeneous formations. Dimension stone producers in Vermont and Minnesota deploy this method to supply high-specification architectural markets.
- Sequential Extraction:Phased bench retreat maintains slope stability in complex geology. This approach extends reserve life in irregular deposits where simultaneous full-face mining risks wall failure.
- Block Caving:Gravity-induced fragmentation captures margin in massive, low-grade granite and marble formations. Capital requirements for shaft sinking and undercut levels limit deployment to long-reserve horizons.
Open Pit methods account for the majority of tonnage moved. Block Caving is gaining share fastest where surface permitting constraints intensify.
End User:
Customer specification rigor shapes quality premiums, with infrastructure contracts embedding certified sourcing requirements that filter supplier pools.
- Construction:Residential and commercial builders specify graded aggregate for concrete batching and structural fill. State highway departments increasingly mandate recycled content thresholds that compress virgin stone offtake in urban markets.
- Infrastructure:Federal transportation projects consume high-specification crushed stone for road base, rail ballast, and airport runway subgrade. Buy America provisions in surface transportation reauthorization bills concentrate awards with domestic quarries.
- Landscaping:Premium dimension stone for public plazas and commercial hardscaping commands price multiples over construction aggregate. Municipal design standards in California and Northeast metros favor natural stone over precast concrete alternatives.
- Roadwork:State maintenance programs sustain steady demand for dense-graded base course and surface treatment aggregate. Seasonal paving windows concentrate delivery schedules and strain logistics networks.
Infrastructure contracts absorb the largest volume share. Landscaping specifications are expanding most quickly as urban design priorities shift toward natural materials.
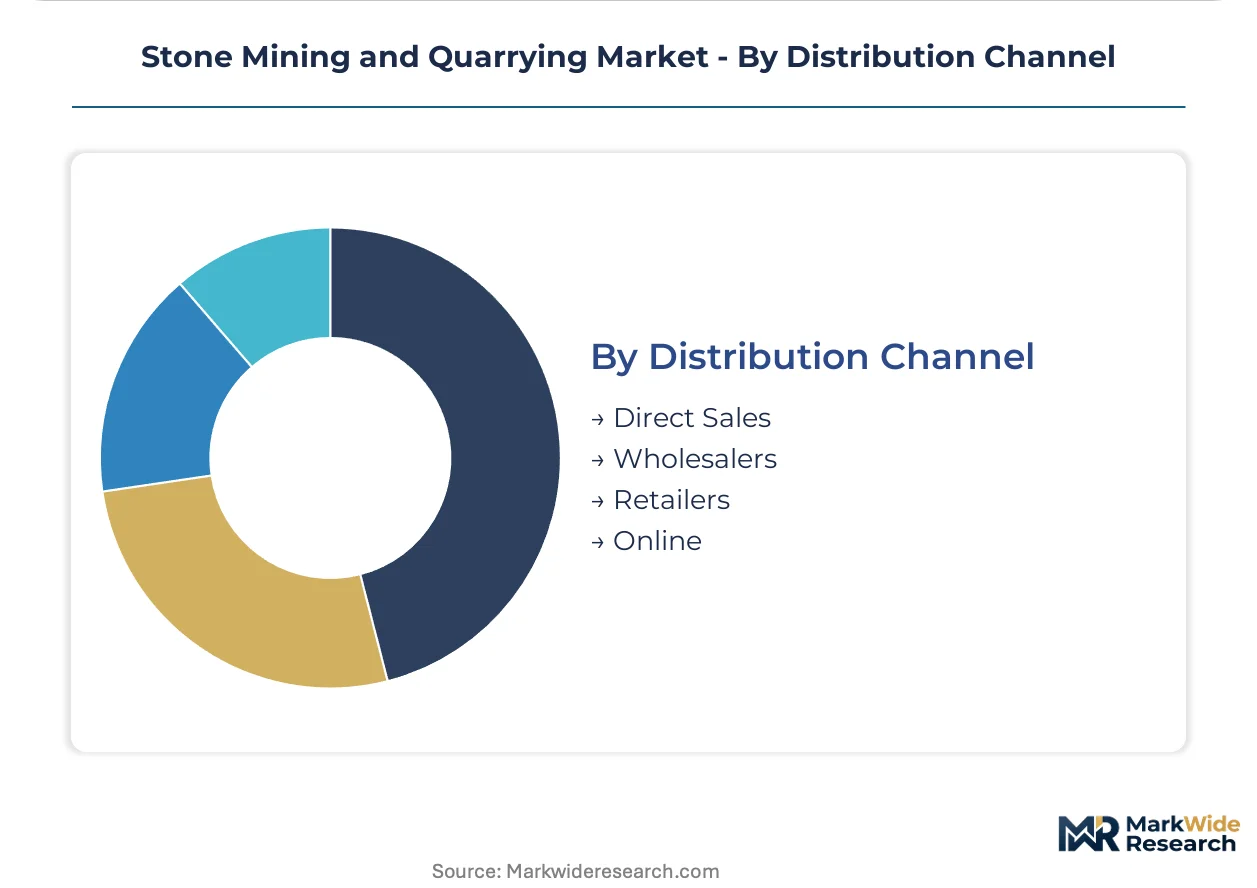
Distribution Channel:
Channel selection reflects shipment scale, specification complexity, and customer procurement sophistication across project-based and maintenance-driven demand.
- Direct Sales:Major producers contract directly with state DOTs and large general contractors for multi-year aggregate supply. These relationships bypass distributor margins but require dedicated logistics coordination and quality certification documentation.
- Wholesalers:Regional distributors aggregate volumes from multiple quarries to serve mid-sized construction firms. Inventory pooling reduces customer capital lockup but adds handling costs and specification variance risk.
- Retailers:Landscape supply yards and home improvement chains stock bagged decorative stone for residential consumers. Premium pricing offsets higher per-ton logistics costs in this fragmented segment.
- Online:Digital platforms facilitate sample ordering and specification comparison for dimension stone selection. Project-scale procurement remains offline due to freight economics and quality verification requirements.
Direct Sales channels move the greatest tonnage. Online penetration is climbing fastest in decorative stone specification and sample sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are reshaping production geography as operators seek jurisdictions with streamlined permitting and lower compliance burdens. Capital migrates toward regions with stable aggregate demand and predictable environmental enforcement timelines.
United States
Federal infrastructure appropriations and state highway rehabilitation programs sustain crushed stone consumption across the Southeast and Midwest. EPA National Ambient Air Quality Standards enforcement compels particulate control investments at surface quarries. Vulcan Materials Company anchors production density in Georgia and Alabama through integrated quarry-terminal networks serving Atlanta and Birmingham construction markets.
Germany
Rail modernization and commercial construction in North Rhine-Westphalia and Bavaria drive dimension stone and aggregate specification. ECHA REACH compliance and Bundesimmissionsschutzgesetz emissions controls elevate operational standards for surface extraction. The Sauerland and Bavarian Forest quarry clusters concentrate limestone and granite production for domestic infrastructure and export architectural markets.
China
Urban rail transit expansion and western region infrastructure development absorb massive aggregate volumes despite property sector headwinds. MEE ambient air quality regulations and provincial mining rehabilitation bonds tighten operational compliance in Yangtze River Delta extraction zones. Fujian and Shandong provinces host mechanized granite block production serving domestic hardscaping and international dimension stone export channels.
India
National highway development and smart city hardscaping programs escalate sandstone and granite demand across Rajasthan and Karnataka. BIS gradation standards and state mining department progressive closure requirements extend pre-production timelines for greenfield sites. The Makrana and Bangalore quarry belts concentrate dimension stone extraction for domestic construction and Middle East export specifications.
Brazil
Agricultural road paving and hydroelectric dam construction in Minas Gerais and São Paulo sustain aggregate consumption despite macroeconomic volatility. ANVISA industrial hygiene guidelines and state environmental licensing processes shape operational compliance costs. The Cachoeiro de Itapemirim cluster anchors granite block production for North American and European architectural specification markets.
Stone Mining and Quarrying Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding infrastructure contracts while regional wholesalers serve fragmented construction demand. The market structure concentrates around large reserve holders with captive logistics networks, though mid-sized operators persist in specialty dimension stone niches. Three archetypes dominate: vertically integrated aggregate-asphalt-concrete conglomerates, family-owned regional quarry operators, and international dimension stone exporters. Competitive dynamics center on reserve acquisition and permitting speed rather than price competition, with automation investments and land restoration capabilities serving as secondary differentiation vectors.
Among North American reserve-heavy operators, Vulcan Materials Company, Martin Marietta, and CRH Americas exemplify the integrated conglomerate archetype with multi-state quarry networks and dedicated distribution infrastructure. These entities occupy positions defined by long-horizon reserve bases and direct state department of transportation contracting relationships rather than transactional wholesale channels. Their scale permits sustained capital deployment into emissions compliance and autonomous haulage systems that smaller operators cannot replicate.
| Leading Market Players |
|---|
| Lehigh Hanson |
| Carmeuse |
| Vulcan Materials Company |
| Tarmac |
| Cemex |
| Martin Marietta |
| Adbri Limited |
| Oldcastle |
| CRH Americas |
| Others |
Value Chain & Pricing Dynamics
Diamond wire sawing and CNC profiling adoption simultaneously compresses dimension stone production costs and consolidates output toward capital-rich operators in Vermont and Georgia. This mechanization shift redraws competitive boundaries between automated block extraction facilities and labor-dependent quarries.
Pricing Analysis
Distributor margins in wholesale channels absorb 12-18% of ex-quarry value before reaching mid-sized construction firms. Three-tier pricing structure across premium dimension stone, standard construction aggregate, and economy road base materials stratifies the market. Cost compression in economy grades intensifies as recycled concrete aggregate substitution expands in urban markets. State DOTs exhibit lowest price sensitivity due to specification rigor and Buy America mandates, while residential landscaping buyers drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and Georgia form hub-and-spoke networks radiating from Vulcan Materials and Martin Marietta quarry clusters. Supply concentrates in the United States, China, and India, with Brazil anchoring export-oriented dimension stone block production. Diesel fuel, ammonium nitrate explosives, and diamond wire consumables constitute critical input dependencies. Single-source vulnerability runs through specialized cutting equipment OEMs in Italy and Germany. Distribution runs through direct sales to infrastructure contractors, bypassing wholesale layers for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stone mining and quarrying functions as a stable compounder anchored by federal infrastructure appropriations that sustain aggregate consumption regardless of residential construction cyclicality.
For Market Incumbents: Acquire permitted limestone reserves in the Southeast and Texas to extend reserve horizons beyond 30 years. Consolidate family-owned quarries facing OSHA silica compliance retrofit burdens. Recycled concrete aggregate substitution in urban markets threatens virgin aggregate offtake; backward integration into demolition waste processing defends volume positions. Automation investment in autonomous haul trucks compresses labor exposure and insurance premiums simultaneously. For New Entrants and Emerging Players: Digital platforms for dimension stone specification and sample sourcing open white-space penetration in architectural procurement workflows. Target premium landscaping stone in California and Northeast metros where municipal design standards favor natural materials over precast alternatives. Drone-based inventory surveying services offer low-capital entry into mid-sized quarry technology upgrading without reserve ownership requirements. For Investors and Strategic Acquirers: Roll-up economics work for regional limestone aggregate operators because EPA emissions compliance capital requirements favor scaled particulate control investments. Five-to-ten year viability hinges on reserve life extension and permitting pipeline depth rather than near-term pricing cyclicality. Monitor state-level aggregate taxation proposals as inflection signals for regional cost curve restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Reserve Acquisition | Permitted limestone deposits in Texas and Georgia anchor multi-decade production visibility against permitting timeline extensions. |
| Automation Deployment | Autonomous haul trucks with LiDAR collision avoidance compress incident-related downtime at Vulcan Materials pit operations. |
| Carbon Capture Integration | Limestone quarries with adjacent geological formations host direct air capture projects qualifying for Inflation Reduction Act tax credits. |
| Land Restoration Monetization | Post-extraction sites convert to solar development or water storage assets creating value beyond mineral extraction horizons. |
| Certified Sourcing Documentation | Chain-of-custody accreditation satisfies state DOT bid evaluations embedding recycled content and local procurement mandates. |
Study Parameters
Multiple input streams — quarry operations executives, state DOT procurement officers, equipment manufacturer technical directors, and environmental compliance consultants — were reconciled against trade association production surveys and EPA emissions enforcement records. Secondary validation drew from USGS mineral commodity summaries, state mining department permit databases, and OSHA silica exposure enforcement patterns. Bottom-up reserve-to-production modeling and top-down infrastructure spending correlation anchored volume estimates across the analysis window.
Historical production trajectories were cross-referenced against expert panel inputs on mechanization adoption timelines and regulatory compliance cost curves. Segmentation modeling spanned product type, extraction method, end-user specification tier, and distribution channel complexity. CAGRs were derived from elasticity-adjusted demand functions tied to federal highway appropriation schedules and state-level road program visibility. Forecast inputs incorporated diesel fuel price volatility assumptions and recycled aggregate substitution penetration rates in urban markets.
The model assumes a particular technology adoption path for autonomous haulage and diamond wire extraction; alternative pathways for electrified pit equipment or alternative dimension stone cutting methods would alter the outlook. Forecasts reflect documented assumptions regarding infrastructure spending continuity and EPA enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Collectors Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Drill Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
DTH Drill Market