
 Dewatering Aids for Mining Market | 2026-2036
Dewatering Aids for Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Dewatering Aids for Mining Market Outlook
Multi-source procurement of specialty chemistries is restructuring how mining operators secure dewatering aids across dispersed extraction sites. Kemira Oyj leverages its Nordic manufacturing base to supply tailored flocculant programs for Scandinavian iron ore complexes. BASF SE anchors its position through backward integration into acrylamide monomer production, ensuring feedstock security for polymer output. Solvay SA competes via specialized surfactant formulations engineered for high-salinity process water common in Chilean copper operations.
Dewatering aids comprise synthetic and natural polymers, inorganic coagulants, and surface-active agents engineered to accelerate solid-liquid separation in mineral slurries, typically achieving cake moisture reductions of 5-15 percentage points versus untreated tailings. Their primary industrial purpose centers on enabling water recycling, reducing tailings dam volumes, and ensuring regulatory-compliant effluent discharge from mineral processing circuits. Flocculants command the largest product category share due to universal applicability across sulfide and oxide ore types, while centrifugation technology represents the fastest-growing deployment mode as operators retrofit legacy gravity thickeners with high-G force separators. Coagulants concentrate margin pools in jurisdictions with stringent turbidity limits, where dual-chemical programs command pricing premiums over single-polymer treatment.
EPA effluent guidelines in the United States, the EU Mining Waste Directive enforced by national environmental agencies, and Environment and Climate Change Canada's Metal Mining Effluent Regulations collectively mandate progressive water quality thresholds that expand addressable demand for advanced dewatering chemistries. These frameworks penalize exceedance of suspended solids and heavy metals limits, directly linking compliance costs to reagent performance specifications. Stakeholders must monitor evolving tailings storage facility safety standards and their ripple effects on dewatering intensity requirements at existing operations.
Market Dynamics
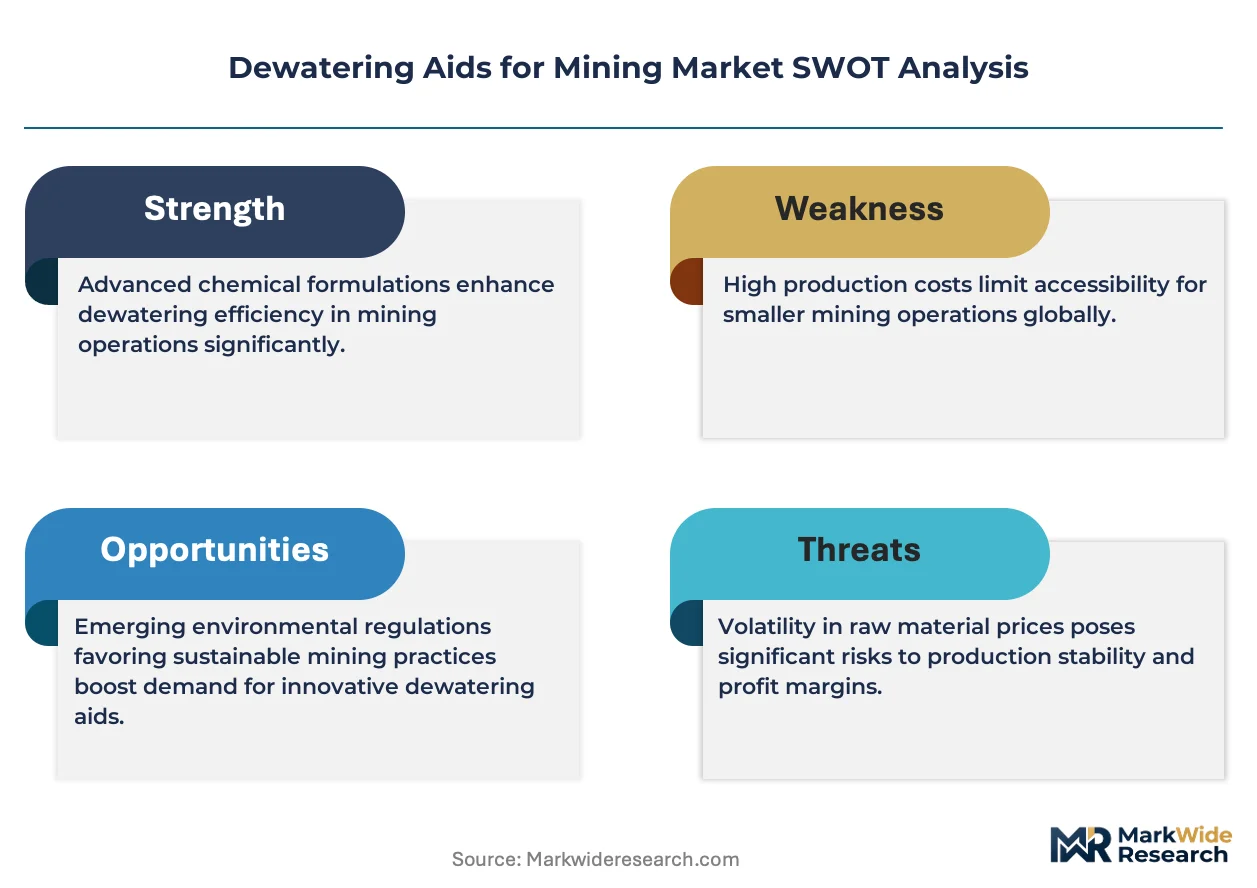
Stringent tailings containment regulations across copper and iron ore jurisdictions are forcing operators to upgrade from gravity thickeners to high-performance dewatering chemistries, compressing equipment replacement cycles and expanding reagent intensity per ton processed.
Growth Catalysts
- EU Mining Waste Directive:National environmental agencies in EU member states enforce progressive suspended solids thresholds, mandating dual-chemical flocculant programs at sulfide ore operations.
- Centrifugation retrofit wave:Copper producers in Chile's Atacama belt replace legacy thickeners with high-G force separators, doubling polymer consumption per treated cubic meter.
- Pilbara iron ore expansion:Western Australian operators scale procurement of tailored anionic flocculants to process increasing volumes of below-water-table ore.
Market Restraints
- Acrylamide monomer volatility:Polyacrylamide feedstock costs fluctuate with oil-derived propylene supply, squeezing margin stability for polymer blenders.
- High-salinity formulation barriers:Chilean copper operators require specialized surfactant chemistries that narrow qualified supplier pools and extend qualification timelines.
- Natural polymer substitution:Starch-based alternatives from agricultural processors compete in jurisdictions with relaxed turbidity standards, capping pricing power for synthetic suppliers.
Strategic Opportunities
- Canada oil sands dewatering:Bitumen tailings ponds in Alberta face mandated reclamation deadlines, opening demand for high-molecular-weight flocculants in froth treatment circuits.
- Digital dosing integration:Convergence of inline turbidity sensors with automated polymer injection systems enables real-time optimization and premium service contracts.
- EU Green Deal tailings funding:Circular economy grants for water recovery infrastructure subsidize advanced dewatering installations at Eastern European base metal mines.
Industry Challenges
- Process chemist scarcity:Mining operators struggle to recruit specialists capable of calibrating dual-chemical programs across variable ore mineralogy.
- Legacy thickener integration:Retrofitting centrifuges into existing tailings circuits requires custom concrete foundations and extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dewatering Aids for Mining Market |
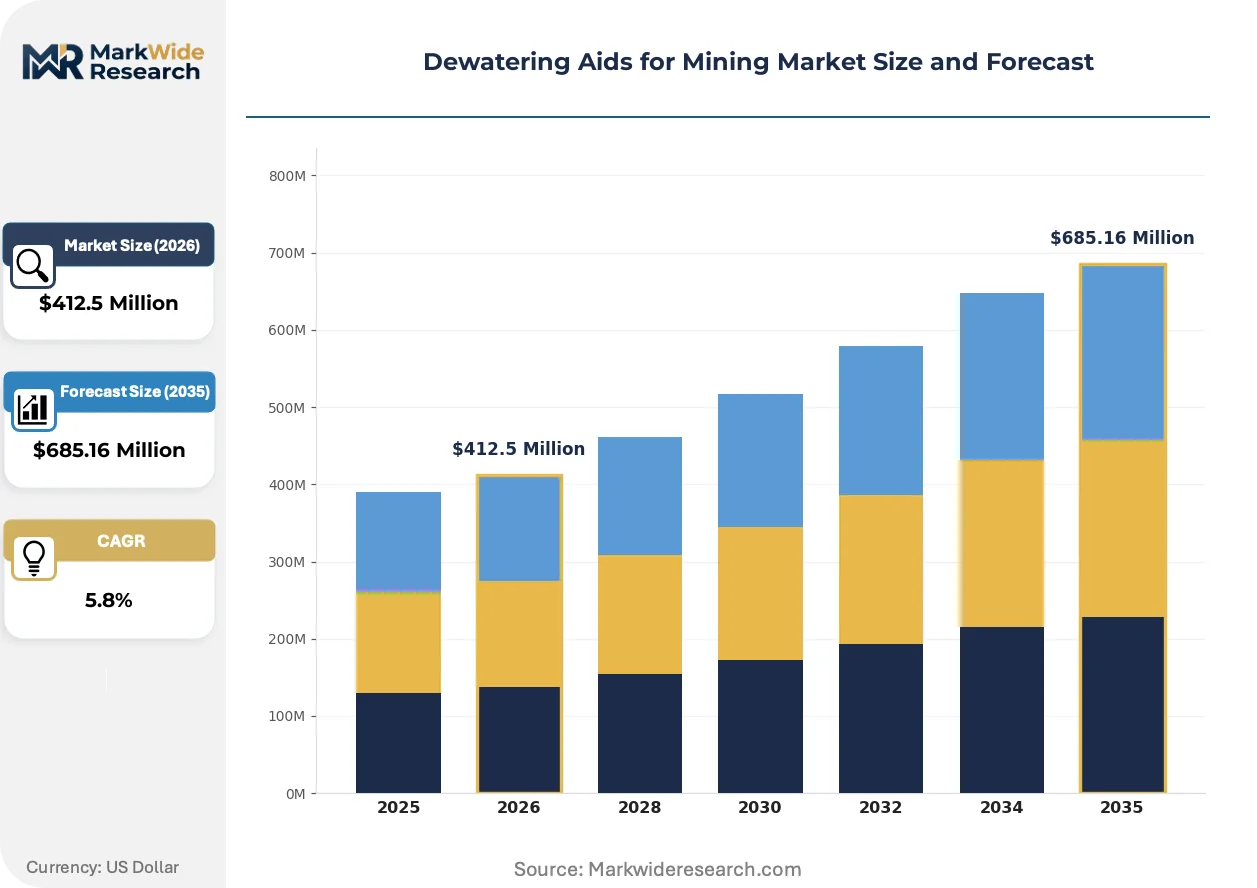
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Polymers, Surfactants Application: Tailings Management, Ore Processing, Water Recovery, Sludge Treatment End User: Mining Operations, Mineral Processing Plants, Environmental Services, Wastewater Treatment Facilities Technology: Centrifugation, Filtration, Vacuum Dewatering, Gravity Separation |
| Companies Covered | Kemira Oyj, Clariant AG, BASF SE, Solvay SA, Ashland Global Holdings Inc., Solenis LLC, SNF Floerger, Nouryon Chemical B.V., Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dewatering Aids for Mining Market Strategic Shifts
Active developments across polymer chemistry, regulatory enforcement, and procurement models are compressing supplier qualification timelines while expanding performance guarantees demanded by mining operators.
Next-generation hybrid flocculant-coagulant chemistries is rewriting solid-liquid separation economics at high-clay ore bodies. Copper-gold producers in Peru's Andean districts pilot these formulations to reduce cake moisture below transportable thresholds. The technology is compressing capital requirements for new tailings facilities by enabling dry-stack alternatives to conventional impoundments.
Environment and Climate Change Canada's Metal Mining Effluent Regulations tighten monthly average limits for total suspended solids and ammonia. Base metal operators in British Columbia and Quebec expand on-site analytical laboratories to demonstrate continuous compliance. The regulations are accelerating demand for automated sampling systems tied to polymer dosing controls.
Site-level chemical management contracts are displacing traditional spot purchasing for bulk flocculants. Major copper concentrators in Chile now procure through multi-year performance agreements with guaranteed moisture reduction targets. This model concentrates volume with integrated suppliers capable of field technical service deployment.
Dewatering Aids for Mining Market Segmentation
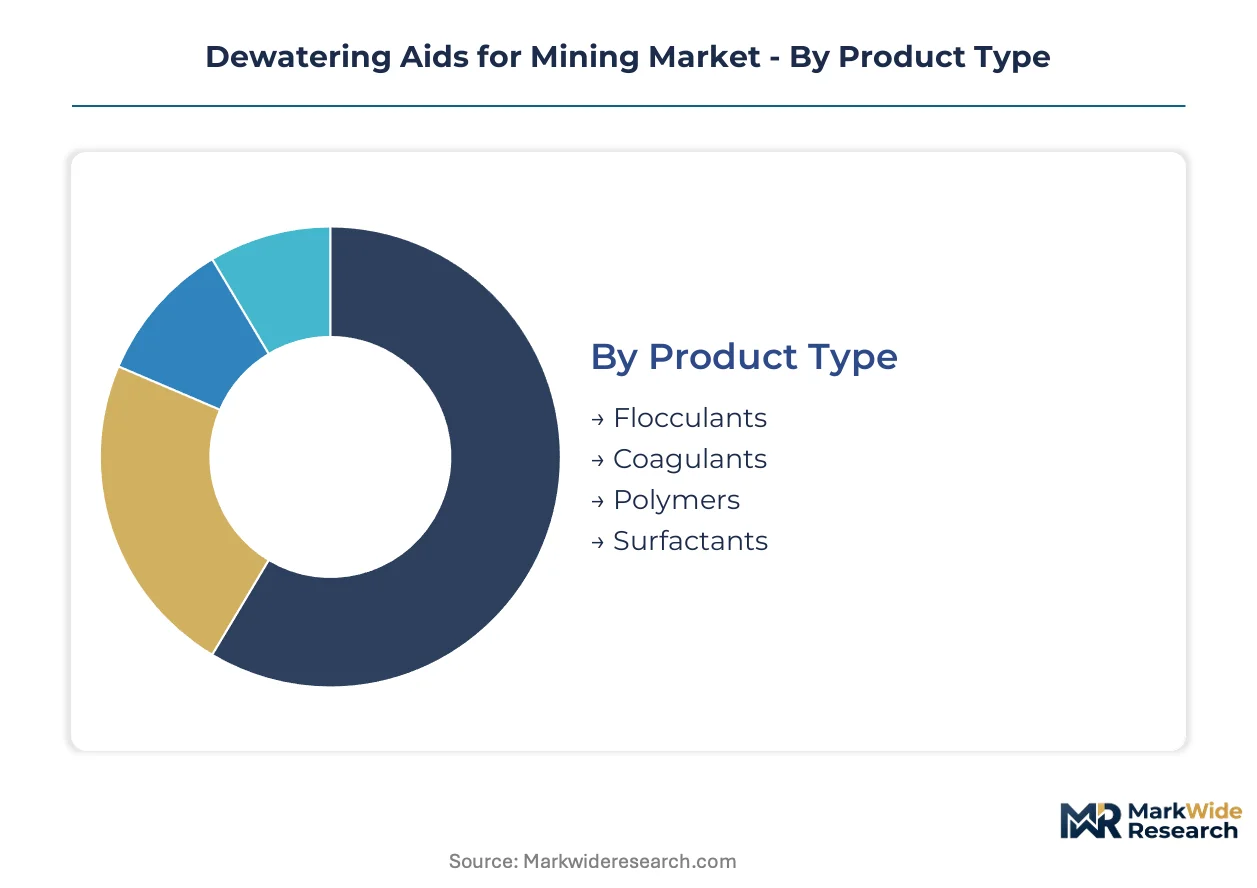
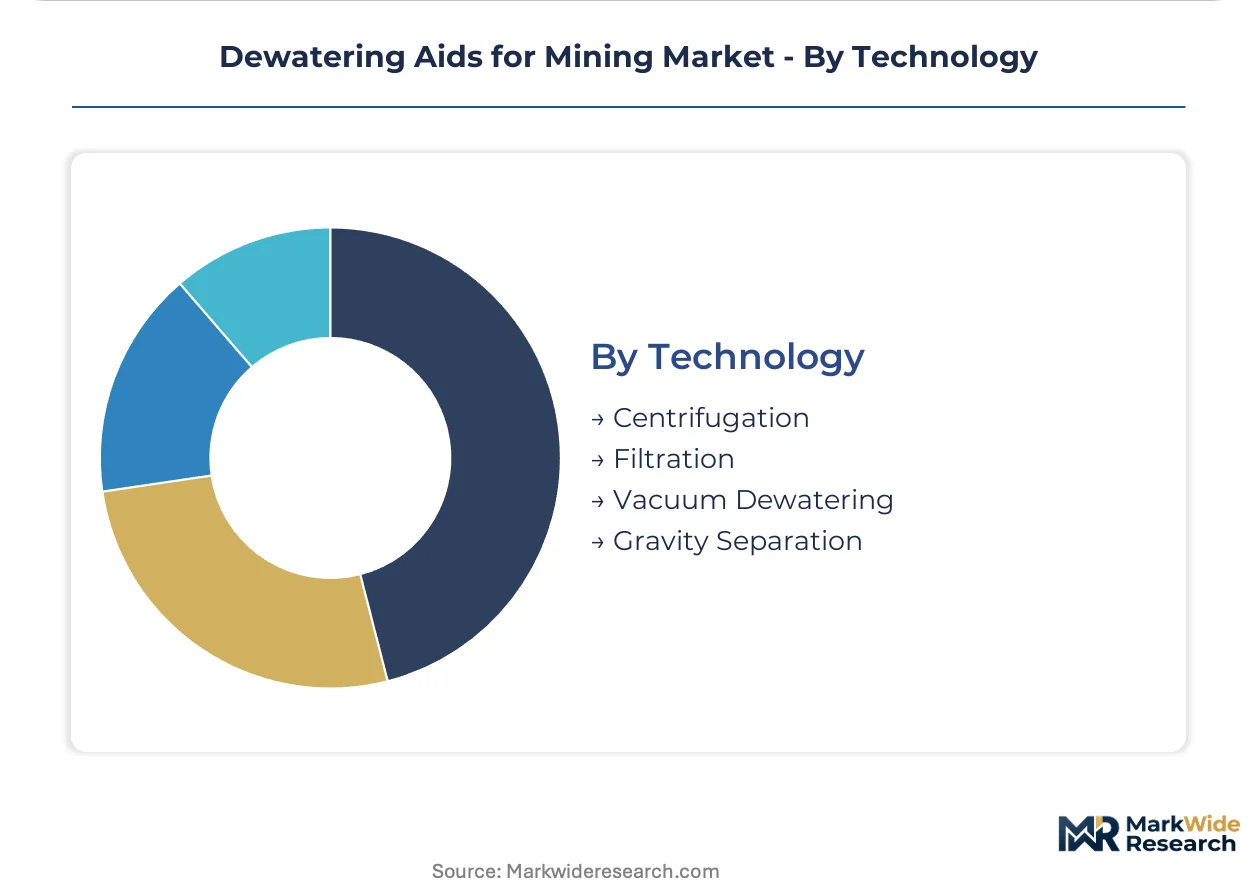
Dewatering aid procurement patterns diverge sharply across product chemistries and deployment technologies, with upgrade cycles compressing as operators retrofit legacy circuits to meet tightening effluent mandates. Segment-specific qualification requirements create distinct margin pools that reward technical service depth over commodity supply.
Product Type:
Equipment replacement cycles are shortening as copper and iron ore operators abandon single-chemistry programs for dual-reagent systems that extract more water from finer tailings fractions.
- Flocculants:High-molecular-weight polyacrylamide chains aggregate suspended solids into rapid-settling flocs, with anionic variants dominating Pilbara iron ore thickener circuits where below-water-table ore volumes are expanding. Western Australian procurement offices now specify tailored charge density profiles to match variable ore mineralogy.
- Coagulants:Inorganic salts and low-molecular-weight polymers neutralize surface charges on colloidal particles, commanding pricing premiums in Canadian jurisdictions where Environment and Climate Change Canada's Metal Mining Effluent Regulations enforce stringent turbidity limits. British Columbia base metal operators deploy dual-chemical programs combining coagulants with flocculants.
- Polymers:Synthetic and natural polymer backbones provide structural integrity to settled solids, with starch-based alternatives competing in relaxed-regulation markets.
- Surfactants:Surface-active agents reduce interfacial tension in high-salinity process water, essential for Chilean copper belt operations.
Flocculants sit at the top of the volume ranking, with surfactants climbing the fastest as high-salinity deposits expand.
Application:
Cost tier differentiation separates premium chemistries for new-build dry-stack facilities from standard reagents for legacy dam maintenance.
- Tailings Management:Dewatering chemistries enable dry-stack alternatives to conventional impoundments, with Peru's Andean copper-gold districts piloting hybrid flocculant-coagulant formulations to achieve transportable cake moisture. The technology compresses capital requirements for new tailings facilities.
- Ore Processing:Solid-liquid separation circuits in concentrators demand precise polymer dosing to maximize metal recovery while minimizing water carryover to downstream flotation stages.
- Water Recovery:Closed-loop process water systems in arid jurisdictions depend on high-performance dewatering to maintain circuit water balances.
- Sludge Treatment:Final dewatering of treatment plant residuals requires specialized conditioning chemistries.
Tailings management captures the largest application spend, while water recovery gains share fastest in water-stressed mining districts.
End User:
Customer type determines procurement contract structure, with multi-year performance agreements displacing spot purchasing among major concentrator operators.
- Mining Operations:Integrated miners with captive processing infrastructure specify reagent performance guarantees tied to moisture reduction targets, with Chilean copper concentrators leading the shift to site-level chemical management contracts.
- Mineral Processing Plants:Independent concentrators serving multiple mine feeds require flexible polymer programs adaptable to variable ore blends.
- Environmental Services:Third-party tailings remediation contractors procure dewatering aids for legacy pond reclamation projects.
- Wastewater Treatment Facilities:Municipal and industrial treatment plants adjacent to mining districts handle mine-influenced effluent.
Mining operations dominate end-user demand, with environmental services expanding most quickly as reclamation deadlines approach.
Technology:
Volume deployment concentrates in mature thickener circuits, while margins concentrate in high-G force separation retrofits requiring specialized polymer formulations.
- Centrifugation:High-G force separators double polymer consumption per treated cubic meter versus gravity thickeners, with Chile's Atacama belt operators retrofitting legacy circuits to meet stricter containment rules. The technology demands tailored flocculant rheology to withstand shear forces.
- Filtration:Pressure and vacuum filtration systems achieve lowest cake moisture for dry-stack tailings applications.
- Vacuum Dewatering:Reduced-pressure systems handle coarse, free-draining solids in specific ore types.
- Gravity Separation:Conventional thickener circuits remain prevalent but face replacement pressure from regulatory tightening.
Gravity separation retains installed base leadership, with centrifugation posting the steepest expansion trajectory as retrofit investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama copper belt concentrates procurement of high-performance flocculants as operators retrofit legacy thickeners with centrifugation systems. Regulatory tightening across copper and iron ore jurisdictions is restructuring regional demand patterns for dewatering chemistries.
Chile
Copper concentrators in the Atacama Desert deploy specialized surfactant formulations to handle high-salinity process water from deeper ore bodies. The country's environmental regulator enforces progressive tailings containment standards that mandate dual-chemical treatment programs. Antofagasta and Calama processing clusters anchor procurement of tailored anionic flocculants for below-water-table extraction.
Australia
Western Australia's Pilbara iron ore operators scale procurement of charge-density-optimized polymers to process expanding below-water-table volumes. The Western Australian Department of Water and Environmental Regulation administers strict effluent discharge limits for suspended solids. Perth-based procurement offices coordinate multi-year chemical management contracts across the region's integrated mining camps.
Canada
Alberta's oil sands districts face mandated tailings pond reclamation deadlines that open demand for high-molecular-weight flocculants in froth treatment circuits. Environment and Climate Change Canada's Metal Mining Effluent Regulations tighten monthly average limits for total suspended solids and ammonia. Fort McMurray processing facilities pilot automated polymer dosing tied to inline turbidity sensors.
Peru
Andean copper-gold producers pilot hybrid flocculant-coagulant formulations to achieve transportable cake moisture for dry-stack tailings alternatives. The country's national environmental certification system penalizes exceedance of heavy metals limits in effluent discharge. Cajamarca and Arequipa mining districts compress capital requirements for new tailings facilities through advanced dewatering chemistry deployment.
United States
Southwestern copper operations in Arizona and New Mexico upgrade water recovery systems to maintain circuit balances amid prolonged drought conditions. The EPA's effluent guidelines mandate technology-based limits for suspended solids from mineral processing circuits. Morenci and Safford concentrator clusters expand on-site analytical laboratories to demonstrate continuous compliance with federal thresholds.
Dewatering Aids for Mining Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital dosing integration and performance-guarantee contracting. The supplier base concentrates among integrated chemical conglomerates with captive monomer production and specialized polymer blenders with deep field technical service capabilities. Three archetypes dominate: Nordic-based flocculant specialists, diversified European chemical majors with acrylamide backward integration, and surfactant-focused formulators serving high-salinity deposits. Competitive moves center on multi-year site-level chemical management contracts and automated dosing system partnerships.
Within the integrated chemical tier, BASF SE and Solvay SA exemplify divergent specialization strategies. BASF SE anchors its position through in-house production of acrylamide monomer feedstock, ensuring supply security for polymer output. Solvay SA occupies a niche serving high-salinity process water common in Chilean copper belt operations through specialized surfactant expertise. Kemira Oyj represents the regional specialist archetype, leveraging Nordic manufacturing proximity to serve Scandinavian iron ore complexes with tailored flocculant programs.
| Leading Market Players |
|---|
| Kemira Oyj |
| Clariant AG |
| BASF SE |
| Solvay SA |
| Ashland Global Holdings Inc. |
| Solenis LLC |
| SNF Floerger |
| Nouryon Chemical B.V. |
| Ecolab Inc. |
| Others |
Value Chain & Pricing Dynamics
Acrylamide monomer feedstock costs cascade through polymer blending operations into tiered pricing for mining operators, with oil-derived propylene volatility compressing margins at the standard chemistry tier while specialized surfactant formulations for high-salinity deposits sustain premium positioning.
Pricing Analysis
Input-cost pass-through from acrylamide monomer suppliers structures contract negotiations between polymer blenders and mining procurement offices. Three-tier pricing separates performance-guaranteed dual-chemical programs from single-polymer treatments and commodity flocculant spot purchases. Pricing pressure stems from agricultural starch alternatives competing in jurisdictions with relaxed turbidity standards. Spot purchasers at independent mineral processing plants exhibit highest price sensitivity; integrated miners with multi-year chemical management contracts prioritize moisture reduction guarantees over unit cost.
Supply Chain Analysis
Freight costs from Nordic manufacturing bases to Western Australia's Pilbara region and Chile's Atacama belt shape regional supply economics for tailored flocculant programs. Production concentrates in Germany, Finland, and Belgium for acrylamide backward integration; surfactant formulation clusters in France and Belgium serve high-salinity copper operations. Supply chains draw from oil-derived propylene, sulfuric acid for inorganic coagulants, and agricultural starch feedstocks. Single-source vulnerability concentrates around acrylamide monomer supply. Distribution runs through site-level chemical management contracts displacing spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dewatering aids market compounds steadily as tailings containment regulations tighten across copper and iron ore jurisdictions, mandating permanent upgrades to water recovery chemistry intensity.
For Market Incumbents: Cement market position through backward integration into acrylamide monomer production and expansion of field technical service teams across Chile's Atacama belt and Western Australia's Pilbara region. Digital dosing integration threatens equipment-centric suppliers; prioritized investment in automated polymer injection systems with real-time turbidity feedback loops defends service contract renewals. For New Entrants and Emerging Players: Launch via performance-guaranteed contracting for oil sands froth treatment circuits in Alberta where mandated reclamation deadlines concentrate demand for high-molecular-weight flocculants. Environmental services contractors handling legacy tailings pond remediation represent the most penetrable customer segment with minimal incumbent technical service presence. For Investors and Strategic Acquirers: Roll-up economics work for specialized surfactant formulators serving high-salinity deposits because qualified supplier pools remain narrow and extend customer switching costs through multi-year qualification timelines. Five-to-ten year viability hinges on regulatory enforcement continuity rather than commodity cycle exposure. Monitor Environment and Climate Change Canada's enforcement patterns for Metal Mining Effluent Regulations as inflection indicator for North American demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Captive feedstock supply secures polymer output stability for BASF SE and SNF Floerger against propylene volatility. |
| Digital Dosing System Partnerships | Inline turbidity sensor integration with automated injection enables premium service contracts at Chilean copper concentrators. |
| High-Salinity Surfactant Formulation Expansion | Specialized chemistries for Chilean process water narrow qualified competition and extend Solvay SA's technical moat. |
| Oil Sands Froth Treatment Capacity Addition | Alberta reclamation deadlines open demand for high-molecular-weight flocculants in bitumen tailings circuits. |
| Site-Level Chemical Management Contracts | Multi-year performance agreements with guaranteed moisture targets displace spot purchasing among major concentrator operators. |
Study Parameters
Multiple input streams — technical interviews with plant metallurgists and process chemists, procurement lead surveys at copper and iron ore concentrators, regulatory filing analysis from Environment and Climate Change Canada and EPA effluent guidelines, and customs trade data for acrylamide polymer imports — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from SEC 10-K disclosures of integrated chemical suppliers, national mining association technical reports, and environmental compliance databases tracking tailings storage facility incidents.
Data-stream reconciliation anchored volume projections to segmented modeling across product chemistry tiers, deployment technology types, and end-user procurement contract structures throughout the forecast period. CAGRs were derived from regression analysis of historical reagent intensity per ton processed against regulatory tightening trajectories. Industry-specific forecast inputs included copper head grade decline curves forcing finer grinding and below-water-table ore expansion rates in Western Australia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement pauses or breakthrough natural polymer substitution at relaxed-standard jurisdictions. Forecasts reflect assumptions about continuous tightening of tailings containment rules and centrifugation retrofit adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Logging Cable Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Mining Tester Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Rock Duster Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Stone Mining and Quarrying Market