
 Global Connected Mining Market | 2026-2036
Global Connected Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Mining Market Foresight
Copper is expanding its role as the conductive backbone in ruggedized IoT sensor networks, displacing aluminum in underground deployment due to superior corrosion resistance and signal integrity at depth. Siemens AG leverages deep vertical integration across industrial automation to sustain its position in mine electrification infrastructure. Caterpillar Inc. anchors its competitive stance through proprietary MineStar autonomous command systems that dominate open-pit copper operations. Hexagon AB differentiates through specialized underground positioning and collision avoidance software that competes directly with Komatsu Ltd.'s growing portfolio in smart machine control.
Connected mining integrates real-time data acquisition, edge processing, and wireless telemetry to optimize extraction workflows, safety protocols, and asset utilization across geographically dispersed mineral operations. The technology stack typically encompasses IP67-rated sensors operating at 2.4 GHz and 900 MHz bands, hardened gateways, and centralized platforms that process terabyte-scale geospatial and machine-health feeds for immediate operational decisions. Fleet management applications currently occupy the largest addressable segment within connected mining deployments, while predictive maintenance is registering the fastest adoption curve as operators seek to compress unplanned downtime in capital-intensive extraction equipment. Cloud computing platforms are capturing expanding margin pools as quarry operators and precious metal producers migrate from on-premise historian systems to subscription-based operational intelligence architectures.
The US Mine Safety and Health Administration enforces continuous respirable dust and methane monitoring standards that directly mandate connected sensor networks in underground coal and metal operations. Australia's Work Health and Safety Act, administered by state regulators including SafeWork NSW and Resources Safety WA, compels mineral extractors to implement real-time worker proximity detection and autonomous equipment isolation protocols. Stakeholders must monitor how the EU's CSRD extends sustainability disclosure requirements to downstream mineral supply chains, reshaping procurement criteria for connected environmental compliance modules.
Market Dynamics
The EU Green Deal's emissions disclosure mandates are forcing mineral extractors to retrofit legacy fleets with connected telemetry, compressing upgrade timelines across copper, coal, and iron ore operations worldwide.
Growth Catalysts
- CSRD compliance mandates:The EU's Corporate Sustainability Reporting Directive compels mineral extractors to deploy real-time environmental monitoring across downstream supply chains, accelerating telemetry retrofits.
- Autonomous haulage standardization:Open-pit copper operators in Chile are standardizing integrated autonomous haulage networks, pulling demand for unified fleet management platforms.
- Worker safety digitization:Australia's Work Health and Safety Act drives real-time proximity detection and autonomous equipment isolation protocols in underground coal and metal operations.
Market Restraints
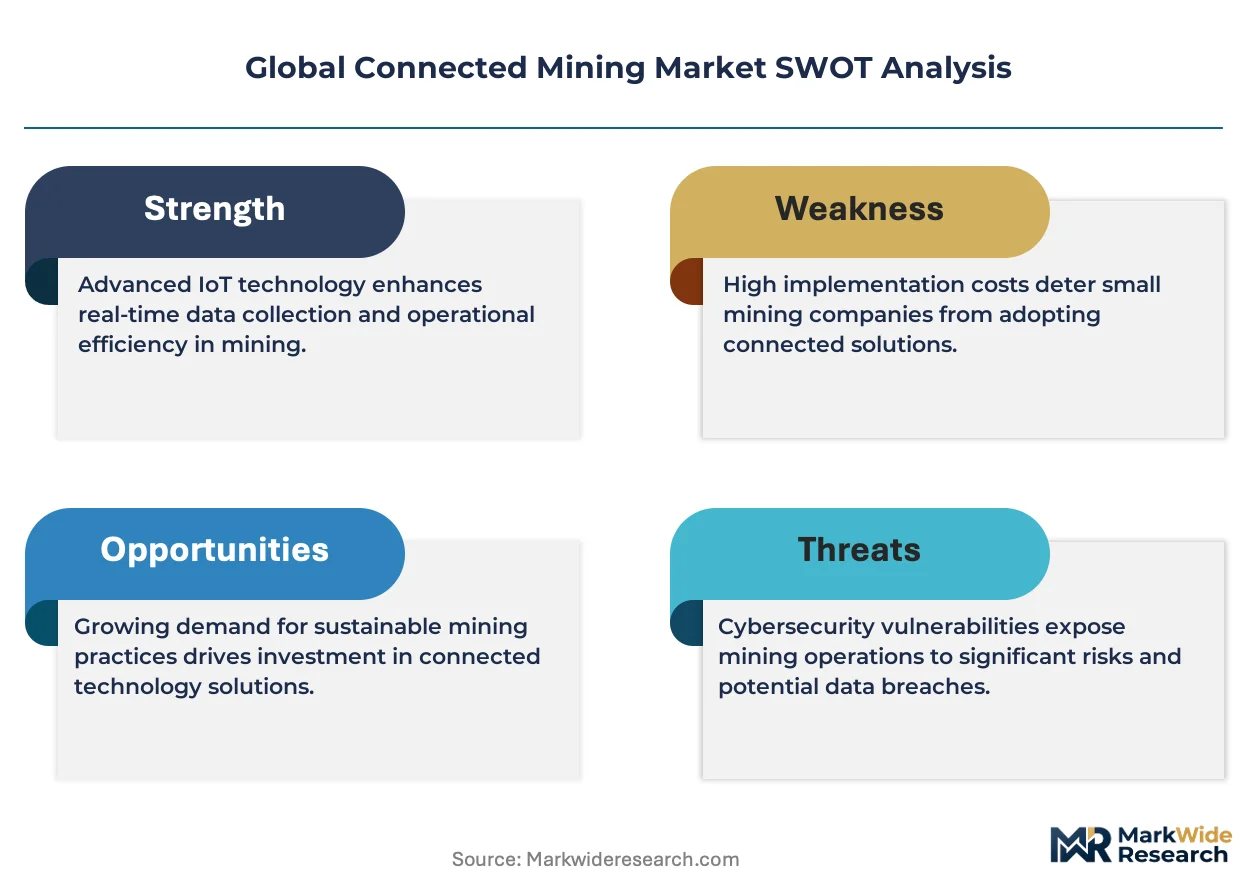
- Copper supply concentration:Chile and Peru dominate refined copper cathode output, exposing sensor network manufacturers to concentrate price volatility and export disruption.
- Legacy system integration costs:Underground coal operators in Australia face prohibitive capital requirements to bridge 1980s-era SCADA architectures with IP67-rated wireless sensor meshes.
- Radio frequency fragmentation:Mine operators must support simultaneous 2.4 GHz and 900 MHz bands across heterogeneous equipment fleets, complicating gateway standardization.
Strategic Opportunities
- Underpenetrated African copperbelt:Zambia and the Democratic Republic of Congo host substantial untapped reserves where connected mining infrastructure remains nascent relative to South American benchmarks.
- Predictive maintenance convergence:Edge computing combined with vibration analysis and thermal imaging creates white space for subscription-based equipment health monitoring in precious metal extraction.
- India's PLI scheme for mining equipment:Production-linked incentives for capital goods manufacturing attract component suppliers to establish localized sensor and gateway assembly.
Industry Challenges
- Subsurface RF engineering talent scarcity:Mining operators compete with telecommunications and defense sectors for specialists capable of designing wireless propagation in high-interference geological conditions.
- ATEX/IECEx certification timelines:Intrinsically safe device approvals for explosive atmospheres extend product launch cycles by 18-24 months, compressing competitive windows.
- Interoperability protocol fragmentation:Proprietary data formats from incumbent fleet management vendors obstruct seamless integration with third-party predictive analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Mining Market |
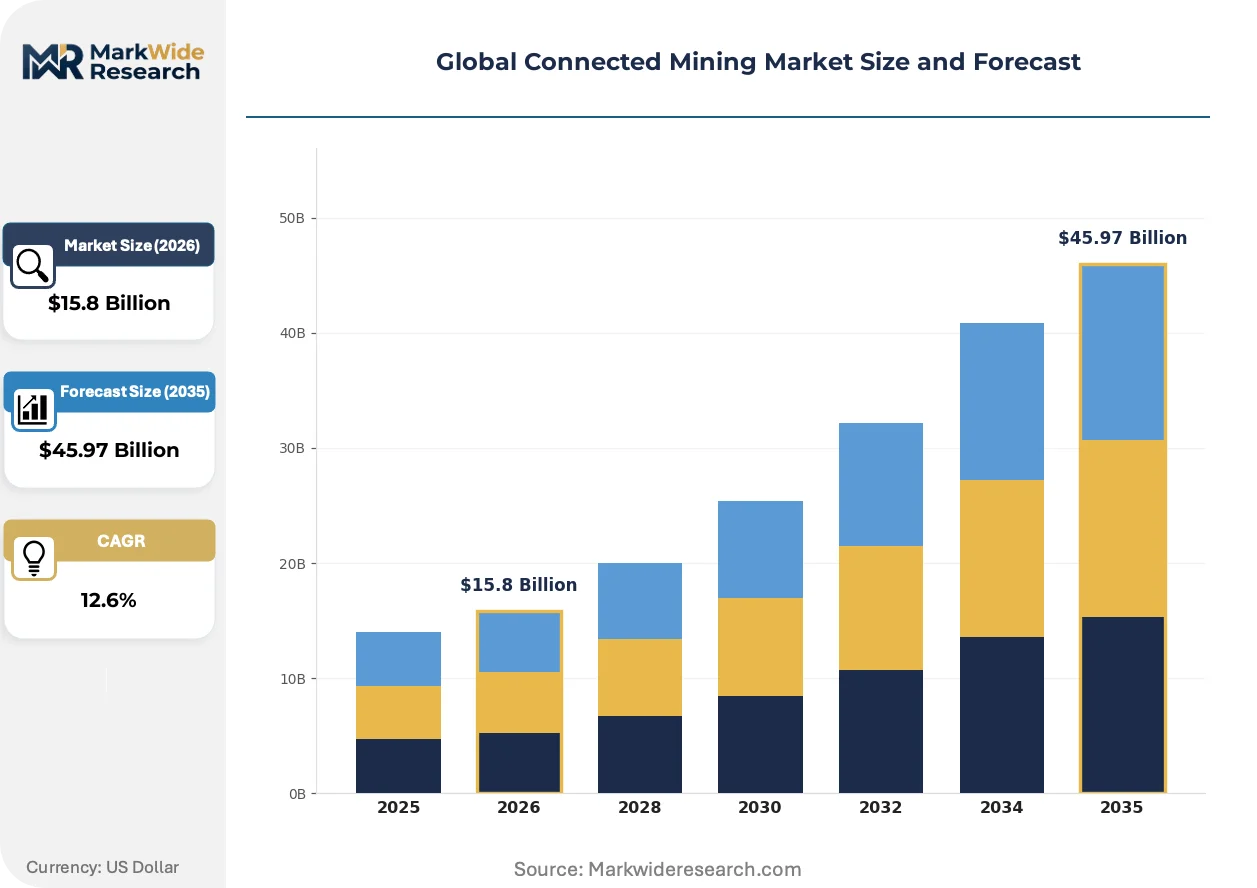
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $45.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Wireless Communications, Data Analytics, Cloud Computing, Artificial Intelligence, Edge Computing Application: Fleet Management, Predictive Maintenance, Resource Extraction Optimization, Safety Monitoring, Environmental Compliance, Asset Tracking End User: Mineral Extractors, Quarry Operators, Precious Metal Producers, Coal Extractors, Industrial Miners, Exploration Companies Deployment Type: On-Premise Systems, Cloud-Based Platforms, Hybrid Solutions, Mobile Applications, Edge Devices, Integrated Networks |
| Companies Covered | Siemens AG, Hexagon AB, Caterpillar Inc., Sandvik AB, Rockwell Automation Inc., ABB Ltd., Cisco Systems Inc., Schneider Electric SE, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Mining Market Shifts & Advancements
Edge computing architectures are decentralizing data processing from centralized historians to hardened underground gateways, compressing latency for safety-critical ventilation and collision avoidance decisions.
Mesh networking protocols are decentralizing connectivity architecture in deep-level extraction operations. Underground gold and platinum producers in South Africa deploy self-healing 900 MHz sensor grids that reroute around rockfall damage without surface intervention. This topology eliminates single-point failures that previously shut down real-time methane monitoring in vertical shaft configurations.
REACH chemical registration requirements are tightening material specifications for ruggedized sensor housings. European mining equipment suppliers reformulate elastomer seals and conformal coatings to eliminate Substances of Very High Concern from IP67-rated enclosures. German and Finnish underground machinery exporters accelerate supply chain audits to maintain CE marking eligibility for battery-electric vehicle integration kits.
Subscription-based operational intelligence is displacing perpetual license models for fleet management software. Mid-tier quarry operators in Brazil and Indonesia migrate from on-premise historian systems to consumption-priced cloud platforms that scale with active machine counts. This shift transfers capital expenditure to operating budgets while forcing incumbent vendors to restructure revenue recognition and customer success functions.
Global Connected Mining Market Segmentation
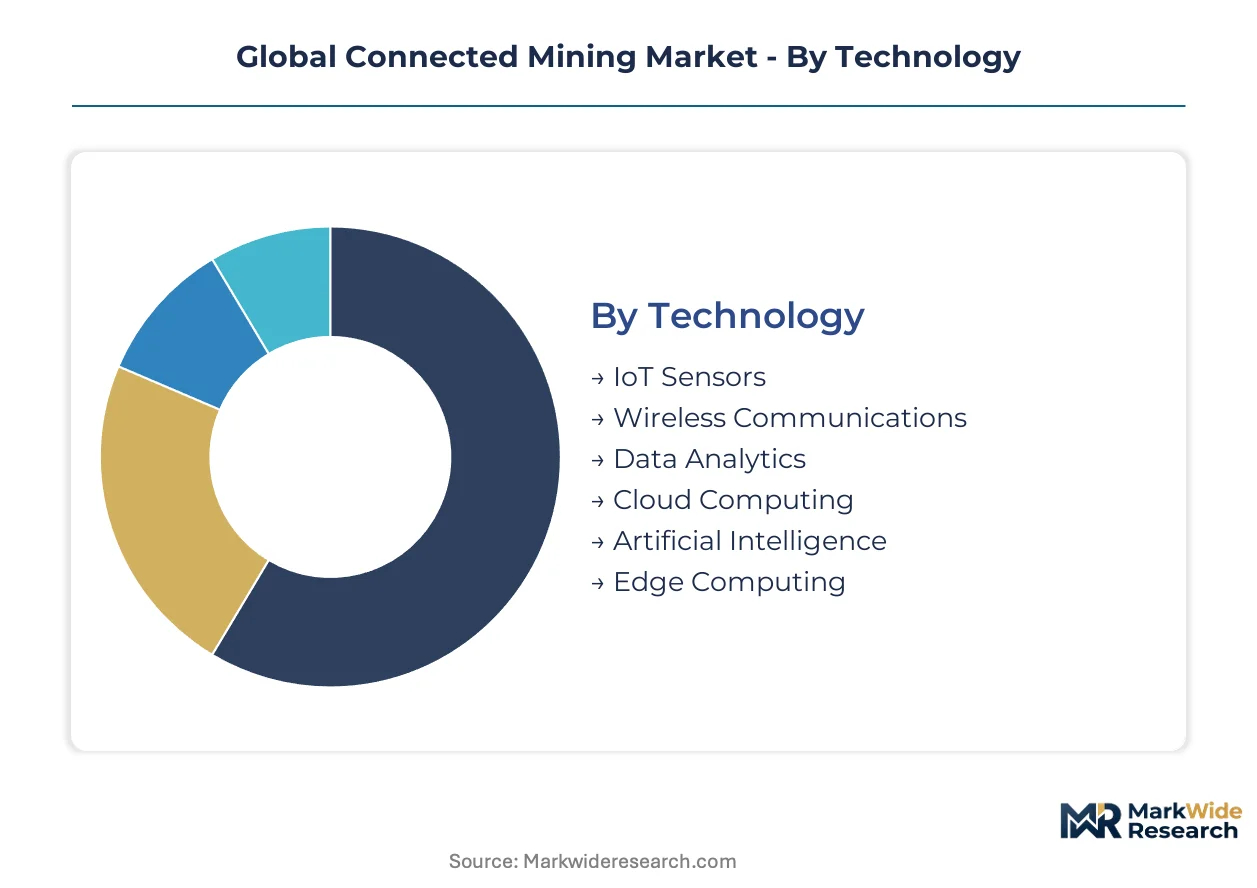
Connected mining technology stacks fragment across integration depths, from standalone sensors to fully embedded autonomous systems. Understanding where each segment sits on this spectrum reveals procurement patterns and margin structures across underground and open-pit operations.
Technology:
Integration depth varies sharply — some technologies operate as discrete point solutions while others require full-stack embedding into mine control systems.
- IoT Sensors:IP67-rated devices operating at 2.4 GHz and 900 MHz bands provide the physical data acquisition layer for ventilation, methane, and equipment health monitoring. Australian underground coal operators are accelerating deployment for real-time respirable dust tracking under Work Health and Safety Act mandates. These sensors sit at the shallow integration end, often retrofit to legacy SCADA architectures.
- Edge Computing:Hardened underground gateways decentralize processing from centralized historians, compressing latency for safety-critical collision avoidance decisions. Chile's open-pit copper operators embed these directly into autonomous haulage command loops, representing the deepest integration tier where compute becomes inseparable from machine control.
- Wireless Communications:Mesh protocols enable self-healing connectivity in deep-level extraction operations.
- Data Analytics:Geospatial and machine-health feed processing platforms transform terabyte-scale inputs into operational decisions.
- Cloud Computing:Subscription-based operational intelligence architectures displace on-premise historian systems among mid-tier quarry operators.
- Artificial Intelligence:Predictive models for equipment failure and resource quality prediction require substantial training data infrastructure.
IoT Sensors leads volumes today; Edge Computing is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive integrated platforms from modular point solutions accessible to smaller operators.
- Fleet Management:Unified platforms coordinating haul truck positioning, dispatch optimization, and fuel consumption across dispersed mineral operations. Chile's copper belt standardization on integrated autonomous haulage networks pulls premium demand for these systems, which sit at the high-cost tier requiring substantial infrastructure commitment.
- Predictive Maintenance:Vibration analysis and thermal imaging combined with edge computing create subscription-based equipment health monitoring. Precious metal extraction operators adopt most aggressively to compress unplanned downtime in capital-intensive processing equipment, representing the fastest-climbing cost-efficiency tier.
- Resource Extraction Optimization:Real-time ore grade analysis and blasting parameter adjustment systems.
- Safety Monitoring:Worker proximity detection and autonomous equipment isolation protocols mandated by Australian regulators.
- Environmental Compliance:Connected telemetry modules for EU Green Deal emissions disclosure requirements.
- Asset Tracking:Real-time location systems for mobile equipment and personnel in underground operations.
Fleet Management dominates revenue concentration; Predictive Maintenance shows steepest expansion trajectory.
End User:
Customer maturity and digital readiness separate early autonomous haulage adopters from compliance-driven retrofitters.
- Mineral Extractors:Large-scale copper, iron ore, and coal operators with capital budgets for integrated network deployment. These entities drive standardization efforts in Chile and Australia, representing the highest maturity tier with dedicated digital transformation functions.
- Coal Extractors:Underground operators in Australia retrofitting 1980s-era SCADA with IP67-rated wireless meshes under MSHA and state regulator mandates. This segment shows forced-maturity characteristics where compliance timelines override organic digital readiness.
- Quarry Operators:Mid-tier Brazilian and Indonesian limestone and aggregate producers migrating to consumption-priced cloud platforms.
- Precious Metal Producers:South African gold and platinum underground operations deploying self-healing 900 MHz sensor grids.
- Industrial Miners:Diversified extraction companies with heterogeneous equipment fleets requiring multi-band gateway support.
- Exploration Companies:Early-stage resource definition operations with limited infrastructure for permanent sensor network deployment.
Mineral Extractors lead deployment scale; Coal Extractors are expanding most quickly due to regulatory compression.
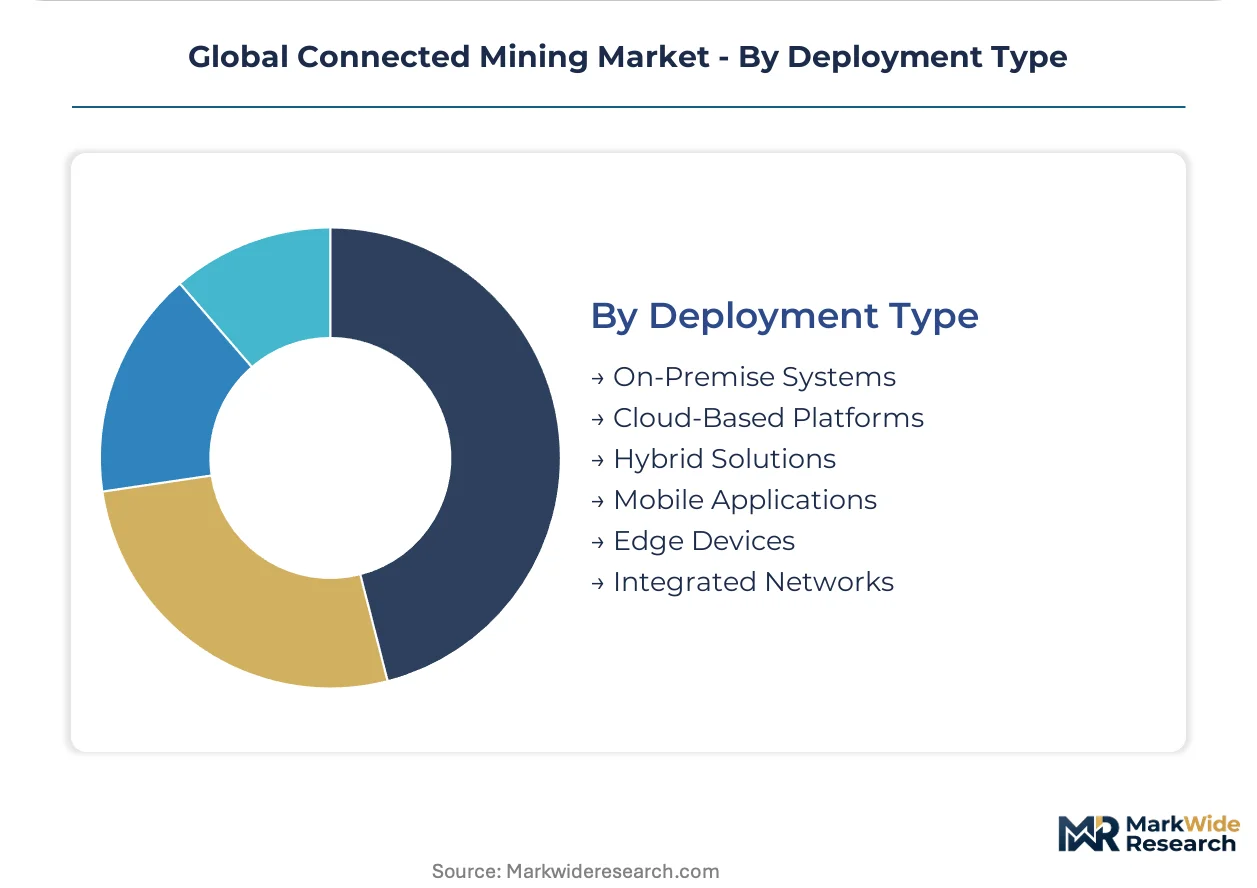
Deployment Type:
Volume concentration versus margin capture distinguishes capex-heavy ownership models from opex-based subscription structures.
- Cloud-Based Platforms:Consumption-priced operational intelligence scaling with active machine counts transfers capital expenditure to operating budgets. Brazilian and Indonesian quarry operators migrate most aggressively, though this model forces incumbent vendors to restructure revenue recognition functions.
- On-Premise Systems:Perpetual license historian architectures retained by security-sensitive underground operators and those with unreliable surface connectivity. These deployments concentrate in remote Chilean copper operations and South African deep-level gold mines where latency tolerance is lowest.
- Hybrid Solutions:Split architectures processing safety-critical data at edge while archiving analytics in cloud.
- Mobile Applications:Supervisor and maintenance technician interfaces for fleet status and work order management.
- Edge Devices:Hardened underground gateways for latency-sensitive ventilation and collision decisions.
- Integrated Networks:Fully unified autonomous command systems embedding compute, communications, and control.
On-Premise Systems retains installed base dominance; Cloud-Based Platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's copper belt concentrates autonomous haulage standardization efforts, while Australian underground coal operations drive regulatory-mandated sensor deployment. National mining codes and emissions frameworks reshape procurement priorities across extraction hubs.
Australia
Underground coal operators in New South Wales and Queensland accelerate IP67-rated wireless mesh retrofits to comply with SafeWork NSW and Resources Safety WA mandates for real-time respirable dust and methane monitoring. The country's Work Health and Safety Act compels proximity detection and autonomous equipment isolation protocols that pull demand for hardened gateway infrastructure.
Chile
Open-pit copper producers in the Atacama Desert standardize integrated autonomous haulage networks that embed edge computing directly into machine control loops. The national mining code and evolving environmental licensing requirements force disclosure of operational emissions, compressing upgrade timelines for connected fleet telemetry across the Antofagasta and Coquimbo regions.
Germany
Underground machinery exporters in North Rhine-Westphalia and Bavaria accelerate supply chain audits to maintain CE marking eligibility under REACH chemical registration requirements for ruggedized sensor housings. The country's industrial automation complex supplies electrification infrastructure to mineral extraction operations worldwide, with German mining equipment suppliers reformulating elastomer seals to eliminate Substances of Very High Concern.
South Africa
Deep-level gold and platinum producers in the Witwatersrand Basin deploy self-healing 900 MHz sensor grids that reroute connectivity around rockfall damage without surface intervention. The Department of Mineral Resources and Energy enforces continuous environmental monitoring standards that mandate connected telemetry for ventilation and worker safety systems in vertical shaft configurations.
United States
Appalachian coal operators and Southwest copper miners retrofit legacy SCADA architectures under Mine Safety and Health Administration continuous monitoring standards for respirable dust and methane. The Environmental Protection Agency and state regulators in Arizona and Nevada impose emissions disclosure requirements that accelerate connected environmental compliance module procurement across dispersed extraction sites.
Global Connected Mining Market Competitive Landscape
Global majors compete with regional champions across technology integration depth, with consolidated positions in autonomous haulage systems fragmenting into specialized niches for underground positioning and predictive analytics. Three archetypes dominate: diversified industrial conglomerates with captive mining automation divisions, pure-play mining technology specialists, and telecommunications equipment vendors extending into ruggedized industrial applications. Competitive moves concentrate on strategic partnerships between sensor manufacturers and cloud platform providers, plus backward integration into edge computing hardware to capture margin pools from subscription-based operational intelligence.
Within the diversified industrial tier, Siemens AG and ABB Ltd. occupy positions spanning mine electrification infrastructure and automation control systems. Caterpillar Inc. and Komatsu Ltd. anchor the heavy equipment-integrated technology segment, their proprietary command systems representing the autonomous haulage standardization pursued by Chilean copper operators. Hexagon AB exemplifies the specialized software archetype, with positioning and collision avoidance offerings competing directly against smart machine control portfolios from equipment manufacturers. Sandvik AB and Rockwell Automation Inc. sit within the underground-focused technology tier, while Cisco Systems Inc. and Schneider Electric SE represent network infrastructure and energy management extensions from adjacent industrial domains.
| Leading Market Players |
|---|
| Siemens AG |
| Hexagon AB |
| Caterpillar Inc. |
| Sandvik AB |
| Rockwell Automation Inc. |
| ABB Ltd. |
| Cisco Systems Inc. |
| Schneider Electric SE |
| Komatsu Ltd. |
| Others |
Supply & Pricing Matrix
Copper cathode pricing volatility in Chile and Peru transmits directly through sensor network manufacturing costs, with premium-tier IP67-rated devices absorbing raw material swings while economy-tier alternatives face margin compression. Subscription-based operational intelligence platforms in Brazil and Indonesia shift buyer economics from capital expenditure to operating budgets, restructuring how vendors capture value across deployment scales.
Pricing Analysis
Input-cost pass-through from refined copper and lithium-ion cell suppliers shapes tiered pricing across sensor hardware, with certification-grade differentiation separating ATEX/IECEx-certified premium units from standard industrial alternatives. Subscription SaaS models for fleet management software dominate recurring revenue streams, while price erosion runs through gateway hardware as Chinese and Indian component suppliers expand localized assembly under production-linked incentive schemes. Mid-tier quarry operators in emerging markets exhibit highest price sensitivity, whereas Chilean open-pit copper extractors prioritize integration depth over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries supplying edge computing chipsets for hardened underground gateways, exposing lead time risks to Australian and South African mining operators. Component sourcing draws from China's PCB manufacturing clusters, Germany's industrial automation component base, and Finland's ruggedized enclosure specialists. Tariff exposure on sensor housings and RF modules complicates procurement for North American operators. Distribution runs through equipment OEM captive channels and specialized mining technology integrators serving geographically dispersed extraction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where edge computing hardware costs compress and premium-tier autonomous haulage integration commands pricing power. Subscription model adoption transfers working capital requirements from buyers to vendors, rewarding platform architecture investments.
For Market Incumbents: Deepen backward integration into edge computing chipsets and RF module design to defend margin position against commoditization in sensor hardware. Secure ATEX/IECEx certification pipelines early to compress competitive windows as regulatory mandates accelerate across EU and Australian jurisdictions. Anchor customer relationships through hybrid cloud-on-premise architectures that address latency-sensitive underground operators while scaling subscription revenue from surface quarry clients.
For New Entrants and Emerging Players: Mid-tier precious metal extractors in South Africa's platinum belt represent underserved buyers lacking capital budgets for full-stack autonomous systems. Target predictive maintenance software layers that interface with incumbent fleet management platforms through API integration, avoiding direct competition with Caterpillar and Komatsu command systems. Pursue partnership routes with Indian component suppliers benefiting from PLI scheme subsidies to establish cost-competitive gateway manufacturing.
For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary data formats from legacy SCADA vendors obstruct interoperability with cloud-native analytics platforms. Position acquisition screening around specialized underground positioning software firms and mesh networking protocol developers with proven deployments in South African deep-level operations. Watch for inflection where REACH chemical registration deadlines force European equipment suppliers to reformulate sensor housings, creating technology refresh cycles among compliance-constrained buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Chipsets | Captures margin pools from subscription platforms while reducing exposure to Taiwanese foundry bottlenecks. |
| ATEX/IECEx Certification Acceleration | Compresses 18-24 month approval timelines to outpace competitors in EU and Australian regulatory markets. |
| Hybrid Cloud-Edge Architecture Launch | Addresses latency requirements of Chilean copper operators while enabling SaaS scaling for Brazilian quarry clients. |
| API-First Predictive Maintenance Platform | Interfaces with incumbent fleet systems to serve South African platinum extractors without full-stack replacement. |
| PLI-Aligned Indian Manufacturing Partnership | Localizes sensor assembly to serve price-sensitive Asian operators with government-subsidized cost structures. |
Research Methodology
Coverage spans Australia, Chile, South Africa, Germany, and the United States, with primary inputs from each mining jurisdiction triangulated against secondary validation. Mine operations directors, automation engineering leads, and procurement managers at mineral extractors provided field-level deployment data. Regulatory affairs specialists at equipment OEMs and certification body representatives contributed compliance timeline intelligence. Secondary sources included MSHA enforcement records, EU CSRD disclosure frameworks, Australian state regulator safety bulletins, SEC filings from listed mining technology vendors, and customs data on mining equipment trade flows. Bottom-up equipment shipment analysis and top-down mineral production value estimates were cross-referenced for triangulation.
Rate-of-change decomposition separated volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include technology integration depth, application cost tier, end-user digital maturity, and deployment type ownership structure. CAGRs were derived from fitted growth curves calibrated to historical adoption rates in comparable industrial automation markets. Industry-specific forecast inputs incorporated copper price scenario sensitivity and regulatory mandate implementation schedules across EU, Australian, and North American jurisdictions.
Underlying measurement precision varies by segment; fleet management platforms and autonomous haulage systems carry tighter precision than emerging predictive maintenance categories. Forecasts embed assumptions around regulatory enforcement consistency, semiconductor supply normalization, and mining capital expenditure cycles that could revise trajectories if commodity prices or policy priorities shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Smart Mining Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Surface Mining Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Rock Duster Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mine Hoisting Systems Market