
 Mining Equipment Rental Market | 2026-2036
Mining Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Equipment Rental Market Outlook
The gap between premium-tier rental fleets with telematics integration and commodity-grade equipment without remote diagnostics is recalibrating how miners evaluate total cost of ownership. Caterpillar (The Cat Rental Store) leverages its Connected Assets platform to sustain premium pricing across long-term contracts. Toromont Cat anchors Eastern Canadian mining corridors with specialized cold-weather machine configurations. Sumitomo Corporation competes through captive financing tied to lease-to-own structures in Southeast Asian mineral concessions.
Mining equipment rental denotes the commercial provision of heavy earthmoving and extraction machinery on a temporary or contractual basis, typically encompassing diesel-powered or electric-drive units rated above 75 kW operating weight. The practice allows mine operators to match fleet capacity to orebody depletion schedules without carrying fixed assets on balance sheets. Excavators dominate rental revenue pools due to their versatility across overburden removal and ore loading workflows, while bulldozers represent a mature segment where hourly rate competition compresses margins. Lease-to-own arrangements capture growing interest from mid-tier metal miners seeking eventual equity conversion without upfront capital deployment.
EPA Tier 4 Final standards and OSHA mine safety mandates in the United States constrain allowable fleet age, directly accelerating rental turnover toward compliant engine technologies. Australia's Work Health and Safety Act and state-based mine inspectorates impose fatigue monitoring and collision avoidance requirements that favor rental providers with capital to retrofit cabins. Stakeholders must weigh the trade-off between operational flexibility through short-term rental and the cost predictability of long-term fleet partnerships as emission thresholds tighten and automation retrofits reshape machine economics.
Market Dynamics
Capital discipline among mid-tier miners is compressing equipment ownership cycles and accelerating fleet outsourcing, while EPA Tier 4 Final and equivalent emissions frameworks in other jurisdictions force rental providers to absorb compliance costs rather than pass them through to rate-sensitive operators.
Growth Catalysts
- Emissions compliance deadlines:EPA Tier 4 Final in the United States and Australia's state-based mine safety inspectorates mandate newer engine technologies that rental fleets already carry, eliminating capital barriers for operators seeking compliant machines.
- Pilbara iron ore expansion:Western Australia's high-grade hematite deposits sustain continuous overburden removal cycles that favor flexible rental terms matching orebody depletion schedules.
- Telematics integration:Remote diagnostics and fatigue monitoring systems embedded in premium rental fleets reduce unplanned downtime and shift maintenance liability to providers.
Market Restraints
- Steel and component volatility:Fluctuations in high-grade steel plate and hydraulic system inputs compress rental rate margins during contract renewal cycles.
- OEM supply concentration:Dominance of integrated engine-hydraulic packages from a narrow supplier base in Germany and Japan limits fleet diversification options for independent rental operators.
- Underground diesel substitution limits:Battery-electric alternatives for longwall shearers and continuous miners remain capacity-constrained, prolonging reliance on emission-controlled diesel fleets.
Strategic Opportunities
- Indonesian nickel laterite expansion:Sulawesi and Halmahera mining concessions face equipment shortages that lease-to-own structures with captive financing can address.
- EU Green Deal machinery retrofit incentives:Carbon border adjustment mechanisms and national green recovery funds subsidize rental fleet electrification in Scandinavian underground operations.
- Collision avoidance retrofit demand:Proximity detection systems converging with autonomous haulage software create aftermarket service revenue streams for rental providers with technical integration capabilities.
Industry Challenges
- Automation technician scarcity:Shortfalls in mechatronics specialists capable of calibrating LiDAR and radar-based proximity systems delay fleet deployment timelines.
- Multi-jurisdictional certification lag:Divergent approval pathways between Australia's state mine inspectorates and MSHA in the United States extend homologation cycles for new machine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Equipment Rental Market |
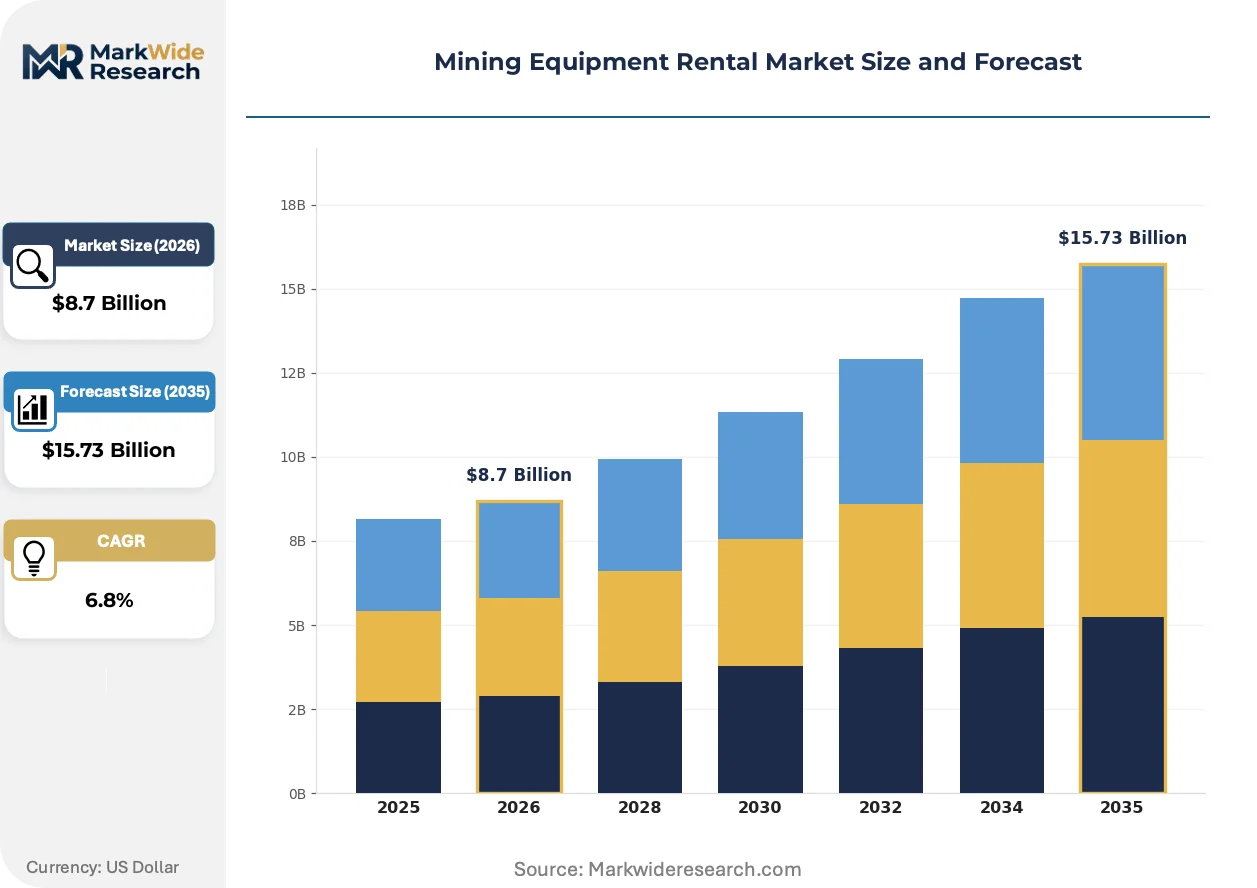
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Drills, Graders Service Type: Short-term Rental, Long-term Rental, Lease-to-Own, Maintenance Services End User: Coal Mining, Metal Mining, Mineral Mining, Quarrying Deployment: On-site, Off-site, Emergency Deployment, Seasonal Deployment |
| Companies Covered | Tim McDowell Equipment, Heavy Iron Inc, Heavy Metal Equipment & Rentals, Toromont Cat, ConTrac Equipment, Caterpillar (The Cat Rental Store), Lou-Tec, Pacesetter Equipment, Sumitomo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Equipment Rental Market Strategic Shifts
Battery-electric powertrains and autonomous retrofit kits are restructuring how rental fleets compete, shifting value capture from hourly rate arbitrage toward outcome-based availability guarantees and predictive maintenance subscriptions.
Diesel-electric hybrid excavators rated above 200 kW are electrifying overburden removal workflows in open-pit copper and iron ore operations. Tier 1 diversified miners in Chile and Western Australia are specifying these platforms for 12-month trial contracts. The technology is electrifying competitive positioning among rental providers, compressing margins on conventional diesel-only fleets while enabling premium pricing for integrated battery systems with regenerative braking.
EPA Tier 4 Final enforcement in the United States and equivalent Euro Stage V frameworks in European mining jurisdictions are prohibiting non-compliant engine sales and restricting resale pathways for older rental units. Rental providers must now retire or export pre-2015 machines, accelerating capital turnover. Underground coal operators in Appalachia and the Powder River Basin face the steepest compliance cliffs, driving consolidation toward rental fleets with newer engine inventories.
Availability-based contracting is displacing traditional hourly rate structures in long-term fleet partnerships. Mid-tier gold and base metal miners in Nevada, Ontario, and Western Australia now specify machine uptime percentages rather than shift-based rates, transferring operational risk to rental providers. This shift concentrates contract awards among vertically integrated rental operators with in-house maintenance depots and spare parts warehousing, marginalizing smaller independents without regional service infrastructure.
Mining Equipment Rental Market Segmentation
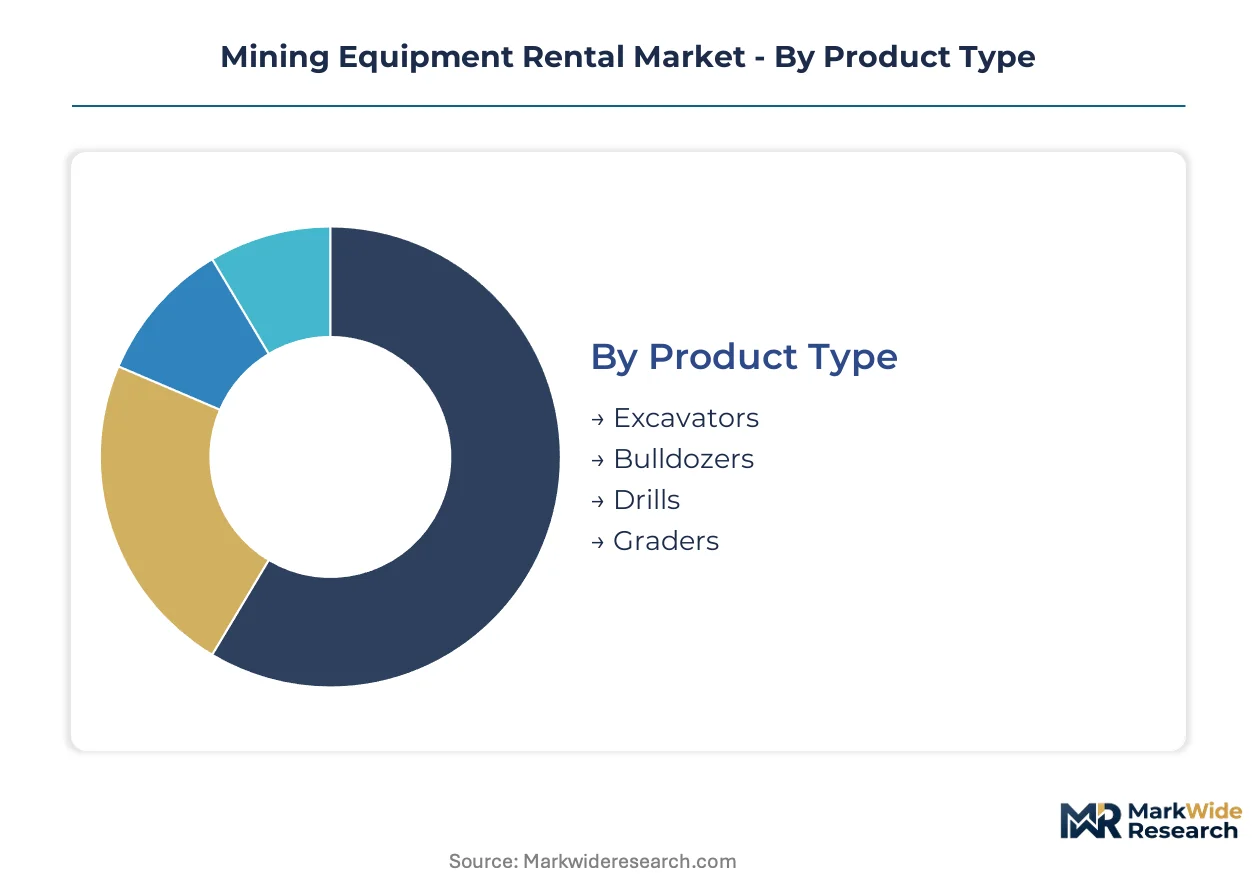
Segmentation in mining equipment rental reveals how capital deployment, contract duration, and operational risk allocation vary across machinery categories and service structures. Rental providers configure fleet composition and pricing tiers to match the depletion timelines and emission compliance requirements specific to each extraction vertical.
Product Type:
Capital intensity varies sharply across machine categories, with hydraulic mining excavators demanding the highest per-unit acquisition outlays and longest depreciation schedules among surface equipment.
- Excavators:Diesel-electric and conventional hydraulic units above 75 kW operating weight handle overburden removal and ore loading workflows. Western Australia's Pilbara iron ore district concentrates demand for 400-ton-class electric drive models configured for continuous 24-hour operations.
- Bulldozers:Tracked dozers with Tier 4 Final or Euro Stage V engines dominate mine site preparation and dump management. Appalachian underground coal operators favor smaller crawler configurations for confined seam access where emission-controlled diesel remains mandatory.
- Drills:Rotary and down-the-hole blasthole rigs serve open-pit copper and iron ore operations.
- Graders:Motor graders maintain haul road profiles in large-scale surface mines.
Excavators absorb the bulk of installed capacity; drills are expanding most quickly as blast pattern automation drives fleet renewal.
Service Type:
Contract structure determines how maintenance liability, residual value risk, and technology obsolescence transfer between operator and provider.
- Short-term Rental:Daily or weekly agreements for peak production periods or unplanned equipment failures. Queensland coal operators deploy short-term excavator contracts during wet season interruptions when owned fleets face utilization volatility.
- Long-term Rental:Multi-year fleet partnerships with fixed monthly rates and bundled maintenance. Chilean copper mines specify 36-month contracts for diesel-electric hybrid excavators to lock in availability guarantees ahead of EPA Tier 4 Final compliance deadlines.
- Lease-to-Own:Structures with captive financing that convert rental payments toward eventual equity. Indonesian nickel laterite concessions in Sulawesi favor these arrangements to circumvent upfront capital barriers while securing equipment for 10-year mine life projections.
- Maintenance Services:Separate contracts for predictive maintenance, collision avoidance retrofits, and telematics integration.
Long-term rental captures the majority of contracted value; lease-to-own is climbing the fastest as mid-tier miners seek balance sheet flexibility.
End User:
Extraction method and commodity economics dictate fleet specifications, with underground operations facing stricter emission and safety retrofit requirements than surface mining.
- Coal Mining:Underground longwall and continuous miner operations in Appalachia and the Powder River Basin drive demand for emission-controlled diesel fleets. EPA enforcement of Tier 4 Final standards forces rapid turnover of pre-2015 machines, compressing rental rate margins.
- Metal Mining:Open-pit copper, gold, and iron ore operations in Nevada, Ontario, and Western Australia specify large-class excavators and autonomous haulage compatibility. Availability-based contracting with uptime percentage guarantees now dominates these agreements.
- Mineral Mining:Potash, lithium, and rare earth extraction requires specialized equipment configurations.
- Quarrying:Dimension stone and aggregate operations favor mid-size excavators and rigid haul trucks with shorter replacement cycles.
Metal mining commands the largest equipment deployment; mineral mining is gaining share fastest as battery supply chain investments accelerate lithium and rare earth extraction.
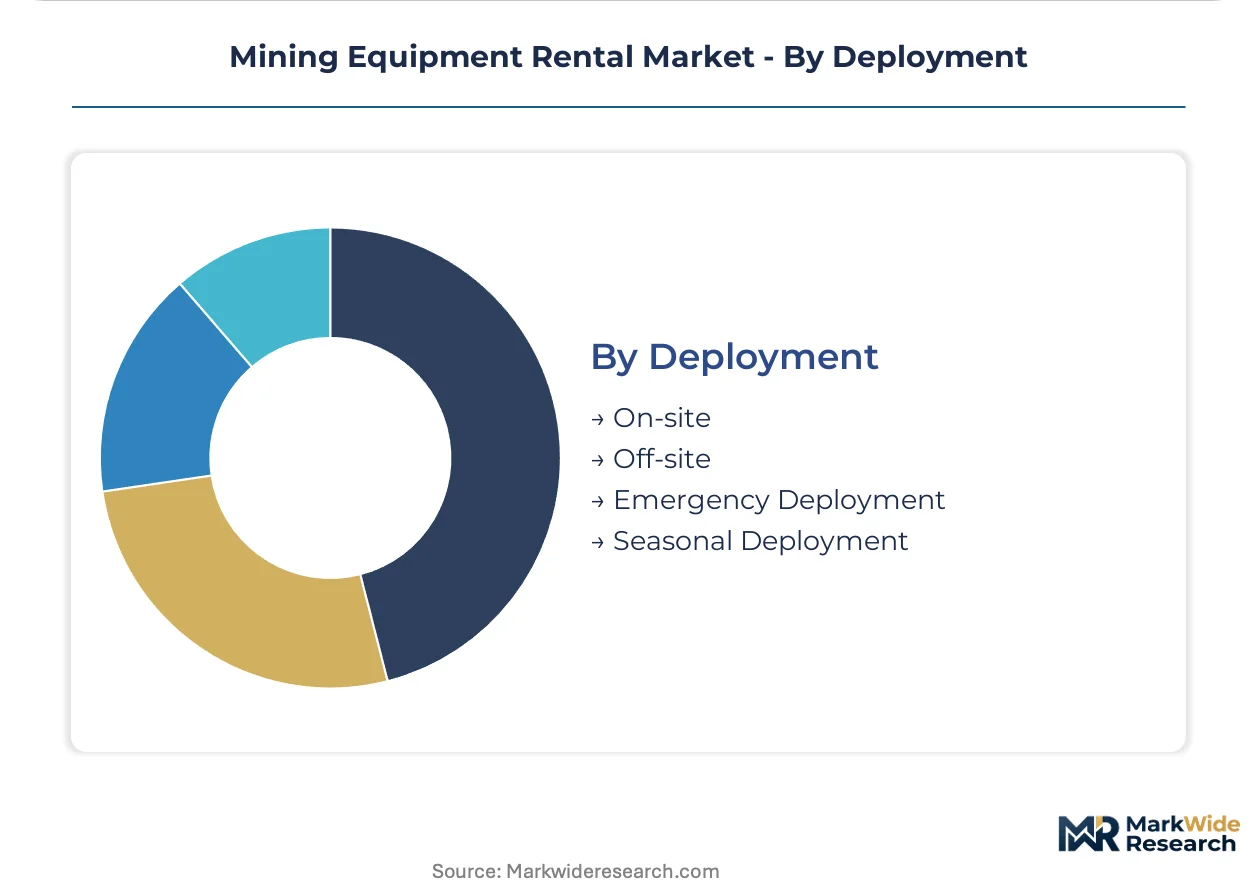
Deployment:
Logistics configuration separates routine fleet positioning from contingency arrangements that command premium pricing.
- On-site:Permanent machine placement at single-mine locations with dedicated maintenance infrastructure. Pilbara iron ore camps maintain on-site rental fleets exceeding 50 excavators per operation.
- Off-site:Centralized depot models serving multiple mine sites within 500-kilometer radii. Eastern Canadian rental providers anchor off-site fleets in Sudbury and Timmins to cover dispersed nickel and gold operations.
- Emergency Deployment:Rapid mobilization contracts for pit wall failures, equipment fires, or regulatory shutdowns. Australian rental networks guarantee 48-hour excavator delivery to any mine site in Queensland or Western Australia.
- Seasonal Deployment:Fleets activated during dry season windows or construction phases.
On-site deployment holds the majority of active machines; emergency deployment is expanding most quickly as climate-related operational disruptions intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara iron ore district concentrates the world's densest deployment of rental excavators, with single operations housing fleets exceeding 50 machines under long-term availability contracts.
Australia
Underground coal operations in Queensland and New South Wales drive fleet outsourcing as operators avoid capital lock-up during volatile commodity cycles. The country's Work Health and Safety Act and state-based mine inspectorates impose fatigue monitoring and collision avoidance requirements that favor rental providers with retrofit capital. Western Australia's Pilbara hematite belt sustains continuous overburden removal cycles that match flexible rental terms to orebody depletion schedules.
United States
Appalachian underground coal and Nevada open-pit gold operations face the steepest EPA Tier 4 Final compliance cliffs, forcing rapid turnover of pre-2015 diesel fleets. EPA emissions standards and OSHA mine safety mandates constrain allowable fleet age, directly accelerating rental turnover toward compliant engine technologies. The Powder River Basin in Wyoming sees consolidation toward rental fleets with newer engine inventories as operators defer balance sheet commitments.
Canada
Eastern Canadian mining corridors in Ontario and Quebec anchor specialized cold-weather machine configurations for nickel and gold extraction. Provincial mine safety regulators enforce proximity detection and ventilation standards that rental providers address through cabin retrofits. Sudbury and Timmins host centralized depot models serving dispersed operations across 500-kilometer radii.
Indonesia
Sulawesi and Halmahera nickel laterite concessions face acute equipment shortages amid battery supply chain investments. Captive financing tied to lease-to-own structures allows mid-tier miners to circumvent upfront capital barriers while securing machinery for 10-year mine life projections. Jakarta-based financial intermediaries structure these arrangements to align with mineral export licensing timelines.
Chile
Open-pit copper operations in the Atacama Desert specify diesel-electric hybrid excavators under 36-month contracts locking in availability guarantees. The country's environmental regulator enforces emission thresholds that accelerate fleet renewal toward electrified platforms. Antofagasta and Calama host the densest concentrations of trial contracts for battery-integrated systems with regenerative braking.
Mining Equipment Rental Market Competitive Environment
Premium-margin players sit above commodity-margin players across telematics integration and predictive maintenance capabilities. The market structure concentrates around vertically integrated rental operators with in-house service depots and spare parts warehousing, marginalizing smaller independents lacking regional infrastructure. Three archetypes dominate: OEM-captive rental networks, independent fleet operators with specialized maintenance capabilities, and trading houses offering captive financing structures. Competitive moves center on collision avoidance retrofit integration and lease-to-own product structuring for mid-tier miners seeking balance sheet flexibility.
Among North American equipment providers, Toromont Cat anchors Eastern Canadian mining corridors while Caterpillar's Cat Rental Store exemplifies the OEM-captive archetype through connected asset platforms. Sumitomo Corporation occupies a distinct position as a trading house integrating captive financing with lease-to-own structures in Southeast Asian mineral concessions. These three represent divergent strategic paths: regional service density, technology-enabled premium pricing, and balance-sheet-driven customer acquisition.
| Leading Market Players |
|---|
| Tim McDowell Equipment |
| Heavy Iron Inc |
| Heavy Metal Equipment & Rentals |
| Toromont Cat |
| ConTrac Equipment |
| Caterpillar (The Cat Rental Store) |
| Lou-Tec |
| Pacesetter Equipment |
| Sumitomo Corporation |
| Others |
Value Chain & Pricing Dynamics
Premium-telemetric fleet differentiation from commodity-grade rental units manifests in dual pricing architectures and supply chain sourcing strategies across the mining equipment rental sector. Availability-based uptime guarantees command rate premiums in Western Australia's Pilbara district while hourly-rate competition compresses margins on standard diesel configurations, with Tier 4 Final compliance costs absorbed rather than passed through to rate-sensitive operators.
Pricing Analysis
Uptime-percentage guarantees anchor value-based pricing for large-class excavators under long-term fleet partnerships. Price differentiation rests on telematics integration depth and collision avoidance certification tiers, with premium providers capturing extended contract durations. Cost compression in commodity-grade bulldozer rentals intensifies due to steel plate input volatility. Mid-tier metal miners exhibit highest price sensitivity; Tier 1 diversified operators prioritize availability over rate.
Supply Chain Analysis
Dual-sourcing requirements from Australian and Chilean mining operators mandate multi-OEM qualification for engine-hydraulic packages. Manufacturing concentration centers on Germany and Japan for integrated powertrain systems. High-grade steel plate, hydraulic pumps, and battery-electric powertrain components constitute critical input dependencies. Single-source vulnerability persists for LiDAR-based proximity detection modules. Distribution feeds from regional depot networks with 500-kilometer service radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where EPA Tier 4 Final and equivalent emissions frameworks erect capital barriers that favor incumbent rental providers with fleet turnover capacity.
For Market Incumbents: Deploy captive financing structures to lock in lease-to-own conversions before emission deadlines tighten. Consolidate maintenance depot density across the Powder River Basin and Appalachian corridors to capture availability-based contract migration. Battery-electric retrofit capabilities represent the critical defensive lever against technology substitution threats. For New Entrants and Emerging Players: Enter via Indonesian nickel laterite concessions where equipment shortages and export licensing timelines create penetrable white space. Target Sulawesi and Halmahera mid-tier miners with lease-to-own structures tied to 10-year mine life projections. Align go-to-market with Jakarta-based financial intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated rental operators given telematics-enabled premium pricing expansion. Long-term viability concentrates among providers with in-house collision avoidance retrofit capabilities and regional spare parts warehousing. Watch automation technician scarcity as the inflection signal for deployment timeline delays.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Connected Assets platforms enable premium pricing across Pilbara long-term contracts. |
| Lease-to-Own Structure Expansion | Captive financing in Indonesian nickel concessions circumvents upfront capital barriers. |
| Cold-Weather Fleet Specialization | Eastern Canadian configurations capture nickel and gold extraction demand. |
| Collision Avoidance Retrofit Capability | Proximity detection integration creates aftermarket revenue streams for technical providers. |
| Battery-Electric Fleet Transition | Diesel-electric hybrid platforms lock in Chilean copper availability guarantees. |
Study Parameters
Document review covered equipment manufacturer technical specifications, EPA and MSHA regulatory filings, and mine operator procurement disclosures, complemented by interviews with fleet maintenance directors, plant engineers at Pilbara operations, OEM aftermarket service heads, and mining procurement leads. Secondary validation drew from Australian Bureau of Statistics mining capital expenditure data, SEC 10-K equipment rental disclosures, and Chilean environmental regulator emission compliance records. Bottom-up unit deployment estimates and top-down market sizing triangulated across data streams.
Historical fleet deployment patterns cross-referenced against panel input from regional rental network managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include machine category, contract structure, extraction method, and deployment configuration. CAGRs derived from equipment replacement cycle analysis and emission compliance deadline clustering. Battery-electric adoption curves and automation retrofit penetration served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price collapse scenarios or accelerated diesel substitution timelines. Projections reflect assumptions regarding Tier 4 Final enforcement consistency and technician training pipeline adequacy. Deviation in Australian state mine inspectorate collision avoidance mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Machinery Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Rock Duster Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mining Drill Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Mining Tester Market
Mining Equipment
Impact Crusher Market