
 Mining Drills and Breakers Market | 2026-2036
Mining Drills and Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Drills and Breakers Market Intelligence
Multi-source procurement for critical drill components is decoupling from traditional single-vendor dependencies. Sandvik AB leverages its automation-ready drill platforms to anchor premium positioning in underground applications. Epiroc AB sustains technology leadership through its electric drive development programs. Caterpillar Inc. dominates surface mining channels with manufacturing scale and aftermarket density.
Mining drills and breakers constitute heavy-duty mechanical systems engineered to fracture rock formations and create blast holes with precision tolerances typically ranging from 76 mm to 400 mm in diameter, serving as essential frontline equipment in mineral extraction workflows. Hydraulic breakers deliver impact energy through pressurized fluid circuits, while rotary drills achieve penetration via continuous torque application with carbide-tipped cutting tools. Rotary drills command the largest installed base across open pit extraction sites, reflecting mature demand patterns in bulk commodity operations. Hydraulic breakers represent the fastest-expanding product category, propelled by quarrying operations and tunnel construction where fragmentation efficiency directly governs downstream hauling economics. Automation technology concentrates margin pools as mining contractors prioritize autonomous drilling fleets that reduce labor exposure and improve pattern consistency.
EPA emissions standards and MSHA workplace safety mandates compel OEMs to redesign breaker powertrains and drill cabin configurations for North American compliance. ISO 18758 and EU machinery directives establish baseline noise and vibration thresholds that filter market access for non-certified equipment suppliers. Stakeholders must weigh electrification roadmaps against residual diesel infrastructure investments when specifying fleet replacement cycles.
Market Dynamics
Battery-electric propulsion systems are forcing capital reallocation across underground mining fleets, as diesel exhaust exposure limits tighten and energy cost differentials widen. Tier-one operators now specify automation-ready platforms that compress labor intensity while extending equipment utilization rates.
Growth Catalysts
- MSHA diesel particulate mandates:Underground coal and metal mines in the United States face phased exposure limits that accelerate electric drill procurement.
- Copper concentrate demand:Electrification infrastructure buildouts across Chile and Peru drive blast hole drilling intensity for porphyry deposits.
- Autonomous pattern drilling:GPS-anchored rig positioning reduces overbreak and improves powder factor consistency in Australian iron ore operations.
Market Restraints
- High-voltage battery supply concentration:Cell manufacturing for 1000V mining platforms clusters in East Asian supply chains, creating procurement vulnerability.
- Steel alloy input volatility:Drill string and breaker tool steel prices fluctuate with nickel and molybdenum exchange dynamics.
- EPA Tier 4 Final compliance costs:Diesel engine aftertreatment systems add capital burden to surface drill rigs in North American markets.
Strategic Opportunities
- Canadian battery-electric adoption:Ontario and Quebec hard-rock mines pilot tethered and trolley-assist drill platforms with provincial clean technology incentives.
- Consolidated telematics platforms:Fleet management systems that integrate drill productivity data with maintenance scheduling create new software revenue pools.
- EU Green Deal machinery standards:CE marking requirements for noise and vibration create certification barriers that favor established OEMs with testing infrastructure.
Industry Challenges
- Automation systems integration:Retrofitting legacy hydraulic drill rigs with collision avoidance and remote operation interfaces demands specialized controls engineering.
- Underground electrician certification:High-voltage battery maintenance requires trades training programs that mining contractors struggle to staff at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Drills and Breakers Market |
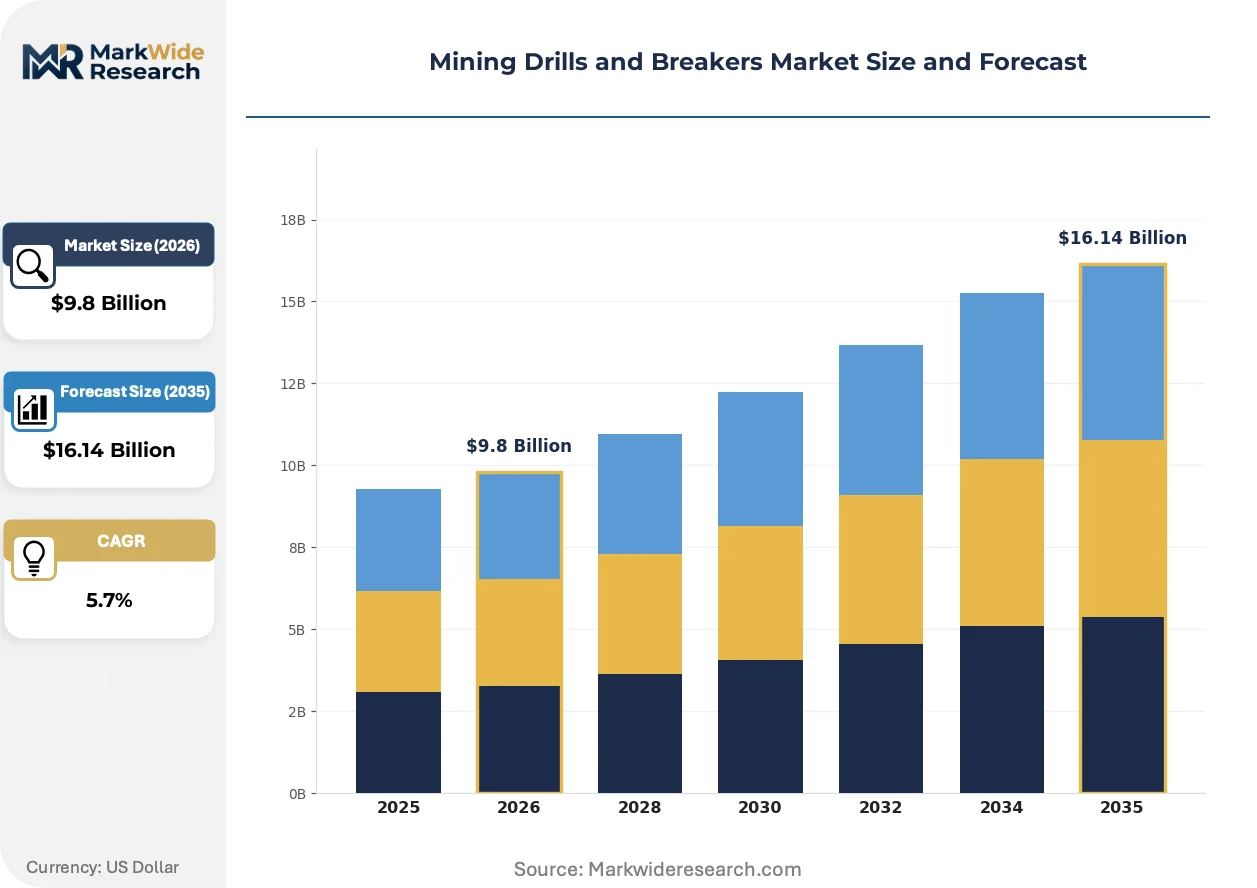
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Drills, Percussive Drills, Hydraulic Breakers, Pneumatic Breakers, Electric Breakers Technology: Automation, Remote Control, Pneumatic Mechanism, Hydraulic System, Electric Drive Application: Open Pit Extraction, Underground Excavation, Quarrying Operations, Tunnel Construction, Mineral Exploration End User: Mining Contractors, Mineral Processing Plants, Excavation Firms, Infrastructure Developers |
| Companies Covered | Caterpillar Inc., Boart Longyear Ltd., Epiroc AB, Hitachi Construction Machinery, Furukawa Rock Drill, Sandvik AB, Komatsu Ltd., Doosan Corporation, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Drills and Breakers Market Strategic Shifts & Innovations
Electrification architectures are compressing the traditional diesel-hydraulic design paradigm across both surface and underground applications. Equipment specification documents now prioritize energy recovery systems and regenerative braking that extend operating cycles between charging events.
Battery-electric drill rigs are electrifying underground development headings where ventilation constraints previously limited diesel equipment deployment. Hard-rock miners in Canada and Scandinavia specify 400kWh-plus battery packs that sustain two full production shifts. This transition is compressing the installed base of diesel-powered jumbo drills and redirecting aftermarket parts demand toward thermal management and power electronics components.
EPA emissions enforcement and EU machinery directives are tightening certification requirements for combustion-powered breakers and drills sold in regulated markets. OEMs must submit full lifecycle noise and vibration test data to secure market access. Surface mining contractors in the United States face equipment procurement delays as manufacturers reconfigure powertrains to meet Tier 4 Final and Stage V standards simultaneously.
Service contract structures are unbundling from equipment sales as mining contractors seek performance guarantees rather than parts availability commitments. Major copper producers in Chile now specify guaranteed availability metrics that shift maintenance risk to OEM service organizations. This compression of traditional dealer service models is most visible in mature mining districts where labor arbitrage no longer offsets downtime costs.
Mining Drills and Breakers Market Segmentation
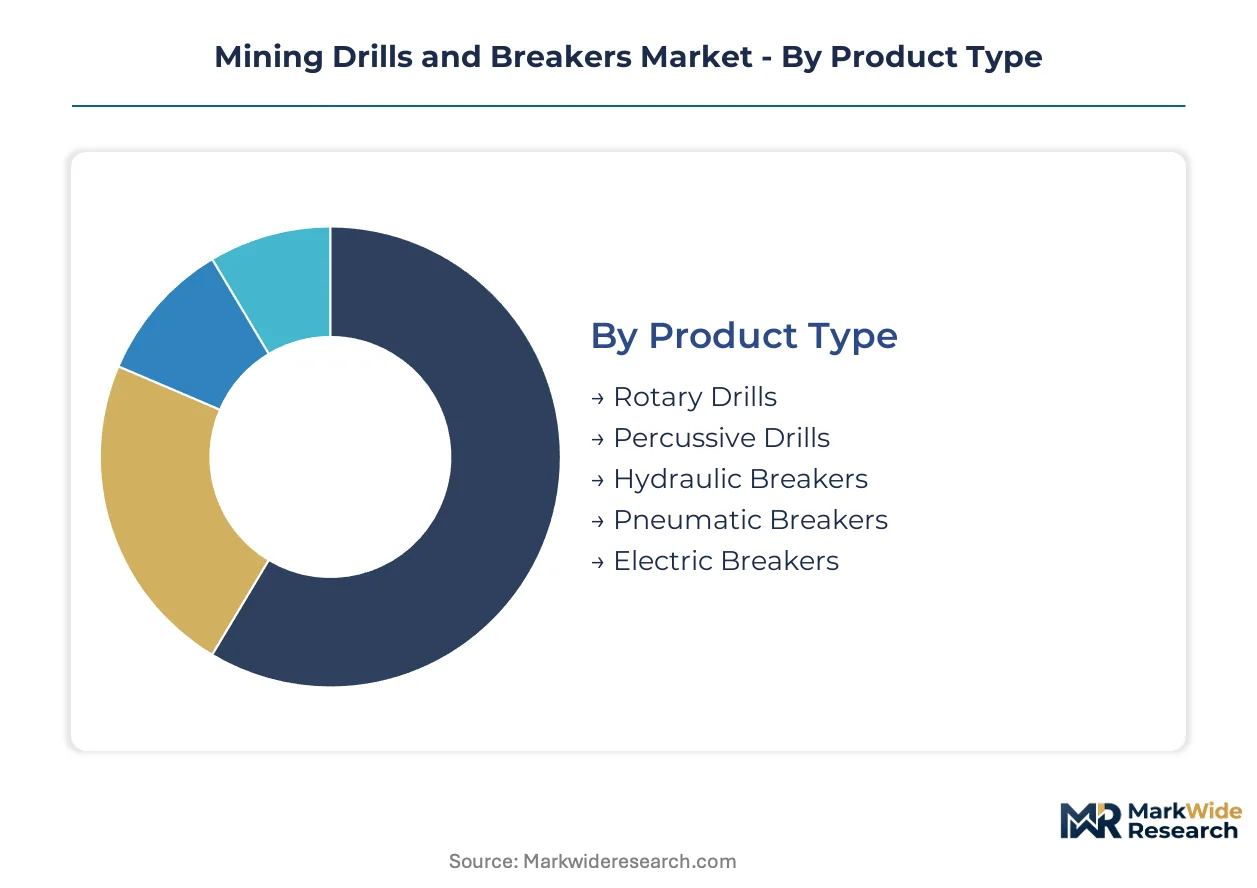
Segmentation in mining drills and breakers reveals divergent equipment specifications across extraction depths and automation readiness. Procurement patterns cluster around diesel-to-electric transition timelines and autonomous fleet deployment schedules.
Product Type:
Volume concentration sits with mature rotary platforms, while premium margins attach to electrified breaker systems.
- Rotary Drills:Continuous torque application through carbide-tipped cutting tools dominates open pit bulk commodity operations. Australian iron ore and Chilean copper porphyry deposits sustain the largest installed base, though electrification retrofits lag hydraulic breaker conversion timelines.
- Hydraulic Breakers:Pressurized fluid circuits deliver impact energy for fragmentation tasks in quarrying and tunnel construction. Scandinavian hard-rock tunneling and Canadian underground development drive specification intensity, with EPA Tier 4 Final compliance adding capital burden to North American procurement.
- Percussive Drills:Reciprocating piston mechanisms create blast holes in confined underground headings. South African platinum and Canadian nickel operations concentrate demand for pneumatic and hydraulic variants.
- Pneumatic Breakers:Compressed air powertrains serve specialized applications where ignition hazards prohibit combustion or electric systems. Underground coal operations in Poland and Czech Republic maintain residual demand.
- Electric Breakers:Corded and battery-electric architectures eliminate diesel exhaust exposure in ventilation-constrained headings. Ontario and Quebec hard-rock mines pilot tethered platforms with provincial clean technology incentives.
Today's leader: Rotary Drills. Tomorrow's challenger: Electric Breakers.
Technology:
Automation readiness separates replacement demand from greenfield specification, with electric drive architectures compressing traditional hydraulic design paradigms.
- Automation:GPS-anchored rig positioning and collision avoidance systems reduce labor exposure while improving blast pattern consistency. Australian tier-one miners specify autonomous drilling fleets that compress operating costs and extend utilization rates.
- Electric Drive:Battery-electric and trolley-assist platforms eliminate diesel particulate exposure in underground headings. Canadian and Scandinavian hard-rock operations specify 400kWh-plus battery packs sustaining dual-shift production cycles.
- Remote Control:Line-of-sight and teleoperation interfaces enable operator positioning outside hazardous zones. Chilean copper concentrators deploy remote drill rigs in high-wall stability risk areas.
- Hydraulic System:Pressurized fluid powertrains maintain dominance in surface applications where energy density requirements exceed current battery specifications. Peruvian open pit gold operations continue hydraulic drill procurement for deep blast hole patterns.
- Pneumatic Mechanism:Compressed air systems persist in specialized underground coal applications and legacy fleet maintenance. Polish mining contractors retain pneumatic drills for methane-risk headings.
Automation commands current capital allocation; electric drive captures tomorrow's specification momentum.
Application:
Surface extraction sustains equipment volume, while underground electrification creates technology substitution pressure.
- Open Pit Extraction:Large-diameter rotary drills create blast patterns for bulk commodity removal. Western Australian iron ore and Chilean copper operations concentrate demand for high-reliability, high-utilization platforms.
- Underground Excavation:Confined headings demand compact drill jumbos and breaker platforms with zero-emission capability. Canadian hard-rock mines lead battery-electric adoption with provincial incentive alignment.
- Quarrying Operations:Fragmentation efficiency governs downstream hauling economics in limestone and aggregate extraction. German and Italian quarrying contractors specify mid-size hydraulic breakers with noise certification for EU machinery directive compliance.
- Tunnel Construction:Mechanized excavation for transportation and utility infrastructure drives specialized breaker and drill demand. Swiss Alpine tunneling projects specify low-vibration equipment for seismic-sensitive geology.
- Mineral Exploration:Portable drill rigs serve greenfield resource definition with rapid deployment requirements. Canadian and Australian junior mining contractors concentrate demand for helicopter-portable diamond drill systems.
Open Pit Extraction anchors current revenue; Underground Excavation offers the steepest expansion trajectory through electrification mandates.
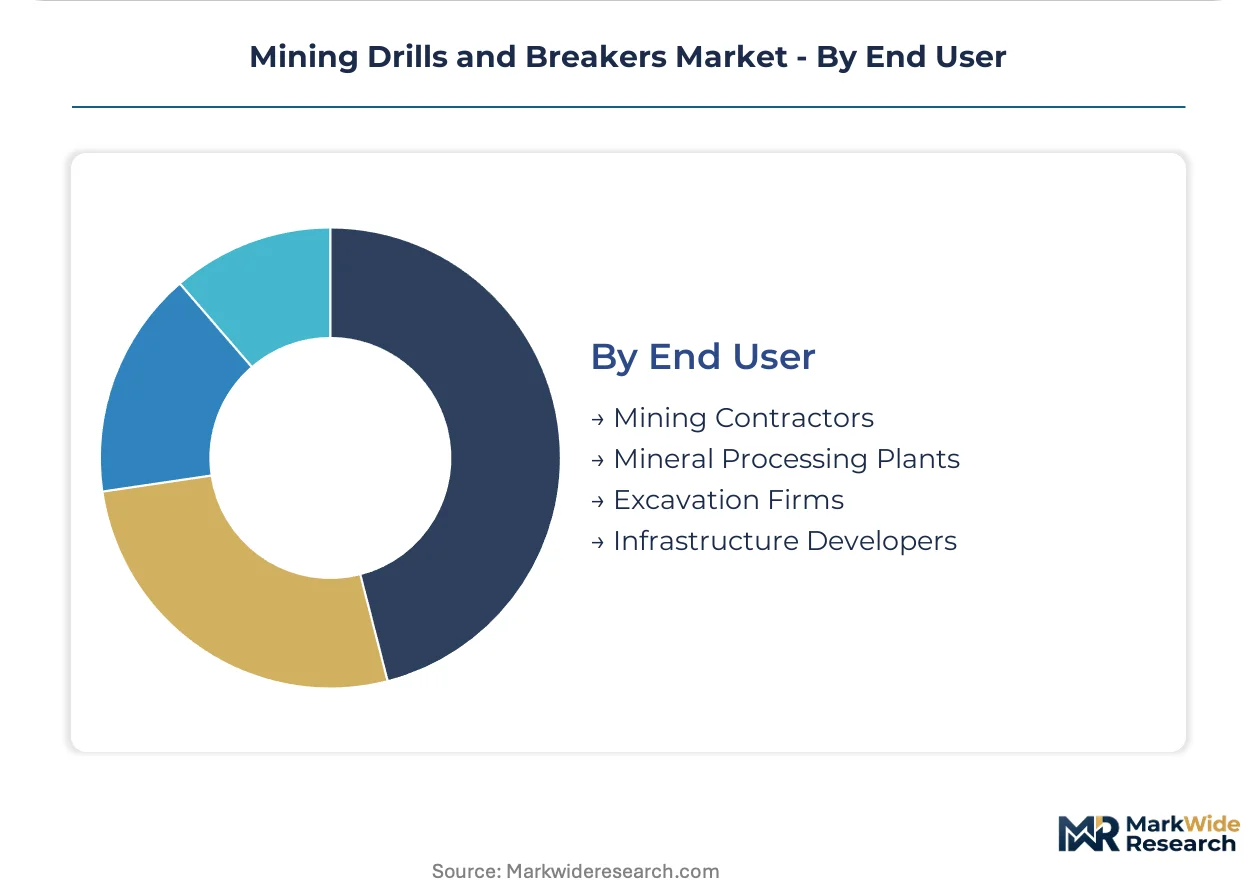
End User:
Mining contractors consolidate procurement authority, while mineral processing plants concentrate aftermarket service demand.
- Mining Contractors:Fleet operators specify performance guarantees and availability metrics that shift maintenance risk to OEM service organizations. Chilean copper producers now contract guaranteed uptime rather than parts availability.
- Excavation Firms:Tunneling and civil engineering contractors demand specialized breaker platforms with noise and vibration certification. Austrian and Swiss Alpine construction projects drive specification intensity.
- Mineral Processing Plants:Downstream operations influence upstream fragmentation specifications to optimize mill feed size distribution. Peruvian concentrators specify blast hole patterns that reduce downstream grinding energy intensity.
- Infrastructure Developers:Transportation and utility tunneling projects create episodic demand for specialized equipment. Norwegian subsea tunnel programs concentrate Nordic breaker procurement cycles.
Mining Contractors dominate current specification authority; Infrastructure Developers present cyclical expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore belt concentrates replacement demand for high-utilization rotary drill platforms as tier-one operators modernize fleet compositions toward automation-ready specifications.
Australia
Western Australia's iron ore operations drive specification intensity for GPS-anchored autonomous drilling fleets that compress labor exposure and improve blast pattern consistency. The country's national mining safety regulator enforces strict diesel particulate exposure limits that accelerate electric drill procurement in underground development headings. Perth-based equipment distributors coordinate fleet management systems that integrate drill productivity data with predictive maintenance scheduling.
Chile
Copper porphyry deposits in the Atacama Desert sustain blast hole drilling intensity as electrification infrastructure buildouts concentrate demand for high-reliability breaker systems. The national environmental regulator enforces emissions standards that compel OEMs to reconfigure powertrains for Tier 4 Final compliance. Antofagasta mining contractors now specify guaranteed availability metrics that shift maintenance risk to OEM service organizations rather than traditional parts availability contracts.
Canada
Ontario and Quebec hard-rock mines pilot tethered and trolley-assist drill platforms with provincial clean technology incentives accelerating battery-electric adoption. Health Canada workplace safety mandates tighten certification requirements for combustion-powered equipment sold in regulated markets. Sudbury nickel operations and Val-d'Or gold camps concentrate demand for 400kWh-plus battery packs sustaining dual-shift production cycles in ventilation-constrained headings.
United States
Surface mining contractors in Arizona and Nevada face equipment procurement delays as manufacturers reconfigure powertrains to meet EPA Tier 4 Final and MSHA diesel particulate mandates simultaneously. The EPA emissions standards compel OEMs to redesign breaker powertrains and drill cabin configurations for North American compliance. Wyoming coal operations and Minnesota iron ranges anchor residual demand for rotary drill platforms in bulk commodity extraction.
China
Domestic coal and metal mining operations concentrate demand for mid-size hydraulic breakers with cost-optimized specifications serving fragmentation-intensive quarrying workflows. The Ministry of Ecology and Environment enforces dual carbon goals that filter market access for non-certified equipment suppliers through tightened emissions protocols. Shanxi coal basins and Inner Mongolia copper camps drive specification volume for pneumatic and hydraulic drill variants in mechanized excavation.
Mining Drills and Breakers Market Key Industry Players
Global majors compete with regional champions across automation-ready platforms and electrification architectures, producing a tiered structure where scale-driven OEMs anchor premium positioning while specialized fabricators capture niche applications. The vendor base clusters around three strategic archetypes: full-line mining equipment conglomerates with manufacturing scale and aftermarket density; automation-focused specialists with integrated telematics and remote operation capabilities; and regional champions with cost-optimized specifications for emerging market quarrying. Dominant competitive moves include portfolio diversification into battery-electric powertrains and strategic partnerships for high-voltage battery supply security.
Among Sweden-based automation specialists, Sandvik AB and Epiroc AB exemplify the technology leadership archetype through their electric drive development programs and underground application focus. Caterpillar Inc. anchors the scale-driven tier with surface mining channel dominance derived from manufacturing footprint and service network density. These three entities collectively represent the competitive fault lines between electrification-first specification and traditional diesel-hydraulic installed base maintenance.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Boart Longyear Ltd. |
| Epiroc AB |
| Hitachi Construction Machinery |
| Furukawa Rock Drill |
| Sandvik AB |
| Komatsu Ltd. |
| Doosan Corporation |
| Atlas Copco AB |
| Others |
Cost & Logistics Intelligence
Certified underground electricians concentrated in Ontario and Quebec hard-rock mining districts command wage premiums that widen pricing spreads between premium automation-ready drill platforms and standard hydraulic configurations.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum alloy volatility anchors pricing dynamics across drill string and breaker tool steel procurement. Three-tier pricing structure across premium automation-certified, standard hydraulic, and economy pneumatic tiers separates OEMs by electrification readiness and EPA Tier 4 Final compliance status. Cost compression in mid-range hydraulic breakers intensifies because Chinese fabricators flood quarrying channels with cost-optimized specifications. Mining contractors in Chile demonstrate lowest price sensitivity through guaranteed-availability contracting, while Indian coal operators exhibit highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Freight costs for oversized drill rig components from Sweden and Finland to Australian Pilbara ports add fifteen to twenty percent landed cost premiums versus regional fabrication alternatives. Cell manufacturing for 1000V mining battery platforms clusters in South Korea and Japan, creating procurement vulnerability for North American and European OEMs. Tool steel feedstock draws from German and Austrian specialty mills, with distribution running through Perth, Santiago, and Toronto equipment distribution hubs serving tier-one mining contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mining drills and breakers rests on electrification-driven aftermarket part substitution toward thermal management and power electronics components, compressing traditional diesel-hydraulic service revenue pools.
For Market Incumbents: Anchor premium positioning through captive battery-electric development programs that preempt emerging automation specialists from securing high-voltage platform certifications. Defend against Chinese cost-optimized entrants by deepening aftermarket service density in Australian and Chilean mining districts where labor arbitrage no longer offsets downtime costs. Prioritize MSHA and EPA compliance investment as regulatory barriers that filter non-certified suppliers from North American procurement channels. For New Entrants and Emerging Players: Begin with Canadian hard-rock underground development, where provincial clean technology incentives reduce customer acquisition friction for tethered and trolley-assist drill platforms. Target mid-size quarrying contractors in Germany and Italy seeking EU machinery directive noise certification without premium OEM pricing. Pursue white-label telematics integration as the go-to-market angle, embedding fleet management software into existing contractor maintenance scheduling systems. For Investors and Strategic Acquirers: Mining equipment conglomerates with manufacturing scale and aftermarket density represent the most active acquirer category in this space, consolidating automation-focused specialists to fill electrification capability gaps. Long-term viability favors targets with integrated high-voltage battery supply agreements and testing infrastructure for ISO 18758 certification. Watch EPA enforcement intensity against Tier 4 Final non-compliance as the inflection signal for accelerated electric platform procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Development | MSHA diesel particulate mandates in US underground coal and metal mines accelerate electric drill procurement timelines. |
| Automation-Ready Fleet Specification | Australian tier-one miners specify GPS-anchored autonomous drilling fleets that compress labor exposure and improve blast pattern consistency. |
| Aftermarket Service Unbundling | Chilean copper producers now contract guaranteed uptime metrics rather than traditional parts availability commitments. |
| High-Voltage Battery Supply Security | Cell manufacturing concentration in East Asian supply chains creates procurement vulnerability for 1000V mining platforms. |
| Consolidated Telematics Platform Integration | Fleet management systems that integrate drill productivity data with predictive maintenance scheduling create new software revenue pools. |
Research Approach
Coverage spans Australia, Chile, Canada, the United States, and China, with primary inputs from each mining district informing demand calibration. The analysis combines structured interviews with mine maintenance directors, OEM procurement teams, aftermarket service heads, and provincial mining safety regulators with secondary validation from MSHA enforcement data, EPA emissions filings, customs trade records, and equipment registration databases. Bottom-up equipment unit economics triangulate against top-down mineral extraction investment flows across the analysis window.
Rate-of-change decomposition separates volume growth from value growth through product mix shifts toward electrified and automation-ready platforms. The analytical framework models segmentation across product type, technology architecture, application depth, and end-user contracting structure throughout the forecast period. CAGRs derive from drill rig replacement cycle analysis, copper concentrate demand intensity, and battery-electric adoption curve assumptions in ventilation-constrained underground headings.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement actions, commodity price collapses affecting mine development timelines, and breakthrough battery chemistry transitions. Forecasts reflect documented assumptions about electrification infrastructure buildout pacing and OEM compliance investment timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Underground Mining Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mining Equipment Market
Mining Equipment
North America Drill Pipe Market