
 Pile Cage Welding Machine Market | 2026-2036
Pile Cage Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pile Cage Welding Machine Market Insights
Specialized equipment distributors in Europe and Asia are reshaping how pile cage welding machines reach construction contractors and steel fabricators. MBK Maschinenbau GmbH leverages its German engineering base to dominate precision-automatic systems for bridge foundations. TJK Machinery (Tianjin) Co., Ltd. anchors high-volume production lines serving China's domestic infrastructure build-out. Schlatter Industries AG competes through resistance welding specialization that extends into dam and heavy civil applications.
A pile cage welding machine automates the fusion of longitudinal rebars with transverse stirrups or spirals, typically handling bar diameters from 8 mm to 40 mm at outputs exceeding 20 cages per hour for foundation piling. Automatic and CNC-controlled configurations lead equipment shipments due to labor cost pressures and repeatability demands in high-rise building foundations. Resistance welding technology occupies the largest installed base, though laser welding differentiates premium systems where minimal heat-affected zones protect high-strength steel grades in seismic zones.
German manufacturers navigate KBA-adjacent machinery safety directives alongside EU CE marking requirements for construction equipment market access. China's SAMR enforces GB standards on welding equipment sold domestically, while India's BIS certification shapes import flows for contractors under the country's infrastructure investment programs. Stakeholders must monitor how carbon-accounting rules in Europe and dual-carbon targets in China redirect procurement toward energy-efficient welding architectures before regulatory thresholds harden.
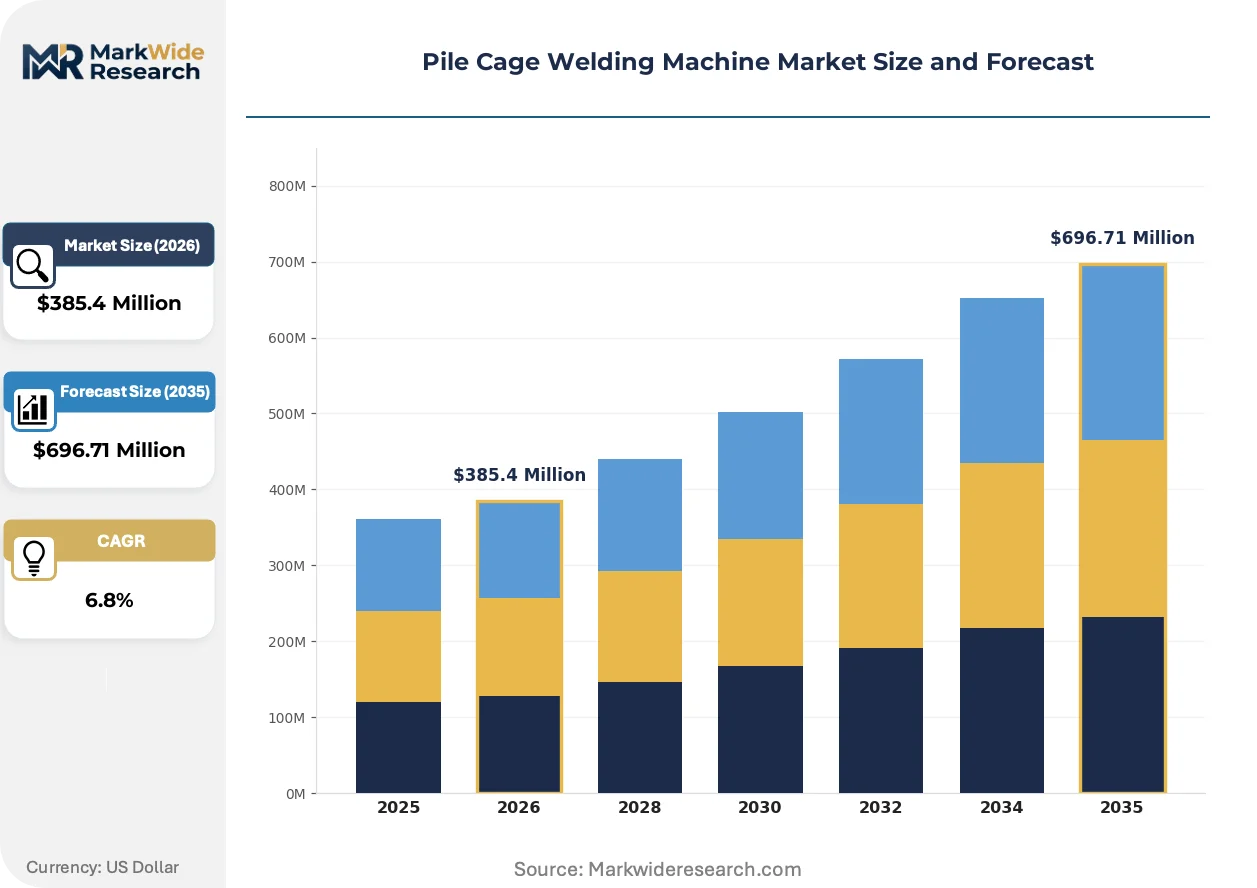
Market Dynamics
Bridge construction contractors in Germany and China are expanding automated welding capacity to meet stricter rebar quality standards under EU CE marking and Chinese GB standards, compressing manual fabrication margins and reshaping equipment procurement cycles.
Growth Catalysts
- EU CE marking enforcement:German and French bridge contractors must certify rebar weld integrity, forcing replacement of semi-automatic systems with precision-automatic pile cage welding machines.
- Indian infrastructure corridors:Government-backed civil engineering projects under the country's investment programs require higher-volume pile cage production, concentrating demand in Maharashtra and Gujarat.
- Resistance welding automation:Labor cost pressures in high-rise building foundations are accelerating CNC-controlled configuration adoption for repeatability in seismic zone foundations.
Market Restraints
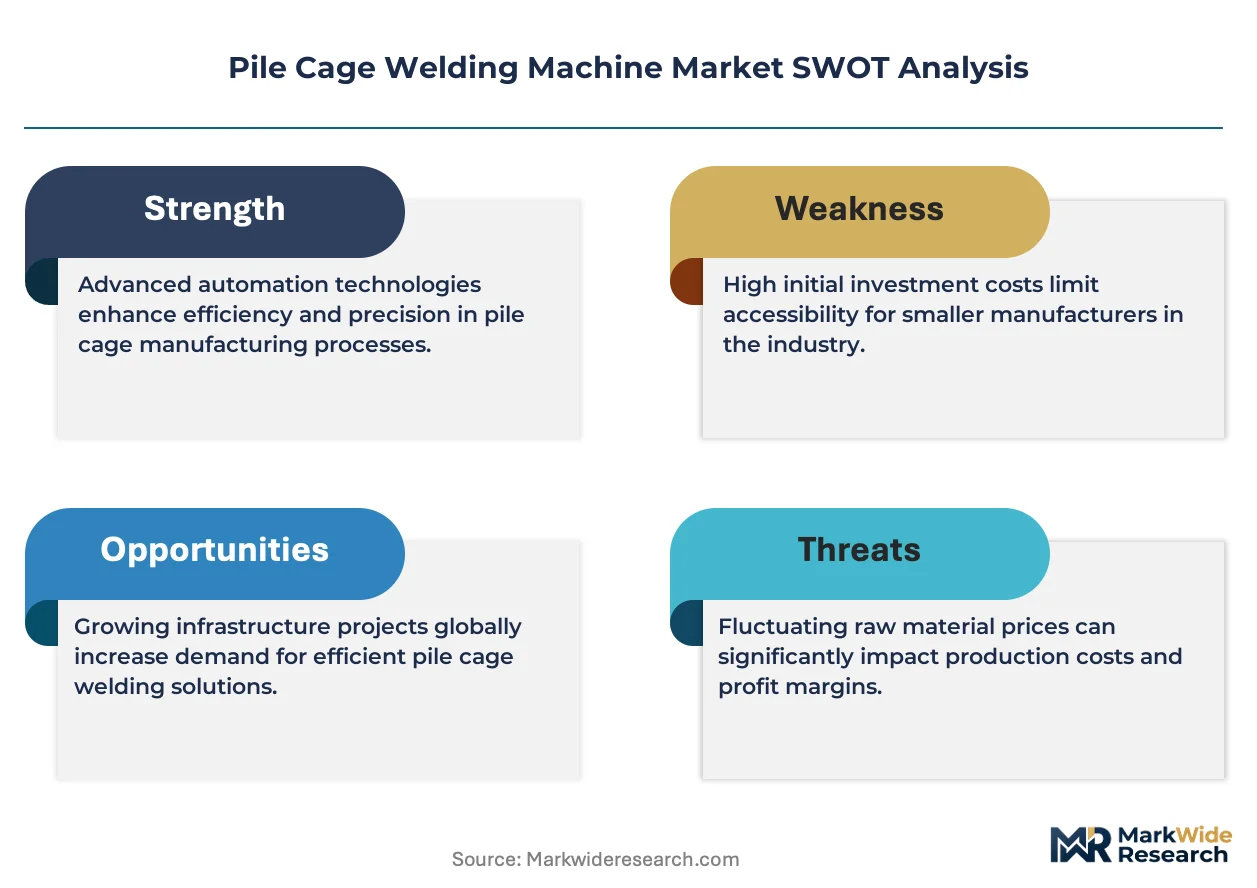
- High-strength steel input volatility:Price swings in thermomechanically treated rebar grades constrain fabricator capex planning for premium laser welding systems.
- German engineering supply concentration:Precision-automatic system component sourcing clusters in Baden-Württemberg, exposing buyers to single-region disruption risk.
- GB standard compliance friction:China's SAMR welding equipment certification timeline extends 8-14 months, delaying foreign manufacturer market entry.
Strategic Opportunities
- Underpenetrated Indian secondary cities:Tier-2 infrastructure hubs in Rajasthan and Madhya Pradesh lack automated pile cage capacity, creating first-mover white space for equipment distributors.
- Laser-resistance hybrid convergence:Systems combining minimal heat-affected zone protection with high throughput open premium positioning for seismic zone contractors.
- EU Green Deal carbon accounting:Energy-efficient welding architectures qualify for preferential procurement scoring in European public foundation tenders.
Industry Challenges
- CNC programming skill scarcity:Bridge contractors in India and China struggle to recruit operators capable of parameter optimization for variable rebar diameters.
- Dual certification burden:Manufacturers serving both EU and Chinese markets must maintain parallel CE marking and GB standard compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pile Cage Welding Machine Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, CNC Technology: Arc Welding, Resistance Welding, Laser Welding, Ultrasonic Welding Application: Bridge Construction, Infrastructure Projects, Building Foundations, Dams End User Industry: Construction Contractors, Steel Fabricators, Civil Engineering Firms, Equipment Rental Services |
| Companies Covered | MBK Maschinenbau GmbH, Schlatter Industries AG, TJK Machinery (Tianjin) Co., Ltd., Progress Maschinen & Automation AG, D.C. Macchine s.r.l., Eurobend S.A., Jiaoyang, XCMG, SANY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pile Cage Welding Machine Market Trends and Innovations
Welding process innovation and procurement model compression are restructuring how pile cage fabrication equipment reaches foundation contractors across infrastructure corridors.
Laser welding technology is collapsing the performance gap between premium seismic-grade systems and standard resistance welding platforms. Japanese dam contractors and German heavy civil specialists are adopting fiber laser configurations for high-strength steel grades requiring minimal heat-affected zones. The technology is collapsing equipment tier boundaries as mid-range buyers gain access to previously premium-only weld integrity specifications.
China's SAMR is tightening GB standard enforcement on welding equipment electromagnetic compatibility and operator safety interlocks. Domestic manufacturers must redesign control architectures to meet revised certification timelines. Indian importers under BIS requirements are responding by pre-certifying equipment configurations before shipment, compressing installation-to-production cycles.
Foundation contractors are consolidating equipment procurement through steel fabricator intermediaries rather than direct manufacturer relationships. This channel compression displaces traditional distributor networks in India's infrastructure corridors and China's provincial state-owned construction groups. Maharashtra-based bridge specialists now specify welding systems through captive rebar suppliers, bundling equipment with long-term material offtake agreements.
Pile Cage Welding Machine Market Segmentation
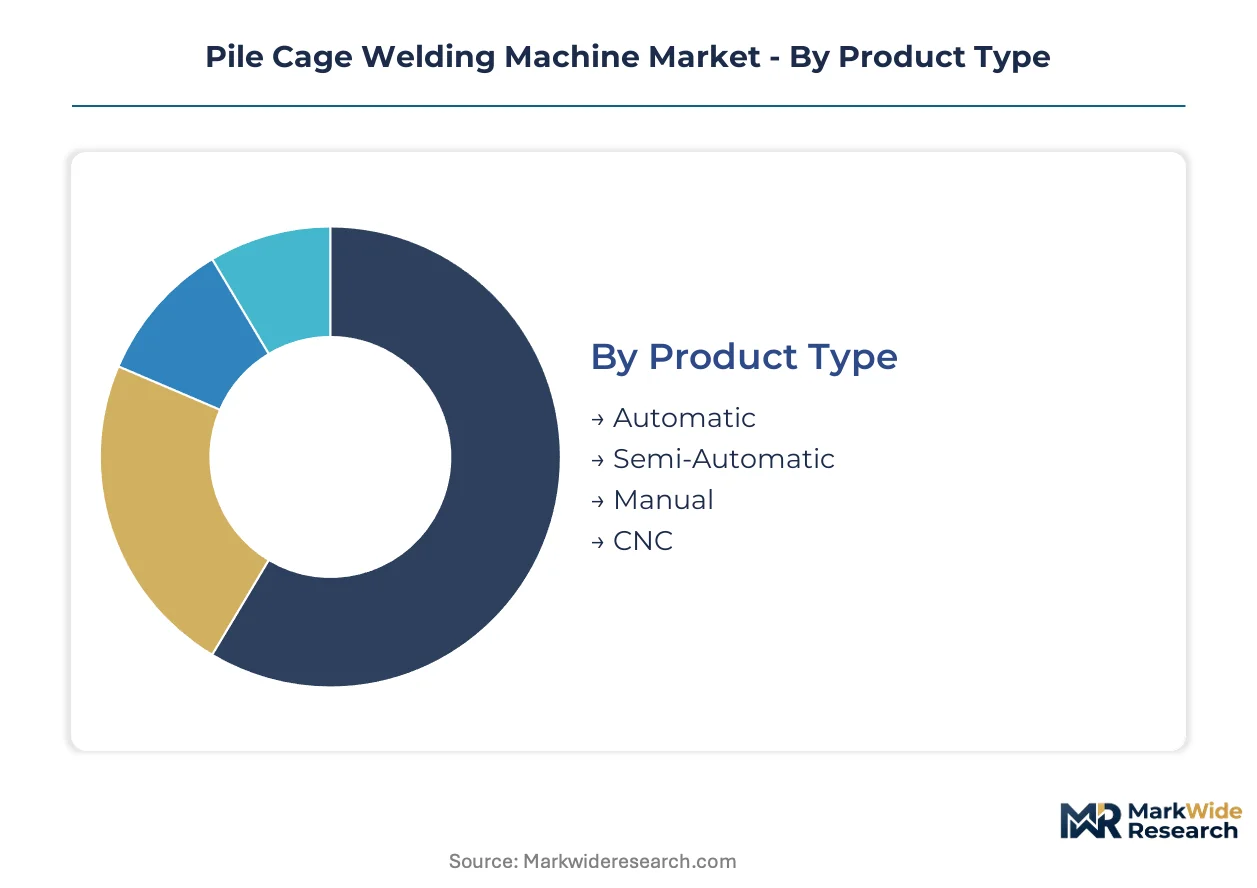
Equipment configuration and welding technology choices in the Pile Cage Welding Machine Market determine maintenance schedules, spare parts inventories, and field service requirements. Segmentation reveals where service intensity concentrates and which buyer profiles prioritize uptime guarantees over acquisition cost.
Product Type:
After-sales-service intensity varies sharply across automation tiers, with CNC and automatic systems requiring specialized technician deployment while manual units need minimal field support.
- Automatic:These systems integrate programmable logic controllers with pneumatic clamping mechanisms for continuous rebar feeding. Bridge contractors in Germany favor automatic configurations under KBA-adjacent safety directives that mandate documented weld traceability, driving replacement demand for older semi-automatic fleets.
- CNC:Computer numerical control architectures enable parameter storage for multiple cage specifications and real-time diameter adjustment. Steel fabricators in Maharashtra and Gujarat are adopting CNC-controlled lines to meet volume targets under India's infrastructure investment programs, though operator training requirements extend commissioning timelines.
- Semi-Automatic:Hybrid systems requiring manual bar loading with automated welding cycle initiation serve smaller fabricators with intermittent production schedules.
- Manual:Hand-operated welding stations persist in rural India's secondary cities where capital constraints outweigh labor cost considerations.
By volume, Automatic leads. By growth pace, CNC is expanding most quickly.
Technology:
Cost tier stratification separates premium laser systems from standard resistance platforms, with arc welding occupying the mid-market and ultrasonic configurations targeting niche applications.
- Resistance Welding:Electric current passing through overlapping rebar sections generates localized heat without filler material, producing consistent fusion at high throughput rates. This technology anchors the largest installed base across China's provincial state-owned construction groups, where GB standard compliance favors proven electromagnetic compatibility profiles.
- Laser Welding:Fiber laser configurations deliver minimal heat-affected zones essential for high-strength steel grades in seismic zone foundations. German heavy civil specialists and Japanese dam contractors are adopting laser systems despite premium pricing, driven by EU Green Deal carbon accounting that rewards energy-efficient weld architectures in public tenders.
- Arc Welding:Consumable electrode processes accommodate variable rebar diameters through parameter adjustment, serving steel fabricators with diverse project portfolios.
- Ultrasonic Welding:High-frequency vibration bonding without bulk heating addresses specialized applications in corrosion-sensitive foundation environments.
By volume, Resistance Welding leads. By growth pace, Laser Welding is gaining share fastest.
Application:
Customer type differentiation separates high-specification bridge work from volume-driven building foundations, with dam applications commanding specialized equipment configurations.
- Bridge Construction:Longitudinal rebar cages exceeding 30 meters in length demand synchronized multi-point welding stations with automated longitudinal travel. Contractors in Germany and China are expanding automated capacity to satisfy stricter rebar quality standards under EU CE marking and Chinese GB standards.
- Building Foundations:High-rise construction requires standardized cage diameters with rapid production turnaround. India's infrastructure corridors concentrate demand here, with government-backed civil engineering projects in Maharashtra requiring higher-volume pile cage production than current domestic capacity supplies.
- Infrastructure Projects:Road and rail corridors generate demand for variable-diameter cages with mobile deployment requirements.
- Dams:Heavy civil applications specify corrosion-resistant weld specifications and oversized rebar handling capacity.
By volume, Building Foundations leads. By growth pace, Bridge Construction is climbing the fastest.
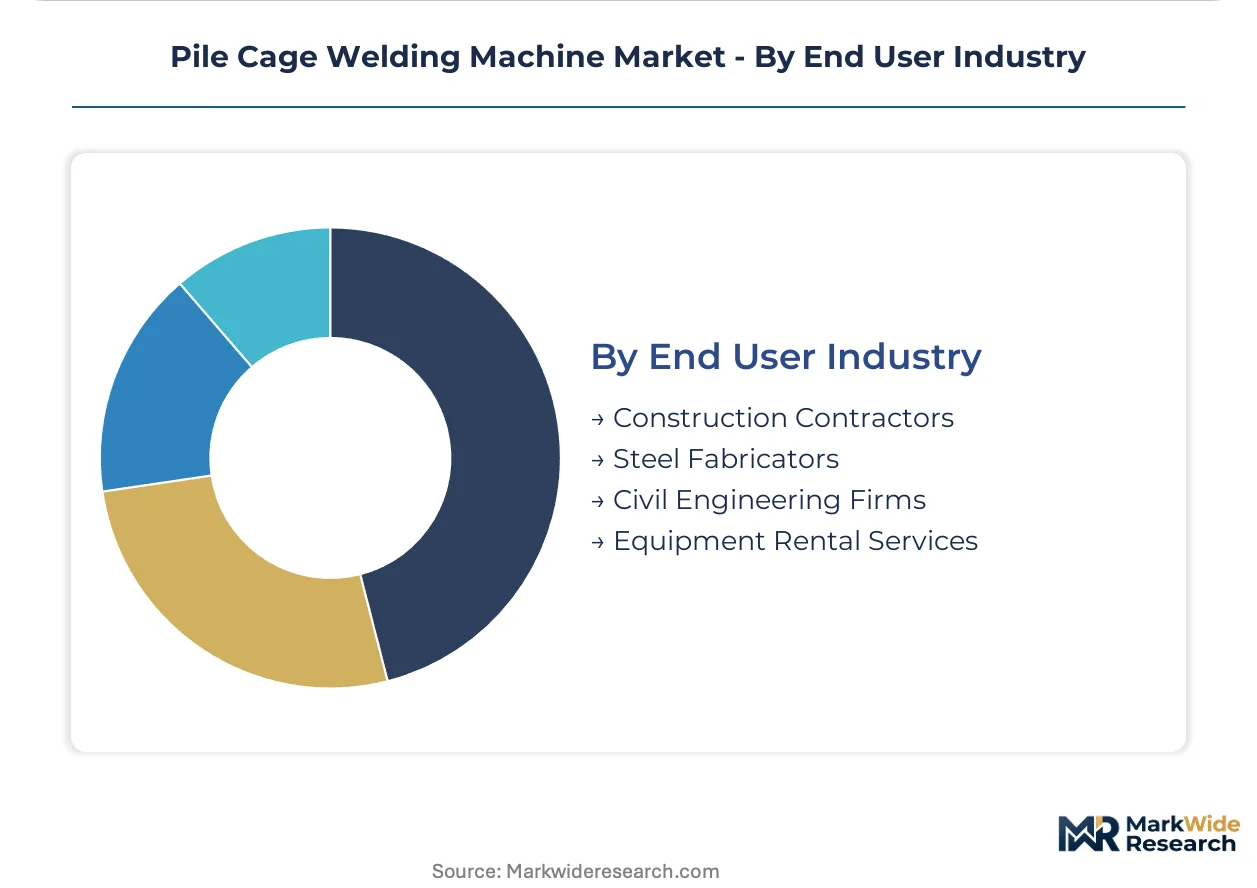
End User Industry:
Supply concentration patterns favor direct manufacturer relationships with construction contractors while steel fabricators increasingly consolidate procurement through bundled equipment-material agreements.
- Construction Contractors:Direct equipment ownership enables schedule control for foundation specialists with continuous project pipelines. German bridge contractors under EU CE marking enforcement must certify rebar weld integrity, forcing replacement of semi-automatic systems with precision-automatic pile cage welding machines.
- Steel Fabricators:Captive rebar suppliers in India and China are bundling welding equipment with long-term material offtake agreements, compressing traditional distributor channels. Maharashtra-based bridge specialists now specify systems through these intermediaries rather than direct manufacturer relationships.
- Civil Engineering Firms:Project-based procurement favors rental or lease arrangements for intermittent foundation work.
- Equipment Rental Services:Fleet operators target Tier-2 infrastructure hubs in Rajasthan and Madhya Pradesh where automated pile cage capacity remains underpenetrated.
By volume, Construction Contractors leads. By growth pace, Steel Fabricators is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision-automatic systems command pricing premiums against Indian volume-tier alternatives, creating a two-speed procurement landscape across foundation engineering corridors.
Germany
Bridge contractors in Baden-Württemberg and North Rhine-Westphalia are replacing semi-automatic fleets under KBA-adjacent machinery safety directives. CE marking enforcement now mandates documented weld traceability for rebar integrity certification. The Stuttgart engineering cluster concentrates precision-automatic system component sourcing, exposing buyers to single-region supply concentration.
China
Provincial state-owned construction groups anchor resistance welding installed base expansion along the Yangtze River Delta infrastructure corridor. SAMR enforces revised GB standards on electromagnetic compatibility and operator safety interlocks, extending certification timelines to 8-14 months for foreign manufacturers. Tianjin-based production lines serve domestic volume requirements under dual-carbon target procurement redirection.
India
Government-backed civil engineering projects in Maharashtra and Gujarat concentrate demand for higher-volume pile cage production than current domestic capacity supplies. BIS certification shapes import flows for contractors under national infrastructure investment programs. Tier-2 hubs in Rajasthan and Madhya Pradesh remain underpenetrated for automated capacity, creating first-mover white space for equipment distributors.
United States
Foundation contractors face OSHA welding fume exposure standards that accelerate CNC-controlled configuration adoption for operator safety compliance. Seismic zone building codes in California and Pacific Northwest states specify minimal heat-affected zone protection for high-strength steel grades. The Southeast construction corridor generates intermittent demand through project-based procurement favoring rental arrangements.
Pile Cage Welding Machine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying pneumatic clamping mechanisms and programmable logic controllers to multiple downstream assemblers. The vendor base stratifies across three tiers: German precision-engineering houses, Chinese scale-driven fabricators, and Italian mid-market specialists serving Mediterranean bridge contractors. Consolidation pressure concentrates among European precision-automatic providers, while Asian markets sustain fragmented competition. Dominant competitive moves include captive rebar supplier bundling agreements and energy-efficient welding architecture development for carbon-accounting procurement scoring.
Within the precision-engineering archetype, MBK Maschinenbau GmbH and Schlatter Industries AG exemplify German platform dominance for bridge foundation applications. TJK Machinery (Tianjin) Co., Ltd. anchors the scale-driven tier serving China's domestic infrastructure build-out. Progress Maschinen & Automation AG occupies a mid-market position between these poles, representing European engineering adapted for variable-diameter cage production.
| Leading Market Players |
|---|
| MBK Maschinenbau GmbH |
| Schlatter Industries AG |
| TJK Machinery (Tianjin) Co., Ltd. |
| Progress Maschinen & Automation AG |
| D.C. Macchine s.r.l. |
| Eurobend S.A. |
| Jiaoyang |
| XCMG |
| SANY |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's precision-automatic component cluster concentrates programmable logic controller and pneumatic clamping mechanism supply, anchoring margin capture with German platform integrators while Chinese scale fabricators compete on configured-to-order cost structures.
Pricing Analysis
Configured-to-order CNC systems command substantial premiums over standard automatic configurations, with pricing stratifying across premium laser welding, mid-tier resistance welding, and economy manual tiers. Price differentiation rests on CE marking certification grade and after-sales service bundling intensity. Cost compression in the manual tier is intensifying because rural Indian fabricators prioritize capital outlay minimization over throughput. Steel fabricators in Maharashtra exhibit highest price sensitivity; German bridge contractors under KBA-adjacent directives show lowest sensitivity due to compliance-driven replacement cycles.
Supply Chain Analysis
Extended payment terms from Tianjin-based production lines are reshaping procurement patterns for provincial state-owned construction groups across China's Yangtze River Delta corridor. Component sourcing draws from Germany for precision controllers, China for structural frames, and Italy for mid-market welding heads. Single-source vulnerability concentrates in Baden-Württemberg's engineering cluster. Distribution runs through steel fabricator intermediaries bundling equipment with rebar offtake agreements, compressing traditional distributor networks in India's infrastructure corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified CNC programming technicians capable of parameter optimization for variable rebar diameters are scarcer than installed base expansion rates, constraining commissioning timelines and aftermarket service scaling across foundation engineering markets.
For Market Incumbents: Harden defensible positioning through backward integration into programmable logic controller supply and captive technician training academies in Maharashtra and Gujarat. Laser-resistance hybrid system development addresses emerging seismic zone specifications. Certification investment for simultaneous CE marking and GB standard compliance documentation mitigates dual-market friction costs. For New Entrants and Emerging Players: Pursue first-mover positioning in Rajasthan and Madhya Pradesh's underpenetrated Tier-2 infrastructure hubs where automated pile cage capacity remains nascent. Equipment rental fleet models targeting intermittent foundation contractors offer lower capital barrier entry than direct sales channels. Pre-certified BIS configurations compress installation-to-production cycles for Indian importers. For Investors and Strategic Acquirers: Capital is best deployed toward precision-automatic specialists with established KBA-adjacent safety directive compliance and documented weld traceability capabilities. Long-term viability across the analysis window favors vendors positioned for EU Green Deal carbon-accounting procurement scoring. Monitor SAMR GB standard enforcement timeline compression as inflection indicator for foreign manufacturer market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Resistance Hybrid System Development | Fiber laser configurations with resistance welding throughput address seismic zone high-strength steel specifications. |
| Captive Rebar Supplier Bundling Agreements | Maharashtra-based bridge specialists now specify welding systems through steel fabricator intermediaries compressing distributor channels. |
| Dual Certification Documentation Investment | Parallel CE marking and GB standard compliance reduces market entry friction for manufacturers serving EU and Chinese contractors. |
| Technician Training Academy Establishment | CNC programming skill scarcity in India and China extends commissioning timelines without qualified operator pipelines. |
| Energy-Efficient Welding Architecture R&D | EU Green Deal carbon accounting rewards low-heat-input systems in European public foundation tenders. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with bridge construction project managers, steel fabricator procurement leads, welding equipment maintenance directors, and aftermarket service heads; and secondary validation through customs/trade data, BIS certification records, SAMR GB standard filings, and EU CE marking documentation. Primary fieldwork centered on foundation engineering corridors in Germany, China, and India. Bottom-up equipment shipment tallies and top-down infrastructure investment pipeline analysis were triangulated against regional regulatory enforcement timelines.
Forecast inputs considered automation tier adoption curves, welding technology substitution rates, and certification compliance cost trajectories across the modeling period. Segmentation dimensions modeled include equipment configuration, welding technology type, application intensity, and end-user procurement channel. CAGRs were derived from infrastructure investment program allocations, rebar demand projections, and replacement cycle analysis for semi-automatic fleet obsolescence. Labor cost pressures and carbon-accounting procurement scoring evolution shaped scenario weightings.
Sensitivities concentrate around SAMR certification timeline compression, EU Green Deal enforcement acceleration, and high-strength steel input cost volatility. Forecasts reflect assumptions on regulatory adherence trajectories and infrastructure program execution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Europe Crane Market
Construction Equipment
Compact Electric Construction Equipment Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Concrete Spreader Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Concrete Placing Booms Market