
 Mining Drill Market | 2026-2036
Mining Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Drill Market Foresight
High-specification drill rigs rated for automated rod handling and real-time telemetry is rotating through the procurement pipeline of tier-one miners. Sandvik AB leverages its digitalization portfolio to sustain premium positioning in autonomous underground drilling. Epiroc AB anchors surface mining contracts across Latin America through its aftermarket service density. Caterpillar Inc. competes on powertrain integration, bundling drills with site-wide fleet management systems.
A mining drill is a mechanized boring apparatus engineered to penetrate rock formations at depths from tens to thousands of meters, typically delivering torque outputs exceeding 20,000 Nm and operating at rotational speeds calibrated to formation hardness. Its primary purpose is to create blastholes for ore fragmentation, core samples for resource estimation, or ventilation and drainage shafts. Rotary drills dominate surface operations where large-diameter production holes justify capital intensity, while percussive and DTH drills retain structural importance in hard-rock underground headings where penetration rate determines stope economics. Electric and hybrid technology segments are capturing margin pools as diesel cost volatility and ventilation constraints reshape total cost of ownership calculations.
The US EPA Tier-4 Final framework and the EU Green Deal's machinery decarbonization pathways are accelerating capital redeployment toward lower-emission platforms. ISO 18758 and national mine safety inspectorates in Australia, Canada, and Chile mandate operator protection and noise suppression standards that filter out lower-specification imports. Stakeholders must weigh captive maintenance infrastructure against technology migration timelines as electrification architectures diverge from legacy diesel supply chains.
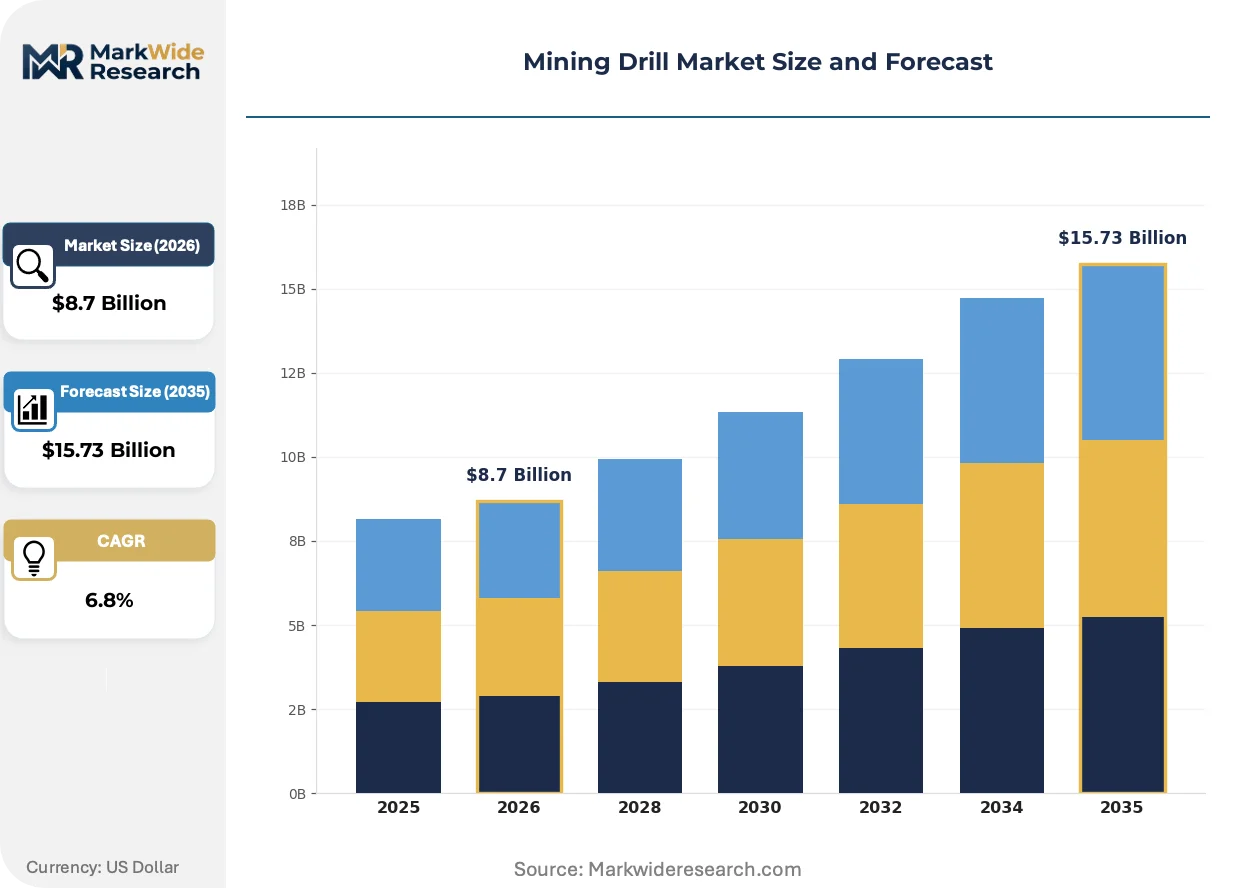
Market Dynamics
Electrification of underground drill fleets is compressing replacement cycles as ventilation costs and diesel price volatility rewrite total cost of ownership equations for hard-rock miners.
Growth Catalysts
- EPA Tier-4 Final:North American surface operations face mandatory diesel particulate filter retrofits, accelerating capital redeployment toward hybrid-electric rotary platforms.
- Pit deepening in Chilean copper districts:High-torque autonomous drills with real-time telemetry penetration rates now determine stope economics in the Atacama cluster.
- Automated rod handling:Tier-one miners specify hands-free rod exchange systems to eliminate operator exposure in unstable ground conditions.
Market Restraints
- High-voltage battery supply concentration:Lithium-ion cell production for 1,000V underground platforms concentrates in East Asian suppliers, exposing fleet operators to geopolitical supply interruptions.
- Legacy maintenance infrastructure:Captive diesel service depots in Australian coal basins resist write-downs as electrification architectures diverge from existing technician skill bases.
- ISO 18758 compliance costs:Noise suppression and operator protection mandates filter out lower-specification import rigs from emerging Asian manufacturers.
Strategic Opportunities
- EU Green Deal machinery decarbonization:Carbon border adjustment mechanisms create premium pricing power for OEMs offering battery-electric surface drill rigs with verified lifecycle emissions data.
- Aftermarket unbundling:Component-level sensor subscriptions enable predictive maintenance revenue streams independent of original equipment sales in Peruvian and Mexican mining corridors.
- Dual-motor rotary head convergence:Synchronous permanent magnet motors paired with silicon carbide inverters enable torque density gains that penetrate harder abrasive formations.
Industry Challenges
- High-voltage technician scarcity:Underground operations in Canada and Australia lack certified electricians capable of servicing 1,500V DC traction systems, extending mean time to repair.
- Interoperability gaps:Proprietary fleet management protocols from incumbent OEMs block third-party automation software integration, fragmenting mine-wide coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Drill Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Drills, Percussive Drills, DTH Drills, Continuous Miners Technology: Electric, Diesel, Hybrid, Pneumatic End User: Coal Mining, Metal Mining, Mineral Exploration, Quarrying Deployment: Underground, Surface, Highwall, Open-pit |
| Companies Covered | Epiroc AB, Sandvik AB, Atlas Copco AB, Caterpillar Inc., Boart Longyear Ltd., Komatsu Ltd., Robit Plc, Mincon Group PLC, Mitsubishi Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Drill Market Shifts & Advancements
Drill rig architectures are splitting between surface bulk-commodity automation and underground precision electrification, with each trajectory demanding incompatible engineering investments from suppliers.
Hybrid-electric powertrains are bifurcating the product landscape. Surface rotary drills above 250mm diameter now standardize on diesel-electric gensets for tramming and grid-tied cable operation during production drilling. Underground jumbo fleets in Canadian base metal mines adopt full battery-electric propulsion to eliminate diesel particulate exposure. This divergence is compressing R&D budgets as engineering teams must maintain parallel development tracks for incompatible energy architectures.
REACH machinery substance restrictions and the EU Green Deal's embedded carbon reporting requirements are forcing OEMs to disclose full supply chain emissions for steel castings and hydraulic fluids. European surface mining contractors now specify drills with Environmental Product Declarations verified under EN 15804. German and Swedish quarry operators delay procurement decisions pending third-party lifecycle assessments, extending sales cycles by four to six months.
Service contracting is unbundling from equipment sales. Chilean copper majors now separately negotiate telemetry subscriptions, consumables logistics, and technician dispatch under performance-based availability guarantees. Sandvik and Epiroc compete on mean time between failure metrics rather than capital cost. Peruvian gold operators pilot usage-based billing where drill meterage triggers automatic spare parts replenishment through integrated ERP systems.
Mining Drill Market Segmentation
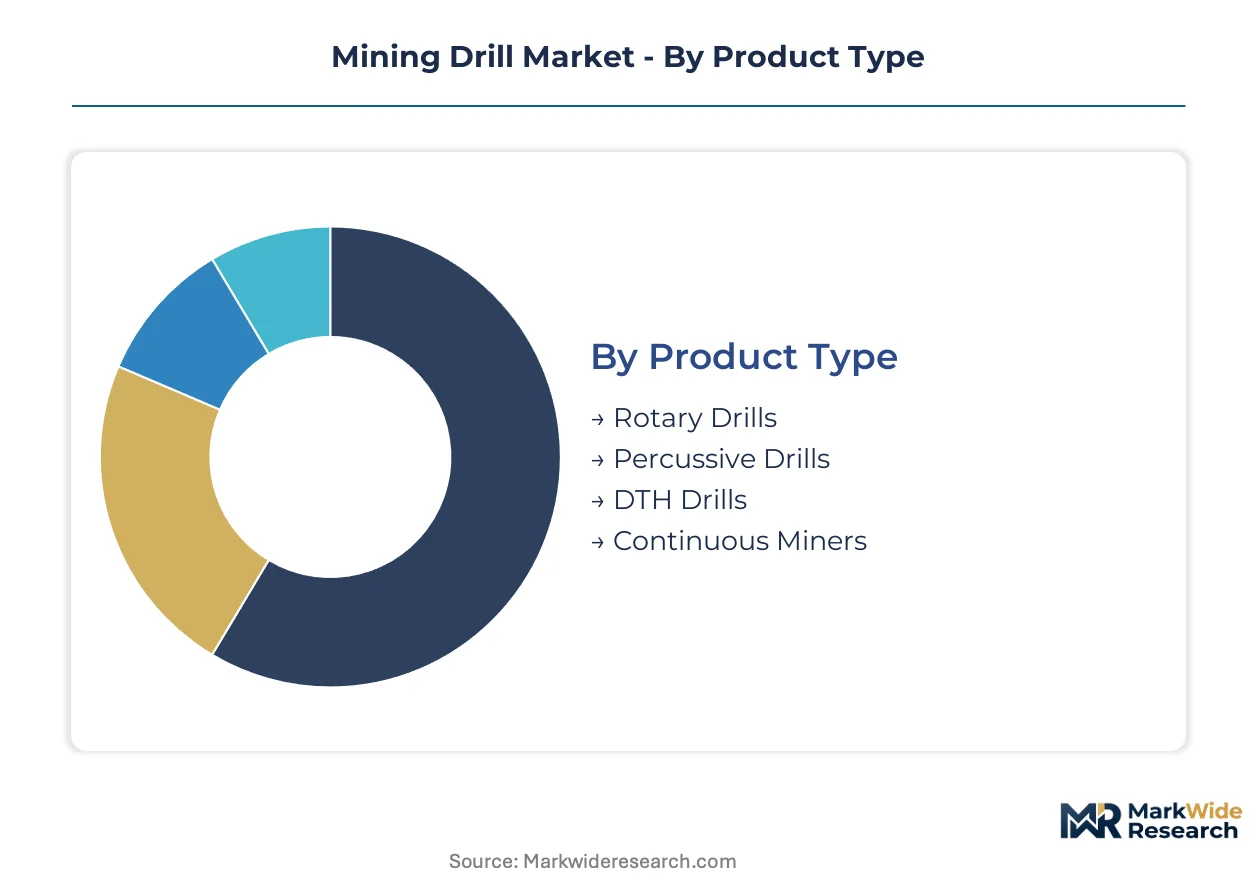
Mining drill procurement splits across incompatible energy architectures and deployment contexts, forcing OEMs to maintain parallel engineering tracks. Segment boundaries determine service infrastructure requirements, technician training pathways, and aftermarket revenue durability.
Product Type:
Margin pools concentrate in high-torque rotary platforms where pit deepening and automation specifications sustain premium pricing.
- Rotary Drills:Diesel-electric gensets power these units for tramming, with grid-tied cable operation during production drilling in Chilean copper districts. Australian iron ore operators specify automated rod handling and real-time telemetry to eliminate exposure in unstable ground.
- Percussive Drills:Piston-driven impact mechanisms deliver high-frequency blows for hard-rock penetration in Canadian base metal headings. Ventilation cost pressures and diesel particulate exposure risks are compressing replacement cycles toward battery-electric alternatives.
- DTH Drills:Down-the-hole hammers with high-pressure air flushing dominate abrasive formations in Peruvian gold corridors.
- Continuous Miners:These integrate cutting, loading, and hauling in a single pass for room-and-pillar coal extraction in Appalachian basins.
Rotary drills hold installed capacity across surface operations. Percussive drills are rotating up the share rankings in electrification-focused jurisdictions.
Technology:
Customer procurement patterns now diverge sharply between surface bulk-commodity automation and underground precision electrification.
- Electric:Grid-tied cable systems eliminate onboard fuel storage and exhaust treatment complexity in fixed-pit surface operations. German quarry operators now delay procurement pending EN 15804-verified Environmental Product Declarations.
- Diesel:Tier-4 Final particulate filter retrofits face mandatory compliance timelines under EPA frameworks, accelerating capital redeployment.
- Hybrid:Dual-mode architectures pair diesel-electric gensets for mobility with shore power during drilling, capturing share in transitional mine sites.
- Pneumatic:Compressed air systems retain niche importance in gassy underground environments where spark suppression is paramount.
Electric platforms command the steepest expansion trajectory in ventilation-constrained jurisdictions. Hybrid systems bridge the technology migration gap for fleet operators with captive diesel infrastructure.
End User:
Application context dictates torque specifications, automation requirements, and regulatory exposure intensity.
- Coal Mining:Room-and-pillar and longwall operations in Australian basins drive equipment replacement cycles, though captive diesel service depots resist write-downs.
- Metal Mining:Copper, gold, and base metal extraction in Chile, Peru, and Canada demands high-torque autonomous drills with penetration rate optimization.
- Mineral Exploration:Core sampling rigs for resource estimation prioritize portability and rapid site relocation.
- Quarrying:Swedish and German aggregate producers specify noise suppression and embedded carbon reporting under EU Green Deal pathways.
Metal mining absorbs the majority of high-specification autonomous capacity. Coal mining is rotating up the share rankings for electrification retrofits as ventilation economics shift.
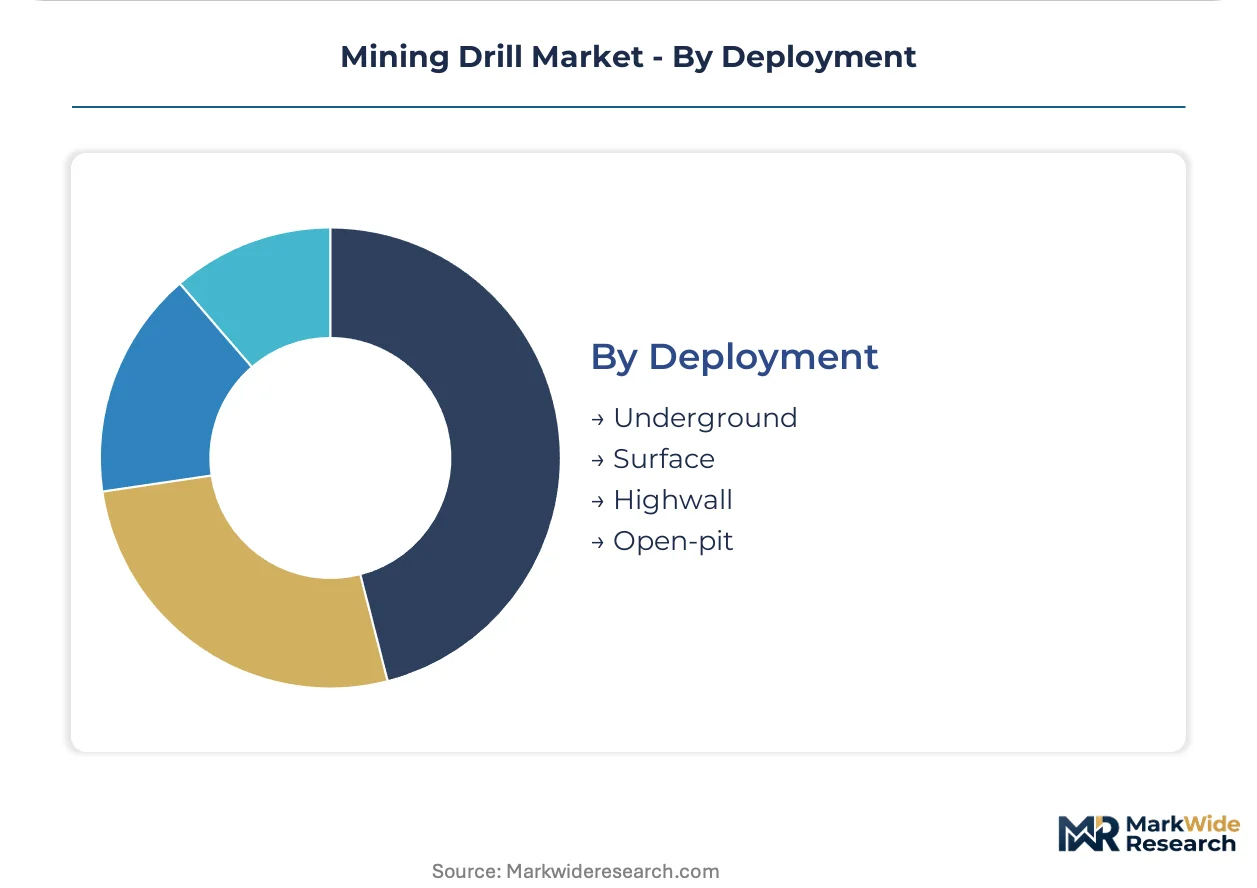
Deployment:
Physical operating environment determines powertrain architecture, operator protection standards, and maintenance infrastructure requirements.
- Underground:Confined headings with ventilation constraints favor battery-electric propulsion to eliminate diesel particulate exposure in Canadian and Australian hard-rock mines.
- Surface:Open terrain permits larger-diameter rotary platforms with diesel-electric gensets and grid-tied cable options.
- Highwall:Contour mining applications along exposed coal seams require specialized mobility and stability systems.
- Open-pit:Large-scale bulk commodity extraction in Chilean Atacama cluster specifications center on autonomous tramming and production drilling integration.
Surface deployment holds installed capacity across mature mining districts. Underground deployment is rotating up the share rankings as electrification compresses replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy fabrication centers in Sweden and Finland supply rotary drill components to Chilean copper districts, while Australian underground operations import battery-electric platforms from Canadian engineering hubs. Trade flows concentrate high-torque equipment toward metal-rich jurisdictions with deepening pit economics.
Australia
Queensland and Western Australian coal basins drive equipment replacement cycles as captive diesel service depots resist write-downs. The country's national mine safety inspectorate mandates ISO 18758 compliance for operator protection and noise suppression. Bowen Basin operators specify automated rod handling systems to eliminate exposure in unstable ground conditions.
Chile
Atacama copper districts demand high-torque autonomous drills with real-time telemetry as pit deepening rewrites stope economics. The national mining regulator enforces ventilation standards that compress replacement cycles toward electrified platforms. Antofagasta cluster procurement concentrates on penetration rate optimization for abrasive formations.
Canada
Ontario and Quebec base metal mines adopt full battery-electric propulsion to eliminate diesel particulate exposure in confined headings. Health Canada and provincial mining inspectorates align with EPA Tier-4 Final frameworks for cross-border fleet standardization. Sudbury Basin operations face technician scarcity for 1,500V DC traction system maintenance.
United States
Appalachian coal corridors and Southwest copper districts face mandatory diesel particulate filter retrofits under EPA Tier-4 Final timelines. The regulatory framework accelerates capital redeployment toward hybrid-electric rotary platforms. Arizona open-pit operations specify grid-tied cable systems for fixed-pit production drilling.
Germany
Quarry operators in Bavaria and North Rhine-Westphalia delay procurement pending EN 15804-verified Environmental Product Declarations under EU Green Deal pathways. REACH machinery substance restrictions force OEM supply chain emissions disclosure for steel castings. Ruhr aggregate producers specify drills with embedded carbon reporting requirements.
Mining Drill Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and aftermarket service density. The vendor base clusters around three tiers: integrated mining equipment conglomerates with powertrain bundling capabilities, pure-play drilling specialists with telemetry subscription models, and regional fabricators serving captive maintenance infrastructure. Consolidation pressure concentrates in the mid-tier as electrification architectures demand incompatible R&D investments. Competitive moves center on aftermarket unbundling and dual-motor rotary head convergence for torque density gains.
Within the integrated equipment tier, Sandvik AB and Caterpillar Inc. exemplify divergent strategic positioning. Sandvik anchors premium positioning through digitalization portfolios and autonomous underground drilling capabilities. Caterpillar occupies a scale-driven position bundling drills with site-wide fleet management systems. Epiroc AB represents the pure-play specialist archetype, sustaining Latin American surface mining contracts through aftermarket service density and performance-based availability guarantees.
| Leading Market Players |
|---|
| Epiroc AB |
| Sandvik AB |
| Atlas Copco AB |
| Caterpillar Inc. |
| Boart Longyear Ltd. |
| Komatsu Ltd. |
| Robit Plc |
| Mincon Group PLC |
| Mitsubishi Materials Corporation |
| Others |
Supply & Pricing Matrix
EPA Tier-4 Final compliance gates both supplier qualification and price differentiation simultaneously, filtering out lower-specification import rigs while creating three distinct pricing tiers based on emissions certification level and automation integration depth. Chilean copper majors and Australian coal operators now demand verified lifecycle emissions data and automated rod handling systems, compressing margins for uncertified fabricators while sustaining premium pricing for compliant OEMs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the mining drill market. Price differentiation stems from ISO 18758 certification grade and aftermarket service bundling density, with autonomous telemetry integration commanding substantial premiums. Pricing pressure stems from high-voltage battery supply concentration in East Asian suppliers, compressing margins for electrification-focused fleet operators. Tier-one miners exhibit lowest price sensitivity due to ventilation cost savings from electrification, while emerging market quarry operators remain most price-sensitive.
Supply Chain Analysis
Extended lead times for silicon carbide inverters and lithium-ion traction cells are stretching order-to-delivery cycles for underground battery-electric platforms. Manufacturing concentrates in Sweden, Finland, and Germany for rotary drill components, while East Asian suppliers dominate high-voltage battery cell production. Raw material dependencies include rare earth permanent magnets, high-grade steel castings, and copper winding stock. Single-source vulnerability for 1,000V battery systems exposes fleet operators to geopolitical supply interruptions. Distribution runs through OEM-direct channels with embedded service contracts, supplemented by regional aftermarket parts depots in mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
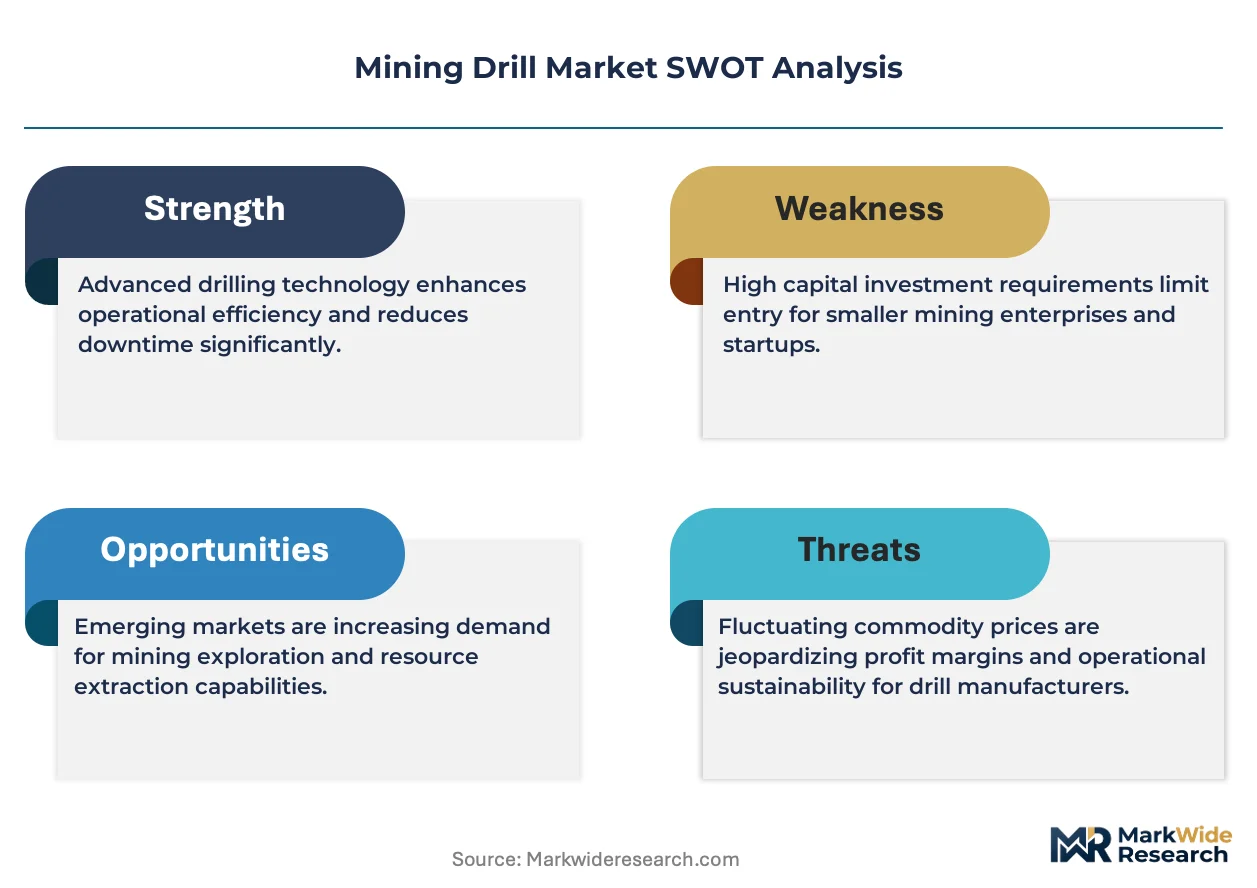
The mining drill market operates as a defensive-moat industry where regulatory entrenchment through EPA Tier-4 Final and ISO 18758 certification creates substantial switching costs for fleet operators. Captive maintenance infrastructure and technician training pathways lock buyers into incumbent relationships.
For Market Incumbents: Secure aftermarket unbundling revenue through component-level sensor subscriptions and predictive maintenance platforms, insulating against price erosion in equipment sales. Deepen backward integration into high-voltage battery pack assembly to reduce exposure to East Asian cell supply concentration. Anchor positioning through dual-motor rotary head convergence for torque density gains in abrasive formations. For New Entrants and Emerging Players: Lead with aftermarket service density in Peruvian and Mexican gold corridors where incumbent coverage gaps persist. Target battery-electric retrofits for Australian coal basins where captive diesel infrastructure resists full fleet replacement. Develop usage-based billing models tied to drill meterage with integrated ERP replenishment systems. For Investors and Strategic Acquirers: EPA Tier-4 Final enforcement timelines reshape the acquisition landscape toward electrification-ready asset bases with certified technician pipelines. Long-term viability centers on OEMs with demonstrated mean time between failure metrics and performance-based availability guarantees. Monitor high-voltage technician certification rates in Canadian and Australian mining jurisdictions as inflection indicators for electrification adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Motor Rotary Head Convergence | Synchronous permanent magnet motors paired with silicon carbide inverters penetrate harder abrasive formations in Chilean copper districts. |
| Aftermarket Unbundling | Component-level sensor subscriptions enable predictive maintenance revenue streams independent of original equipment sales. |
| Battery-Electric Platform Migration | Full electrification eliminates diesel particulate exposure in confined Canadian and Australian underground headings. |
| Backward Integration into Battery Assembly | In-house high-voltage pack production reduces geopolitical exposure to East Asian lithium-ion cell concentration. |
| EU Green Deal Compliance Certification | EN 15804-verified Environmental Product Declarations unlock premium pricing in German and Swedish quarry markets. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads, and refined through secondary validation across SEC filings, customs and trade data, mining equipment registration databases, and national mine safety inspectorate compliance records. Bottom-up triangulation across equipment unit economics and top-down validation against regional mining capex cycles ensured analytical robustness.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects and replacement cycle timing. The analytical framework models segmentation across energy architecture, deployment context, end-use application, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and electrification penetration curves, with specific inputs including pit deepening economics in Chilean copper districts and ventilation cost trajectories in Canadian base metal mines.
The analysis sits within stated boundaries; outcomes outside sustained copper price levels and stable East Asian battery supply chains would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and fleet operator technology migration willingness. Revision becomes warranted when high-voltage technician certification rates or lithium-ion cell supply concentration crosses critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Africa Mining Market
Mining Equipment
Logging Cable Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Mining Tester Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Excavator Drill Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Barite Crusher Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Smart Mining Market
Mining Equipment
Global Dozers Market