
 Air Hammer Market | 2026-2036
Air Hammer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Hammer Market Analytics
Buyer concentration in the construction sector is broadening as mid-tier contractors and specialty demolition firms enter the procurement pool alongside established infrastructure conglomerates. Atlas Copco leverages its compressor-to-tool ecosystem to lock in fleet customers across developing markets. Ingersoll Rand anchors North American distribution through industrial supply houses and rental channel partnerships. Robert Bosch GmbH competes on cordless integration, bridging battery platforms between rotary tools and compact pneumatic hammers.
An air hammer is a percussive power tool driven by compressed air that delivers repeated piston strikes through a chisel or bit attachment, typically operating at blow rates between 2,000 and 3,000 impacts per minute for material removal, riveting, or surface preparation tasks. Pneumatic hammers retain the largest installed base but battery-powered variants are capturing fastest growth as jobsite electrification eliminates compressor logistics. Chisel hammers dominate automotive repair shops where precision metal forming commands premium pricing, while demolition hammers generate the deepest margin pools in heavy-duty applications where tool life and service contracts matter most.
OSHA enforces permissible exposure limits for hand-arm vibration that compel manufacturers to redesign damping systems and trigger mechanisms for US-market tools. The EU Machinery Directive and CE marking requirements impose additional conformity costs that filter smaller exporters from European distribution channels. Stakeholders must monitor how battery chemistry improvements and tightening silica dust regulations reshape the tradeoff between pneumatic reliability and cordless mobility.
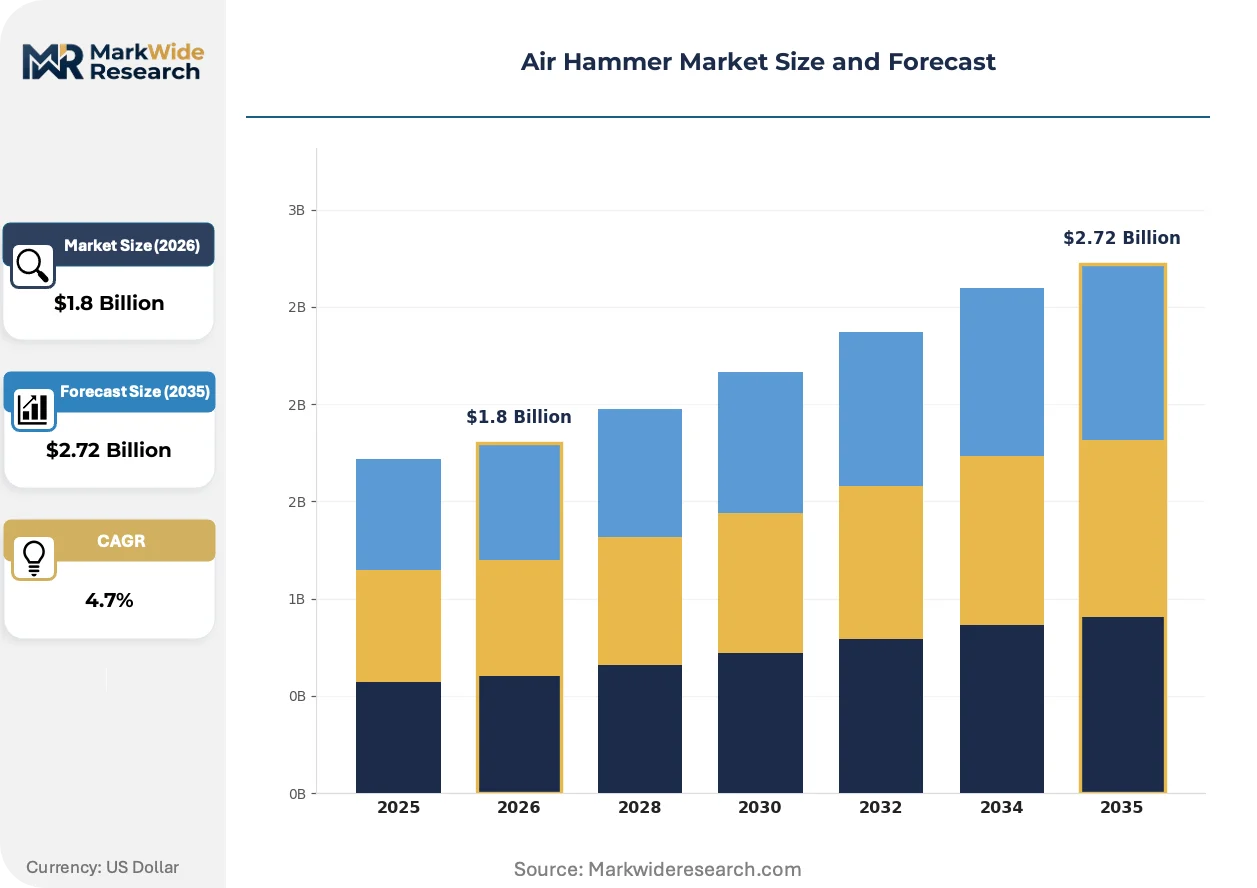
Market Dynamics
The air hammer market is bifurcating between pneumatic reliability and cordless mobility as compressed-air infrastructure costs clash with jobsite electrification mandates. Battery chemistry improvements and tightening hand-arm vibration limits are forcing simultaneous redesigns of power delivery and ergonomic systems.
Growth Catalysts
- India's infrastructure buildout:Government-led highway and urban rail projects are accelerating equipment procurement from construction contractors and demolition specialists.
- OSHA vibration exposure limits:Tighter enforcement of permissible hand-arm vibration thresholds compels manufacturers to invest in damping system innovation for US-market compliance.
- Battery platform convergence:Shared battery ecosystems across rotary tools and compact pneumatic hammers are reducing total cost of ownership for fleet operators.
Market Restraints
- Compressor logistics burden:Pneumatic hammers require portable compressed-air infrastructure that adds transport cost and setup time versus cordless alternatives.
- EU Machinery Directive compliance costs:CE marking requirements and conformity assessment expenses filter smaller exporters from European distribution channels.
- Lithium-ion substitution pressure:Battery-powered variants are capturing fastest growth segments as electrification eliminates pneumatic maintenance cycles.
Strategic Opportunities
- Service contract bundling:Tool life guarantees and predictive maintenance packages generate recurring revenue pools in heavy-duty demolition applications.
- Silica dust regulation tailwinds:Tightening occupational exposure limits for respirable crystalline silica create demand for integrated dust extraction systems.
- Specialty automotive repair:Precision metal forming in chassis restoration shops commands premium pricing for chisel hammer configurations.
Industry Challenges
- Vibration measurement certification:ISO 5349 compliance testing extends product development timelines and requires specialized laboratory accreditation.
- Legacy fleet interoperability:Battery platform fragmentation complicates fleet standardization for rental houses and multi-site contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Hammer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Hammers, Chisel Hammers, Demolition Hammers, Operator-Controlled Hammers End User: Construction Industry, Automotive Repair Shops, Metal Fabrication, DIY Enthusiasts Tool Size: Compact, Standard, Heavy-Duty, Extra Large Power Source: Compressor-Powered, Electric-Powered, Battery-Powered, Manual |
| Companies Covered | Atlas Copco, Ingersoll Rand, Robert Bosch GmbH, Chicago Pneumatic, DEWALT, Makita Corporation, Hilti Corporation, NPK Construction Equipment Inc, Snap-on, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Hammer Market Evolving Landscape
Active vibration control and battery thermal management are converging to redefine ergonomic performance benchmarks. These developments are compressing the traditional tradeoff between pneumatic durability and cordless convenience.
Active vibration damping technology is integrating piezoelectric sensors and counterbalance mechanisms to reduce transmitted hand-arm acceleration. Automotive repair shops and precision metalworking facilities are adopting these systems fastest to meet internal occupational health targets. The technology is integrating real-time feedback loops that automatically adjust piston stroke dynamics based on material resistance.
The EU Machinery Directive's 2023 update tightened noise emission thresholds and expanded documentation requirements for portable power tools. Manufacturers must now submit extended technical files covering full lifecycle environmental impact assessments. Heavy-duty demolition hammer categories face the steepest compliance burden, with several mid-tier suppliers withdrawing from European distribution rather than absorbing conformity costs.
Rental channel penetration is accelerating as contractors prioritize operational flexibility over capital deployment. Industrial supply houses and equipment rental networks are displacing direct OEM sales for mid-tier construction applications. This pattern is most visible in North American infrastructure projects where project duration uncertainty favors short-term equipment access over fleet ownership.
Air Hammer Market Segmentation
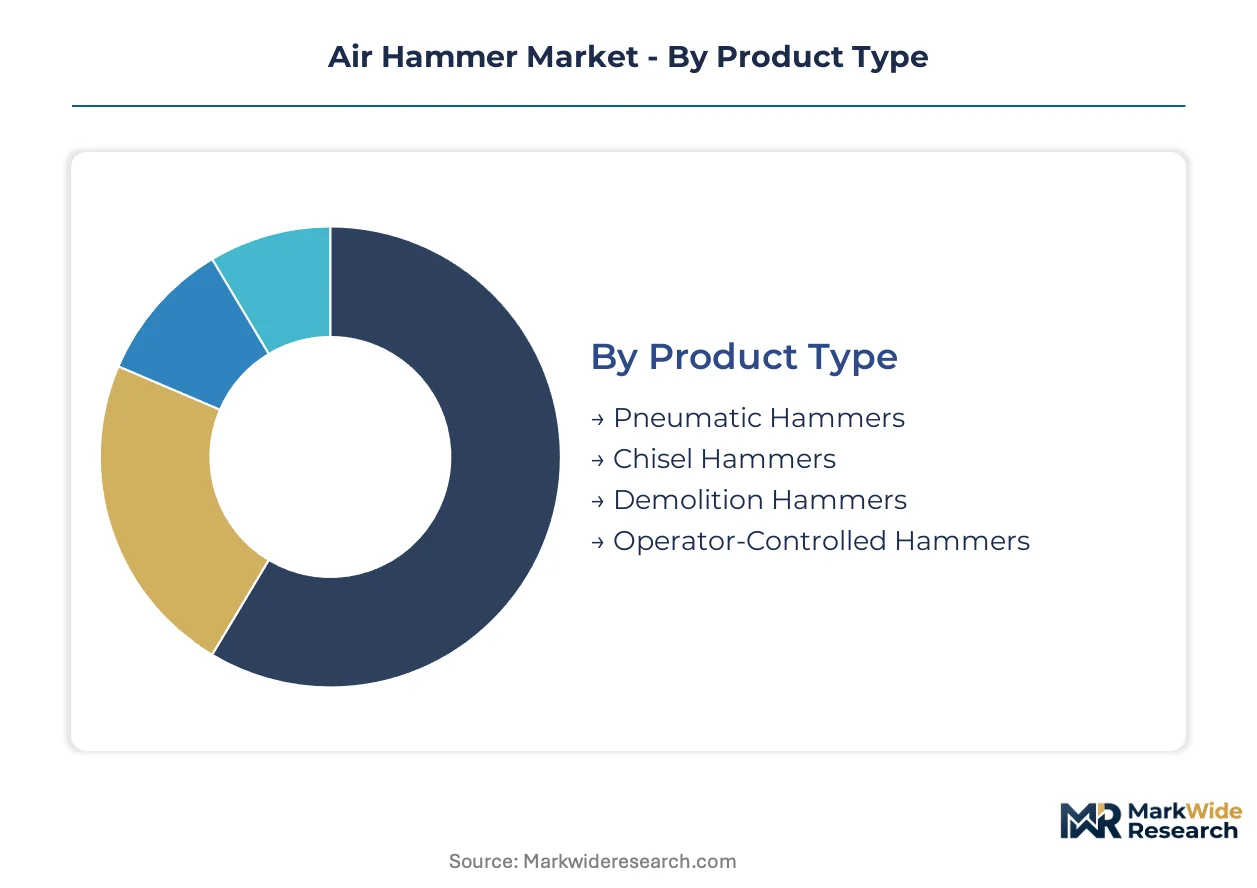
Segmentation in the air hammer market reveals how capital deployment, operator skill requirements, and jobsite infrastructure shape procurement patterns. Contractors and fleet managers use these categories to match tool specifications to project duration, material hardness, and compressor availability.
Product Type:
Pneumatic hammers and demolition hammers demand the heaviest upfront capital outlays due to compressor infrastructure and reinforced housing requirements. Chisel hammers and operator-controlled variants require lower initial investment but carry higher per-unit precision engineering costs.
- Pneumatic Hammers:These tools rely on compressed air systems delivering 90-100 PSI through reinforced hoses, with piston-cylinder assemblies rated for continuous duty cycles. Demand concentrates in Indian highway construction where government infrastructure budgets fund fleet-scale compressor deployments alongside tool procurement. The segment faces substitution pressure from battery alternatives as electrification mandates spread across European jobsites.
- Demolition Hammers:Heavy-duty frames accommodate 2,000-3,000 BPM impact rates with extended piston strokes for concrete fracturing and structural dismantling. German rental houses and North American demolition specialists drive demand through service-contract bundling that guarantees tool life and predictive maintenance coverage. OSHA vibration exposure limits compel manufacturers to integrate active damping systems, extending development timelines and certification costs.
- Chisel Hammers:Precision metal forming tools with reduced stroke lengths for automotive panel work and riveting operations.
- Operator-Controlled Hammers:Variable-speed triggers and ergonomic grips for specialty fabrication tasks requiring manual feed control.
Most installed capacity flows through Pneumatic Hammers. Expansion is steepest in Demolition Hammers.
End User:
Construction industry procurement operates at the highest volume tiers, while automotive repair shops concentrate spending in premium precision segments. Metal fabrication and DIY channels fragment across price-performance tradeoffs.
- Construction Industry:Infrastructure conglomerates and mid-tier contractors in India deploy fleet-scale hammer arrays for highway and urban rail projects. Government procurement mandates favor domestic manufacturing partnerships, compressing margins for imported equipment.
- Automotive Repair Shops:Chassis restoration specialists in Germany and the United States command premium pricing for precision metal forming tools with integrated vibration damping. These operators prioritize occupational health compliance over capital cost minimization.
- Metal Fabrication:Job shops and production facilities balancing throughput requirements against tooling flexibility.
- DIY Enthusiasts:Hobbyist and residential users driving compact tool demand through retail and e-commerce channels.
Construction Industry absorbs the largest unit volumes. Automotive Repair Shops generate the deepest margin pools.
Tool Size:
Heavy-duty and extra-large configurations require substantial capital commitments for reinforced frames and high-capacity power systems. Compact and standard sizes spread investment across broader unit bases with faster replacement cycles.
- Heavy-Duty:Reinforced housings and extended piston strokes for continuous concrete demolition and structural steel preparation. Indian infrastructure contractors favor this tier for highway bridge dismantling and rail bed preparation where tool longevity outweighs portability concerns.
- Compact:Reduced-weight configurations for overhead work and confined-space access in automotive repair and residential renovation. Battery platform convergence enables these tools to share power systems with rotary drills and impact drivers, lowering total cost of ownership for fleet operators.
- Standard:Mid-range specifications balancing power output with operator maneuverability for general construction tasks.
- Extra Large:Specialized frames for industrial demolition and mining applications requiring extended duty cycles.
Standard sizes dominate current installed base. Compact configurations are climbing the fastest as electrification eliminates compressor logistics.
Power Source:
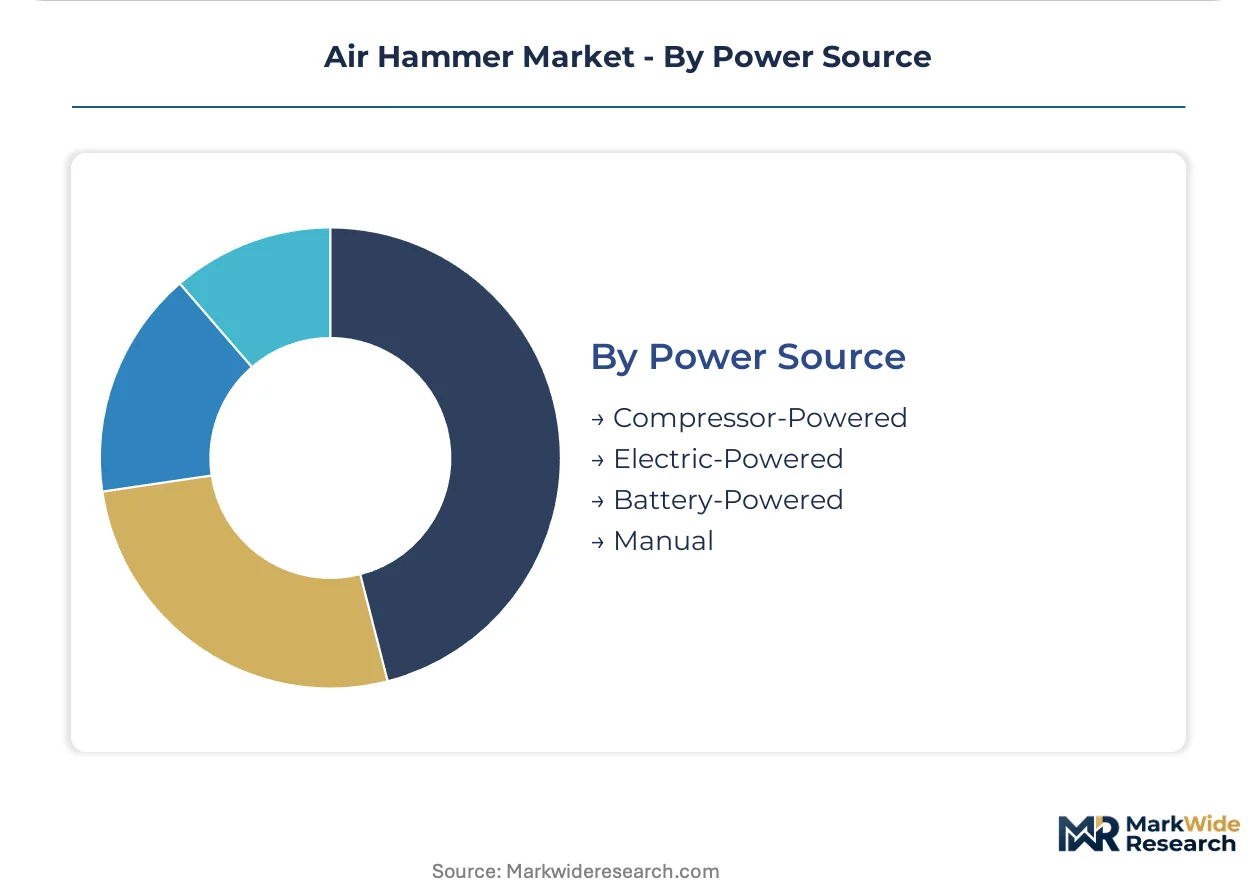
Compressor-powered systems lock in the highest capital intensity through fixed infrastructure investments. Battery-powered alternatives shift spending toward recurring cell replacement and thermal management systems.
- Compressor-Powered:Pneumatic systems delivering consistent torque across temperature extremes and contaminated environments. Indian construction sites and German industrial facilities maintain this installed base despite electrification trends, valuing reliability over portability where compressor infrastructure already exists.
- Battery-Powered:Lithium-ion platforms with integrated thermal management and shared ecosystems across cordless tool portfolios. North American rental channels and European jobsites with strict emissions mandates drive fastest adoption as battery chemistry improvements close the performance gap with pneumatic alternatives.
- Electric-Powered:Corded configurations for stationary fabrication work with continuous power availability.
- Manual:Non-powered striking tools for precision tasks and backup redundancy in remote locations.
Compressor-Powered retains the largest installed base. Battery-Powered is gaining share fastest as silica dust regulations and electrification mandates reshape jobsite power planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's infrastructure acceleration contrasts with Germany's rental-driven equipment turnover, revealing how public investment versus private fleet management shapes distinct procurement rhythms across major markets.
United States
OSHA vibration exposure limits drive damping system redesigns for construction contractors and demolition specialists. The Department of Labor enforces permissible hand-arm vibration thresholds that extend product development timelines. Texas and Florida infrastructure corridors concentrate heavy-duty hammer deployment for highway bridge rehabilitation.
Germany
EU Machinery Directive compliance costs filter smaller exporters while CE marking requirements reshape distribution channels. The 2023 directive update tightened noise emission thresholds and expanded lifecycle documentation obligations. Bavaria and North Rhine-Westphalia host industrial supply houses that anchor rental channel penetration for mid-tier construction applications.
India
Government-led highway and urban rail projects accelerate equipment procurement from construction contractors and demolition specialists. Bureau of Indian Standards certification requirements favor domestic manufacturing partnerships. Maharashtra and Karnataka infrastructure corridors absorb fleet-scale compressor deployments alongside tool procurement.
China
Dual carbon goals and jobsite electrification mandates reshape power source preferences for construction equipment. Ministry of Industry and Information Technology standards guide battery chemistry improvements for cordless platforms. Yangtze River Delta manufacturing clusters supply thermal management systems for lithium-ion hammer platforms.
Japan
Precision metal forming demand in automotive repair shops commands premium pricing for vibration-damped configurations. Ministry of Economy, Trade and Industry promotes occupational health compliance in small-scale fabrication facilities. Kansai region chassis restoration specialists prioritize integrated damping over capital cost minimization.
Air Hammer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated market structure. The vendor base organizes into three tiers: integrated compressor-to-tool ecosystems, standalone pneumatic specialists, and battery-platform convergent players. Strategic moves center on service contract bundling for recurring revenue and active vibration control licensing for regulatory compliance. Geographic expansion into Indian infrastructure corridors and rental channel partnerships in North America represent dominant competitive vectors.
Among diversified industrial equipment manufacturers, Atlas Copco and Ingersoll Rand occupy positions spanning compressor infrastructure through handheld tool deployment. Robert Bosch GmbH exemplifies the battery-platform convergence archetype, bridging power systems across cordless portfolios. Chicago Pneumatic and DEWALT represent mid-tier specialists competing on rental channel accessibility and jobsite electrification readiness. Makita Corporation and Hilti Corporation anchor premium-tier positioning through integrated dust extraction and thermal management systems. These groupings illustrate how scale, specialization, and platform breadth define competitive differentiation.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Robert Bosch GmbH |
| Chicago Pneumatic |
| DEWALT |
| Makita Corporation |
| Hilti Corporation |
| NPK Construction Equipment Inc |
| Snap-on |
| Others |
Value Network & Pricing Analysis
Steel scrap price indices and aluminum alloy benchmarks cascade through air hammer manufacturing, compressing margin pools for standard-grade pneumatic tools while reinforcing premium pricing for vibration-certified configurations in regulated markets.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for compressor-powered hammers as domestic manufacturers absorb damping system certification costs. Three-tier pricing structure across premium, standard, and economy levels separates OSHA-compliant active vibration models from CE-marked mid-tier units and unbranded economy imports. Price differentiation hinges on ISO 5349 certification tier and after-sales service bundling. Cost compression in standard pneumatic tiers is intensifying because rental channels consolidate procurement volumes and squeeze supplier margins. DIY enthusiasts and small contractors exhibit highest price sensitivity, while German automotive repair shops and Indian infrastructure conglomerates prioritize occupational health compliance over capital cost minimization.
Supply Chain Analysis
India's Bureau of Indian Standards local-content mandates and domestic manufacturing partnerships are reshaping sourcing patterns for government procurement contracts. Supply concentrates in China for lithium-ion battery cells and thermal management systems, Germany for precision damping components and piezoelectric sensors, and India for cast iron housings and forged steel pistons. Raw material dependencies draw from high-grade aluminum alloys for lightweight housings, rare earth elements for vibration sensor arrays, and specialty steel grades for piston-cylinder assemblies. Single-source vulnerability in battery cell supply creates exposure to export restriction shocks. Distribution runs through industrial supply houses and equipment rental networks that displace direct OEM sales for mid-tier construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air hammer procurement has shifted toward premium vibration-damped specifications as OSHA and EU Machinery Directive enforcement tightens, rewarding manufacturers with certified ergonomic platforms and locking out undifferentiated commodity suppliers.
For Market Incumbents: Deploy active vibration control licensing as a defensive moat against battery-platform convergence threats from cordless tool specialists. Lock in fleet customers through compressor-to-tool ecosystem bundling in Indian infrastructure corridors. Deepen aftermarket service penetration through predictive maintenance packages that guarantee tool life for demolition specialists facing silica dust regulation compliance costs.
For New Entrants and Emerging Players: Begin with compact battery-powered configurations targeting North American rental channels where jobsite electrification mandates eliminate compressor logistics. Specialty automotive repair shops in Germany and Japan offer penetrable white-space for precision chisel hammers with integrated dust extraction. Partner with industrial supply houses for channel access rather than building direct sales infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier pneumatic specialists possessing Bureau of Indian Standards certification and established domestic manufacturing partnerships. Long-term viability favors vendors bridging battery and pneumatic platforms through shared thermal management architectures. Watch for inflection when silica dust regulation enforcement accelerates integrated extraction system adoption in heavy-duty demolition segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Active Vibration Control Licensing | OSHA compliance requirements in Texas and Florida infrastructure corridors create captive demand for certified damping systems. |
| Battery Platform Convergence | Shared lithium-ion ecosystems with rotary tools reduce total cost of ownership for North American rental fleet operators. |
| Domestic Manufacturing Partnerships | Bureau of Indian Standards certification unlocks government highway and urban rail procurement in Maharashtra and Karnataka. |
| Service Contract Bundling | Predictive maintenance packages generate recurring revenue from German demolition specialists prioritizing tool longevity. |
| Integrated Dust Extraction Development | Tightening respirable crystalline silica limits in EU and US jurisdictions differentiate premium demolition hammer configurations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Indian construction conglomerates, aftermarket service heads at German rental houses, OEM procurement teams at automotive repair chains, and plant engineers at metal fabrication facilities with secondary validation against SEC filings from diversified industrial equipment manufacturers, customs and trade data for pneumatic tool imports, OSHA enforcement action databases, and EU Machinery Directive technical file submissions. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates.
Segment-weighting applied product type, end user industry, tool size tier, and power source architecture as primary dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating infrastructure budget trajectories, regulatory compliance cost pass-through rates, and battery chemistry improvement curves. Forecast inputs included Indian government highway procurement schedules, OSHA vibration exposure limit enforcement intensity, and lithium-ion cell cost decline trajectories.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting China-sourced battery cells, unanticipated breakthroughs in solid-state battery commercialization, and force majeure disruptions to Indian domestic manufacturing partnerships. Forecasts reflect documented assumptions about regulatory enforcement continuity and infrastructure budget execution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Diamond Tools Market
Tools
Rivet Gun Market
Tools
Handheld Engraving Machine Market
Tools
Mechanical Springs Market
Tools
Deburring Tool Market
Tools
United States Machine Tools Market
Tools
Grinding Machines Market
Tools
Europe Paint Spray Guns Market
Tools
Metal Cutting Tools Market
Tools
Lathe Machines Market
Tools
Fiber Laser Cutting Machines Market
Tools
Book Binding Machines Market
Tools
Vertical Milling Machine Market
Tools
Turning Centers Market
Tools
Metal Forming Tools Market
Tools
Parting-Off Blades Market