
 Mini LED Display Market | 2026-2036
Mini LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Mini LED Display Market Intelligence
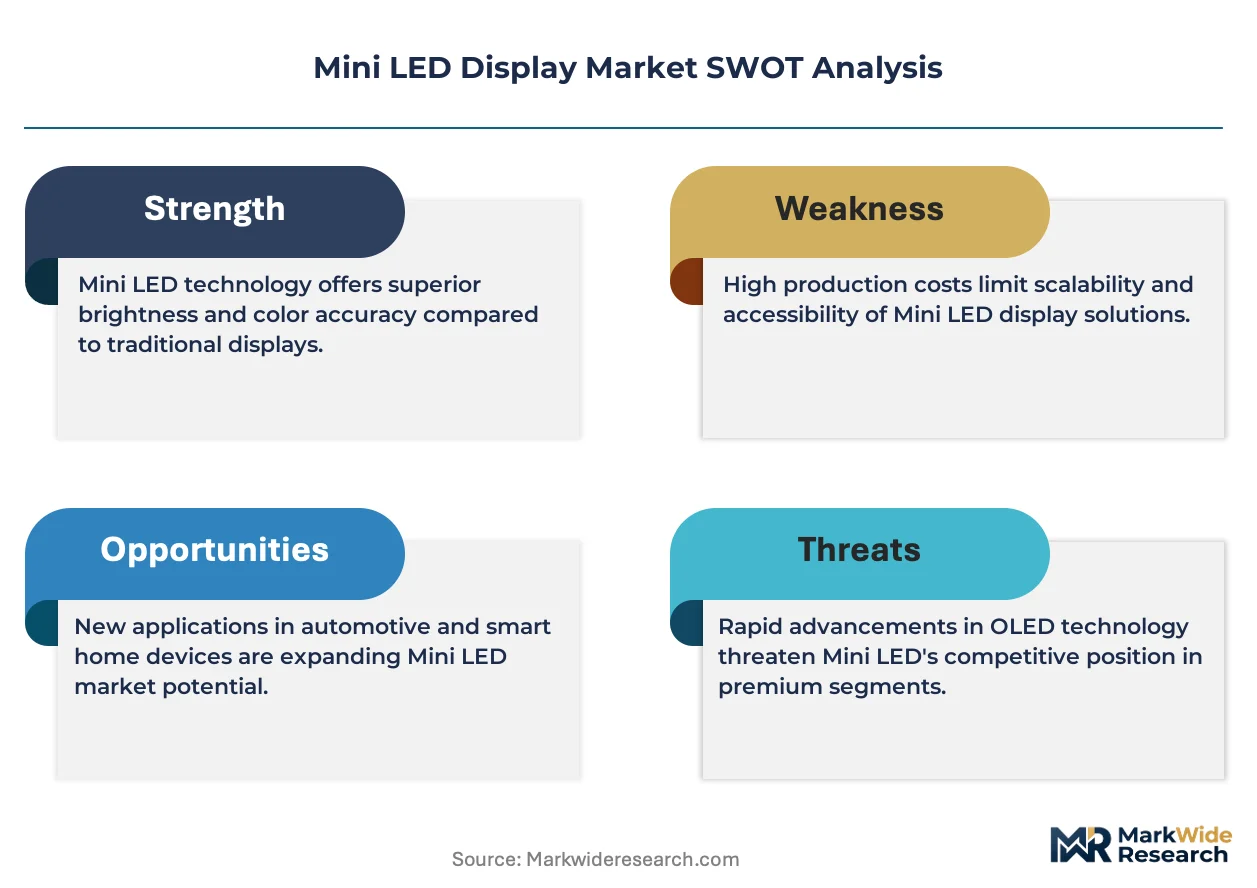
Modular backlight unit bundling with premium panel assemblies is consolidating buyer choice around integrated display ecosystems rather than component sourcing. Samsung Electronics leverages its semiconductor foundry capacity to anchor captive LED supply for vertical control. LG Electronics differentiates through OLED-Mini LED hybrid architectures that occupy the premium home theater tier. PlayNitride specializes in GaN-on-Sapphire epitaxy to sustain chip-scale packaging yields.
Mini LED displays employ arrays of LEDs smaller than 200 micrometers as dense local dimming zones behind LCD panels, enabling contrast ratios exceeding conventional edge-lit systems through thousands of individually addressable backlight segments. The technology serves commercial and consumer applications requiring high dynamic range without OLED burn-in susceptibility. Full-array local dimming configurations command the widest margin pools as television brands prioritize zone count as a premium specification. Gaming monitors represent the fastest-growing application segment as refresh rate synchronization with adaptive backlight scanning reduces motion artifacts. Enterprise digital signage retains mature volume leadership in airport terminals and retail flagship locations.
China's SAMR enforces GB standards for display energy consumption that constrain import eligibility for non-compliant backlight assemblies. South Korea's MFDS and KATS frameworks govern electromagnetic compatibility certification for residential display deployments. The EU Ecodesign Directive and RoHS substance restrictions shape material selection for phosphor-converted LED dies entering European consumer channels. Stakeholders must monitor regulatory divergence between Asian efficiency labeling schemes and European circular economy requirements when configuring regional product portfolios.
Market Dynamics
Television brands are compressing zone counts into premium tier specifications, forcing backlight suppliers to scale die-sorting throughput while China's SAMR tightens GB energy efficiency certification windows.
Growth Catalysts
- GB Standards Convergence:China's SAMR display energy efficiency mandates accelerate replacement cycles for non-compliant edge-lit inventories, pulling demand toward full-array local dimming architectures.
- Gaming Refresh Synchronization:Adaptive backlight scanning at 240Hz-plus refresh rates eliminates motion artifacts for esports monitor deployments, expanding addressable die volume.
- Epitaxy Yield Improvements:GaN-on-Sapphire wafer processing advances reduce chip-scale packaging defect rates, lowering effective cost per zone for television original equipment manufacturers.
Market Restraints
- Blue LED Die Input Volatility:Sapphire substrate pricing fluctuates with industrial gem demand, compressing epitaxy house margins during contract renegotiations.
- South Korean Supply Concentration:Samsung and LG captive foundry arrangements limit third-party backlight assembly access to premium panel supply chains.
- OLED Burn-In Mitigation Advances:Improved pixel compensation algorithms reduce Mini LED's contrast advantage in static-content commercial signage applications.
Strategic Opportunities
- EU Ecodesign Tailwinds:RoHS substance restrictions and circular economy labeling create preference for phosphor-converted LED dies in European consumer channels.
- Automotive Display Integration:Curved dashboard and head-up display applications require high-nit brightness without thermal degradation, opening zone-dense backlight specifications.
- Medical Imaging Calibration:Grayscale accuracy requirements for diagnostic radiology monitors favor individually addressable dimming zones over conventional uniformity correction.
Industry Challenges
- Die-Bonding Technician Scarcity:Micro-LED transfer precision requirements exceed conventional SMT operator skill bases, constraining assembly line expansion.
- MFDS Certification Timelines:South Korean electromagnetic compatibility testing queues extend product launch windows for residential display entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini LED Display Market |
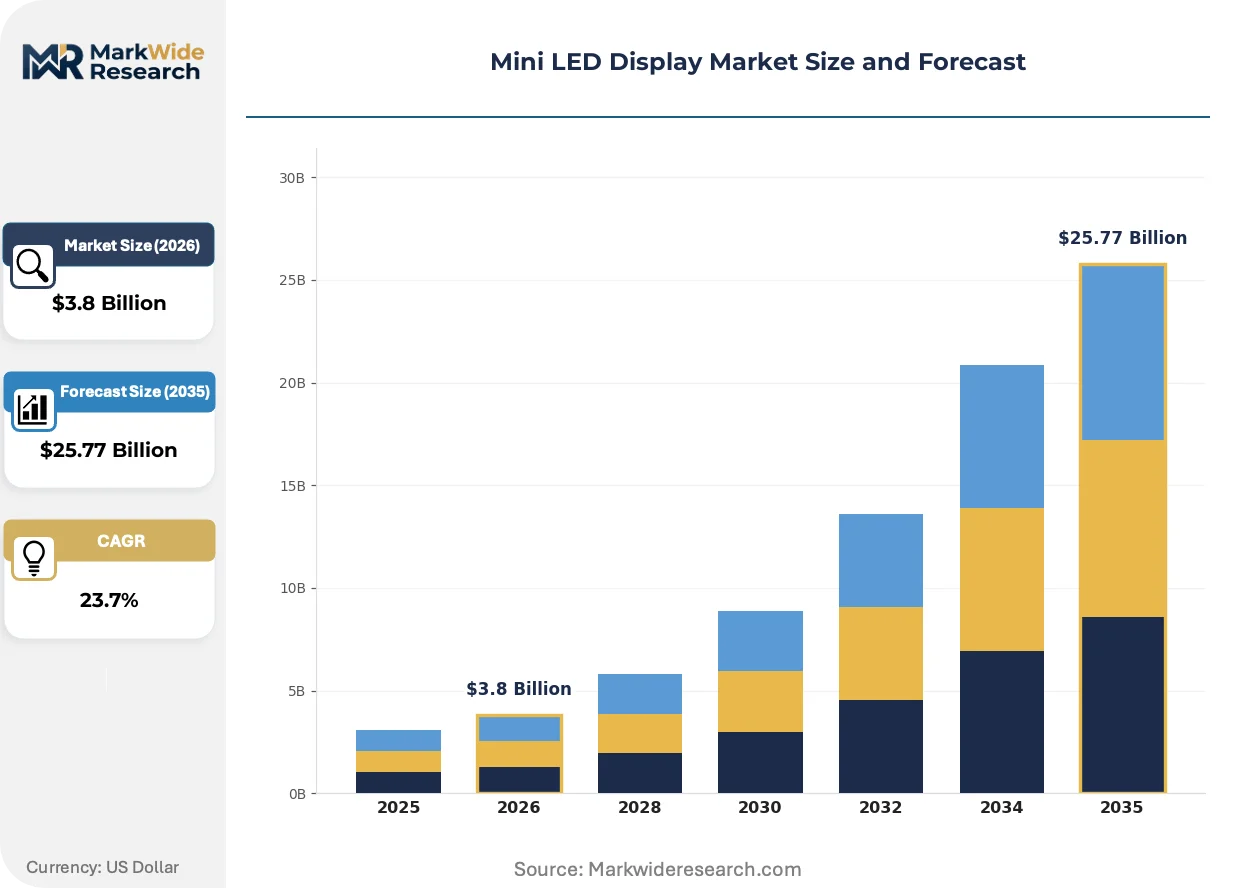
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TVs, Monitors, Digital Signage, Wearables Technology: Full-Array, Edge-Lit, Micro-LED, OLED Application: Retail, Home Theater, Gaming, Virtual Reality End User: Consumers, Enterprises, Event Venues, Schools |
| Companies Covered | Leyard, Innolux Corp., Samsung Electronics, Liantronics, Absen, LG Electronics, AUO Corp., PlayNitride, Unilumin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini LED Display Market Strategic Shifts & Innovations
Backlight architecture is fragmenting from centralized edge-lit designs toward distributed zone control, while regulatory efficiency mandates and buyer specification inflation reshape competitive requirements.
Chip-on-board LED packaging is decentralizing thermal management away from centralized heat sinks toward die-level dissipation. Gaming monitor brands are adopting this architecture fastest, specifying 1,000-plus zone densities at 27-inch form factors. The technology is decentralizing margin capture from panel assemblers toward epitaxy and precision transfer equipment suppliers.
China's GB 24850 display energy consumption standard tightens standby and active-mode thresholds on an accelerated revision cycle. Non-compliant import backlight assemblies face SAMR exclusion from product registration. Premium television lines with full-array local dimming achieve compliance through zone-deactivation algorithms, while edge-lit economy tiers face certification failure.
Buyers are consolidating procurement around integrated panel-backlight-content bundles rather than component sourcing. Streaming service operators specify HDR zone-count minimums for certification logos, displacing pure hardware specifications. South Korean retail channels enforce this bundling most strictly, with Chinese e-commerce platforms following through subsidy-linked upgrade programs.
Mini LED Display Market Segmentation
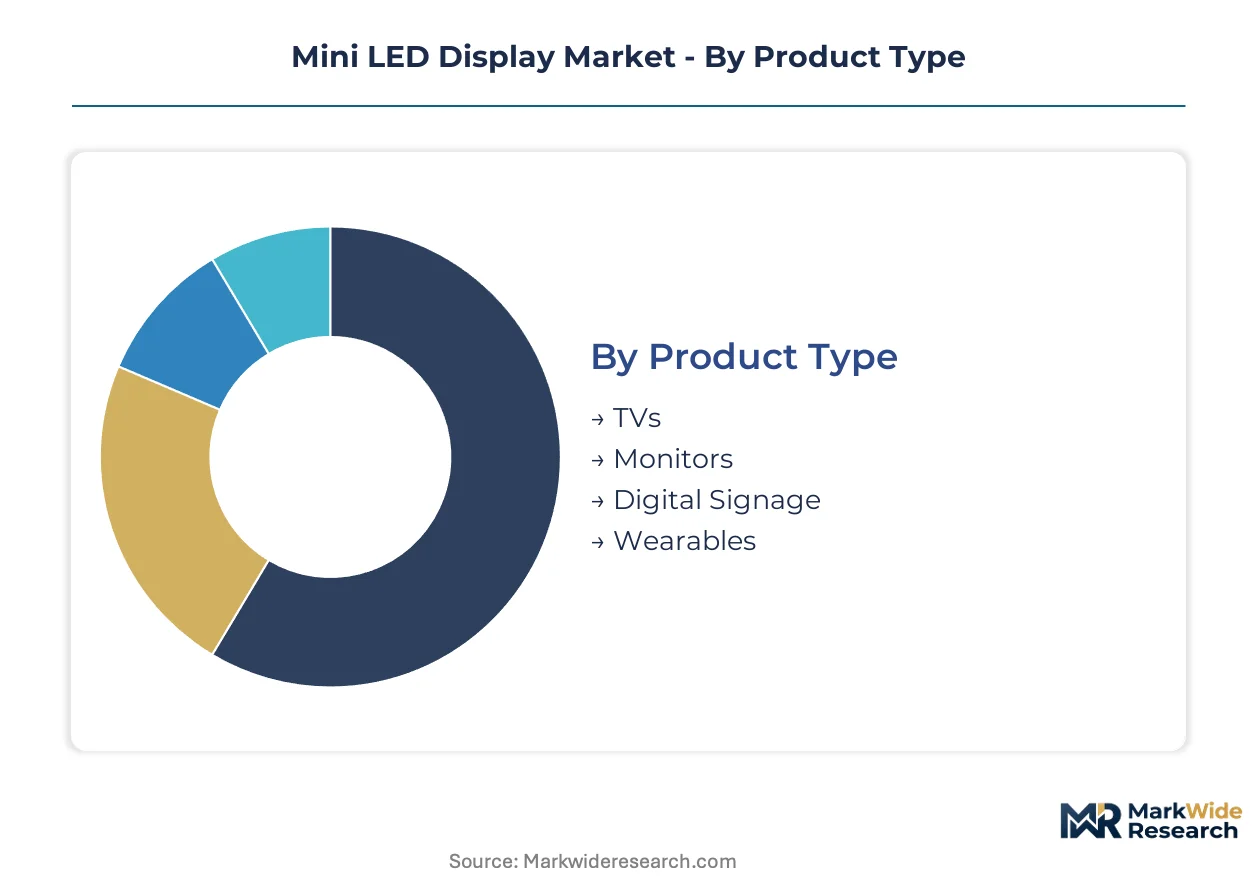
Mini LED displays fragment across four intersecting axes that determine die density requirements, thermal design complexity, and margin capture. Product type and technology specifications anchor procurement decisions, while application context and end-user profile dictate zone-count thresholds and certification compliance.
Product Type:
Screen size and viewing distance specifications create tiered die-density requirements across display categories.
- TVs:Full-array local dimming configurations with 1,000-plus zones dominate premium residential specifications. Samsung and LG supply chains in South Korea concentrate demand for 75-inch-plus formats with HDR10+ certification.
- Monitors:Gaming brands specify 240Hz-plus refresh synchronization with adaptive backlight scanning at 27-inch form factors. Esports monitor deployments are expanding addressable die volume fastest among all product types.
- Digital Signage:Enterprise deployments in airport terminals and retail flagship locations retain mature volume leadership. Static-content applications face pressure from improved OLED pixel compensation algorithms.
- Wearables:Smartwatch and AR headset manufacturers prioritize chip-scale packaging miniaturization. GaN-on-Sapphire epitaxy advances enable sub-100-micrometer die integration for wrist-worn brightness requirements.
TVs lead on scale; Monitors lead on momentum.
Technology:
Backlight architecture determines thermal management strategy and zone-addressability ceiling.
- Full-Array:Thousands of individually addressable segments behind LCD panels enable contrast ratios exceeding conventional systems. China's GB 24850 energy efficiency compliance favors zone-deactivation algorithms in premium television lines.
- Edge-Lit:Centralized LED arrays along panel perimeters face SAMR certification failure under tightened standby and active-mode thresholds. Economy-tier inventories accelerate replacement cycles toward full-array alternatives.
- Micro-LED:Chip-scale self-emissive architectures eliminate backlight layers entirely. Die-bonding technician scarcity constrains assembly line expansion for transfer precision requirements.
- OLED:Organic self-emissive panels compete directly in premium home theater tiers. Burn-in mitigation advances reduce Mini LED's contrast advantage in commercial signage applications.
Full-Array dominates revenue concentration; Micro-LED climbs the fastest on technology roadmap positioning.
Application:
Use-case brightness requirements and content motion characteristics shape zone-density procurement specifications.
- Retail:Flagship store installations specify high-nit output for daylight-visible window displays. Phosphor-converted LED dies satisfy EU Ecodesign Directive substance restrictions for European luxury retail channels.
- Home Theater:Streaming service operators enforce HDR zone-count minimums for certification logos. South Korean retail channels bundle premium panel-backlight-content ecosystems most strictly.
- Gaming:Esports tournament specifications demand sub-5ms input lag with adaptive sync compatibility. Refresh rate synchronization eliminates motion artifacts for competitive monitor deployments.
- Virtual Reality:Head-mounted displays require pancake optics compatibility with localized dimming for contrast preservation. Thermal constraints in sealed headset enclosures favor chip-on-board packaging architectures.
Home Theater commands margin pools; Gaming gains share fastest on specification inflation.
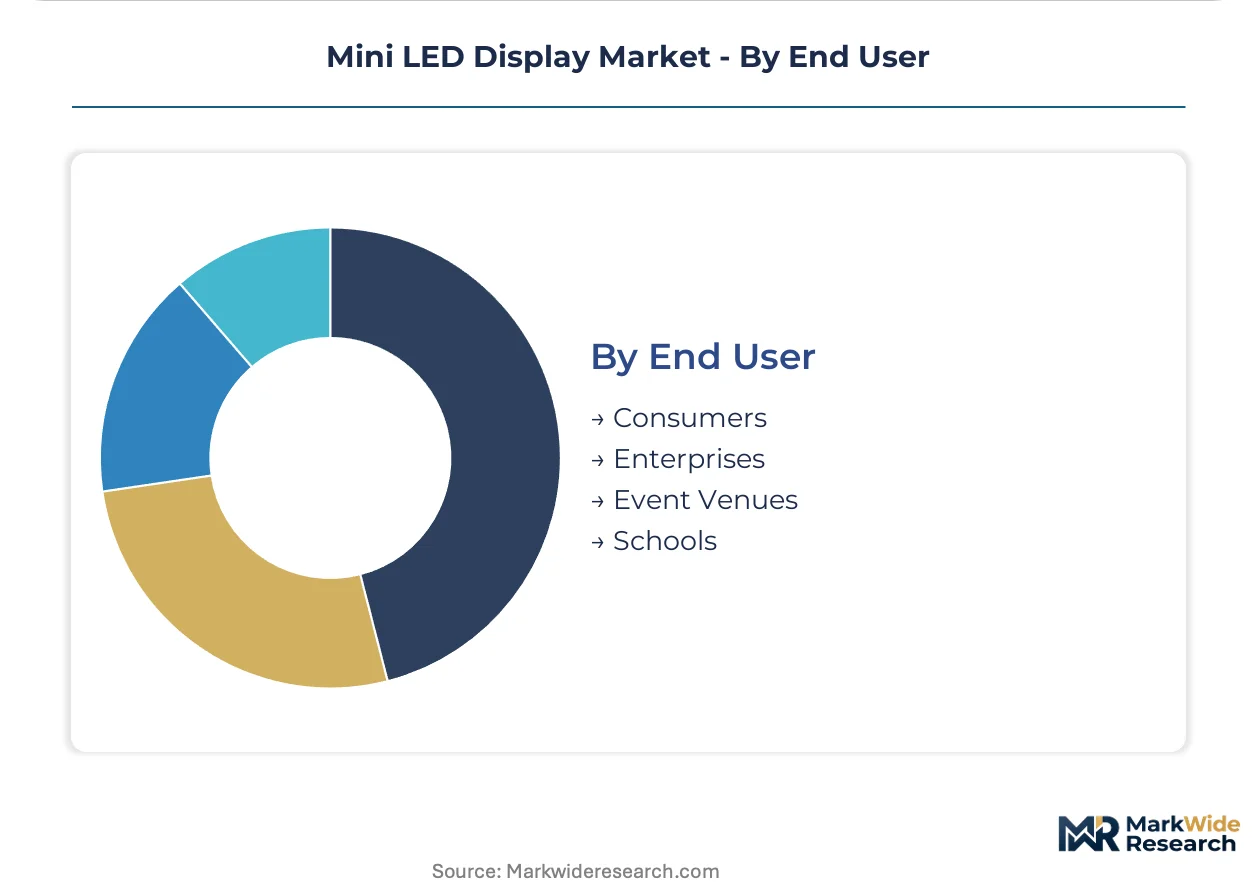
End User:
Procurement authority and volume scale determine contract structures and certification compliance priorities.
- Consumers:Individual purchasers respond to subsidy-linked upgrade programs on Chinese e-commerce platforms. Full-array local dimming specifications displace pure hardware marketing as bundling consolidates choice.
- Enterprises:Corporate procurement departments negotiate multi-site digital signage rollouts with 5-year service agreements. Grayscale accuracy requirements for diagnostic radiology monitors favor individually addressable zones.
- Event Venues:Stadium and arena operators prioritize 10,000-nit brightness for direct-sunlight visibility. Curved dashboard integration in automotive applications opens zone-dense backlight specifications for tier-one suppliers.
- Schools:Educational institutions balance acquisition cost against 8-year operational lifespans. Edge-lit configurations retain share in budget-constrained district procurement despite efficiency regulation pressure.
Enterprises anchor contract value; Event Venues show steepest expansion trajectory on experiential investment recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mini LED display manufacturing traces its industrial lineage to East Asian semiconductor fabrication clusters that scaled GaN epitaxy for solid-state lighting, then adapted those wafer-processing competencies for sub-200-micrometer die production. The technology's commercialization followed display panel assembly corridors in South Korea and Taiwan before diffusing to Chinese module integration centers. Regional competitive positioning now reflects this heritage: epitaxy and precision transfer equipment concentrate in Northeast Asia, while downstream panel assembly and brand integration span Korea, China, and Taiwan.
China
Domestic streaming platforms specify HDR zone-count minimums for certification logos, pulling consumer upgrades toward full-array local dimming configurations. SAMR enforces GB 24850 display energy consumption standards that disqualify non-compliant edge-lit imports from product registration. Shenzhen and Dongguan module assembly corridors absorb GaN-on-Sapphire die from regional epitaxy houses for television backlight integration.
South Korea
Samsung and LG captive foundry arrangements concentrate premium panel supply chain access within the Seoul Capital Area. MFDS electromagnetic compatibility testing queues extend launch windows for residential display entrants, favoring incumbents with established certification relationships. Suwon and Gumi industrial clusters anchor vertical control from semiconductor wafer fabrication through finished television assembly.
Japan
Precision equipment manufacturers supply die-bonding and transfer systems to global Mini LED assembly lines, capturing margin upstream of panel production. METI industrial policy supports next-generation display technology development through consortium-based R&D funding. Chubu/Nagoya manufacturing corridors specialize in high-throughput micro-LED transfer equipment for sub-100-micrometer die placement.
United States
Esports tournament operators and gaming peripheral brands drive specification inflation for 240Hz-plus refresh synchronization with adaptive backlight scanning. FCC electromagnetic emissions certification governs residential display market entry, though most U.S.-bound products undergo pre-certification in Asian test labs. California and Pacific Northwest technology clusters concentrate gaming monitor brand headquarters and content platform engineering.
Taiwan
Epitaxy specialists sustain chip-scale packaging yields through GaN-on-Sapphire wafer processing advances that reduce defect rates. Industrial Technology Research Institute coordinates display technology roadmaps linking domestic LED die producers with panel assembler requirements. Hsinchu Science Park anchors the island's compound semiconductor fabrication ecosystem for LED and micro-LED supply.
Mini LED Display Market Key Industry Players
The competitive structure tilts toward vertically integrated electronics conglomerates with captive semiconductor foundry capacity. Market concentration reflects the capital intensity of GaN epitaxy and the technical barriers of precision die transfer at television-scale volumes. Two strategic archetypes dominate: diversified display-panel assemblers leveraging backward integration into LED supply, and specialized epitaxy houses supplying merchant die to third-party backlight manufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as zone-count inflation forces throughput scaling at die-sorting and bonding stages.
Among diversified Korean electronics conglomerates, Samsung Electronics and LG Electronics exemplify the vertically integrated archetype through in-house production of semiconductor and display components. PlayNitride occupies a specialist position within the epitaxy tier, representing merchant suppliers that sustain yields for chip-scale packaging applications. Leyard, Innolux Corp., Liantronics, Absen, AUO Corp., and Unilumin populate the panel assembly and systems integration segments across Chinese and Taiwanese manufacturing corridors.
| Leading Market Players |
|---|
| Leyard |
| Innolux Corp. |
| Samsung Electronics |
| Liantronics |
| Absen |
| LG Electronics |
| AUO Corp. |
| PlayNitride |
| Unilumin |
| Others |
Cost & Logistics Intelligence
China's GB 24850 energy efficiency mandates gate qualified supply access for backlight assemblies, compressing margin pools for non-compliant edge-lit configurations while concentrating premium-tier pricing power among full-array local dimming suppliers with zone-deactivation algorithm certification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates zone-dense HDR-certified panels from mid-tier gaming monitors from edge-lit commercial signage. Price differentiation hinges on SAMR compliance status and Samsung-LG supply chain access. Cost compression in economy tiers intensifies as GB standards accelerate replacement cycles. Educational procurement departments show highest price sensitivity; South Korean residential buyers exhibit lowest sensitivity due to bundled content ecosystem anchoring.
Supply Chain Analysis
Sapphire substrate supply rests on Japanese and Taiwanese specialty material producers, with GaN-on-Sapphire epitaxy concentrated in South Korea, Taiwan, and China. Blue LED die production draws from regional wafer fabrication clusters; precision die-bonding equipment sources from Japanese Chubu/Nagoya corridors. Single-source vulnerability concentrates in PlayNitride merchant die supply for chip-scale packaging. Distribution runs through Shenzhen-Dongguan module assembly corridors before panel integration at Korean and Taiwanese brand facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mini LED Display Market represents a late-cycle quality story as streaming platform HDR zone-count minimums displace pure hardware specifications and consolidate procurement around integrated ecosystems.
For Market Incumbents: Acquire precision transfer equipment capabilities to defend against OLED burn-in mitigation advances threatening commercial signage share. Samsung and LG should deepen backward integration into GaN epitaxy to secure captive LED supply against sapphire substrate volatility. Certification investment in SAMR GB 24850 compliance windows remains essential for Chinese market access retention. For New Entrants and Emerging Players: Begin with automotive curved dashboard applications where zone-dense backlight specifications remain underpenetrated by established television suppliers. Medical imaging calibration for diagnostic radiology monitors offers second white-space target with grayscale accuracy requirements favoring individually addressable dimming. Go-to-market through tier-one automotive supplier qualification programs bypasses Samsung-LG captive foundry barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized epitaxy houses because zone-count inflation forces throughput scaling that favors consolidated die-sorting operations. Five-to-ten year viability centers on micro-LED technology roadmap positioning as chip-scale self-emissive architectures mature. Watch die-bonding technician training pipeline expansion as inflection indicator for assembly capacity constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy | Samsung Electronics secures captive LED supply against sapphire substrate pricing volatility. |
| Zone-Deactivation Algorithm Development | Full-array configurations achieve SAMR GB 24850 compliance while edge-lit tiers face certification failure. |
| Automotive Display Partnership | Curved dashboard specifications open zone-dense backlight demand outside television supply chains. |
| Medical Imaging Certification | Diagnostic radiology monitors favor individually addressable zones for grayscale accuracy requirements. |
| Micro-LED Transfer Equipment Scale-Up | Sub-100-micrometer die placement advances reduce chip-scale packaging defect rates for merchant suppliers. |
Research Approach
Bottom-up gaming and home theater modeling reconciled against top-down epitaxy and panel assembly tracking forms the analytical core. Primary interviews with television procurement directors, LED die sorting engineers, streaming platform certification managers, and automotive tier-one display buyers combined with secondary validation from SAMR GB standard filings, MFDS electromagnetic compatibility registries, SEC 10-K display segment disclosures, and customs trade data for sapphire substrate and GaN wafer movements. Triangulation between supply-side capacity announcements and demand-side zone-count specifications anchored volume estimates.
Historical trendline analysis of die density progression across television and monitor product cycles informed projection parameters. Segmentation modeling spanned product type, backlight architecture, application context, and end-user procurement authority across the analysis window. CAGRs derived from zone-count inflation trajectories correlated with epitaxy yield improvement curves and gaming refresh rate synchronization adoption patterns. Forecast inputs incorporated GB standards revision timelines and OLED pixel compensation algorithm advancement rates.
Caveats apply where sapphire substrate industrial gem demand fluctuations, MFDS certification queue extensions, or OLED burn-in mitigation breakthroughs could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
UK Indoor LED Lighting Market
LED
LED Mask Market
LED
Biometrics Infrared LED Market
LED
LED Panel Market
LED
Infrared (IR) LED Market
LED
LED Panel Light Drivers Market
LED
Micro LED Display Market
LED
High-Brightness LED Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
LED Modular Display Market
LED
LED Power Supplies Market
LED
Dot-Matrix LED Displays Market
LED
North America Commercial LED Lighting Market
LED
UAE LED Lights Market
LED
China Outdoor LED Lighting Market
LED
Middle East and Africa Indoor LED Lighting Market