
 High-Intensity LED Logo and Livery Lighting Systems Market | 2026-2036
High-Intensity LED Logo and Livery Lighting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High-Intensity LED Logo and Livery Lighting Systems Market Insights
Software-defined brightness calibration is realigning how lighting systems get specified and sold, shifting value from hardware-only transactions to recurring feature-enabled contracts. Collins Aerospace leverages its integrated avionics platform to bundle livery lighting with digital fleet management tools. Diehl Aerospace sustains manufacturing scale across European aerospace clusters, while Luminator Technology Group specializes in rail and bus exterior display applications.
High-intensity LED logo and livery lighting systems are semiconductor-based illumination assemblies engineered for exterior mounting on transport vehicles, typically operating at luminous intensities exceeding 500 candela with IP67 environmental sealing and vibration resistance to DO-160G standards. Their primary commercial purpose is to render carrier branding, registration markings, and safety beacons visible under night operations and adverse weather. Fixed LED Modules anchor current revenue across commercial aviation retrofit cycles, while Dynamic LED Displays capture expanding interest from fleet operators seeking programmable route-specific messaging. COB LED technology dominates aircraft exterior applications for thermal management and optical density, though Micro-LED architectures are gaining evaluation in next-generation programs.
FAA airworthiness standards and EASA CS-25 certification requirements shape product development timelines, mandating chromaticity consistency and electromagnetic compatibility testing that filters out uncertified suppliers. The EU Green Deal's embodied carbon tracking for aerospace components adds compliance layers to material sourcing and end-of-life recycling protocols. Stakeholders must weigh certification investment against the service-revenue potential of software-upgradable lighting architectures.
Market Dynamics
Software-defined brightness calibration is restructuring how lighting systems get specified, shifting value capture from hardware-only transactions toward recurring feature-enabled contracts tied to fleet management platforms.
Growth Catalysts
- FAA airworthiness directives:Mandates on exterior lighting visibility push OEMs toward higher-output LED architectures, accelerating retrofit cycles across narrow-body fleets.
- Commercial fleet branding:Airlines operating large retrofit programs demand illuminated tail logos for night-time brand visibility, concentrating procurement in the United States.
- COB LED thermal management:Chip-on-board architectures deliver optical density and heat dissipation required for aircraft exterior mounting, displacing legacy lamp technologies.
Market Restraints
- Certification investment burden:FAA and EASA CS-25 electromagnetic compatibility testing filters out uncertified suppliers, raising capital barriers for market entry.
- Material cost volatility:Semiconductor substrates and rare-earth phosphors expose manufacturers to supply chain price swings.
- Substitution risk from OLED:Organic electroluminescent alternatives threaten niche applications where weight reduction outweighs brightness requirements.
Strategic Opportunities
- EU Green Deal compliance services:Embodied carbon tracking for aerospace components creates revenue streams in material sourcing verification and end-of-life recycling protocols.
- Dynamic LED Displays:Programmable route-specific messaging systems capture expanding interest from fleet operators seeking operational flexibility beyond static branding.
- Micro-LED evaluation programs:Next-generation architectures enable pixel-level brightness control for adaptive visibility in adverse weather conditions.
Industry Challenges
- DO-160G vibration testing expertise:Qualified engineering talent for environmental qualification remains scarce, extending product development timelines.
- Legacy avionics integration:Retrofit installations must interface with existing aircraft electrical buses without triggering electromagnetic interference faults.
- Chromaticity consistency at scale:Binning variations across LED batches complicate fleet-wide visual uniformity for carrier brand standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Intensity LED Logo and Livery Lighting Systems Market |
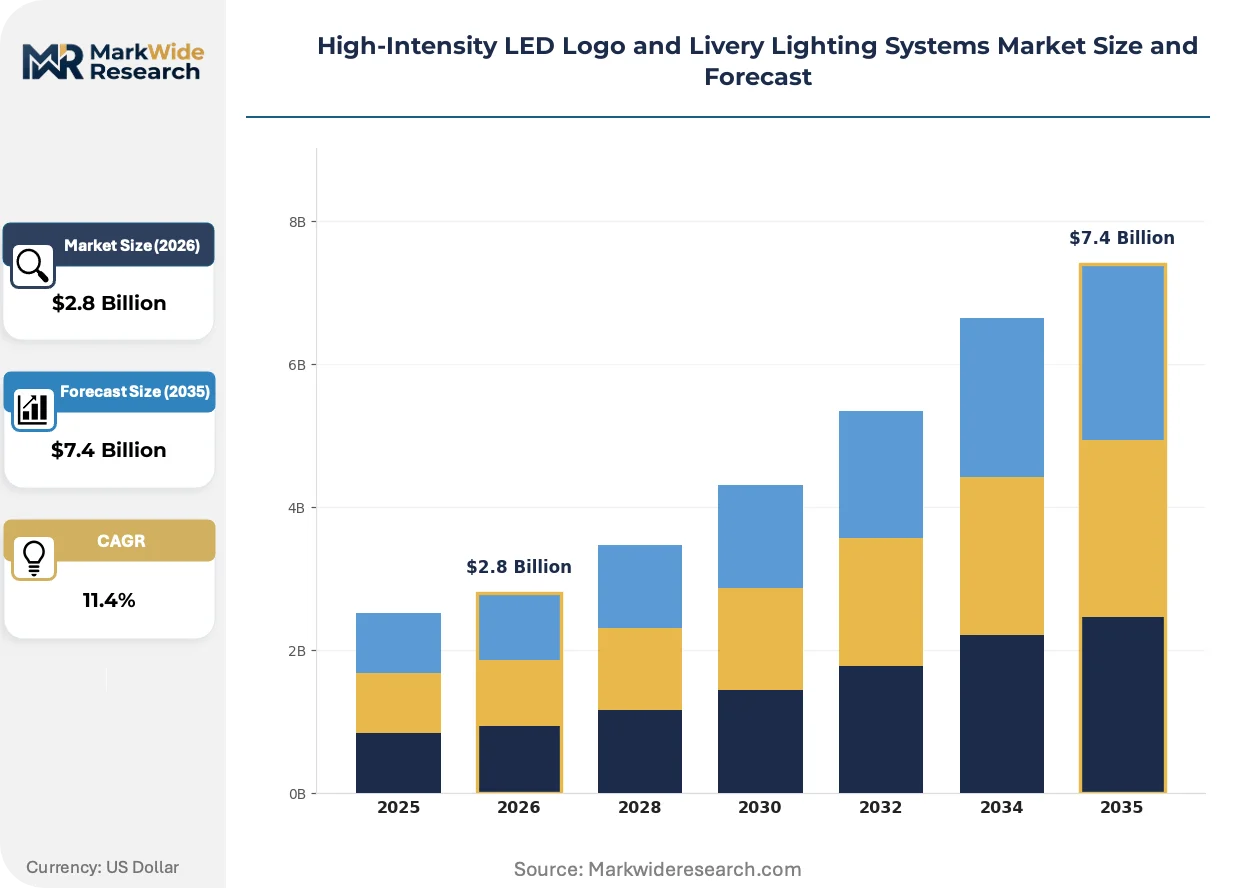
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed LED Modules, Dynamic LED Displays, Edge-Lit Panels, Miniature LED Clusters Technology: COB LED, SMD LED, OLED, Quantum Dot LED, Micro-LED Application: Aircraft Exterior, Commercial Fleet Branding, Rail Transport Signage, Marine Vessel Identification End User: Airline Companies, Fleet Operators, Train Service Providers, Shipping Lines |
| Companies Covered | Collins Aerospace, Honeywell Aerospace, Astronics, Talon Aerospace, Oxley Group, PWI, IFE Products, Diehl Aerospace, Luminator Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Intensity LED Logo and Livery Lighting Systems Market Trends and Innovations
Three forces are actively reshaping how high-intensity LED systems get engineered, sold, and maintained across commercial transport applications.
Micro-LED architectures enable pixel-dense illumination with localized thermal zones, allowing adaptive brightness zoning for aircraft tail surfaces. Major carriers evaluating next-generation narrow-body programs are requesting programmable logo geometries that shift between carrier alliances. This capability is converging with digital twin platforms, compressing the specification cycle from months to weeks.
EASA CS-25 certification requirements now explicitly address chromaticity drift over operational life, forcing manufacturers to implement closed-loop color feedback systems. The regulation tightens allowable CIE coordinate deviation, particularly for safety beacon applications. European OEMs are responding with in-situ calibration modules that adjust output based on ambient temperature sensing.
Fleet procurement teams now unbundle hardware acquisition from software maintenance, treating lighting control updates as subscription services. Airlines operating mixed-generation fleets prioritize vendors offering backward-compatible firmware architectures. This pattern is most visible among United States-based carriers with large retrofit programs spanning multiple aircraft types.
High-Intensity LED Logo and Livery Lighting Systems Market Segmentation
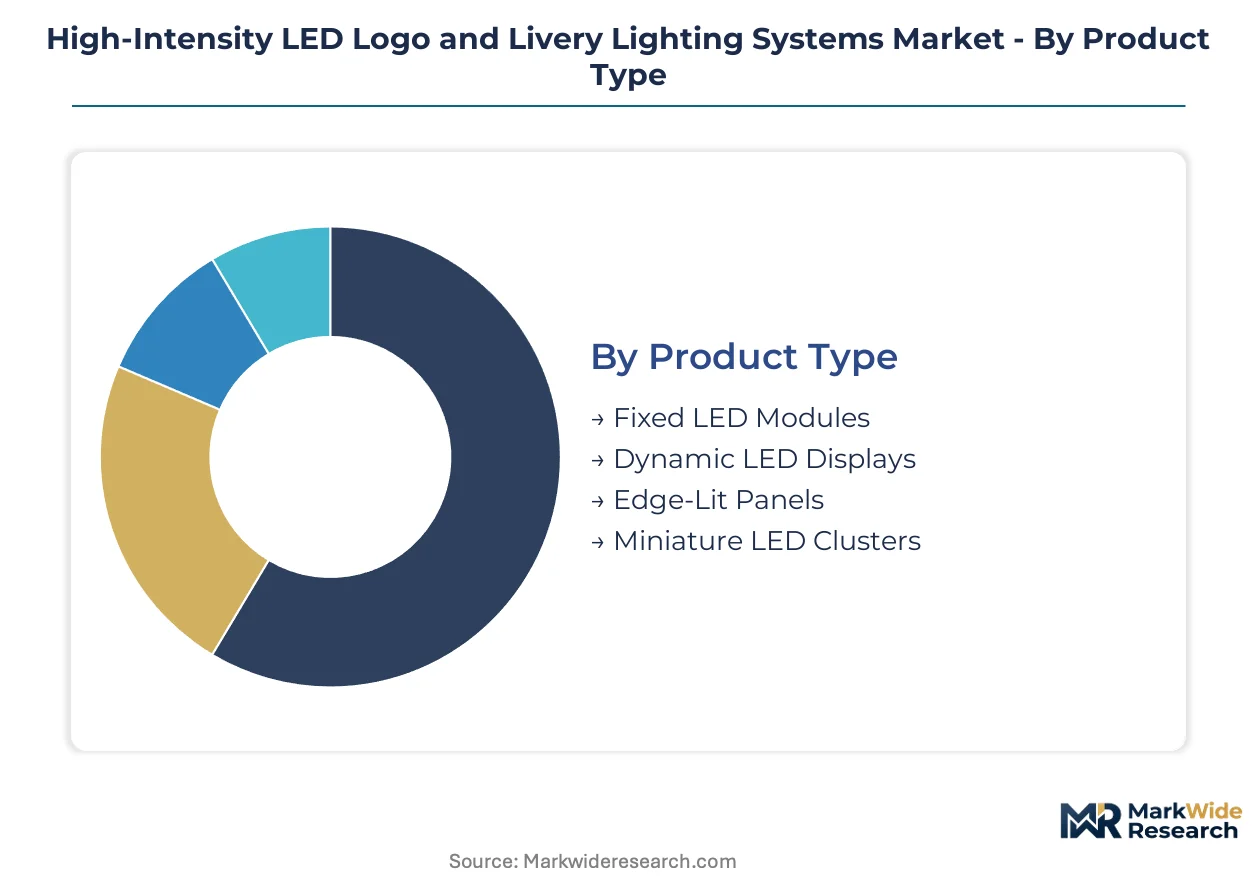
Segmentation in this market reveals how procurement patterns diverge between retrofit aviation programs and emerging transport applications. Technical specifications, certification requirements, and software integration capabilities shape buyer decisions across each dimension.
Product Type:
Customization intensity varies sharply across this category, from standardized fixed modules to fully programmable display architectures requiring bespoke firmware integration.
- Fixed LED Modules:Static illumination assemblies with sealed optical chambers deliver consistent luminous output for tail-mounted carrier logos. Demand concentrates in United States narrow-body retrofit programs where FAA airworthiness directives mandate visibility upgrades. Thermal management via aluminum substrates ensures DO-160G compliance without active cooling systems.
- Dynamic LED Displays:Programmable pixel arrays enable route-specific messaging and alliance branding transitions through software-defined content. Fleet operators in European rail corridors deploy these for real-time destination updates alongside static livery elements. Integration with CAN bus architectures requires customized control electronics per vehicle platform.
- Edge-Lit Panels:Thin-form-factor illumination using side-mounted LED strips and light-guide plates suits registration marking applications with strict weight budgets.
- Miniature LED Clusters:Compact multi-emitter arrays serve safety beacon and anti-collision lighting with minimal aerodynamic penalty.
Most installed capacity flows through Fixed LED Modules. Expansion is steepest in Dynamic LED Displays.
Technology:
Cost tiers separate mature packaging formats from emerging architectures still navigating qualification timelines.
- COB LED:Chip-on-board integration eliminates individual LED packages, concentrating thermal load into manageable zones for aircraft exterior mounting. Optical density exceeds surface-mount alternatives, supporting narrow-beam projection required for tail logo visibility at distance. European aerospace clusters favor COB for chromaticity consistency across production batches.
- Micro-LED:Pixel-level addressability enables adaptive brightness zoning and programmable geometries without mechanical masking. Next-generation narrow-body evaluations in United States carrier programs are requesting micro-LED demonstrations for alliance flexibility. Manufacturing yield challenges currently limit deployment to premium retrofit lines.
- SMD LED:Surface-mount discrete packages dominate aftermarket replacement demand with established supply chains and rapid procurement cycles.
- OLED:Organic electroluminescent layers offer weight reduction for applications where brightness requirements remain modest.
- Quantum Dot LED:Nanocrystal-enhanced emission improves color gamut for brand-accurate reproduction in controlled viewing angles.
COB LED anchors current production volumes. Micro-LED is gaining share fastest among technology options.
Application:
Application focus determines margin structure, with aviation programs commanding certification premiums versus surface transport's volume-driven procurement.
- Aircraft Exterior:Vertical tail surfaces, fuselage registration zones, and wingtip safety beacons constitute the highest-value installation category. EASA CS-25 chromaticity drift requirements now mandate closed-loop calibration systems, adding recurring service revenue to hardware sales. United States-based carriers with mixed-generation fleets drive specification complexity for backward-compatible architectures.
- Rail Transport Signage:Exterior destination displays and operator branding panels operate under less stringent vibration standards than aviation equivalents. European train service providers are unbundling hardware acquisition from content management subscriptions, treating lighting control as operational technology rather than capital equipment.
- Commercial Fleet Branding:Ground vehicle applications including trucking and bus fleets prioritize rapid installation and field serviceability over extreme environmental sealing.
- Marine Vessel Identification:Hull-mounted illumination for cruise operators and cargo vessels faces salt corrosion requirements distinct from aerospace qualification protocols.
Aircraft Exterior captures the dominant revenue share. Commercial Fleet Branding is expanding most quickly as ground transport operators adopt aviation-grade visibility standards.
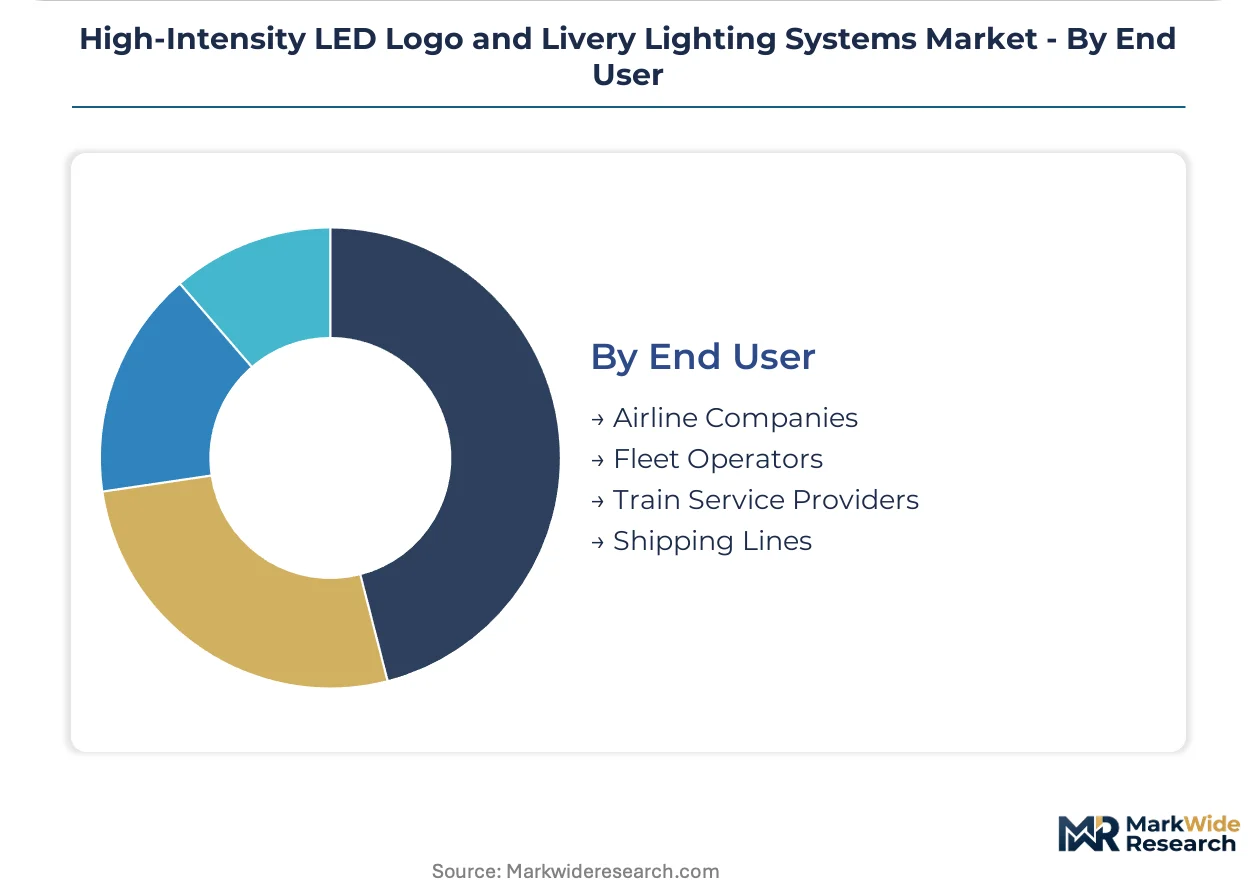
End User:
Customer type shapes contract structure, from airline long-term service agreements to shipping line spot procurement.
- Airline Companies:Major carriers with large retrofit programs specify integrated avionics platforms bundling livery lighting with digital fleet management tools. Software-defined brightness calibration enables recurring feature contracts rather than one-time hardware transactions. Procurement teams prioritize vendors offering firmware architectures compatible across multiple aircraft types.
- Fleet Operators:Ground-based commercial vehicle managers emphasize total cost of ownership and rapid deployment timelines over extended certification documentation.
- Train Service Providers:European rail operators are consolidating lighting specifications across national networks to simplify maintenance training and spare parts logistics.
- Shipping Lines:Marine procurement focuses on corrosion-resistant sealing and global service network coverage for vessel routing flexibility.
Airline Companies account for the largest installed base. Fleet Operators are climbing the fastest as ground transport electrification expands addressable applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers retrofit narrow-body fleets at scale, while German aerospace clusters engineer thermal management solutions for exterior LED mounting. France concentrates certification expertise around EASA CS-25 chromaticity standards.
United States
Major airlines operate large retrofit programs for illuminated tail logos on Boeing 737 and Airbus A320 families. FAA airworthiness directives on exterior lighting visibility accelerate procurement cycles for higher-output LED architectures. Dallas-Fort Worth and Seattle aerospace corridors host integration facilities where Collins Aerospace bundles livery lighting with digital fleet management platforms.
Germany
Diehl Aerospace sustains manufacturing scale across European aerospace clusters with COB LED thermal management systems. EASA CS-25 certification requirements filter supplier participation through electromagnetic compatibility testing protocols. Hamburg and Munich engineering centers develop closed-loop color feedback systems addressing chromaticity drift over operational life.
France
Toulouse and Bordeaux aerospace networks concentrate EASA certification expertise for exterior lighting systems on Airbus platforms. EU Green Deal embodied carbon tracking adds compliance layers to material sourcing for aerospace components. French OEMs respond with in-situ calibration modules adjusting output based on ambient temperature sensing.
United Kingdom
Oxley Group anchors defense and commercial aviation lighting supply from Cumbria manufacturing facilities. UK aerospace regulators align with EASA CS-25 standards while maintaining distinct national certification pathways. Southeast England electronics corridors source rare-earth phosphors for semiconductor substrates under post-Brexit trade frameworks.
China
Domestic narrow-body programs evaluate Micro-LED architectures for programmable carrier alliance branding. MIIT standards for commercial aircraft exterior lighting converge with FAA and EASA benchmarks for export market access. Shanghai and Xi'an aerospace clusters develop localized supply chains for LED substrates and optical components.
High-Intensity LED Logo and Livery Lighting Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aviation-grade certification creating tiered participation barriers. The vendor base concentrates around three strategic archetypes: integrated avionics platforms bundling lighting with fleet software, specialized exterior lighting manufacturers with EASA/FAA qualification depth, and diversified aerospace suppliers leveraging existing airframe relationships. Competitive moves center on backward integration into semiconductor packaging and strategic partnerships with digital twin platform providers.
Within the integrated platform tier, Collins Aerospace exemplifies the bundled avionics-to-lighting model, while Diehl Aerospace represents European manufacturing scale across certification-intensive aerospace clusters. Luminator Technology Group occupies a distinct position bridging rail and bus exterior display applications with aviation-adjacent technology transfer.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell Aerospace |
| Astronics |
| Talon Aerospace |
| Oxley Group |
| PWI |
| IFE Products |
| Diehl Aerospace |
| Luminator Technology Group |
| Others |
Pricing and Supply Chain Analysis
COB LED thermal management standardization across European aerospace clusters compresses manufacturing cost curves while concentrating qualified supplier pools around EASA certification hubs. This production-method transition simultaneously reduces per-unit assembly labor and raises capital barriers for uncertified competitors, reshaping how procurement teams negotiate multi-year fleet retrofit contracts.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for aviation-grade exterior lighting systems. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified OEM bundles from aftermarket SMD replacements and uncertified gray-market imports. Price differentiation centers on electromagnetic compatibility documentation depth and DO-160G vibration testing completeness. Cost compression in the standard tier is intensifying because Chinese substrate suppliers are qualifying for European aerospace material specifications. Fleet operators with mixed-generation aircraft prove least price-sensitive due to firmware compatibility requirements, while regional cargo carriers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from United States-based airline procurement teams require qualified semiconductor substrate suppliers in Germany, Japan, and the United States. Manufacturing draws from aluminum nitride ceramic substrates, rare-earth phosphor coatings, and precision optical lenses. Single-source vulnerability persists around MIIT-certified Chinese LED die suppliers seeking EASA equivalency recognition. Distribution runs through airframe OEM integration facilities and specialized aviation aftermarket distributors with hangar-level technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA CS-25 chromaticity drift regulations impose stricter compliance costs on European manufacturers than FAA equivalents, creating arbitrage opportunities for United States-based suppliers with backward-compatible firmware architectures serving mixed-generation fleets.
For Market Incumbents: Lock in long-term service revenue by bundling closed-loop color calibration modules with subscription-based brightness management platforms. Threats from Micro-LED substitution in next-generation narrow-body programs demand accelerated R&D partnerships with digital twin platform providers. Backward integration into semiconductor packaging secures phosphor supply continuity against rare-earth price volatility. For New Entrants and Emerging Players: Launch via direct airframe OEM partnerships targeting the rail transport signage segment where vibration standards remain less stringent than aviation equivalents. White-space concentrates in European train service providers consolidating lighting specifications across national networks. Marine vessel identification offers secondary penetration with corrosion-resistant sealing as the differentiated entry angle. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized exterior lighting manufacturers with EASA/FAA qualification depth but limited software platform integration. Five-to-ten-year viability hinges on recurring service revenue capture from firmware-update subscriptions rather than hardware replacement cycles. Acquisition targets should demonstrate in-situ calibration module deployment with ambient temperature sensing capabilities. The signal to watch is airline procurement team unbundling of hardware acquisition from software maintenance contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Packaging | Captive supply of aluminum nitride substrates insulates Diehl Aerospace from rare-earth phosphor price swings. |
| Digital Twin Platform Partnership | Collins Aerospace compresses specification cycles from months to weeks through virtual lighting geometry validation. |
| Closed-Loop Calibration Module Deployment | French OEMs address EASA CS-25 chromaticity drift mandates with in-situ color feedback systems. |
| Rail-to-Aviation Technology Transfer | Luminator Technology Group leverages bus exterior display expertise for lower-vibration aviation applications. |
| EU Green Deal Compliance Service Launch | Material sourcing verification and end-of-life recycling protocols create recurring revenue streams for certified suppliers. |
Research Methodology
Bottom-up aircraft exterior modeling reconciled against top-down LED component production tracking forms the analytical core of this study. Primary interviews with airline procurement directors, EASA certification engineers, airframe OEM integration specialists, and fleet maintenance supervisors were cross-validated against FAA airworthiness directive filings, EASA CS-25 amendment records, semiconductor trade customs data, and OEM annual disclosures. Triangulation between supply-side capacity surveys and demand-side retrofit program announcements ensures segment-level precision.
Input-output matrices map COB LED thermal management adoption rates, Micro-LED evaluation program progressions, and software-defined brightness calibration penetration across fixed module and dynamic display product categories throughout the forecast period. CAGRs derive from logistic diffusion curves fitted to certification timeline data and fleet replacement cycle analysis. Industry-specific forecast inputs include narrow-body aircraft delivery schedules and EU Green Deal embodied carbon tracking implementation phases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT-EASA regulatory equivalency delays or rare-earth export restriction scenarios. Outcomes reflect documented assumptions regarding airline retrofit program pacing and semiconductor yield improvement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
OLED Blue Emitter Market
LED
Japan Indoor LED Lighting Market
LED
China Outdoor LED Lighting Market
LED
7 Segment LED Displays Market
LED
Russia LED Market
LED
Architectural LED Products Market
LED
Mexico LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
LED and OLED Display Market
LED
Led Video Walls Market
LED
LED Panel Market
LED
LED Lighting Controllers Market
LED
Middle East and Africa Indoor LED Lighting Market
LED
Small Pitch LED Display Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Middle East LED Lighting Market