
 High-Brightness LED Market | 2026-2036
High-Brightness LED Market Size, Share, and Industry Trends Forecast 2026-2036
High-Brightness LED Market Intelligence
Automotive OEMs is bifurcating demand away from traditional general lighting contractors as electric vehicle platforms integrate matrix headlamps and cabin ambient systems. Nichia Corporation leverages its phosphor technology leadership to dominate high-CRI automotive applications. Samsung Electronics Co Ltd anchors display backlighting through vertical control over GaN-on-sapphire supply chains. Seoul Semiconductor differentiates via its WICOP chip-scale package architecture, competing directly against incumbent COB specialists.
High-brightness LEDs are solid-state emitters producing luminous intensities exceeding 50 lumens per watt at drive currents above 350 milliamps, fabricated through metal-organic chemical vapor deposition of InGaN quantum wells on sapphire or silicon carbide substrates. Their primary purpose is to deliver directional, energy-efficient illumination for applications requiring high luminance density in compact form factors. Automotive lighting applications command premium pricing due to thermal management and beam precision requirements, while backlighting segments face margin compression as mini-LED alternatives penetrate display supply chains. Quantum dot technology variants represent the fastest-growing technology segment as color conversion efficiency gains traction in professional display markets.
The US Department of Energy enforces efficacy benchmarks through ENERGY STAR and DLC qualification programs, while the EU's Ecodesign Directive phases out low-efficiency LED modules through minimum performance standards. China's MIIT administers national standards for semiconductor lighting under GB 24906, creating compliance layers for export-oriented manufacturers. Japan's METI promotes next-generation lighting roadmaps that accelerate adoption of human-centric circadian lighting specifications. Stakeholders must monitor divergence between regional efficacy mandates and material substance restrictions as RoHS exemptions for LED phosphors expire across multiple jurisdictions.
Market Dynamics
Automotive electrification is compressing development cycles for matrix headlamp systems, forcing suppliers to align thermal management architectures with EV platform thermal budgets rather than legacy internal combustion constraints.
Growth Catalysts
- EU Ecodesign efficacy mandates:Minimum luminous efficacy thresholds are phasing out legacy LED modules, compelling replacement demand across commercial and residential retrofit channels.
- GaN-on-sapphire substrate advances:Improved crystal quality is reducing defect densities in InGaN quantum wells, enabling higher drive currents without efficiency droop.
- China's Guangdong manufacturing concentration:Shenzhen and Dongguan anchor vertically integrated supply chains spanning epitaxy through packaging, compressing lead times for export orders.
Market Restraints
- Sapphire substrate cost volatility:Energy-intensive boule growth exposes input costs to electricity pricing fluctuations in producing regions.
- Phosphor supply concentration:Rare-earth dopant processing clusters in limited jurisdictions create vulnerability to export restriction policies.
- Thermal management complexity:High-luminance density requirements in compact automotive form factors demand exotic ceramic substrates and active cooling systems.
Strategic Opportunities
- Human-centric circadian lighting:METI roadmaps in Japan are accelerating adoption of tunable white systems in healthcare and education facilities.
- Micro-LED convergence with quantum dots:Hybrid architectures combining chip-scale emitters with color conversion layers address professional display color gamut requirements.
- Direct-to-OEM distribution channels:Automotive tier-1 suppliers are bypassing traditional lighting distributors to secure volume commitments for EV platform launches.
Industry Challenges
- Multi-jurisdiction RoHS compliance:Expiring exemptions for LED phosphors require reformulation across EU, US, and Asian markets simultaneously.
- Epitaxy equipment capex intensity:MOCVD reactor clusters for 8-inch wafer processing demand capital deployment at scale that mid-tier foundries cannot access.
- Cross-licensing complexity in chip-scale packaging:WICOP and competing architectures face overlapping patent claims that complicate international market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Brightness LED Market |
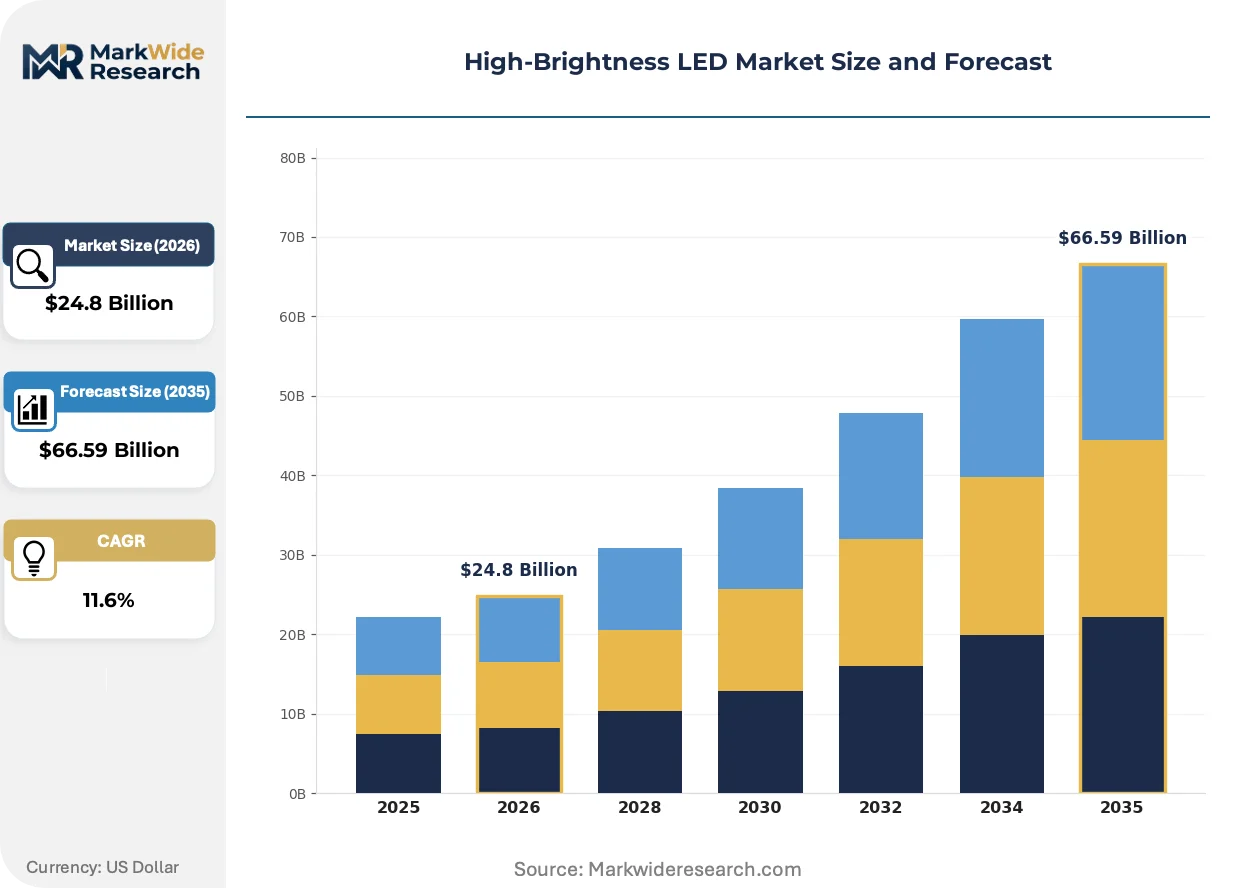
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting, Backlighting, Displays, Automotive Lights Technology: Chip-on-Board, Surface Mount, Through-Hole, Quantum Dot Application: Aerospace, Architectural, Sports, Medical End User: Retail, Hospitality, Industrial, Residential |
| Companies Covered | Nichia Corporation, Cree Inc, Samsung Electronics Co Ltd, Osram Opto Semiconductor, Seoul Semiconductor, Philips Lumileds, LG Innotek, Epistar Corp, Everlight Electronics Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Brightness LED Market Strategic Shifts & Innovations
Technology roadmaps are diverging between cost-optimized general illumination and performance-driven automotive and display applications, creating distinct competitive arenas with incompatible investment requirements.
Mini-LED backlighting is fragmenting the display illumination market into discrete tiers. The technology enables local dimming zones exceeding 10,000 units in premium television panels. Television OEMs are adopting mini-LED for high-end product lines while maintaining conventional edge-lit LED for volume segments. This bifurcation is fragmenting supplier relationships as display makers dual-source from distinct technology specialists.
China's MIIT is tightening GB 24906 efficacy standards through staged implementation of minimum performance thresholds. Domestic manufacturers must certify products against updated test protocols before market placement. Export-oriented producers in Guangdong province are pre-emptively redesigning driver electronics to meet both domestic and EU Ecodesign requirements, consolidating certification costs.
Fleet procurement of commercial lighting is compressing specification cycles as facility managers bundle LED retrofits with energy service company performance contracts. Traditional distributor relationships are yielding to direct manufacturer engagement for large-scale rollouts. North American big-box retail and logistics warehouse verticals exhibit the most pronounced shift toward consolidated procurement functions.
High-Brightness LED Market Segmentation
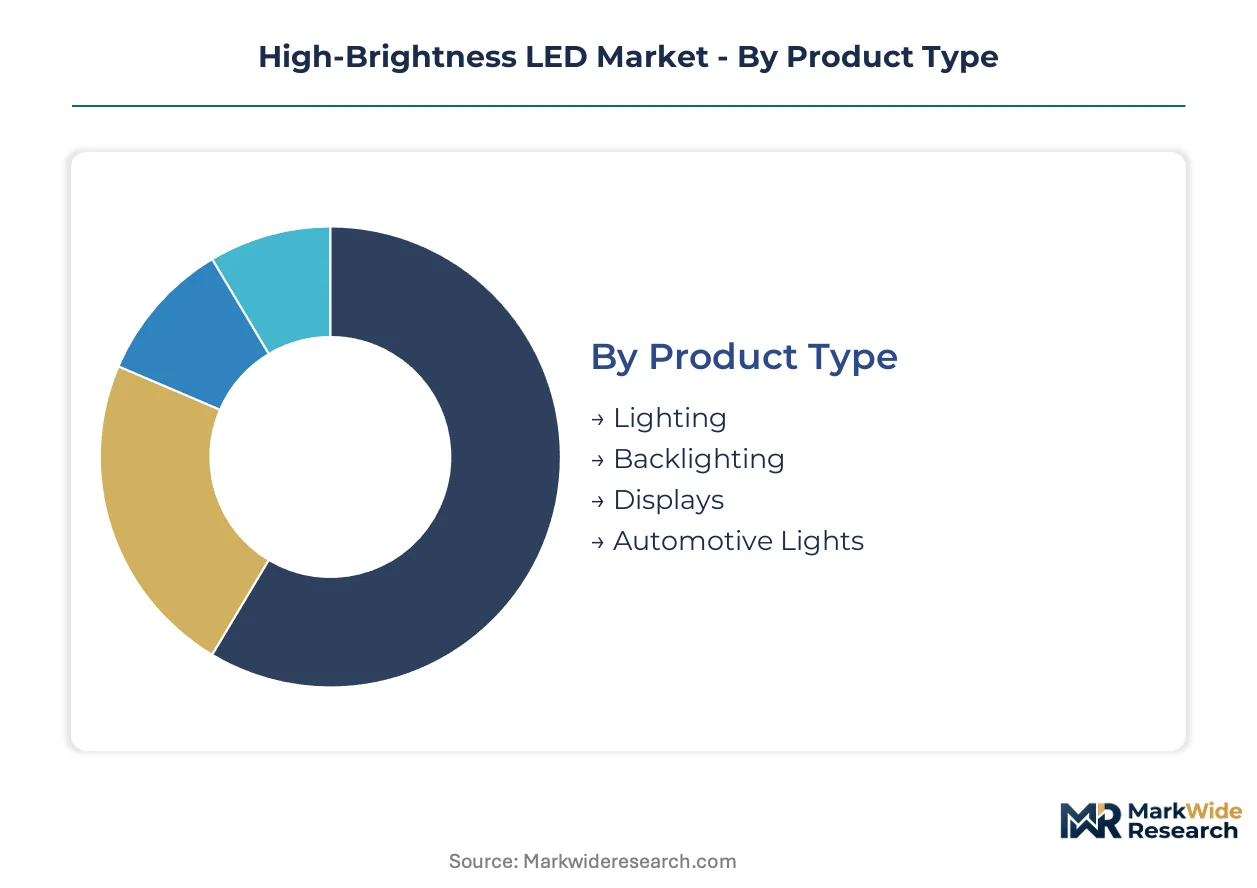
HB-LED market segmentation reveals divergent margin architectures across product categories. Technology choices determine capital intensity and IP licensing exposure. Application verticals impose distinct thermal and reliability specifications that reshape supplier qualification requirements.
Product Type:
Automotive and display applications command premium margin pools through specialized thermal management and beam precision requirements.
- Lighting:General illumination modules emphasize luminous efficacy and color rendering index for commercial retrofit installations. Demand concentrates in China's Guangdong province where Shenzhen manufacturers serve export markets under tightened EU Ecodesign efficacy mandates.
- Backlighting:Edge-lit and direct-lit configurations for LCD panels face margin compression as mini-LED alternatives penetrate premium television segments. Korean and Taiwanese display OEMs are dual-sourcing from distinct technology specialists to manage supply risk.
- Displays:Direct-view LED screens for digital signage and command centers prioritize pixel pitch density and outdoor ingress protection ratings.
- Automotive Lights:Matrix headlamp systems and cabin ambient lighting integrate with EV platform thermal budgets rather than legacy internal combustion constraints.
Automotive Lights holds installed capacity. Backlighting is rotating up the share rankings.
Technology:
Packaging architecture determines thermal performance ceilings and manufacturing capital requirements across the technology spectrum.
- Chip-on-Board:Direct die attachment to metal-core PCBs enables high lumen density in compact footprints for spotlight and downlight applications. Japanese manufacturers dominate high-CRI automotive implementations through phosphor deposition expertise.
- Quantum Dot:Color conversion layers using semiconductor nanocrystals deliver narrow emission spectra for professional display color gamut requirements. The technology is climbing the fastest as broadcast monitor and cinema projection specifications tighten.
- Surface Mount:Standardized package footprints suit high-volume automated assembly for consumer electronics and general illumination retrofit lamps.
- Through-Hole:Legacy leaded packages persist in industrial indicator applications and replacement markets where soldering equipment infrastructure remains entrenched.
Chip-on-Board holds installed capacity. Surface Mount is rotating up the share rankings.
Application:
Certification requirements and procurement cycles vary dramatically across application verticals, fragmenting go-to-market approaches.
- Medical:Surgical lighting and diagnostic equipment demand strict color temperature stability and shadow reduction specifications regulated by FDA device classification requirements.
- Aerospace:Cabin lighting and exterior navigation systems must satisfy FAA airworthiness standards for electromagnetic interference and vibration tolerance.
- Architectural:Façade illumination and landscape lighting projects bundle with energy service company performance contracts, compressing specification cycles.
- Sports:Stadium floodlighting requires glare control and broadcast color rendering metrics under FIFA and IOC venue certification protocols.
Architectural holds installed capacity. Medical is rotating up the share rankings.
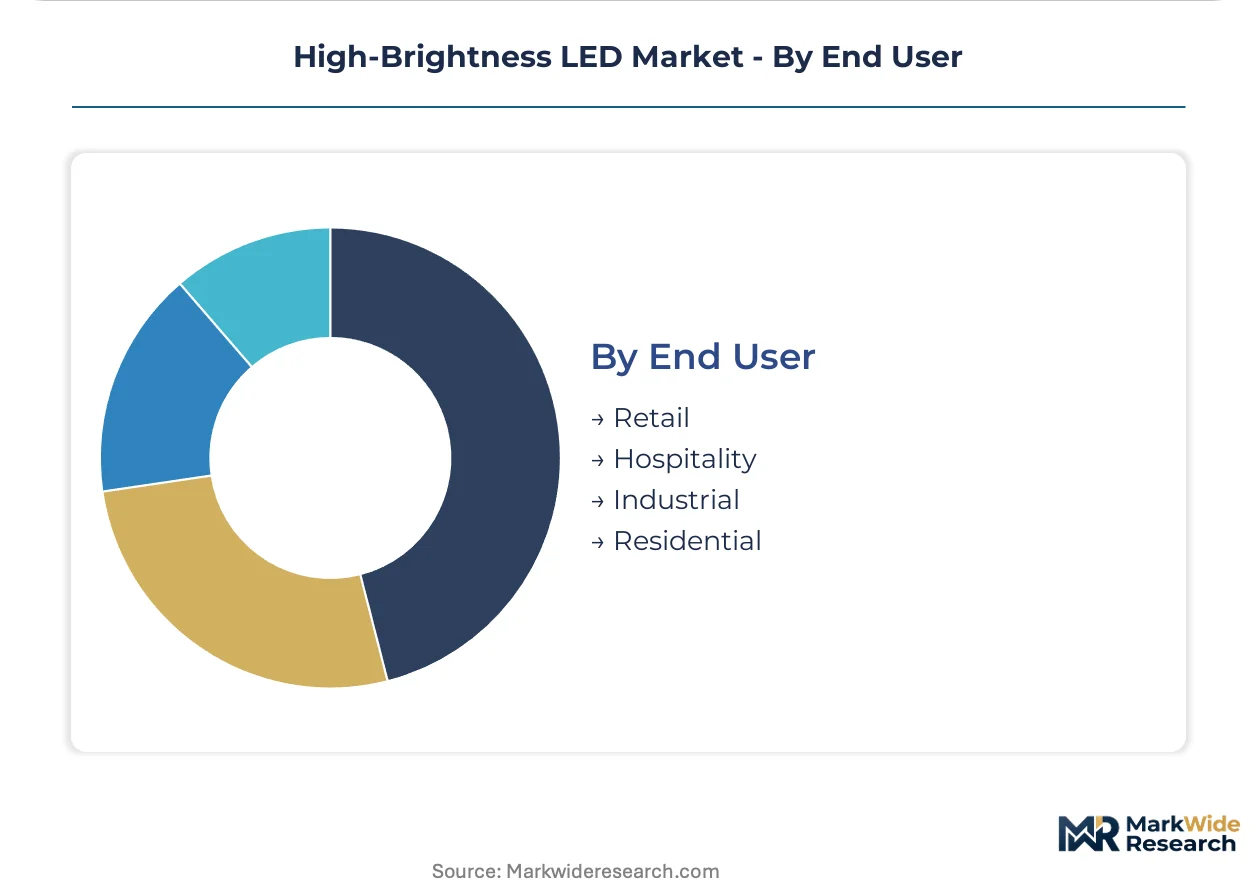
End User:
Procurement sophistication and volume concentration differ sharply between fragmented residential channels and consolidated industrial accounts.
- Industrial:Warehouse and manufacturing facility retrofits consolidate through direct manufacturer engagement rather than traditional distributor relationships. North American logistics verticals exhibit the most pronounced shift toward bundled energy service contracts.
- Retail:Big-box chains and grocery operators standardize specification templates across property portfolios, enabling volume commitments that bypass tier-1 lighting distributors.
- Hospitality:Hotel and restaurant operators prioritize human-centric circadian lighting specifications for guest experience differentiation.
- Residential:Fragmented consumer channels through home improvement retailers and electrical wholesalers face price pressure from unbranded imports.
Industrial holds installed capacity. Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers in Guangdong province export HB-LED modules to European automotive OEMs and North American lighting retrofit contractors, with shipment values concentrated through Shenzhen port terminals. Trade flows reflect regulatory compliance layering as EU Ecodesign and US ENERGY STAR standards diverge on efficacy test protocols.
China
Guangdong province anchors global HB-LED fabrication capacity, with Shenzhen and Dongguan hosting vertically integrated epitaxy-through-packaging clusters. MIIT's GB 24906 efficacy mandates force domestic redesigns ahead of export certification cycles. Dongguan manufacturers pre-emptively retool driver electronics to satisfy concurrent EU Ecodesign and domestic compliance requirements.
United States
Automotive OEMs in Detroit and Southern California integrate matrix headlamp systems with EV thermal budgets, bypassing traditional lighting distributors for direct supplier contracts. DOE ENERGY STAR and DLC programs enforce efficacy benchmarks that phase out legacy modules. Texas and Arizona warehouse operators consolidate LED retrofit procurement through bundled energy service company performance contracts.
Germany
Automotive tier-1 suppliers in Bavaria and Baden-Württemberg source HB-LEDs for premium matrix headlamp platforms, compressing development cycles to match EV platform launches. EU Ecodesign Directive minimum efficacy standards eliminate low-performance imports from non-compliant jurisdictions. Stuttgart industrial clusters specialize in thermal management substrates for high-luminance automotive applications.
Japan
METI roadmaps accelerate human-centric circadian lighting adoption in Tokyo and Osaka healthcare and education facilities. PMDA device classification requirements govern surgical lighting color stability specifications. Nagoya-area manufacturers dominate high-CRI automotive implementations through phosphor deposition expertise.
South Korea
Display OEMs in Suwon and Gumi dual-source HB-LEDs for mini-LED backlighting tiers, fragmenting supplier relationships across technology specialists. MFDS regulates medical lighting equipment while KBA oversees automotive lamp certification. Seoul Capital Area packaging houses specialize in chip-scale architectures for consumer electronics integration.
High-Brightness LED Market Key Industry Players
Player mix skews toward integrated phosphor-technology specialists and substrate-scale fabricators with captive epitaxy capacity. Market structure concentrates around Japanese and Korean conglomerates controlling quantum well deposition IP, with Taiwanese and Chinese mid-tier foundries competing on cost-optimized general illumination. Two strategic archetypes dominate: phosphor-leaders serving automotive CRI requirements, and substrate-scale players anchoring display backlighting through vertical GaN-on-sapphire control. Competitive moves center on M&A for phosphor IP consolidation and strategic partnerships for 8-inch wafer processing capacity.
Within the phosphor-technology tier, Nichia Corporation and Seoul Semiconductor occupy positions defined by deposition expertise and chip-scale packaging architectures respectively. Samsung Electronics Co Ltd anchors the substrate-scale archetype through control over GaN-on-sapphire supply chains. These three exemplify the divergence between automotive-precision and display-volume competitive arenas, with each representing incompatible capital allocation priorities across the industry.
| Leading Market Players |
|---|
| Nichia Corporation |
| Cree Inc |
| Samsung Electronics Co Ltd |
| Osram Opto Semiconductor |
| Seoul Semiconductor |
| Philips Lumileds |
| LG Innotek |
| Epistar Corp |
| Everlight Electronics Co Ltd |
| Others |
Cost & Logistics Intelligence
Forty-five-day wafer inventory cycles in Guangdong province compress pricing power for mid-tier foundries while amplifying margin capture for integrated substrate-scale players with captive epitaxy capacity.
Pricing Analysis
Quantum dot versus conventional phosphor-converted packages versus legacy chip-on-board architectures stratify across premium, standard, and economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between automotive OEM specifications and general illumination retrofit channels. Cost compression in edge-lit backlighting tiers intensifies because mini-LED alternatives penetrate premium television segments. Residential retrofit channels exhibit highest price sensitivity, while automotive matrix headlamp systems demonstrate lowest sensitivity due to thermal management and beam precision requirements.
Supply Chain Analysis
Wafer inventory cycles stretching to forty-five days signal supply chain stress concentrated in sapphire substrate procurement. Manufacturing gravity centers on China, South Korea, and Japan, with epitaxy equipment clusters in Taiwan feeding downstream packaging houses. Rare-earth phosphor dopants and GaN-on-sapphire substrates constitute critical input dependencies. Single-source vulnerability in MOCVD reactor supply creates bottleneck risk for 8-inch wafer processing capacity. Distribution runs through Shenzhen port terminals for export-oriented manufacturers serving EU and North American automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification cycles position this market for recovery as EV platform launches compress supplier qualification timelines and concentrate procurement decisions.
For Market Incumbents: Shield automotive margin pools by securing captive phosphor deposition capacity against quantum dot substitution threats. Deepen upstream control over GaN-on-sapphire supply chains to defend against substrate cost volatility. Prioritize certification investment for concurrent EU Ecodesign and China MIIT GB 24906 compliance to consolidate testing costs. For New Entrants and Emerging Players: Lead with human-centric circadian lighting specifications in Japanese healthcare and education facilities where METI roadmaps accelerate adoption. Target medical surgical lighting segments where FDA device classification requirements create qualification barriers favoring specialized entrants. Pursue direct-to-OEM distribution channels for EV platform matrix headlamp programs. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because phosphor IP scarcity and epitaxy equipment capex intensity favor scaled integrated players over fragmented mid-tier foundries. Acquisition targets should exhibit captive 8-inch wafer processing capacity or quantum dot color conversion expertise. Monitor divergence between EU Ecodesign efficacy mandates and RoHS phosphor exemption expirations as inflection signal for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor IP Consolidation | Acquisition of deposition expertise strengthens automotive CRI positioning against Nichia Corporation dominance. |
| 8-Inch Wafer Capacity Expansion | MOCVD reactor deployment captures cost advantages in general illumination as sapphire quality improves. |
| Quantum Dot Color Conversion Partnership | Hybrid architectures address broadcast monitor specifications tightening in professional display markets. |
| Direct-to-OEM Channel Development | Bypassing tier-1 lighting distributors secures volume commitments for EV platform launch timelines. |
| Concurrent Certification Investment | Pre-emptive EU Ecodesign and China GB 24906 compliance reduces redesign cycles for export manufacturers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, MIIT certification databases, and automotive OEM procurement disclosures. Primary interviews engaged epitaxy equipment specialists, automotive tier-1 supplier procurement leads, lighting distributor category managers, and regulatory affairs directors at phosphor compound manufacturers. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Guangdong province fabrication clusters.
Segmentation dimensions modeled span product type, packaging technology, application vertical, and end-user procurement sophistication across the projection horizon. CAGRs derive from installed base turnover rates, replacement demand elasticity, and technology substitution curves. Forecast inputs incorporate MIIT efficacy mandate implementation schedules and EU Ecodesign Directive phase-out timelines for low-performance modules.
Underlying assumptions cover sustained automotive electrification, stable rare-earth phosphor supply, and continued sapphire substrate quality improvements, with deviation risk concentrated in RoHS exemption expirations and MOCVD equipment delivery bottlenecks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Display Control Card Market
LED
LED Modules and Light Engines Market
LED
India Indoor LED Lighting Market
LED
7 Segment LED Displays Market
LED
Japan LED Market
LED
Bluetooth LED Bulb Market
LED
LED Display Market
LED
LED Lighting Solution Market
LED
Europe Outdoor LED Lighting Market
LED
Global LED Phosphor Market
LED
LED Encapsulation Market
LED
Led Video Walls Market
LED
Saudi Arabia LED Lights Market
LED
Organic Light Emitting Diode (OLED) Market
LED
LED Street Light Drivers Market
LED
Indonesia LED Market