
 Mini LED Market | 2026-2036
Mini LED Market Size, Share, and Industry Trends Forecast 2026-2036
Mini LED Market Intelligence
A shift from outsourced component assembly to greater in-house production of Mini LED modules is pivoting the supply chain. This move gives manufacturers more control over quality and innovation. Samsung Electronics leverages its vast manufacturing scale to integrate these displays into its premium consumer electronics. Leyard specializes in fine-pitch display panels for large-format digital signage, while LG Electronics competes across both consumer and commercial applications.
Mini LED technology utilizes light-emitting diodes typically between 100 and 200 micrometers in size. This smaller form factor allows for backlights with thousands of local dimming zones, which drastically improves contrast ratios for high-performance displays. While backlight units for consumer electronics constitute the largest product type, automotive displays are expanding rapidly due to demand for brighter, more durable screens. Chip-on-Board (COB) technology is gaining traction for its superior reliability and pixel density in direct-view applications.
Display performance and safety are governed by multiple frameworks. The European Union's RoHS directive restricts hazardous materials used in electronic components, while its CE marking certifies product safety for market access. In the United States, the EPA's ENERGY STAR program sets voluntary efficiency benchmarks that influence consumer electronics design. The key decision for device makers remains balancing the superior brightness and longevity of Mini LEDs against manufacturing cost and complexity.
Market Dynamics
The central dynamic in the Mini LED market is the tension between the technology's superior display performance and its inherent manufacturing complexity. This is compounded by a supply chain where production capabilities for key components are highly concentrated in China, Taiwan, and South Korea.
Growth Catalysts
- HDR Content Proliferation:The widespread availability of High Dynamic Range content on streaming and gaming platforms creates persistent demand for displays with the high contrast ratios and peak brightness levels that Mini LED backlights deliver.
- Automotive Sector Integration:The automotive industry's push for larger, brighter, and more durable screens for digital cockpits and infotainment systems provides a significant demand driver, valuing the technology's performance over its cost premium.
- Advanced Manufacturing Processes:The maturation of Chip-on-Board (COB) packaging technology is enhancing the pixel density, reliability, and thermal performance of direct-view displays, expanding their viability for large-scale digital signage and public information systems.
Market Restraints
- High Production Costs:The manufacturing process, particularly the mass transfer and testing of thousands of microscopic LEDs per panel, requires substantial capital investment and results in higher unit costs compared to conventional LCD and even some OLED technologies.
- Component Supply Concentration:A heavy reliance on a small number of specialized suppliers in East Asia for critical components like LED chips and driver ICs exposes the entire value chain to geopolitical risks and regional supply disruptions.
- OLED Technology Competition:In premium consumer electronics, Organic Light-Emitting Diode (OLED) displays offer a compelling alternative with per-pixel illumination, true blacks, and greater form-factor flexibility, directly competing for market share in high-end segments.
Strategic Opportunities
- Medical and Diagnostic Imaging:The superior brightness, contrast, and color accuracy of Mini LED displays present an opportunity for adoption in high-resolution medical monitors, where enhanced image clarity can improve diagnostic precision.
- Micro LED Technology Pathway:Building manufacturing expertise and supply chain relationships in Mini LED production provides a direct strategic path for companies to develop capabilities for the eventual transition to next-generation Micro LED displays.
- Augmented and Virtual Reality:Next-generation AR/VR headsets require extremely high-brightness and high-pixel-density displays to deliver immersive experiences, creating a new application frontier for miniaturized LED technology.
Industry Challenges
- Yield Rate Optimization:Achieving and maintaining high, consistent yield rates during the mass transfer and bonding stages of backlight unit assembly remains a primary operational hurdle that directly impacts production costs and scalability.
- Thermal Management Complexity:The high density of light-emitting diodes in a compact area generates significant heat, necessitating advanced thermal dissipation solutions to ensure long-term reliability and prevent color shift or brightness degradation.
- Lack of Standardization:The absence of universally accepted standards for LED binning, color uniformity, and defect classification complicates supply chain management and makes it difficult for device integrators to source interchangeable components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini LED Market |
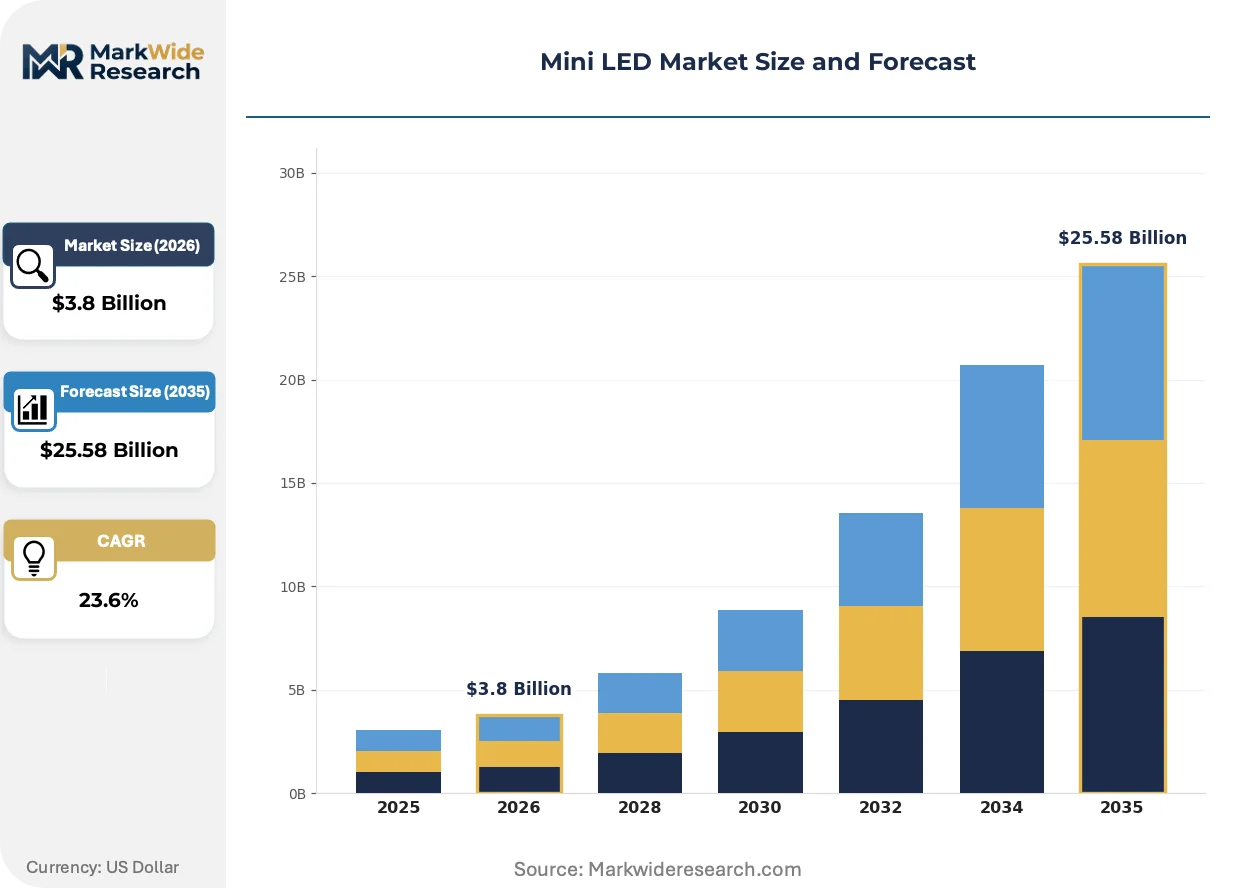
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.58 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backlight Units, Display Panels, Embedded Lighting, Automotive Displays, Wearable Screens Technology: RGB Mini LED, White Mini LED, Chip-on-Board, Direct-lit, Edge-lit Application: Consumer Electronics, Broadcast Monitors, Digital Signage, Medical Imaging, Aviation Displays End User: Consumer Electronics Manufacturers, Broadcast Equipment Makers, Medical Device Providers, Aviation Electronics Firms |
| Companies Covered | Unilumin, Absen, Samsung Electronics, Barco, Daktronics, LG Electronics, Liantronics, BOE Technology Group, Leyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini LED Market Strategic Shifts & Innovations
Industrialization of Mini LED manufacturing is evolving from basic component assembly toward deeper integration into system-level design. This shift enables greater performance differentiation while forcing producers to navigate a complex web of global environmental and safety regulations.
Active-matrix backplanes provide granular control over individual local dimming zones, significantly improving response times and reducing halo effects. High-end gaming monitors and professional design displays are adopting this technology to meet demands for superior motion clarity and contrast. This technology is modularizing the backlight unit, enabling manufacturers to create scalable performance tiers based on the number and precision of controlled zones.
The European Union's RoHS directive restricts the use of hazardous materials in electronic products, impacting the entire Mini LED component supply chain. This regulation forces manufacturers of LED chips, substrates, and driver ICs to ensure their products are free from substances like lead and cadmium. The consumer electronics segment is most affected, requiring suppliers in Asia to certify and often maintain separate production lines to access the EU market.
A pronounced shift from component-level purchasing toward the procurement of fully integrated display modules is altering supply chain interactions. The traditional model where device makers source discrete LEDs and driver ICs is being challenged by suppliers offering pre-assembled and pre-calibrated backlight systems. This trend is most apparent in the notebook and tablet markets, where original equipment manufacturers seek to simplify assembly and accelerate their time to market.
Mini LED Market Segmentation
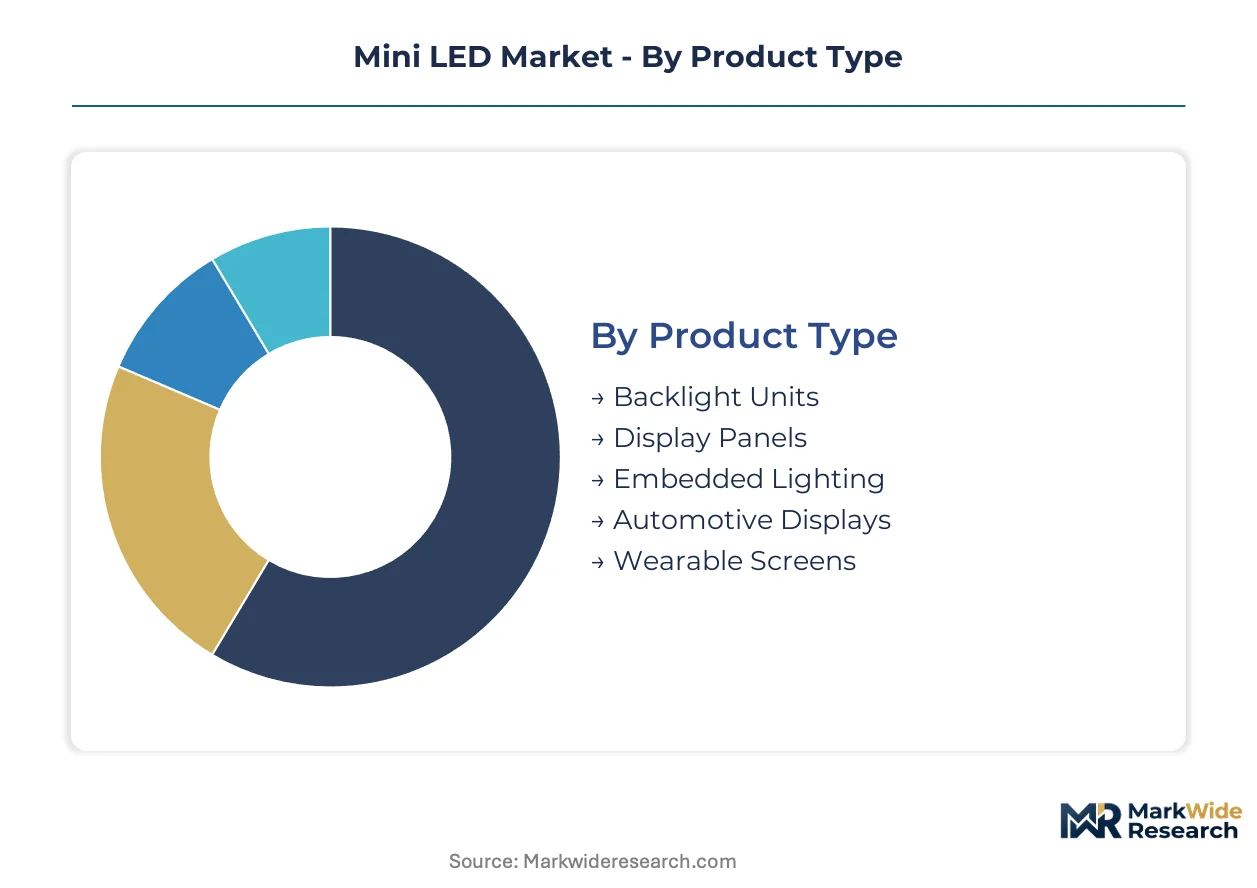
The Mini LED market's segmentation reflects distinct technological applications and end-user demands, each driving specific innovation and supply chain configurations. Understanding these categories illuminates the varying performance requirements and economic incentives across the display industry. This detailed breakdown helps identify areas of concentrated investment and emerging growth opportunities for display manufacturers.
Product Type:
The market's product segmentation highlights the split between high-volume consumer applications and more specialized, premium display solutions. Each product type addresses unique performance criteria and cost considerations for device makers.
- Backlight Units:These units integrate thousands of Mini LEDs behind an LCD panel, enabling precise local dimming across numerous zones. Demand concentrates in premium televisions and high-end monitors, driven by the need for superior contrast ratios and peak brightness for HDR content.
- Automotive Displays:Designed for vehicle interiors, these screens require enhanced durability, wider operating temperatures, and higher brightness for visibility in varying light conditions. The automotive industry integrates them into digital cockpits and infotainment systems, prioritizing performance and longevity over initial cost.
- Display Panels:This category includes fully integrated Mini LED panels, particularly those for direct-view applications like large-format digital signage.
- Embedded Lighting:Mini LED technology finds application in specialized lighting solutions where compact size and precise control are critical.
- Wearable Screens:Small-form-factor displays for devices like smartwatches and augmented reality glasses benefit from Mini LED's brightness and power efficiency.
Mature deployment sits with Backlight Units. Newer deployment is concentrated in Automotive Displays.
Technology:
Different Mini LED technologies serve specific application requirements, influencing display performance characteristics like color accuracy, contrast, and pixel density. The choice of technology often depends on the desired balance between visual quality and manufacturing complexity.
- Chip-on-Board:This packaging technology directly mounts LED chips onto a substrate, enhancing reliability, thermal performance, and pixel density. It gains traction for fine-pitch direct-view displays used in large-format digital signage.
- Direct-lit:LEDs are positioned directly behind the display panel, allowing for thousands of individual local dimming zones. High-performance displays for consumer electronics leverage direct-lit configurations to achieve superior contrast ratios.
- RGB Mini LED:Utilizing individual red, green, and blue Mini LEDs per pixel, this technology is ideal for full-color direct-view displays requiring precise color reproduction.
- White Mini LED:These LEDs typically serve as backlights for LCD panels, generating white light that passes through color filters.
- Edge-lit:LEDs are placed along the edges of the display, with a light guide plate distributing illumination across the screen for thinner form factors.
Chip-on-Board technology is expanding most quickly. White Mini LED technology holds a significant share of existing installations.
Application:
The market's application landscape reveals where Mini LED technology provides the most significant performance advantages and where specific industry needs drive adoption. Each application segment presents unique demands for display characteristics.
- Consumer Electronics:This segment encompasses premium televisions, monitors, and laptops, where Mini LED backlights deliver superior contrast, brightness, and color accuracy. HDR content proliferation drives demand for these high-performance displays in homes.
- Digital Signage:Large-format displays for public information, advertising, and corporate communication utilize Mini LED for its brightness, durability, and high pixel density in direct-view configurations. Leyard specializes in fine-pitch panels for this sector.
- Broadcast Monitors:Professional monitors for television studios and post-production require extreme color accuracy, uniformity, and contrast for critical image evaluation.
- Medical Imaging:High-resolution medical displays benefit from Mini LED's enhanced brightness and contrast, improving diagnostic precision for healthcare professionals.
- Aviation Displays:Cockpit and cabin displays in aircraft demand ruggedized, high-brightness screens with excellent readability in various lighting conditions.
Consumer Electronics holds the largest share of Mini LED applications. Medical Imaging applications are gaining share fastest.
End User:
The end-user segmentation highlights the primary purchasers and integrators of Mini LED technology, reflecting the industry's value chain. Each end-user type has distinct procurement strategies and product development cycles.
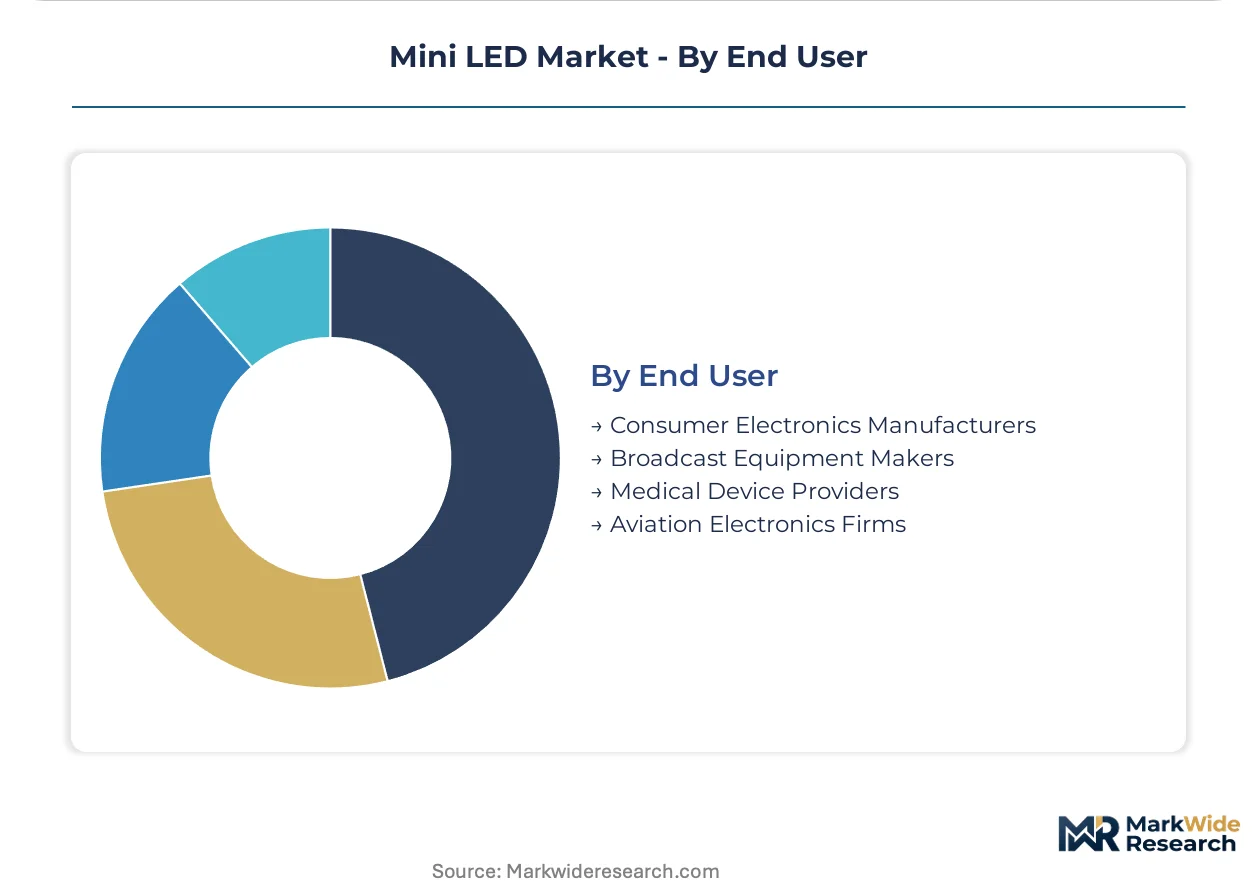
- Consumer Electronics Manufacturers:Companies like Samsung Electronics integrate Mini LED displays into their premium product lines, leveraging in-house production capabilities to differentiate offerings. These manufacturers focus on volume and cost efficiency.
- Medical Device Providers:These firms incorporate Mini LED screens into diagnostic and surgical equipment, prioritizing image clarity, reliability, and regulatory compliance. Enhanced visual precision is a key requirement for their products.
- Broadcast Equipment Makers:Manufacturers of professional video and audio equipment utilize Mini LED displays for their high fidelity and color accuracy in studio monitors.
- Aviation Electronics Firms:Companies specializing in avionics and aerospace systems integrate durable, high-performance Mini LED displays into aircraft cockpits and passenger entertainment systems.
Consumer Electronics Manufacturers drive the greatest volume demand. Medical Device Providers represent a rapidly expanding demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand-side concentration for Mini LED technology is most pronounced in major electronics manufacturing nations, where advanced display production capabilities meet a robust market for premium devices. These regions also host critical component suppliers and display panel producers, creating a self-reinforcing ecosystem for Mini LED adoption.
China
Consumer electronics demand, particularly for premium televisions and high-resolution monitors, drives significant Mini LED adoption in China. The country's GB standards ensure product quality and safety for locally manufactured displays. Shenzhen's vast electronics manufacturing cluster continues to lead in Mini LED panel production and assembly.
South Korea
South Korea exhibits strong demand for Mini LED in high-end consumer electronics and automotive displays. The national quality standards, enforced by organizations like the Korea Agency for Technology and Standards, influence display component specifications. The Seoul-Gyeonggi region hosts major display manufacturers and R&D centers pushing Mini LED innovation.
United States
Demand for Mini LED displays in the United States stems from premium gaming monitors, professional-grade displays, and the expanding automotive sector. The EPA's ENERGY STAR program influences design for energy-efficient Mini LED products in consumer electronics. Silicon Valley and other tech hubs drive innovation in display applications and integration.
Germany
Germany's robust automotive industry and strong market for high-performance industrial displays create significant demand for Mini LED technology. The CE marking certification ensures Mini LED products meet essential health and safety requirements for market access. Bavaria's concentration of automotive suppliers and research institutes fosters advanced display integration.
Taiwan
Taiwan is a critical hub for Mini LED component manufacturing, including LED chips and driver ICs, and also sees demand for high-performance display panels. The Bureau of Standards, Metrology and Inspection (BSMI) sets technical regulations for electronic components. The Hsinchu Science Park anchors a dense cluster of semiconductor and display technology companies.
Mini LED Market Key Industry Players
Backward integration dominates the current landscape, as major display manufacturers seek greater control over the Mini LED supply chain. The market structure is tiered, with large, diversified electronics conglomerates competing alongside specialized display panel producers and component suppliers. Strategic partnerships for technology development and capacity expansion are also key competitive moves.
Among the scale-driven end of the market, Samsung Electronics and LG Electronics exemplify global consumer electronics manufacturers leveraging in-house display technology for premium product lines. Leyard occupies a position as a specialist in large-format digital signage, representing dedicated display solutions providers focused on commercial applications.
| Leading Market Players |
|---|
| Unilumin |
| Absen |
| Samsung Electronics |
| Barco |
| Daktronics |
| LG Electronics |
| Liantronics |
| BOE Technology Group |
| Leyard |
| Others |
Cost & Logistics Intelligence
Mandated safety certifications for consumer electronics in the European Union are forcing Mini LED component suppliers to adapt production processes, directly influencing material costs and pricing structures across the value chain.
Pricing Analysis
Volume-driven segments like consumer electronics experience significant margin compression, while specialized applications such as medical imaging command premium pricing. Transactional per-unit pricing dominates the market. Price differentiation stems from display quality grade, particularly color uniformity, and the level of customization required for specific device integration. Pricing pressure stems from intense competition from OLED technology in high-end consumer electronics. Consumer electronics manufacturers exhibit the highest price sensitivity, whereas medical device providers prioritize performance over initial cost.
Supply Chain Analysis
Regulatory qualification for automotive displays acts as a significant gating factor for new suppliers, ensuring product reliability and safety. Geographic supply concentration for Mini LED components centers on China, Taiwan, and South Korea. The supply chain draws from critical inputs such as microscopic LED chips, specialized driver ICs, and advanced mass transfer equipment. Geopolitical risks and regional supply disruptions pose a structural vulnerability. Downstream distribution runs through direct sales to original equipment manufacturers and through integrated display module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mini LED market is increasingly defined by a cost-of-compliance narrative, where adherence to directives like the European Union's RoHS creates a barrier-to-entry moat for compliant players.
For Market Incumbents:Anchor market share by deepening vertical integration into Mini LED module production. This move helps mitigate supply chain vulnerabilities and enhances quality control. Invest in advanced thermal management solutions to address reliability concerns and differentiate premium offerings. The threat from Micro LED technology necessitates continuous R&D in miniaturization and efficient mass transfer processes. Securing long-term supply agreements for specialized LED chips provides a crucial lever against input price volatility.
For New Entrants and Emerging Players:Capture white-space opportunities in high-growth, less price-sensitive segments like medical imaging or augmented reality. Focus on developing specialized Chip-on-Board (COB) solutions that offer superior pixel density and reliability for niche applications. The automotive sector represents a penetrable segment due to its high demand for durability and performance over cost. A go-to-market angle centered on superior thermal performance and extended product longevity can differentiate new offerings.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking to consolidate manufacturing expertise and intellectual property. Long-term viability over the next 5-10 years depends on technology maturation and cost reduction in mass transfer. Acquisition targets should include mid-sized firms specializing in advanced packaging technologies or high-yield mass production equipment. A signal to watch is the consistent achievement of high manufacturing yield rates, indicating scalability and profitability potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen in-house Mini LED module production | This secures critical supply and enables greater control over display quality for premium products. |
| Invest in advanced thermal management R&D | This extends display longevity and prevents performance degradation in high-brightness applications. |
| Target specialized medical display applications | This captures high-margin demand where superior image clarity directly improves diagnostic precision. |
| Develop standardized component interfaces | This simplifies integration for device makers and reduces supply chain complexity. |
| Form strategic partnerships for Micro LED transition | This positions companies for future display technology shifts and shared development costs. |
Research Approach
Industry reports from leading display technology associations, company annual filings, and patent databases formed the secondary backbone for this analysis. Primary research involved in-depth interviews with display engineers, procurement managers at consumer electronics firms, automotive design leads, and digital signage integrators. This approach combined bottom-up market sizing with top-down validation to ensure comprehensive data coverage.
Historical trendline analysis provided the foundation for projecting market trajectories across the analysis window. The analytical framework modeled market dynamics by product type, technology, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from a synthesis of historical performance and anticipated technological advancements. Forecast inputs included projected HDR content proliferation rates and automotive display integration curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Micro LED technology advancements and manufacturing yield improvements. Forecasts reflect assumptions regarding technological evolution, market acceptance, and regulatory stability. A model refresh is warranted upon material change in mass transfer efficiency or component pricing structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Monochrome Outdoor LED Display Market
LED
Microled Market
LED
UK LED Lighting Market
LED
Architectural LED Products Market
LED
LED Tube Drivers Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Chip on Board LED Market
LED
LED Panel Market
LED
China LED Market
LED
China LED Lighting Market
LED
LED Light Bar Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Europe Outdoor LED Lighting Market
LED
LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market