
 UAE LED Lights Market | 2026-2036
UAE LED Lights Market Size, Share, and Industry Trends Forecast 2026-2036
UAE LED Lights Market Intelligence
Market Overview
China's manufacturing scale is rewriting component economics for UAE importers. Signify N.V. leverages its Eindhoven R&D base to sustain premium positioning in Gulf commercial projects. Acuity Brands Lighting Inc. anchors its regional presence through specification-grade downlight portfolios for hospitality developers. Opple Lighting Co., Ltd. competes aggressively on cost in the residential retrofit channel.
Product & Technology Landscape
LED lights are semiconductor-based solid-state devices that convert electrical energy into visible light through electroluminescence in gallium nitride substrates, typically operating at 80-150 lumens per watt with lifespans exceeding 50,000 hours for commercial-grade modules. Their primary purpose is to displace legacy fluorescent and halogen systems in energy-intensive built environments. Smart lighting controls are capturing the highest margin pools as building automation integration becomes standard in new UAE commercial towers. RGB technology segments are expanding fastest in entertainment and hospitality verticals where dynamic ambience drives specification. Bulb categories remain mature with compressed margins, while fixture and downlight segments concentrate value in specification-driven project channels.
Regulatory Environment
MOHAP enforces energy efficiency labeling for imported lighting products, while the Emirates Authority for Standardization and Metrology mandates IEC 62471 photobiological safety compliance for all LED luminaires sold in the federation. Dubai's Al Saafat green building rating system and Abu Dhabi's Pearl rating criteria embed minimum luminous efficacy thresholds that effectively filter substandard imports from Asian trading partners. Stakeholders must monitor how federal net-zero pathway revisions tighten commercial building energy intensity benchmarks and reshape retrofit prioritization across emirate-level procurement calendars.
Market Dynamics
Federal net-zero building codes are compressing payback periods for commercial retrofits across Dubai and Abu Dhabi, forcing fixture replacement cycles that favor high-efficacy LED systems over legacy fluorescent infrastructure.
Growth Catalysts
- MOHAP Efficiency Mandates:The Ministry of Health and Prevention enforces energy efficiency labeling for imported lighting products, filtering substandard imports and elevating demand for certified commercial-grade LED modules in healthcare and hospitality facilities.
- Smart District Developments:Dubai's smart city initiatives and Abu Dhabi's Masdar City expansion zones are embedding building automation integration as standard, creating specification pull for connected lighting controls in new commercial towers.
- Gallium Nitride Substrates:Advances in GaN-based electroluminescence are pushing commercial-grade LED efficacy toward 150 lumens per watt, shortening payback calculations for large-scale retrofit projects in energy-intensive built environments.
Market Restraints
- Import Concentration Risk:Component sourcing concentrates in Chinese manufacturing clusters, exposing UAE importers to logistics volatility and tariff friction in semiconductor supply chains.
- Technical Degradation Thresholds:Lumen depreciation curves for mid-tier LED modules often underperform rated 50,000-hour lifespans in Gulf ambient temperatures above 45°C, creating warranty exposure for installers.
- Fluorescent Stockpile Inertia:Existing T8 and T5 fluorescent inventories in aging commercial stock delay replacement decisions despite regulatory pressure, particularly in secondary emirate markets outside Dubai and Abu Dhabi.
Strategic Opportunities
- Ras Al Khaimah Hospitality Pipeline:Northern emirate tourism investments remain underpenetrated by specification-grade lighting vendors, creating first-mover positioning for fixture portfolios targeting resort and entertainment developments.
- Human-Centric Lighting Convergence:Circadian rhythm tuning is hybridizing with building management systems in premium commercial towers, opening specification channels for tunable-white and dynamic CCT products in wellness-focused workplace design.
- Al Saafat Rating Acceleration:Dubai's green building rating system is tightening minimum luminous efficacy thresholds faster than federal baselines, creating regulatory tailwind for super-premium LED categories that exceed code by 20-30%.
Industry Challenges
- Photobiological Safety Certification:IEC 62471 compliance testing creates 8-12 week approval bottlenecks at the Emirates Authority for Standardization and Metrology, compressing procurement calendars for fast-track construction projects.
- Legacy Control Protocol Fragmentation:Integration complexity with existing DALI, KNX, and proprietary building automation systems requires specialized commissioning expertise that remains scarce in UAE MEP contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE LED Lights Market |
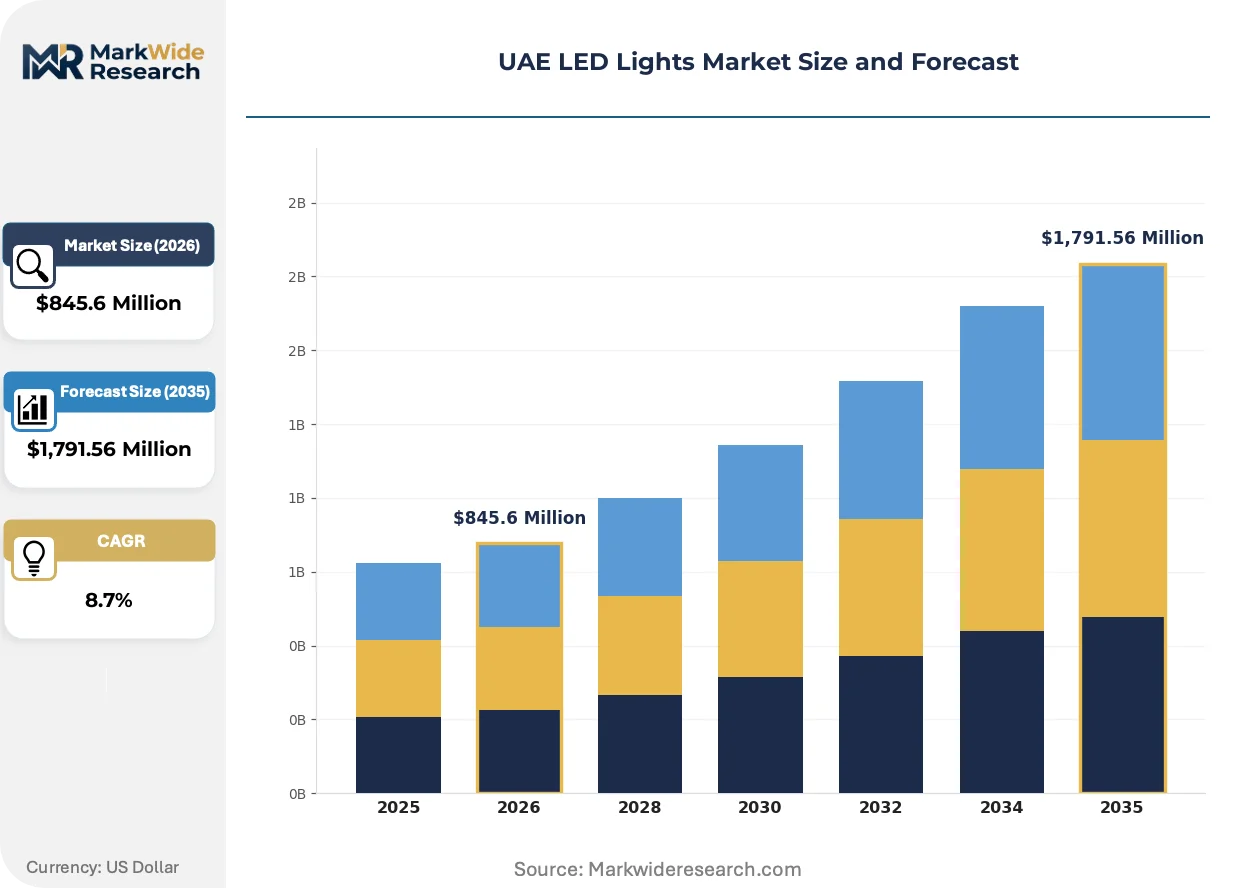
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,791.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Downlights Technology: Smart Lighting, Linear, Dimmable, RGB Application: Residential, Commercial, Industrial, Outdoor End User: Builders, Designers, Homeowners, Businesses |
| Companies Covered | Cree Lighting, Philips Lighting, Signify N.V., GE Lighting, Eaton Corporation, ams OSRAM AG, Opple Lighting Co., Ltd., Ideal Industries, Inc., Acuity Brands Lighting Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE LED Lights Market Strategic Shifts & Innovations
Smart lighting controls are capturing margin pools as building automation integration becomes standard in new UAE commercial towers, while RGB technology segments expand fastest in entertainment and hospitality verticals where dynamic ambience drives specification.
Li-Fi visible light communication is hybridizing data transmission with illumination infrastructure in high-security government and financial facilities. Dubai's smart district developers are piloting Li-Fi-enabled fixtures for electromagnetic-sensitive environments where Wi-Fi interference creates operational risk. This convergence is compressing the boundary between lighting infrastructure and IT network architecture, forcing MEP contractors to acquire data-communications competencies.
MOHAP's energy efficiency labeling requirements are tightening photometric performance disclosure for imported LED products. The regulation forces manufacturers to submit third-party verified lumen maintenance data, elevating documentation burdens for Asian trading partners while creating specification advantage for vendors with established UAE test house relationships. Commercial project channels are responding by consolidating procurement around pre-approved supplier lists.
Buying committees in hospitality and retail sectors are compressing fixture replacement cycles from historical 7-10 year intervals toward 4-5 year technology refresh timelines. This behavioral shift reflects pressure from brand standards teams to maintain consistency with international design trends, displacing the traditional capital-asset depreciation mindset. The pattern is most visible in Dubai's luxury hotel renovation pipeline, where ownership groups treat lighting as a disposable interior element rather than permanent infrastructure.
UAE LED Lights Market Segmentation
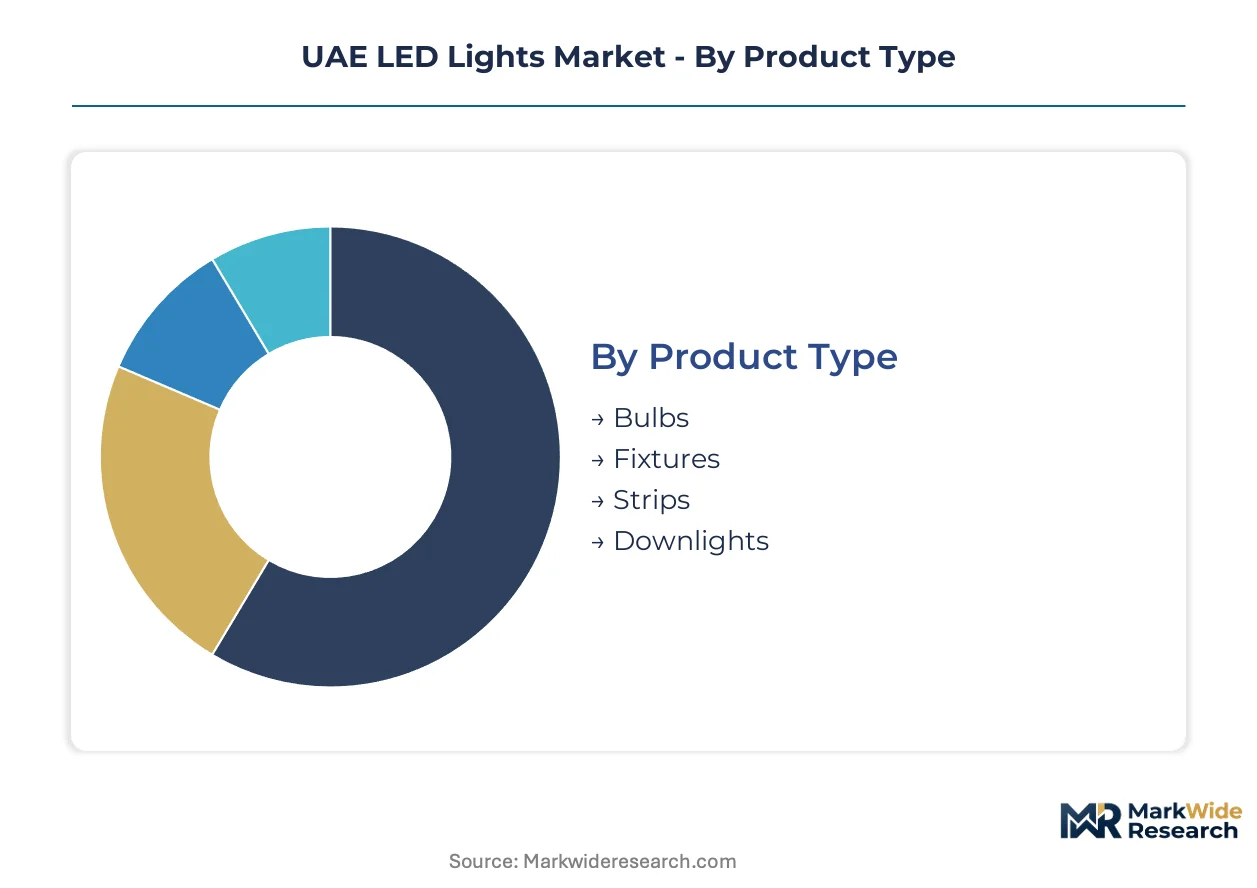
UAE LED market segmentation reveals how regulatory pressure and construction typology reshape procurement patterns. Product and technology categories fragment along specification-grade versus cost-driven fault lines, while application and end-user dimensions track the emirates' divergent real estate development cycles.
Product Type:
Mature categories dominate residential retrofit channels, while emerging fixture formats capture specification margins in commercial new-builds.
- Fixtures:Integrated luminaire systems with heat-dissipating aluminum housings and optical-grade diffusers command premium positioning in Dubai hospitality developments. MOHAP efficiency labeling mandates filter substandard imports, consolidating procurement around certified suppliers for Masdar City commercial towers.
- Downlights:Recessed ceiling modules with 90+ CRI and tight beam-angle control concentrate demand in Abu Dhabi luxury retail fit-outs. Al Saafat rating thresholds for luminous efficacy drive specification toward premium-tier products exceeding federal baselines by substantial margins.
- Bulbs:Retrofit lamps with Edison and bayonet bases serve replacement demand in aging residential stock across secondary emirates.
- Strips:Flexible PCB-mounted diode arrays with adhesive backing penetrate entertainment and cove lighting applications in Ras Al Khaimah resort developments.
Fixtures retain volume leadership; downlights hold the steepest expansion curve.
Technology:
Cost tiers separate connected control systems from commodity illumination, with integration complexity determining margin capture.
- Smart Lighting:Networked luminaires with DALI-2 or wireless mesh protocols embed sensors for occupancy and daylight harvesting. Dubai smart district developers specify these for building automation integration, compressing commissioning timelines for MEP contractors with scarce systems-integration expertise.
- RGB:Multi-diode modules with independent red-green-blue channels enable dynamic color temperature and saturation control. Hospitality brand standards teams in Abu Dhabi and Dubai compress replacement cycles to maintain consistency with international design trends.
- Dimmable:Phase-cut and 0-10V compatible drivers serve commercial retrofit projects seeking compliance with net-zero building codes.
- Linear:Continuous-run extruded aluminum systems with uniform batwing optics address open-plan office and retail corridor applications.
Smart Lighting retains volume leadership; RGB holds the steepest expansion curve.
Application:
Customer type segmentation tracks capital deployment patterns, with institutional procurement diverging sharply from discretionary residential spending.
- Commercial:Office towers, retail malls, and hospitality properties across Dubai and Abu Dhabi drive specification-grade demand. Federal net-zero pathway revisions tighten energy intensity benchmarks, forcing fixture replacement cycles that favor high-efficacy systems.
- Residential:Villa and apartment retrofits in Sharjah and Ajman concentrate demand in cost-optimized bulb and strip categories. Homeowners respond to electricity tariff structures with payback-sensitive purchasing decisions.
- Industrial:Warehousing and manufacturing facilities in Jebel Ali Free Zone require high-bay luminaires with impact-resistant housings and extreme ambient temperature tolerance.
- Outdoor:Street lighting and landscape illumination for municipal infrastructure projects follow emirate-level procurement calendars with extended tender cycles.
Commercial retains volume leadership; Outdoor holds the steepest expansion curve.
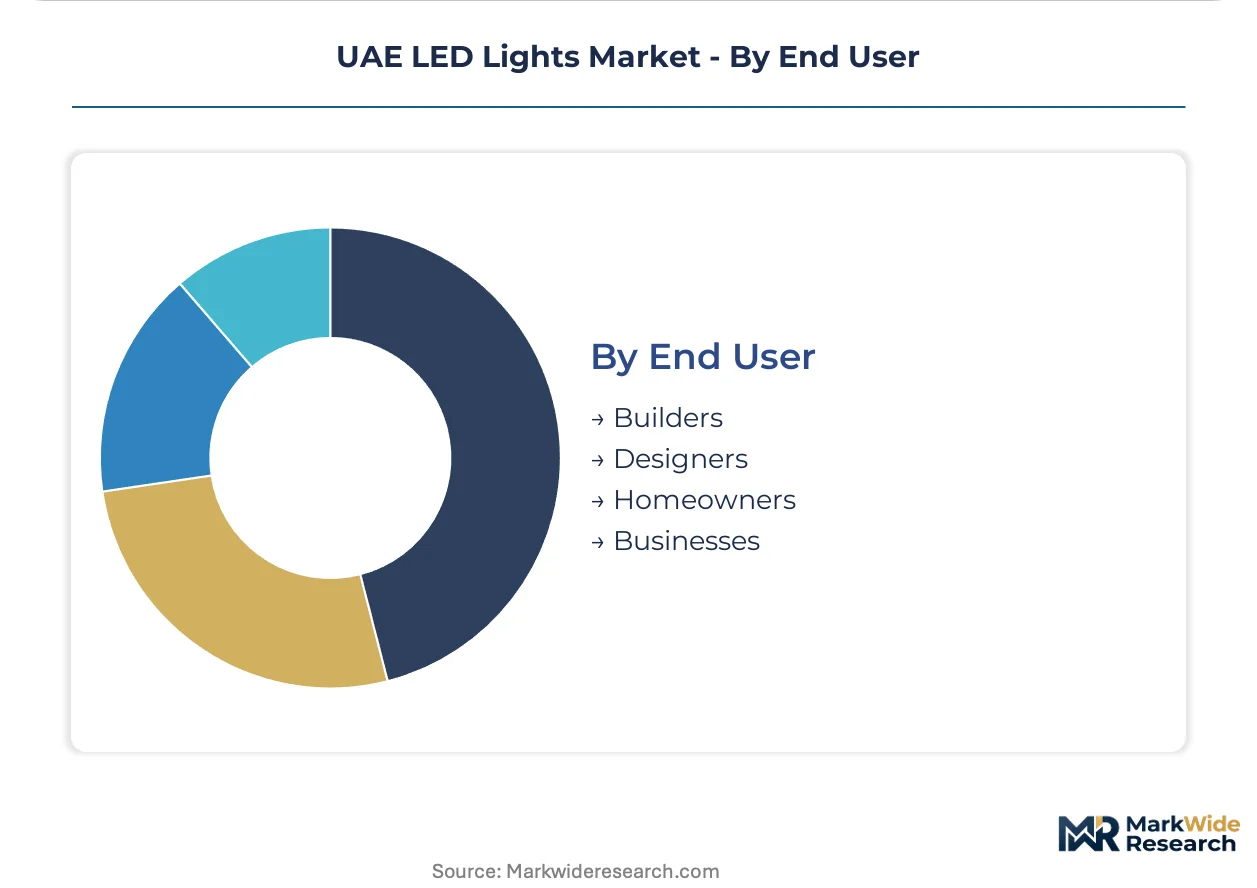
End User:
Volume concentration varies across professional specification channels versus fragmented consumer access points.
- Builders:Large-scale developers with master-planned community mandates consolidate procurement through pre-approved supplier lists. Their buying committees prioritize warranty terms and installation support over upfront unit cost.
- Businesses:Corporate facility managers and retail chains operate on technology refresh timelines compressed from historical intervals. Brand consistency requirements treat lighting as disposable interior elements rather than permanent infrastructure.
- Designers:Interior design and lighting specification consultants influence premium product selection in luxury hospitality and workplace projects.
- Homeowners:Individual purchasers through retail and e-commerce channels exhibit price elasticity and limited technical sophistication.
Builders retain volume leadership; Businesses hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP efficiency mandates and the UAE's net-zero building codes anchor the federation's LED lighting transformation, compressing payback periods for commercial retrofits across emirate-level procurement calendars.
Dubai
Dubai's smart district developments and Al Saafat green building rating system drive specification-grade demand for connected lighting controls. The emirate's minimum luminous efficacy thresholds exceed federal baselines by 20-30%, filtering substandard imports from Asian trading partners. Hospitality and retail buying committees in Downtown Dubai and Dubai Marina compress replacement cycles toward 4-5 year technology refresh timelines.
Abu Dhabi
Abu Dhabi's Masdar City expansion zones embed building automation integration as standard for new commercial towers. The Pearl rating criteria enforce photobiological safety compliance that elevates procurement standards for healthcare and hospitality facilities. Specification consultants influence premium product selection in luxury developments across Saadiyat Island and Al Maryah Island.
Sharjah
Sharjah's residential retrofit channels concentrate demand in cost-optimized bulb and strip categories as homeowners respond to electricity tariff structures. The emirate's aging commercial stock outside prime districts delays fixture replacement decisions despite regulatory pressure. Villa developments in Al Zahia and Tilal City create volume opportunities for mid-tier LED suppliers.
Northern Emirates
Ras Al Khaimah's hospitality pipeline remains underpenetrated by specification-grade lighting vendors targeting resort and entertainment developments. Ajman's secondary market position concentrates procurement in economy-tier products through fragmented retail channels. Tourism investments in Al Marjan Island and Jebel Jais create first-mover positioning for fixture portfolios serving wellness-focused workplace design.
UAE LED Lights Market Key Industry Players
European R&D-centric specialists and Asian cost-optimized manufacturers split the market along specification-grade versus volume-driven fault lines. The vendor base concentrates around three strategic archetypes: premium technology licensors with Eindhoven or Munich R&D bases, mid-tier integrators serving project channels, and scale-driven exporters competing on component economics. Dominant competitive moves include portfolio diversification into smart controls and strategic partnerships with UAE-based MEP contractors.
Within the premium technology tier, Signify N.V. and ams OSRAM AG exemplify R&D-centric positioning through their European headquarters structures. Acuity Brands Lighting Inc. anchors the specification-grade project channel for hospitality developers. Opple Lighting Co., Ltd. occupies the cost-optimized archetype for residential retrofit segments. These three players represent the competitive spectrum from premium luminaire systems to volume bulb categories.
| Leading Market Players |
|---|
| Cree Lighting |
| Philips Lighting |
| Signify N.V. |
| GE Lighting |
| Eaton Corporation |
| ams OSRAM AG |
| Opple Lighting Co., Ltd. |
| Ideal Industries, Inc. |
| Acuity Brands Lighting Inc. |
| Others |
Cost & Logistics Intelligence
Chinese gallium nitride substrate manufacturing clusters concentrate upstream component supply, anchoring margin capture in UAE specification-grade fixture channels where MOHAP certification and Al Saafat rating compliance create procurement filters. Pricing power accumulates with vendors holding established test house relationships and pre-approved supplier status in Dubai smart district developments.
Pricing Analysis
Dubai commands 20-30% premiums over federal baselines for super-premium LED categories exceeding Al Saafat luminous efficacy thresholds. Three-tier pricing structure across specification-grade, certified-commercial, and economy-import levels separates vendors by certification investment and warranty bundling. Cost compression in bulb categories intensifies as Opple Lighting and Asian trading partners compete on component economics. Residential retrofit channels in Sharjah and Ajman exhibit highest price sensitivity, while hospitality developers in Downtown Dubai prioritize technology refresh timelines over unit cost.
Supply Chain Analysis
Export control regimes on advanced GaN epitaxy equipment limit technology transfer from European and American equipment vendors to Chinese manufacturing clusters. Component sourcing concentrates in China, South Korea, and Taiwan for LED chips, drivers, and optical-grade diffusers. Raw material dependencies span rare earth phosphors, aluminum heat-dissipation housings, and copper winding stock. Single-source vulnerability concentrates in advanced GaN substrate supply from Japanese and American wafer manufacturers. Distribution runs through Dubai-based MEP contractor networks and specification consultant channels for commercial projects, with retail fragmentation serving residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP efficiency mandates and federal net-zero pathway revisions are compressing payback periods for commercial retrofits, creating a high-growth disruption as fixture replacement cycles accelerate from 7-10 year intervals toward 4-5 year technology refresh timelines.
For Market Incumbents: Build certification moats through pre-approval relationships with Emirates Authority for Standardization and Metrology test houses. Deepen backward integration into GaN substrate supply partnerships to offset import concentration risk from Chinese manufacturing clusters. Invest in DALI-2 and wireless mesh protocol commissioning capabilities to capture building automation integration demand in Masdar City and Dubai smart district developments. Defend against mid-tier LED module warranty exposure by establishing UAE-based thermal testing facilities for Gulf ambient temperature validation. For New Entrants and Emerging Players: Build out first-mover positioning in Ras Al Khaimah hospitality pipeline where specification-grade lighting vendors remain underpenetrated. Target resort and entertainment developments in Al Marjan Island and Jebel Jais with fixture portfolios emphasizing circadian rhythm tuning and wellness-focused workplace design. Penetrate Ajman and secondary emirate markets through economy-tier bulb and strip categories serving cost-sensitive residential retrofit channels. Establish go-to-market partnerships with UAE-based MEP contractors lacking systems-integration expertise for smart lighting controls. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European R&D-centric specialists holding Eindhoven or Munich headquarters structures and premium technology licensing positions. Long-term viability centers on vendors with established UAE test house relationships and pre-approved supplier status in federal procurement channels. Acquisition targets should demonstrate building automation integration capabilities and human-centric lighting product development. Watch for IEC 62471 photobiological safety compliance bottlenecks compressing procurement calendars as inflection indicator for specification-grade vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Controls Integration | DALI-2 protocol mastery captures building automation specification in Dubai commercial towers. |
| GaN Substrate Partnership | Upstream alliances with Japanese wafer manufacturers reduce single-source supply vulnerability. |
| Test House Pre-Approval | Emirates Authority relationships accelerate IEC 62471 certification for fast-track construction. |
| Circadian Product Development | Tunable-white portfolios penetrate wellness-focused workplace design in premium hospitality. |
| Northern Emirates Distribution | Ras Al Khaimah and Ajman channel buildout captures underpenetrated resort development pipeline. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with lighting specification consultants, MEP contractors, hospitality brand standards teams, and federal procurement officers; and secondary validation through MOHAP regulatory filings, Emirates Authority for Standardization and Metrology certification databases, Al Saafat and Pearl rating system documentation, and customs import records. Bottom-up triangulation across product category shipment data and top-down reconciliation against emirate-level construction spend produced volume and value estimates.
Forecast inputs incorporated technology refresh timeline compression in hospitality and retail sectors, net-zero building code adoption curves across Dubai and Abu Dhabi, and gallium nitride efficacy improvement trajectories. Segmentation modeling spanned product type, technology tier, application vertical, and end-user channel dimensions. CAGRs were derived from installed base replacement dynamics and new-build specification patterns across the projection horizon.
Stress conditions across supply chain disruption severity, regulatory tightening pace, and technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MOHAP enforcement consistency and federal net-zero pathway revision timing. Material shifts in GaN substrate export controls or Emirates Authority certification bottlenecks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Small Pitch LED Display Market
LED
Bluetooth LED Bulb Market
LED
Microled Market
LED
LED Light Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Pixel Pitch LED Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Germany Automotive LED Lighting Market
LED
China LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
Russia LED Market
LED
UK LED Lighting Market
LED
LED Lighting Controllers Market
LED
India Indoor LED Lighting Market
LED
Thailand LED Market
LED
Middle East LED Lighting Market