
 Gaming GPU Market | 2026-2036
Gaming GPU Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming GPU Market Foresight
4K and 8K resolution tiers is unwinding the baseline performance floor for mainstream Gaming GPU purchases. NVIDIA leverages its CUDA ecosystem dominance to sustain developer lock-in across ray-tracing workloads. AMD competes on chiplet architecture economics, while Intel anchors its position through integrated-to-discrete upgrade pathways.
A Gaming GPU is a specialized graphics processing unit engineered for real-time rendering, featuring dedicated VRAM pools, thousands of shader cores, and thermal design power envelopes typically ranging from 75W to 450W. Its primary commercial purpose is to deliver frame rates and visual fidelity required by interactive entertainment software. Discrete GPU configurations command the dominant margin pool as enthusiasts prioritize dedicated memory bandwidth over integrated solutions. Ray Tracing and DLSS technology segments are expanding fastest as game engines natively adopt path-traced lighting and AI upscaling pipelines.
The EPA ENERGY STAR program and EU F-Gas Regulation constrain cooling system chemistries and idle power draw, forcing manufacturers to redesign thermal solutions. China's GB standards and NMPA certification protocols govern electromagnetic compatibility and safety marking for imported graphics hardware. Stakeholders must monitor foundry allocation shifts between AI accelerator and consumer Gaming GPU wafer commitments as capacity trade-offs intensify.
Market Dynamics
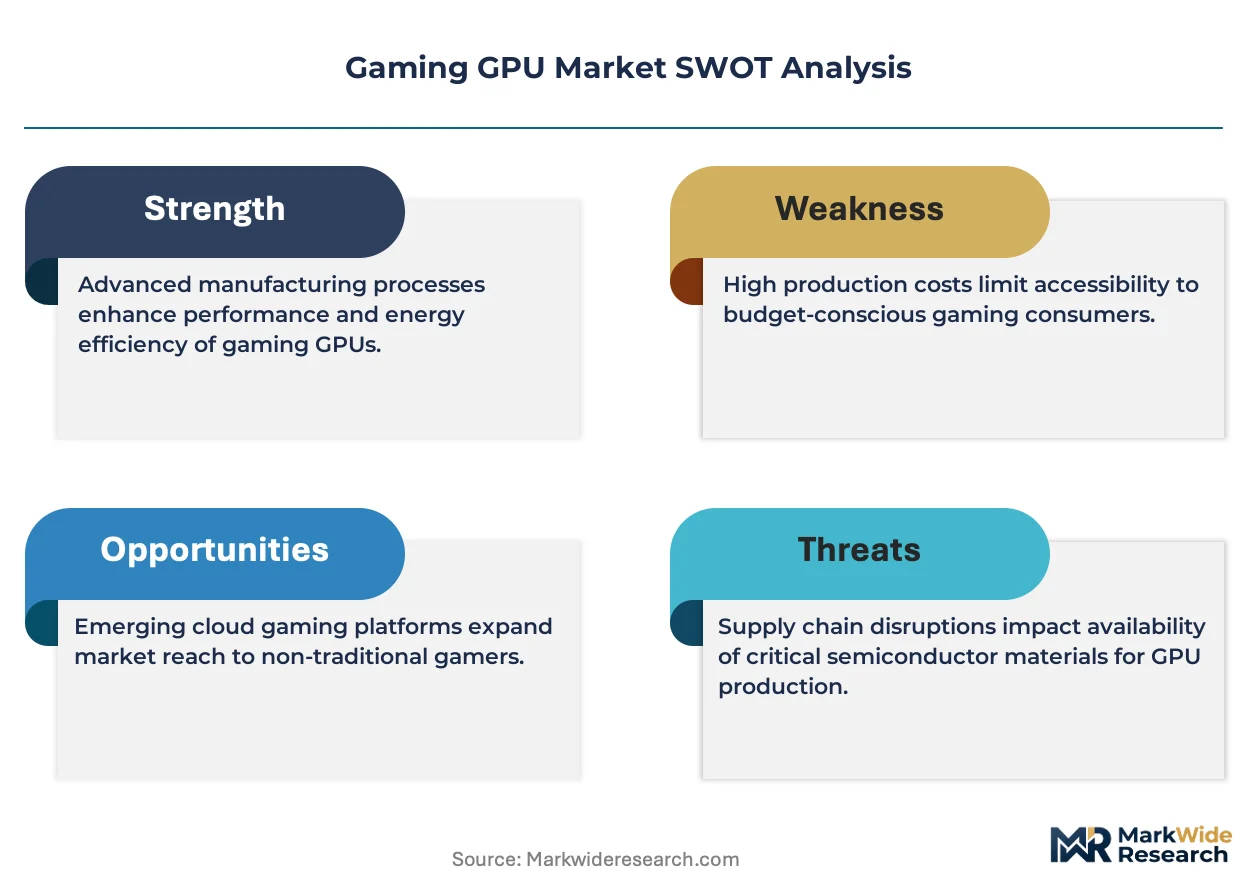
The Gaming GPU market confronts a fundamental capacity tension: foundry wafer allocation now tilts toward AI accelerators, compressing die supply for consumer graphics while cloud gaming simultaneously expands the addressable user base beyond hardware ownership.
Growth Catalysts
- China's GB standards compliance:Domestic electromagnetic compatibility certification accelerates local assembly of gaming systems, shortening upgrade cycles in the world's largest discrete GPU demand pool.
- Path-traced lighting pipelines:Game engines natively integrating ray tracing workloads create mandatory hardware refresh pressure across enthusiast and mainstream tiers simultaneously.
- EU F-Gas Regulation:Thermal design power constraints force innovation in vapor chamber and liquid cooling solutions, opening premium positioning for efficient architectures.
Market Restraints
- TSMC N4/N3 node concentration:Advanced process dependency on Taiwan-based foundries exposes supply continuity to geopolitical friction and natural disaster risk.
- GDDR6X memory cost volatility:High-bandwidth memory module pricing fluctuates with commodity DRAM cycles, squeezing margin on mid-range SKUs.
- Integrated graphics substitution:AMD RDNA3 and Intel Arc iGPU performance gains satisfy casual gaming demand without discrete card purchase.
Strategic Opportunities
- India's esports infrastructure buildout:Arena construction and tournament licensing creates first-time discrete GPU demand among price-sensitive competitive players.
- AI upscaler convergence:Frame generation technology bridging gaming and professional visualization workloads opens workstation adjacent revenue.
- Direct-to-consumer channel expansion:Founders Edition reference sales and subscription bundling bypass distributor margin extraction in established markets.
Industry Challenges
- Verification engineer scarcity:Complex shader compiler and driver stack development bottlenecks product cadence acceleration despite silicon availability.
- Multi-jurisdiction certification lag:Sequential NMPA, FCC, and CE marking timelines delay regional launch windows by 90-120 days post-qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming GPU Market |
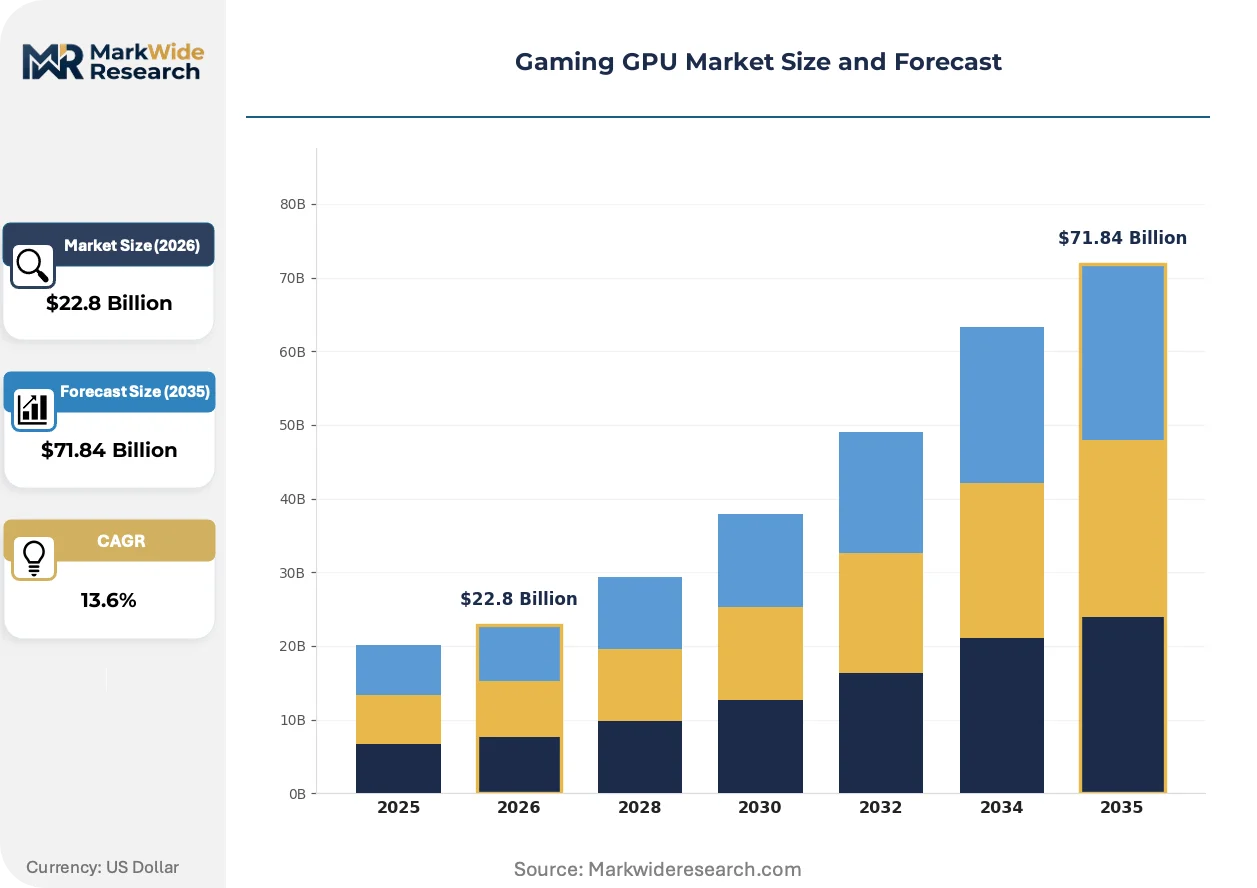
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $71.84 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete GPU, Integrated GPU, External GPU, Workstation GPU Technology: Ray Tracing, Rasterization, DLSS, Variable Rate Shading, Mesh Shading Application: PC Gaming, Console Gaming, Virtual Reality, Cloud Gaming, Esports End User: Hardcore Gamers, Casual Players, Game Developers, Streaming Platforms |
| Companies Covered | MSI, Gigabyte, NVIDIA, PowerColor, Sapphire Technology, AMD, ASUS, Zotac, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming GPU Market Shifts & Advancements
Real-time rendering architectures are bifurcating between brute-force rasterization scaling and neural-compression pipelines, forcing hardware designers to optimize for divergent computational patterns within unified silicon budgets.
Chiplet-based GPU architectures are supplanting monolithic die designs in high-end segments. AMD's RDNA3 and forthcoming RDNA4 products segment compute and memory controllers across multiple dies connected by high-speed interconnects. Enthusiast buyers now accept inter-die latency tradeoffs in exchange for improved yield economics and scalable VRAM configurations. This modular approach is supplanting traditional monolithic flagship dies as the dominant cost-control mechanism for complex silicon.
The EU F-Gas Regulation and EPA ENERGY STAR program impose concurrent constraints on cooling system chemistries and idle power draw. Manufacturers must eliminate high-global-warming-potential refrigerants from vapor chamber production while maintaining thermal headroom for 450W flagship SKUs. European and North American product lines now diverge in thermal solution specification, complicating global SKU rationalization and inventory positioning.
Subscription bundling of cloud gaming services with broadband and mobile plans is fragmenting the traditional hardware upgrade cycle. Microsoft, NVIDIA, and emerging regional platforms now capture gaming spend through recurring fees rather than discrete component sales. China and Southeast Asia exhibit the most pronounced behavioral shift, where 5G infrastructure enables low-latency streaming that substitutes for local GPU investment among casual and mid-core player segments.
Gaming GPU Market Segmentation
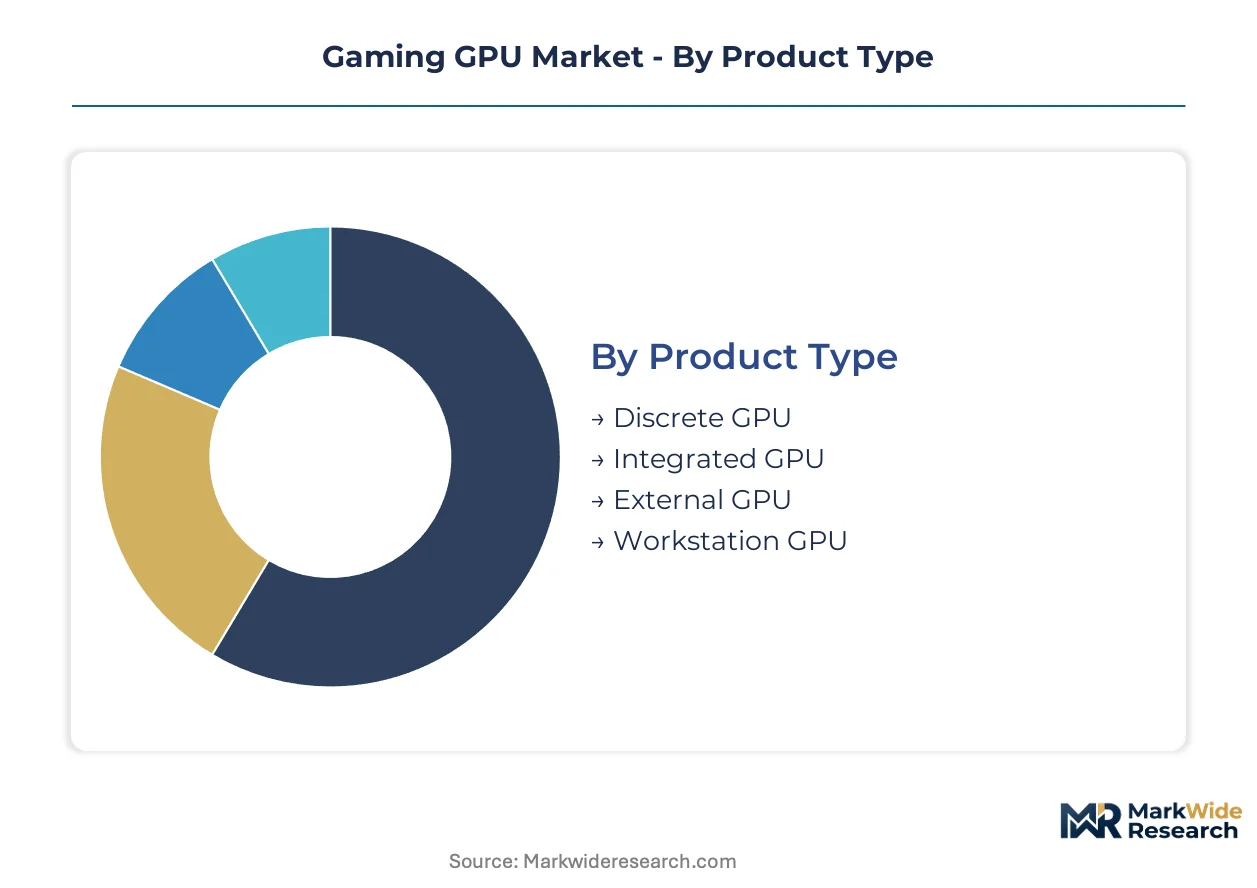
Gaming GPU segmentation reveals how substitution pressures fragment demand across hardware ownership models. Discrete and integrated solutions now compete directly for the same user minutes, while cloud infrastructure abstracts performance from local silicon entirely.
Product Type:
Integrated graphics substitution threatens discrete GPU volume most acutely at the entry tier, where RDNA3 and Intel Arc iGPUs now satisfy casual gaming requirements without add-in card purchase.
- Discrete GPU:Dedicated add-in cards with dedicated VRAM pools and thermal envelopes spanning 75W to 450W. Demand concentrates among China's esports infrastructure buildout and enthusiast upgrade cycles, though foundry wafer allocation tilts toward AI accelerators compressing die supply.
- Integrated GPU:Silicon embedded within CPU packages sharing system memory bandwidth. Casual players in Southeast Asia increasingly defer discrete purchases as AMD and Intel iGPU performance crosses 1080p60 thresholds in popular multiplayer titles.
- External GPU:Thunderbolt and USB4 enclosures housing desktop-class graphics for laptop expansion. Niche positioning among mobile workstation users and compact form-factor builders seeking thermal flexibility.
- Workstation GPU:Professional-certified silicon with ISV validation and ECC memory support. Game developers and visualization studios bridge gaming and professional pipelines through AI upscaler convergence.
Discrete GPU anchors the volume base while integrated GPU gains share at the steepest rate.
Technology:
Cost tier stratification separates premium neural-compression pipelines from baseline rasterization, with ray tracing and DLSS commanding price premiums that widen manufacturer margins.
- Ray Tracing:Hardware-accelerated path-traced lighting through dedicated RT cores. Hardcore gamers in China and North America drive mandatory refresh pressure as Unreal Engine and Unity natively integrate real-time global illumination.
- Rasterization:Traditional triangle-based rendering without lighting simulation overhead. Casual players and esports competitors prioritize frame rate consistency over visual fidelity, sustaining demand for efficient shader architectures.
- DLSS:AI frame generation and upscaling reconstructing higher-resolution output from lower internal render targets. Cloud gaming platforms license NVIDIA's SDK to reduce datacenter GPU density requirements.
- Variable Rate Shading:Per-pixel shading rate modulation preserving performance in peripheral vision regions. VR headset manufacturers adopt foveated rendering pipelines to manage wireless bandwidth constraints.
- Mesh Shading:Geometry pipeline reorganization enabling orders-of-magnitude more objects per scene. Open-world game developers leverage amplification shaders for dense foliage and crowd simulation.
Rasterization retains the installed base while ray tracing expands most quickly through engine-native adoption.
Application:
Volume concentration in PC gaming confronts behavioral fragmentation as 5G infrastructure enables streaming substitution across emerging markets.
- PC Gaming:Windows-based discrete and integrated graphics driving Steam and Epic Games Store libraries. China's domestic foundry investments and GB standards compliance accelerate local system assembly.
- Console Gaming:Semi-custom AMD silicon in PlayStation and Xbox platforms with fixed specifications. Console refresh cycles drive discrete GPU architecture roadmaps through volume guarantees.
- Virtual Reality:High-refresh, low-persistence displays demanding sustained 90-120fps rendering. Meta and ByteDance hardware investments concentrate demand in North America and China.
- Cloud Gaming:Remote rendering with video stream delivery to thin clients. Microsoft, NVIDIA, and regional platforms capture recurring revenue in India and Southeast Asia where infrastructure investment outpaces local GPU affordability.
- Esports:Competitive titles optimized for frame rate consistency over visual quality. Tournament organizers in India and China specify certified hardware configurations creating reference design demand.
PC gaming anchors the revenue base while cloud gaming climbs the fastest through subscription bundling with broadband and mobile plans.
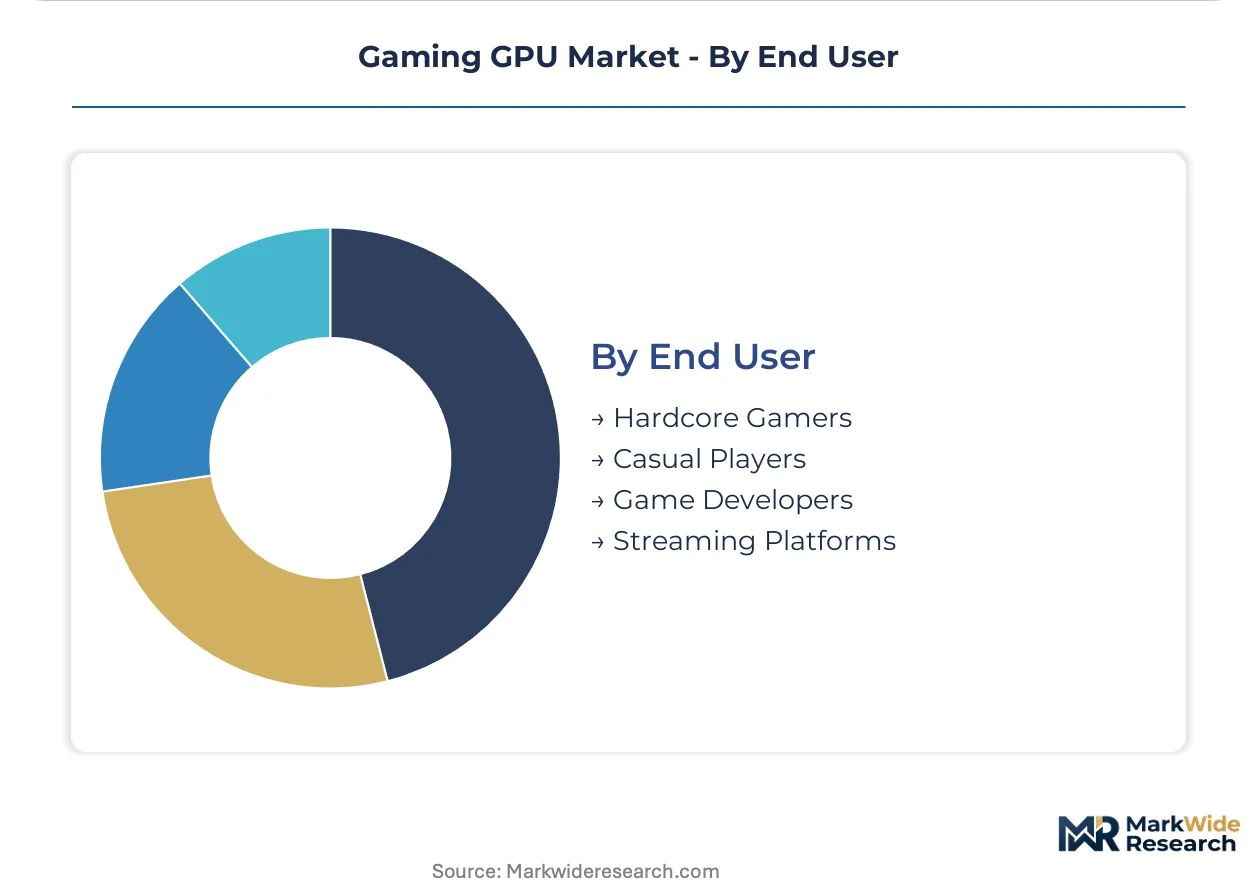
End User:
Customer type maturity separates replacement-driven enthusiasts from first-time purchasers, with streaming platforms emerging as indirect demand aggregators through content creator sponsorship.
- Hardcore Gamers:Enthusiasts prioritizing 4K and 8K resolution tiers with maximum settings. China's esports infrastructure and North American content creator economy sustain premium SKU pricing power.
- Casual Players:Intermittent users satisfied by integrated graphics or entry discrete cards. Mobile-to-PC migration in India and Southeast Asia creates price-sensitive volume requiring efficient architectures.
- Game Developers:Studios requiring workstation-class validation and debug tooling. Unreal Engine and Unity native ray tracing adoption forces hardware refresh across indie and AAA tiers simultaneously.
- Streaming Platforms:Cloud service operators and content delivery networks provisioning GPU density. Microsoft Azure and regional Chinese platforms negotiate wafer allocation commitments directly with foundries.
Hardcore gamers anchor the margin pool while streaming platforms expand most quickly through infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry wafer allocation tilts heavily toward Taiwan-based production, exposing consumer Gaming GPU supply chains to geopolitical friction while China's domestic assembly accelerates through GB standards compliance. Regulatory divergence between the EU F-Gas Regulation and EPA ENERGY STAR programs forces thermal solution customization by geography.
China
Domestic foundry investments and esports infrastructure buildout compress upgrade cycles in the world's largest discrete GPU demand pool. GB standards certification for electromagnetic compatibility accelerates local system assembly, reducing import dependency. Shanghai and Shenzhen clusters concentrate add-in card manufacturing and tournament venue construction.
United States
Content creator economy monetization and 4K/8K display adoption sustain premium SKU pricing power among enthusiast segments. EPA ENERGY STAR idle power draw constraints force vapor chamber redesigns for flagship thermal envelopes. Austin and Silicon Valley host GPU architecture design centers and cloud gaming platform headquarters.
Germany
EU F-Gas Regulation compliance eliminates high-global-warming-potential refrigerants from cooling system production, favoring efficient architectures. CE marking and dual carbon goal alignment position German distributors as regulatory gatekeepers for European volume. Munich and Stuttgart clusters specialize in workstation GPU integration for automotive visualization pipelines.
India
Esports arena construction and tournament licensing create first-time discrete GPU demand among price-sensitive competitive players. BIS electromagnetic compatibility certification and PLI scheme incentives attract local assembly investment. Bangalore and Hyderabad concentrate game development studios driving hardware refresh requirements.
South Korea
5G infrastructure density enables low-latency cloud gaming substitution, fragmenting traditional hardware ownership models among casual segments. MFDS and KC certification protocols govern electromagnetic safety for imported graphics hardware. Seoul Capital Area hosts esports tournament operators specifying certified hardware configurations.
Gaming GPU Market Competitive Landscape
Concentration sits with semiconductor architects controlling foundry allocation and software ecosystem lock-in. Three archetypes define competitive positioning: silicon designers with foundry partnerships, add-in card partners executing thermal and distribution customization, and cloud platform operators abstracting hardware ownership entirely. Strategic moves center on AI upscaler licensing expansion and direct-to-consumer channel bypass of distributor margins.
Among fabless semiconductor architects, NVIDIA, AMD, and Intel occupy distinct positioning vectors. NVIDIA exemplifies ecosystem dominance through developer toolchain integration. AMD represents chiplet architecture economics and console semi-custom volume guarantees. Intel anchors integrated-to-discrete upgrade pathway capture for casual segment conversion.
| Leading Market Players |
|---|
| MSI |
| Gigabyte |
| NVIDIA |
| PowerColor |
| Sapphire Technology |
| AMD |
| ASUS |
| Zotac |
| Intel |
| Others |
Supply & Pricing Matrix
Foundry-scale economics at TSMC and Samsung anchor both die supply availability and baseline cost floors for add-in card manufacturers. Wafer allocation trade-offs between AI accelerators and consumer Gaming GPUs compress die supply while simultaneously elevating price floors for available capacity. China's GB standards compliance and the EU F-Gas Regulation add certification and thermal redesign costs that stratify final pricing across regional product lines.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure through thermal solution compliance costs that manufacturers pass to European markets. Three-tier pricing structure across premium, standard, and economy levels separates enthusiast flagships with vapor chamber liquid cooling from mainstream dual-fan designs and entry blower configurations. Cost compression in the mid-range tier is intensifying because GDDR6X memory module pricing fluctuates with commodity DRAM cycles. Casual players in Southeast Asia exhibit highest price sensitivity, while China's esports infrastructure sustains premium SKU pricing power among hardcore enthusiasts.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced process nodes, with TSMC N4/N3 production concentrated in Hsinchu and Samsung's EUV lines in Pyeongtaek. Silicon draws from high-purity germanium substrates and specialized photoresist chemistries, while packaging rests on ABF substrate and GDDR6X memory module supply from Samsung and Micron. Single-source vulnerability at TSMC for leading-edge nodes exposes continuity to geopolitical friction. Distribution runs through add-in card partners executing thermal customization, then through distributor networks to system integrators and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gaming GPU market sits in early-stage cyclical recovery as path-traced lighting pipelines in Unreal Engine and Unity force mandatory hardware refresh across enthusiast and mainstream tiers simultaneously.
For Market Incumbents: Compound ecosystem lock-in through AI upscaler SDK licensing to cloud gaming platforms, reducing datacenter GPU density requirements while capturing recurring revenue streams. Defend against integrated graphics substitution by accelerating chiplet architecture roadmaps that improve yield economics. Deepen backward integration into ABF substrate supply to secure packaging capacity amid allocation constraints.
For New Entrants and Emerging Players: Lead with external GPU enclosures targeting mobile workstation users and compact form-factor builders seeking thermal flexibility outside incumbent add-in card dominance. India's esports infrastructure buildout offers the most penetrable geography, where tournament licensing creates first-time discrete GPU demand among price-sensitive competitive players. Pursue direct-to-consumer channel expansion through reference design sales to bypass established distributor margin extraction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chiplet architecture specialists with console semi-custom volume guarantees and foundry allocation commitments. Long-term viability rests on capturing AI upscaler convergence bridging gaming and professional visualization workloads. The signal to monitor is wafer allocation shifts between AI accelerator and consumer Gaming GPU commitments at TSMC and Samsung.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Upscaler SDK Licensing | NVIDIA's DLSS licensing to Microsoft Azure reduces datacenter GPU density requirements while capturing recurring platform revenue. |
| Chiplet Architecture Roadmap | AMD's RDNA4 segmentation across multiple dies improves yield economics and enables scalable VRAM configurations for enthusiast tiers. |
| Direct-to-Consumer Channel Expansion | Founders Edition reference sales bypass distributor margin extraction and capture price-sensitive volume in established markets. |
| External GPU Enclosure Development | Thunderbolt and USB4 enclosures address mobile workstation users seeking desktop-class graphics without system replacement. |
| Thermal Solution Regional Customization | EU F-Gas Regulation compliance eliminates high-GWP refrigerants, favoring efficient architectures in European product lines. |
Research Methodology
A spread of perspectives from GPU architecture leads at fabless semiconductor designers, add-in card thermal engineering directors, esports tournament organizers, and cloud gaming platform procurement officers converged on the working assumptions. Secondary validation drew from TSMC and Samsung foundry capacity disclosures, EPA ENERGY STAR program specifications, EU F-Gas Regulation compliance timelines, and China GB standards certification protocols. Bottom-up triangulation across discrete GPU unit economics and top-down reconciliation against foundry wafer allocation estimates anchored volume and value outputs.
Segmentation dimensions modeled include product type, technology tier, application, and end user archetype across the projection horizon. CAGRs derived from installed base refresh cycle analysis, engine-native ray tracing adoption curves, and cloud gaming subscription penetration patterns in India and Southeast Asia. Foundry capacity trade-offs between AI accelerators and consumer Gaming GPUs, alongside GDDR6X memory cost volatility, fed sensitivity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained path-traced lighting pipeline adoption or accelerated foundry node transitions would require recalibration. Forecasts reflect assumptions regarding electromagnetic compatibility certification timelines and thermal solution chemistry compliance. Recalibration cycles align with material shifts in foundry allocation priorities and game engine rendering architecture decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Polymer Core Solder Ball Market