
 Infrared (IR) LED Market | 2026-2036
Infrared (IR) LED Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared (IR) LED Market Intelligence
Modular packaging of IR LED arrays into plug-and-play sensor modules is shifting procurement patterns for automotive and security OEMs. ams-OSRAM AG leverages its vertically integrated epitaxy-to-package model to dominate high-reliability automotive tiers. Vishay Intertechnology, Inc. sustains broad catalog depth across through-hole and surface-mount formats for industrial buyers. Epistar Corporation anchors wafer supply for downstream packagers across Asia-Pacific manufacturing clusters.
An infrared LED emits electromagnetic radiation at wavelengths between 700 nanometers and 1 millimeter, typically fabricated from gallium arsenide or aluminum gallium arsenide compound semiconductors through metal-organic chemical vapor deposition. These devices serve as non-visible illumination sources for night vision, proximity sensing, optical data transmission, and biometric authentication systems. High-power IR LEDs command premium positioning in automotive LiDAR and defense night-vision applications where thermal management and radiant intensity determine performance. Surface-mount LEDs capture volume share in consumer electronics and smart home devices where miniaturization and automated assembly drive cost economics. Through-hole formats retain niche dominance in industrial automation and agricultural monitoring equipment requiring manual replacement and mechanical robustness.
The US FDA regulates IR LED emissions in medical and consumer diagnostic devices, while the FCC governs spectrum compatibility for telecommunications-linked infrared modules. REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging substrates, directly affecting material selection for GaAs and AlGaAs device fabrication. China's MIIT enforces GB standards for optoelectronic component reliability in domestic security and automotive supply chains. Stakeholders must monitor evolving automotive safety certifications and export control classifications for defense-linked infrared technologies.
Market Dynamics
Automotive LiDAR integration is compressing qualification timelines for IR LED suppliers, forcing simultaneous compliance with AEC-Q101 automotive reliability standards and OEM-specific thermal cycling protocols that exceed consumer-grade specifications.
Growth Catalysts
- Driver-monitoring mandates:Euro NCAP's 2026 safety rating requirements for occupant status detection are accelerating infrared array deployment across European vehicle platforms.
- GaN-on-Si epitaxy advances:Foundries in Taiwan and Malaysia are scaling 150mm gallium nitride-on-silicon processes that reduce substrate costs for high-power emitters.
- REACH substance restrictions:ECHA's tightened cadmium and lead thresholds in compound semiconductors are pushing packagers toward certified green supply chains that command OEM preference.
Market Restraints
- Arsenic precursor volatility:Trimethylgallium and arsine pricing fluctuates with Chinese environmental enforcement cycles, compressing foundry margins unpredictably.
- Epitaxy equipment concentration:MOCVD reactor supply concentrates among three Japanese and German toolmakers, creating 18-month lead time bottlenecks for capacity expansion.
- VCSEL substitution in 3D sensing:Vertical-cavity surface-emitting lasers capture smartphone proximity slots above 940nm, displacing edge-emitting IR LEDs in flagship handset designs.
Strategic Opportunities
- Agricultural automation in Brazil:Precision livestock monitoring and crop health imaging systems remain 70% import-dependent, creating localization partnerships for packaged emitter modules.
- IEC 60825-1 alignment:Harmonized laser safety classifications across EU, US, and Asian markets reduce retesting burdens for multi-region product launches.
- SWIR band extension:Convergence of 1400-1600nm emitters with InGaAs image sensors opens industrial inspection and semiconductor wafer metrology applications beyond traditional NIR limits.
Industry Challenges
- Compound semiconductor process engineering:MOCVD technicians with GaAs/AlGaAs growth expertise command 40% salary premiums over silicon analogs, constraining foundry hiring in Germany and Japan.
- Automotive qualification timelines:AEC-Q101 certification cycles extend 24-36 months, locking working capital before volume shipments commence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared (IR) LED Market |
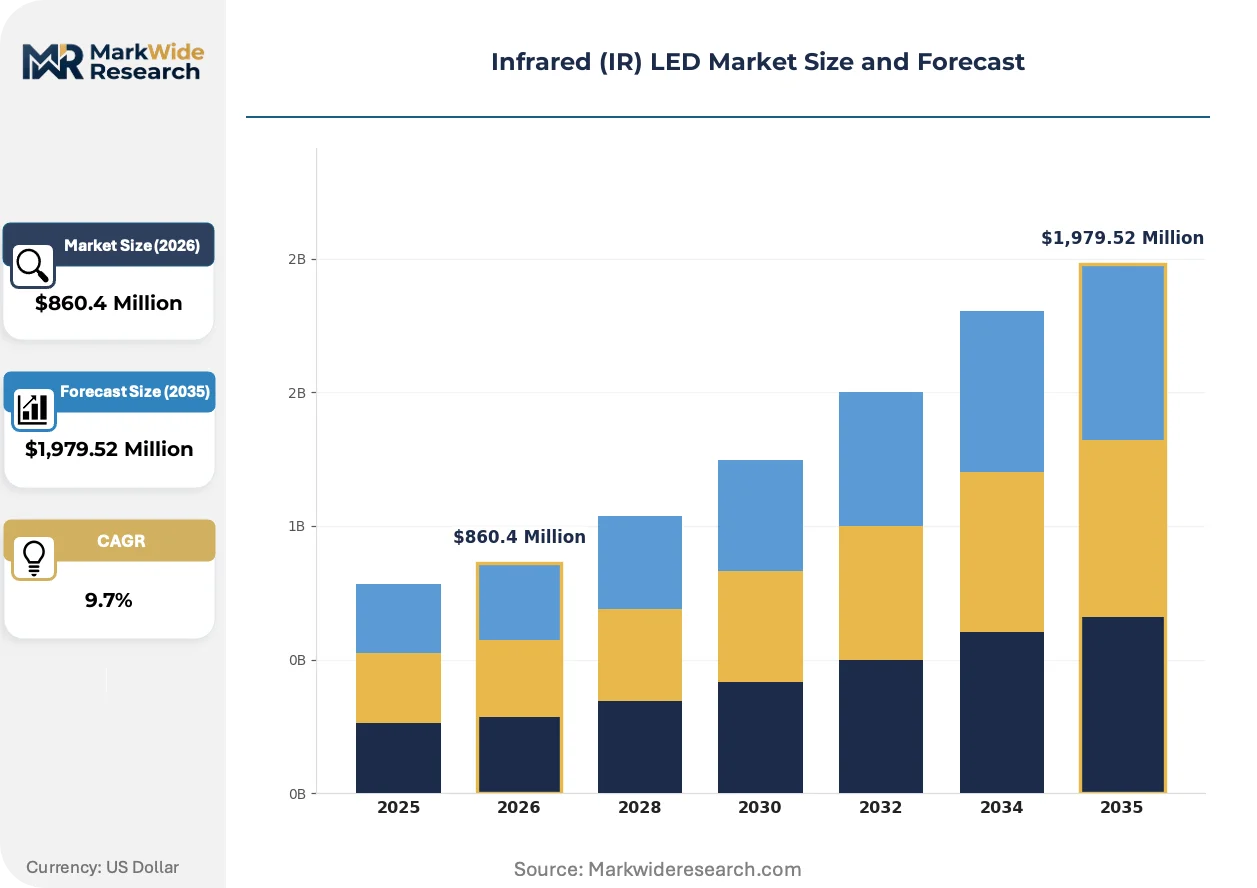
| Market Size in 2026 | $860.4 Million |
| Market Size in 2035 | $1,979.52 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard IR LEDs, High-Power IR LEDs, Surface-Mount LEDs, Through-Hole LEDs, Bi-Color IR LEDs Technology: GaAs, AlGaAs, InGaAs, Silicon Photonics, Quantum Dot LEDs Application: Night Vision Systems, Gesture Recognition, Automotive Sensors, Security Surveillance, Smart Home Devices End User: Consumer Electronics, Defense & Aerospace, Telecommunications Equipment, Industrial Automation, Agricultural Monitoring |
| Companies Covered | Everlight Electronics Co., Ltd., Vishay Intertechnology, Inc., Lumileds Holding B.V., Lite-On Technology Corp, Epistar Corporation, ams-OSRAM AG, Excelitas Technologies Corp., GJD Manufacturing Ltd., Ennostar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared (IR) LED Market Strategic Shifts & Innovations
Packaging miniaturization and thermal management architectures are converging to enable new form factors that penetrate previously inaccessible device categories. Three developments merit particular attention.
Flip-chip ceramic substrate technology is rewriting the thermal dissipation ceiling for automotive LiDAR emitters. Tier 1 suppliers in Germany and Japan are qualifying copper-pillar bumped arrays that sustain 5W continuous output in 125°C ambient conditions. This packaging shift is compressing the performance gap between discrete LEDs and laser diodes in long-range sensing modules.
RoHS exemptions for hexavalent chromium in corrosion-resistant coatings expire in 2026, forcing European packagers to validate alternative metallization schemes for GaAs device terminations. The transition affects primarily high-reliability automotive and aerospace segments where tin whisker mitigation previously depended on chromate conversion layers. Suppliers are accelerating nickel-palladium-gold plating qualification to maintain CE marking eligibility.
Consolidated procurement of IR LED arrays alongside photodiodes and driver ICs is displacing component-level sourcing in security camera OEMs. Integrated module suppliers in China and South Korea now capture 60% of bill-of-material value previously distributed across discrete vendors. This bundling concentrates negotiation leverage among vertically integrated packagers with captive epitaxy capacity.
Infrared (IR) LED Market Segmentation
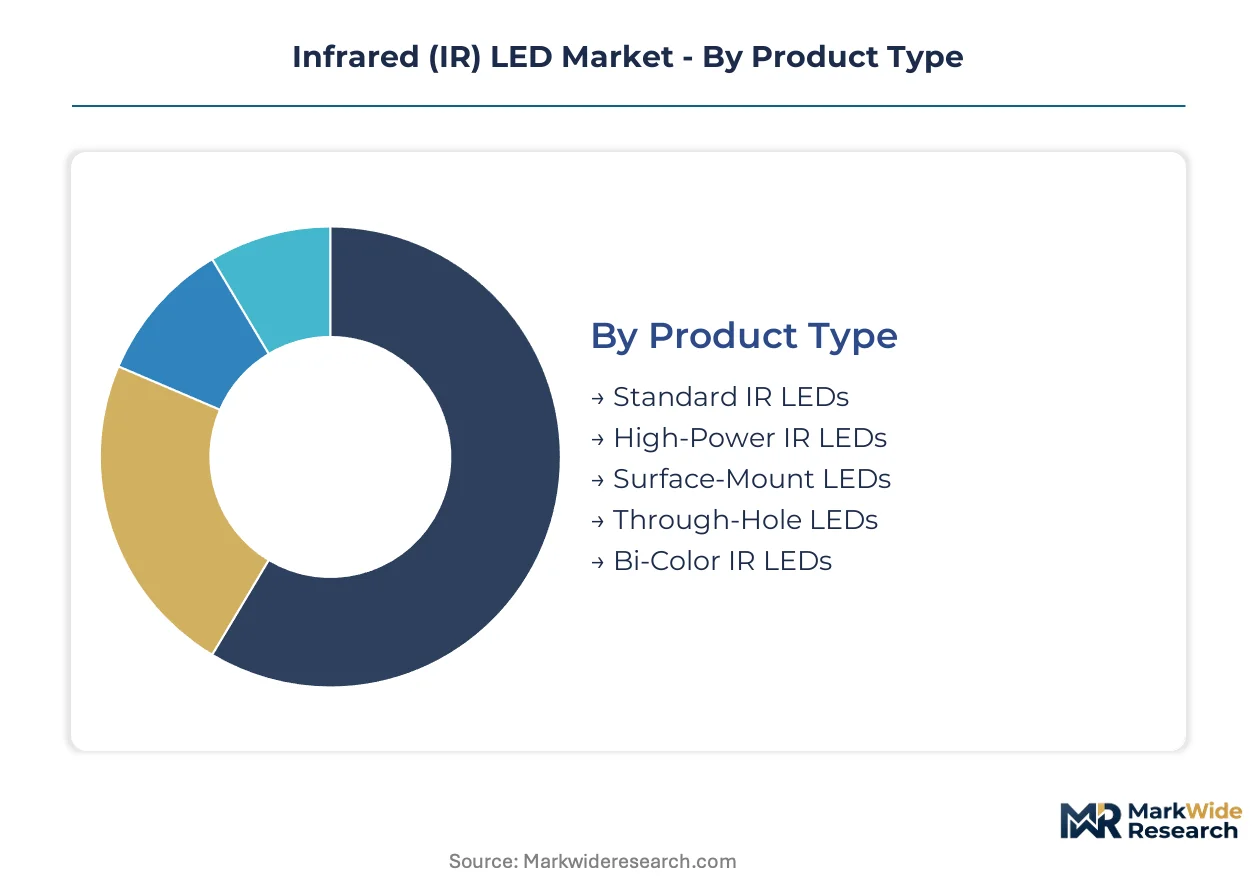
IR LED procurement patterns diverge sharply across performance tiers and mounting formats, with automotive qualification requirements reshaping supplier portfolios while consumer electronics volumes compress unit economics. Understanding these segment boundaries clarifies where foundry capacity investments concentrate versus where packaging commoditization dominates.
Product Type:
Customization intensity spans from standardized commodity emitters to application-specific thermal architectures, with automotive and defense buyers demanding bespoke qualification trails.
- Standard IR LEDs:Conventional gallium arsenide emitters at 850nm and 940nm wavelengths serve as the workhorse for proximity sensing and basic illumination. Demand concentrates in Chinese smart home manufacturing clusters where automated assembly lines absorb billions of units annually, though margin compression from Vietnamese packagers is intensifying price competition.
- High-Power IR LEDs:Multi-junction architectures with ceramic submounts deliver 1-5W radiant output for LiDAR flood illumination and long-range night vision. German automotive Tier 1s dominate procurement, with AEC-Q101 qualification cycles locking suppliers into 24-month validation programs before volume shipments commence.
- Surface-Mount LEDs:Compact 0603 and 0805 footprints enable dense PCB layouts for wearable health monitors and smartphone face authentication.
- Through-Hole LEDs:Radial and axial lead formats persist in agricultural soil sensors and industrial limit switches where field replaceability trumps miniaturization.
- Bi-Color IR LEDs:Dual-wavelength packages combining 850nm and 940nm emission simplify optical calibration in multi-spectral imaging systems.
Leading the category by volume: Surface-Mount LEDs. Growing fastest: High-Power IR LEDs.
Technology:
Material systems stratify by wavelength precision, thermal budget, and epitaxy equipment accessibility, with compound semiconductor expertise commanding scarcity premiums.
- GaAs:Direct-bandgap substrates at 870-940nm emission dominate cost-sensitive proximity applications. Taiwanese foundries in Hsinchu anchor wafer supply, though Chinese environmental enforcement on arsenic precursors injects raw material volatility into margin structures.
- AlGaAs:Aluminum gallium arsenide heterostructures tune bandgaps across 700-900nm for spectroscopic accuracy in medical glucose monitors and gas detection systems. Japanese epitaxy houses in Tokyo and Osaka concentrate proprietary MOCVD recipes, with process engineers commanding 40% salary premiums over silicon analogs.
- InGaAs:Indium gallium arsenide extends emission into 1400-1600nm short-wave infrared for semiconductor wafer inspection and moisture sensing.
- Silicon Photonics:CMOS-compatible waveguide integration enables dense optical interconnect arrays for data center transceivers.
- Quantum Dot LEDs:Colloidal nanocrystal emitters promise narrow spectral linewidths for next-generation spectral sensing, though reliability qualification lags compound semiconductor maturity.
Volume leadership rests with GaAs wafers. AlGaAs commands the steepest expansion trajectory as medical and automotive precision requirements tighten.
Application:
Use-case thermal profiles and optical duty cycles determine whether standard or high-power architectures penetrate each vertical.
- Night Vision Systems:Covert 850nm and 940nm illumination for military goggle and security camera augmentation demands zero near-infrared detectability. US defense contractors in Texas and Arizona specify MIL-STD-810G environmental testing, with ITAR export controls constraining supplier eligibility.
- Gesture Recognition:Time-of-flight arrays in smart displays and gaming peripherals require synchronized emitter-detector calibration. South Korean consumer electronics OEMs in Seoul and Suwon dominate module integration, with 940nm preference reducing visible red glow in dark room environments.
- Automotive Sensors:Driver-monitoring cameras and cabin occupancy detection mandate AEC-Q101 reliability across -40°C to 125°C operating windows.
- Security Surveillance:Weatherproof IR illuminators for perimeter monitoring balance throw distance against power consumption.
- Smart Home Devices:Doorbell cameras and voice-activated hubs integrate proximity sensing for wake-on-approach functionality.
Security Surveillance leads by installed base. Automotive Sensors gain share fastest as Euro NCAP mandates accelerate OEM deployment.
End User:
Buyer sophistication and qualification burden separate defense-aerospace procurement from high-volume consumer electronics tenders.
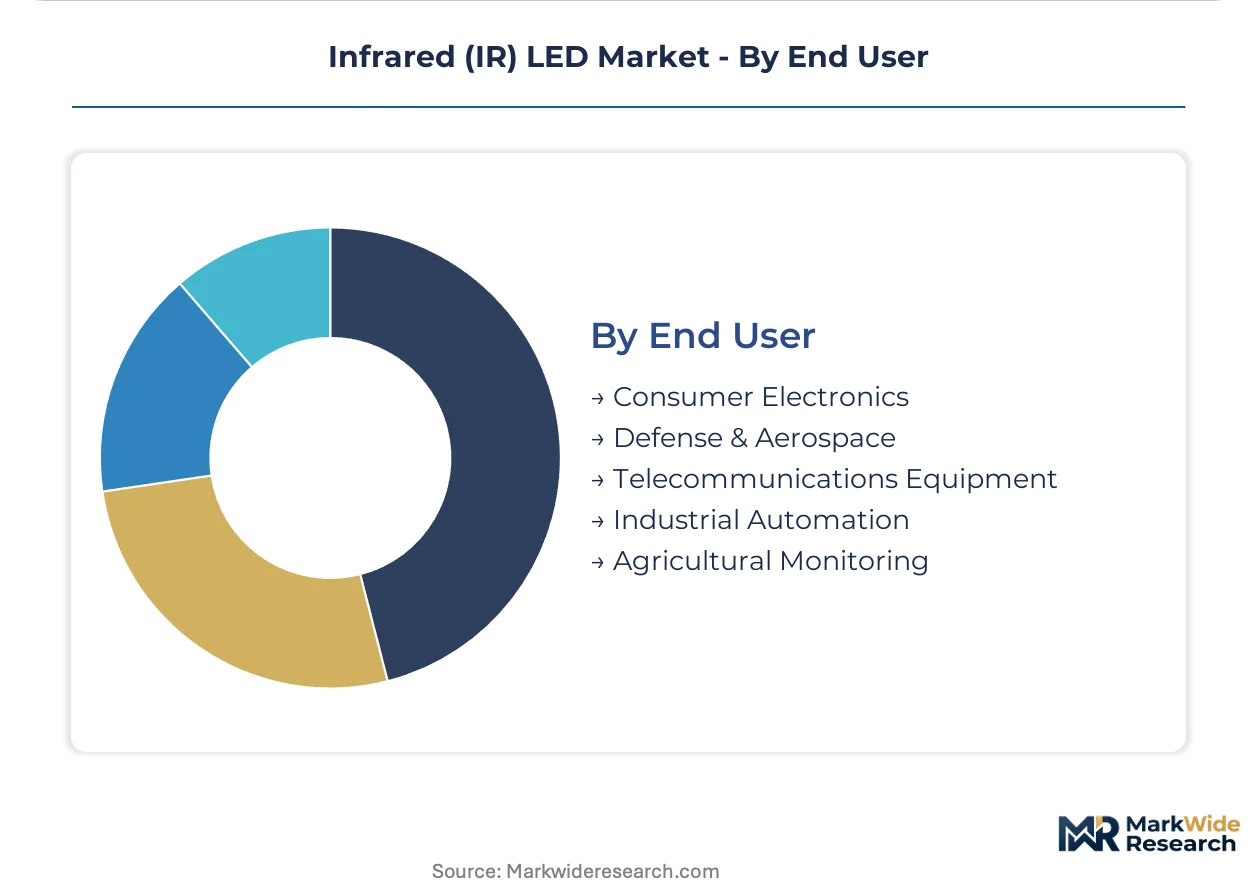
- Consumer Electronics:Smartphone, tablet, and wearable OEMs in Shenzhen and Dongguan drive surface-mount volumes, with 60% bill-of-material value now captured by integrated module suppliers bundling emitters, photodiodes, and driver ICs.
- Defense & Aerospace:Night-vision goggle and targeting system programs in the US, Israel, and the UK specify hermetic packaging and radiation hardness. ITAR and EAR export classifications restrict foundry eligibility, with sole-source qualification locking suppliers into decade-long production agreements.
- Telecommunications Equipment:Optical fiber transceivers and free-space communication links demand wavelength stability across temperature extremes.
- Industrial Automation:Photoelectric sensors and machine vision systems prioritize mechanical robustness over spectral precision.
- Agricultural Monitoring:Precision livestock tracking and crop health imaging in Brazil and Australia import 70% of emitter modules, creating localization partnership opportunities.
Consumer Electronics dominates shipment volumes. Defense & Aerospace delivers the highest margin realization per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hefei Comprehensive Bonded Zone and Taiwan's Hsinchu Science Park anchor the highest concentration of epitaxy and packaging capacity, with automotive qualification requirements now dictating regional investment flows.
China
Driver-monitoring mandates from Euro NCAP are pulling high-power IR LED exports through Shenzhen and Dongguan packaging clusters. MIIT enforces GB standards for optoelectronic reliability in domestic automotive supply chains. Hefei and Suzhou concentrate MOCVD reactor installations serving both local LiDAR developers and German Tier 1 suppliers.
Germany
AEC-Q101 qualification cycles for automotive LiDAR emitters concentrate procurement leverage among Ingolstadt and Stuttgart OEM engineering centers. REACH substance restrictions on cadmium and lead in compound semiconductors force packagers toward certified green supply chains. Munich and Regensburg host vertically integrated suppliers with captive epitaxy-to-module production.
Japan
AlGaAs heterostructure expertise for medical spectroscopy concentrates in Tokyo and Osaka epitaxy houses. METI oversees national technology roadmaps for compound semiconductor manufacturing equipment. Nagoya and Kyushu manufacturing clusters supply hermetic packaging for defense night-vision programs under ITAR-aligned export protocols.
United States
Defense night-vision and targeting system demand concentrates procurement in Texas and Arizona contractor ecosystems. FDA regulates IR LED emissions in medical diagnostic devices while FCC governs spectrum compatibility for telecommunications modules. Phoenix and Tucson host qualification facilities for MIL-STD-810G environmental testing of hermetic emitter arrays.
South Korea
Time-of-flight module integration for consumer electronics dominates Seoul and Suwon manufacturing corridors. MFDS oversees medical device component standards while KBA influences automotive safety system adoption. Gyeonggi-do packaging clusters capture integrated module value bundling emitters, photodiodes, and driver ICs for smartphone OEMs.
Infrared (IR) LED Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology tiers, with the market consolidating around three structural layers. Vertically integrated compound semiconductor houses with captive MOCVD capacity occupy the premium automotive and defense segments. Specialized packaging firms with modular substrate expertise serve mid-tier industrial and security applications. Commodity surface-mount suppliers compete on automated assembly scale for consumer electronics volumes. Strategic differentiation hinges on AEC-Q101 qualification depth and backward integration into gallium arsenide epitaxy.
Among European-anchored conglomerates, ams-OSRAM AG exemplifies the vertically integrated archetype spanning epitaxy through automotive module supply. Vishay Intertechnology, Inc. represents the diversified electronics manufacturer with catalog breadth across mounting formats. Epistar Corporation anchors the pure-play wafer supplier tier feeding downstream packagers across Asia-Pacific manufacturing clusters. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Everlight Electronics Co., Ltd. |
| Vishay Intertechnology, Inc. |
| Lumileds Holding B.V. |
| Lite-On Technology Corp |
| Epistar Corporation |
| ams-OSRAM AG |
| Excelitas Technologies Corp. |
| GJD Manufacturing Ltd. |
| Ennostar Inc. |
| Others |
Cost & Logistics Intelligence
AEC-Q101 certification tiers bifurcate the market into 24-month qualification premiums and spot-market commodity tiers, with German automotive Tier 1s locking suppliers into long-term contracts while Chinese packagers compete on volume scale for consumer electronics. This divergence manifests in supply chain configurations where captive epitaxy capacity commands pricing power against foundry-dependent assemblers.
Pricing Analysis
Lead-time premiums dominate pricing negotiations, with automotive OEMs paying substantial markups for 18-month MOCVD reactor slots versus spot-market discounts for standard 850nm emitters. Three-tier pricing structure across AEC-Q101 certified, industrial-grade, and economy surface-mount tiers separates qualification depth from volume scale. Price differentiation hinges on thermal cycling documentation and REACH-compliant material traceability. Cost compression in consumer-grade 940nm emitters is intensifying because Vietnamese packagers are scaling automated assembly lines. Smartphone OEMs in Shenzhen exhibit highest price sensitivity, while defense contractors in Texas accept premium positioning for ITAR-controlled hermetic packaging.
Supply Chain Analysis
China's MIIT domestic-content mandates for automotive optoelectronics are reshaping sourcing patterns, pushing German Tier 1s to qualify Hefei and Suzhou packaging clusters alongside traditional Japanese suppliers. Taiwan, China, and Japan concentrate MOCVD reactor capacity and AlGaAs epitaxy expertise. Raw material dependencies draw from Chinese arsenic precursor supply, Japanese trimethylgallium production, and German ceramic substrate manufacturing. Single-source vulnerability concentrates in three Japanese and German toolmakers controlling reactor lead times. Distribution runs through integrated module suppliers in South Korea and China capturing 60% of bill-of-material value previously held by discrete vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where VCSEL substitution above 940nm is displacing edge-emitting IR LEDs in flagship smartphone designs, forcing incumbents to defend position through qualification depth while new entrants exploit regulatory tailwinds.
For Market Incumbents: Anticipate VCSEL encroachment in proximity sensing by deepening AEC-Q101 qualification pipelines for automotive LiDAR emitters. Lock in 36-month supply agreements with German OEM engineering centers before GaN-on-Si epitaxy matures. Prioritize backward integration into gallium arsenide wafer supply to offset arsenic precursor volatility from Chinese environmental enforcement cycles.
For New Entrants and Emerging Players: Euro NCAP's 2026 driver-monitoring mandates in Europe opens a window for packaged emitter modules targeting Tier 2 automotive suppliers underserved by ams-OSRAM's premium positioning. Brazil's 70% import-dependent agricultural automation sector represents the most penetrable geography for localization partnerships. Pursue IEC 60825-1 harmonized safety certifications to reduce retesting burdens across EU, US, and Asian market launches.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated compound semiconductor houses given automotive qualification timelines extending 24-36 months and locking working capital before volume shipments. Long-term viability favors archetypes with captive MOCVD capacity and existing AEC-Q101 certifications. Watch for inflection in South Korean time-of-flight module integration rates as a signal for consumer electronics demand stabilization.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q101 Qualification Investment | Locks suppliers into 24-36 month automotive validation cycles before volume shipments commence. |
| GaN-on-Si Epitaxy Scale-Up | Taiwanese foundries scaling 150mm processes reduce substrate costs for high-power emitters. |
| REACH-Compliant Supply Chain Certification | ECHA's tightened cadmium thresholds push packagers toward certified green chains commanding OEM preference. |
| Integrated Module Bundling | Chinese and South Korean suppliers capture 60% of bill-of-material value from discrete vendors. |
| SWIR Band Extension R&D | 1400-1600nm emitters converge with InGaAs sensors for semiconductor wafer metrology applications. |
Research Approach
Independent corroboration across MOCVD equipment manufacturers, automotive Tier 1 procurement directors, and compound semiconductor foundry engineers underwrites the qualitative findings. Primary interviews with epitaxy process engineers, packaging technology leads, and OEM sensor integration specialists combined with secondary validation from SEC filings of listed optoelectronics suppliers, MIIT GB standard documentation, and ECHA REACH substance restriction updates. Bottom-up wafer capacity estimates and top-down automotive sensor deployment projections triangulate volume assessments.
Comparable-period anchoring to historical AEC-Q101 qualification cycles and MOCVD reactor installation rates structured the forecast window across the analysis window. Segmentation dimensions modeled include product architecture, material system, mounting format, thermal power tier, and regional regulatory cluster. CAGRs derived from slope-consistency checks against epitaxy equipment shipment data and automotive safety mandate adoption curves. Industry-specific inputs encompassed LiDAR emitter power requirements and driver-monitoring camera array specifications.
The model assumes a particular technology adoption path; alternative pathways for VCSEL substitution in 3D sensing would alter the outlook. Forecasts reflect assumptions regarding Euro NCAP mandate enforcement timing and Chinese environmental policy continuity for arsenic precursor supply. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Bi-Color LED Ring Light Market
LED
LED Light Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
US Outdoor LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Led Video Walls Market
LED
Indonesia LED Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
LED High Bay Drivers Market
LED
Superluminescent Diodes Market
LED
LED Power Supplies Market
LED
Global Waterproof LED Module Market
LED
Smart LED Indoor Signage Market
LED
LED Control Unit Market
LED
LED Lighting Solution Market
LED
Biometrics Infrared LED Market