
 LED Power Supplies Market | 2026-2036
LED Power Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
LED Power Supplies Market Analytics
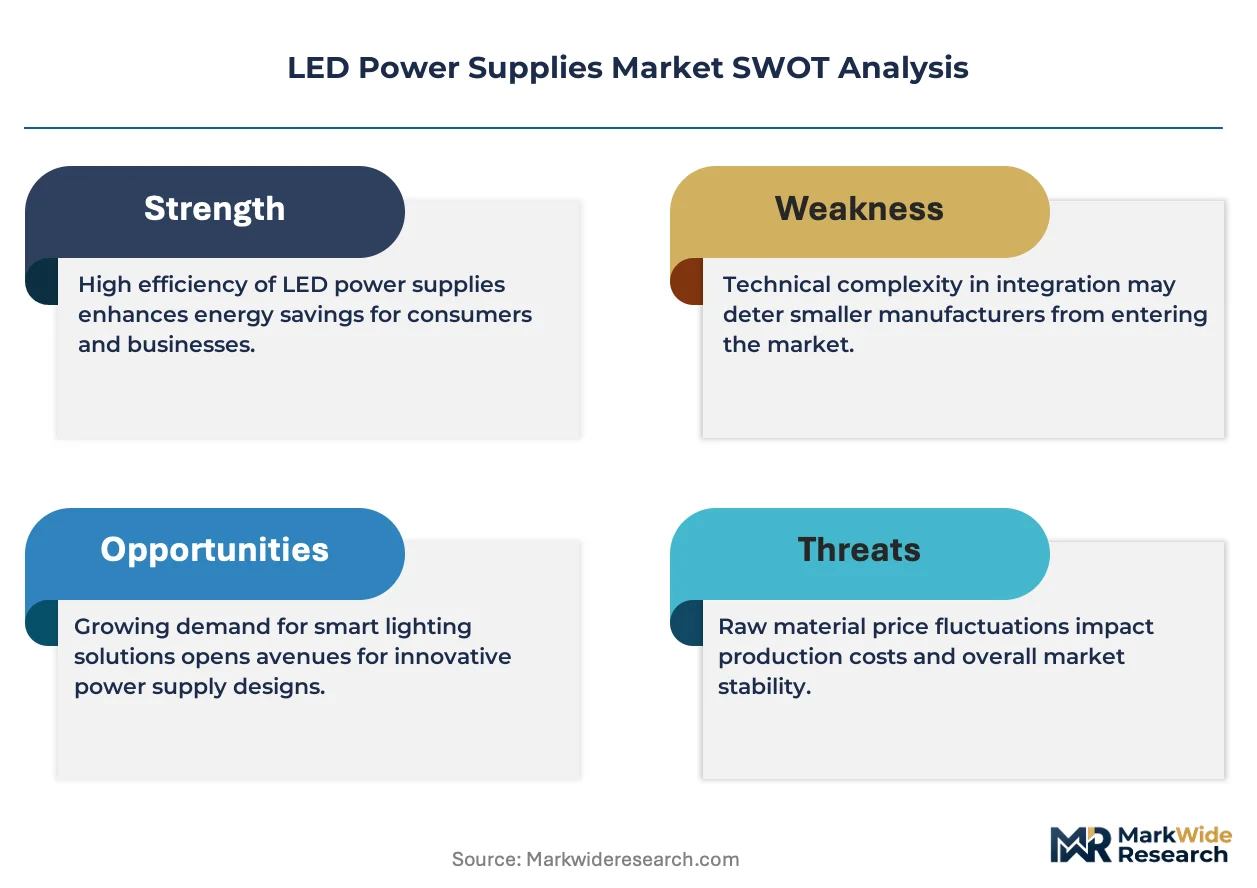
The gap between discrete component architectures and integrated driver-on-board designs is narrowing as manufacturers consolidate power conversion, thermal management, and control logic into single modules. Mean Well leverages its vertically integrated manufacturing base in Taiwan to sustain cost leadership across standard-output ranges. Signify anchors European demand through its dominance in connected lighting systems that bundle proprietary drivers with luminaire sales. Inventronics competes aggressively in outdoor and horticultural segments where waterproof and high-voltage tolerance specifications command premium positioning.
LED power supplies are electrical conversion devices that transform mains AC voltage into regulated DC output—typically 12V, 24V, or current-limited configurations—to drive solid-state lighting arrays with precise thermal and optical stability. Switching-mode topologies dominate volume production due to superior efficiency exceeding 90% and compact form factors, while magnetic and linear alternatives persist in niche noise-sensitive installations. Constant current products lead revenue pools because they protect LED arrays from thermal runaway and extend operational life, whereas dimmable variants capture the fastest expansion as building automation systems mandate granular lumen control across commercial end users.
EU Ecodesign requirements and the F-Gas Regulation shape product roadmaps by mandating higher efficiency tiers and restricting thermal management chemistries, while the US Department of Energy enforces minimum efficacy standards through ENERGY STAR qualification thresholds that gate retail and institutional procurement. China's GB standards and MIIT directives enforce domestic efficiency benchmarks that influence export-oriented manufacturing. Stakeholders must monitor regulatory divergence between efficiency metrics, harmonic distortion limits, and electromagnetic compatibility testing protocols to avoid certification fragmentation that adds cost and delays market entry.
Market Dynamics
The LED power supplies sector faces intensifying pressure from integrated driver-on-board architectures that compress bill-of-materials and thermal management footprints, forcing discrete component suppliers to consolidate value-add functions or surrender margin to luminaire OEMs.
Growth Catalysts
- EU Ecodesign tier upgrades:Mandatory efficiency thresholds for commercial luminaires accelerate replacement cycles across German and French retail chains.
- Horticultural LED expansion:Controlled-environment agriculture in the Netherlands and Canada drives demand for waterproof high-voltage drivers with spectral tuning capabilities.
- Building automation integration:DALI-2 and wireless mesh protocols enable granular lumen control that mandates dimmable driver penetration in US commercial retrofits.
Market Restraints
- Magnetic component cost volatility:Ferrite core and copper winding prices fluctuate with energy-intensive Chinese smelter output, squeezing mid-tier driver margins.
- Taiwan manufacturing concentration:Switching-mode IC fabrication clusters in Hsinchu create single-source vulnerability for global supply continuity.
- Linear topology persistence:Noise-sensitive medical and laboratory installations in Switzerland and Japan retain electromagnetic-silent alternatives that cap switching-mode volume share.
Strategic Opportunities
- Indian commercial building stock:BIS efficiency mandates and CEA grid codes create first-mover advantage for ENERGY STAR-equivalent driver certification.
- Vehicle exterior lighting:Convergence of GaN switching and AEC-Q100 automotive qualification opens OEM supply positions for headlamp and taillight modules.
- Direct-to-installer e-commerce:Amazon Business and specialized electrical distributor platforms disintermediate traditional wholesale channels for standard-output SKU procurement.
Industry Challenges
- Power electronics engineering scarcity:Magnetic design and thermal simulation expertise concentrates in Taiwan and Germany, constraining R&D scaling elsewhere.
- Multi-jurisdiction certification timelines:Divergent ENERGY STAR, CE marking, and GB standard test protocols extend product launch cycles by 8-14 months.
- Legacy fluorescent ballast compatibility:Retrofit installations require driver form factors that fit existing luminaire housings, limiting thermal optimization freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Power Supplies Market |
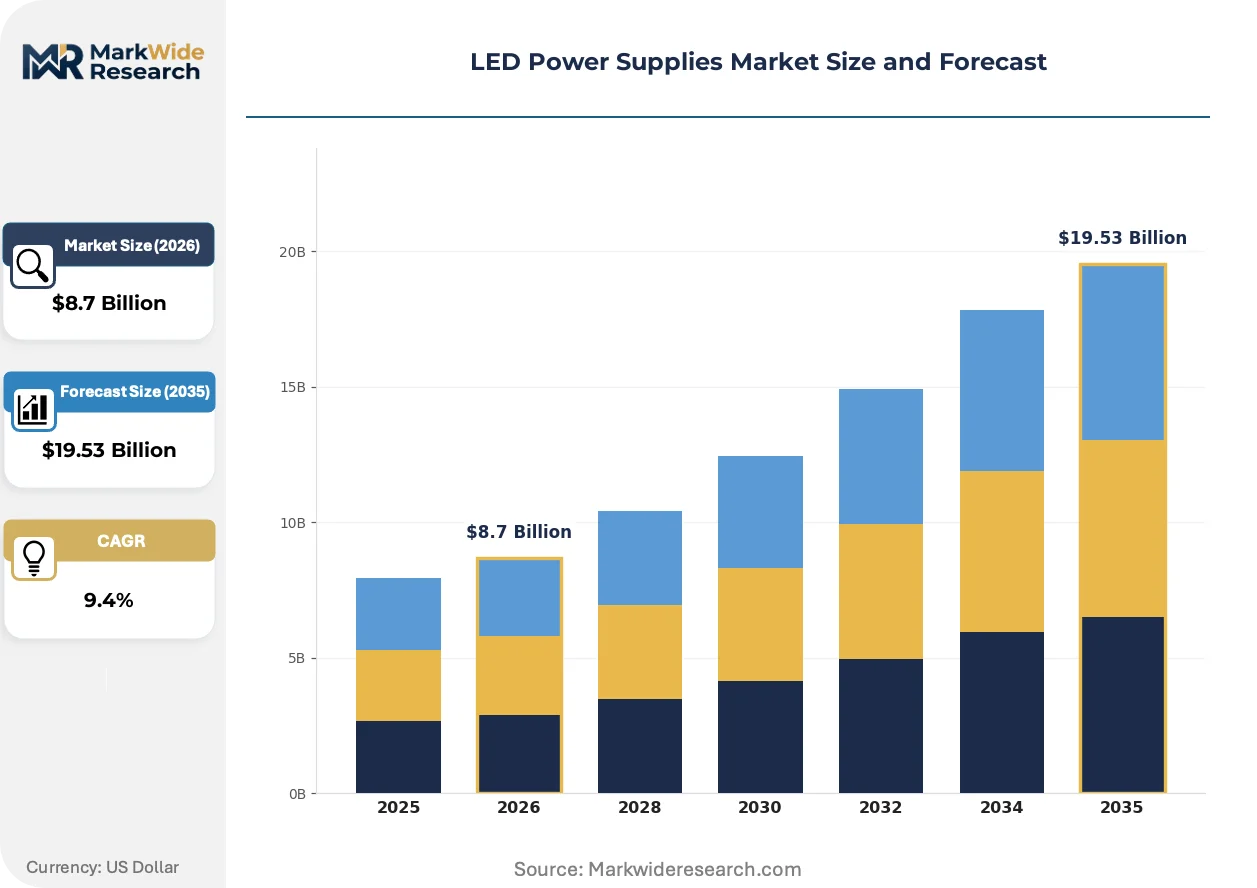
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Voltage, Constant Current, Dimmable, Waterproof End User: Residential, Commercial, Industrial, Automotive Technology: Linear, Switching, Magnetic, LED Driver Installation: Surface Mount, Panel Mount, Flush Mount, Outdoor |
| Companies Covered | Mean Well, Signify, ams OSRAM, Acuity Brands Lighting, Inventronics, Tridonic, Lifud Technology, Eaglerise, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Power Supplies Market Evolving Landscape
Digital control architectures are displacing analog feedback loops across driver designs, enabling predictive thermal management and remote diagnostics that reshape how luminaire OEMs specify power conversion partners.
GaN switching transistors are digitizing power conversion topologies by replacing silicon MOSFETs in 100W-plus outdoor drivers. Signify and Acuity Brands are qualifying these devices for streetlight and high-bay retrofits where efficiency gains above 94% justify unit cost premiums. This transition is digitizing supply chain relationships as driver vendors must secure GaN foundry allocation ahead of silicon-legacy competitors.
The EU F-Gas Regulation and accompanying Ecodesign lot 19 revisions are prohibiting perfluorinated thermal interface materials and mandating minimum standby power below 0.5W. Driver manufacturers serving German and Dutch commercial markets are reformulating potting compounds and revising no-load consumption circuits. Outdoor and industrial segments face the steepest compliance redesign costs due to IP67 sealing requirements that complicate passive cooling.
Electrical contractors and facility managers are consolidating vendor relationships around suppliers offering 10-year warranty coverage and cloud-connected failure monitoring. This specification compression favors vertically integrated driver-luminaire bundles over standalone component procurement. The shift is most pronounced in US healthcare and education verticals where total-cost-of-ownership calculations dominate capital allocation committees.
LED Power Supplies Market Segmentation
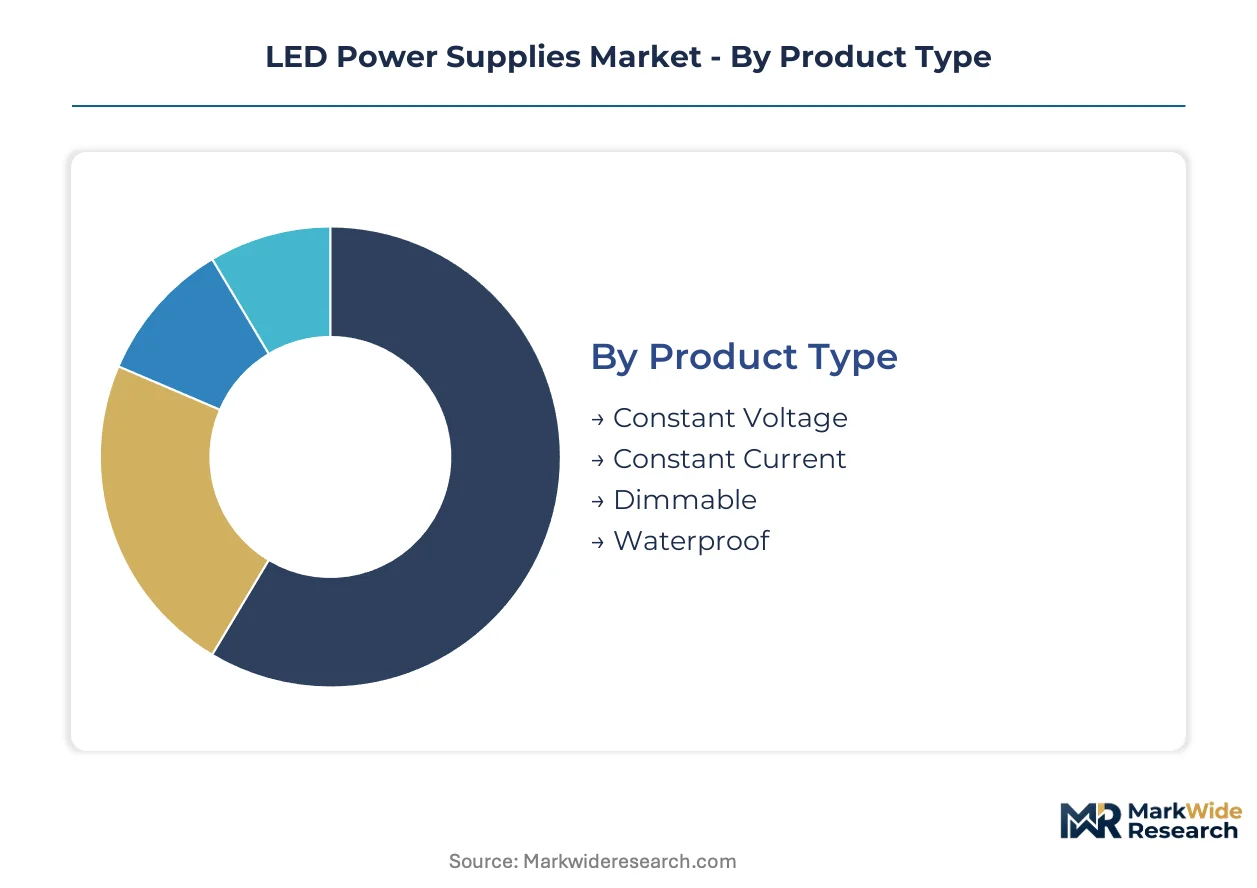
LED power supply segmentation reveals how technical specifications align with distinct thermal, electrical, and environmental demands across lighting applications. Product architecture choices directly determine compatibility with building codes, luminaire form factors, and control system integration requirements.
Product Type:
Mature constant voltage and constant current architectures dominate procurement volumes, while emerging dimmable and waterproof variants capture specification upgrades in connected and harsh-environment installations.
- Constant Current:These drivers regulate output amperage to prevent thermal runaway in LED arrays, typically delivering 350mA to 700mA with tight tolerance bands. Demand concentrates in commercial retrofit projects across Germany and the United States where extended operational life reduces total ownership costs. ENERGY STAR qualification thresholds and EU Ecodesign tier upgrades accelerate displacement of legacy magnetic ballasts.
- Constant Voltage:Fixed DC output configurations—commonly 12V or 24V—simplify parallel LED string wiring for signage and strip lighting applications. Residential and retail installations in China and India specify these units for cost-sensitive replacement cycles where precise current matching is less critical than procurement simplicity.
- Dimmable:Phase-cut and 0-10V control interfaces enable granular lumen adjustment for building automation integration.
- Waterproof:IP67-rated encapsulation protects driver electronics from moisture ingress in horticultural and marine environments.
Constant Current retains volume leadership; Dimmable holds the steepest expansion curve.
End User:
Cost tier differentiation separates specification-intensive commercial and automotive segments from price-sensitive residential procurement patterns.
- Commercial:Office towers, retail chains, and hospitality properties demand 50,000-hour rated lifespans with DALI-2 protocol compatibility. US healthcare and education verticals consolidate vendor relationships around 10-year warranty coverage and cloud-connected failure monitoring.
- Industrial:High-bay warehouses and manufacturing floors require surge protection and wide temperature operating ranges.
- Residential:Single-family and multi-unit dwellings prioritize compact form factors and plug-and-play installation simplicity.
- Automotive:Exterior lighting modules for headlamps and taillights require AEC-Q100 qualification and GaN switching tolerance.
Commercial installations command the highest average selling prices; Automotive represents the fastest-growing trajectory.
Technology:
Volume concentration favors switching-mode topologies while margin pools concentrate in specialized magnetic and integrated driver architectures.
- Switching:PWM-based conversion achieves efficiency above 90% through high-frequency transformer operation, dominating volume production for standard-output ranges. Taiwan's Hsinchu fabrication clusters supply the MOSFET and control IC components that define competitive positioning.
- Magnetic:Electromagnetic ballast alternatives persist in legacy fluorescent retrofit compatibility scenarios.
- Linear:Resistive drop regulation eliminates switching noise for medical imaging suites and laboratory instrumentation in Switzerland and Japan.
- LED Driver:Integrated driver-on-board modules consolidate power conversion with thermal management for luminaire OEMs.
Switching technology retains volume leadership; LED Driver holds the steepest expansion curve.
Installation:
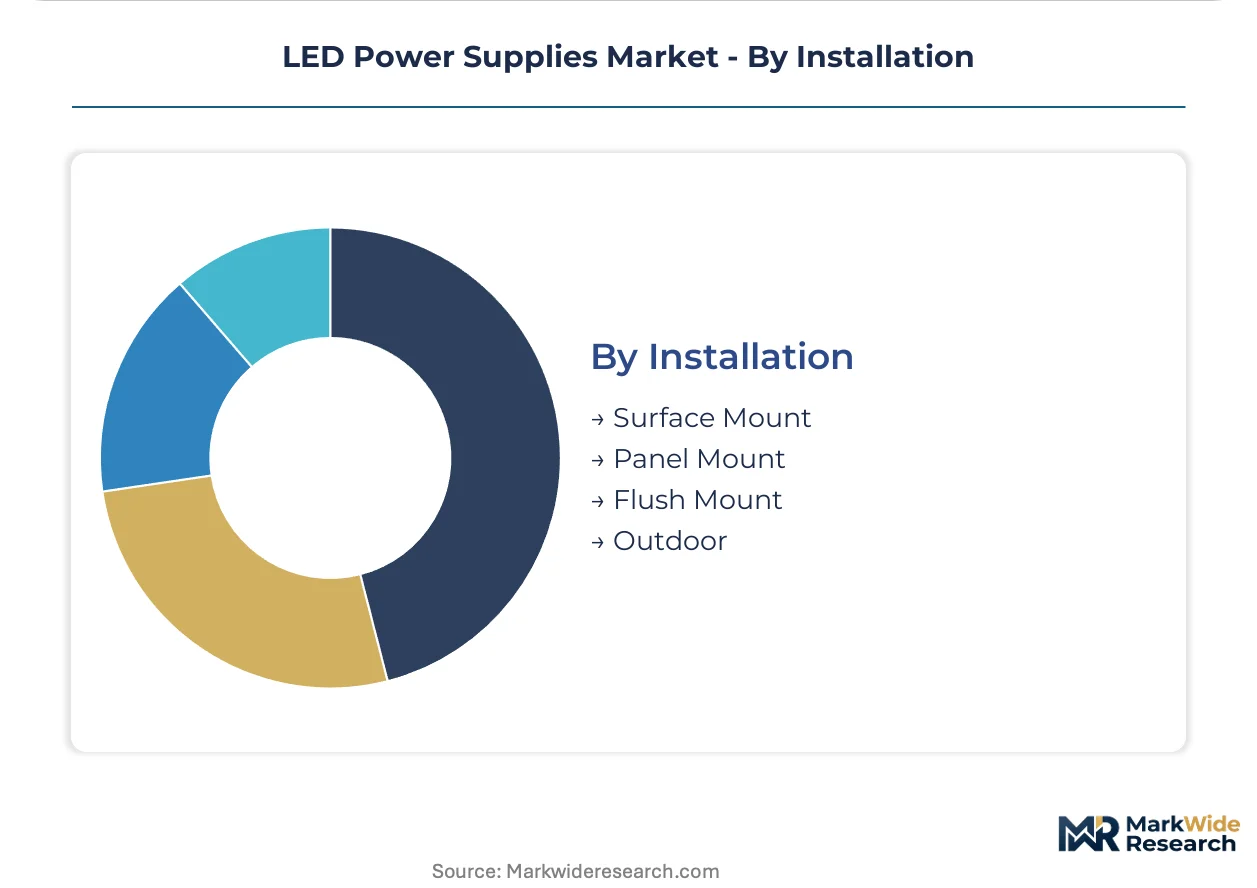
Application context dictates mechanical mounting constraints and environmental sealing requirements across indoor and outdoor deployment scenarios.
- Outdoor:Pole-mounted streetlight and area lighting applications specify IP66 or IP67 ingress protection with 6kV surge withstand capability. Dutch and Canadian horticultural operations drive demand for waterproof housings with spectral tuning driver compatibility.
- Surface Mount:Wall or ceiling attachment simplifies maintenance access for commercial building retrofits.
- Panel Mount:Chassis integration into electrical enclosures serves industrial control cabinet applications.
- Flush Mount:Recessed luminaire integration requires low-profile thermal designs for ceiling plenum clearance.
Outdoor installations command premium positioning; Surface Mount retains volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building owners and electrical contractors concentrate procurement decisions across manufacturing clusters in Germany, China, and the United States, with horticultural operators in the Netherlands and Canada emerging as specification-intensive buyers for high-voltage waterproof drivers.
United States
Healthcare and education verticals drive demand for 10-year warranty coverage with cloud-connected failure monitoring. The US Department of Energy enforces ENERGY STAR qualification thresholds that gate institutional procurement. Chicago and Dallas-Fort Worth electrical distributors consolidate vendor relationships around dimmable driver bundles for commercial retrofits.
Germany
Retail chains and automotive suppliers specify DALI-2 protocol compatibility for granular lumen control in manufacturing floors. The EU Ecodesign tier upgrades and F-Gas Regulation mandate higher efficiency thresholds and restrict thermal management chemistries. Bavarian industrial zones concentrate driver-luminaire bundle assembly for European export markets.
China
Export-oriented manufacturing and domestic commercial construction sustain volume demand for standard-output switching-mode drivers. MIIT directives and GB standards enforce domestic efficiency benchmarks that influence global supply configurations. Shenzhen and Dongguan electronics corridors house vertically integrated power conversion and thermal management module production.
Netherlands
Controlled-environment agriculture operators require waterproof IP67 housings with spectral tuning driver compatibility for greenhouse LED installations. The EU Ecodesign lot 19 revisions prohibit perfluorinated thermal interface materials in driver designs. Eindhoven's high-tech campus anchors horticultural lighting R&D partnerships between driver vendors and luminaire OEMs.
Canada
Cold-climate horticultural facilities and streetlight retrofit programs drive demand for wide temperature operating ranges and surge protection. Health Canada's energy efficiency regulations align with ENERGY STAR thresholds for institutional procurement. Ontario's Golden Horseshoe manufacturing belt assembles outdoor-rated drivers for North American distribution.
LED Power Supplies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where vertically integrated luminaire OEMs bundle proprietary drivers while standalone component suppliers defend specification positions in retrofit and aftermarket channels. The vendor base separates into three strategic archetypes: Taiwan-based scale manufacturers with captive IC fabrication, European connected-lighting systems integrators, and Chinese specialists in waterproof and horticultural segments. Dominant competitive moves include backward integration into GaN foundry allocation and consolidation of cloud-connected warranty and diagnostic services.
Among Taiwan-based scale manufacturers, Mean Well exemplifies cost leadership through vertically integrated production. Signify and Inventronics occupy differentiated positions within the European and horticultural specialist tiers respectively, with Signify representing systems integration archetypes and Inventronics anchoring premium waterproof specifications.
| Leading Market Players |
|---|
| Mean Well |
| Signify |
| ams OSRAM |
| Acuity Brands Lighting |
| Inventronics |
| Tridonic |
| Lifud Technology |
| Eaglerise |
| Delta Electronics |
| Others |
Value Network & Pricing Analysis
Taiwan's Hsinchu fabrication clusters for switching-mode ICs concentrate upstream margin capture, leaving downstream driver assemblers to compete on thermal management integration and certification bundling rather than semiconductor cost control.
Pricing Analysis
Cost-plus contracts with ferrite core and copper winding indexation dominate procurement between driver manufacturers and magnetic component suppliers. Pricing stratifies across ENERGY STAR-qualified premium tiers, standard commercial SKUs, and economy-grade residential units, with certification grade and volume scale as the primary differentiation drivers. Cost compression in mid-tier driver segments is intensifying because luminaire OEMs are consolidating vendor relationships around vertically integrated bundles. Residential retrofit buyers exhibit the highest price sensitivity, while healthcare and education verticals prioritize total-cost-of-ownership metrics over unit procurement costs.
Supply Chain Analysis
Export-control regimes on wide-bandgap semiconductor technology restrict GaN switching transistor flows from US and Japanese foundries to Chinese driver assemblers, reshaping sourcing strategies. Supply concentrates in Taiwan for IC fabrication, China for magnetic component winding and final assembly, and Germany for high-reliability industrial-grade units. Raw material dependencies center on ferrite cores, copper windings, and aluminum thermal housings. Single-source vulnerability in Hsinchu MOSFET supply creates structural risk for global production continuity. Distribution runs through electrical distributor networks in Chicago and Dallas-Fort Worth, with direct-to-installer e-commerce platforms gaining share in standard-output procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED power supplies sector rewards magnetic design and thermal simulation capabilities that concentrate in Taiwan and Germany, creating geographic barriers to R&D scaling for competitors elsewhere.
For Market Incumbents: Insulate specification positions in connected lighting and horticultural segments by securing captive GaN foundry allocation ahead of silicon-legacy competitors, while consolidating cloud-connected warranty and diagnostic services to deepen luminaire OEM dependencies. Backward integration into switching-mode IC design protects margin pools from discrete component commoditization. For New Entrants and Emerging Players: Establish a beachhead in Indian commercial building retrofits where BIS efficiency mandates and CEA grid codes create first-mover advantage for ENERGY STAR-equivalent certification. Target vehicle exterior lighting modules where AEC-Q100 qualification requirements and GaN switching tolerance specifications favor specialist entrants over diversified incumbents. Pursue direct-to-installer e-commerce channels for standard-output SKU procurement to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated driver-luminaire bundle providers with established DALI-2 protocol compatibility and 10-year warranty infrastructure, as specification compression favors bundled solutions over standalone component procurement. The inflection signal to watch is GaN switching transistor cost parity against silicon MOSFETs in 100W-plus outdoor applications, which would accelerate topology transition and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Allocation Securement | Early access to wide-bandgap capacity locks in efficiency leadership for streetlight and high-bay retrofits. |
| Cloud-Connected Warranty Platform | Remote failure monitoring consolidates vendor relationships in US healthcare and education verticals. |
| DALI-2 Protocol Certification Investment | Building automation integration mandates granular lumen control compatibility across commercial retrofits. |
| Waterproof IP67 Housing Development | Horticultural LED expansion in the Netherlands and Canada requires spectral tuning driver compatibility. |
| Direct-to-Installer E-Commerce Launch | Amazon Business and specialized electrical platforms disintermediate traditional wholesale channels. |
Research Methodology
Initial hypotheses were tested against primary input from driver design engineers, luminaire OEM procurement directors, electrical distributor category managers, and facility management executives, and refined through secondary validation against MIIT directive filings, ENERGY STAR qualification databases, EU Ecodesign lot 19 revision texts, and customs trade data for ferrite core and copper winding flows. Bottom-up unit economics from component cost structures were triangulated against top-down market sizing from end-use installation volumes.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by constant current, constant voltage, dimmable, and waterproof architectures; end-user segmentation across commercial, industrial, residential, and automotive verticals; technology segmentation by switching-mode, magnetic, linear, and integrated driver-on-board topologies; and installation segmentation by outdoor, surface mount, panel mount, and flush mount configurations. CAGRs were derived from installation growth rates, replacement cycle acceleration from regulatory tier upgrades, and technology transition curves for GaN switching adoption. Forecast inputs included EU F-Gas Regulation compliance cost estimates and horticultural LED penetration rates in controlled-environment agriculture.
Stress conditions across ferrite core price volatility, Taiwan semiconductor supply disruption, and EU Ecodesign tier acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology cost curves. Material shifts in GaN switching transistor foundry capacity allocation or ENERGY STAR threshold revision timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Xenon Market
LED
Smart LED Indoor Signage Market
LED
LED Phosphor Materials Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Pixel Pitch LED Market
LED
UK Outdoor LED Lighting Market
LED
Gan Substrate Market
LED
Four-Digit 7 Segment LED Displays Market
LED
LED Floodlight Drivers Market
LED
High-Brightness LED Market
LED
Japan Indoor LED Lighting Market
LED
China LED Lighting Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
LED Lamp Market
LED
LED Panel Market
LED
Global LED Phosphor Market