
 Industrial Display Market | 2026-2036
Industrial Display Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Display Market Intelligence
The IEC 60950-1 safety standard for information technology equipment is collapsing the distinction between consumer-grade and industrial-grade display components. This shift benefits specialized suppliers over generalists. Siemens integrates its displays deeply within its own automation ecosystems. Advantech leverages its extensive portfolio to serve diverse end-user industries across Asia and North America, while Kontron specializes in ruggedized displays for transportation and defense applications.
An industrial display is an electronic visualization device engineered for reliability in harsh operational environments, often featuring IP65 or higher ratings for dust and water ingress. Its primary purpose is to provide human-machine interface (HMI) and data visualization for process monitoring and control. While LCD remains the dominant product type by volume, emerging MicroLED technology offers superior brightness and longevity for high-value applications. Within touch technologies, projected capacitive screens represent the fastest-growing segment due to their multi-touch capabilities and durability.
Regulatory frameworks such as the EU's RoHS directive restricting hazardous substances and the US FCC regulations on electromagnetic interference govern component design and market access. These standards enforce higher reliability and safety benchmarks than in the consumer sector. The critical decision for manufacturers now centers on balancing investment in next-generation OLED and MicroLED technologies against the enduring cost-effectiveness of mature LCD platforms.
Market Dynamics
The convergence of safety standards like IEC 60950-1 and stricter regional mandates such as the EU's CE marking is forcing a re-evaluation of component sourcing and design, favoring specialized, high-reliability suppliers over generalist component manufacturers.
Growth Catalysts
- Manufacturing Automation:Expanding use of robotics and process control systems in sectors like automotive and pharmaceuticals requires more sophisticated HMI panels for real-time data visualization and operator interaction.
- CE Marking Directives:In the European Union, stricter CE marking requirements for industrial machinery mandate higher-quality, more reliable display components, boosting demand for certified products in advanced manufacturing clusters.
- Projected Capacitive Touch:The adoption of projected capacitive (PCAP) technology is accelerating due to its durability, resistance to contaminants, and multi-touch capabilities, which are critical for complex control applications in harsh environments.
Market Restraints
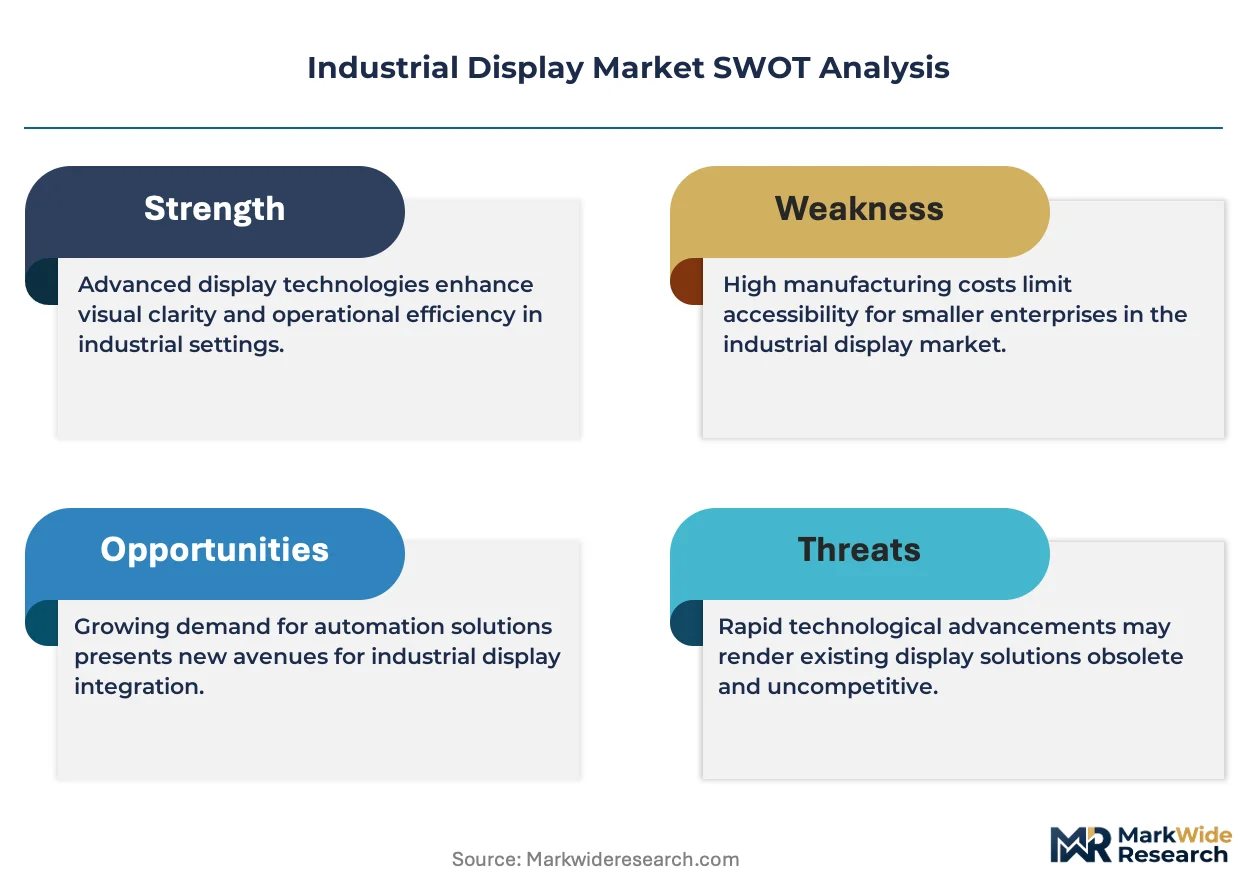
- High Initial Capital Outlay:The significant investment required for ruggedized displays with high IP ratings and certifications acts as a barrier, particularly for smaller manufacturers or those in price-sensitive emerging markets.
- LCD Technology Limitations:While dominant, traditional LCD platforms face performance limitations in extreme temperatures and direct sunlight, constraining their use in outdoor or unconditioned industrial settings without costly modifications.
- Component Sourcing Volatility:The supply chain for specialized components like high-brightness backlights and durable touch controllers is concentrated, creating vulnerability to price fluctuations and lead-time extensions from key Asian suppliers.
Strategic Opportunities
- MicroLED for Niche Applications:The superior brightness, contrast, and longevity of MicroLED technology create an opportunity to develop premium display solutions for high-value sectors like medical imaging and military command-and-control centers.
- Underpenetrated Sectors in India:India's push for domestic manufacturing under its PLI scheme presents an opportunity to supply industrial displays for newly established electronics, automotive, and pharmaceutical production facilities.
- Smart Agriculture Integration:The adoption of precision farming techniques requires rugged, sunlight-readable displays for in-cab controllers on tractors and harvesters, representing a new application vertical for specialized HMI.
Industry Challenges
- Legacy System Integration:Integrating modern, high-resolution displays with older industrial control systems and proprietary communication protocols presents significant technical hurdles and software development costs for end-users and system integrators.
- Complex Certification Pathways:Navigating multiple, often overlapping certification requirements for different regions, such as ATEX for explosive atmospheres and specific marine certifications, extends product development timelines and increases costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Display Market |
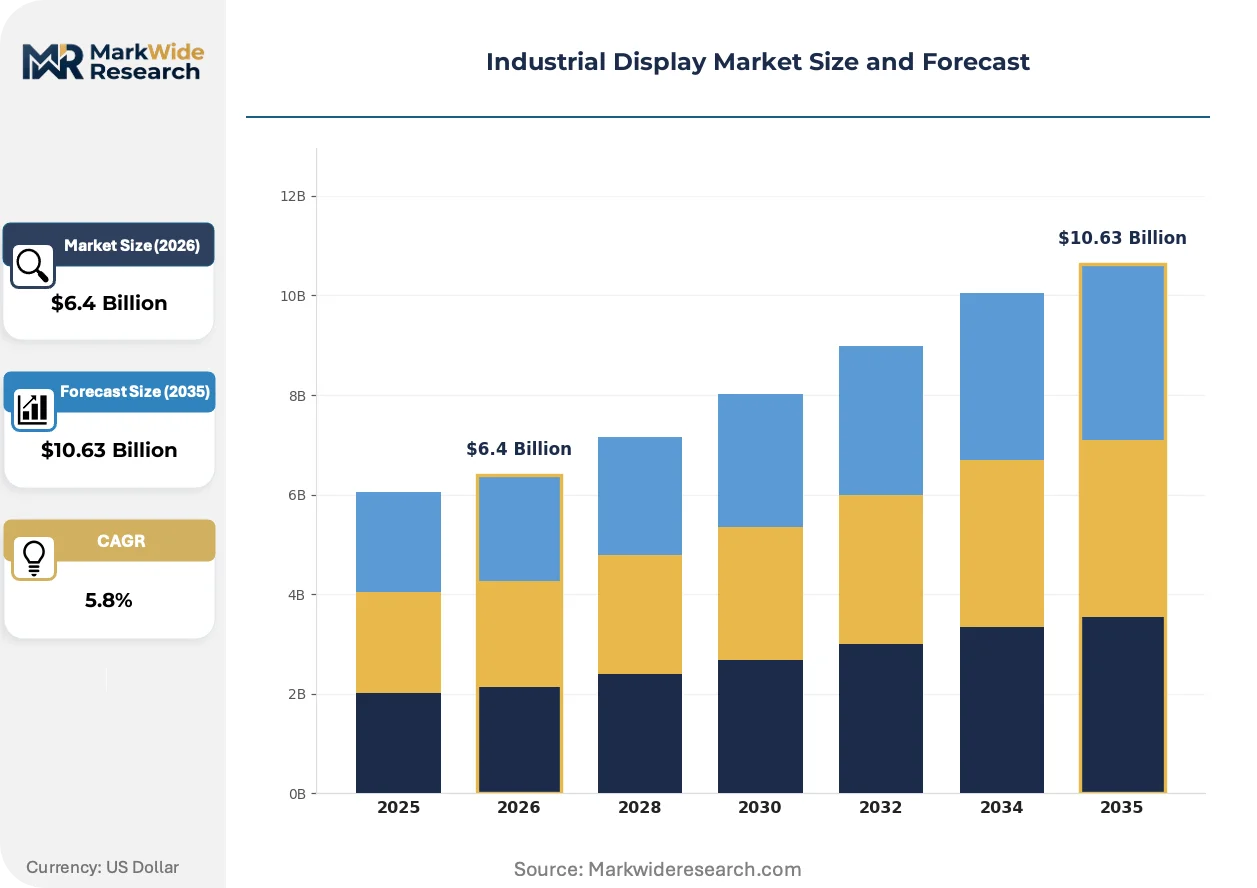
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, E-Ink, TFT, MicroLED Technology: Capacitive Touch, Resistive Touch, Infrared Touch, Projected Capacitive, Multi-Touch, Optical Touch Application: Automation Control, Process Monitoring, Robotics Interface, Digital Signage, Factory Instrumentation, Public Kiosks End User Industry: Manufacturing, Energy Production, Transportation Systems, Aerospace Firms, Defense Contractors, Telecommunication Providers |
| Companies Covered | NEC Display Solutions, Pro-face, Advantech, Kontron, ADLINK Technology, Siemens, Winmate, Daktronics, AU Optronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Display Market Strategic Shifts & Innovations
The industrial display is evolving from a passive information screen into an active, intelligent interface. This transformation is driven by the need for deeper system integration and compliance with increasingly stringent operational and safety standards across global industries.
MicroLED technology offers self-emissive pixels that provide superior brightness, energy efficiency, and operational lifespan compared to conventional LCD or OLED panels. High-value sectors such as medical device manufacturing and aerospace are beginning to adopt these displays for critical visualization tasks. The technology's modular, scalable nature is decomposing the traditional fixed-size panel paradigm, allowing for custom-shaped and large-format video walls in control rooms.
The European Union's RoHS directive, restricting hazardous materials in electronics, directly impacts component design. This regulation is forcing manufacturers to re-engineer products and validate their entire supply chain for compliance, affecting everything from solder to substrates. This standard necessitates investment in compliant materials, which often carry a cost premium, particularly for companies exporting into the European market.
Customers are increasingly purchasing displays as part of pre-validated, integrated HMI systems rather than as standalone components. This shift away from component-level procurement benefits system integrators and automation providers who can offer a complete hardware and software stack. The trend is most prominent in the pharmaceutical and food processing industries, where validation and certification of the entire control system are paramount.
Industrial Display Market Segmentation
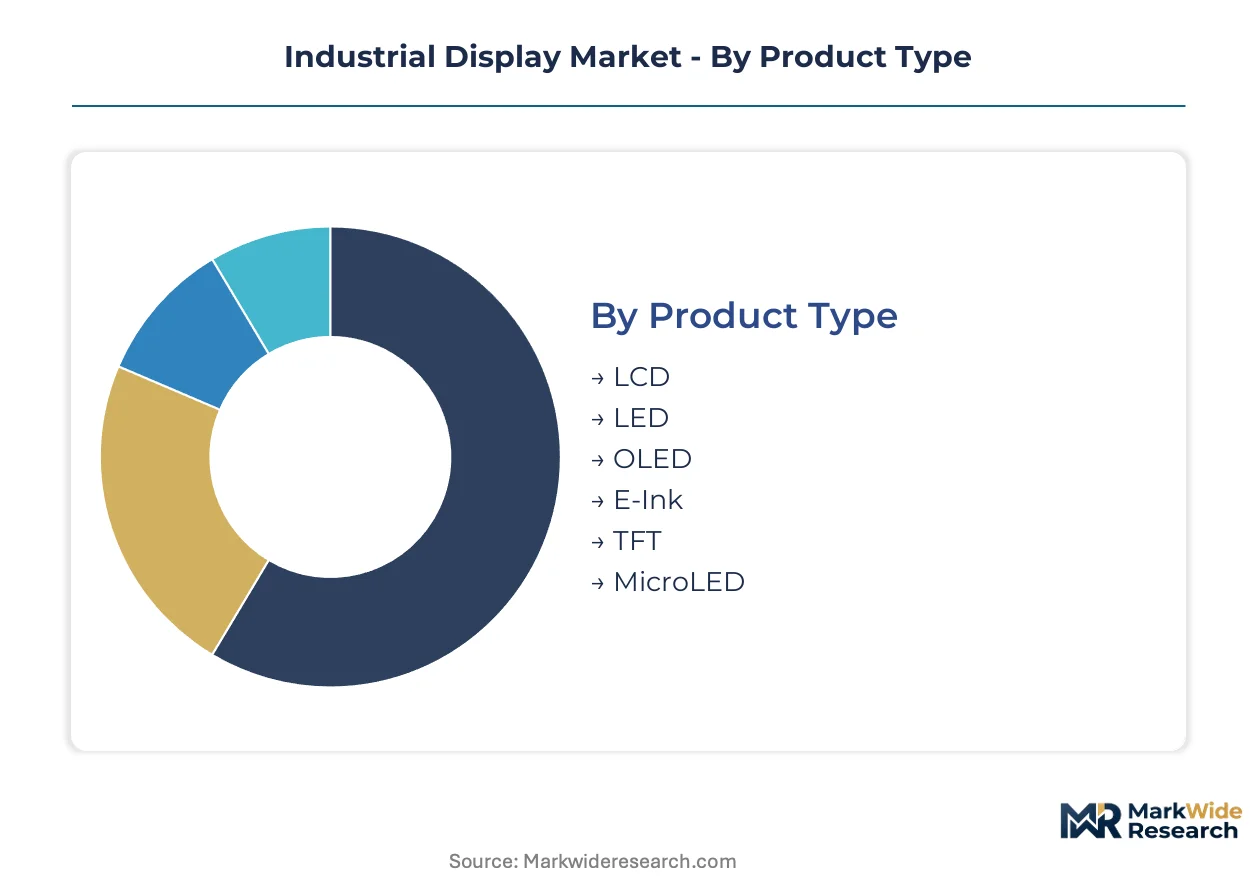
The industrial display market's segmentation reveals the diverse operational demands driving product innovation and adoption across various end-use environments. Understanding these distinct segments helps manufacturers tailor offerings and optimize supply chains for specialized performance requirements. Each category reflects unique technical specifications and end-user expectations.
Product Type:
Substitution pressure is most evident in product type, where emerging technologies threaten established display platforms. Legacy LCDs face performance limitations in extreme conditions, creating opportunities for advanced alternatives.
- LCD:Liquid Crystal Displays remain the dominant product type by volume, offering cost-effectiveness and mature manufacturing processes. Demand concentrates in general manufacturing automation in countries like China and India, driven by the need for economical HMI solutions.
- MicroLED:This advanced display technology features self-emissive pixels, providing superior brightness, contrast, and extended operational lifespan. High-value applications in medical imaging in Germany and military command-and-control centers in the United States increasingly adopt MicroLED for critical visualization tasks.
- LED:Light Emitting Diode displays offer high brightness and energy efficiency, finding use in outdoor digital signage and large-format industrial visualizations.
- OLED:Organic Light Emitting Diode panels provide excellent contrast and wide viewing angles, suitable for specialized industrial monitoring where color accuracy is paramount.
- E-Ink:Electronic Ink displays consume minimal power and offer high readability in direct sunlight, ideal for low-power information panels in logistics facilities.
- TFT:Thin-Film Transistor displays are a variant of LCD technology, offering improved image quality and faster response times for process control applications.
LCD anchors the volume base while MicroLED gains share at the steepest rate.
Technology:
Application-driven functionality differentiates various touch technologies, influencing their suitability for specific industrial environments and user interactions. Specialized requirements determine the choice of interface.
- Projected Capacitive:PCAP technology supports multi-touch gestures and offers high durability, resisting contaminants and scratches. Complex control applications in automotive manufacturing in Japan and pharmaceutical production in Switzerland increasingly adopt PCAP for its robust performance.
- Resistive Touch:These screens respond to pressure, allowing operation with gloves or a stylus, and provide a cost-effective solution for basic HMI. Price-sensitive emerging markets, including Brazil and Indonesia, utilize resistive touch for straightforward industrial interfaces.
- Capacitive Touch:Capacitive screens detect touch through electrical changes, offering good responsiveness for general industrial applications in clean environments.
- Infrared Touch:Infrared touch technology uses an array of IR beams to detect touch, providing high clarity and supporting large display formats for public kiosks.
- Multi-Touch:This capability allows simultaneous input from multiple points, enhancing user interaction for complex data visualization and control.
- Optical Touch:Optical touch screens use cameras to detect touch, offering scalability for very large displays and resistance to surface damage.
Reliability and precision define the value proposition for advanced touch technologies, while cost remains a key differentiator for established solutions.
Application:
End-user operational requirements dictate the specific application of industrial displays, ranging from machine control to public information dissemination. Each application demands tailored display characteristics.
- Automation Control:Industrial displays serve as critical Human-Machine Interfaces (HMI) for real-time data visualization and operator interaction in automated systems. Expanding use of robotics in German automotive plants and process control systems in US pharmaceutical facilities drives demand for these panels.
- Robotics Interface:These displays facilitate programming, monitoring, and human-robot collaboration in advanced manufacturing environments. Precision farming equipment in Canada and automated logistics centers in South Korea require robust interfaces for complex robotic systems.
- Process Monitoring:Displays provide continuous visual feedback on industrial processes, ensuring operational efficiency and safety in chemical plants.
- Digital Signage:Rugged displays are deployed in industrial settings for displaying safety information, production metrics, or wayfinding in large facilities.
- Factory Instrumentation:Displays integrate into control panels and machinery, providing essential readings and status updates for factory floor operations.
- Public Kiosks:Industrial-grade displays ensure durability and continuous operation in self-service kiosks located in transportation hubs and public spaces.
The shift towards intelligent automation is expanding the functional scope of industrial displays beyond traditional monitoring tasks.
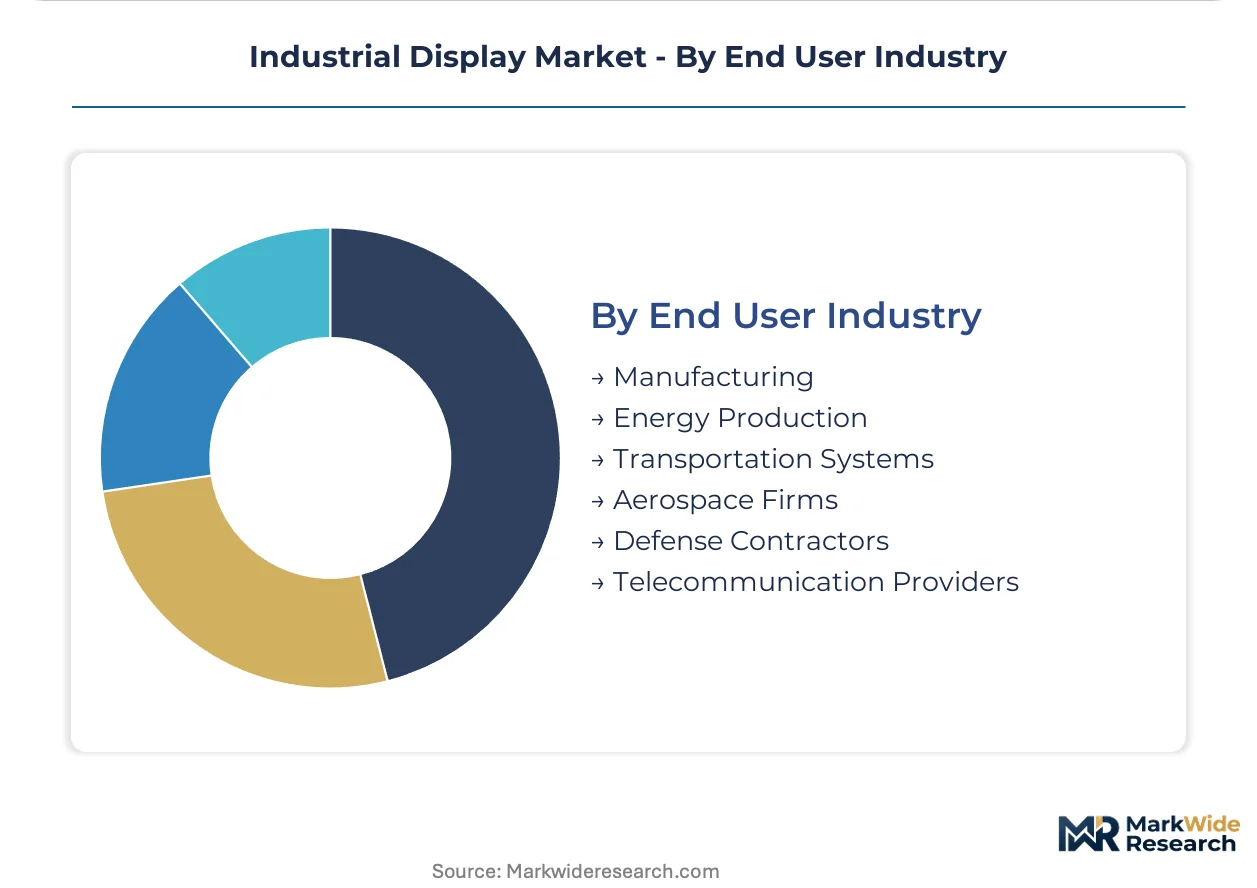
End User Industry:
Regulatory compliance and operational uptime are paramount considerations for industrial display adoption across various end-user industries. Each sector imposes unique demands on display performance and certification.
- Manufacturing:This sector represents the largest end-user segment, employing industrial displays for automation, quality control, and HMI on factory floors. The push for domestic manufacturing under India's PLI scheme and advanced production in Germany drives significant demand.
- Aerospace Firms:Displays in this sector require extreme ruggedization, specific certifications (e.g., FAA in the US), and high reliability for cockpit instrumentation and ground control systems. Defense contractors in the United Kingdom and aerospace manufacturers in France demand displays capable of operating in harsh conditions.
- Energy Production:Industrial displays monitor and control processes in power plants, oil rigs, and renewable energy facilities, requiring durability in harsh environments.
- Transportation Systems:Displays are used in railway control centers, marine navigation, and vehicle telematics, demanding resistance to vibration and extreme temperatures.
- Defense Contractors:Military applications require secure, ruggedized displays for command-and-control systems, vehicle integration, and portable field devices.
- Telecommunication Providers:Displays monitor network infrastructure, server rooms, and data centers, requiring reliable operation for critical system oversight.
Industrial displays are critical components across diverse sectors where operational continuity and data integrity are non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stricter regulatory frameworks across multiple regions are driving demand for high-reliability industrial displays. These directives, coupled with national manufacturing initiatives, are reshaping sourcing patterns. Localized production and certified components are becoming critical for market access and competitive advantage.
Germany
Demand for advanced HMI panels is strong in Germany's automotive and pharmaceutical sectors. Stricter CE marking requirements mandate higher-quality, certified display components across industrial machinery. The Bavaria and Baden-Württemberg regions, known for their advanced manufacturing clusters, actively integrate these specialized displays.
China
China's expanding electronics production and general manufacturing automation fuel significant demand for cost-effective HMI solutions. GB standards and dual carbon goals influence component design and material choices for display manufacturers. Industrial parks in the Yangtze River Delta concentrate production and adoption of these displays.
United States
The United States requires ruggedized displays for its military, aerospace, and pharmaceutical facilities. FCC regulations on electromagnetic interference and FAA certifications for aerospace applications are critical. Silicon Valley and the Detroit automotive corridor are key hubs for advanced display integration.
India
India's Production Linked Incentive (PLI) scheme stimulates domestic manufacturing across electronics and automotive sectors, creating new demand. BIS standards ensure product quality and safety for locally produced and imported industrial displays. Manufacturing facilities in Maharashtra and Tamil Nadu are rapidly adopting HMI technologies.
Japan
Automotive manufacturing in Japan is accelerating the adoption of projected capacitive (PCAP) touch technology. JIS standards guide the design and performance of industrial displays for precision applications. The Kansai region, with its strong industrial base, sees significant integration of advanced HMI solutions.
Industrial Display Market Key Industry Players
Player mix skews toward specialized component providers and integrated solution vendors. The market structure exhibits a tiered approach, with premium suppliers focusing on high-reliability, certified products. Two strategic archetypes include niche specialists serving specific industries and broader portfolio players. Dominant competitive moves involve strategic partnerships for system integration and technology licensing for advanced display solutions.
Specialists in integrated solutions, such as Siemens, deeply embed displays within proprietary automation ecosystems. Advantech, a prominent Taiwanese entity, leverages its extensive portfolio to serve diverse end-user industries across Asia and North America. Kontron, a German-based company, exemplifies a focus on ruggedized displays for transportation and defense applications, emphasizing durability and specific certifications for harsh environments.
| Leading Market Players |
|---|
| NEC Display Solutions |
| Pro-face |
| Advantech |
| Kontron |
| ADLINK Technology |
| Siemens |
| Winmate |
| Daktronics |
| AU Optronics |
| Others |
Cost & Logistics Intelligence
Volume-driven manufacturing scale in Asia shapes the global industrial display market, influencing both component availability and baseline price floors for mature LCD platforms.
Pricing Analysis
Certification level (CE, FCC, FAA-grade) creates the primary spread in industrial display pricing, differentiating premium offerings from standard components. The dominant pricing model is per-unit transactional, though project-based pricing applies to integrated HMI solutions. Price differentiation stems from customization levels and included after-sales service. Pricing softness reflects the enduring cost-effectiveness of mature LCD platforms. Smaller manufacturers in emerging markets are most price-sensitive, while aerospace and medical sectors prioritize performance over cost.
Supply Chain Analysis
Inbound logistics costs for specialized components, such as high-brightness backlights, influence regional pricing and availability. The industrial display supply chain concentrates in China, Japan, and Taiwan for core components and assembly. Raw material dependencies include specialized glass substrates and durable touch controllers. Component sourcing volatility, particularly from key Asian suppliers, presents a structural risk. Downstream distribution runs through specialized component providers and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial display market offers a significant service-attach opportunity, with software integration and validation services expanding faster than hardware sales.
For Market Incumbents:Fortify core market positions by deepening integration within proprietary automation ecosystems, such as Siemens' offerings. Invest strategically in next-generation display technologies like MicroLED to counter LCD performance limitations. Pursue strategic partnerships for complete system integration to address end-user demand for pre-validated HMI solutions. Emphasize investment in certifications like CE marking and FCC regulations to maintain market access and premium positioning.
For New Entrants and Emerging Players:Differentiate on niche application performance by focusing on superior brightness and longevity for high-value sectors like medical imaging. Target underpenetrated sectors in India, leveraging the country's PLI scheme for domestic manufacturing. A viable go-to-market angle involves offering integrated HMI systems for specialized industrial environments, bypassing component-level procurement. Focus on projected capacitive touch technology for its durability and multi-touch capabilities.
For Investors and Strategic Acquirers:Specialized suppliers with strong intellectual property in MicroLED and projected capacitive technologies represent attractive acquisition targets. The market's long-term viability is anchored in increasing automation and stringent regulatory demands across industries. A key signal to watch is the accelerating adoption rate of MicroLED in critical visualization tasks within aerospace and defense. System integrators with deep vertical expertise also offer compelling investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in MicroLED R&D | This initiative develops superior displays for high-value medical and military applications. |
| Deepen HMI System Integration | This move aligns with customer demand for validated hardware and software stacks in pharma. |
| Secure Component Supply Agreements | Long-term agreements mitigate sourcing volatility for high-brightness backlights from Asia. |
| Expand PCAP Touch Portfolio | This expansion addresses the growing demand for durable multi-touch interfaces in automotive. |
| Pursue India Market Entry | This strategy capitalizes on India's PLI scheme and expanding manufacturing base. |
Research Approach
The analysis maps industrial display sub-sectors, each validated through primary interviews with automation engineers, procurement managers, and regulatory compliance officers. Secondary data sources include industry association reports, national manufacturing initiatives, and regulatory body publications from the EU, US, and China. This approach combines bottom-up market sizing with top-down validation through expert insights.
Outputs were validated for consistency against external benchmarks and historical market trends across the analysis window. The analytical framework incorporated segmentation dimensions such as product type, touch technology, application, end-user industry, and geographic region. Compound Annual Growth Rates were derived from historical data, projected market drivers, and forecast inputs like automation investment trends and regulatory compliance costs.
Forecasts assume regulatory continuity in key regimes like the EU and the US; material policy shifts would require re-modeling. The analysis acknowledges potential revisions due to rapid technological disruption, unforeseen supply chain shocks, or significant changes in global manufacturing policies. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Electronic Display Signs Market
Display Technologies
8K Display Resolution Market
Display Technologies
Global UHD Display Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
OLED Display Market
Display Technologies
3D Display Module Market
Display Technologies
Electrochromic Window Market
Display Technologies
TFT LCD Panel Market
Display Technologies
Projector Screen Market
Display Technologies
Large Industrial Displays Market
Display Technologies
Flexible Display Market
Display Technologies
Global Display Market
Display Technologies
Global Transparent Display Market
Display Technologies
AMOLED Substrate Market
Display Technologies
OLED Panel Market
Display Technologies
Global Portable Monitor Market