
 Middle East and Africa Indoor LED Lighting Market | 2026-2036
Middle East and Africa Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Indoor LED Lighting Market Insights
Chip-on-board LED architecture is tilting fixture design toward higher lumen density with smaller form factors across commercial interiors. Signify leverages its connected lighting platform to secure large-scale hospitality contracts in the Gulf. OSRAM sustains R&D intensity in tunable white systems for healthcare and educational environments. Al Nasser Group dominates regional distribution channels through direct contractor relationships in Saudi Arabia and the UAE.
Middle East and Africa indoor LED lighting encompasses solid-state luminaires engineered with gallium nitride emitters, typically operating at 80-100 lumens per watt efficacy, designed for enclosed interior spaces requiring controlled color temperature and beam distribution. Panel lights and downlights anchor current volume as building codes tighten minimum efficacy thresholds across Gulf Cooperation Council jurisdictions. Smart lighting technology captures expanding margin pools as facility managers prioritize occupancy-based controls and daylight harvesting in commercial retrofits. The residential end user segment competes primarily on first-cost economics, while hospitality buyers differentiate through circadian rhythm tuning and brand-aligned RGB accent systems.
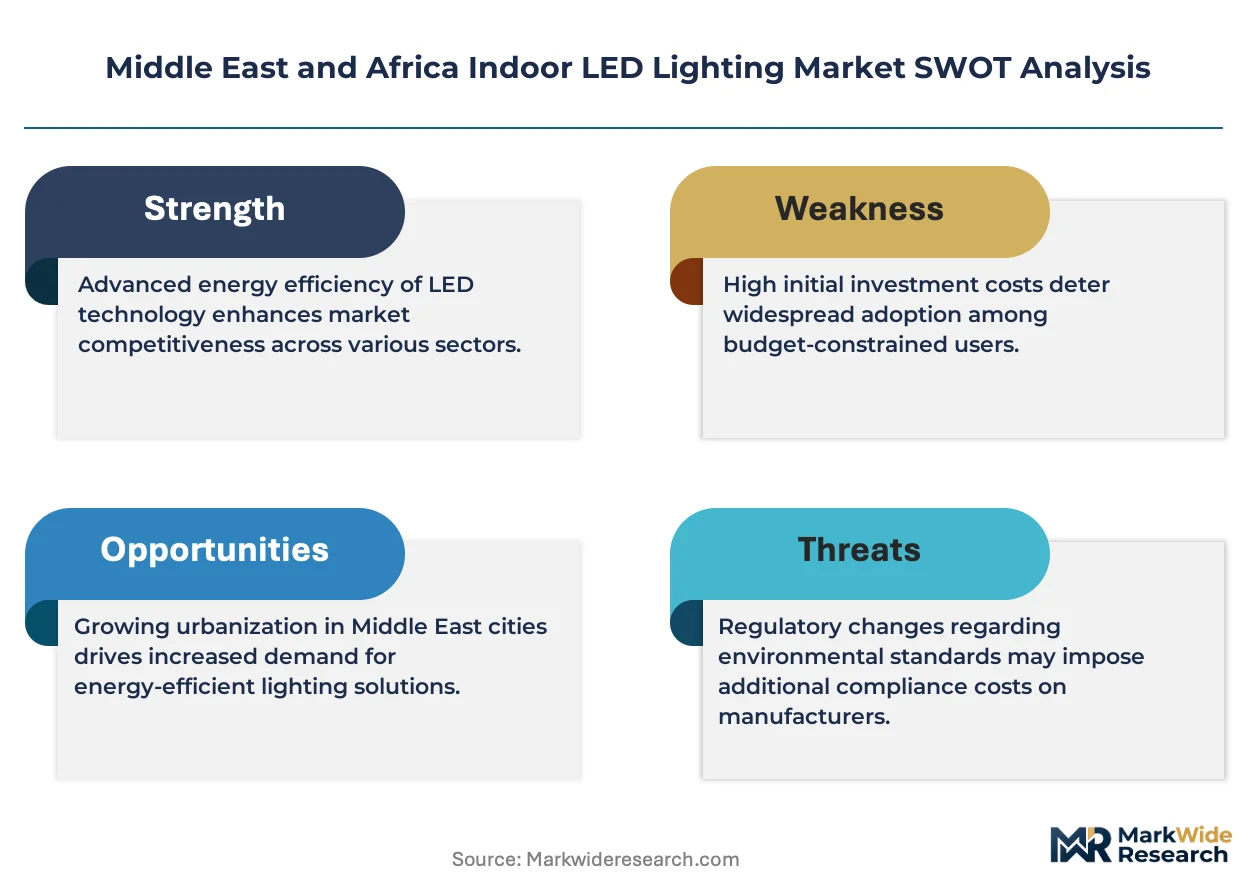
Saudi Standards, Metrology and Quality Organization (SASO) mandates IECEE certification for LED lighting imports, effectively filtering substandard products from Saudi Arabian distribution channels. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces SANS performance classes that shape procurement specifications for government buildings and schools. Dubai Municipality's green building regulations require LED compliance for all new commercial interiors above specified floor areas. Stakeholders must monitor evolving carbon disclosure requirements under the UAE's Net Zero 2050 pathway and assess how local content rules in Saudi Vision 2030 projects redirect supplier qualification criteria.
Market Dynamics
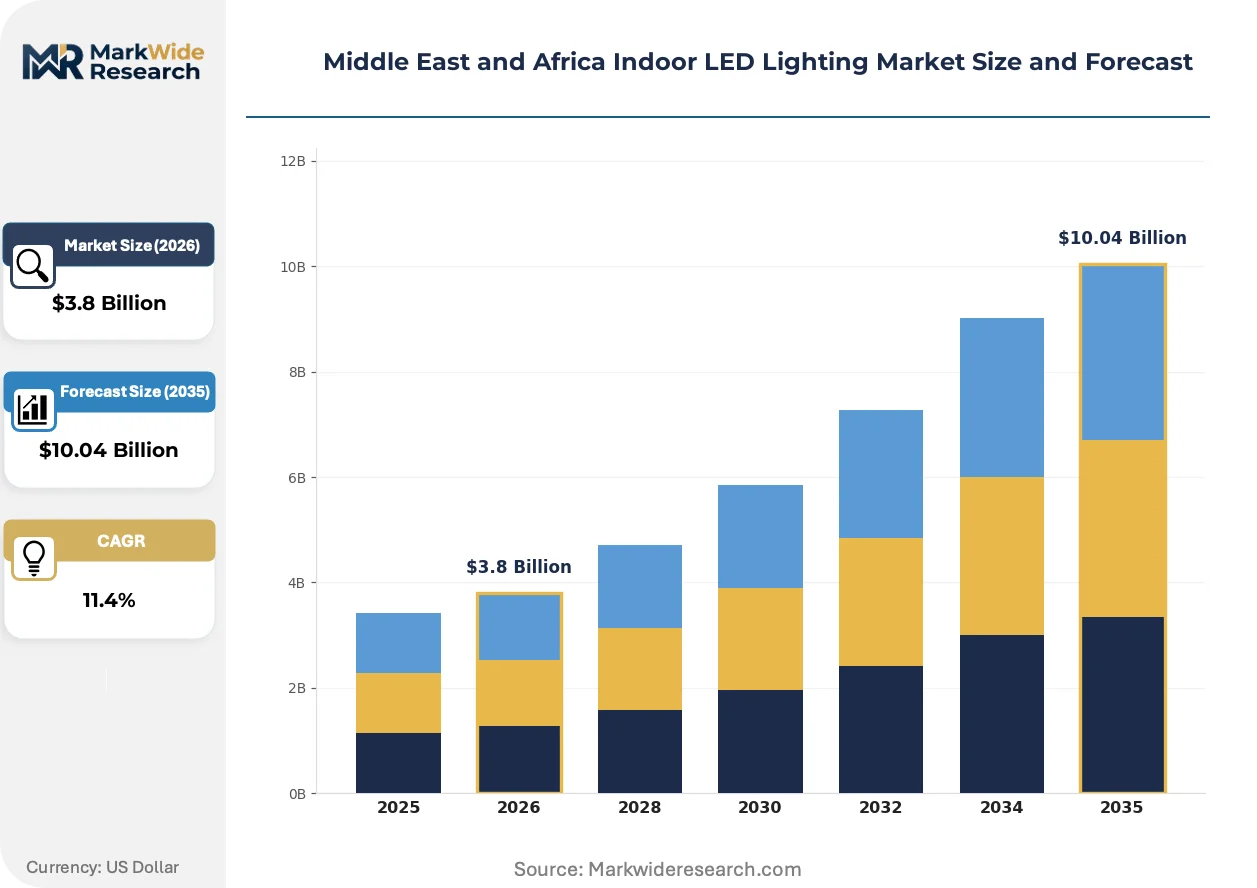
Energy performance mandates across Gulf Cooperation Council jurisdictions are compressing replacement cycles and forcing rapid technology turnover in commercial building stock. SASO's IECEE certification requirements and Dubai Municipality's green building codes together create a compliance-driven demand floor that manufacturers must meet to access premium project pipelines.
Growth Catalysts
- SASO IECEE Certification Mandate:Saudi Arabia's technical barrier filters substandard imports, elevating quality tiers across the Kingdom's distribution channels and accelerating premium product penetration in hospitality and healthcare verticals.
- Giga-Project Construction Pipeline:Saudi Vision 2030 developments in NEOM, The Line, and Qiddiya generate concentrated demand for tunable white and circadian lighting systems in hotels, hospitals, and educational facilities.
- Chip-on-Board Architecture:Higher lumen density in smaller form factors enables recessed and surface-mounted fixtures to meet stringent efficacy thresholds without sacrificing aesthetic integration in high-end interiors.
Market Restraints
- Gallium Nitride Substrate Volatility:Raw material concentration in East Asian supply chains exposes fixture manufacturers to input cost swings and extended lead times for high-efficacy emitters.
- Technical Limitation in Retrofit Compatibility:Legacy dimming infrastructure using phase-cut protocols creates flicker and color shift issues when paired with modern LED drivers, slowing residential upgrade velocity.
- SANS Performance Class Friction:South Africa's NRCS enforcement creates certification bottlenecks for imported luminaires, extending time-to-market for new product introductions.
Strategic Opportunities
- Underpenetrated Nigerian Commercial Stock:Lagos and Abuja office buildings retain substantial fluorescent and CFL penetration, creating retrofit white space as grid reliability improves and energy costs rise.
- Human-Centric Lighting Convergence:Integration of tunable white systems with building management platforms enables circadian rhythm programming in healthcare and education verticals across the UAE.
- Direct Contractor Channel Development:Bypassing traditional distributor markups through project-specific procurement relationships captures margin in Saudi giga-projects where specification control rests with EPC firms.
Industry Challenges
- Certification Timeline Compression:SASO's evolving technical regulations require continuous retesting of existing product lines, straining R&D budgets and delaying regional launches.
- Integration Complexity with Legacy Controls:Facility managers in Dubai's existing commercial towers face interoperability gaps between new LED fixtures and installed BAS infrastructure, requiring costly gateway hardware.
- Skill Scarcity in Commissioning:Shortage of technicians trained in DALI-2 and wireless mesh configuration limits smart lighting deployment speed in Saudi healthcare facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Indoor LED Lighting Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Troffers, High Bay Lights Technology: Smart Lighting, Dimmable, Tunable White, RGB End User: Residential, Commercial, Hospitality, Educational Installation Type: New Installation, Retrofit, Integrated System, DIY |
| Companies Covered | Signify, OSRAM, Acuity Brands, Samsung, Panasonic, Al Nasser Group, EGLO Leuchten, LEDVANCE, OPPLE Lighting, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Indoor LED Lighting Market Trends and Innovations
Illumination architecture across Middle East and Africa interiors is pivoting from static fixtures toward adaptive, sensor-integrated systems that respond to occupancy patterns and daylight availability. This transformation compresses traditional product lifecycles while elevating software and controls to parity with hardware in procurement decisions.
Chip-on-board LED packaging is migrating from conventional surface-mount device configurations toward direct emitter arrays on thermally conductive substrates. Hospitality operators in Dubai and Riyadh specify these modules for lobby and corridor applications where ceiling plenum depth is constrained. The technology is migrating from premium custom fixtures into standardized downlight and panel formats, eroding the price premium that earlier generations commanded.
Dubai Municipality's green building regulations now mandate LED compliance for all new commercial interiors above specified floor areas, with enforcement tied to building permit issuance. This policy compresses specification timelines for developers and elevates efficacy thresholds above minimum SASO requirements. Healthcare and educational facilities face the tightest compliance windows, driving accelerated procurement cycles for tunable white systems.
Facility management contracts across Gulf commercial towers are unbundling lighting maintenance from bundled mechanical service agreements. Specialized lighting integrators now compete directly with traditional MEP contractors for long-term service revenue. This shift is most visible in Dubai's Grade A office stock, where landlords seek performance-based contracts guaranteeing maintained illuminance levels rather than equipment replacement schedules.
Middle East and Africa Indoor LED Lighting Market Segmentation
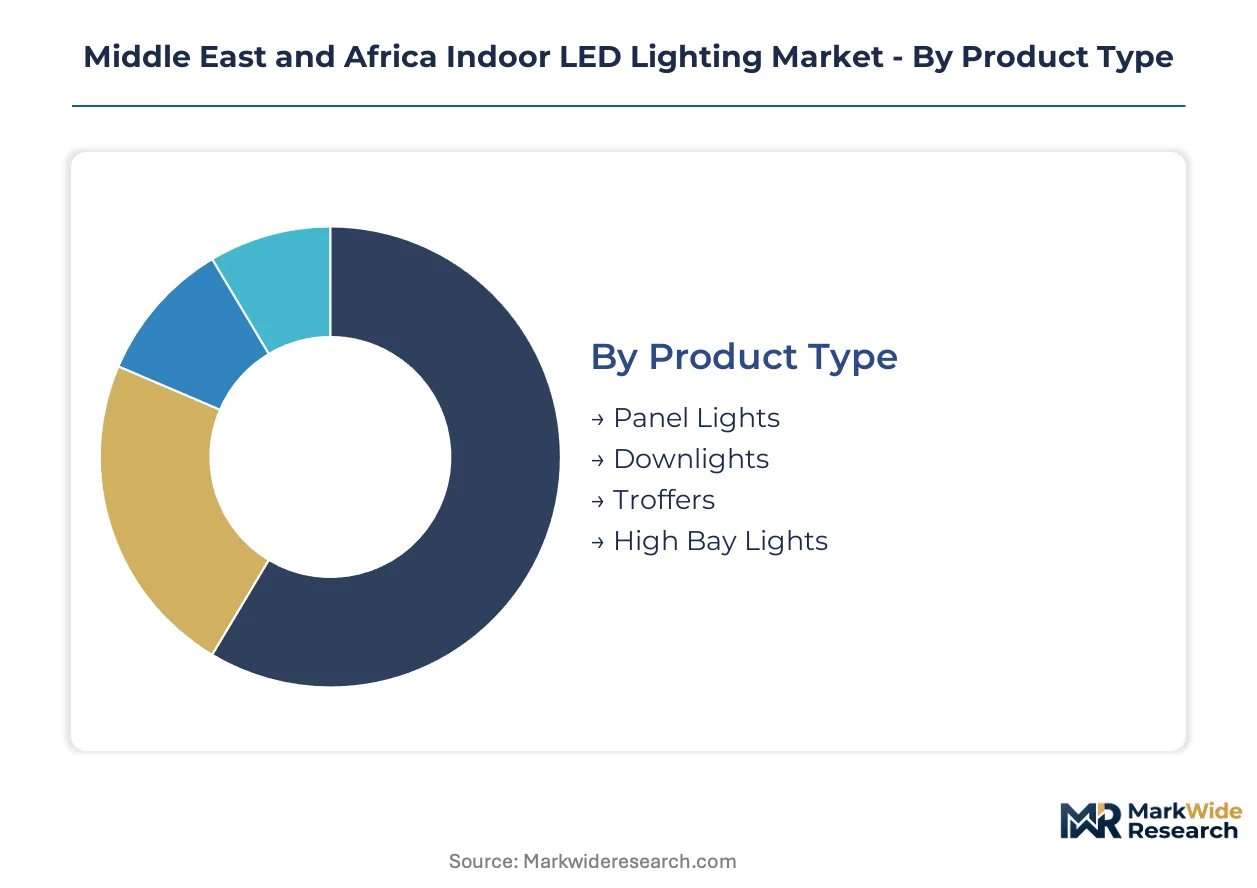
Segmentation in Middle East and Africa indoor LED lighting reveals how procurement criteria diverge across building types and technology maturity. Specification control varies sharply between SASO-regulated Saudi projects and South Africa's SABS-enforced public sector tenders.
Product Type:
Cost tier differentiation separates commodity volume fixtures from specification-grade architectural luminaires serving Gulf giga-projects.
- Panel Lights:Edge-lit and backlit flat panels dominate commercial office retrofits across Dubai and Riyadh, where ceiling grid compatibility and uniform illuminance override first-cost sensitivity. Procurement concentrates in hospitality and healthcare verticals requiring UGR<19 glare control for extended occupancy comfort.
- Downlights:COB emitter arrays in compact housings address plenum depth constraints in Saudi hotel corridors and UAE residential towers. Demand clusters in premium residential and boutique hospitality segments where beam angle precision and trim aesthetics command specification priority.
- Troffers:T-bar grid fixtures retain share in South African educational and government buildings with legacy ceiling infrastructure.
- High Bay Lights:Industrial warehouses and logistics centers in Nigeria and Kenya specify these for high-bay racking illumination.
Panel lights command the established base. The steepest expansion runs through downlights.
Technology:
Application requirements determine whether buyers prioritize energy savings, human-centric outcomes, or aesthetic differentiation.
- Smart Lighting:Sensor-integrated systems with DALI-2 or wireless mesh protocols capture facility management contracts in Dubai's Grade A commercial towers. Procurement friction arises from legacy BAS interoperability gaps requiring gateway hardware investments.
- Tunable White:CCT-shifting systems align with circadian rhythm programming in Saudi healthcare facilities and UAE educational environments. SASO's IECEE certification filters substandard driver electronics from premium specification channels.
- Dimmable:Phase-cut and 0-10V protocols address residential retrofit compatibility constraints across South Africa's housing stock.
- RGB:Color-changing accent systems serve hospitality brand alignment in Dubai and Riyadh luxury properties.
Smart lighting commands the established base. Tunable white is climbing the fastest as healthcare and education procurement accelerates.
End User:
Customer type shapes whether procurement prioritizes first-cost economics, lifecycle energy savings, or experiential outcomes.
- Commercial:Office landlords across Dubai's DIFC and Riyadh's King Abdullah Financial District specify efficacy-driven retrofits with occupancy-based controls. Performance-based maintenance contracts are displacing traditional equipment replacement schedules.
- Hospitality:Hotel operators in NEOM, The Line, and Qiddiya mandate tunable white and RGB systems for guest experience differentiation. Brand-aligned lighting design consultants control specification authority ahead of EPC contractors.
- Residential:First-cost sensitivity dominates mass-market housing in Egypt and Nigeria, constraining premium fixture penetration.
- Educational:South Africa's NRCS-enforced SANS performance classes shape procurement for government school retrofits.
Commercial commands the established base. Hospitality is gaining share fastest through Saudi giga-project construction velocity.
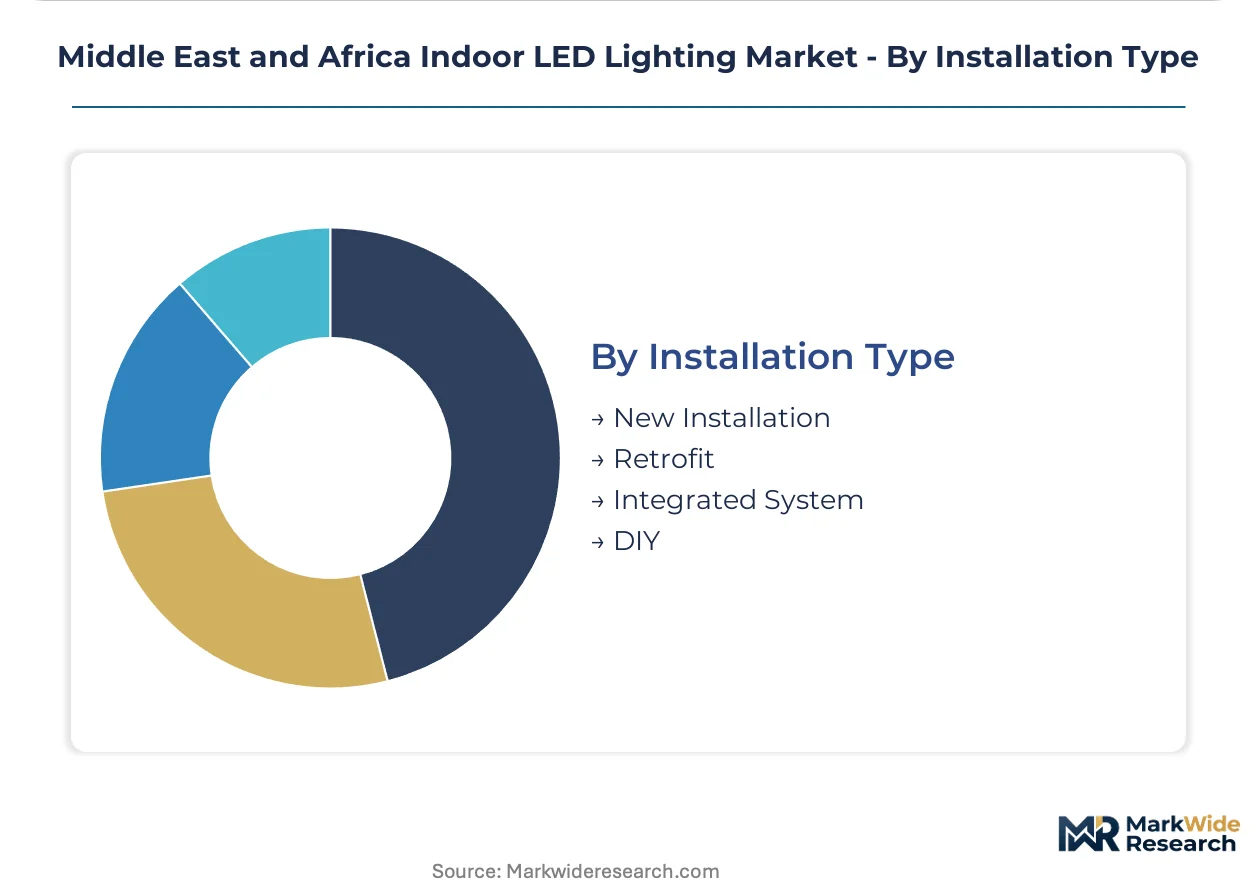
Installation Type:
Volume concentration tracks building stock age, grid reliability, and contractor capability distribution across the region.
- Retrofit:Fluorescent and CFL replacement programs accelerate in South Africa's compulsory SABS labeling environment and Dubai's green building compliance windows. Technical limitation in legacy dimming infrastructure creates flicker and driver compatibility friction.
- New Installation:Integrated LED luminaires in Saudi Vision 2030 developments bypass retrofit constraints entirely. NEOM and Qiddiya projects specify circadian-ready systems from foundation phase.
- Integrated System:Turnkey lighting-with-controls packages capture large-format commercial developments in Abu Dhabi and Jeddah.
- DIY:Retail channel fixtures serve residential replacement demand in urban Nigerian and Kenyan markets.
Retrofit commands the established base. New installation is expanding most quickly through concentrated giga-project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality-led procurement in Saudi Arabia and compliance-driven retrofits in South Africa concentrate buyer archetypes across distinct regulatory environments. Dubai's green building mandates attract specification-grade suppliers seeking premium project access. Nigerian commercial stock underpenetration creates retrofit opportunity as grid reliability improves.
Saudi Arabia
NEOM, The Line, and Qiddiya giga-projects generate concentrated demand for tunable white and circadian lighting systems in hotels, hospitals, and educational facilities. SASO mandates IECEE certification for all LED lighting imports, filtering substandard products from distribution channels. Riyadh's King Abdullah Financial District anchors commercial retrofit activity as landlords pursue occupancy-based control systems.
United Arab Emirates
Dubai Municipality's green building regulations require LED compliance for all new commercial interiors above specified floor areas, with enforcement tied to building permit issuance. The UAE's Net Zero 2050 pathway introduces evolving carbon disclosure requirements that reshape supplier qualification criteria. Dubai's Grade A office stock in the DIFC cluster drives performance-based maintenance contracts displacing traditional equipment replacement schedules.
South Africa
The National Regulator for Compulsory Specifications enforces SANS performance classes that shape procurement specifications for government buildings and schools. Compulsory SABS energy performance labeling for luminaires accelerates replacement cycles across fluorescent and CFL legacy stock. Johannesburg and Cape Town educational facilities face tightened compliance windows driving accelerated procurement for standardized panel and troffer fixtures.
Nigeria
Lagos and Abuja office buildings retain substantial fluorescent and CFL penetration, creating retrofit white space as grid reliability improves and energy costs rise. The country's national standards organization develops technical regulations for LED imports that will reshape distribution channel access. Lagos commercial towers concentrate specification activity where facility managers prioritize first-cost economics over smart control integration.
Egypt
Mass-market residential housing drives volume demand for first-cost-sensitive fixtures with limited premium penetration. The country's building and housing ministry advances energy efficiency codes that will compress replacement cycles in new construction. Cairo's satellite city developments concentrate new installation activity where integrated LED luminaires bypass retrofit infrastructure constraints entirely.
Middle East and Africa Indoor LED Lighting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority in Saudi giga-projects and Dubai commercial towers. The vendor base spans multinational lighting platforms, regional distribution conglomerates, and specialized architectural fixture houses. Three archetypes dominate: connected lighting platform operators, regional channel captains with direct contractor relationships, and COB emitter technology specialists. Competitive moves concentrate on strategic partnerships with EPC firms and geographic expansion through SASO certification acquisition.
Among multinational platform operators, Signify and OSRAM represent the connected lighting and tunable white specialization archetypes respectively. Signify occupies a position exemplifying hospitality contract capture through software-integrated platforms. OSRAM sits within the healthcare-education vertical focus tier. Regional channel control concentrates with Al Nasser Group, which anchors the direct contractor relationship archetype across Saudi Arabia and UAE distribution. These three players illustrate the competitive structure: technology platforms compete for specification authority while channel captains compete for procurement access.
| Leading Market Players |
|---|
| Signify |
| OSRAM |
| Acuity Brands |
| Samsung |
| Panasonic |
| Al Nasser Group |
| EGLO Leuchten |
| LEDVANCE |
| OPPLE Lighting |
| Others |
Pricing and Supply Chain Analysis
Guangdong Province's emitter manufacturing clusters dictate downstream pricing power across Middle East and Africa distribution channels. Fixture assemblers in Jeddah and Dubai face margin compression when gallium nitride substrate costs spike, forcing tiered pricing adjustments across hospitality and commercial contract tiers.
Pricing Analysis
Cost-plus contracts with gallium nitride indexation dominate procurement for Saudi giga-projects and Dubai commercial towers. Pricing stratifies across IECEE-certified premium tiers, SANS-compliant standard tiers, and unlabeled economy imports serving Nigerian residential channels. Price erosion runs through economy fixtures as Chinese exporters absorb tariff friction to maintain volume. Residential buyers in Egypt and Nigeria exhibit highest price sensitivity, while hospitality procurement in NEOM prioritizes circadian performance over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day terms have become standard for UAE distributors stocking specification-grade architectural fixtures. Manufacturing concentrates in China, South Korea, and Taiwan for gallium nitride substrates, driver electronics, and COB emitter arrays. Fixture assembly draws from aluminum extrusions and thermal management components anchored in Turkish and Egyptian industrial zones. Single-source vulnerability in East Asian substrate supply creates exposure to logistics chokepoints through the Strait of Hormuz. Distribution runs through Al Nasser Group's direct contractor relationships across Saudi Arabia and the UAE, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED panel and laser diode substitutes threaten premium specification tiers if efficacy gaps narrow and cost curves steepen. Incumbents must navigate this substitution pressure while defending installed base revenue in retrofit-heavy markets.
For Market Incumbents: Pre-empt OLED encroachment by accelerating tunable white R&D investment and securing exclusive circadian lighting patents for healthcare verticals. Deepen backward integration into gallium nitride substrate sourcing through offtake agreements with Taiwanese foundries. Fortify SASO certification moats by pre-positioning product lines for anticipated efficacy threshold increases.
For New Entrants and Emerging Players: Mid-market commercial buildings in Lagos and Abuja represent the most penetrable entry point, with fluorescent legacy stock exceeding sixty percent penetration and rising grid reliability enabling payback calculations. Nigerian government building retrofits offer tender-based volume without established incumbent relationships. Target EPC contractor direct relationships rather than distributor channel buildout to capture specification authority early.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SASO and Dubai Municipality compliance windows concentrate procurement authority with certified suppliers. Acquisition targets should display IECEE certification breadth across product lines and established EPC relationships in Saudi Vision 2030 developments. Monitor gallium nitride spot pricing as inflection indicator for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Acquisition | IECEE compliance unlocks access to Saudi giga-project pipelines and filters low-cost competition. |
| Direct EPC Channel Development | Bypassing distributor markups captures margin in NEOM and Qiddiya specification-controlled procurements. |
| Tunable White R&D Investment | Circadian rhythm programming differentiates hospitality and healthcare offerings in premium segments. |
| Backward Integration into Substrates | Gallium nitride supply agreements with Taiwanese foundries mitigate East Asian concentration risk. |
| Smart Controls Platform Integration | DALI-2 and wireless mesh capability secures facility management contracts in Dubai Grade A towers. |
Research Methodology
A spread of perspectives from lighting design consultants, EPC procurement directors, facility management operators, and SASO certification specialists converged on the working assumptions. Primary interviews with hospitality specification architects and educational facility planners were cross-referenced against secondary sources including SASO technical regulation filings, Dubai Municipality green building permit databases, and SANS performance class enforcement records. Bottom-up channel volume estimates were triangulated with top-down construction pipeline valuations across the analysis window.
Demand-supply balance dynamics shaped the forecast framework, modeling consumption across product type, technology tier, end-user vertical, and installation mode dimensions. CAGRs were derived from replacement cycle compression rates tied to regulatory enforcement timelines and giga-project construction velocity. Industry-specific inputs included gallium nitride substrate pricing trajectories and IECEE certification approval backlogs.
Practitioners should monitor SASO regulatory amendments, Dubai Municipality efficacy threshold revisions, and Strait of Hormuz logistics disruptions for early signals. Forecasts reflect assumptions about continued Saudi Vision 2030 execution and South African grid stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Germany Automotive LED Lighting Market
LED
Middle East LED Lighting Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Infrared (IR) LED Market
LED
China LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
LED Tester Market
LED
UAE LED Lights Market
LED
Thailand LED Market
LED
UK Indoor LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
Japan LED Market
LED
OLED Blue Emitter Market
LED
Europe Indoor LED Lighting Market
LED
Programmable LED Drivers Market
LED
GCC LED Lighting Market