
 LED Panel Light Drivers Market | 2026-2036
LED Panel Light Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
LED Panel Light Drivers Market Analytics
Silicon carbide is shifting into mainstream driver topologies as manufacturers pursue higher switching frequencies and reduced thermal losses. Signify leverages vertical integration across LED modules and driver electronics to capture margin pools in specification-grade projects. Mean Well Enterprises anchors its position through standardized form factors and global distribution density. Inventronics competes by specializing in outdoor and high-bay driver portfolios with extended temperature ratings.
LED panel light drivers are power-electronics subassemblies that convert mains AC or DC input into regulated current or voltage output matched to LED array electrical characteristics, typically operating at efficiencies above 85 percent and incorporating power-factor correction. Their primary commercial purpose is to ensure stable luminous flux, protect against thermal runaway, and enable dimming or networked control in flat-panel luminaires. Dimmable drivers command premium positioning as building-automation integration becomes standard in commercial specifications, while smart drivers represent the fastest-expanding technology segment due to IoT-enabled energy management mandates. Constant current architectures dominate unit volume across industrial and retail installations where LED string configurations vary.
Europe's Ecodesign and RoHS frameworks restrict hazardous substances in driver assemblies and mandate minimum efficiency tiers, while China's GB standards and MIIT directives enforce domestic performance certification for lighting power supplies. The US EPA Energy Star program and DOE testing protocols shape procurement criteria for federal and utility-rebate-funded retrofits. Stakeholders must monitor evolving efficiency tier thresholds and wireless-protocol interoperability requirements as procurement specifications harden.
Market Dynamics
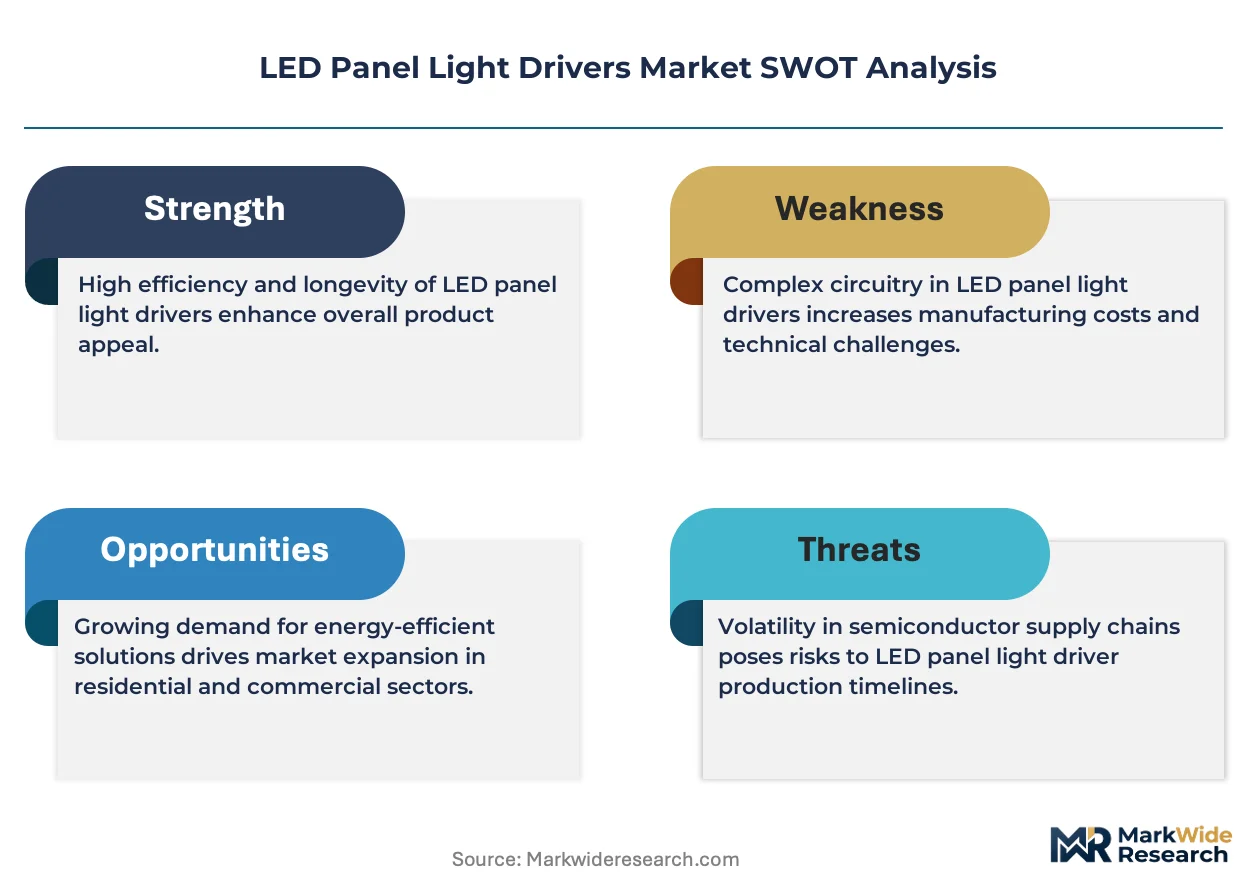
Silicon carbide power semiconductors are compressing thermal management costs and enabling higher-frequency switching topologies that reduce driver size and weight for slim panel form factors.
Growth Catalysts
- Commercial building automation mandates:Ecodesign requirements in Europe and GB standards in China enforce dimming compatibility and minimum efficiency tiers that accelerate specification-grade driver procurement.
- Smart driver architectures:IoT-enabled power electronics with wireless protocol stacks are capturing share in facility management retrofits requiring centralized energy monitoring and predictive maintenance.
- East Asian manufacturing concentration:Shenzhen and Suzhou industrial clusters provide integrated PCB assembly, magnetic component sourcing, and burn-in testing infrastructure that compresses lead times for export markets.
Market Restraints
- Silicon carbide substrate costs:Wide-bandgap semiconductor wafers command premiums over silicon IGBTs that constrain adoption in economy-tier driver lines serving price-sensitive residential channels.
- Magnetic component supply concentration:Ferrite core and copper winding production clusters in southeastern China create single-source vulnerability during regional power rationing or logistics disruptions.
- Electromagnetic compatibility certification friction:Divergent FCC Part 15, CE EMC, and GB/T 9254 testing requirements extend validation timelines for multi-region product families.
Strategic Opportunities
- German specification market penetration:DIN standards and VDE certification requirements create defensible positioning for suppliers offering documented lumen maintenance curves and failure rate data.
- Healthcare and cleanroom applications:Flicker-free drivers with sub-5% total harmonic distortion are capturing specification share in surgical suites and pharmaceutical manufacturing where visual task precision is critical.
- Wireless protocol convergence:Drivers integrating both Bluetooth Mesh and Zigbee stacks are enabling interoperability across competing building automation platforms without hardware duplication.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized expertise in magnetics design, thermal simulation, and EMC mitigation is concentrating at tier-one suppliers and contract manufacturers.
- Legacy fluorescent ballast replacement complexity:Retrofit projects require drivers compatible with existing ceiling grid wiring configurations and control voltage standards that vary across installation vintages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Panel Light Drivers Market |
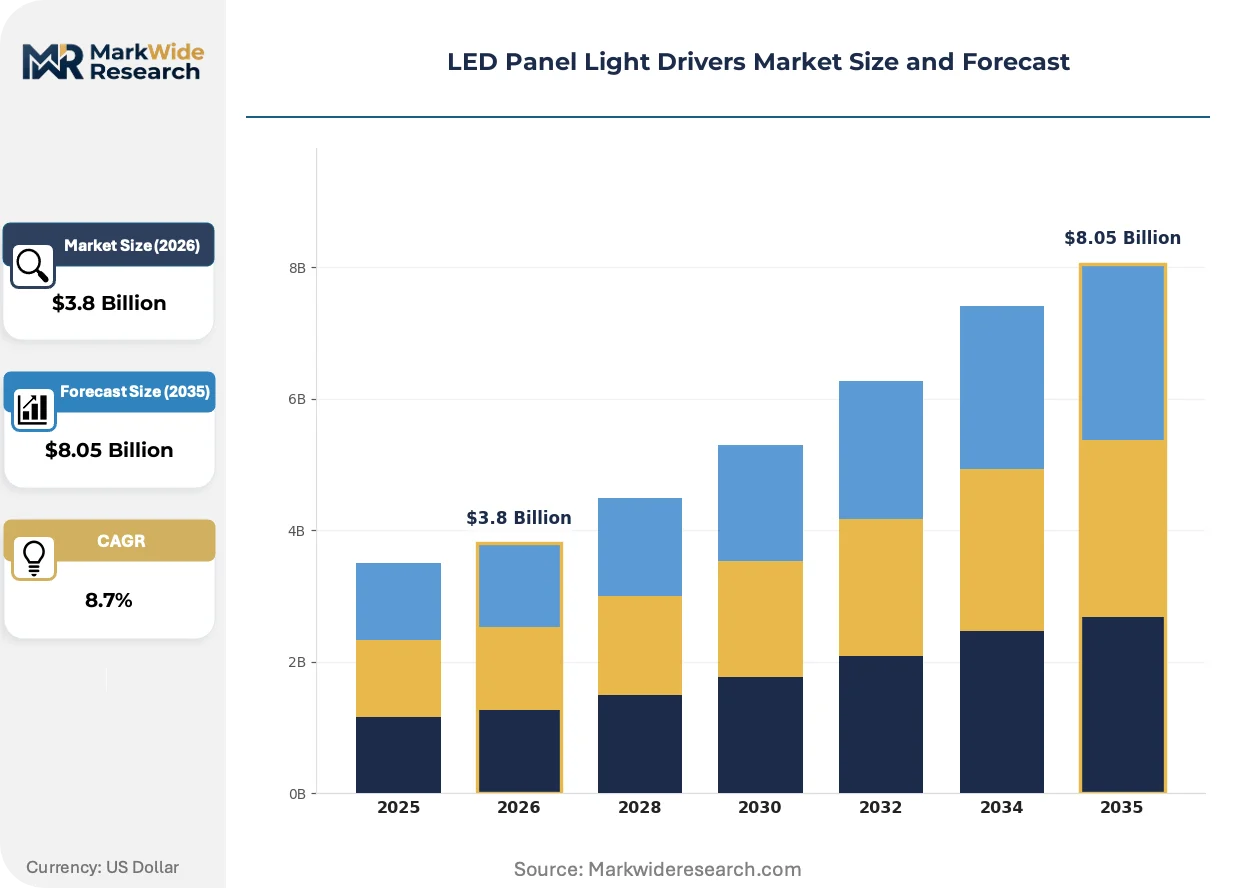
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Constant Voltage, Constant Current, Dimmable, Non-Dimmable Technology: Switching Power Supply, Linear Regulators, Programmable Drivers, Smart Drivers End User: Residential, Commercial, Industrial, Retail Installation Type: Surface Mount, Recessed Mount, Pendant Mount, Wall Mount |
| Companies Covered | Signify, ams OSRAM, Mean Well Enterprises, Inventronics, Tridonic, Acuity Brands Lighting, Lifud Technology, Delta Electronics, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Panel Light Drivers Market Evolving Landscape
Power semiconductor material transitions and wireless control integration are restructuring competitive differentiation beyond basic efficiency metrics toward system-level reliability and interoperability.
GaN-on-silicon transistors are expanding into mainstream driver designs by enabling switching frequencies above 100kHz that shrink magnetic component volume and reduce audible noise in open-office installations. Commercial specification buyers in North America and Europe are qualifying these topologies for high-density ceiling deployments where space and acoustic comfort constrain legacy silicon solutions. The technology is expanding into mid-power segments previously reserved for silicon MOSFETs as foundry capacity scales and device costs converge.
Europe's Ecodesign Directive and RoHS substance restrictions are tightening permissible limits on standby power consumption and hazardous material content in driver assemblies sold across EU member states. Manufacturers must redesign PCB layouts and solder formulations to eliminate restricted substances while maintaining thermal cycling reliability. The regulations are compressing margins for economy-tier suppliers lacking in-house materials engineering and compliance documentation capabilities.
Specification buyers are consolidating procurement around driver suppliers offering integrated luminaire-lifetime warranties and documented lumen depreciation curves rather than component-only coverage. Lighting designers and facility managers in German-speaking markets are requiring 50,000-hour minimum rated life with 90% lumen maintenance as baseline qualification criteria. This behavioral shift is disqualifying pure-component vendors lacking luminaire-level testing partnerships and field failure databases.
LED Panel Light Drivers Market Segmentation
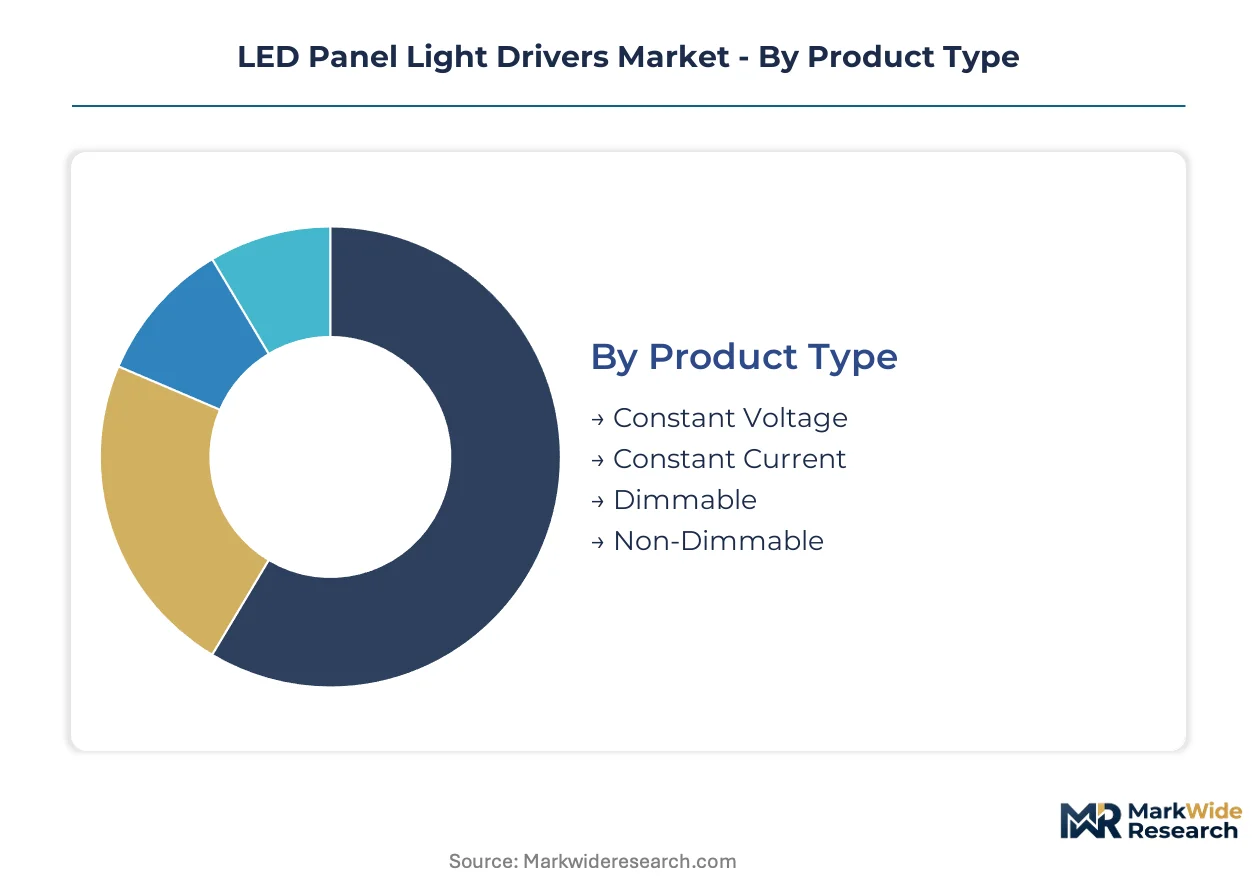
Driver architectures diverge sharply across application contexts, with specification-grade installations demanding programmable control while commodity replacements prioritize cost minimization. Technology selection cascades through thermal design, electromagnetic compatibility, and warranty positioning decisions that separate premium suppliers from economy assemblers.
Product Type:
Customization intensity spans from fixed-output economy units to field-configurable intelligent drivers with embedded protocol stacks.
- Constant Current:Regulates output current regardless of LED string voltage variations, essential for series-connected arrays in high-bay and street lighting where thermal drift protection is mandatory. Industrial procurement in Germany and Japan concentrates here due to lumen maintenance guarantees required by DIN and JIS certification protocols.
- Dimmable:Incorporates 0-10V, DALI, or phase-cut control interfaces enabling building automation integration. Commercial office retrofits across US Energy Star jurisdictions and European Ecodesign zones are consolidating procurement around these variants as dimming mandates harden.
- Constant Voltage:Maintains fixed output voltage for parallel LED configurations, common in strip lighting and signage applications with simpler thermal management requirements.
- Non-Dimmable:Fixed-output designs for cost-sensitive residential replacements and basic panel installations without control infrastructure.
Most installed capacity flows through Constant Current architectures. Expansion is steepest in Dimmable configurations.
Technology:
Cost tier stratification separates silicon-based legacy topologies from wide-bandgap semiconductor implementations commanding specification premiums.
- Smart Drivers:Integrate wireless protocol stacks, energy metering, and predictive maintenance algorithms for IoT-enabled facility management. US commercial building automation mandates and China's MIIT smart city directives are accelerating specification in new construction and deep retrofit projects.
- Switching Power Supply:Dominant topology using high-frequency conversion to achieve efficiency above 85% with active power-factor correction. Volume production concentrates in Shenzhen and Suzhou manufacturing clusters serving global export markets.
- Linear Regulators:Simpler designs with lower electromagnetic emissions for noise-sensitive healthcare and residential applications where efficiency trade-offs are acceptable.
- Programmable Drivers:Field-configurable output parameters enabling inventory consolidation across multiple luminaire SKUs, favored by specification-grade lighting OEMs.
Switching Power Supply architectures carry the majority of unit volume. Smart Drivers are climbing the fastest as wireless commissioning becomes standard in commercial specifications.
End User:
Application maturity separates established commercial retrofit channels from emerging residential smart home integration.
- Commercial:Office, hospitality, and institutional installations requiring 50,000-hour rated life, sub-20% total harmonic distortion, and documented lumen depreciation curves. German VDE certification and US DLC qualification filter supplier participation.
- Industrial:High-bay, warehouse, and manufacturing environments demanding extended temperature ratings and surge protection. Mean Well and Inventronics compete here through outdoor-rated portfolios.
- Retail:Merchandising and display applications prioritizing color consistency and flicker-free operation for visual merchandise presentation.
- Residential:Replacement and new construction markets with fragmented distribution through electrical wholesalers and big-box retail channels.
Commercial segment channels the largest revenue pool. Industrial applications are gaining share fastest as LED penetration in high-bay metal halide replacement accelerates.
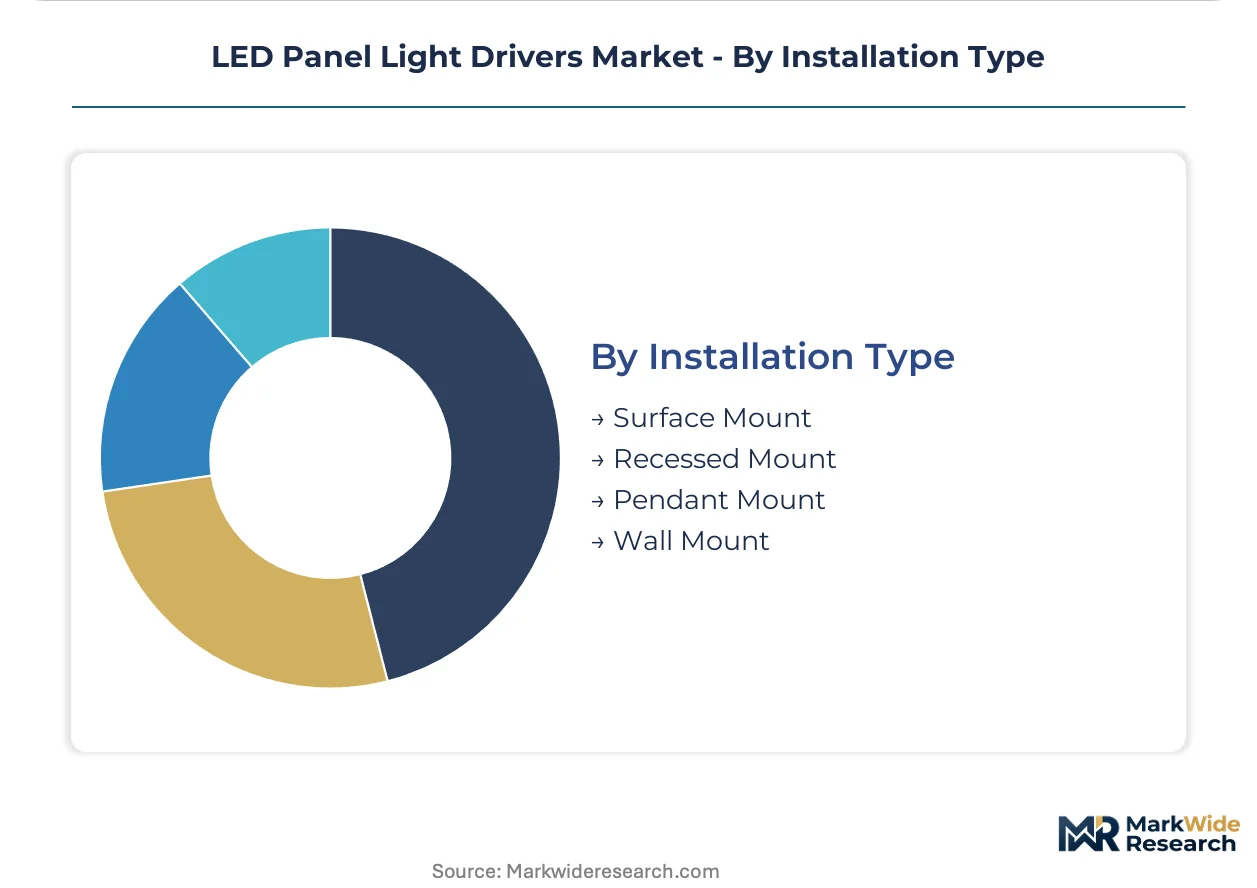
Installation Type:
Mounting geometry dictates driver form factor, thermal pathway design, and accessibility for maintenance in finished ceiling systems.
- Recessed Mount:Integrated into suspended ceiling grids, requiring slim profiles and passive thermal management for plenum-rated installations. Dominates commercial office specifications in North America and Europe.
- Surface Mount:Exposed ceiling applications in industrial and retail environments where thermal dissipation through visible heat sinks is acceptable.
- Pendant Mount:Suspended luminaire configurations for atrium, circulation, and task lighting with remote driver placement options.
- Wall Mount:Architectural and cove lighting applications with lateral emission patterns and constrained depth envelopes.
Recessed Mount carries the majority of panel driver shipments. Surface Mount is expanding most quickly in industrial retrofit conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the global LED panel light driver manufacturing base, with integrated PCB assembly and magnetic component sourcing compressing lead times for export markets across all major demand regions.
China
Commercial building retrofits in tier-one cities drive specification-grade driver procurement. MIIT directives and GB standards enforce domestic performance certification for lighting power supplies. Shenzhen and Suzhou industrial clusters provide burn-in testing infrastructure and ferrite core sourcing that feeds global supply chains.
Germany
DIN standards and VDE certification requirements filter supplier participation in specification-grade projects. Ecodesign Directive mandates accelerate dimmable driver adoption across federal states. Bavaria and North Rhine-Westphalia concentrate lighting OEM procurement offices demanding documented lumen maintenance curves.
United States
Commercial office retrofits requiring Energy Star qualification shape procurement criteria for federal and utility-rebate-funded projects. DOE testing protocols and EPA Energy Star programs enforce minimum efficiency tiers. California Title 24 building codes drive smart driver specification in new construction across the Pacific Coast and Southwest.
Japan
Industrial high-bay LED penetration accelerates demand for constant current architectures with extended temperature ratings. METI efficiency standards and JIS certification protocols mandate thermal cycling reliability. Kansai and Chubu manufacturing clusters concentrate precision magnetics production for premium driver lines.
India
Smart city infrastructure investments expand procurement of IoT-enabled drivers for municipal lighting networks. BIS certification and CEA efficiency regulations enforce minimum power factor correction thresholds. Maharashtra and Gujarat industrial corridors develop domestic PCB assembly capacity serving South Asian retrofit markets.
LED Panel Light Drivers Market Competitive Landscape
Global majors compete with regional champions across certification depth and distribution density, producing a tiered structure where specification-grade suppliers capture premium positioning while economy assemblers serve price-sensitive residential channels. Three archetypes dominate: vertically integrated lighting conglomerates controlling captive driver supply, specialized power electronics manufacturers with standardized form factors, and regional fabricators leveraging proximity to East Asian component clusters. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through distribution partnerships.
Among vertically integrated lighting suppliers, Signify exemplifies the conglomerate archetype through captive control over LED module and driver electronics production. Mean Well Enterprises and Inventronics occupy positions within the specialized power electronics tier, with the former anchoring global distribution density and the latter representing the outdoor-rated portfolio specialist. These three companies illustrate the strategic divergence between margin capture through upstream integration versus market access through specification-grade certification depth.
| Leading Market Players |
|---|
| Signify |
| ams OSRAM |
| Mean Well Enterprises |
| Inventronics |
| Tridonic |
| Acuity Brands Lighting |
| Lifud Technology |
| Delta Electronics |
| Eaton |
| Others |
Value Network & Pricing Analysis
Ferrite core and copper winding costs cascade through three distinct pricing tiers as Shenzhen-based magnetic component suppliers feed both premium specification-grade driver lines and economy residential replacements. Raw material volatility in wide-bandgap semiconductor substrates compresses margins at the mid-tier while reinforcing premium positioning for silicon carbide-enabled architectures.
Pricing Analysis
Input-cost pass-through from magnetic components and power semiconductors stratifies pricing across certification-grade tiers. Three-tier pricing structure across premium, standard, and economy levels reflects VDE certification depth, lumen maintenance documentation, and wireless protocol integration. Cost compression in economy channels intensifies as residential buyers prioritize unit cost over efficiency ratings. Commercial specification buyers exhibit lowest price sensitivity due to lifecycle energy savings and warranty bundling requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for standardized driver form factors, while distributor networks serve fragmented retrofit contractors. Manufacturing concentrates in China, Taiwan, and Germany with magnetic component sourcing anchored in southeastern Chinese industrial clusters. Production draws from silicon carbide wafers, ferrite cores, and copper windings as primary inputs. Single-source vulnerability in ferrite core supply creates exposure during regional power rationing. Distribution runs through lighting OEM direct procurement and electrical wholesaler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LED panel light driver procurement has shifted toward documented reliability metrics and integrated luminaire warranties, elevating quality-tier suppliers over component-only vendors. This late-cycle quality story rewards players with certification depth and field failure databases.
For Market Incumbents: Hedge against GaN-on-silicon displacement by securing magnetics engineering talent and expanding burn-in testing capacity in Suzhou. Backward integration into semiconductor sourcing protects margin pools as substrate costs fluctuate. DIN and VDE certification maintenance creates switching costs against emerging Asian competitors.
For New Entrants and Emerging Players: Capture share in Indian smart city infrastructure and US utility rebate programs where specification requirements remain fluid. Healthcare flicker-free applications offer penetrable white-space with sub-5% THD thresholds. Partner with lighting OEMs seeking second-source qualification for 50,000-hour rated life portfolios.
For Investors and Strategic Acquirers: Roll-up economics work for regional certification specialists because fragmented VDE and UL testing capabilities concentrate buyer relationships. Five-to-ten year viability favors suppliers with wireless protocol integration and predictive maintenance software. Monitor Ecodesign Directive efficiency tier escalations as inflection signals for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Silicon Topology Migration | Enables switching frequencies above 100kHz that shrink magnetic volume for high-density ceiling deployments. |
| VDE Certification Investment | Opens German specification markets requiring documented lumen maintenance curves and failure rate data. |
| Wireless Protocol Stack Integration | Captures IoT-enabled facility management demand through Bluetooth Mesh and Zigbee interoperability. |
| Backward Integration into Magnetics | Reduces single-source exposure to southeastern China ferrite core concentration during logistics disruptions. |
| Healthcare Flicker-Free Portfolio | Addresses surgical suite and pharmaceutical manufacturing specifications with sub-5% total harmonic distortion. |
Research Methodology
Bottom-up commercial and industrial installation modeling reconciled against top-down semiconductor and magnetic component supply tracking forms the analytical core. Primary interviews with lighting OEM procurement directors, electrical contractor specification engineers, power electronics R&D leads, and facility management technology officers combined with secondary validation from UL certification databases, DOE Lighting Facts listings, and Ecodesign Directive compliance registries. Trade data from customs authorities and SEC filings of listed lighting conglomerates anchored supply-side triangulation.
Input-output matrices map driver unit demand by installation type against power semiconductor wafer supply and magnetic component production capacity across the analysis window. Segmentation dimensions span product architecture, technology tier, end-use vertical, and mounting geometry with regional regulatory cluster overlays. CAGRs derive from installed base replacement cycles, building automation mandate phase-ins, and semiconductor cost convergence curves. Forecast inputs incorporate LED penetration rates in high-bay metal halide retrofits and smart city infrastructure deployment schedules.
Underlying measurement precision varies by segment; smart driver and healthcare applications carry tighter precision than commodity residential replacements due to documented procurement data availability. Forecasts reflect assumptions on wireless protocol standardization timelines and wide-bandgap semiconductor foundry capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
India LED Outdoor Lighting Market
LED
LED Lighting Market
LED
LED Display Market
LED
North America LED Packaging Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
Arrow LED Displays Market
LED
Small Pitch LED Display Market
LED
Bluetooth LED Bulb Market
LED
China Outdoor LED Lighting Market
LED
Africa LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
Europe Indoor LED Lighting Market
LED
LED Digital Scoreboard Market
LED
Architectural LED Products Market
LED
China Indoor LED Lighting Market